Author: lawizer003@gmail.com

  • Myths About Registering a Company in India: 10 Facts

    Myths About Registering a Company in India: 10 Facts

    Myths About Registering a Company in India: 10 Myths

    Starting a business is exciting. However, the legal side of building a business can quickly become confusing, especially when founders receive different advice from friends, social media, consultants and other business owners.

    Some of the most common myths about registering a company relate to minimum capital, GST, office space, company names, trademarks and ongoing compliance. A statement may sound simple, yet the actual legal position can depend on the type of business, its activities and the applicable rules.

    This guide separates common misconceptions from the practical reality for Indian founders and small-business owners. The goal is not to suggest that every entrepreneur needs a Private Limited Company. Instead, it is to help you understand when company incorporation makes sense and what it does—and does not—do for your business.

    Understanding company registration can help founders make better legal and business decisions.

    What Does Registering a Company Actually Mean?

    Before looking at individual myths, it helps to understand what company registration means. A company incorporated under the Companies Act, 2013 becomes a separate legal entity from its shareholders. It can enter contracts, own assets and conduct business in its own name, subject to applicable law.

    A Private Limited Company is only one possible business structure. Depending on the founder’s needs, alternatives can include a Limited Liability Partnership (LLP), One Person Company (OPC), partnership firm or sole proprietorship.

    For example, a founder planning to build a technology startup and raise equity investment may have different needs from a freelancer who is testing a small service business. Therefore, choosing the structure should come before assuming that incorporation is automatically necessary.

    Lawizer’s Private Limited Company Registration service provides a starting point for founders considering incorporation.

    Myth #1: You Must Register a Company Before Starting a Business

    This is one of the most common misconceptions. Starting a business and incorporating a company are not the same thing.

    Indian businesses can operate through different structures. A sole proprietorship, partnership, LLP and company each have different legal characteristics and compliance requirements.

    Can You Run a Business Without Registering a Company?

    In many cases, yes. A business does not automatically have to become a Private Limited Company simply because it wants to sell products or services.

    However, this does not mean that an unincorporated business has no legal obligations. Depending on the activity, the business may need registrations, licences, tax registrations or local approvals.

    • A freelancer may operate as a sole proprietor.
    • Two or more professionals may consider an LLP or partnership.
    • A scalable startup may consider a Private Limited Company.
    • An eligible solo entrepreneur may consider an OPC.

    Therefore, the better question is not simply, “Do I need a company?” Instead, ask, “Which business structure fits my current activity and future plans?”

    For a detailed comparison, read Lawizer’s Private Limited vs LLP vs Sole Proprietorship guide.

    Myth #2: An Unregistered Business Is Automatically Illegal

    The word “unregistered” can create confusion because it can describe several different situations.

    A business that is not incorporated as a company is not automatically illegal. For example, a sole proprietorship does not become a Private Limited Company simply because its owner starts selling goods or services.

    At the same time, failing to obtain a registration that is actually required can create legal and financial problems. The correct requirements depend on the business activity, location, turnover and applicable law.

    What Happens If a Company Is Not Registered?

    If you intend to operate through a company, incorporation is what creates that company as a separate legal entity. Without incorporation, you cannot simply treat an informal business as though it were a Private Limited Company.

    This distinction matters for contracts, ownership, banking, taxation and liability. It also matters when dealing with investors or institutional customers.

    What Are the Legal Consequences of Having a Non-Registered Firm?

    The answer depends on what “non-registered” means. A business may be legally operating under one structure while not having another registration that someone assumes is mandatory.

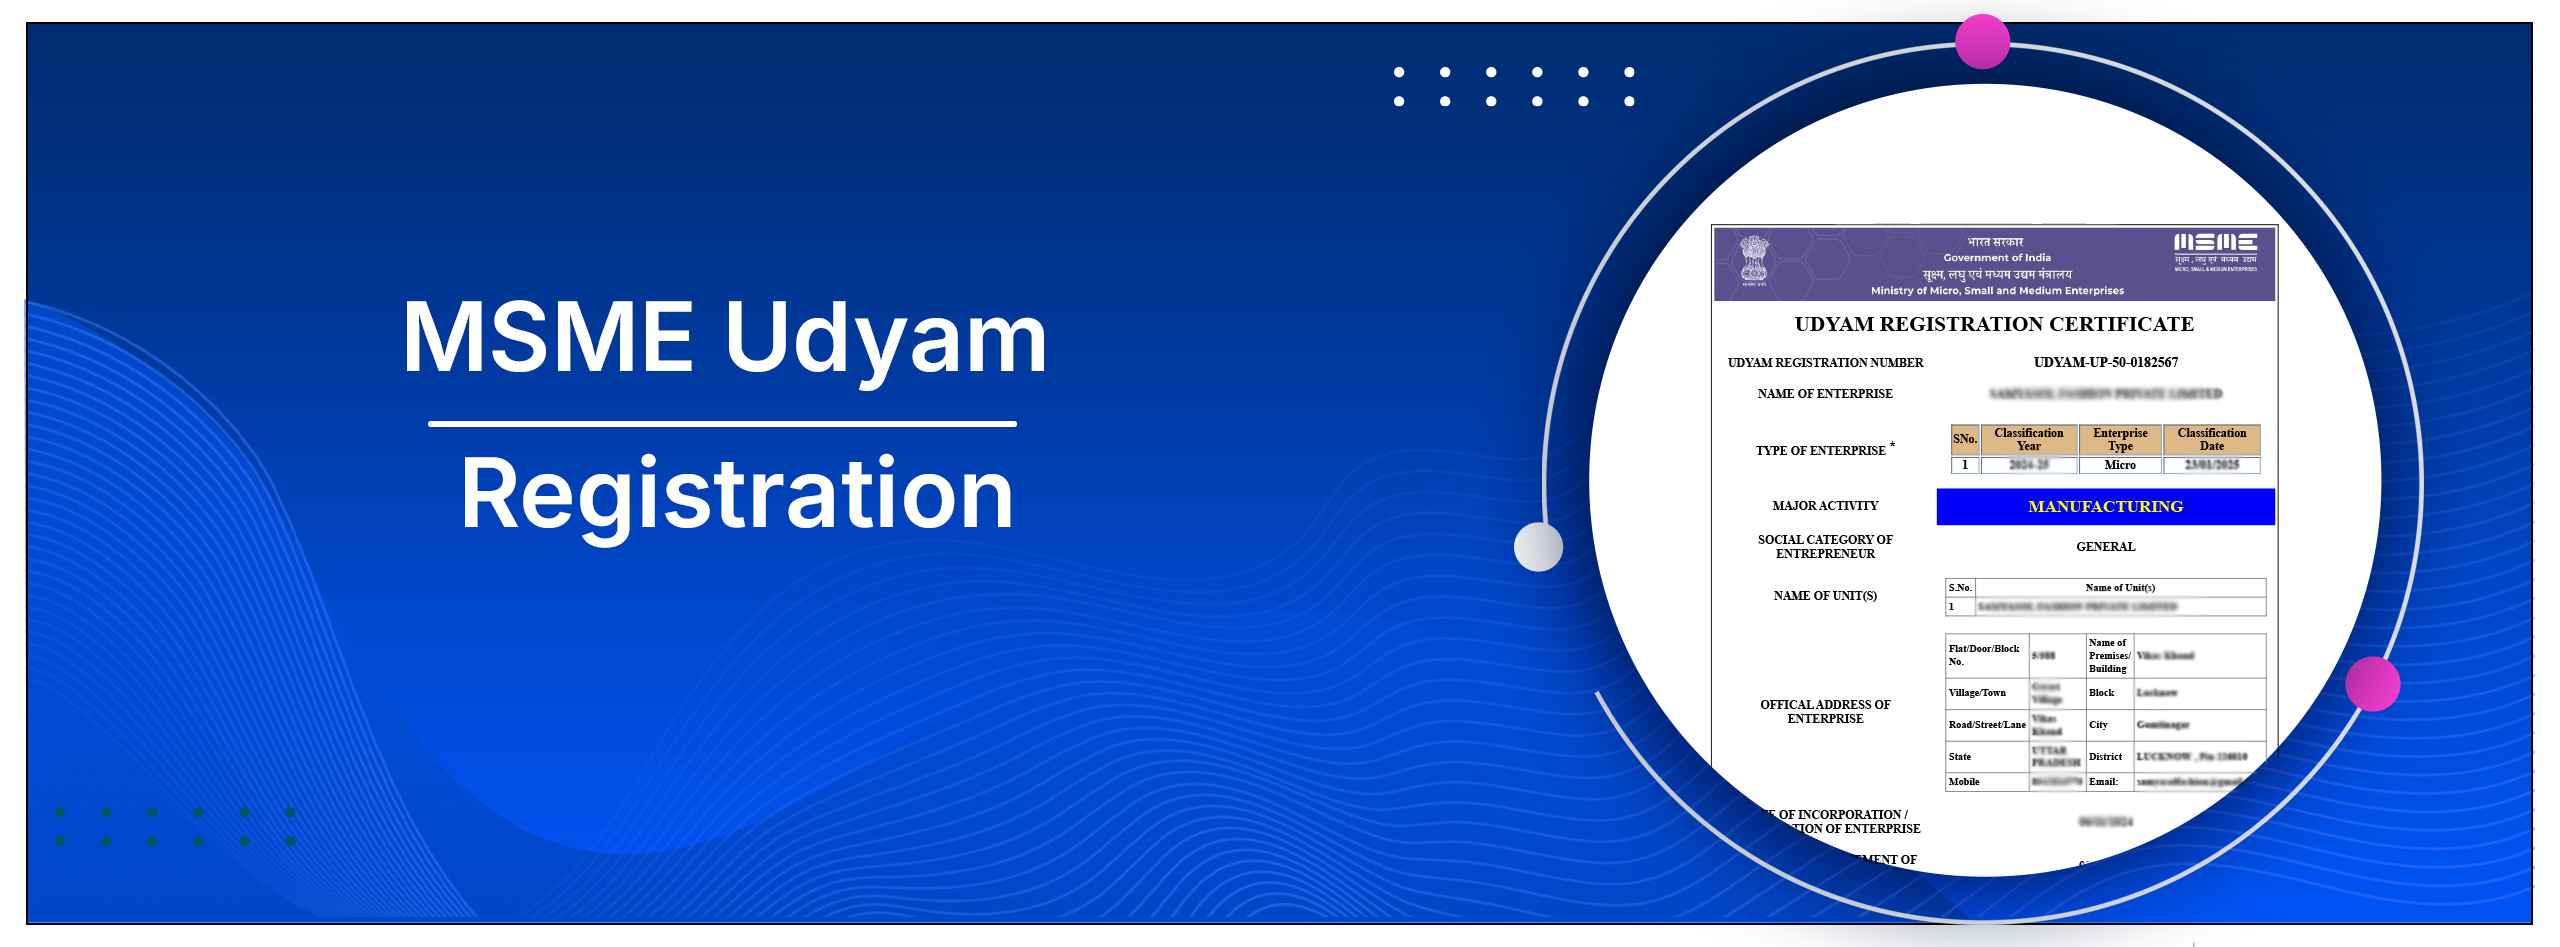
    For example, company incorporation, GST registration, MSME registration and trademark registration are separate legal processes. One does not automatically replace the others.

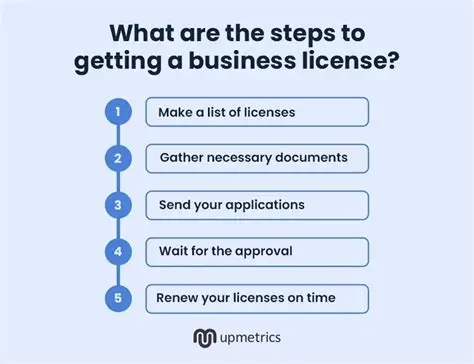
    Lawizer’s guide to business licences and registrations for startups explains why founders should create a requirement-specific checklist instead of copying another business’s registrations.

    Can a Third Party Sue an Unregistered Partnership Firm?

    Yes, generally. The restrictions created by Section 69 of the Indian Partnership Act, 1932 mainly affect the ability of an unregistered firm or partner to institute certain suits to enforce contractual rights. They do not create a blanket rule that protects an unregistered partnership from being sued by outsiders.

    Therefore, partnership registration should not be viewed as a shield against all legal claims. The precise position depends on the nature of the dispute and the right being enforced.

    Can an Unregistered Partnership Firm Open a Bank Account?

    Banking and registration are separate questions. Banks have their own KYC and documentation requirements, and an account may be available depending on the entity and documents provided.

    However, founders should not confuse having a business bank account with having a separately incorporated legal entity.

    What Are the Disadvantages of Not Registering a Partnership Firm?

    For an unregistered partnership, one important concern is the restriction on bringing certain contractual claims under Section 69 of the Partnership Act.

    There can also be practical disadvantages, such as weaker documentation, credibility concerns and difficulty proving the agreed business arrangement if the partners have relied mainly on informal promises.

    Myth #3: You Need Huge Capital to Register a Company

    Many first-time founders believe that incorporating a Private Limited Company requires them to deposit a large amount of money. That is not generally correct.

    There is no general minimum paid-up capital requirement for incorporating an ordinary Private Limited Company. However, founders still need to decide the company’s authorised capital and initial subscription based on the proposed ownership and funding structure.

    It is important to understand the difference between capital and registration costs. Government charges, stamp duty, Digital Signature Certificate costs and professional fees are separate from the company’s share capital.

    For example, a founder should not assume that paying incorporation-related charges means that the same amount becomes the company’s share capital.

    Capital planning also matters later. Changes to share capital can require additional corporate documentation and filings.

    For a detailed explanation of incorporation documents and capital, see Lawizer’s Private Limited Company Registration guide.

    You can also read the Private Limited Company Registration Cost guide to understand the different components of incorporation expenses.

    Myth #4: Only Big Businesses Need Company Registration

    Company incorporation is not reserved for large corporations. A small business can also choose a formal structure when that structure fits its goals.

    For example, a startup expecting external investment may prefer a Private Limited Company even when its current revenue is small. The reason is not size alone. The structure can support share-based ownership and future investment.

    On the other hand, a small professional business with two partners may prefer an LLP because its requirements and operating model may be different.

    Therefore, founders should consider:

    • Number of founders and owners.
    • Personal liability concerns.
    • Plans to raise equity investment.
    • Expected growth and expansion.
    • Compliance capacity.
    • Tax and accounting considerations.
    • Whether employees or investors will receive equity.

    There is no single business structure that is perfect for every entrepreneur. Lawizer’s LLP Registration service and OPC Registration service can help founders compare alternatives to a Private Limited Company.

    Myth #5: Company Registration Automatically Protects Your Brand

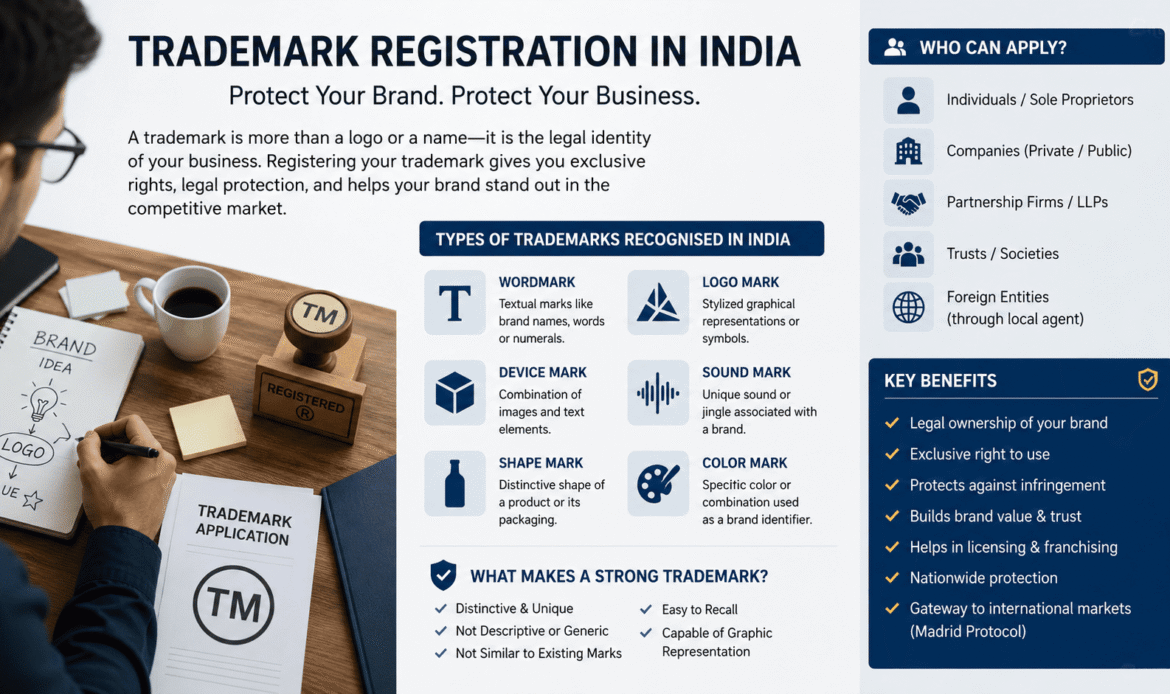
    Registering a company name with the Ministry of Corporate Affairs and registering a trademark are two different things.

    This distinction is extremely important for founders. A company name gives the entity its legal identity. A trademark, on the other hand, is concerned with protecting a brand or other qualifying mark under trademark law.

    Is Company Name Registration the Same as Trademark Registration?

    No. MCA name approval does not automatically give you comprehensive trademark rights over the brand.

    A founder could therefore incorporate a company and later discover that a similar brand is already protected by another party. That is why checking the proposed name from both a company-law and trademark perspective is a sensible step.

    Before investing heavily in a logo, website, packaging or marketing campaign, consider conducting an appropriate trademark search.

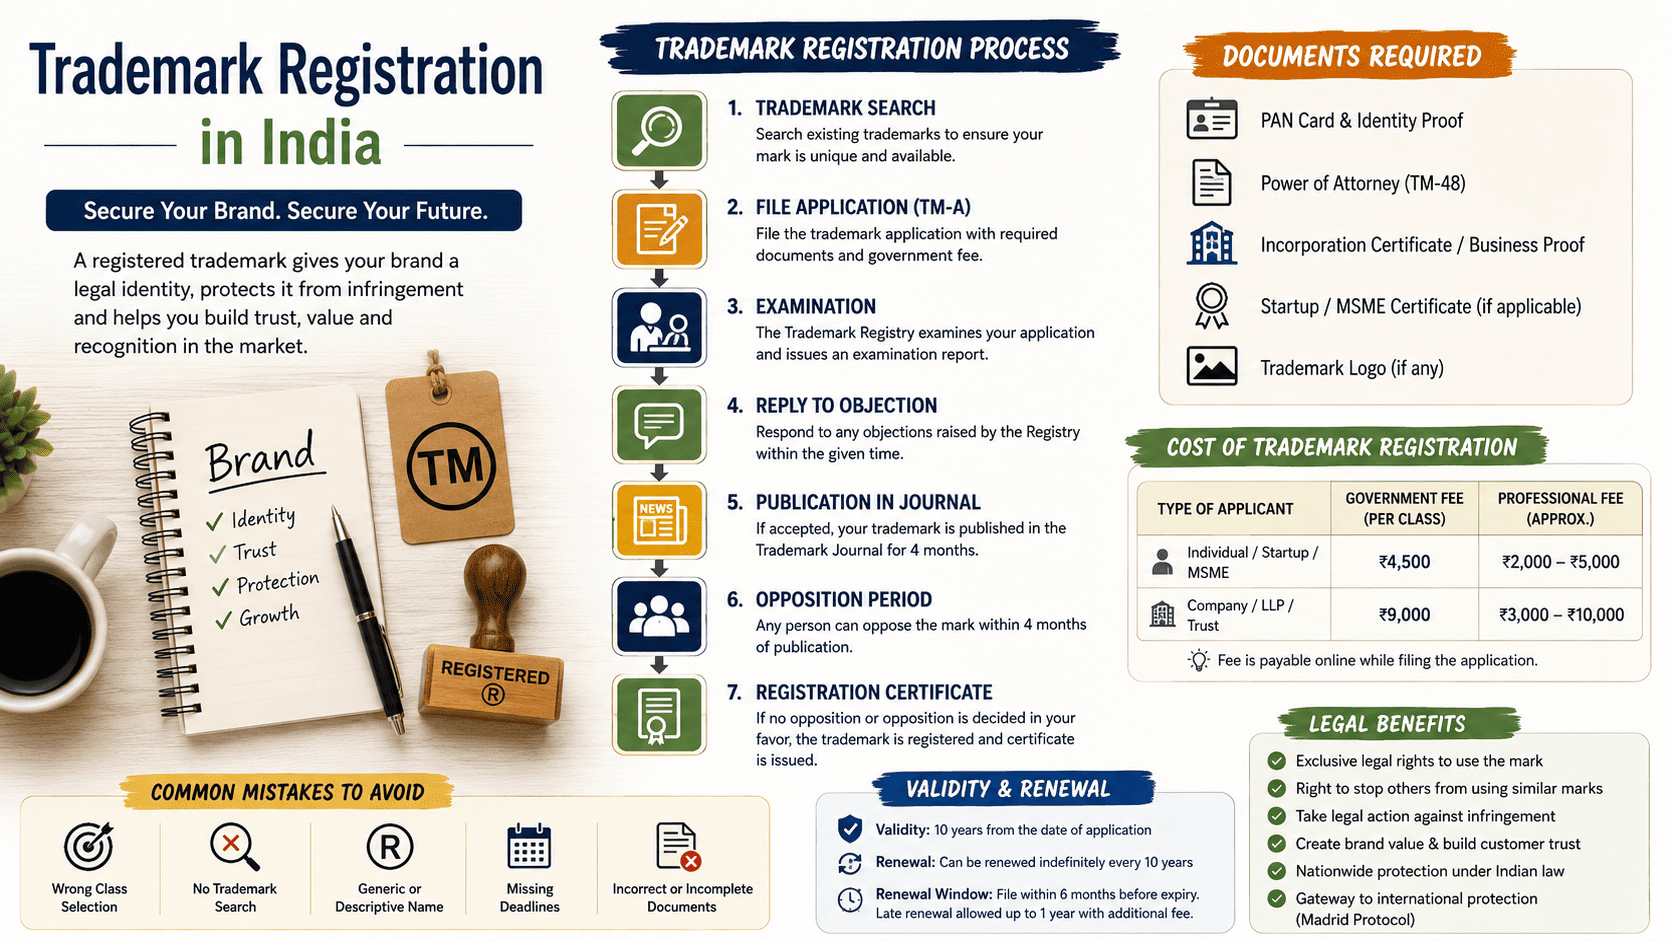
    Lawizer provides Trademark Registration services for businesses looking to protect their brands.

    You can also read Trademark Registration in India: Cost, Process and Timeline for a deeper explanation.

    Myth #6: You Can Choose Any Company Name You Want

    Founders have considerable freedom when choosing a business name. However, that freedom is not unlimited.

    The proposed name must satisfy applicable company-name rules. It can also face issues if it is too similar to an existing company, LLP or protected trademark.

    What Are the Rules for Naming a Company?

    Before submitting a proposed name, founders should consider whether it is distinctive, legally acceptable and suitable for the proposed business activity.

    A sensible name-checking process should consider:

    • Existing company and LLP names.
    • Existing trademarks.
    • Restricted or regulated expressions.
    • Potentially misleading words.
    • Similarity with well-known brands.
    • Whether the name accurately reflects the proposed business.

    What Words Are Not Allowed in Company Names in India?

    There is no short universal list that can safely be applied to every proposed name. Certain expressions may be restricted, inappropriate or subject to additional requirements depending on their use and context.

    Therefore, instead of relying on a social-media list of “banned words”, founders should check the current MCA naming rules when preparing the incorporation application.

    What Should You Avoid When Naming a Company?

    • Names that are confusingly similar to existing entities.
    • Names that may conflict with existing trademarks.
    • Names that falsely suggest government affiliation.
    • Names that make misleading claims about the business.
    • Names that unnecessarily restrict future expansion.

    Choosing a name carefully at the beginning can save time and reduce the risk of having to rethink your branding later.

    Myth #7: You Need an Expensive Commercial Office to Register a Company

    Another common misconception is that a founder must rent a large commercial office before incorporating a company.

    In reality, what matters is having a valid registered office that satisfies the applicable legal requirements. A commercial office is not automatically required simply because the business is a Private Limited Company.

    Depending on the circumstances, a residential or rented premises may be used as the registered office if the required documentation and conditions are satisfied.

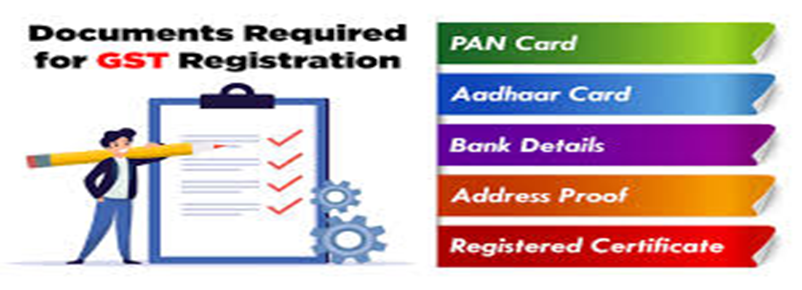
    Typical documents can include appropriate address proof, ownership or possession documents, a rent or lease agreement and an owner’s no-objection certificate where applicable.

    Lawizer’s Company Registration Documents Checklist explains the documents founders should prepare before incorporation.

    For Kolkata and West Bengal founders, Lawizer also provides a guide to registering a startup in Kolkata and West Bengal.

    Myth #8: Company Registration Automatically Means GST Registration

    Company incorporation and GST registration are separate processes.

    Incorporating a Private Limited Company does not, by itself, mean that GST registration is automatically required in every case. GST applicability depends on factors such as the nature of supplies, aggregate turnover, location and specific compulsory-registration provisions.

    For example, a founder should not simply copy the GST registration status of another company and assume that the same rule applies to their business.

    When Should a Founder Check GST Registration?

    A founder should assess GST requirements before beginning taxable business activity and whenever there is a significant change in turnover, business model, location or type of supply.

    Particular attention may be needed where the business makes supplies or transactions that fall under compulsory-registration provisions.

    Because GST rules and notifications can change, founders should check the current position rather than relying on an old turnover figure found online.

    Lawizer’s GST Registration service can be used alongside the more detailed GST Registration for Startups guide.

    Myth #9: Once the Company Is Registered, the Legal Work Is Finished

    This is perhaps the most expensive misconception for a new founder.

    Incorporation creates the company. It does not remove the company’s future statutory, tax and regulatory responsibilities.

    After incorporation, a company may need to deal with matters such as corporate records, accounting, applicable tax registrations, commencement-related requirements, annual filings and event-based filings.

    What Happens After Company Registration?

    The exact requirements depend on the company and its activities. However, founders should generally create a post-incorporation checklist covering:

    • Corporate bank-account arrangements.
    • Share capital and initial corporate records.
    • Applicable commencement-of-business requirements.
    • GST and other tax registrations, where applicable.
    • Accounting and financial records.
    • Annual MCA/ROC compliance.
    • Income-tax compliance.
    • Director-related filings and requirements.
    • Industry-specific licences and registrations.

    For example, missing recurring ROC filings can lead to additional fees and compliance problems. Therefore, founders should think about compliance from the beginning rather than waiting until the first deadline approaches.

    Lawizer’s Annual Compliance service can help businesses understand recurring compliance requirements.

    You can also read What Happens If You Miss Your ROC Annual Filing Deadline? to understand why timely filings matter.

    Company incorporation is only the first step. Ongoing compliance also matters.

    Myth #10: Company Registration Is Too Complicated to Complete Online

    Company incorporation in India involves several documents and declarations. However, the process is substantially digital.

    The MCA’s prescribed incorporation system allows founders to submit the required information electronically. Depending on the company, the process can involve Digital Signature Certificates, director information, registered-office documents, constitutional documents and other linked requirements.

    Can a Founder Register a Private Limited Company Online?

    Yes. Much of the process can be handled online. However, “online” does not mean “no legal formalities”. The quality of the documents and accuracy of the information still matter.

    Common causes of delays include:

    • Incorrect names or spellings.
    • Mismatched address details.
    • Incomplete identity documents.
    • Problems with registered-office documentation.
    • Errors in the proposed business objects.
    • Incorrect or incomplete declarations.

    Therefore, preparing the documents before filing can make the process much smoother.

    Read Lawizer’s Private Limited Company Registration guide for a detailed overview of the incorporation process.

    Bonus Myth: Registering a Company Automatically Makes It a Startup

    Incorporating a company and receiving official startup recognition are not necessarily the same thing.

    DPIIT startup recognition under the Startup India framework has its own eligibility requirements. Current Startup India guidance includes eligible Private Limited Companies, registered partnership firms, LLPs and certain cooperative entities within the recognition framework, subject to the applicable conditions. :contentReference[oaicite:1]{index=1}

    Therefore, a newly incorporated company should not assume that incorporation alone automatically gives it every Startup India benefit.

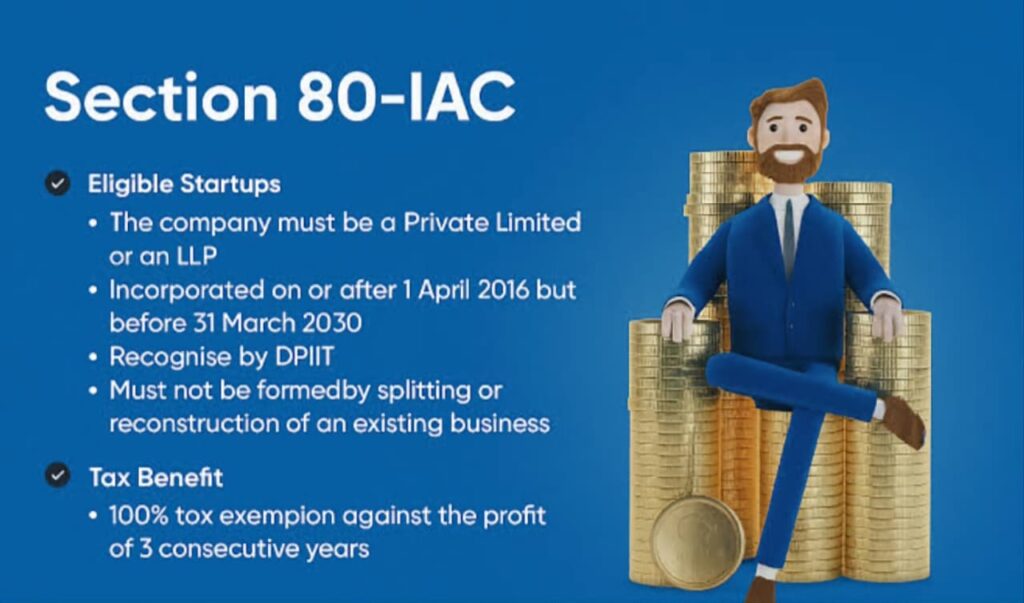
    Recognition and specific benefits can have separate eligibility conditions. For example, Section 80-IAC tax exemption has its own requirements beyond simply having a new company. :contentReference[oaicite:2]{index=2}

    Founders interested in this route can explore Lawizer’s Startup India Registration assistance.

    10 Myths About Registering a Company: Myth vs Reality

    Myth Reality
    You must register a company before starting any business. Different businesses can operate through different legal structures.
    An unregistered business is automatically illegal. The legal position depends on the structure and applicable requirements.
    You need huge capital to incorporate. There is no general minimum paid-up capital requirement for an ordinary Private Limited Company.
    Only large businesses need formal structures. Small businesses may also choose formal structures based on their goals.
    Company registration protects your brand. Company incorporation and trademark registration are separate.
    You can choose any company name. Proposed names must satisfy applicable legal and naming requirements.
    You need an expensive commercial office. You need a valid registered-office arrangement, not necessarily a premium office.
    Company incorporation automatically means GST registration. GST applicability depends on the relevant GST rules and the business’s circumstances.
    There is nothing to do after incorporation. Companies have continuing corporate, tax and regulatory obligations.
    Company incorporation is too complicated to do online. The incorporation process is substantially digital, although documentation and legal formalities still matter.

    How to Avoid Common Company Registration Mistakes

    Understanding the myths is useful, but founders also need a practical checklist. Before registering a business, take the following steps.

    1. Choose the right structure. Compare a Private Limited Company, LLP, OPC, partnership or proprietorship based on your actual needs.
    2. Decide the ownership structure. Agree on founder contributions and ownership before filing.
    3. Check the proposed name. Review both company-name availability and potential trademark conflicts.
    4. Prepare your documents. Keep identity, address and registered-office documents ready.
    5. Understand GST applicability. Do not assume incorporation automatically creates a GST obligation.
    6. Review industry licences. Some sectors have additional approvals.
    7. Protect the brand. Consider trademark registration where appropriate.
    8. Document founder relationships. A written Co-Founder Agreement can clarify roles, ownership, responsibilities and exit arrangements.
    9. Plan for future shareholders. Where relevant, understand how a Shareholder Subscription Agreement or shareholders’ agreement may fit into future fundraising.
    10. Plan compliance from Day One. Incorporation should be followed by a clear compliance calendar.

    Lawizer’s Legal List for New Founders is another useful resource for organising these early legal steps.

    Frequently Asked Questions About Company Registration Myths

    1) What Are the Top 10 Myths About Registering a Company?

    The most common myths are that every business must incorporate, incorporation requires huge capital, a commercial office is mandatory, company registration protects a trademark, GST automatically becomes mandatory, any company name can be chosen, and compliance ends after incorporation. In reality, each issue depends on the business structure and applicable law.

    2) What Are 5 Examples of Myths About Company Registration?

    • Every business must become a Private Limited Company.
    • A founder needs a large amount of capital to incorporate.
    • A company must have an expensive commercial office.
    • Company incorporation automatically protects the brand name.
    • There are no legal obligations after incorporation.

    3) What Is the Biggest Myth About Registering a Company?

    One of the biggest misconceptions is that company incorporation is the same as business registration in general. In reality, India has several business structures, and each has its own legal and compliance framework.

    4) Can You Run a Business Without Registering a Company?

    Yes, depending on the business and its legal requirements. A sole proprietorship or partnership, for example, is different from an incorporated company. However, the business may still need GST, local, sector-specific or other registrations depending on its activities.

    5) What Happens If a Company Is Not Registered?

    If you intend to operate through a company, incorporation is required to create that company as a separate legal entity. If you instead operate through another lawful structure, the business will be governed by the rules applicable to that structure.

    6) What Are the Legal Consequences of Having a Non-Registered Firm?

    The consequences depend on the structure and the registration being discussed. For example, an unregistered partnership can face restrictions under Section 69 of the Indian Partnership Act when attempting to enforce certain contractual rights. Other registrations have different rules.

    7) Can a Third Party Sue an Unregistered Partnership Firm?

    Yes, generally. The restrictions under Section 69 mainly concern suits brought by an unregistered firm or partner to enforce certain contractual rights. They do not provide blanket immunity from claims brought by third parties.

    8) Can an Unregistered Partnership Firm Open a Bank Account?

    Possibly, depending on the bank’s KYC and documentation requirements. However, a business bank account should not be confused with incorporation as a separate legal entity.

    9) What Are the Disadvantages of Not Registering a Partnership Firm?

    An important disadvantage is the restriction on certain contractual suits under Section 69 of the Partnership Act. Informal arrangements can also create practical problems when partners disagree about ownership, contributions or responsibilities.

    10) What Are the Rules for Naming a Company?

    The proposed name must comply with applicable MCA requirements and should not create prohibited or confusing similarities with existing entities. Founders should also check trademark conflicts before committing to a brand.

    11) What Words Are Not Allowed in Company Names in India?

    There is no single short list that safely covers every situation. Certain words or expressions may be restricted or may require additional approvals. The current MCA naming rules should be checked before submitting the proposed name.

    12) What Should You Avoid When Naming a Company?

    Avoid names that are confusingly similar to existing entities, conflict with trademarks, falsely imply government affiliation or make misleading claims about the business.

    13) Can AI Create a Business Name?

    Yes. AI can be useful for generating creative business-name ideas. However, an AI-generated name is not automatically legally available. Before adopting it, check company-name availability and potential trademark conflicts.

    14) What Is the Luckiest Business Name?

    There is no universally recognised “luckiest” business name under company law. From a business perspective, a strong name should be distinctive, memorable, suitable for the brand and legally available.

    15) What Are Some Fake Business Names?

    Rather than using real businesses as examples, consider generic names such as “Government India Finance Services” or “National Authority Consulting” where the wording falsely suggests a government connection. The broader lesson is to avoid names that could mislead customers about who operates the business.

    16) What Are the Four Main Types of Entrepreneurs?

    There is no single legally prescribed list of four entrepreneur types. Common business textbooks may classify entrepreneurs as innovative, imitative, Fabian and drone entrepreneurs. These are educational classifications, not legal business structures.

    17) What Are the 7 Ms of Entrepreneurship?

    The “7 Ms” is an entrepreneurship framework rather than a statutory company-registration requirement. Different textbooks use slightly different versions. It is generally used to discuss business resources and management rather than legal incorporation.

    18) What Are the 4 Ms of Entrepreneurship?

    The “4 Ms” is another business-management framework. Depending on the source, it can refer to different groups of business resources. Founders should therefore check the specific textbook or course context rather than treating it as an official legal requirement.

    19) What Are the Four Cs of Entrepreneurship?

    The Four Cs is also a business concept rather than a company-law rule. Different entrepreneurship frameworks use the term differently, so the meaning should be understood in the context in which it is being taught.

    20) What Are the 12 Different Types of Entrepreneurs?

    There is no universally accepted legal list of twelve entrepreneur types. Different business and entrepreneurship resources use different classifications. These classifications describe entrepreneurial styles; they do not determine whether someone should register a Private Limited Company, LLP or another entity.

    Final Takeaway: Do Not Let Myths Decide Your Business Structure

    Company registration is an important step, but it should not be driven by assumptions. A business does not become better simply because it chooses the most formal structure. The right structure is the one that fits its ownership, liability, funding plans, operations and long-term goals.

    Similarly, incorporation is not the same as GST registration, trademark protection, MSME registration or startup recognition. These are separate areas that may become relevant at different stages.

    Most importantly, the legal work does not necessarily end when the Certificate of Incorporation arrives. Ongoing corporate, tax and regulatory compliance should be planned from the beginning.

    If you are unsure whether your business should be a Private Limited Company, LLP, OPC or another structure, start by understanding your actual requirements. You can then build the appropriate registration and compliance checklist around them.

    Lawizer provides Startup & Business Legal Services covering company incorporation, LLP registration, GST, Startup India, MSME, trademark protection and related business documentation.

    Need help deciding what your business actually needs? Consult Lawizer before you register so that your business structure, documentation and compliance plan are aligned from the beginning.
    Explore Lawizer’s Startup & Business Legal Services

  • Founders Agreement Explained

    Founders Agreement Explained

    founders agreement explained: clauses & legal guide

    Starting a business with a co-founder often begins with trust, shared goals and an exciting idea. However, as the business grows, questions about ownership, salary, responsibilities and decision-making can become difficult. This is where founders agreement explained in practical terms becomes important for Indian entrepreneurs. A founders agreement records what the founders have agreed about the business before disagreements arise.

    For example, what happens if one founder stops working full-time? Who owns the intellectual property created before incorporation? Can a founder sell their shares to an outsider? What happens if two founders disagree about a major business decision?

    A properly drafted agreement can provide a framework for answering these questions. The Government of India’s Startup India guidance also recognises a co-founder agreement as a way to set out equity ownership, initial investment and founder responsibilities in writing.

    In this guide, we explain the purpose of a founders agreement, important clauses, founder salary and equity, CEO and founder authority, exit provisions and common questions Indian founders should understand.

    Founders agreement explained: what is a founders’ agreement?

    A founders’ agreement, also called a co-founders agreement, is a written contract between the people starting or jointly running a business. It records important arrangements between the founders, such as their responsibilities, ownership, contributions, decision-making rights and what happens if the relationship changes.

    The agreement is particularly useful when two or more people are building a business together. It converts important conversations into documented terms that the founders can refer to later.

    Depending on the business structure and circumstances, the agreement may work alongside documents such as the company’s Articles of Association, employment agreements, intellectual property assignments and a shareholders’ agreement.

    Lawizer provides business documentation and agreement drafting services, including a dedicated Co-Founder Agreement service for founders who want their arrangements documented clearly.

    What does a founders agreement cover?

    A founders agreement can cover many areas, including:

    • Founder names and business details
    • Equity ownership and capital contributions
    • Roles and responsibilities
    • Founder salary and expense reimbursement
    • Decision-making and voting
    • Founder vesting arrangements
    • Intellectual property ownership
    • Confidentiality
    • Share transfer restrictions
    • Founder exit and separation
    • Deadlock and dispute resolution

    The exact clauses should be tailored to the business rather than copied from a generic internet template.

    What is the purpose of a founders agreement?

    The main purpose is to reduce uncertainty between co-founders. Startup India describes a co-founder agreement as a way to formally record equity ownership, initial investments and responsibilities and reduce the possibility of serious surprises later.

    In practical terms, the agreement creates a written framework for situations that may be easy to ignore when the business is new.

    1. It defines founder roles and responsibilities

    Founders should decide who is responsible for areas such as technology, sales, finance, operations, marketing or product development.

    The agreement can also record whether each founder is expected to work full-time, how much time they are expected to contribute and which decisions fall within their authority.

    2. It records ownership and contributions

    Founders may contribute different amounts of money, intellectual property, experience, contacts or working time. The agreement can record the agreed ownership structure and the basis on which it was determined.

    There is no universal rule saying that two founders must split a company 50:50. The appropriate allocation depends on the circumstances and should be discussed carefully before it becomes a source of conflict.

    3. It establishes decision-making rules

    Not every business decision needs the same level of approval. Founders can establish which matters can be handled by an individual founder and which require approval from multiple founders, the board or shareholders.

    This can be especially important when founders have equal or similar ownership and a disagreement could otherwise create a deadlock.

    4. It prepares for a founder’s exit

    A founder may eventually resign, become unable to continue, move to another country, start another venture or simply decide that the business is no longer suitable for them.

    An agreement can establish what happens to their shares, confidential information, company property and responsibilities when they leave.

    5. It protects intellectual property

    For many startups, intellectual property is one of the most valuable assets. This can include software, source code, designs, branding, written content, inventions, databases and business processes.

    Founders should clearly address ownership and assignment of relevant intellectual property. Lawizer also provides an IP Assignment Agreement service for businesses that need separate documentation for intellectual property ownership.

    Key clauses in a founders agreement

    A strong agreement should deal with the issues that are most likely to create disagreement later. The following clauses are commonly considered when preparing founder documentation.

    Founder details and business information

    Start with the identity of each founder and the relevant business details. The document should clearly identify who is entering into the agreement and, where applicable, the company or proposed company connected with it.

    Equity ownership and capital contributions

    The agreement should state the agreed ownership structure and explain the founders’ initial contributions.

    Contributions may involve cash, assets, intellectual property, services or other agreed commitments. If additional funding may be required from founders, the agreement can also explain how those contributions will be handled.

    Founders should remember that an agreed percentage in a contract is not necessarily the same thing as the company’s legally issued and recorded shareholding. Corporate records, share issuances and applicable company documents must also be kept consistent.

    Roles, responsibilities and time commitment

    A founders agreement should explain who will perform which functions.

    • Who will lead operations?
    • Who will manage technology?
    • Who will handle sales and business development?
    • Who will manage finance?
    • Who will represent the company externally?

    Clear responsibilities reduce duplication and make accountability easier.

    Founder salary and expenses

    Founders should decide whether they will receive a salary, when salary will begin and how expenses will be reimbursed.

    Early-stage businesses may have limited cash. Therefore, founders may agree to take lower compensation initially and revisit it when revenue or funding reaches an agreed level.

    The important point is not choosing one universal salary. It is documenting the arrangement clearly enough that founders understand what they can expect.

    Founder vesting

    Vesting connects ownership to continued participation over an agreed period. It can help protect a company when a founder leaves soon after the business starts.

    A commonly discussed startup structure is four years with a one-year cliff. However, this is a market convention, not a mandatory statutory rule for every Indian startup. The actual arrangement should be drafted according to the company’s structure and legal requirements.

    Lawizer also explains founder vesting schedules in India in greater detail.

    Intellectual property and confidentiality

    The agreement should identify how intellectual property created for the business will be owned or assigned. It should also protect confidential business information.

    For example, the agreement may address source code, product designs, customer lists, pricing information, business plans and trade secrets.

    Founders can also consider a separate Non-Disclosure Agreement where appropriate.

    Decision-making and reserved matters

    Founders should identify important decisions that require additional approval. These may include issuing new shares, taking significant debt, selling substantial assets, changing the business model or entering major transactions.

    The exact approval thresholds should be tailored to the company’s ownership and governance structure.

    Founder exit and share transfers

    The agreement can establish procedures for voluntary resignation, termination where legally applicable, death, incapacity and other forms of departure.

    It can also address whether a departing founder can transfer shares to outsiders and whether existing shareholders receive a right to purchase those shares first.

    For a broader explanation of shareholder rights, see Lawizer’s guide to the key clauses in a shareholders’ agreement.

    Dispute resolution

    Disagreements are not always avoidable. A good agreement therefore establishes how disputes should be handled.

    Possible mechanisms include negotiation, mediation and arbitration, depending on the circumstances and drafting. The agreement should also address applicable law and jurisdiction where appropriate.

    Is a founders agreement legally binding?

    A founders agreement can be legally binding when it satisfies the requirements of a valid contract and its terms are enforceable under applicable law. The Indian Contract Act, 1872 contains the general framework for determining when agreements become contracts.

    Section 10 is important because it deals with agreements that qualify as contracts, subject to requirements including free consent, competent parties, lawful consideration and a lawful object, and subject to other provisions of law.

    However, simply signing a document does not make every clause automatically enforceable. Some provisions may be affected by statutory restrictions, company law, employment law, public policy or the particular facts of a dispute.

    For example, post-employment restrictions and non-compete provisions require particular care in India because Section 27 of the Indian Contract Act addresses agreements in restraint of trade.

    For authoritative reference, founders can review the Indian Contract Act, 1872 on India Code.

    If a company is already incorporated, the founders agreement should also be considered alongside its constitutional documents and other shareholder arrangements. Lawizer’s shareholders’ agreement guide explains why these documents should be coordinated.

    How much salary do founders take?

    There is no standard founder salary in India. Compensation varies according to the company’s stage, revenue, funding, founder responsibilities, industry and available cash.

    An early-stage founder may choose to take a modest salary to preserve cash for product development and hiring. A profitable business may support a higher salary.

    Founder salary should also be distinguished from founder equity. A person can have a large ownership stake but take a modest salary, particularly in the early stages.

    The agreement should make the compensation arrangement clear. If salary changes require founder, board or shareholder approval, that process should also be documented.

    How much of a company do founders usually own?

    There is no legally prescribed founder ownership percentage that applies to every startup.

    Founders may divide ownership based on their respective contributions, responsibilities, capital, intellectual property, time commitment and future role. They should also consider future investors, employees and other shareholders.

    Startup India’s guidance notes that deciding how to divide equity among co-founders and early contributors can be challenging and should be approached carefully rather than treated as an automatic equal split.

    If you are still deciding on your business structure, Lawizer’s guide comparing OPC, LLP and Private Limited Company can help explain the main structural differences.

    Who is more powerful: CEO or founder?

    The answer depends on the company’s ownership, board structure, constitutional documents and the person’s actual position in the organisation.

    A founder is someone who helped establish the business. A CEO is generally an executive responsible for managing the company’s operations within the authority given to them.

    One person can be both founder and CEO. Another founder can be a shareholder without being the CEO. Similarly, a professional CEO can be appointed even when the founders remain shareholders.

    Founder vs CEO: what is the difference?

    Founders may have ownership rights because they hold shares or other interests in the business. A CEO’s authority primarily comes from their appointment, employment terms, board authority and the company’s governance arrangements.

    Therefore, the title alone does not determine who has greater legal power.

    Can the chairman fire the CEO?

    Not automatically. Whether a chairman can remove a CEO depends on the company’s structure, the CEO’s legal position and the authority given by the company’s governing documents and applicable law.

    If the CEO is also a director, removal from the board is a separate corporate-law matter. Section 169 of the Companies Act, 2013 deals with removal of directors by the company, subject to the statutory procedure and exceptions.

    The Companies Act, 2013 on India Code contains the statutory framework governing directors and their removal.

    Who has higher power: CEO or chairman?

    The chairman and CEO normally have different roles. The board and its chair are associated with governance and oversight, while the CEO generally handles executive management.

    The exact division of authority depends on the company’s Articles of Association, board decisions, employment arrangements and applicable law.

    Who holds a CEO accountable?

    In a company structure, the board generally plays an important role in overseeing the CEO. Shareholders can also exercise rights provided by company law and the company’s governing documents.

    A founders agreement can help clarify how founders participate in major decisions, but it should not be drafted as though it overrides mandatory provisions of company law.

    Common problems a founders agreement can prevent

    Many founder disputes start with assumptions rather than deliberate wrongdoing. The founders simply remember their original conversation differently.

    A written agreement can reduce this uncertainty in several areas.

    • Unequal work: One founder may eventually contribute much more time than another.
    • Salary disputes: Founders may disagree about when compensation should increase.
    • Ownership disputes: A founder may believe that a different equity split was promised.
    • IP disputes: A departing founder may claim rights over work they created.
    • Decision deadlocks: Equal ownership can make major decisions difficult.
    • Founder exits: A departure can become disruptive if there are no agreed procedures.
    • Investor concerns: Unclear founder arrangements can create additional questions during due diligence.

    Lawizer’s guide on protecting Indian startups from co-founder disputes covers these risks in greater detail.

    How to create a founders agreement in India

    The process should begin with an honest discussion between all founders. The goal is not simply to sign a template. It is to make sure everyone understands the commercial arrangement.

    Step 1: Identify the founders and business

    Clearly identify every party and the business or proposed company to which the agreement relates.

    Step 2: Agree on ownership and contributions

    Record the agreed equity structure and initial contributions. If additional funding may be required, decide how future contributions will be handled.

    Step 3: Define roles and authority

    Set out each founder’s responsibilities, expected commitment and decision-making authority.

    Step 4: Decide compensation

    Document salary, reimbursements and the procedure for changing compensation.

    Step 5: Address vesting and exits

    Decide what happens if a founder leaves early, resigns, becomes unable to work or wants to transfer shares.

    Step 6: Protect intellectual property

    Make sure relevant business IP is appropriately assigned or licensed to the company. This is particularly important when founders create software, branding or other assets before incorporation.

    Step 7: Review and execute the agreement

    All founders should understand the final document before signing. The agreement should also be checked against the company’s Articles of Association, shareholder arrangements and other relevant contracts.

    If you are still setting up the business, Lawizer can assist with Private Limited Company registration, LLP registration and Startup India registration.

    What happens if there is no founders agreement?

    There is no single automatic outcome when founders have not signed a founders agreement. The parties may still have rights under applicable contracts, company law and other legal principles.

    The practical problem is uncertainty. Founders may disagree about what was promised and may have to rely on emails, messages, company records, share documents and other evidence.

    Disputes can become particularly difficult when they involve equity, intellectual property, founder responsibilities or an attempted exit.

    This is why documenting important arrangements early is usually easier than trying to reconstruct them after a disagreement.

    Frequently asked questions about founders agreements

    Is a founders agreement legally binding?

    It can be, provided the agreement satisfies the requirements of a valid contract and its individual provisions are legally enforceable. The Indian Contract Act, 1872 provides the general contractual framework, but specific clauses may be affected by other laws.

    How much salary do founders take?

    Founder salaries vary widely. Early-stage founders often balance personal compensation against the company’s cash requirements. Salary should be decided according to the business’s financial position and documented clearly.

    How much of a company do founders usually own?

    There is no standard percentage. Ownership depends on the founders’ contributions, responsibilities, funding and the company’s future financing plans.

    Is a low founder salary a red flag?

    Not necessarily. A low salary can be normal when a startup is conserving cash. It becomes important to understand the complete compensation arrangement, including equity, expenses and the expected timeline for reviewing salary.

    Who earns more, CEO or founder?

    It depends on the circumstances. A founder may receive substantial value through equity while taking a modest salary. A professional CEO may receive a higher cash compensation package. Salary and ownership should therefore be compared separately.

    What is a top 1% salary in India?

    The answer depends on the dataset and whether the measure refers to individual earnings, household income, salary or total income. A 2025 Institute for Competitiveness report based on PLFS data for 2023–24 stated that the top 1% income threshold was at least ₹75,000 per month. This should not be treated as a universal definition of a “top 1% salary” because income measures and datasets differ.

    What is Narendra Modi’s monthly salary?

    The Prime Minister’s remuneration is governed by the Salaries and Allowances of Ministers Act, 1952 and related rules. Official government information states that the Prime Minister’s pay and allowances are provided under that framework. Public figures commonly reported for the Prime Minister’s monthly remuneration can include salary and allowances, so figures should not be confused with basic salary alone.

    The official Salaries and Allowances of Ministers Act, 1952 is the appropriate legal reference.

    Who earns ₹48 crore per day?

    A widely circulated 2025 claim stated that Indian-origin technology executive Jagdeep Singh was earning an amount equivalent to about ₹48 crore per day. However, the figure was derived from a reported annual compensation figure and was widely described in media coverage as an exceptional stock-option and performance-linked package rather than an ordinary daily salary.

    Reports also noted that the compensation figure was not independently verified by all outlets. Therefore, it should not be presented as a normal CEO salary or as a guaranteed cash payment of ₹48 crore every day.

    Who is the richest CEO in India?

    There is no single reliable answer without defining what “richest” means. Net worth, founder ownership, salary and annual compensation are different measurements.

    A founder-CEO may have a large net worth because they own shares in a company. That does not mean they receive the same amount as salary.

    Which job pays ₹1 crore per month?

    ₹1 crore per month is an exceptionally high level of compensation. It is not a standard salary attached to one particular job. Such figures can arise in senior executive roles, investment management, entrepreneurship or performance-linked compensation, but they vary substantially.

    Who is the youngest CEO ever?

    Claims about the “youngest CEO” depend on the definition being used. Some lists include children who became CEOs of family businesses or small ventures, while others refer to CEOs of established companies. Therefore, age alone does not provide a meaningful comparison of executive responsibility.

    What should you do about a toxic CEO?

    The appropriate response depends on the company’s governance structure and the conduct involved. Founders or directors should document serious issues, review the company’s governing documents and use the appropriate internal escalation process.

    Where the issue involves potential misconduct, employment disputes, shareholder rights or corporate governance, professional legal advice may be appropriate.

    What are 10 signs of a toxic manager?

    Common warning signs may include:

    1. Micromanaging employees excessively
    2. Consistently shifting blame
    3. Ignoring reasonable feedback
    4. Favouritism or unfair treatment
    5. Publicly humiliating team members
    6. Creating unreasonable or constantly changing expectations
    7. Refusing to accept responsibility for mistakes
    8. Using intimidation instead of constructive management
    9. Withholding important information unnecessarily
    10. Creating a consistently unhealthy working environment

    Final takeaway: why founders should put agreements in writing

    A founders agreement is not about assuming that a business relationship will fail. It is about deciding important issues while the founders are still aligned.

    Ownership, responsibilities, salary, intellectual property, decision-making, vesting and founder exits are much easier to discuss before a disagreement occurs.

    For Indian startups, the agreement should also be coordinated with the company’s constitutional documents and other contracts. A carefully drafted document can provide clarity without trying to replace mandatory legal requirements.

    Founders should review the arrangement whenever there is a major change, such as a new investor, new co-founder, significant change in ownership or change in the business structure.

    Need help preparing your founders agreement?

    If you are starting a business with one or more co-founders, documenting your arrangement early can help reduce uncertainty later. Lawizer provides business agreement and legal documentation services, including Co-Founder Agreements, IP assignment and other startup documentation.

    If your business is still being established, you can also explore Private Limited Company registration, GST registration, trademark registration and annual compliance support.

    For founders who want to discuss their specific circumstances, consult Lawizer for professional legal documentation support before signing an agreement.

    Important: This article provides general legal information for Indian founders. It is not a substitute for legal advice on a specific agreement, company structure or dispute.

  • Shareholder Agreement Basics

    Shareholder Agreement Basics

    shareholder agreement basics: India Guide

    A clear understanding of shareholder agreement basics can help Indian founders avoid disputes over ownership, voting, management, share transfers and exits. A Shareholders’ Agreement (SHA) sets out agreed rights and obligations between shareholders and can provide a practical framework for running a company when more than one person owns it.

    For founders, the value of an SHA is often most obvious when circumstances change. A co-founder may want to leave, a new investor may join, shareholders may disagree about a major decision, or someone may want to sell their shares. A well-drafted agreement can make these situations easier to manage.

    This guide explains the key concepts in simple language, with a focus on Indian companies and small businesses.

    shareholder agreement basics for Indian startups and founders

    What Is a Shareholders’ Agreement?

    A Shareholders’ Agreement is a contract between some or all of the shareholders of a company. It records how the shareholders will exercise certain rights, make decisions and deal with events such as share transfers, founder exits and disputes.

    An SHA can be particularly useful for a private company where a small group of founders or investors needs clear rules for ownership and decision-making.

    It may cover matters such as:

    • Shareholding and ownership rights
    • Voting and decision-making
    • Appointment of directors
    • Reserved matters
    • Share transfer restrictions
    • Right of first refusal or similar transfer rights
    • Tag-along and drag-along rights
    • Founder vesting and exit arrangements
    • Confidentiality and intellectual property
    • Deadlock and dispute resolution

    An SHA should not be treated as a replacement for the Companies Act, 2013 or the company’s Articles of Association (AoA). It operates within the wider legal and constitutional framework of the company.

    Is a Shareholders’ Agreement Mandatory in India?

    There is no general rule under the Companies Act, 2013 requiring every Indian company to have a separate Shareholders’ Agreement. However, an SHA can be highly useful where there are multiple founders or investors.

    Without a written agreement, shareholders may have to rely on the company’s constitutional documents, applicable law and evidence of their other arrangements. That can leave important commercial questions unclear.

    Founders can also review Lawizer’s guide to important Shareholders’ Agreement clauses for a more detailed discussion of common SHA provisions.

    Shareholders’ Agreement vs Articles of Association

    The Articles of Association are the company’s internal rules and form part of its constitutional framework. A Shareholders’ Agreement is a private contract between the relevant parties.

    The distinction matters because an SHA should not contain provisions that conflict with mandatory company law or the company’s constitutional documents.

    The Supreme Court’s decision in V.B. Rangaraj v. V.B. Gopalakrishnan is an important authority on restrictions concerning share transfers and the Articles of Association. The practical lesson for founders is simple: important restrictions intended to operate at company level should be properly reflected in the company’s constitutional documents where required.

    shareholder agreement basics: What Should an SHA Include?

    The exact terms depend on the company, its shareholders and its funding arrangements. However, several areas commonly deserve careful attention.

    1. Shareholding and Ownership

    The agreement should clearly record the current ownership structure. This can include the number and class of shares held by each shareholder and, where relevant, the rights attached to those shares.

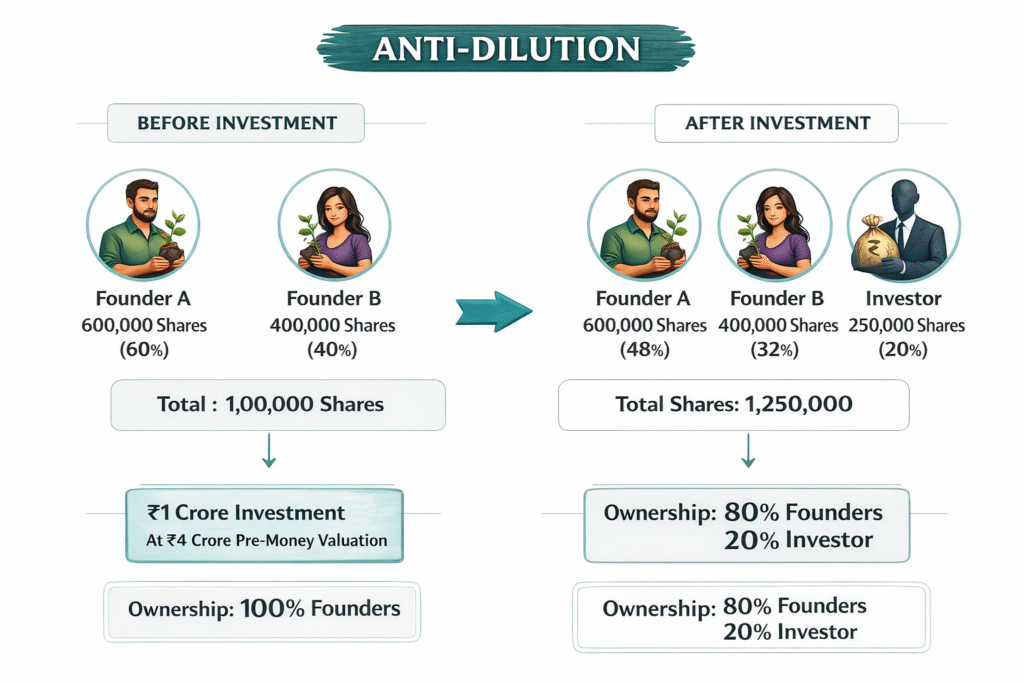
    It is also sensible to consider what happens if the company issues additional shares. A future funding round can change existing ownership percentages, so shareholders should understand how new capital may affect their interests.

    2. Voting Rights and Decision-Making

    An SHA can establish how shareholders will vote on important matters. It may also identify decisions that require a higher approval threshold than ordinary business decisions.

    For example, reserved matters may include:

    • Changing the Articles of Association
    • Issuing new shares
    • Taking on significant debt
    • Acquiring another business
    • Changing the company’s main business
    • Approving a major transaction
    • Winding up the company

    The exact list and approval threshold should be tailored to the company rather than copied from another business.

    3. Board and Management Rights

    Shareholders own shares, while directors generally manage the company through the Board subject to the Companies Act, the Articles and the company’s governance arrangements.

    An SHA may specify who can nominate directors, how board decisions are made and what happens if shareholders disagree with the Board.

    This distinction is especially important for founders. Owning a particular percentage of shares does not automatically mean that the shareholder personally manages every aspect of the company.

    4. Share Transfer Restrictions

    A shareholder may eventually want to sell or transfer shares. An SHA can establish procedures for such transfers.

    Common mechanisms include:

    • Right of First Refusal (ROFR)
    • Right of First Offer (ROFO)
    • Pre-emption rights
    • Restrictions on transfers to competitors
    • Consent requirements

    These provisions can help existing shareholders manage who may become a shareholder and protect the company from an unwanted transfer.

    5. Tag-Along and Drag-Along Rights

    Tag-along rights generally protect minority shareholders when a majority shareholder sells shares to a third party. Subject to the agreed terms, minority shareholders may have the right to participate in the sale on similar terms.

    Drag-along rights work differently. They can allow qualifying shareholders to require other shareholders to participate in a sale, subject to the agreement and applicable law.

    Both provisions should be drafted carefully because they can significantly affect a shareholder’s exit rights.

    6. Founder Vesting and Exit Provisions

    Founders may hold substantial equity from the beginning. A vesting arrangement can help address the risk of a founder leaving soon after incorporation while retaining a large stake.
    Founder arrangements may address:

    • Vesting periods
    • Cliff periods
    • Good leaver and bad leaver situations
    • Treatment of unvested shares
    • Buyback or transfer mechanisms where legally permissible

    These provisions should be structured carefully because Indian company law, contract law, securities rules and tax considerations can affect how an arrangement is implemented.

    Lawizer’s guide to founder vesting schedules in India explains why founders should address equity vesting before a dispute arises.

    7. Confidentiality and Intellectual Property

    An SHA can contain confidentiality obligations and provisions dealing with intellectual property. However, founders should not assume that a general SHA clause automatically handles every IP issue.

    For software, brands, designs, documents and other intellectual property, a separate assignment arrangement may also be appropriate.

    Businesses can also consider a separate intellectual property assignment agreement and NDA for protecting confidential information.

    8. Dispute Resolution

    Shareholder disputes can become expensive when there is no agreed process for resolving them. An SHA can establish a sequence such as negotiation, mediation and arbitration, depending on the parties’ requirements.

    The agreement should clearly identify the governing law and the dispute-resolution mechanism. Arbitration clauses should also be drafted consistently with the Arbitration and Conciliation Act, 1996.

    What Are the 7 Rules of a Contract?

    There is no single statutory list called the “seven rules of a contract” in Indian law. However, several core principles are useful when considering whether an SHA is legally sound.

    1. Offer and Acceptance

    The parties should reach an agreement through a valid offer and acceptance.

    2. Intention to Create Legal Relations

    The parties should intend their arrangement to have legal consequences.

    3. Lawful Consideration

    Where consideration is required, it must satisfy the requirements of Indian contract law.

    4. Capacity to Contract

    The parties must have legal capacity to enter into the agreement.

    5. Free Consent

    Consent should not be obtained through coercion, undue influence, fraud or misrepresentation.

    6. Lawful Object

    The purpose of the agreement must be lawful.

    7. Certainty and Enforceability

    The terms should be sufficiently clear and should not be contrary to applicable law.

    Section 10 of the Indian Contract Act, 1872 is particularly important because it identifies the requirements for agreements to qualify as contracts, including free consent, competent parties, lawful consideration and a lawful object.

    What Are the 5 Main Elements of a Contract?

    People often search for five main elements of a contract. In practical terms, an Indian business agreement should be examined for several connected requirements:

    • Agreement between the parties
    • Competency of the parties
    • Free consent
    • Lawful consideration and object
    • Terms that are not expressly void and can be legally enforced

    These requirements should be considered alongside the specific law applicable to the transaction.

    What Are the Five Principles of Contract Law?

    For a founder, the five principles can be simplified as consent, capacity, legality, consideration and enforceability.

    The Indian Contract Act, 1872 addresses these concepts through provisions dealing with contracts, competency, consent, lawful consideration and lawful objects.

    For business agreements, clarity is equally important. A clause that looks commercially attractive may still create problems if it is uncertain, unlawful or inconsistent with mandatory legislation.

    What Are the Three Stages of a Contract?

    1. Formation

    The parties negotiate and agree on the terms.

    2. Performance

    The parties perform the obligations they accepted under the contract.

    3. Discharge or Termination

    The contract eventually ends through performance, expiry, termination, agreement or another legally recognised mechanism.

    For an SHA, these stages may occur over several years because the agreement can continue while the shareholders remain invested in the company.

    Can a 50% Shareholder Remove a Director?

    Owning 50% of the shares does not automatically mean that a shareholder can personally remove a director whenever they choose.

    For companies governed by the Companies Act, 2013, director removal is subject to statutory procedure. Section 169 deals with removal of directors and generally provides for removal by ordinary resolution, subject to the section’s requirements and exceptions.

    A shareholder holding exactly 50% may also face a deadlock if another shareholder holds the other 50%. The outcome can depend on the company’s Articles, voting rights, board structure and any valid contractual arrangements.

    This is why a good SHA should address deadlocks before they happen.

    Who Is More Powerful: a Director or a Shareholder?

    There is no simple answer because directors and shareholders exercise different powers.

    What Shareholders Do

    • Hold ownership interests in the company
    • Exercise voting rights attached to their shares
    • Participate in shareholder resolutions
    • Exercise rights provided by company law and the Articles

    What Directors Do

    • Participate in Board decision-making
    • Oversee company management
    • Exercise powers assigned to the Board
    • Comply with statutory duties

    A shareholder can therefore have substantial ownership without directly running daily operations. Similarly, a director may have significant management authority without owning a controlling percentage of the company.

    Can a Company Director Just Quit and Walk Away?

    A director can resign, but resignation should be handled formally rather than by simply stopping work.

    Section 168 of the Companies Act, 2013 provides that a director may resign by giving written notice to the company. The section also sets out the effective date and continuing liability for offences committed during the director’s tenure.

    Resigning as a director is also different from selling shares. A person can cease to be a director while continuing to own shares in the company.

    Lawizer’s director resignation service can be useful when a company needs assistance with the formal process.

    What Should I Not Say When Resigning?

    A resignation letter should normally be factual, professional and clear.

    Avoid unnecessary accusations, threats or statements that could create unintended legal consequences. If there is a genuine dispute, it may be better to take legal advice before putting detailed allegations into a resignation letter.

    Also avoid suggesting that resignation automatically cancels your shareholding. Directorship and share ownership are separate matters.

    How Do I Resign in a Classy Way?

    A professional resignation usually contains:

    • A clear statement that you are resigning as a director
    • The intended effective date
    • A brief and professional explanation, if appropriate
    • A willingness to assist with a reasonable handover
    • A request for the company to complete the required records and filings

    Keeping the letter concise can help avoid unnecessary conflict.

    What Is Silent Quitting?

    “Silent quitting” is a workplace phrase describing a person doing only the work they are required to do rather than going beyond their formal responsibilities.

    It is not the same as legally resigning as a company director.

    A director who simply stops participating may still have statutory or contractual obligations. If the person intends to leave the Board, formal resignation should be considered instead.

    What Is the Format of a Shareholders’ Agreement?

    There is no single mandatory format for every SHA. A practical agreement may contain the following sections:

    1. Title and date
    2. Details of the parties
    3. Background and purpose
    4. Definitions
    5. Shareholding structure
    6. Shareholder rights and obligations
    7. Board and governance provisions
    8. Reserved matters
    9. Share transfer restrictions
    10. ROFR, ROFO or pre-emption provisions
    11. Tag-along and drag-along provisions
    12. Founder vesting and exit provisions
    13. Confidentiality and intellectual property
    14. Dispute resolution
    15. Amendment and termination
    16. Signatures and schedules

    The final document should be customised to the company’s actual ownership structure and commercial arrangements.

    What Are the Three Types of Shareholders?

    There is no universal statutory classification called the “three types of shareholders”. For practical business discussions, shareholders may be described as:

    Founders or Promoter Shareholders

    These are the people who establish or promote the business and commonly hold significant ownership.

    Investor Shareholders

    These shareholders invest capital and may receive negotiated voting, information, governance or exit rights.

    Minority Shareholders

    These shareholders hold a smaller percentage and may need specific protections, particularly regarding transfers, information and major transactions.

    The exact rights of any shareholder depend on the class of shares, the Articles, applicable law and valid agreements.

    What Is the “10 Shareholder Rule”?

    The phrase “10 shareholder rule” can be misleading because Indian company law does not have one universal rule stating that every company can have only ten shareholders.

    Depending on the context, people may actually be referring to a percentage-based voting or requisition requirement, a company’s membership rules or a rule from another jurisdiction.

    For example, the Companies Act contains provisions where specific percentages of members or voting rights matter. Therefore, founders should identify the exact provision before relying on a “10 shareholder rule”.

    The type of company also matters. A private company, public company and One Person Company do not have identical membership structures.

    What Are the Five Types of Shares?

    There is no universal statutory list of exactly five “types of shares” that applies in every Indian company context.

    For founders, the important distinction is often between equity shares and preference shares, along with the different rights or structures that may apply to securities issued by a company.

    Companies can also issue securities through mechanisms such as rights issues, bonus issues or employee stock option arrangements. These are not simply five different classes of shares.

    Before issuing or transferring shares, a company should review its Articles, capital structure and the applicable provisions of the Companies Act.

    What Are C Shares?

    “C shares” is not a universal standard category of shares under Indian company law. The term can have different meanings depending on the company, jurisdiction or transaction documents.

    If an SHA or investment document refers to “C shares”, the parties should read the definition and the rights attached to that particular class rather than assuming that every C share has the same legal characteristics.

    What Are the Top 10 Shares?

    “Top 10 shares” is generally an investment-market search query rather than a shareholder-agreement concept.

    The answer depends on factors such as the market, investment horizon, valuation, risk tolerance and financial performance. It should not be confused with ownership rights under an SHA.

    An Indian founder deciding how to structure a private company should focus on the company’s capital structure and shareholder rights rather than public-market stock rankings.

    Shareholder Agreement Basics: Common Mistakes to Avoid

    Even when founders have an SHA, the document may fail to protect them if important issues were overlooked.

    Using a Generic Template

    A template may provide a useful starting point, but every company has a different cap table, governance structure and commercial relationship.

    Ignoring the Articles of Association

    An SHA should be reviewed alongside the Articles. If the documents do not work together, enforcement problems can arise.

    Leaving Share Transfers Unclear

    Founders should understand what happens if someone wants to sell shares, transfer them to a family member or transfer them to an outside party.

    Ignoring Deadlock

    A 50–50 ownership structure can create a serious governance problem if both sides disagree. The SHA should establish a practical route for resolving a deadlock.

    Forgetting Future Funding

    New shares can dilute existing shareholders. The agreement should address how future fundraising and ownership changes will be handled.

    Not Planning for Founder Exit

    Founders should discuss what happens if someone resigns, becomes unable to continue, breaches the agreement or wants to sell their stake.

    Shareholders’ Agreement vs Founders’ Agreement

    A founders’ agreement generally focuses on the relationship between the founding team. It may address roles, equity, vesting, intellectual property, responsibilities and founder exits.

    A Shareholders’ Agreement generally governs the relationship between shareholders and can become particularly important when external investors join the company.

    The two documents should not contradict one another. Lawizer’s guide to founders’ agreements for Indian startups explains the issues founders should consider at an early stage.

    Founders preparing for incorporation can also explore Lawizer’s Private Limited Company registration guide.

    Frequently Asked Questions About Shareholder Agreement Basics

    What are the 5 main elements of a contract?

    The practical elements include agreement, competent parties, free consent, lawful consideration and lawful object, together with the requirement that the agreement is not expressly void and is legally enforceable.

    What are the five principles of contract law?

    For a simple explanation, focus on consent, capacity, legality, consideration and enforceability. The exact legal requirements depend on the applicable statute and facts.

    What are the 7 rules of a contract?

    There is no single statutory list of seven rules. The commonly discussed principles include offer and acceptance, intention, capacity, free consent, lawful consideration, lawful object and certainty.

    What are the three stages of a contract?

    The three broad stages are formation, performance and discharge or termination.

    Can a 50% shareholder remove a director?

    Not automatically. Director removal must follow the applicable statutory procedure, the company’s Articles and relevant voting requirements.

    Who has more control, a director or a shareholder?

    They exercise different powers. Shareholders exercise ownership and voting rights, while directors exercise Board and management powers subject to law and the company’s governance documents.

    Can a company director just quit and walk away?

    A director can resign by following the applicable legal procedure. However, resignation does not automatically dispose of any shares the person owns or remove other contractual obligations.

    What should I not say when resigning?

    Avoid unnecessary accusations, threats or admissions. Keep the resignation professional and seek legal advice before making detailed allegations if there is an ongoing dispute.

    How do I resign in a classy way?

    Give a clear written resignation, state the effective date, offer a reasonable handover and maintain a professional tone.

    What is silent quitting?

    Silent quitting is a workplace phrase. It is not a legal method of resigning as a company director.

    What is the format of a shareholders’ agreement?

    An SHA commonly contains parties, definitions, shareholding, governance, voting, reserved matters, transfers, exit provisions, confidentiality, IP, dispute resolution and termination provisions.

    What are the three types of shareholders?

    “Three types” is not a universal statutory classification. In business discussions, founders, investors and minority shareholders are commonly used descriptive categories.

    What is the 10 shareholder rule?

    There is no universal Indian rule limiting every company to ten shareholders. The correct answer depends on the provision and type of company being discussed.

    What are the five types of shares?

    Indian company law does not provide one universal list of exactly five share types. Equity and preference shares are important categories, while other terms may describe rights, classes or methods of issue.

    What are C shares?

    C shares do not have one universal meaning under Indian company law. Their rights depend on the company’s documents and the terms of the particular issue.

    What are the top 10 shares?

    This is generally a stock-market question rather than a shareholder-agreement question. The appropriate answer depends on the market, valuation, risk and investment objectives.

    Final Checklist for Indian Founders

    Before signing or updating an SHA, review the following:

    • Is the current shareholding accurately recorded?
    • Are voting rights clear?
    • Are reserved matters identified?
    • Are share-transfer restrictions clear?
    • Are ROFR or similar rights properly defined?
    • Are tag-along and drag-along provisions appropriate?
    • Are founder exit and vesting provisions clear?
    • Is intellectual property properly protected?
    • Are confidentiality obligations appropriate?
    • Is there a workable deadlock mechanism?
    • Does the SHA align with the Articles of Association?
    • Have all shareholders understood the document before signing?

    Companies should also keep their broader legal and compliance structure organised. Lawizer provides support for Private Limited Company registration, GST registration, trademark registration and annual compliance.

    Conclusion: Why a Good Shareholders’ Agreement Matters

    A Shareholders’ Agreement is not simply a document to sign when an investor asks for one. It can help founders establish clear expectations about ownership, voting, governance, transfers, exits and disputes.

    The most useful time to resolve shareholder questions is before a disagreement occurs. Once relationships have broken down, changing the agreed rules can become much harder.

    If your company is being incorporated, raising investment, changing its ownership structure or dealing with a founder exit, review the SHA alongside the Articles of Association and the Companies Act.

    Need help with your shareholder agreement? Lawizer can help founders and businesses prepare, review and organise important legal documents with professional support.

    Consult Lawizer for business legal documentation and get guidance suited to your company’s structure and requirements.

    Tags

    • shareholder agreement basics
    • shareholders agreement India
    • shareholders agreement for startups
    • shareholder rights India
    • founders agreement
    • company law India
    • Companies Act 2013
    • share transfer agreement
    • director rights India
    • startup legal documents
    • corporate governance India
    • startup compliance India
  • Business Licenses Every Startup Needs

    Business Licenses Every Startup Needs

    Business Licenses Every Startup Needs in India

    business licenses every startup needs in India checklist
    Business licence and compliance checklist for Indian startups.

    Starting a business in India involves more than registering a company and opening a bank account. The business licenses every startup needs depend on the business structure, industry, location, turnover, employees and activities of the startup. A food business, SaaS company, manufacturer and online retailer can have very different legal requirements.

    There is also an important distinction between a business registration, tax registration, licence and permit. Incorporating a Private Limited Company, for example, does not automatically give the company permission to carry out every regulated activity. Similarly, GST registration is a tax registration, while an FSSAI licence is relevant to food businesses.

    This guide explains the main registrations, licences and approvals Indian founders should evaluate before launching. It also covers industry-specific permissions, online businesses, MSME registration, Startup India, trademark protection and ongoing compliance.

    What Are the Business Licenses Every Startup Needs?

    There is no single licence package that applies to every Indian startup. The correct checklist depends on what the business does and where it operates.

    Most founders should review these categories:

    • Business or entity registration
    • PAN and TAN requirements
    • GST registration, where applicable
    • MSME Udyam registration
    • Shops and Establishments requirements
    • Local trade licences and municipal permissions
    • Industry-specific licences
    • Import and export registrations
    • Employment and labour registrations
    • Intellectual property protection

    Not every item on this list is mandatory for every startup. The goal is to identify which requirements apply to your specific business before you begin commercial operations.

    Business Registration Is the First Legal Step

    Before asking which licence you need, decide how the business will be structured. Common options include a sole proprietorship, partnership firm, LLP, One Person Company and Private Limited Company.

    Private Limited Company

    A Private Limited Company is commonly considered by startups planning to raise equity investment, issue shares or build a scalable corporate structure. It is a separate legal entity and offers limited liability, subject to applicable law.

    Founders can review Lawizer’s Private Limited Company registration service when evaluating this structure.

    Limited Liability Partnership

    An LLP combines partnership-style flexibility with limited liability protection. It can be suitable for professional firms, service businesses and founders who do not need the conventional share structure of a company.

    See Lawizer’s LLP registration service for more information.

    One Person Company

    An OPC can be considered by an eligible solo entrepreneur who wants a corporate structure with a single member. The suitability of an OPC depends on the founder’s plans, compliance requirements and future growth.

    Lawizer also provides One Person Company registration assistance.

    GST Registration: One of the Most Important Startup Tax Registrations

    GST is not a general business licence. It is a tax registration that becomes relevant when the business falls within the registration requirements under GST law.

    For many businesses, the commonly applicable threshold is based on aggregate turnover, with different thresholds and exceptions depending on the nature of supply, state and applicable notifications. Certain categories can also have registration obligations regardless of ordinary turnover thresholds.

    Therefore, founders should not assume that incorporation automatically means GST registration is mandatory. They should assess turnover, taxable supplies, location and the nature of their transactions.

    Lawizer’s GST registration service can help founders organise the registration process.

    For a deeper explanation, read GST Registration for Startups: Who Needs It and How to Apply.

    When Should a Startup Check GST Registration?

    • When turnover approaches the applicable registration threshold.
    • When the business makes transactions that trigger compulsory registration.
    • When the business model involves e-commerce or other specified categories.
    • When the startup begins making taxable supplies in circumstances where registration is required.
    • When the founder wants to evaluate voluntary registration for commercial reasons.

    GST rules can change through legislation, notifications and government decisions. Always check the current position before relying on a particular threshold.

    MSME Udyam Registration for Eligible Startups and Small Businesses

    Udyam registration is different from incorporation and GST registration. It is the government’s MSME registration mechanism for eligible enterprises.

    It is generally not a universal licence required before every startup can begin operations. However, eligible businesses may find Udyam registration useful for accessing schemes, credit-related benefits, government procurement opportunities and protections available under the MSME framework.

    The official Udyam portal states that registration is free and does not require renewal. The current MSME classification is based on investment and turnover criteria, so founders should check the latest government thresholds before applying.

    You can also review Lawizer’s MSME Udyam registration service.

    For more detail, read Udyam Registration: MSME Benefits, Eligibility & How to Apply Online.

    Shops and Establishments Registration

    State-specific Shops and Establishments laws can impose registration, working-condition and record-keeping requirements on certain commercial establishments. The exact rules differ from one state to another.

    A startup operating from a physical office, shop, commercial establishment or similar premises should therefore check the law applicable in its state.

    This is particularly important for founders who assume that company incorporation automatically covers local establishment requirements. It usually does not.

    Do Startups Need a Local Trade Licence?

    A local trade licence may be required by the relevant municipal or local authority depending on the business activity and premises. The requirement is therefore not identical across India.

    Restaurants, shops, workshops, manufacturing units and other establishments may face different local requirements. The location of the premises can also affect which authority is responsible.

    Before signing a long-term commercial lease, founders should check whether their intended business activity is permitted at the premises and whether additional local permissions are required.

    Industry-Specific Business Licences Every Startup Needs to Check

    The most important lesson for founders is that regulated industries can require additional licences beyond normal business registration and tax formalities.

    FSSAI Registration or Licence for Food Businesses

    Food businesses are regulated by the Food Safety and Standards Authority of India. Food Business Operators generally need the appropriate FSSAI registration or licence for their activity.

    This can affect restaurants, cloud kitchens, food manufacturers, processors, distributors, retailers and other food-related businesses.

    The exact category depends on factors such as the nature and scale of the food business. Founders should therefore check the applicable FSSAI category rather than choosing a licence solely based on the business name.

    Importer Exporter Code for Import and Export

    Businesses involved in import or export activities should assess whether they require an Importer Exporter Code, commonly called an IEC.

    DGFT rules generally require an IEC for undertaking import or export activities, subject to applicable exemptions. The IEC process is separate from ordinary company incorporation.

    This matters for manufacturers buying components from overseas, exporters selling Indian products abroad and businesses that regularly conduct cross-border trade.

    Environmental and Pollution-Control Approvals

    Manufacturing, processing, construction and other activities may require permissions from the relevant pollution-control or environmental authorities.

    The requirements can depend on the industry, location, scale and environmental impact. A startup should identify these requirements before establishing a factory or production facility.

    Fire Safety Approvals

    Certain commercial premises may require fire-safety approvals or a Fire NOC depending on local rules, building use, occupancy and other factors.

    Do not assume that the landlord’s existing approval automatically covers your particular business activity. Confirm the position with the relevant local authority.

    Legal Metrology Requirements

    Businesses selling packaged products may need to consider Legal Metrology requirements relating to declarations, quantities, weights, measures and packaged commodities.

    This can be particularly relevant to D2C brands, manufacturers, importers and e-commerce sellers.

    Sector-Specific Financial, Healthcare and Other Licences

    Some sectors have dedicated regulators and licensing frameworks. Financial services, healthcare, pharmaceuticals, education, insurance, telecom and other regulated industries can require approvals beyond the standard startup checklist.

    For such businesses, founders should conduct a sector-specific legal review before accepting customers or launching the regulated service.

    What Licences Does an Online Startup Need?

    An online business is not automatically exempt from regulatory requirements. The internet changes the delivery channel, but it does not necessarily remove the underlying legal obligations.

    For example, an online food business may still need FSSAI compliance. An e-commerce seller may need to assess GST, consumer protection and Legal Metrology requirements. An online business handling personal data should also review its privacy and data-protection obligations.

    Lawizer provides Privacy Policy and Terms of Use documentation for businesses that need appropriate website or application documents.

    Online startups should also consider trademark registration before investing heavily in a brand.

    Trademark Registration Is Not a Business Licence

    A trademark is not a licence to operate a business. Instead, trademark registration protects a brand identifier such as a name, logo or other distinctive mark, subject to the applicable legal requirements.

    Registering a trademark can help a startup protect the identity it is building. It can also become an important business asset when the company expands, raises investment or licenses its brand.

    Lawizer’s Trademark Registration service can assist founders with the filing process.

    You can also read Trademark Registration in India: A No-Jargon Guide for First-Time Founders.

    Startup India Registration: Is It Mandatory?

    DPIIT recognition under the Startup India initiative is not the same as incorporating a business. It is also not a universal licence that every startup must obtain before operating.

    Eligible startups can consider DPIIT recognition to access benefits available under the Startup India framework, subject to the relevant eligibility conditions and separate requirements for individual benefits.

    Founders interested in recognition can review Lawizer’s Startup India registration assistance.

    What Are the Business Licenses Every Startup Needs Before Launch?

    A practical pre-launch checklist can help founders avoid missing an important requirement.

    • Choose the appropriate business structure.
    • Complete company, LLP or other applicable registration.
    • Obtain or confirm PAN and TAN requirements.
    • Check GST applicability.
    • Evaluate Udyam registration if eligible.
    • Check Shops and Establishments requirements.
    • Check local trade licence requirements.
    • Identify industry-specific licences.
    • Check import/export requirements if relevant.
    • Review employee and labour-law registrations when hiring.
    • Protect the brand through trademark registration.
    • Prepare appropriate customer, vendor and founder contracts.
    • Set up a system for recurring tax and corporate compliance.

    Business Licences vs Registrations vs Permits

    These terms are often used interchangeably, but they can serve different purposes.

    Registration

    A registration records a business, taxpayer or enterprise with the relevant authority. Company incorporation and Udyam registration are examples of different types of registration.

    Licence

    A licence generally gives permission to conduct a regulated activity subject to specified conditions. Food businesses are a common example.

    Permit or NOC

    A permit or No Objection Certificate may relate to a particular activity, premises, safety requirement or local approval.

    This distinction matters because obtaining one registration does not automatically satisfy every other regulatory requirement.

    What Happens If a Startup Operates Without a Required Licence?

    The consequences depend on the specific law and the nature of the violation. Possible consequences can include notices, monetary penalties, suspension of operations, cancellation of a registration, difficulty continuing the regulated activity and, in serious cases, prosecution.

    There can also be commercial consequences. Investors may identify compliance gaps during due diligence. Customers may ask for regulatory certificates. Banks, marketplaces or enterprise clients may require evidence of registration before onboarding the business.

    That is why compliance should be treated as part of business planning rather than as paperwork to complete after launch.

    How to Identify the Right Licence Checklist for Your Startup

    Step 1: Identify the Business Activity

    Start with what you actually sell or provide. A software company, restaurant, manufacturer, consultant and pharmaceutical distributor should not use the same checklist.

    Step 2: Identify the Business Structure

    Determine whether you will operate as a proprietorship, partnership, LLP, OPC or company. The structure affects registration and continuing compliance.

    Step 3: Check Your State and Location

    Review state and municipal requirements for the location where the business operates. This is especially important for physical premises.

    Step 4: Check Tax Obligations

    Assess GST, TDS, income-tax and other applicable obligations. Tax registrations depend on the nature of the business and transactions.

    Step 5: Check Sector Regulations

    Ask whether your industry has a dedicated regulator. If yes, identify its registration, licence and reporting requirements before launch.

    Step 6: Review Ongoing Compliance

    Some registrations are only the beginning. Companies and LLPs have recurring filing obligations, while tax and sector-specific registrations can involve regular returns, renewals or updates.

    Lawizer’s annual compliance services can help businesses organise recurring corporate compliance.

    What Are the 7 Stages of a Startup?

    The commonly discussed seven stages are:

    1. Ideation
    2. Validation
    3. Business formation
    4. Launch
    5. Early growth
    6. Scaling
    7. Maturity, acquisition or exit

    Legal requirements can change as the startup moves through these stages. A founder may need only basic registrations initially but later require employment, intellectual-property, fundraising, data, sector or corporate compliance support.

    What Are the 7 Types of Business With Examples?

    There is no single statutory list of exactly seven business types. For practical purposes, businesses can be grouped into categories such as:

    • Retail: shops selling products directly to consumers.
    • Wholesale: businesses supplying products to other businesses.
    • Manufacturing: businesses producing physical goods.
    • Services: consultants, agencies and professional firms.
    • E-commerce: businesses selling through digital channels.
    • Technology/SaaS: software and technology platforms.
    • Import/export: businesses involved in international trade.

    The type of business often determines which regulatory requirements need to be investigated.

    What Are the 7 Main Points in a Business Plan?

    A practical business plan can include:

    1. Executive summary
    2. Business description
    3. Market analysis
    4. Products or services
    5. Marketing and sales strategy
    6. Operations and management plan
    7. Financial plan

    Founders should include legal and compliance costs in the operations and financial sections. This helps prevent unexpected expenses after launch.

    Frequently Asked Questions About Business Licences

    What are all the licences required to start a business in India?

    There is no universal list. Requirements depend on the business structure, state, location, turnover, employees and industry. Common areas include entity registration, GST where applicable, local registrations and industry-specific licences.

    What are the 10 types of business?

    There is no universal legal list of ten types. Common categories include retail, wholesale, manufacturing, services, e-commerce, technology, professional services, franchising, import/export and subscription businesses.

    What are the three types of licensing?

    There is no universal legal classification of exactly three types. In business discussions, licensing can refer to government or regulatory licences, intellectual-property licensing and commercial licensing arrangements.

    How many types of licences are there?

    There is no fixed number applicable to every Indian business. Licences can be created under central, state and local laws and can vary by industry and activity.

    What is the CC BY 4.0 licence?

    CC BY 4.0 is a Creative Commons licence that generally allows others to share and adapt licensed material, including for commercial purposes, provided they follow the licence conditions and give appropriate attribution.

    Is CC BY 4.0 free for commercial use?

    Generally, yes. CC BY 4.0 permits commercial use, subject to its attribution and other licence conditions. Always check that the material is actually offered under CC BY 4.0 and that third-party rights do not create additional restrictions.

    What are the six types of Creative Commons licences?

    The six main Creative Commons licences are CC BY, CC BY-SA, CC BY-ND, CC BY-NC, CC BY-NC-SA and CC BY-NC-ND. Their differences mainly concern attribution, commercial use and whether adaptations can be shared under the same or modified terms.

    What is the 80/20 rule for startups?

    The 80/20 rule, or Pareto principle, is a business-management concept rather than a startup law. It suggests that a relatively small number of inputs can produce a large share of results. Founders can use it to identify their most valuable customers, products and activities.

    Why do 90% of startups fail?

    The claim that 90% of startups fail should not be treated as a universal Indian statistic. Startup failure varies by industry, dataset and definition. Common risks include poor product-market fit, cash-flow problems, weak unit economics, founder disputes and regulatory failures.

    What business is easiest to start?

    Service businesses can often have lower initial capital requirements than manufacturing or inventory-heavy businesses. However, the easiest business depends on your skills, capital, customers, location and applicable regulations.

    What business has a 90% success rate?

    No general business category can reliably guarantee a 90% success rate. Business success depends on execution, demand, capital, competition, management and many other factors.

    What business will boom in 2026?

    Areas attracting attention include technology-enabled services, AI-related solutions, digital commerce, specialised professional services and businesses supporting India’s expanding digital economy. However, no sector is guaranteed to boom, so founders should validate actual customer demand.

    Who are Gen Z entrepreneurs?

    Gen Z entrepreneurs are founders from Generation Z who build businesses using approaches shaped by digital platforms, social media, online communities and technology. Their businesses can range from creator-led brands to software, e-commerce and professional services.

    How can I earn ₹2 lakh per month in business?

    Start by separating revenue from profit. To earn ₹2 lakh in monthly profit, calculate your expected gross margin, operating costs, customer acquisition costs and required sales volume. Then work backwards to determine how many customers or transactions you need.

    What are the 7 pillars of business?

    A useful seven-pillar framework is strategy, finance, operations, marketing, sales, people and legal/compliance. The exact framework varies, but these areas cover most of the core functions required to build a sustainable business.

    What are the 12 components of a business plan?

    A detailed business plan may include an executive summary, company description, problem and solution, market analysis, customer profile, competitive analysis, business model, marketing strategy, operations, management, financial projections and funding requirements.

    What are the 10 types of business plans?

    Common formats include startup plans, traditional plans, lean plans, strategic plans, operational plans, growth plans, expansion plans, feasibility plans, internal plans and contingency plans. The right format depends on the purpose of the document.

    What are the 7 key elements of a business plan?

    The seven key elements can be summarised as the executive summary, business description, market analysis, product or service strategy, marketing and sales plan, operations and management plan, and financial projections.

    Business Licences Every Startup Needs: Final Checklist

    Before launching, do not ask only whether your company is incorporated. Ask whether the business is legally ready to perform the specific activities it plans to undertake.

    • Choose the right business structure.
    • Complete the applicable business registration.
    • Confirm PAN and TAN requirements.
    • Check GST registration requirements.
    • Evaluate Udyam registration.
    • Check state Shops and Establishments requirements.
    • Check local trade licences.
    • Identify sector-specific licences.
    • Review FSSAI requirements if you operate a food business.
    • Check IEC requirements for import/export activities.
    • Review environmental, fire-safety and Legal Metrology requirements where relevant.
    • Protect your brand with trademark registration.
    • Prepare appropriate contracts and online business documents.
    • Set up a system for ongoing compliance and renewals.

    Get Help With Your Startup Compliance Checklist

    The right legal checklist depends on your business activity, structure, state, location and growth plans. A startup should therefore avoid copying another company’s licence list without checking whether the same rules actually apply.

    Lawizer helps Indian founders with company registration, LLP registration, GST registration, MSME Udyam registration, trademark registration, Startup India registration and ongoing annual compliance.

    If you are unsure which registrations, licences or permits apply to your startup, consult a qualified legal, tax or compliance professional before launching the regulated part of your business. Getting the checklist right early can help you avoid preventable penalties, delays and compliance gaps later.

    Ready to organise your startup’s legal setup? Explore Lawizer’s startup and business legal services and build a compliance checklist based on your actual business model.

  • How to sell trademark in India: A Legal Guide

    How to sell trademark in India: A Legal Guide

    How to sell trademark in India: A Legal Guide

    If you are wondering how to sell trademark rights in India, the process is generally possible through a legal assignment or transmission of the trademark. A trademark can be a valuable business asset, particularly when it has established goodwill, customer recognition and commercial value. However, selling a trademark is not simply a matter of agreeing on a price and handing over a brand name.

    The transaction should be properly documented, the ownership and status of the mark should be checked, and the transfer should be recorded with the Trade Marks Registry where required. The seller should also consider whether the transaction includes the goodwill associated with the business and whether any restrictions apply to the proposed assignment.

    This guide explains the process in practical terms for Indian founders and small-business owners, including trademark valuation, ownership transfer, assignment agreements, non-use risks and the difference between selling and licensing a trademark.

    If you are still building your brand, you can first explore trademark registration in India to understand how trademark ownership is established and protected.

    Can You Sell a Trademark in India?

    Yes. Under Indian trademark law, a registered trademark can generally be assigned or transmitted, subject to the provisions of the Trade Marks Act, 1999. The Act also recognises the assignment or transmission of unregistered trademarks, although the applicable legal requirements and practical considerations may differ.

    In simple terms, an assignment means transferring ownership of the trademark from one party to another. The person transferring the mark is commonly referred to as the assignor, while the person receiving it is the assignee.

    What Does Selling a Trademark Mean?

    When people talk about selling a trademark, they usually mean transferring the ownership rights in the mark for consideration. The transaction may relate to a brand name, logo, word mark or another protected trademark.

    This is different from merely allowing another business to use the mark. A licence generally gives someone permission to use intellectual property while ownership remains with the original owner. An assignment, by contrast, is intended to transfer ownership.

    Can I Sell My Registered Trademark?

    Yes. The registered proprietor has the statutory power to assign a trademark, subject to the applicable provisions of the Act. Section 38 also provides that registered trademarks are assignable and transmissible, subject to the restrictions contained in the relevant chapter of the Act.

    Before entering into a transaction, the seller should verify the registration details, proprietor information, goods or services covered and the current status of the trademark.

    It is also sensible to check whether the mark is involved in an opposition, rectification proceeding, infringement dispute or other legal issue.

    Can I Transfer Ownership of a Trademark?

    Yes. Trademark ownership may be transferred between individuals, companies or other eligible parties, depending on the circumstances of the transaction.

    For example, a founder may transfer a personally owned trademark to a company. A company may transfer a brand to another company as part of a restructuring or business sale. A trademark may also form part of a wider intellectual property transaction.

    The transfer should be supported by appropriate documentation and the change in title should be dealt with through the prescribed procedure.

    How to sell trademark: Step-by-Step Process

    There is no single “sell” button for a trademark. A proper transaction usually involves commercial negotiation, legal documentation and registration-related formalities.

    Step 1: Verify Trademark Ownership and Status

    Start by checking exactly what is being sold. The seller should verify the trademark application or registration number, proprietor details, classes and goods or services covered.

    Also check:

    • Whether the trademark is registered or still pending.
    • Whether the registration is currently in force.
    • Whether renewal requirements have been complied with.
    • Whether there are pending oppositions or rectification proceedings.
    • Whether the trademark is subject to any restrictions or limitations.
    • Whether third parties have any recorded rights or interests.

    If the trademark is approaching renewal, review the applicable requirements before completing the transaction. Lawizer provides a trademark renewal service for businesses that need assistance maintaining their registration.

    Step 2: Determine the Trademark’s Value

    A trademark does not have a fixed resale price simply because it is registered. Its commercial value depends on the strength and economic significance of the brand.

    Factors that may influence value include:

    • Brand recognition and reputation.
    • Revenue generated using the trademark.
    • Customer loyalty and goodwill.
    • Market share and geographic reach.
    • Distinctiveness of the mark.
    • Goods and services covered by the registration.
    • Online presence and domain-name value.
    • Existing licensing or distribution arrangements.
    • Potential for future expansion.
    • Existing disputes or enforcement history.

    Step 3: Negotiate the Assignment

    The parties should agree on the commercial terms before signing the final assignment document.

    Important points may include:

    • Purchase consideration.
    • Payment schedule.
    • Effective date of transfer.
    • Trademark numbers and classes covered.
    • Territory of the transfer.
    • Whether goodwill is included.
    • Existing licences or third-party arrangements.
    • Representations and warranties.
    • Indemnity and liability provisions.
    • Responsibility for government filings and transaction costs.

    The exact terms should reflect the nature of the transaction rather than relying on a generic template.

    Step 4: Execute a Trademark Assignment Agreement

    A written assignment document is central to the transaction. It records what is being transferred, from whom, to whom and on what terms.

    Depending on the transaction, the agreement may identify the trademark, registration number, classes, consideration, effective date, territory and whether the assignment is with or without goodwill.

    Where a more detailed intellectual property transfer document is required, Lawizer also provides IP Assignment Agreement drafting support.

    Step 5: Record the Transfer With the Trade Marks Registry

    Completing the private agreement is not the end of the process. Section 45 of the Trade Marks Act deals with registration of assignments and transmissions. A person who becomes entitled to a registered trademark by assignment or transmission is required to apply in the prescribed manner to have the title registered.

    The Registry process therefore matters because the official record should reflect the new proprietor. The parties should retain the executed assignment documentation and evidence of the filing.

    The exact procedural requirements and forms can depend on the circumstances of the transaction. For this reason, sellers should avoid assuming that every assignment follows exactly the same filing route.

    How to sell trademark at the Right Value

    One of the most difficult parts of a trademark transaction is deciding what the mark is actually worth. Registration alone does not automatically make a trademark commercially valuable.

    What Is a Trademark Worth?

    The value of a trademark depends largely on the economic benefit associated with the brand. A recognised mark with substantial customer goodwill can be worth considerably more than a newly registered mark that has never been commercially used.

    There is no universal government-set resale price for trademarks. The parties generally negotiate consideration based on the commercial value of the asset and the terms of the transaction.

    How Do You Calculate Trademark Value?

    Businesses may use different intellectual property valuation approaches depending on the circumstances.

    • Income approach: Estimates the economic benefit or future income attributable to the trademark.
    • Market approach: Considers comparable transactions, licensing arrangements or market evidence where reliable comparisons are available.
    • Cost approach: Considers the cost associated with developing or replacing the relevant brand asset, although this may not fully capture goodwill.

    For a significant transaction, valuation should be approached carefully and may require advice from appropriate legal, financial or valuation professionals.

    Trademark Value Checklist

    Before negotiating a price, consider:

    • How well known is the brand?
    • How much revenue is generated under the mark?
    • How loyal are its customers?
    • How distinctive is the mark?
    • How broad is its registration?
    • Are there existing licences?
    • Is the mark actively used?
    • Are there disputes involving the mark?
    • Does the brand have expansion potential?

    What Are the Different Types of Trademarks?

    Trademarks can take different forms. The relevant category depends on the nature of the mark and how it is used to distinguish goods or services.

    What Are the Four Types of Trademarks?

    Commonly discussed types include:

    • Word marks: Protection centred on words, names or combinations of letters and numbers.
    • Device or logo marks: Protection for a distinctive graphical representation.
    • Shape marks: Protection may apply to distinctive shapes associated with goods or packaging where legal requirements are satisfied.
    • Sound marks: Certain distinctive sounds may qualify for trademark protection where the statutory requirements are met.

    This is a simplified classification. Indian trademark law can cover a wider range of marks, and registrability depends on the facts.

    What Is the Strongest Type of Trademark?

    There is no single trademark category that is automatically the “strongest”. Legal strength often depends more on distinctiveness, scope of protection, actual use and the ability to enforce the rights than on whether the mark is a word, logo or sound mark.

    In general, distinctive marks are easier to protect than marks that are generic or purely descriptive of the goods or services.

    If you are deciding whether a brand should be protected before building significant goodwill, Lawizer’s trademark registration service can help with the registration process.

    Who Owns a Trademark?

    Trademark ownership should not be confused with who happens to use the brand in day-to-day business. For a registered mark, the register records the proprietor and the registered rights associated with the mark.

    Who Is the Owner of a Trademark?

    The person or entity recorded as the registered proprietor is central to determining registered ownership. The ownership structure may involve an individual, company or, depending on the circumstances, more than one proprietor.

    Before a sale, verify the official record and make sure the person signing the assignment has the necessary authority.

    Can a Trademark Be Sold by Someone Who Is Not the Registered Owner?

    A person should not assume that simply using a brand gives them authority to sell a registered trademark. The seller’s title and authority should be established before the transaction is completed.

    Where a company owns the trademark, the company should act through an appropriately authorised representative and maintain the necessary corporate records.

    What Happens If a Registered Trademark Is Not Used?

    Use of a trademark can become important when assessing its legal position and commercial value. A registration is not necessarily immune from challenge merely because it appears on the register.

    Do You Lose a Trademark If You Don’t Use It?

    Not automatically. However, Indian trademark law provides mechanisms for removal of a registered trademark on grounds of non-use in appropriate circumstances.

    Section 47 of the Trade Marks Act addresses removal from the register on the ground of non-use. Among other things, it deals with situations involving a continuous period of five years from the date the trademark was actually entered in the register, subject to the statutory requirements and exceptions.

    Therefore, “five years of non-use” should not be described as an automatic cancellation rule. A legal proceeding and the applicable statutory conditions matter.

    What Happens If a Registered Trademark Is Not Used for 5 Years?

    Where the statutory conditions are satisfied, an aggrieved person may seek removal of the trademark in relation to the relevant goods or services. Section 47 also recognises circumstances in which non-use may be excused, including certain special circumstances in the trade.

    This makes non-use an important due-diligence issue for a prospective purchaser. A buyer should investigate whether the trademark has actually been used and whether evidence of use and goodwill exists.

    Why Does Trademark Use Matter When Selling a Trademark?

    Actual use can affect both legal risk and commercial value. A buyer may want evidence showing that customers associate the mark with the business and that the brand has genuine commercial goodwill.

    Useful records may include:

    • Invoices and sales records.
    • Product packaging.
    • Advertising and marketing material.
    • Website and social-media records.
    • Distribution documents.
    • Licensing arrangements.
    • Other evidence of genuine commercial use.

    What Is Rule 47 in Trademark Law?

    Rule 47 of the Trade Marks Rules, 2017 should not be confused with Section 47 of the Trade Marks Act, 1999.

    What Is Rule 47 in Trademarks?

    Rule 47 deals with evidence in reply by an opponent in trademark opposition proceedings. It concerns the opportunity for the opponent to file evidence by affidavit in reply after receiving the applicant’s evidence.

    It is therefore not the provision that creates the general five-year non-use rule. The five-year non-use issue discussed above arises under Section 47 of the Trade Marks Act, 1999.

    This distinction is important because “Rule 47” and “Section 47” are sometimes incorrectly treated as referring to the same subject.

    What Are the Disadvantages of Selling a Trademark?

    Selling a trademark can provide an immediate financial return, but the decision can also have long-term consequences.

    Loss of Brand Control

    With a complete assignment, the seller gives up ownership of the transferred trademark. The new owner will generally control the future use of the mark within the scope of the transferred rights.

    Loss of Future Commercial Value

    If the brand has significant growth potential, selling it today may mean giving up future licensing, franchising or expansion opportunities.

    Contractual and Legal Risks

    A poorly drafted assignment can create disputes over consideration, territory, goodwill, existing licences or continuing obligations.

    Clear documentation is therefore important. Lawizer also provides IP assignment agreement drafting and licensing agreement drafting services for businesses dealing with intellectual property rights.

    Tax and Financial Considerations

    The tax treatment of a trademark transaction can depend on the nature of the asset, the seller, the transaction structure, the period of ownership and other facts. Do not assume that the sale price represents the seller’s final post-tax amount.

    For a material transaction, obtain appropriate tax advice before finalising the consideration and transaction structure.

    Selling vs Licensing a Trademark

    Not every founder who wants to monetise a trademark needs to sell it. Licensing can be an alternative when the owner wants another party to use the mark while retaining ownership.

    Factor Assignment Licensing
    Ownership Transfers to the assignee Remains with the owner
    Control Generally moves to the new owner Can be retained through contractual terms
    Payment May involve a one-time sale consideration May involve royalties or licence fees
    Long-term relationship Usually represents a permanent transfer Can be limited by duration and conditions

    If you want to retain ownership while allowing another party to use the intellectual property, a properly drafted licensing agreement may be more appropriate than an outright assignment.

    Documents Required to Sell or Transfer a Trademark

    The exact documentation depends on the transaction, but a seller should generally be prepared with the following:

    • Trademark application or registration details.
    • Details of the current proprietor.
    • Details of the proposed assignee.
    • Trademark assignment deed or agreement.
    • Consideration and payment details.
    • Authority documents where a company is involved.
    • Board resolution or other corporate authorisation, where applicable.
    • Documents required for the relevant Registry filing.
    • Evidence relating to goodwill or commercial use, where relevant.

    Lawizer’s Sell Your Trademark service specifically provides assignment deed support, Registry filing support and ownership-transfer assistance.

    Common Mistakes to Avoid When Selling a Trademark

    • Assuming registration automatically determines commercial value.
    • Failing to verify the registered proprietor.
    • Ignoring pending opposition or disputes.
    • Using an unclear or incomplete assignment agreement.
    • Failing to specify the trademarks and classes being transferred.
    • Ignoring whether goodwill is included.
    • Overlooking existing licences or contractual rights.
    • Failing to address the Registry filing.
    • Ignoring non-use risks.
    • Finalising the price without considering applicable tax and transaction costs.

    Frequently Asked Questions About Selling a Trademark

    Can I sell my registered trademark?

    Yes. A registered trademark can generally be assigned, subject to the Trade Marks Act and applicable restrictions. The transfer should be documented and the new proprietor’s title should be dealt with through the prescribed Registry procedure.

    Can you sell a trademark?

    Yes. Selling a trademark generally means transferring ownership of the trademark to another party in return for agreed consideration.

    Can I transfer ownership of a trademark?

    Yes. Ownership can generally be transferred by assignment or transmission, subject to applicable legal requirements.

    What is a trademark worth?

    There is no universal resale value. The value depends on factors such as goodwill, revenue, recognition, distinctiveness, market position, scope of protection and future commercial potential.

    How do I calculate the value of a trademark?

    Businesses may consider income, market and cost approaches, together with brand-specific factors such as customer recognition, revenue, goodwill and licensing potential.

    What are the disadvantages of selling a trademark?

    The seller loses ownership and future control over the transferred mark. The seller may also give up future licensing or expansion opportunities and must consider contractual, tax and transaction risks.

    Who is the owner of a trademark?

    For a registered trademark, the registered proprietor recorded on the register is central to determining ownership. Before an assignment, the parties should verify the registration record and the authority of the person signing the transaction.

    What happens if a registered trademark is not used for 5 years?

    Five years of continuous non-use can become relevant to a removal proceeding under Section 47 of the Trade Marks Act, subject to the statutory conditions and exceptions. It does not mean that a trademark is automatically cancelled the moment five years pass.

    Do you lose a trademark if you don’t use it?

    Not automatically. However, genuine use is important because Indian law provides grounds for seeking removal of a registered mark for non-use in appropriate circumstances.

    What is Rule 47 in trademarks?

    Rule 47 of the Trade Marks Rules, 2017 concerns evidence in reply by an opponent in opposition proceedings. It should not be confused with Section 47 of the Trade Marks Act, which deals with removal on grounds of non-use.

    What are the four types of trademarks?

    Commonly discussed categories include word marks, device or logo marks, shape marks and sound marks. Indian trademark law can recognise other forms of marks where the statutory requirements are satisfied.

    What is the strongest type of trademark?

    There is no universally strongest type. Distinctiveness, scope of protection, genuine use and enforceability are often more important than the category of the mark itself.

    Conclusion: Is Selling Your Trademark Right for You?

    A trademark can be an important business asset, and Indian law generally permits its assignment or transmission. But a successful transaction involves more than agreeing on a sale price.

    Before transferring the mark, verify ownership, assess its commercial value, review its use and legal status, document the transaction carefully and address the applicable Registry formalities.

    If your objective is to monetise the brand without permanently giving up ownership, licensing may also be worth considering.

    If you want professional assistance with the transaction, you can explore Lawizer’s Sell Your Trademark service for trademark assignment and ownership-transfer support. For businesses that need a customised document, Lawizer also offers IP Assignment Agreement drafting.

    For a significant transaction, particularly one involving substantial goodwill, multiple trademarks, existing licences or tax implications, consider obtaining appropriate legal and tax advice before signing the final agreement.

  • What Is Intellectual Property?

    What Is Intellectual Property?

    What Is Intellectual Property? India Guide

    If you are a founder, creator or small-business owner, you may be wondering what is intellectual property and why it matters to your business. Intellectual property, commonly called IP, refers broadly to creations of the mind and the legal rights that may protect qualifying creations, inventions, brands and creative works.

    Unlike physical property such as a building, vehicle or machine, intellectual property is intangible. However, it can have significant commercial value. A business name, logo, software code, product invention, original content or confidential business method can all represent valuable intellectual assets.

    Understanding intellectual property is therefore important before launching a brand, developing a product, hiring employees or sharing a new invention publicly. The right form of protection depends on the nature of the asset and the legal requirements that apply to it.

    In this guide, we explain the meaning of intellectual property, its major types, practical examples, ownership, protection in India and why IP matters to startups and small businesses.

    What Is Intellectual Property in Simple Terms?

    Intellectual property is a broad term for creations and commercially valuable intangible assets that may receive legal protection. The World Intellectual Property Organization describes IP as creations of the mind, including inventions, artistic works, computer programs, trademarks and other commercial signs.

    In simple terms, think of IP as something your business creates or develops that has value but cannot be physically held.

    For example, a startup might own:

    • A brand name that identifies its products.
    • A logo used on its website and packaging.
    • Original articles, photographs and videos.
    • Software and source code.
    • A qualifying technical invention.
    • A distinctive product design.
    • Confidential business information.

    These assets do not all receive the same type of legal protection. A brand name is generally considered for trademark protection, while original creative expression may receive copyright protection. A qualifying invention may be protected through a patent if it satisfies the applicable requirements.

    This distinction is important because registering one type of IP does not automatically protect every other asset belonging to the business.

    What Is the IP Meaning?

    IP stands for Intellectual Property. The term is used to describe a broad area of law covering different forms of intangible creations and commercial identifiers.

    Intellectual property rights can give their owners certain exclusive or enforceable rights, depending on the type of IP and the applicable law.

    What Is the Definition of Intellectual Property?

    There is no single Indian statute that provides one exhaustive definition covering every form of intellectual property. Instead, different forms of IP are governed by different laws.

    For example, trademarks are governed primarily by the Trade Marks Act, 1999, patents by the Patents Act, 1970, copyright by the Copyright Act, 1957, and industrial designs by the Designs Act, 2000.

    The official IP India website provides access to information on patents, designs, trademarks, geographical indications and copyright.

    What Is Intellectual Property in Business?

    For a business, IP can be an important intangible asset. A company’s intellectual property may help distinguish its products, protect its innovations, preserve its creative work and maintain its competitive advantage.

    For example, a technology startup could have a registered trademark for its brand, copyright in its software and website content, a patent application for a qualifying invention, and confidential information protected through contractual confidentiality obligations.

    This is why founders should identify their IP early rather than waiting until a dispute or funding round forces them to investigate ownership.

    What Are the 7 Types of Intellectual Property?

    There is no single universal list that every jurisdiction or organisation describes as exactly “seven types” of IP. Different classifications group intellectual property differently. For an Indian business, however, the following categories are useful to understand.

    1. Patents

    A patent protects a qualifying invention when the statutory requirements for patentability are satisfied.

    In India, patentability generally involves requirements such as novelty, inventive step and industrial applicability, along with the requirement that the subject matter is not excluded from patent protection.

    Examples may include a new technical product, a qualifying manufacturing process or a technical improvement that meets the requirements of patent law.

    Not every idea, discovery or business concept qualifies for a patent. A founder should assess patentability before publicly disclosing a potentially patentable invention.

    2. Trademarks

    A trademark helps distinguish the goods or services of one business from those of others. It can protect qualifying brand identifiers such as names, logos and certain other distinctive marks.

    For founders, trademark protection is particularly important because a brand can become one of the most recognisable and valuable assets of a business.

    If you are building a new brand, you can explore Lawizer’s Trademark Registration service.

    You can also read Lawizer’s practical guide on how to register a trademark in India.

    3. Copyright

    Copyright protects original expression in qualifying creative works. It can apply to literary, artistic, musical and dramatic works, cinematograph films, sound recordings and computer programmes, subject to the Copyright Act, 1957.

    For businesses, copyright can be relevant to:

    • Website content.
    • Software and source code.
    • Photographs.
    • Illustrations and artwork.
    • Videos.
    • Books and articles.
    • Advertising and creative material.

    Copyright generally arises automatically when an eligible original work is created. Registration is not a prerequisite for copyright to exist, although registration can provide an official record and useful evidence concerning the registered particulars.

    Lawizer also provides a Copyright Registration service for eligible creative works.

    4. Industrial Designs

    Design protection can apply to qualifying visual features of an article, including its shape, configuration, pattern or ornamentation, as recognised under the Designs Act, 2000.

    Design protection focuses on the visual appearance of an article rather than its underlying technical function.

    For example, a business developing a distinctive product shape or visual configuration may need to consider design protection separately from trademark or patent protection.

    5. Geographical Indications

    A geographical indication, or GI, identifies goods associated with a particular geographical territory where a specific quality, reputation or other characteristic is attributable to that origin.

    Indian examples include Darjeeling Tea, Basmati Rice, Kanchipuram silk saree and Kolhapuri chappal. The official IP India GI resources explain the connection between the product and its geographical origin.

    6. Trade Secrets and Confidential Information

    Trade secrets refer broadly to commercially valuable information that is kept confidential and provides an economic advantage.

    Examples can include:

    • Proprietary processes.
    • Manufacturing know-how.
    • Business strategies.
    • Confidential pricing information.
    • Customer or supplier information.
    • Internal technical information.

    Unlike a trademark or patent, a trade secret is generally protected through secrecy and appropriate contractual and organisational measures rather than simply obtaining a registration certificate.

    7. Plant Varieties and Specialised IP Rights

    India also has specialised legislation dealing with plant varieties and related rights. The Protection of Plant Varieties and Farmers’ Rights Act, 2001 provides a separate legal framework for eligible plant varieties and associated rights.

    This category is particularly relevant to agriculture, plant breeding and related industries rather than most ordinary service businesses.

    What Are the 4 Main Types of Intellectual Property?

    When people ask about the four main types of intellectual property, they commonly mean patents, trademarks, copyright and trade secrets. These four categories are especially useful for understanding the intellectual property needs of a typical business.

    IP Type What It Can Protect Example
    Patent Qualifying inventions New technical product
    Trademark Distinctive brand identifiers Brand name or logo
    Copyright Original creative expression Software, article or photograph
    Trade Secret Confidential commercial information Proprietary process

    These categories are not necessarily alternatives. A single business can own several types of intellectual property at the same time.

    Why Are These Four Important for Businesses?

    Imagine an Indian technology startup launching a new product. Different aspects of the same business may require different forms of IP protection.

    • Trademark: The startup’s brand name or logo may be protected as a trademark.
    • Copyright: Its original software, website content or marketing material may qualify for copyright protection.
    • Patent: A new technical invention may be considered for patent protection if it satisfies the applicable legal requirements.
    • Trade Secret: A confidential algorithm, formula or business process may be protected through appropriate confidentiality measures.

    Understanding these differences helps founders choose the appropriate form of protection instead of assuming that one registration protects every asset of the business.

    Protect Your Intellectual Property With Lawizer

    Protecting intellectual property is an important part of building and growing a business. Lawizer can help you with trademark registration, copyright registration, IP assignment, licensing and other legal documentation.

    Protect your intellectual property and strengthen your business with the right legal support.

  • Trademark Objection Reply: Process, Fees & Timeline

    Trademark Objection Reply: Process, Fees & Timeline

    Trademark objection reply is the written response submitted to the Trade Marks Registry when an examiner raises objections against a trademark application. Seeing “Objected” on the IP India portal can be worrying, but an objection is not the same as a final rejection. The applicant gets an opportunity to explain why the mark should proceed, address the examiner’s concerns, and provide supporting evidence where appropriate.

    For Indian founders and small-business owners, the important point is simple: do not ignore the examination report. The Trade Marks Registry’s current procedure states that an applicant should respond to office objections within 30 days from receipt of the examination report. If no response is submitted within the prescribed period, the application may be treated as abandoned. If the response does not overcome the objections, a hearing may follow.

    This guide explains how to check a trademark objection, prepare a response, understand common grounds such as Sections 9 and 11 of the Trade Marks Act, assess fees and timelines, and know what happens after the reply is filed.

    What Is a Trademark Objection?

    A trademark objection is an objection raised by the Trade Marks Registry during examination of an application. The examiner reviews the application and may identify legal, factual or procedural issues that need to be addressed before the application can proceed.

    The objection is generally communicated through an Examination Report. The report explains the grounds on which the application has been objected to and may identify earlier trademarks or other issues relevant to the application.

    The key distinction is that an objection is not automatically a rejection. The applicant has an opportunity to respond. Under the Trade Marks Rules, 2017, a timely response is considered by the Registrar. If the response resolves the objection, the application can proceed to publication in the Trade Marks Journal. If the objection remains unresolved, the matter may move to a hearing.

    Applicants can refer to the Trade Marks Act, 1999 and the Trade Marks Rules, 2017 for the governing provisions.

    What Does “Objected” Mean in Trademark?

    When the application status says “Objected”, it generally means that an examination objection has been raised and the application requires a response.

    It does not mean that the trademark has already been permanently refused. The next step is to read the Examination Report, understand the grounds raised by the examiner and prepare an appropriate response within the applicable period.

    Founders should also distinguish an examination objection from a third-party opposition. An examination objection comes from the Registry during examination. An opposition is a separate proceeding that can be initiated by another person after the mark is advertised in the Trade Marks Journal.

    Why Is a Trademark Application Objected To?

    There is no single reason why an application may be objected to. The grounds depend on the mark, the goods or services covered, earlier marks on the Register and the information provided in the application.

    Common issues include:

    • The mark may lack sufficient distinctiveness.
    • The mark may describe the kind, quality, purpose or other characteristics of the goods or services.
    • The mark may be similar to an earlier trademark.
    • The goods or services may create a likelihood of confusion with those covered by an earlier mark.
    • There may be classification, specification or other procedural issues.
    • The examiner may raise another objection under the Trade Marks Act or Rules based on the circumstances of the application.

    What Are the Common Grounds for Trademark Objection?

    Section 9 Objection: Lack of Distinctiveness

    Section 9 of the Trade Marks Act deals with absolute grounds for refusal. Among other things, it covers marks that are devoid of distinctive character and marks that exclusively describe certain characteristics of goods or services.

    For example, a mark that simply describes what a product is, what it does or a characteristic of the product may face difficulty in registration. The exact assessment depends on the mark and the goods or services involved.

    A response to a Section 9 objection may therefore need to explain why the mark is distinctive. Depending on the circumstances, evidence of use and market recognition may also be relevant.

    Read the official Section 9 provisions of the Trade Marks Act before relying on a particular legal argument.

    Section 11 Objection: Similarity With an Earlier Trademark

    Section 11 deals with relative grounds for refusal. A trademark may face an objection where it is identical or similar to an earlier trademark and the relevant goods or services are identical or similar, creating a likelihood of confusion or association.

    This is why a trademark search should consider more than an exact spelling match. Phonetic similarity, visual similarity and the relationship between the relevant goods or services can matter.

    If a Section 11 objection is raised, the response should deal with the cited mark carefully. Simply saying “the names are different” may not be enough. The applicant should examine the overall marks, the relevant goods or services and the circumstances of the market.

    How to Check a Trademark Objection?

    Before drafting anything, confirm exactly what the Registry has objected to. Do not rely only on the application status shown on a third-party website or an old screenshot.

    You can use the official IP India Trade Mark Public Search to investigate earlier marks. You can also use the official Trade Marks Registry system to track the application and related proceedings.

    Step 1: Check the Application Status

    Search for the trademark application using the application number and review its current status. If the application is shown as objected, look for the corresponding Examination Report or communication from the Registry.

    Step 2: Read the Examination Report

    Read the complete report rather than focusing only on the word “Objected”. Identify every objection raised by the examiner.

    Make a simple list of the issues. For example:

    • Section 9 objection.
    • Section 11 objection.
    • Classification or specification issue.
    • Requirement for additional information or documents.

    This makes it easier to ensure that your response answers every point.

    Step 3: Check the Cited Trademarks

    If the report cites earlier marks, search those marks and review their status, classes and relevant goods or services.

    Do not assume that every cited mark automatically prevents registration. The legal assessment depends on the specific facts, including similarity and the goods or services involved.

    How to File a Trademark Objection Reply?

    A good response should be structured, specific and supported by the facts of the application. The aim is not simply to disagree with the examiner. The aim is to explain why the objection should be waived or why the application should be allowed to proceed.

    Step 1: Understand Every Objection

    Start with the Examination Report. Identify the legal provision relied upon and the reason given by the examiner.

    If the report raises multiple objections, deal with each one separately. A response that addresses only the most obvious objection may leave another objection unresolved.

    Step 2: Prepare a Point-by-Point Response

    The response should explain the applicant’s position in relation to each objection.

    For a Section 9 objection, the argument may focus on the distinctiveness of the mark, the nature of the mark and, where relevant, evidence showing how the mark is used in the market.

    For a Section 11 objection, the response may need to distinguish the applicant’s mark from the cited mark and address the relevant goods or services and likelihood of confusion.

    Where an objection concerns classification or the description of goods or services, the response should address the specific classification issue rather than relying on general arguments about brand ownership.

    Step 3: Add Relevant Supporting Evidence

    Evidence can be particularly important where the applicant relies on use, goodwill or acquired distinctiveness.

    Depending on the facts, supporting material may include:

    • Invoices and sales records.
    • Product packaging and labels.
    • Advertising material.
    • Website pages.
    • Social media records.
    • Marketing material.
    • Business documents showing use of the mark.
    • Other dated documents that support the applicant’s position.

    Not every objection requires every document listed above. The evidence should be relevant to the argument being made.

    Step 4: File the Response Within the Applicable Time

    IP India’s current Standard Operating Procedure states that a response to the Examination Report should be submitted within one month, or 30 days, from receipt of the report. The Trade Marks Rules also provide that an application may be treated as abandoned if the applicant fails to respond within the prescribed period.

    For this reason, check the actual communication and application record and do not rely on a generic online deadline calculator.

    Step 5: Track the Application After Filing

    Filing the response is not necessarily the end of the process. The Registry may accept the application, or it may determine that the objections remain unresolved and provide an opportunity for a hearing.

    Continue monitoring the application after the response has been submitted.

    What Documents Are Required for a Trademark Objection Reply?

    There is no universal document list for every application. The documents required depend on the objections and the arguments being made.

    Common supporting documents can include:

    • A copy of the Examination Report.
    • Trademark application details.
    • Proof of use, where use is relevant to the response.
    • Invoices and sales documents.
    • Advertisements and promotional material.
    • Website and social media evidence.
    • Product packaging or labels.
    • Affidavits or declarations, where appropriate.
    • Other documents specifically relevant to the objection.

    Evidence should be organised chronologically where dates are important. Poorly organised documents can make an otherwise useful response harder to assess.

    How Much Does a Trademark Objection Reply Cost?

    The cost depends on what exactly needs to be filed and whether professional assistance is used.

    A routine response to an Examination Report should be distinguished from proceedings such as a third-party opposition, amendment request, renewal or expedited processing. These proceedings can have their own prescribed fees.

    IP India’s current official fee schedule separately lists fees for applications, oppositions, renewals and various requests. It does not list a separate standard government fee simply described as a “reply to examination report”. However, a particular matter may involve a fee if another request or proceeding is also required.

    Professional fees are separate. A lawyer, trademark agent or legal service provider may charge for reviewing the Examination Report, conducting legal research, preparing the response, organising evidence and handling subsequent proceedings.

    For current professional pricing, founders can review Lawizer’s startup and business legal services, where trademark objection support is listed among its business protection services.

    What Is the Time Limit for a Trademark Objection Reply?

    The Trade Marks Registry’s current Standard Operating Procedure states that the applicant should submit a reply to office objections within 30 days from receipt of the Examination Report. The Trade Marks Rules, 2017 similarly provide that if the applicant fails to respond within one month, the Registrar may treat the application as abandoned.

    This makes the response deadline one of the most important parts of the process.

    Do not wait until the final few days. A complicated Section 11 objection may require searching earlier marks, collecting business evidence and reviewing the goods or services before the response can be properly prepared.

    If the objection has already been raised, you can also read Lawizer’s guide to trademark registration in India for broader context on examination, publication and registration.

    What Happens After Filing a Trademark Objection Reply?

    After the reply is submitted, the Registry considers the response. There are several possible outcomes.

    If the Registrar Accepts the Response

    If the objections are considered satisfactorily addressed, the application can proceed to the next stage. After acceptance, the trademark is published in the Trade Marks Journal.

    Publication creates an opportunity for third parties to oppose the application within the applicable statutory period.

    If the Registrar Is Not Satisfied

    If the response does not overcome the objections, the applicant may be given an opportunity to attend a hearing. The hearing gives the applicant an opportunity to make submissions before the matter is decided.

    A hearing does not automatically mean the trademark will be rejected. The outcome depends on the objections, the evidence, the submissions and the applicable law.

    If the Application Is Refused

    If the objection remains unresolved after the relevant proceedings, the application may ultimately be refused. The available remedy depends on the nature and stage of the decision.

    At that point, professional legal advice can be useful because the next step may involve a more formal challenge rather than another routine examination response.

    What Happens If You Do Not Reply to a Trademark Objection?

    Ignoring an Examination Report is risky. Under the Trade Marks Rules, 2017, an application may be treated as abandoned if the applicant does not respond within the prescribed period.

    Abandonment is different from a simple pending objection. Once an application is abandoned, the applicant cannot assume that the original application will continue automatically.

    If your application is already close to its response deadline, check the official record immediately and obtain advice on the available procedural options.

    Trademark Objection vs Trademark Opposition: What Is the Difference?

    These terms are often confused because both can prevent a trademark application from moving smoothly toward registration. However, they occur at different stages and involve different parties.

    Trademark ObjectionTrademark Opposition
    Raised during examination by the RegistryInitiated by a third party after publication
    Usually communicated through an Examination ReportBegins with a notice of opposition
    Applicant responds to the examiner’s objectionsApplicant responds to the opponent’s case through the prescribed process
    May lead to a hearing if objections remainCan become a contested proceeding involving evidence and hearings

    Section 21 of the Trade Marks Act provides the framework for opposition. The Act states that an opposition may be filed within three months from advertisement or re-advertisement, with the Registrar having power to allow a further period of up to one month. This creates a maximum period of four months in the circumstances permitted by the provision.

    IP India’s processing guidance also describes the four-month opposition window following publication in the Trade Marks Journal.

    Therefore, a founder should not treat an examination objection and a third-party opposition as the same procedure.

    What Happens After a Trademark Is Published for Opposition?

    Once the application is accepted and published in the Trade Marks Journal, third parties get the opportunity to oppose registration within the applicable period.

    If no opposition is filed within the applicable period, the application can proceed toward registration. If an opposition is filed, the matter becomes a contested proceeding and the applicant must respond through the prescribed procedure.

    Can You Renew a Trademark After It Has Ended?

    This question concerns a registered trademark rather than an application that has merely been objected to.

    Under Section 25 of the Trade Marks Act, a registered trademark is valid for 10 years and can be renewed for further periods of 10 years. If the renewal fee is not paid, the law provides mechanisms involving surcharge and, in certain circumstances, restoration after removal from the Register.

    The current IP India rules provide a six-month period after expiry for renewal with the applicable surcharge. If the mark has already been removed, restoration and renewal may be possible within the statutory period and subject to the prescribed requirements.

    For current renewal requirements, see Lawizer’s trademark renewal services or check the official IP India trademark forms and official fees.

    Common Mistakes to Avoid in a Trademark Objection Reply

    1. Treating an Objection as a Final Rejection

    An examination objection gives the applicant an opportunity to respond. Do not abandon the application simply because the status has changed to “Objected”.

    2. Sending a Generic Response

    A response should address the actual grounds in the Examination Report. Generic statements about having a unique brand may not adequately answer a specific Section 9 or Section 11 objection.

    3. Ignoring Cited Trademarks

    If the examiner has cited earlier marks, study them. The response should explain the relevant differences and circumstances rather than ignoring the cited marks.

    4. Filing Irrelevant Evidence

    More documents do not automatically make a response stronger. Evidence should support the legal and factual arguments being made.

    5. Missing the Deadline

    This is one of the most avoidable mistakes. Put the response deadline on your compliance calendar as soon as the Examination Report is received.

    6. Failing to Monitor the Application Afterwards

    Even after filing the response, monitor the application. A hearing notice or further communication may require action.

    FAQ: Trademark Objection Reply

    How do I file a trademark objection reply?

    First, review the Examination Report and identify every objection. Prepare a point-by-point response supported by relevant evidence, then submit it through the prescribed Trade Marks Registry process within the applicable deadline. Keep the filing acknowledgement and continue monitoring the application.

    How to reply to a trademark objection?

    Start by understanding the legal ground cited by the examiner. Address each objection separately, explain why the mark should proceed, distinguish cited marks where relevant and attach evidence that supports the applicant’s position.

    What does “objected” mean in trademark?

    “Objected” generally means that the Trade Marks Registry has raised an examination objection against the application. It is not, by itself, a final rejection. The applicant gets an opportunity to respond within the prescribed period.

    How do I check my trademark objection?

    Use the official IP India Trade Mark Public Search and application-status facilities. Search using the trademark application details and review the Examination Report or related communication attached to the application.

    What is the difference between a trademark objection and opposition?

    An objection is raised by the Registry during examination. An opposition is generally filed by a third party after the trademark application is advertised in the Trade Marks Journal. The procedures and response requirements are different.

    What happens if my trademark is rejected?

    If the application is ultimately refused, the next available remedy depends on the decision, procedural stage and facts of the case. A professional should review the order before deciding whether to pursue a further challenge.

    What happens if a trademark application is abandoned?

    An abandoned application does not continue through the normal registration process. If an application has been marked abandoned, the applicant should review the reason and the available procedural remedy rather than assuming that the application will automatically revive.

    How long does it take to respond to a trademark office objection?

    The Registry’s current procedure provides one month, or 30 days, from receipt of the Examination Report for the applicant to respond. The time needed to prepare the response itself depends on the complexity of the objections and the amount of evidence required.

    What is the time limit for opposing a trademark application in India?

    Section 21 provides three months from advertisement or re-advertisement, with a further period of up to one month that may be allowed by the Registrar on application and payment of the prescribed fee. Thus, the maximum period can be four months where the additional period is granted.

    What happens after a trademark is published for opposition?

    Third parties get the statutory opportunity to oppose registration. If there is no opposition within the applicable period, the application can proceed toward registration. If an opposition is filed, the applicant must defend the application through the prescribed opposition procedure.

    What are the fees for filing a trademark objection reply in India?

    There is no single universal “trademark objection reply fee”. A routine examination-report response should be distinguished from separate requests and proceedings that have prescribed fees. Professional fees for drafting and handling the response are separate and vary by service provider and complexity.

    Can I renew my trademark after it has ended?

    A registered trademark can generally be renewed every 10 years. The Trade Marks Act also provides a six-month period after expiry for renewal with the applicable surcharge, and restoration provisions may apply after removal subject to statutory conditions and time limits.

    How Lawizer Can Help With a Trademark Objection

    A trademark objection can be difficult to handle when you are running a business at the same time. The response may require legal analysis, review of cited marks and organisation of supporting evidence.

    Lawizer provides trademark and startup legal services, including support for responding to trademark objections. The service is designed to help businesses prepare and manage the response while keeping the process online.

    If you are still at the application stage, you can also explore Lawizer’s trademark registration service for assistance with trademark search, filing and application tracking.

    For broader brand-protection planning, Lawizer also publishes practical guidance such as its trademark registration guide for first-time founders.

    Conclusion: Respond to a Trademark Objection Promptly

    A trademark objection does not necessarily mean that your brand cannot be registered. It means that the Trade Marks Registry has identified an issue that needs to be addressed.

    The safest approach is to act promptly. Check the Examination Report, understand each objection, examine any cited trademarks, prepare a specific response, attach relevant evidence and submit it within the prescribed period.

    Do not stop after filing. Continue tracking the application because the Registry may accept the response, request further action or schedule a hearing.

    If you are unsure how to respond or the objection involves complex similarity, prior use or substantial evidence, consider getting professional assistance before the deadline expires.

    Received an examination objection on your trademark? Consult Lawizer for trademark objection support and get help understanding the objection, preparing the response and moving your application forward.

    Legal information disclaimer: This article is intended for general information and does not constitute legal advice. Trademark procedures, fees, forms and Registry practice can change. Check the latest official IP India communication and applicable rules for your specific application.

  • How Startups Raise Funds in India

    How Startups Raise Funds in India

    How startups raise funds in India: A Guide

    Understanding how startups raise funds in India is important for founders who want to build, launch and scale a business without giving away more ownership than necessary. Startup funding can come from several sources, including personal savings, business revenue, friends and family, angel investors, venture capital firms, loans, incubators and government-backed schemes.

    There is no single funding route that works for every startup. A bootstrapped SaaS business may need very different funding from a deep-tech company developing a new product. Your stage, revenue, market opportunity, capital requirement and growth plans should determine the funding method you choose.

    This guide explains the main startup funding options in India, how the fundraising process works, government funding opportunities, founder equity and common reasons startups fail.

    How startups raise funds in India

    Indian startups generally use a combination of equity, debt and non-dilutive funding. The right option depends on how much money the business needs and what it can offer in return.

    1. Bootstrapping

    Bootstrapping means funding the business with the founders’ own savings or money generated by the business. It allows founders to retain greater control because there is no external investor taking equity.

    Bootstrapping can work well when the initial costs are manageable and the business can generate revenue quickly. It can also help founders prove demand before approaching investors.

    The limitation is that growth may be slower. Founders also carry more financial risk because they are using their own resources.

    2. Friends and family funding

    Some startups raise their first external capital from relatives, friends or personal networks. This can be useful at the idea or pre-seed stage when institutional investors may not yet be interested.

    However, informal funding should still be documented properly. The parties should clearly establish whether the money is a loan, equity investment or another arrangement.

    3. Angel investors

    Angel investors are individuals who invest their own money in early-stage businesses. In return, they may receive shares or another agreed investment instrument, depending on the structure of the transaction.

    Angels often evaluate the founding team, market opportunity, product, early traction and potential for growth. Some also provide introductions, mentoring and industry expertise.

    4. Venture capital

    Venture capital is generally aimed at startups that have the potential for substantial growth. VC investors typically invest in exchange for equity and expect the company to scale significantly over time.

    Funding rounds can occur at different stages, such as seed, Series A and later rounds. Each round can affect the founders’ ownership because new shares or other investment instruments may be issued.

    5. Startup and business loans

    Debt funding allows a business to raise money without immediately giving investors ownership of the company. However, loans create repayment obligations and may involve interest, security or other eligibility requirements.

    Debt can be appropriate for a business with predictable cash flow. It may be less suitable for an early-stage startup that has no revenue and cannot comfortably service repayments.

    6. Incubators and accelerators

    Incubators and accelerators can provide funding, mentorship, networking, workspace, technical support and access to investors. Some programmes take equity, while others provide grants or other forms of assistance.

    Founders should check the programme’s eligibility requirements, funding terms, equity conditions and obligations before joining.

    How to raise funds for a startup in India

    Fundraising is not simply about finding someone willing to invest. Investors usually want evidence that the business understands its market, has a credible team and can use capital efficiently.

    Step 1: Calculate how much funding you actually need

    Start by preparing a realistic financial plan. Estimate product development, salaries, technology, marketing, professional fees, office expenses and other operating costs.

    Then determine how much runway the proposed funding would provide. Avoid choosing a fundraising target simply because another startup raised a large amount.

    Step 2: Choose the right funding source

    Ask whether equity, debt, grants or bootstrapping is most appropriate for your stage.

    • Use bootstrapping when initial costs are manageable.
    • Consider angels when you need early-stage capital and strategic support.
    • Consider venture capital when the business has strong scalability potential.
    • Consider debt when cash flows can support repayment.
    • Explore government schemes when your startup meets their eligibility conditions.

    Step 3: Prepare your pitch deck

    A good pitch deck should explain the business clearly. It normally covers the problem, solution, market, business model, competition, traction, team, financial projections and funding requirement.

    Do not exaggerate revenue, market size or customer numbers. Investors conduct due diligence, and inconsistencies can damage trust.

    Step 4: Organise your legal documents

    Legal readiness can become particularly important during investor due diligence. Your company records, ownership information and contracts should match what you present to investors.

    For example, founders should review their startup legal documents and agreements, including founder arrangements, intellectual property assignments and investor documentation.

    If your business has multiple founders, a properly drafted Co-Founder Agreement can clarify roles, ownership, decision-making and exit arrangements.

    Step 5: Keep your cap table accurate

    A cap table records who owns what percentage of the company. It should account for founder shares, previous investments, employee equity arrangements and new securities issued during fundraising.

    A messy cap table can make due diligence harder. It can also create disagreements over valuation and dilution.

    Step 6: Complete due diligence and documentation

    Once an investor shows serious interest, the process may involve commercial, financial and legal due diligence. The parties may negotiate a term sheet before final investment documentation is signed.

    The exact documents depend on the transaction. They can include a share subscription agreement, shareholders’ agreement and corporate approvals.

    How startups raise funds in India through government schemes

    Government support can be useful for eligible startups, but founders should not assume that every government programme is a universal grant.

    One important example is the Startup India Seed Fund Scheme. The official scheme information states that eligible startups can receive up to ₹20 lakh as a grant for proof of concept, prototype development or product trials. It also provides for investment support of up to ₹50 lakh for market entry, commercialisation or scaling through specified instruments, subject to the scheme’s conditions.

    The scheme has specific eligibility requirements. For example, its published criteria include DPIIT recognition and incorporation within the specified period at the time of application. The official scheme page should always be checked for the current application status and applicable rules.

    For current information, founders should consult the official Startup India Seed Fund Scheme FAQ.

    What is a ₹20 lakh grant for startups?

    The ₹20 lakh figure generally refers to the grant component of the Startup India Seed Fund Scheme for eligible startups. It is not a universal ₹20 lakh payment available to every new business.

    The grant is intended for defined early-stage activities such as validation, proof of concept, prototype development and product trials. Eligibility and disbursement conditions apply.

    Therefore, founders should first determine whether their startup qualifies instead of treating the ₹20 lakh amount as guaranteed funding.

    How to get money from the government for a startup

    Government funding can take different forms. Depending on the programme, support may include grants, seed funding, credit support, subsidies or access to incubators.

    A practical process is:

    • Check whether your business meets the relevant definition and eligibility criteria.
    • Consider obtaining DPIIT recognition if your startup qualifies.
    • Identify central and state government programmes relevant to your sector.
    • Prepare your business plan, financial information and supporting documents.
    • Apply through the official portal or designated incubator.
    • Follow the programme’s reporting and utilisation requirements.

    Current DPIIT recognition rules should be checked before applying because eligibility criteria can change. The Startup India portal currently states that eligible recognised startups can include Private Limited Companies, LLPs, registered partnerships and cooperative societies, subject to the applicable conditions.

    Lawizer also provides assistance with Private Limited Company registration and Startup India registration for founders who need help getting their business structure and documentation ready.

    How much equity should founders give investors?

    Equity is one of the most important parts of startup fundraising. Giving away shares means giving investors a portion of future ownership and economic value.

    Is 1% equity in a startup good?

    There is no universal answer. One percent can be valuable in a highly successful company and nearly worthless in a company that never achieves significant value.

    The important question is what the 1% represents in relation to the company’s valuation and the investment being made.

    Founders should also consider future dilution. If the company issues additional shares in later funding rounds, an existing shareholder’s percentage may decrease.

    How much equity should a CEO get in a startup?

    If the CEO is also a founder, their ownership depends on the founders’ contributions, responsibilities, investment, intellectual property and agreed ownership structure.

    If the CEO is hired later, their compensation may instead combine salary, incentives and potentially equity or employee stock options, depending on the company’s structure and applicable rules.

    There is no legally prescribed percentage that every startup CEO must receive.

    Should co-founders be 50/50 or 51/49?

    Neither split is automatically correct. A 50/50 structure can reflect equal contribution, but it may create deadlock if the founders disagree on an important decision.

    A 51/49 structure gives one founder a numerical majority, but that does not automatically solve every governance issue.

    Founders should consider roles, capital contribution, expected workload, decision-making rights, vesting, founder exits and dispute resolution.

    A written Co-Founder Agreement can help document these arrangements before disagreements arise.

    Is having three co-founders too much?

    Three co-founders are not inherently too many. The real question is whether each founder contributes something important to the business.

    Three complementary founders may divide responsibilities effectively. However, three founders can also create disagreements over authority, equity and decision-making.

    The founders should establish clear responsibilities and governance arrangements from the beginning.
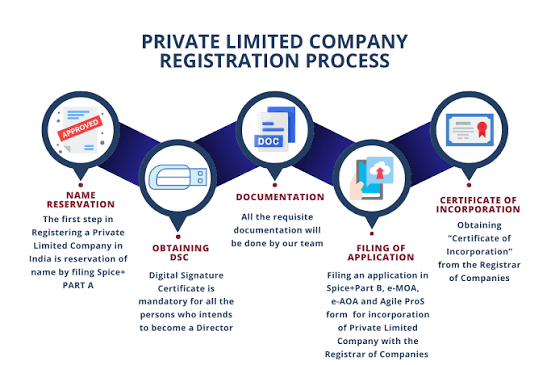
    What is the 80/20 rule for startups?

    The 80/20 rule, also called the Pareto principle, is the idea that a relatively small portion of inputs can sometimes produce a large portion of results.

    What does Pareto mean?

    The principle is associated with Italian economist Vilfredo Pareto. The concept became widely used in business to describe situations where results are unevenly distributed.

    The ratio does not have to be exactly 80/20. The important idea is to identify the activities or inputs producing the greatest impact.

    What is the 80/20 rule in business?

    A business might discover that a small group of customers generates a large share of revenue. Another business might find that a few products generate most sales.

    Similarly, a small number of marketing channels may produce most qualified leads.

    How does the 80/20 rule apply to startups?

    Founders can use the principle to identify high-impact activities.

    • Which customers generate the most revenue?
    • Which products have the strongest margins?
    • Which marketing channels produce the best leads?
    • Which tasks directly support growth?
    • Which expenses create little measurable value?

    The objective is not to force every business into an 80/20 ratio. Instead, founders can use their own data to decide where limited resources should go.

    Does the 80/20 rule really work?

    It can be a useful management principle, but it is not a guaranteed mathematical formula. Some businesses may have a very different distribution of results.

    Founders should therefore test the idea against actual customer, revenue and operational data.

    Why do startups fail in India?

    Startup failure is often discussed using simple statistics. However, the frequently repeated claim that 90% of startups fail should not be treated as a universal rule for every startup, sector or period.

    1) Is it true that 90% of startups fail?

    The “90% failure” statement is commonly repeated online, but the exact figure depends on how failure is defined and which companies are included in the dataset.

    A startup shutting down, being acquired, becoming inactive or failing to achieve its original growth target are not necessarily the same event.

    Founders should therefore focus on measurable risks instead of relying on a single failure percentage.

    2) Why do startups fail?

    Common reasons include:

    • Lack of product-market fit.
    • Insufficient customer demand.
    • Poor cash-flow management.
    • Running out of funding before reaching important milestones.
    • Weak pricing or unit economics.
    • Premature expansion.
    • Founder disagreements.
    • Strong competition.
    • Regulatory or compliance problems.
    • Failure to retain customers.

    Funding itself cannot fix a weak business model. A startup can raise substantial capital and still fail if it cannot create sustainable customer demand.

    3) Why do some startups fail after raising funding?

    External funding can increase the amount of money available, but it can also increase spending expectations.

    If a startup hires too quickly, spends heavily on marketing without proven economics or expands before establishing product-market fit, a large funding round can disappear faster than expected.

    Founders should treat every funding round as capital for achieving specific business milestones.

    Legal and compliance preparation before raising funds

    Investors usually want confidence that the company is legally organised and that its records accurately reflect the business.

    1) Choose an appropriate business structure

    Many startups that plan to raise equity investment choose a Private Limited Company because it provides a share-based corporate structure that is familiar to investors.

    However, the right structure depends on the business. Founders should compare the legal, tax and compliance implications before incorporation.

    Lawizer’s comparison of OPC, LLP and Private Limited Company can help founders understand the major differences.

    2) Protect the brand and intellectual property

    Your company name, logo, technology, content and other intellectual property can become valuable business assets.

    Consider protecting the brand through Trademark Registration where appropriate.

    Founders should also ensure that intellectual property created by founders, employees and contractors is properly assigned to the company where required.

    3) Keep tax and GST records organised

    Tax and GST compliance can become part of investor due diligence. Missing filings or inconsistent records may create unnecessary questions during a funding round.

    Where GST registration is applicable, Lawizer provides GST Registration and related compliance support.

    4) Maintain annual corporate compliance

    A company continues to have legal and reporting obligations after incorporation. Annual filings, financial statements, auditor-related requirements and other compliance obligations should be handled on time.

    Lawizer’s Annual Compliance service can help businesses manage recurring corporate compliance requirements.

    Common startup fundraising mistakes to avoid

    1) Raising money without a clear purpose

    Do not raise capital simply because funding is available. Define the milestones the money is expected to achieve.

    2) Giving away too much equity

    Consider valuation, dilution and future funding requirements before accepting an equity investment.

    3) Ignoring founder arrangements

    Verbal agreements between founders can become difficult to enforce or interpret later. Put important arrangements in writing.

    4) Having an inaccurate cap table

    Ownership records should be consistent across corporate records, investment documents and internal records.

    5) Ignoring compliance until the investor arrives

    Trying to repair years of missing filings immediately before a funding round can delay the transaction.

    Lawizer’s guide on why compliance gaps can affect startup funding rounds explains why legal readiness matters during due diligence.

    Frequently Asked Questions About How Startups Raise Funds in India

    1) How do most startups raise money?

    Startups commonly use bootstrapping, friends and family funding, angel investment, venture capital, loans, incubator support and government schemes. The most suitable option depends on the startup’s stage and financial needs.

    2) What is a ₹20 lakh grant for startups?

    The ₹20 lakh figure refers to the grant component available under the Startup India Seed Fund Scheme for eligible purposes such as proof of concept, prototype development and product trials. It is subject to eligibility and scheme conditions.

    3) What is a 20 lakh grant for startups?

    It is generally a reference to the Startup India Seed Fund Scheme’s provision for a grant of up to ₹20 lakh for specified early-stage activities. It should not be treated as an automatic grant for every startup.

    4) How to get money from government for startup?

    Identify a suitable central or state scheme, check eligibility, prepare the required documents and apply through the designated official channel or incubator. DPIIT recognition may be relevant for certain programmes.

    5) Is 1% equity in a start-up good?

    It depends on the company’s valuation, investment amount, growth prospects, investor rights and future dilution. The percentage alone does not determine whether an investment is good.

    6) How much equity should a CEO get in a startup?

    There is no standard percentage. Founder CEOs and professional CEOs may have very different compensation structures. Equity should reflect contribution, responsibilities, ownership arrangements and the company’s future funding plans.

    7) Should co-founders be 50/50 or 51/49?

    Both structures can work. Founders should consider contribution, responsibilities, decision-making, vesting and dispute resolution rather than choosing a percentage simply because it is common.

    8) Is 1% equity in a startup good?

    There is no universal answer. A 1% stake can be significant in a valuable company, but it can also become heavily diluted or have little value if the business does not succeed.

    9) Is 3 co-founders too much?

    No. Three founders can work well when their skills and responsibilities are complementary. The key is to document ownership, roles, authority and exit arrangements clearly.

    10) Is it true that 90% of startups fail?

    The 90% figure is a commonly repeated generalisation. The actual rate depends on the dataset, definition of failure, sector and period being studied.

    11) What is the Pareto rule?

    The Pareto principle suggests that a relatively small portion of inputs may produce a disproportionately large portion of results. It is often called the 80/20 rule.

    12) What is the 80-20 rule in business and how does it apply?

    Businesses can use it to identify customers, products, marketing channels or activities that generate a large share of their results. The exact ratio does not need to be 80/20.

    13) What does Pareto mean?

    Pareto refers to Vilfredo Pareto, whose observations about unequal distributions later became the basis of the Pareto principle used in business and management.

    14) What is the 80/20 rule in Pareto?

    It is the idea that approximately 80% of outcomes may sometimes come from approximately 20% of causes or inputs. It is a practical principle rather than a universal law.

    15) Does the 80/20 rule really work?

    It can help businesses focus on high-impact areas, but the exact distribution varies. Founders should use their own data rather than assuming that every business follows an 80/20 split.

    16) What is the 80/20 rule for startups?

    For startups, it can be used to identify the customers, products, channels and activities that contribute most to revenue or growth. This can help founders allocate limited resources more effectively.

    17) What are the top 10 failed startups in India?

    There is no universally accepted list of the top 10 failed startups. Different sources use different definitions of failure. It is more useful to study failed businesses by looking at factors such as product-market fit, cash flow, competition, execution and governance.

    18) Why do 90% of startups fail in India?

    There is no reliable universal rule that exactly 90% of Indian startups fail. Common causes of failure include weak market demand, poor financial management, excessive spending, founder disputes, competition and regulatory challenges.

    19) What are the richest startups in India?

    Startup wealth can be measured in different ways, including valuation, revenue and founder wealth. These measures are not interchangeable. A company’s valuation can also change significantly between funding rounds.

    Final takeaway: choose the funding that fits your startup

    Learning how startups raise funds in India is only the first step. The more important decision is choosing a funding method that fits your business model, growth stage and ability to manage financial and legal obligations.

    Before approaching investors, make sure your company structure, ownership records, founder agreements, intellectual property documents, tax records and statutory filings are organised.

    Funding should help your startup reach meaningful milestones. It should not become a goal by itself.

    Need help getting your startup funding-ready?

    If you are preparing for your first funding round, Lawizer can help you organise the legal and compliance foundation behind your business.

    Planning to raise funds? Get your legal structure, founder arrangements and compliance records in order before you approach investors. Consult Lawizer for practical startup legal and compliance support.

  • ESOP Guide for Startups: Equity Plans Explained

    ESOP Guide for Startups: Equity Plans Explained


    ESOP Guide for Startups: Equity Plans Explained

    An ESOP guide for startups is useful for founders who want to attract and retain talented employees without relying only on higher salaries. An Employee Stock Option Plan gives eligible employees the right to acquire shares in the company in the future, subject to the terms of the scheme.

    For an Indian startup, however, ESOPs are more than an employee benefit. They involve company law, shareholder dilution, vesting, exercise terms, tax implications and proper documentation. A well-designed plan can align employees with the long-term growth of the business. A poorly structured plan can create confusion about ownership, taxation and exit rights.

    This guide explains how startup ESOPs work, how equity is allocated, how vesting works, what employees should check and what founders should consider before implementing an ESOP scheme.

    ESOP guide for startups explaining employee equity, vesting and taxation in India
    Understanding employee stock options, vesting and equity can help Indian startups structure employee incentives more effectively.

    What Is an ESOP for a Startup?

    An Employee Stock Option Plan, commonly called an ESOP, is a plan under which eligible employees receive an option or right to acquire shares of the company at a future date at a predetermined price, subject to the applicable scheme and legal requirements.

    Under the Companies Act, 2013, an employee stock option is broadly defined as an option given to eligible directors, officers or employees that provides a benefit or right to purchase or subscribe for company shares at a future date at a predetermined price.

    The important point is that receiving an ESOP does not normally mean that an employee immediately owns the underlying shares. The employee first receives an option. That option may become exercisable after the relevant vesting conditions are satisfied.

    ESOP, shares and options: What is the difference?

    • Option: A contractual right to acquire shares in accordance with the ESOP terms.
    • Vesting: The process through which the employee earns the right to exercise vested options.
    • Exercise: The employee uses the vested option and pays the applicable exercise price, subject to the scheme.
    • Shares: After a valid exercise and allotment/transfer process, the employee becomes a shareholder to the extent provided by the applicable documents.

    Why Do Startups Offer Employee Stock Options?

    Startups often compete with established companies for employees. A young business may not have the cash resources to match every large company’s salary package. Equity-based incentives can provide another way to reward employees for contributing to long-term growth.

    Common reasons for creating an ESOP scheme include:

    • Attracting skilled employees.
    • Retaining key employees for longer periods.
    • Aligning employee incentives with company performance.
    • Creating a sense of long-term ownership.
    • Balancing cash compensation with potential future upside.

    Founders should still remember that an ESOP is not a guaranteed substitute for salary. The eventual value of startup equity depends on the company’s performance, valuation, dilution, liquidity and the terms attached to the options.

    How Does an ESOP Work in a Startup Company?

    The basic process can be understood through five stages: creating the pool, granting options, vesting, exercising and eventually holding or selling the shares where a lawful liquidity opportunity exists.

    1. Create the ESOP pool

    The company first determines how many shares may be reserved for employee options. The size should reflect expected hiring, employee seniority, future fundraising and the founders’ desired ownership structure.

    There is no universal ESOP percentage that is correct for every startup. A founder should model the proposed pool against the company’s current cap table and expected future funding rounds.

    2. Grant options to employees

    The company may grant a specified number of options to an eligible employee under the approved scheme. The grant documentation should clearly state relevant terms such as the number of options, exercise price, vesting conditions and applicable exercise period.

    3. Vesting

    Vesting determines when the employee earns the right to exercise the options. A scheme may use a cliff followed by monthly or quarterly vesting, depending on its terms.

    For example, a four-year vesting structure with a one-year cliff is common in startup practice. However, it should not be treated as a mandatory legal formula. The actual terms depend on the company’s ESOP scheme and grant documentation.

    4. Exercise

    Once options become vested and the employee meets the applicable conditions, the employee may exercise them by following the procedure in the ESOP scheme and paying the exercise price.

    The employee should understand the exercise price before accepting an ESOP grant. A large number of options does not automatically mean a valuable grant.

    5. Holding or selling the shares

    After exercise and the relevant corporate process, the employee may hold shares. Selling those shares depends on applicable law, the company’s constitutional documents, shareholder arrangements and whether a genuine liquidity opportunity exists.

    Private startup shares are generally not as liquid as listed shares. An employee should therefore avoid treating an ESOP grant as cash in hand.

    How Much Equity Should a Startup Give Employees?

    There is no single percentage that works for every startup. The right allocation depends on the company’s stage, valuation, existing shareholders, hiring plans, employee role and expected future dilution.

    Is 1% Equity in a Startup Good?

    One percent can be meaningful in one startup and relatively small in another. The percentage should always be examined alongside the company’s total share capital, valuation, ESOP pool and expected dilution.

    An employee evaluating a 1% grant should ask:

    • Is the 1% calculated on a fully diluted basis?
    • How many options does the percentage represent?
    • What is the exercise price?
    • What is the vesting schedule?
    • What happens if the employee leaves?
    • Are there restrictions on transferring the shares?
    • What future fundraising could dilute the holding?

    How Much Equity Should a CEO Get in a Startup?

    CEO equity is highly dependent on whether the CEO is also a founder. A founder-CEO may hold a substantial founding stake, while a professional CEO hired later may receive a smaller equity package combined with salary and other incentives.

    Instead of copying another startup’s percentage, founders should consider responsibility, joining stage, capital contributed, previous experience, expected contribution and future dilution.

    How Much Equity Do Startup Employees Get?

    Employee grants vary widely. Early senior employees may receive larger grants because they join when the company carries greater risk. Later employees may receive smaller grants because the company has progressed further and its valuation may be higher.

    Roles that are critical to the startup’s growth may also receive different grants from general positions. The most important point is to document the grant precisely rather than making informal promises such as “you will get 1% later.”

    ESOP Guide for Startups: Understanding Vesting

    Vesting is one of the most important concepts in an ESOP. It prevents an employee from receiving the full economic benefit of an option grant immediately when the company’s objective is to reward continued service.

    What is a cliff?

    A cliff is an initial period during which no options vest. Once the cliff is completed, a specified portion may vest at once, followed by periodic vesting under the scheme.

    For example, if a scheme uses a four-year vesting period with a one-year cliff, an employee may receive no vested options during the first year and then become entitled to the portion specified in the scheme at the one-year point. The remaining options may vest periodically afterward.

    The exact terms should always be checked in the approved ESOP scheme and individual grant letter.

    ESOP Taxation in India

    Tax is one of the most important parts of any startup equity plan. Employees should understand that ESOP taxation can involve different stages and that the tax treatment depends on the applicable law and circumstances.

    Is ESOP Taxable Under Salary?

    Generally, the taxable value of specified securities or sweat equity received under an ESOP arrangement can be treated as a perquisite under the income-tax rules at the relevant stage of exercise, subject to the applicable provisions.

    For eligible unlisted shares, fair market value may need to be determined using the prescribed valuation rules. Current income-tax rules provide specific mechanisms for determining fair market value, including valuation by a merchant banker in relevant cases.

    Because tax rules can change, employees should verify the calculation applicable for the relevant assessment year rather than relying on an old ESOP calculator or internet example.

    How to Calculate ESOP in Salary

    At a simplified level, the taxable perquisite is generally linked to the fair market value of the security on the relevant date less the amount actually paid by the employee, subject to the applicable provisions and valuation rules.

    For example, suppose an employee exercises options when the relevant fair market value is ₹100 per share and the exercise price is ₹40. The difference of ₹60 per share is the basic economic difference used in the perquisite calculation, subject to the tax rules applicable to that employee and transaction.

    This example is for understanding the concept only. The actual tax calculation can involve specific valuation rules, eligibility conditions and tax treatment.

    What Happens When ESOP Shares Are Sold?

    Taxation may also arise when the employee later sells the shares. At that stage, capital gains rules can become relevant. The applicable treatment depends on factors such as the type of shares, holding period, acquisition cost determined under tax law and the date of sale.

    Employees should therefore keep their grant letter, exercise records, valuation documents, tax statements and sale documentation.

    Do I Need to Declare ESOP in ITR?

    ESOP-related income and capital gains may need to be reported in the appropriate income-tax return, depending on what occurred during the financial year and the taxpayer’s circumstances.

    The Income Tax Department’s current guidance also identifies situations involving unlisted shares and deferred ESOP taxation that affect eligibility for simplified return forms. Therefore, employees should choose the correct ITR form rather than assuming that a salary-only return is always sufficient.

    If your ESOPs involve foreign shares or foreign assets, additional reporting requirements may apply. In such cases, professional tax advice is particularly important.

    Is ESOP Part of CTC?

    There is no universal rule that every ESOP must be treated as a fixed part of CTC in the same way as basic salary or other cash components. Employers may present equity separately or include it in an overall compensation discussion.

    Employees should read the offer letter and ESOP documents carefully. Look beyond the headline CTC and check the number of options, exercise price, vesting schedule and other conditions.

    What Are the Benefits of ESOPs for Startups?

    Attract and retain talent

    Equity can make an early-stage offer more attractive to employees who believe in the company’s long-term potential.

    Align employees with growth

    When employees have an economic interest in the company’s success, the incentive structure can encourage a longer-term perspective.

    Reduce pressure on cash compensation

    ESOPs can complement salary and benefits, particularly when a startup is managing limited cash resources.

    Build an ownership culture

    A properly explained option plan can help employees understand how their work connects with company value.

    What Are the Disadvantages of ESOPs?

    ESOPs are not risk-free. Founders and employees should understand the downside before signing the documents.

    • Dilution: New shares issued on exercise can reduce existing shareholders’ percentage ownership.
    • No guaranteed value: Startup equity may never become liquid or profitable.
    • Tax exposure: Tax can arise at the exercise stage in applicable circumstances, even when the employee has not sold the shares.
    • Administrative complexity: Companies need proper records, approvals and documentation.
    • Employee expectations: Confusion about valuation or future liquidity can create dissatisfaction.

    Is ESOP a Trap?

    An ESOP is not automatically a trap. It becomes risky when employees accept an equity grant without understanding what they are actually receiving.

    When can an ESOP become risky?

    • The exercise price is not properly understood.
    • The company has no realistic liquidity pathway.
    • The employee does not understand vesting or exit conditions.
    • The quoted percentage is not defined on a clear basis.
    • Future funding may cause significant dilution.
    • The tax implications have not been considered.

    How employees can evaluate an ESOP

    Before accepting a grant, ask the company for the relevant ESOP scheme and grant documentation. Review:

    • Number of options.
    • Exercise price.
    • Vesting schedule.
    • Cliff period, if any.
    • Exercise window.
    • What happens after resignation or termination.
    • Transfer restrictions.
    • Potential dilution.
    • Tax implications.

    The percentage alone is not enough to determine whether an ESOP is attractive.

    ESOP Guide for Startups: ESOP vs RSU

    ESOPs and Restricted Stock Units, or RSUs, are both equity-linked compensation tools, but they are not identical.

    Key differences between ESOPs and RSUs

    • ESOP: Generally gives an option or right to acquire shares subject to the plan.
    • RSU: Generally represents a promise to deliver shares or their value after specified vesting conditions are satisfied.
    • Exercise: Options typically involve an exercise process, while RSUs generally do not operate in the same way.
    • Tax: Tax treatment differs and must be assessed under the applicable provisions.

    There is no universal answer to whether ESOP or RSU is better. The appropriate structure depends on the company, employee, tax position, legal framework and liquidity expectations.

    Can a Company Buy Back ESOP Shares?

    A company may have ways to provide liquidity to shareholders, but a buyback is not simply an automatic right created by receiving an ESOP. Any company buyback must comply with the applicable legal requirements and corporate documents.

    Why might a startup provide an ESOP liquidity opportunity?

    • To provide employees with some liquidity.
    • To reward long-term contributors.
    • To support employee retention.
    • To facilitate a structured secondary transaction or exit.

    The exact mechanism can depend on the company’s structure, applicable law, shareholder arrangements and transaction terms. Employees should not assume that every startup will provide a buyback.

    How to Create an ESOP Plan for a Startup in India

    For an Indian company, an ESOP should be treated as a formal corporate and legal process rather than an informal promise to employees.

    Step 1: Decide the objective and pool

    Determine why the company wants an ESOP and how much equity it may need for current and future employees.

    Step 2: Review the company’s capital structure

    Prepare a clear cap table showing founders, investors, existing shareholders and the proposed option pool. Model potential dilution before finalising the pool.

    Founders should also consider related shareholder arrangements. Lawizer’s guide to shareholders’ agreements for startups explains why equity, transfer and governance provisions deserve careful drafting.

    Step 3: Draft the ESOP scheme

    The scheme should address matters such as eligibility, number of options, vesting, exercise price, exercise period, lapse conditions and treatment when an employee leaves.

    Step 4: Obtain the required approvals

    Section 62(1)(b) of the Companies Act, 2013 and the Companies (Share Capital and Debentures) Rules, 2014 contain the principal framework for employee stock options for companies to which those provisions apply. Required corporate approvals and disclosures should be completed according to the applicable rules and the company’s circumstances.

    The MCA framework also provides for maintaining a register of employee stock options. Proper records are therefore an important part of implementation.

    Step 5: Issue grants and maintain records

    Each employee should receive appropriate grant documentation. The company should maintain accurate records of grants, vesting, exercises, lapsed options and resulting shareholding.

    Step 6: Review the plan periodically

    Fundraising, acquisitions, changes in valuation and hiring plans can affect the usefulness of an ESOP pool. Review the plan when the company’s capital structure changes.

    If your business is still being incorporated, Lawizer provides Private Limited Company incorporation and startup legal services that can help founders establish the corporate structure needed for an equity-based growth plan.

    What Are the 7 Stages of a Startup?

    There is no single legally prescribed seven-stage startup lifecycle. However, founders commonly describe startup development through stages such as:

    1. Idea and problem validation.
    2. Product development.
    3. Pre-seed or seed funding.
    4. Early market traction.
    5. Growth and expansion.
    6. Scaling operations.
    7. Maturity, acquisition or another exit pathway.

    The ESOP strategy can change as the company moves through these stages. Early employees may receive larger grants because they take greater business risk. Later grants may be smaller as the company’s valuation and workforce increase.

    Common ESOP Mistakes Startups Should Avoid

    • Making informal equity promises.
    • Creating an option pool without modelling dilution.
    • Failing to explain the exercise price.
    • Ignoring vesting and exit provisions.
    • Not keeping the cap table updated.
    • Failing to maintain statutory and internal records.
    • Ignoring tax consequences for employees.
    • Using an outdated template without checking current law.
    • Promising employees a guaranteed future value.
    • Failing to review the scheme after funding or restructuring.

    Equity documentation should also be coordinated with other startup agreements. Lawizer’s founder’s agreement guide explains why roles, equity, vesting and exit arrangements should be addressed in writing.

    ESOP Guide for Startups: Frequently Asked Questions

    How does ESOP work in a startup company?

    An ESOP gives eligible employees options to acquire company shares subject to the scheme. Options generally vest according to specified conditions and may then be exercised at the applicable exercise price.

    Is ESOP taxable under salary?

    In applicable cases, the benefit arising when specified securities or sweat equity are allotted or transferred under an employee stock option arrangement can be taxed as a salary perquisite. The exact calculation depends on the applicable income-tax provisions and valuation rules.

    Do I lose my ESOP if I get fired?

    It depends on the ESOP scheme and the employee’s grant terms. Unvested options may lapse when employment ends, while vested options may remain exercisable for a specified period or may be subject to other conditions. Always check the termination provisions.

    Do I need to declare ESOP in ITR?

    ESOP-related taxable income, capital gains and applicable foreign-asset information may need to be reported in the appropriate income-tax return. The correct reporting depends on what happened during the financial year and the taxpayer’s circumstances.

    How to calculate ESOP in salary?

    For applicable ESOP taxation, the taxable perquisite generally involves the prescribed fair market value at the relevant exercise point minus the amount paid by the employee, subject to the applicable tax and valuation rules.

    Is ESOP part of CTC?

    It depends on how the employer structures and presents the compensation package. Employees should separately review the ESOP grant, number of options, exercise price and vesting terms instead of relying only on the total CTC figure.

    Is ESOP better than salary?

    Neither is automatically better. Salary provides predictable current income, while ESOPs may provide future upside but also carry risk and liquidity limitations. The right balance depends on the employee and the startup.

    Should cofounders be 50/50 or 51/49?

    There is no universally correct founder split. The allocation should reflect contribution, roles, responsibilities, investment, future commitment and decision-making arrangements. Founders should document the arrangement in a properly drafted agreement.

    Is it true that 90% of startups fail?

    There is no single reliable universal failure percentage that applies to every startup, country, industry and time period. Founders should avoid making equity decisions based on a simplified statistic and instead assess the actual risk of the business.

    Is 30% equity good?

    Thirty percent may be substantial, but the percentage alone does not determine value. The company’s valuation, share count, dilution, vesting, exercise price and exit prospects all matter.

    What is the 80/20 rule for startups?

    The 80/20 rule, or Pareto principle, is a general business idea suggesting that a relatively small number of inputs may produce a large proportion of results. It is not a statutory startup rule and should not be treated as a fixed formula for equity allocation.

    Why do startups fail?

    Startups can fail for many reasons, including weak product-market fit, insufficient capital, poor execution, regulatory issues, ineffective sales, competition and founder or team problems. There is no single cause that applies to every failed startup.

    At what stage do most startups fail?

    Failure can occur at different stages. Early-stage startups may struggle with product-market fit and funding, while later-stage businesses can face scaling, governance or cash-flow problems. Risk changes rather than disappearing as the company grows.

    What are the 10 steps in the startup process?

    A practical startup journey may include identifying a problem, validating the idea, choosing a business structure, incorporating, protecting intellectual property, building the product, finding customers, raising capital, hiring a team and scaling operations. The exact sequence varies by business.

    What are the 5 key elements of a startup?

    Five useful areas to evaluate are the problem, solution, market, team and financial model. Legal structure and compliance should support these areas from the beginning.
    What’s the next stage after startup?

    There is no universally defined stage after “startup.” A successful company may move into growth, scale-up, maturity, acquisition or public-market preparation depending on its business model.

    How many types of startups are there?

    There is no fixed legal classification that limits startups to a particular number of types. Startups may be described as technology, fintech, SaaS, D2C, social-impact, marketplace or other businesses based on their model and industry.

    What are the five pillars of a successful startup?

    A practical framework is a strong problem-solution fit, capable team, sustainable economics, effective execution and sound legal and financial governance. The exact framework can vary between businesses.

    What are the disadvantages of ESOPs?

    Potential disadvantages include dilution, uncertain value, tax exposure, administrative requirements and limited liquidity. Both founders and employees should understand these risks before implementing or accepting an ESOP.

    Which is better, ESOP or RSU?

    Neither is universally better. Options and RSUs have different legal, tax and economic characteristics. The appropriate structure depends on the company, employee, jurisdiction and applicable rules.

    How many ESOPs fail?

    There is no meaningful universal failure rate for ESOPs. An option grant may expire, lapse or become economically unattractive without representing a failure of the ESOP scheme itself.

    Can a company buy back ESOP?

    A company may provide liquidity through a legally compliant buyback or another permitted transaction, but employees should not assume that a buyback is guaranteed. The company’s documents and applicable law must be reviewed.

    Final Thoughts: Should Your Startup Create an ESOP?

    A well-structured ESOP can be a powerful tool for an Indian startup. It can help attract talent, encourage retention and connect employees with the company’s long-term success.

    However, equity should never be treated casually. Founders need to consider the ESOP pool, dilution, vesting, exercise terms, employee exits, taxation, corporate approvals and ongoing records.

    If your startup is planning to introduce employee equity, it is also worth reviewing its wider legal structure. Lawizer can help with startup incorporation and business legal requirements, while its guide to setting up ESOPs for startup employees provides additional context on scheme design, vesting and compliance.

    For founders who are still deciding their structure, Lawizer’s startup registration guide explains the incorporation process and related registrations. You can also explore shareholders’ agreement considerations when your equity structure involves multiple shareholders or investors.

    Need Help Structuring Your Startup’s Equity?

    ESOPs sit at the intersection of corporate law, employee compensation, taxation and shareholder rights. Before issuing options, founders should ensure that the scheme and supporting documents match the company’s structure and current legal requirements.

    Consult Lawizer for practical startup legal and compliance support. You can review the available startup and business legal services from Lawizer and discuss the requirements of your company before implementing an employee equity plan.

    Important: This article provides general educational information and is not a substitute for personalised legal, tax or financial advice. ESOP rules, tax provisions, valuation requirements and corporate compliance can change. Obtain professional advice for your specific transaction.

  • How to Open a Current Account for Business in India :

    How to Open a Current Account for Business in India :

    Featured image alt text: how to open a current account for business in India

    Starting a business involves more than choosing a name and finding customers. A separate bank account helps you manage business income, expenses, vendor payments and customer collections more efficiently. If you are wondering how to open a current account for business in India, the process generally involves choosing the right account, preparing KYC and business documents, completing the bank’s verification process and meeting any applicable account conditions.

    The exact requirements can vary depending on your business structure, the bank you choose and the nature of your transactions. A sole proprietor may have a different document requirement from a private limited company or an LLP. GST registration is also a separate legal requirement and is not automatically compulsory merely because you want to open a current account.

    This guide explains the process in simple terms, including eligibility, documents, GST, minimum balance, charges, large deposits and how to compare business banking options.

    What Is a Business Current Account?

    A current account is a bank account designed primarily for frequent transactions. Businesses commonly use current accounts to receive payments from customers, pay suppliers, manage operating expenses and handle regular business transactions.

    Unlike a typical savings account, a current account is generally designed around transaction convenience rather than earning interest on the account balance. The features, transaction limits and charges depend on the bank and the particular account product.

    Why Do Businesses Need a Current Account?

    A dedicated business account can make financial management much easier. It helps keep business transactions separate from personal spending and creates a clearer record for bookkeeping and tax purposes.

    • Receive payments from customers.
    • Pay suppliers, employees and service providers.
    • Track business income and expenses separately.
    • Manage regular bank transfers and collections.
    • Maintain cleaner financial records for accounting and tax purposes.
    • Access business-focused banking facilities offered by the bank.

    Separating business and personal transactions is particularly useful when the business begins handling a larger number of payments. It can also make it easier for your accountant or tax professional to reconcile business transactions.

    Current Account vs Savings Account

    A savings account is generally intended for personal savings and routine individual transactions. A current account is designed for businesses and other customers who need frequent commercial transactions.

    Before choosing an account, compare the transaction limits, cash-handling charges, minimum balance requirements, digital banking features and other conditions rather than choosing an account only because it has a low opening requirement.

    Who Can Open a Business Current Account?

    Banks may offer current accounts to several types of businesses. The documentation depends largely on the legal structure and the bank’s KYC requirements.

    • Sole proprietorships: The proprietor’s identity must be verified along with documents establishing the business or business activity.
    • Partnership firms: The bank may require the partnership deed, PAN and KYC documents of relevant partners or authorised persons.
    • LLPs: The LLP’s incorporation and constitutional documents, PAN and details of designated partners or authorised signatories may be required.
    • Private limited companies: The company generally provides incorporation and constitutional documents, PAN and authorisation for operating the account.
    • Other eligible organisations: Trusts, societies and other entities may have their own documentation and authorisation requirements.

    If you have not yet formalised your business, consider the structure before opening the account. Lawizer provides guidance on Private Limited Company registration, One Person Company registration and LLP registration.

    How to Open a Current Account for Business in India

    For most founders, the process can be broken into a few practical steps. The bank may request additional information depending on its internal policies and your business profile.

    Step 1: Choose the Right Business Bank Account

    Start by identifying how your business will use the account. A small consultancy with mostly digital payments may have different needs from a retailer that deposits cash regularly.

    Consider:

    • Expected monthly transaction volume.
    • Cash deposits and withdrawals.
    • Online payment requirements.
    • NEFT, RTGS and IMPS facilities.
    • Cheque and collection facilities.
    • Minimum balance requirements.
    • Cash deposit limits and charges.
    • Internet and mobile banking features.
    • Availability of branches or relationship managers.

    Do not select an account solely because the bank advertises it as “free”. Check the complete schedule of charges and account conditions.

    Step 2: Check the Eligibility and Documentation

    The bank will need to establish who owns or controls the business and who is authorised to operate the account. KYC requirements apply to account opening, and additional business information may be requested.

    For a company or LLP, make sure the entity’s legal name is consistent across the documents. For a proprietorship, keep documents showing the proprietor’s identity and the existence or activity of the business ready.

    Step 3: Prepare the Required Documents

    Prepare your PAN, identity and address documents and business registration or activity proofs before submitting the application. The exact list differs between banks and business structures.

    Step 4: Submit the Application

    Many banks allow applications to begin online, while some account types may require additional verification or a branch interaction. Complete the application with accurate information about the business, beneficial owners, authorised signatories and expected account activity.

    Step 5: Complete KYC and Business Verification

    The bank may verify the identity of the relevant individuals, the business address and the nature of the business. It may also ask questions about the expected transaction pattern or source of funds.

    RBI’s KYC framework requires regulated entities to conduct customer due diligence when establishing account relationships. For sole proprietary firms, additional business or activity documents may be required along with the proprietor’s KYC.

    Read the RBI KYC Directions and amendments for the regulatory framework applicable to customer due diligence.

    Step 6: Activate and Start Using the Account

    Once the bank completes its verification and opens the account, follow the bank’s instructions for activation. Set up internet banking, mobile banking, authorised users and transaction controls where applicable.

    Keep the account opening documents and statements safely. They can become important records for accounting, taxation, audits and business compliance.

    Documents Required to Open a Business Current Account

    There is no single document list that applies identically to every business. Banks can request documents according to their KYC policy and the nature of the entity.

    Common Documents

    • PAN of the business or relevant person, as applicable.
    • Identity and address proof of the proprietor, partners, directors or authorised signatories.
    • Business address proof.
    • Business registration or incorporation documents, where applicable.
    • GST registration certificate, where applicable.
    • Partnership deed or LLP agreement, where applicable.
    • Company constitutional documents and account-opening authorisation, where applicable.
    • Photographs or other KYC information requested by the bank.

    Documents for a Sole Proprietorship

    A proprietor normally needs to establish both the identity of the individual and the identity or business activity of the proprietary concern. RBI’s KYC directions specifically provide for customer due diligence of the proprietor and business or activity proof for a sole proprietary firm.

    The accepted documents can vary, so check the bank’s current list before applying. If you need to formalise a sole business, you can also explore Lawizer’s startup and business legal services.

    Documents for an LLP or Company

    An LLP or company generally has its own legal identity. The bank may therefore request incorporation documents, PAN, constitutional documents, registered office information and evidence showing who is authorised to operate the account.

    If you are still deciding between business structures, Lawizer’s guide on Private Limited vs LLP vs Sole Proprietorship can help you compare the main differences.

    For a more detailed document checklist, see Lawizer’s guide on documents required for company registration in India.

    Can I Open a Current Account Without GST?

    Yes, a business may be able to open a current account without GST registration if the business is not otherwise required to register under GST and the bank accepts the available business documents.

    It is important to separate two questions: whether a bank will open the account and whether the business is legally required to register under GST. A current account does not by itself create GST registration liability.

    When Is GST Registration Required?

    GST registration depends on factors such as aggregate turnover, the nature of supplies, the state or territory involved and specific compulsory-registration provisions. Thresholds and exceptions can differ depending on the circumstances.

    For this reason, do not assume that you need GST registration simply because a bank asks whether you have a GSTIN. Conversely, do not assume that GST is unnecessary just because your turnover is currently low.

    The official GST framework contains both threshold-based registration rules and specific cases where registration can become compulsory. You can check the CBIC GST FAQs and the GST registration rules for the applicable provisions.

    If you need help determining whether your business should register, Lawizer provides GST registration support.

    Can a Proprietorship Open a Current Account Without GST?

    A proprietorship does not automatically need GST registration simply to have a business bank account. However, the proprietor must satisfy the bank’s KYC and business-proof requirements.

    Depending on the bank, accepted business proof may include relevant registrations, licences or other documents that establish the name, address and activity of the concern.

    How Much Money Is Required to Open a Current Account?

    There is no single opening amount that applies to every current account in India. Banks offer different products with different opening requirements, minimum balance conditions and fee structures.

    Opening Deposit vs Minimum Balance

    These are two different concepts. An opening deposit is the amount the bank may require when the account is opened. A minimum or average balance condition determines whether you need to maintain a particular balance after opening the account.

    Always check the bank’s latest terms before opening an account. A product with a low opening deposit can still have higher maintenance or transaction charges.

    Are Zero-Balance Business Current Accounts Available?

    Some banks may offer products with low or zero balance requirements, but eligibility and conditions vary. “Zero balance” does not necessarily mean that every banking service is free.

    Check transaction limits, cash handling fees, payment charges and other service fees before deciding.

    Which Bank Is Good to Open a Current Account for Business?

    There is no single bank that is best for every business. The right choice depends on your transaction pattern and the services your business actually uses.

    What Should Small Business Owners Compare?

    • Monthly or quarterly balance requirements.
    • Cash deposit and withdrawal charges.
    • Digital banking facilities.
    • NEFT, RTGS and IMPS charges.
    • Cheque and collection services.
    • Transaction and withdrawal limits.
    • Payment collection and merchant services.
    • Branch and customer support availability.
    • Business loan or credit facilities, if required.

    Which Bank Is Best for Small Business Owners?

    A small business that receives most payments digitally may value strong online banking and payment integrations. A cash-heavy retailer may care more about cash deposit limits, branch access and cash-handling charges.

    Similarly, a growing company may prefer a bank with stronger business credit, collection and payment infrastructure. The best account is therefore the one that fits your actual operating pattern.

    Which Is the Cheapest Business Bank Account?

    The cheapest account is not always the one with the lowest advertised fee. Calculate the likely total cost based on how your business will use the account.

    For example, a business that makes frequent cash deposits should pay close attention to cash-handling charges. A digital-first company should compare online transaction and payment-related charges.

    Can I Deposit ₹50 Lakh in My Current Account?

    A balance of ₹50 lakh is not, by itself, a universal prohibition on holding money in a current account. However, large transactions can attract greater scrutiny, and businesses should be able to explain the source and purpose of funds with proper records.

    What Should You Keep in Mind With Large Deposits?

    • Maintain invoices and supporting business records.
    • Keep the source of funds properly documented.
    • Follow applicable tax and accounting requirements.
    • Be prepared to respond to legitimate bank KYC or transaction-monitoring queries.
    • Do not structure transactions merely to avoid reporting or compliance requirements.

    A bank account is not a substitute for proper accounting. If your business receives substantial amounts, reconcile the transactions with invoices, sales records and accounting entries.

    Is Money in a Current Account Taxable?

    The balance sitting in a bank account is not automatically a separate taxable item simply because it is in a current account. Tax consequences generally depend on the underlying income, transaction and applicable tax rules.

    For example, receiving business revenue into a current account does not mean the entire bank balance is automatically your taxable income. Business expenses, income recognition, applicable deductions and the nature of the transaction all matter.

    Advantages and Disadvantages of a Business Current Account

    Advantages

    • Designed for frequent business transactions.
    • Keeps business and personal finances separate.
    • Supports regular customer and vendor payments.
    • Can provide business-oriented banking services.
    • Makes transaction tracking and reconciliation easier.

    Disadvantages

    • Some accounts require a minimum or average balance.
    • Cash handling and other services may attract charges.
    • Transaction fees can become significant for high-volume businesses.
    • Current accounts are generally not designed primarily for earning interest.
    • Businesses may face additional KYC and verification requirements.

    Current Account or Savings Account: Which Is Better for Business?

    For a business with frequent commercial transactions, a current account is generally more suitable because it is designed around business banking needs.

    A savings account is primarily designed for personal savings and individual banking. Using a personal account for substantial business activity can also make bookkeeping and financial separation more difficult.

    The correct choice should therefore reflect the nature and scale of your transactions, not just the account’s opening balance.

    Current Account Charges You Should Check

    Before opening an account, review the bank’s latest schedule of charges. Fees can vary significantly between account products.

    • Minimum or average balance non-maintenance charges.
    • Cash deposit and withdrawal charges.
    • Cheque book or cheque-related charges.
    • Fund transfer charges, where applicable.
    • Debit card or business card charges.
    • Statement or notification charges.
    • Collection and payment-related charges.
    • Other account-specific service charges.

    Always rely on the bank’s current official tariff rather than an old comparison article because banking charges and account features can change.

    Frequently Asked Questions About Business Current Accounts

    Is GST compulsory for current accounts?

    No. GST registration is not automatically compulsory merely because you want to open a current account. GST liability depends on the applicable registration provisions and the facts of your business. The bank may, however, request a GST certificate if you are registered or if its account-opening requirements call for it.

    Which bank gives a free business account?

    Some banks may advertise accounts with zero or low fees under particular conditions. However, “free” does not necessarily mean every service is free. Compare the complete fee schedule, balance requirements, transaction limits and cash-handling charges.

    Which bank is best for small business owners?

    The best bank depends on the business. Compare the account’s balance requirements, transaction limits, cash deposit facilities, digital banking, payment collection options and customer support before choosing.

    What is the disadvantage of a current account?

    Potential disadvantages include minimum balance requirements, transaction charges, cash-handling fees and other service charges. Current accounts are generally focused on transaction convenience rather than interest on balances.

    Can I open a zero-balance current account for my proprietorship?

    Some banks offer products with low or zero balance requirements, but eligibility and conditions vary. A proprietor should compare the full terms rather than relying only on the zero-balance label.

    Which bank is best for a current account for proprietorship?

    Choose based on your transaction pattern. A cash-heavy proprietor may prioritise branch access and cash deposit facilities, while a digital business may prioritise online banking, payment collection and low digital transaction costs.

    Which current accounts are free?

    There is no universal category of completely free current accounts. Banks may waive certain charges subject to conditions. Review the latest account-specific schedule of charges before opening one.

    How much money do I need to open a current account?

    The required amount varies by bank and account product. Check both the initial funding requirement and the ongoing minimum or average balance condition.

    Which is the easiest current account to open?

    The easiest account is usually one for which your business structure and documentation match the bank’s requirements. Digital application options can make the process more convenient, but KYC and business verification still apply.

    Does a current account charge a monthly fee?

    It depends on the account. Some banks charge account maintenance or service fees, while others may waive particular charges if specified conditions are met. Check the latest tariff before applying.

    Which is better, current or cheque account?

    The term “cheque account” is not a universal Indian banking category equivalent to a current account. If you need frequent business transactions and cheque facilities, compare business current accounts and their specific cheque services.

    How much tax do I pay on ₹30 lakh?

    There is no single tax amount based only on a ₹30 lakh figure in a bank account. The answer depends on what the ₹30 lakh represents, such as business turnover, taxable profit, salary, capital receipt or another transaction.

    The applicable tax also depends on the taxpayer, business structure, deductions, applicable tax regime and the nature of the income. A bank balance should not be treated as the same thing as taxable income.

    For broader tax and return support, explore Lawizer’s ITR and tax services.

    Is money in a current account taxable?

    Keeping money in a current account does not, by itself, create a separate tax merely because the money is in the bank. The tax treatment depends on the underlying source and nature of the income or transaction.

    What are the four types of current accounts?

    There is no single universal four-type classification that applies to every bank in India. Banks may classify current accounts differently based on customer segment, transaction volume, balance requirements and features.

    How much amount can be kept in a current account?

    There is no simple universal balance figure that applies to every current account. The applicable account terms, banking controls and regulatory requirements should be considered. Large transactions should always be supported by proper business records.

    Which type of current account is best?

    The best account depends on your business needs. Compare transaction volume, cash deposits, digital payments, balance requirements, charges, branch access and other services before selecting an account.

    Key Takeaways Before Opening a Business Current Account

    Opening a business bank account is straightforward when your business documents and banking requirements are clear. Before applying, make sure you understand the following:

    • Choose an account based on your expected transaction pattern.
    • Check the bank’s current KYC and document requirements.
    • Do not assume GST registration is automatically required just to open an account.
    • Check minimum or average balance requirements.
    • Compare cash deposit and transaction charges.
    • Keep business and personal transactions separate.
    • Maintain proper invoices and accounting records for significant transactions.

    If you are still setting up the business itself, it may be useful to complete the relevant legal registrations before approaching a bank. Lawizer offers support across business registration and legal services, including incorporation, GST and MSME-related services.

    Need Help Setting Up Your Business?

    A current account is only one part of getting a business ready to operate. Depending on your business, you may also need entity registration, GST registration, MSME registration, tax filing or ongoing compliance support.

    Lawizer helps Indian founders and small-business owners handle these legal and compliance requirements online. You can explore Private Limited Company registration, OPC registration, LLP registration and GST registration based on your needs.

    If you are unsure which registrations or documents apply to your business, speak with a professional before submitting your bank application. Getting the underlying business structure and documentation right can make the banking process much smoother.

    Relevant Lawizer Resources

    Tags: Current Account, Business Current Account, Business Banking, Current Account for Business, GST Registration, Business Registration, Small Business India, Startup Compliance, KYC, Business Finance

  • NDA Explained For Businesses

    NDA Explained For Businesses


    NDA explained for businesses: Types, Red Flags & Risks

    NDA explained for businesses is a topic every founder should understand before sharing sensitive information with an employee, consultant, investor, vendor or business partner. A Non-Disclosure Agreement, commonly called an NDA, is a contract designed to protect confidential information from unauthorised disclosure or misuse.

    For an Indian business, confidential information can include customer lists, pricing models, source code, product plans, financial information, marketing strategies, supplier details and trade secrets. Sharing this information is often necessary to grow a business, but doing so without clear contractual protection can create avoidable risks.

    This guide explains what an NDA does, the main types of NDAs, how long they can last, common NDA red flags, potential risks of signing, and what founders should check before accepting one.


    NDA explained for businesses: What is an NDA?

    NDA stands for Non-Disclosure Agreement. It is a contract under which one or more parties agree to protect specified confidential information and use it only for an agreed purpose.

    For example, imagine that a startup wants to hire a software developer to work on an unreleased application. The developer may need access to source code, product specifications, customer information and business plans. An NDA can establish contractual obligations regarding how that information must be handled.

    Similarly, a founder negotiating with an investor or potential business partner may need to disclose financial projections, technology details or commercial plans. An NDA can define what information is confidential and what the recipient can and cannot do with it.

    Indian contract law provides the broader legal framework within which contractual obligations operate. The Indian Contract Act, 1872 contains provisions concerning valid contracts, lawful objects, restraint of trade and consequences of breach.

    What does an NDA protect?

    An NDA may protect different categories of information depending on how the agreement is drafted. Common examples include:

    • Business plans and growth strategies
    • Customer and supplier information
    • Pricing and commercial information
    • Financial records and projections
    • Source code and technical documentation
    • Product designs and prototypes
    • Marketing strategies
    • Manufacturing processes and know-how
    • Unreleased intellectual property
    • Trade secrets and other proprietary information

    The agreement should not simply say that “everything” is confidential without providing useful boundaries. A clear definition makes it easier for both parties to understand their obligations.

    When should a business use an NDA?

    An NDA can be useful whenever confidential information must be shared with someone outside the business or with people whose access needs contractual controls.

    • Before discussing a startup idea with a potential partner
    • When hiring employees or senior executives
    • When engaging consultants and freelancers
    • Before sharing information with manufacturers or vendors
    • During joint venture discussions
    • During investment or acquisition negotiations
    • When outsourcing software development
    • When sharing proprietary processes with another business

    Lawizer also provides a Non-Disclosure Agreement service along with other business documentation options for founders who need formal agreements.

    NDA explained for businesses: What are the three types?

    NDAs are commonly divided into unilateral, mutual or bilateral, and multilateral agreements. The correct structure depends on who will disclose confidential information.

    1. Unilateral or one-way NDA

    A unilateral NDA is used when primarily one party discloses confidential information and the other party receives it.

    For example, a startup may provide confidential information to a freelancer. The startup is the disclosing party, while the freelancer is the receiving party.

    Common situations include:

    • Employer and employee relationships
    • Startup and consultant relationships
    • Company and freelancer relationships
    • Business and vendor discussions
    • Founder and prospective investor discussions

    2. Mutual or bilateral NDA

    A mutual NDA applies when both parties expect to exchange confidential information.

    For example, two companies considering a strategic partnership may each need to disclose sensitive commercial information. A mutual NDA gives both parties confidentiality obligations.

    This structure is common in partnership negotiations, joint ventures, mergers, acquisitions and other commercial discussions.

    3. Multilateral NDA

    A multilateral NDA involves three or more parties. It can be useful when several businesses or individuals participate in the same confidential project.

    For example, a company, investor and external consultant may all exchange confidential information. Instead of relying on several separate agreements, the parties may use a multilateral NDA that clearly defines each party’s obligations.

    Are there two types or three types of NDAs?

    You may see sources describing only two main types: unilateral and mutual. Others add multilateral agreements as a third category.

    Both descriptions can be useful. The important point for a business owner is not the label but the actual obligations in the agreement. Always check who must keep information confidential, what information is covered and who can receive it.

    How long do NDAs usually last?

    There is no single universal NDA duration that applies to every business agreement. The period depends on the wording of the contract, the nature of the information and the commercial circumstances.

    Some NDAs contain a fixed confidentiality period. Others provide different treatment for different categories of information. For example, ordinary business information may be protected for a defined period, while information that remains a genuine trade secret may require continuing protection, subject to applicable law.

    What determines NDA duration?

    • The type of confidential information
    • How quickly the information becomes outdated
    • The purpose of the business relationship
    • The length of the project
    • Whether confidentiality obligations survive termination
    • The wording and enforceability of the agreement

    Founders should therefore avoid assuming that every NDA lasts for a particular number of years. Read the confidentiality period and any survival clause carefully.

    Can an NDA last indefinitely?

    An NDA can contain continuing confidentiality obligations, but an indefinite obligation should not automatically be treated as appropriate for every category of information.

    The more important question is whether the restriction is appropriately connected to the legitimate interest being protected. A clause covering genuine trade secrets may need different treatment from a clause covering information that becomes public or commercially irrelevant after a short period.

    If you are unsure whether the duration is appropriate, consider getting the agreement reviewed before signing it.

    What are the red flags in an NDA?

    One of the most important parts of NDA explained for businesses is learning how to recognise provisions that deserve closer review.

    1. An extremely broad definition of confidential information

    A definition that covers practically everything the recipient sees or hears may create uncertainty. The agreement should make it reasonably clear what information is protected.

    2. An unnecessarily long confidentiality period

    A long confidentiality period is not automatically invalid or unfair. However, founders should ask why such a period is necessary and whether it matches the information being protected.

    3. Excessive financial consequences

    Pay particular attention to clauses that specify large sums or penalties for breach. Under Section 74 of the Indian Contract Act, where a contract stipulates a sum or penalty for breach, the party complaining of the breach may be entitled to reasonable compensation subject to the statutory limits. The exact outcome depends on the agreement and circumstances.

    See the official text of Section 74 of the Indian Contract Act for the statutory provision.

    4. One-sided obligations

    If both parties exchange confidential information but only one party has meaningful protection, the agreement may deserve negotiation.

    5. Hidden restrictions on competition

    An NDA should protect confidential information. It should not automatically be treated as a general agreement preventing someone from carrying on a profession or business.

    Section 27 of the Indian Contract Act addresses agreements in restraint of trade. The official Indian Contract Act text should be consulted for the statutory wording and applicable exceptions.

    6. Unclear permitted use

    The recipient should understand why the information is being shared and what they are allowed to do with it. An NDA that prohibits practically every use may be difficult to comply with.

    7. Missing confidentiality exceptions

    Many well-drafted agreements address information that is already public, was already known to the recipient, is independently developed, or must be disclosed because of law or a legal requirement.

    8. Unclear return or destruction obligations

    Check what happens to documents, files, copies and other materials when the relationship ends. Digital information can make these clauses particularly important.

    9. Unfavourable dispute provisions

    Review the governing law, jurisdiction and dispute-resolution provisions. This becomes especially important when the parties operate in different states or countries.

    What are the main red flags in an NDA?

    For a quick review, founders can use the following NDA checklist:

    • Broad or vague confidentiality definitions
    • Unclear confidentiality duration
    • Disproportionate financial exposure
    • One-sided obligations
    • Restrictions that go beyond confidentiality
    • No clear exceptions
    • Unclear permitted use of information
    • Unreasonable return or destruction requirements
    • Unfavourable dispute-resolution terms
    • Clauses that are difficult to follow in day-to-day business operations

    A red flag does not necessarily mean that the entire NDA is invalid. It means that the clause deserves closer attention before you agree to it.

    Is signing an NDA risky?

    Signing an NDA is not inherently risky. A clear and proportionate NDA can actually reduce business risk by setting expectations before confidential information is exchanged.

    The risk arises when you agree to obligations that you do not fully understand or cannot realistically comply with.

    When is signing an NDA generally reasonable?

    • The confidential information is clearly identified.
    • The purpose of disclosure is clear.
    • The duration is understandable.
    • Standard exclusions are included.
    • The permitted recipients are clear.
    • The remedies are proportionate and legally appropriate.

    When should you be more cautious?

    Take additional care if the NDA contains unusually broad restrictions, substantial financial exposure, unclear obligations or provisions that appear to restrict your future work beyond protecting confidential information.

    Founders should also remember that an NDA is not a substitute for other intellectual-property protections. Depending on the asset, you may also need trademark protection, copyright protection, IP assignment clauses or other contractual safeguards.

    What voids an NDA?

    The question “what voids an NDA?” needs a careful answer. A problematic clause does not automatically mean that the entire agreement disappears.

    Contractual validity and enforceability depend on the facts, wording and applicable law. The Indian Contract Act contains provisions dealing with lawful objects, free consent, uncertainty and agreements that are void in specified circumstances.

    For example, Section 29 deals with agreements that are void for uncertainty, while Section 27 deals with restraint of trade. These provisions should not be used to assume that every imperfect NDA is automatically void.

    Can one problematic clause affect the whole NDA?

    Not necessarily. Some contracts contain severability provisions designed to separate an unenforceable provision from the remaining agreement. The effect depends on the wording and applicable law.

    For a specific agreement, professional legal review is preferable to relying on a general assumption about validity.

    Can you be sued for breaking an NDA?

    Yes, a party may face contractual proceedings after an alleged NDA breach. The precise remedy depends on the agreement, facts and applicable law.

    Section 73 of the Indian Contract Act provides for compensation for loss or damage caused by breach of contract, subject to the requirements stated in the provision.

    The official Section 73 text explains the statutory approach to compensation for contractual breach.

    What might happen after an alleged breach?

    • The parties may attempt to resolve the dispute commercially.
    • A legal notice may be issued.
    • The affected party may seek appropriate legal relief.
    • A claim for compensation may be made where legally available.
    • The dispute may proceed through the mechanism specified in the agreement.

    This is why businesses should maintain reasonable controls over confidential information and limit access to people who genuinely need it.

    What is a 3-way NDA called?

    A three-party NDA is commonly described as a multilateral NDA or three-party NDA.

    It is useful when three parties need to exchange confidential information for the same commercial purpose. The document should identify each party and explain how information shared by one party must be treated by the others.

    For example, a startup may work with an investor and an external technical consultant. A multilateral agreement can establish confidentiality obligations across the relationship.

    Can I tell my wife about an NDA?

    Being married to someone does not automatically mean that you are permitted to disclose confidential business information to that person.

    If the NDA limits disclosure to authorised representatives, employees, professional advisers or other specified recipients, a spouse may not fall within those categories.

    Before sharing confidential information with a family member, check the agreement’s permitted-disclosure provisions. If the agreement does not permit the disclosure, obtaining consent from the relevant party may be safer than assuming that personal relationships create an exception.

    What is a PIA vs NDA?

    PIA and NDA are not generally interchangeable terms.

    If PIA refers to a Privacy Impact Assessment, it is normally a process used to identify and assess privacy risks associated with handling personal information. An NDA, by contrast, is a contractual confidentiality mechanism.

    A business may need both depending on its activities. For example, a company processing personal information may assess privacy risks while also using contractual confidentiality provisions with employees or service providers.

    How to review an NDA before signing

    Before signing, founders should read the document systematically rather than focusing only on the confidentiality heading.

    Step 1: Check the parties

    Confirm that the legal names of the individuals or entities are correct. If a company is signing, ensure that the person signing has appropriate authority.

    Step 2: Identify confidential information

    Look for a clear definition. Ask whether it covers the information you actually expect to share.

    Step 3: Check the permitted purpose

    Make sure the recipient can use the information for the commercial purpose for which it was provided.

    Step 4: Check exclusions

    Look for provisions dealing with public information, previously known information, independently developed information and legally required disclosures.

    Step 5: Review the duration

    Check when confidentiality begins, how long it continues and whether obligations survive termination.

    Step 6: Review liability and remedies

    Look carefully at damages, indemnity provisions, injunction-related language and any specified amounts payable after breach.

    Step 7: Check return and destruction requirements

    Understand what must happen to documents and electronic information after the relationship ends.

    Step 8: Review dispute resolution

    Check the governing law, jurisdiction, arbitration provisions and other dispute mechanisms.

    If the document is complex, Lawizer’s business documentation services can be relevant when you need a professionally prepared agreement rather than relying blindly on a generic template.

    NDA best practices for Indian businesses

    A good confidentiality strategy involves more than signing an NDA. Businesses should also control how information is created, stored and shared.

    • Use written confidentiality terms before sharing sensitive information where appropriate.
    • Define confidential information clearly.
    • Share only the information necessary for the specific purpose.
    • Limit access to employees and contractors who need it.
    • Use appropriate access controls for digital information.
    • Keep records of important confidential disclosures.
    • Review employee and consultant agreements for confidentiality obligations.
    • Use separate IP agreements where ownership of work product needs to be addressed.
    • Review cross-border agreements carefully.
    • Seek legal advice for high-value transactions or unusually restrictive terms.

    For businesses that are still establishing their legal foundation, Lawizer also provides business registration support, Private Limited Company registration, Startup India registration, GST registration and MSME/Udyam registration.

    Once a company is operating, founders can also consider appropriate annual compliance support so that contractual protection is part of a broader compliance framework.

    NDA explained for businesses:

    Frequently Asked Questions:

    1) What are red flags in an NDA?

    Common red flags include vague confidentiality definitions, excessive duration, disproportionate liability, one-sided obligations, unclear permitted use, unusual restrictions and unfavourable dispute provisions. A red flag means the clause deserves review; it does not automatically mean the entire NDA is invalid.

    2) How long do NDAs usually last?

    There is no universal duration. The period depends on the agreement and the information being protected. Some agreements use a fixed period, while certain confidential information may require continuing protection. Always check the duration and survival provisions.

    3) What are the main red flags in an NDA?

    Look for broad definitions, excessive financial exposure, unclear obligations, restrictions beyond confidentiality, missing exceptions and difficult return or destruction requirements. Also check governing law and dispute-resolution clauses.

    4) What are the three types of NDA?

    The commonly discussed structures are unilateral, mutual or bilateral, and multilateral. A unilateral NDA primarily protects information disclosed by one party. A mutual NDA protects information exchanged by both parties. A multilateral NDA involves three or more parties.

    5) Can I tell my wife about an NDA?

    Not automatically. Whether you can disclose information to a spouse depends on the NDA’s permitted-disclosure provisions and the nature of the information. If a spouse is not an authorised recipient, sharing confidential information may create a contractual issue.

    6) What are the two types of NDAs?

    Many business resources describe the two principal NDA structures as unilateral and mutual. A multilateral NDA can be treated as a third structure when three or more parties participate in the confidential relationship.

    7) What are common NDA red flags?

    Common concerns include vague definitions, indefinite obligations without justification, excessive penalties, broad non-compete language, unclear exceptions and provisions that are difficult to follow in normal business operations.

    8) What is a 3-way NDA called?

    A three-party NDA is commonly called a multilateral NDA or three-party NDA. It establishes confidentiality obligations among three parties that need to exchange sensitive information for a shared purpose.

    9) What is a PIA vs NDA?

    A Privacy Impact Assessment is generally a risk-assessment process relating to privacy and personal information. An NDA is a contractual agreement concerning confidentiality. They address different purposes and may sometimes be used together.

    10) Is signing an NDA risky?

    Signing an NDA is not inherently risky. The risk depends on the terms. Pay particular attention to the definition of confidential information, duration, permitted use, liability, remedies and restrictions that may go beyond legitimate confidentiality protection.

    11) What voids an NDA?

    An NDA may be affected by issues such as unlawful terms, uncertainty, problems with consent or other defects recognised by applicable contract law. However, one problematic clause does not necessarily make the entire agreement void.

    12) Can I be sued for breaking an NDA?

    A breach can potentially lead to contractual proceedings and claims for legally available remedies. The consequences depend on the agreement, evidence, applicable law and circumstances. Section 73 of the Indian Contract Act addresses compensation for loss or damage caused by contractual breach.

    13) How long can an NDA last?

    The duration depends on the contract and the nature of the confidential information. Instead of relying on a standard number of years, review the actual confidentiality period and any provisions that continue after the business relationship ends.

    Conclusion: Protect confidential information carefully

    NDA explained for businesses is ultimately about understanding what you are agreeing to protect, how you can use confidential information and what happens if the agreement is breached.

    A well-drafted NDA can help founders share information more confidently with employees, consultants, investors, vendors and business partners. However, an NDA should be specific enough to be understood and proportionate to the legitimate business interest being protected.

    Before signing, check the definition of confidential information, permitted use, exclusions, duration, liability, remedies, return obligations and dispute-resolution terms.

    For startups and growing businesses, confidentiality should also work alongside appropriate intellectual-property protection, business contracts and ongoing compliance.

    Need help preparing or reviewing a business NDA? Lawizer provides legal documentation and business compliance support for Indian founders. You can explore the business documentation services or speak with the Lawizer team about your specific requirements.

    Important: This article provides general legal information for educational purposes. The enforceability of an NDA depends on its wording, the parties, the facts and applicable law. For a specific agreement or dispute, obtain professional legal advice before taking action.

  • Why Startups Should Trademark Early

    Why Startups Should Trademark Early

    Building a startup involves hundreds of decisions, from choosing a business structure to developing a product and finding customers. One decision that is often postponed is brand protection. Understanding why startups should trademark early matters because a brand name can become one of the most valuable assets a young business builds.

    A founder may spend months developing a name, designing a logo, buying a domain, creating social-media profiles and investing in advertising. But registering a company name or securing a domain does not automatically provide comprehensive trademark protection. If a similar mark already exists, or another party files a conflicting application, changing the brand later can become expensive and disruptive.

    This guide explains the practical reasons to consider trademark protection early, how trademark registration works in India, what it does and does not protect, and the common questions founders ask before filing.

    What Does a Trademark Protect for a Startup?

    A trademark is a sign capable of distinguishing the goods or services of one person from those of others. Depending on the circumstances, this can include a brand name, logo, slogan, letters, numbers, shapes and other distinctive elements.

    For a startup, the important point is that trademark protection is connected to the mark and the goods or services covered by the application or registration. Registration does not give a business ownership of an ordinary word in every possible context.

    For example, two businesses may potentially use similar words in unrelated fields where there is no relevant likelihood of confusion and no other legal bar. The analysis depends on the marks, goods or services and the surrounding facts.

    Founders can learn more about the process through Lawizer’s guide to registering a trademark in India.

    Why Startups Should Trademark Early: 7 Key Reasons

    1. Protect the Brand Before You Invest Heavily in It

    The earlier a startup begins thinking about trademark protection, the easier it is to identify a potential problem before large amounts of money are committed to the brand.

    Imagine launching a product after spending heavily on packaging, advertising and influencer campaigns, only to discover that another business has an earlier conflicting trademark. The business may then have to consider changing its name or defending a dispute.

    A trademark search before substantial investment gives founders an opportunity to assess whether the proposed name is commercially and legally sensible.

    2. Reduce the Risk of an Expensive Rebrand

    Rebranding is more than changing a logo on a website. An established startup may need to replace packaging, signage, advertisements, domain assets, sales material and social-media branding.

    There can also be an intangible cost. Customers may already associate the original name with the business. Changing that identity can create confusion and require additional marketing to rebuild recognition.

    Early clearance and filing do not guarantee that a mark will be registered, but they can help founders identify risks while changing course is still relatively manageable.

    3. Reduce the Risk of a Competing Trademark Application

    The filing date of a trademark application can be strategically important. However, founders should not reduce Indian trademark law to the simple statement that “whoever files first always wins.” Prior use and other provisions of the Trade Marks Act can affect the legal position.

    What early filing does provide is a formal application record and an important date in the trademark process. It can therefore be sensible to address brand protection once the founder has finalised a distinctive name and completed appropriate clearance.

    Section 11 of the Trade Marks Act, 1999 is particularly relevant where an applied-for mark conflicts with an earlier mark and there is a likelihood of confusion. This is one reason why searching before filing is so important.

    4. Turn the Brand Into a Recognisable Business Asset

    A successful brand can acquire goodwill and commercial value over time. A registered trademark can form part of the intellectual property portfolio of the business.

    Depending on the business model, trademarks can also become relevant to licensing, franchising, assignment and other commercial arrangements.

    For startups preparing for expansion, it is useful to think about intellectual property as part of the company’s overall asset base rather than as paperwork that only becomes relevant after the business becomes large.

    If multiple founders are involved, an IP Assignment Agreement can help clarify ownership of intellectual property created by founders, employees or contractors.

    5. Support Investor and Due-Diligence Readiness

    Investors, lenders, acquirers and strategic partners may conduct legal due diligence before entering a significant transaction. Intellectual-property ownership can be one part of that review.

    If a startup has a valuable brand but unclear ownership, unresolved conflicts or no organised record of its IP, those issues may need to be addressed during due diligence.

    Trademark registration is not a substitute for good corporate records, founder agreements or IP assignment documents. It is one component of a broader legal foundation.

    6. Strengthen Your Position Against Brand Misuse

    A registered trademark can provide important statutory rights against qualifying infringing uses. Section 29 of the Trade Marks Act deals with infringement of registered trademarks, subject to the conditions and exceptions provided by law.

    This does not mean registration automatically resolves every dispute. Trademark disputes can involve questions about similarity, goods or services, prior use, reputation, honest concurrent use and other facts.

    Still, registration can give a business a clearer legal position than relying entirely on unregistered rights and a passing-off action.

    7. Prepare for Expansion Into New Products and Markets

    Startups rarely remain exactly the same as they were on day one. A software company may add consulting services. A D2C brand may introduce new product categories. A local business may expand nationally or internationally.

    Trademark protection is tied to the goods and services covered. Founders should therefore think about the business’s realistic growth plans when deciding which classes and marks to consider.

    The goal is not to register every imaginable class. It is to build a sensible trademark strategy around the business you actually operate and the expansion you genuinely expect.

    When Should a Startup Trademark Its Brand?

    There is no universal date that applies to every startup. A practical point to consider trademark protection is when the founder has substantially finalised the brand and before significant expenditure has been made on building it.

    This may be before launch, particularly where the name is already finalised. A business can consider trademark registration separately from incorporation; Section 18 of the Trade Marks Act allows a person claiming to be the proprietor of a mark used or proposed to be used to apply for registration.

    That means a founder does not necessarily have to wait until a private limited company is incorporated before considering trademark protection.

    However, the applicant and eventual business structure should be planned carefully. If the brand will ultimately belong to a company, founders should consider ownership and IP assignment issues rather than casually filing everything in an individual’s name.

    Trademark Name, Logo or Both?

    A startup may have several brand elements worth protecting. The most important may be the word or name itself, while a logo may have separate commercial value.

    A word mark can be particularly important where the name is the core brand identity. A device or logo mark can protect the particular visual representation, subject to the scope of registration.

    Whether a startup should file one mark or multiple marks depends on its brand strategy, budget and the importance of each element. Founders should avoid assuming that one registration automatically gives comprehensive protection over every variation of a brand.

    Company Registration Is Not the Same as Trademark Registration

    One of the most common misconceptions among new founders is that registering a company name protects the brand.

    It does not. Company registration and trademark registration serve different purposes. A company name identifies the legal entity, while a trademark distinguishes goods or services in the marketplace.

    For example, a founder might incorporate a company under a particular name and separately operate a consumer-facing brand under another name. The company’s incorporation does not automatically create comprehensive trademark rights over that consumer brand.

    If you are still deciding on your business structure, Lawizer provides Private Limited Company registration and LLP registration services.

    What Happens If You Do Not Trademark Early?

    Not registering immediately does not mean that every legal right disappears. Indian law recognises certain rights arising from prior use, and an unregistered mark may in appropriate circumstances be protected through passing-off principles.

    But relying on unregistered rights can make a dispute more complicated because the business may need to establish facts such as goodwill, reputation, misrepresentation and damage.

    By contrast, a registered trademark can provide statutory rights against infringement, subject to the Act and the facts of the case.

    The biggest practical problem is often not the lawsuit itself. It is discovering the conflict after the startup has already invested heavily in the brand.

    How to Register a Trademark for a Startup in India

    Step 1: Choose a Distinctive Mark

    Start with the brand you actually want to build. A distinctive mark is generally easier to protect than a generic or purely descriptive expression.

    Before committing to a name, consider pronunciation, spelling, meaning, existing brands and the markets in which you expect to operate.

    Step 2: Conduct a Trademark Search

    Search the official trademark records before filing. Do not search only for an identical spelling.

    A sensible preliminary search should also consider:

    • Phonetically similar names.
    • Similar spellings.
    • Visually similar marks.
    • Existing applications as well as registrations.
    • Relevant and closely related goods or services.

    The official IP India trademark system provides government infrastructure for trademark applications and searches.

    Lawizer also explains this process in its article on how to protect your brand name in India.

    Step 3: Identify the Correct Trademark Class

    India uses the Nice Classification system for goods and services. There are 45 classes, with Classes 1–34 generally covering goods and Classes 35–45 covering services.

    The correct class depends on what your business actually offers. A software company and a clothing brand will generally have different classification considerations.

    Choosing classes simply because another business used them can be a mistake. The specification should reflect the applicant’s real goods or services and the intended scope of protection.

    Step 4: File Form TM-A

    The standard application for registration is filed using Form TM-A. The application identifies the applicant, the mark and the goods or services for which protection is sought.

    Government fees depend on the applicant category and filing method. For current fees, founders should verify the latest official IP India fee schedule before filing.

    Eligible startups may also have access to intellectual-property support and applicable fee concessions under government startup programmes, subject to the relevant eligibility requirements.

    Step 5: Monitor Examination and Respond to Objections

    Filing the application is not the end of the process. The Trade Marks Registry examines the application and may raise objections.

    An examination objection is not the same as a third-party opposition. An objection comes from the Registry during examination. An opposition is initiated by another party after the application reaches the relevant publication stage.

    If your application receives an objection, review the examination report carefully and respond within the applicable deadline. Lawizer provides a dedicated trademark objection reply service.

    Step 6: Publication and Opposition

    If an application progresses through examination, it may be advertised in the Trade Marks Journal. Third parties can oppose registration within the prescribed period.

    Under the Trade Marks Rules, 2017, the opposition procedure has specific timelines for notices, counter-statements and evidence. These procedural deadlines matter because missing them can affect the application or opposition.

    Step 7: Registration and Renewal

    If the application successfully completes the relevant stages, the mark can be entered on the Register and a registration certificate issued.

    Under the current framework, a registered trademark is valid for 10 years and can be renewed for successive 10-year periods. Government renewal fees depend on the applicable filing method and circumstances, so founders should verify the current fee schedule before renewal.

    Lawizer also provides trademark renewal assistance for businesses maintaining their registrations.

    How Much Does Startup Trademark Registration Cost?

    The government fee is only one part of the total cost. Your overall expenditure can depend on the applicant category, number of marks, number of classes and whether professional assistance is used.

    • Applicant category: Government fees vary depending on whether the applicant qualifies as an Individual, Startup, Small Enterprise or another category.
    • Number of classes: Government fees generally apply per mark and per class.
    • Filing method: Online and physical filing can have different government fees.
    • Professional assistance: Professional or facilitation charges are separate from government fees.

    Fees can change, so always check the latest official fee schedule before budgeting. For a broader explanation, see Lawizer’s guide to trademark registration cost, process and timeline in India.

    Common Startup Trademark Mistakes

    • Choosing a name before searching: A good-sounding name may already conflict with an earlier mark.
    • Searching only identical names: Similarity can arise from pronunciation, appearance or overall commercial impression.
    • Assuming company incorporation is enough: Entity registration and trademark registration are different.
    • Choosing the wrong class: Protection is linked to the goods and services covered.
    • Ignoring ownership: Founders should consider who should own the trademark and whether IP assignment documents are needed.
    • Forgetting renewal: A registered trademark requires timely renewal to maintain protection.
    • Using ® too early: The registered symbol should be used only after registration has actually been obtained.

    Lawizer’s legal checklist for new founders also covers wider legal groundwork that startups should consider alongside intellectual-property protection.

    Trademark FAQ for Indian Startup Founders

    Is It True That 90% of Startups Fail?

    No single 90% failure rate should be treated as a universal fact. Startup failure rates vary according to the definition of failure, industry, geography, time period and dataset. The more useful lesson for founders is to identify preventable risks and build a legal and financial foundation appropriate to the business.

    Is the 80/20 Rule Useful for Startups?

    The 80/20 rule, or Pareto principle, is a business heuristic suggesting that a relatively small number of inputs can account for a large proportion of results. Founders may use it to prioritise customers, products, channels or tasks. It is not a legal rule and does not replace proper compliance.

    What Is the 80/20 Rule for Startups?

    In startup planning, the 80/20 rule is commonly used to identify the activities or customers producing disproportionate results. For example, a small group of customers may generate a large share of revenue. The exact ratio does not have to be literally 80/20.

    Is 1% Equity in a Startup Good?

    There is no universal answer. The value of 1% depends on the company’s valuation, stage, dilution, vesting, the person’s role and the rights attached to the equity. A percentage should never be evaluated in isolation.

    Should Co-Founders Be 50/50 or 51/49?

    Neither split is automatically correct. Founders should consider contribution, responsibilities, decision-making, vesting, future fundraising and deadlock mechanisms. A well-drafted Co-Founder Agreement can help clarify these issues.

    Is Having Three Co-Founders Too Much?

    Not necessarily. Three founders can work well if responsibilities, ownership, decision-making and dispute-resolution mechanisms are clear. The number of founders matters less than whether the founding team has a workable governance structure.

    Is 1% Equity a Lot in a Startup?

    It depends on context. One percent of a very valuable company can be significant, while 1% of an early-stage company may carry substantial risk. Valuation, dilution, vesting and the person’s contribution all matter.

    What Are the Top 10 Failed Startups in India?

    There is no single authoritative list of the “top 10” failed Indian startups. Different publications use different definitions and datasets. Rather than relying on rankings, founders should examine the reasons behind individual failures, such as weak economics, poor governance, excessive spending or unresolved legal risks.

    Who Is Considered the “Bad Boy” of Indian Startups?

    “Bad boy” is an informal media or internet phrase, not a legal or official category. There is no authoritative Indian startup-law designation by that name. Any claim about a particular founder should be evaluated against reliable reporting and verified facts.

    Which Startup Is the Most Successful in India?

    There is no single objective answer. Success can mean valuation, revenue, profitability, market share, user growth, longevity or an eventual exit. A startup can rank highly on one measure and not another.

    Which Indian Startups Are in Loss?

    Startup financial performance changes over time. A company reporting a loss in one financial year is not necessarily failing. Revenue growth, operating margins, cash burn, funding position and the business model all need to be considered together.

    Who Are the Richest Startup Founders in India?

    Rankings of founder wealth are estimates and can change with private-company valuations, ownership percentages, secondary transactions and market movements. They should not be treated as precise unless supported by reliable financial information.

    What Are the Four Types of Trademarks?

    There is no complete statutory classification that limits Indian trademarks to exactly four types. Commonly discussed categories include word marks, device or logo marks, shape marks and sound marks. Other forms of marks can also be protected if they satisfy the legal requirements.

    What Happens If a Registered Trademark Is Not Used for 5 Years?

    Section 47 of the Trade Marks Act deals with removal of a registered trademark on grounds of non-use. In particular circumstances, a continuous period of five years and three months from the date on which the mark was actually entered in the Register can become relevant. The mark is not simply cancelled automatically after five years; a prescribed legal process and the facts of the case matter.

    What Is Rule 47 in Trademarks?

    Rule 47 of the Trade Marks Rules, 2017 concerns evidence in reply by the opponent in opposition proceedings. After receiving the applicant’s evidence, the opponent may file evidence by affidavit in reply within the period prescribed by the Rule. Rule 47 should not be confused with Section 47 of the Trade Marks Act, which concerns removal on grounds of non-use.

    How Do You Renew a Trademark After 10 Years?

    A registered trademark is generally valid for 10 years and may be renewed for further 10-year periods. Renewal is made using the prescribed process, including Form TM-R and the applicable fee. Founders should check the current official requirements and deadlines rather than relying on an old fee or timeline.

    How Much Does It Cost to Renew a Trademark in India?

    Renewal costs depend on the applicable government fee, filing method and whether additional charges apply because of delay or restoration. Government fees are separate from professional or facilitation charges. Check the current IP India fee schedule before renewal.

    What Is the Most Famous Trademark?

    “Most famous” is subjective. Brands such as Coca-Cola, Apple, Google and Nike are widely recognised examples, but fame does not have a single universal ranking. In legal terms, the more important question is whether a particular mark qualifies for protection and what rights it has in the relevant market.

    Is Sprite a Trademark?

    Yes. “Sprite” is used as a brand identifier and functions as a trademark for relevant goods. The important legal point is that trademark protection applies to the mark in connection with the relevant goods and services, rather than giving unrestricted ownership of the word in every context.

    Why Is Coca-Cola Not Patented?

    The Coca-Cola formula is widely discussed as a trade secret rather than a patent-protected formula. A patent generally requires disclosure of the invention and provides protection for a limited statutory period. A trade secret can potentially remain protected for as long as the information remains confidential and the legal requirements for trade-secret protection are met.

    Is “Coca-Cola” a Trademarked Name?

    Yes. Coca-Cola is a well-known brand and trademark. Its brand name and other identifying elements are distinct from the separate question of how the beverage formula is protected.

    Key Takeaway for Indian Startup Founders

    A startup’s brand may begin as just a name on a pitch deck. If the business succeeds, that same name can appear on products, websites, contracts, invoices, advertisements and customer reviews. At that point, changing it can become much harder.

    The practical approach is straightforward:

    • Choose a distinctive brand.
    • Search for conflicting marks before investing heavily.
    • Identify the correct goods and services classes.
    • Consider who should own the trademark.
    • File the application when commercially appropriate.
    • Monitor examination and opposition stages.
    • Maintain the registration and renew it on time.

    Trademark protection should therefore be considered alongside other early-stage legal requirements. Lawizer’s GST, MSME and trademark guide for founders explains how these different parts of the business-compliance picture can fit together.

    Protect Your Startup Brand Before It Becomes Expensive to Change

    If you have already finalised your startup’s brand name, the next sensible step is to check whether it is available and suitable for trademark protection.

    Lawizer can assist with trademark search, application filing and ongoing support through the trademark process. You can explore the Lawizer Trademark Registration service or review the trademark guide for first-time founders before deciding how to proceed.

    If your application later receives an objection, Lawizer also offers trademark objection reply assistance. For businesses with an existing registration, trademark renewal support can help with the next stage.

    f your startup has a brand worth building, make sure it is a brand worth protecting.

  • Copyright Registration in India : Cost & Process

    Copyright Registration in India : Cost & Process

    Copyright registration in India is an important way for creators, founders and businesses to document ownership of original creative work. Books, software, photographs, artwork, music, films, website content and other eligible works can have significant commercial value.

    Under Indian copyright law, copyright generally arises automatically when an original eligible work is created. Registration is therefore not mandatory for copyright to exist. However, registration can provide an official record and serve as useful prima facie evidence concerning ownership in a dispute.

    This guide explains what copyright protects, whether registration is compulsory, how to apply online, the applicable government fees, the documents generally required, the registration timeline and practical ways to protect your creative work.

    What Is Copyright Registration in India?

    Copyright protects original expression in qualifying creative works. The Copyright Act, 1957 covers literary, dramatic, musical and artistic works, cinematograph films and sound recordings. Computer programmes are treated as literary works under the Act.

    For a business, copyright may be relevant to assets such as:

    • Website articles and original written content
    • Software and source code
    • Photographs and illustrations
    • Advertising videos
    • Training manuals and educational material
    • Music and sound recordings
    • Books and other literary works

    Copyright protects the original expression of an idea rather than the idea itself. This distinction is important when deciding whether a work is suitable for registration.

    If you also want to protect your business name, logo or other brand identifier, consider Trademark Registration with Lawizer. Copyright and trademark protection address different types of intellectual property.

    Is Copyright Registration Mandatory in India?

    No. Copyright registration is not mandatory for copyright protection to arise.

    The official IP India guidance states that copyright protection generally arises automatically when an eligible original work is created. Registration is not a prerequisite for acquiring copyright.

    However, registration has an important evidentiary benefit. An entry in the Register of Copyrights can serve as prima facie evidence in court regarding particulars recorded in the register.

    In simple terms:

    • Copyright protection: Can arise automatically when an eligible original work is created.
    • Copyright registration: Creates an official record that may help establish ownership and other particulars.

    For commercially valuable work, registration may therefore be worth considering even though it is not compulsory.

    What Can Be Copyrighted in India?

    Section 13 of the Copyright Act, 1957 identifies the principal categories of works in which copyright may subsist.

    These include:

    • Literary works
    • Dramatic works
    • Musical works
    • Artistic works
    • Cinematograph films
    • Sound recordings

    Can Software Be Protected by Copyright?

    Yes. Computer programmes are treated as literary works for copyright purposes. Software developers and technology businesses can therefore consider copyright protection for eligible original software and source code.

    Because software ownership can involve founders, employees, freelancers and contractors, businesses should also maintain clear written ownership arrangements.

    Lawizer’s startup legal services can help businesses organise their broader legal documentation and compliance requirements.

    Can Books and Written Content Be Copyrighted?

    Yes. Original literary works can qualify for copyright protection. This can include books, articles, manuals, training material and other qualifying written works.

    Authors and publishers should also keep evidence of authorship, creation and ownership. Contracts become particularly important when a work is created or edited by multiple people.

    Can Photographs, Artwork and Designs Be Copyrighted?

    Original artistic works may qualify for copyright protection. This can include photographs, drawings, paintings, illustrations, diagrams and other qualifying artistic creations.

    However, copyright protection should not be confused with design registration or trademark protection. The appropriate form of intellectual property protection depends on the nature and intended use of the asset.

    Can Music, Sound Recordings and Films Be Copyrighted?

    Yes. Musical works, sound recordings and cinematograph films are recognised categories under the Copyright Act.

    Businesses in music, advertising, film and digital media should pay particular attention to contracts because several people may contribute to the final work.

    What Is Not Protected by Copyright?

    Copyright protects original expression. It does not generally protect an idea, procedure, method of operation or mathematical concept as such.

    For example, suppose an entrepreneur has an idea for a food-delivery application. The general idea of delivering food through an app is not itself protected by copyright.

    However, original elements created to implement that idea, such as qualifying software code, photographs, written material and artwork, may receive copyright protection.

    Are Names and Titles Protected by Copyright?

    Names, titles and short phrases generally do not receive copyright protection merely because they have been created by someone.

    If you want to protect a distinctive business name, logo or brand identifier, trademark law may be more appropriate.

    Read Lawizer’s guide on Trademark Registration in India to understand how trademark protection differs from copyright.

    How to Get Copyright Registration in India

    The Copyright Office provides an online filing facility for copyright applications. The application is made using the prescribed form and supporting particulars.

    Step 1: Identify the Work

    First, determine the category of work you want to register.

    • Literary work
    • Artistic work
    • Musical work
    • Dramatic work
    • Sound recording
    • Cinematograph film

    The category matters because the filing requirements and statutory fee can differ.

    Step 2: Identify the Author and Copyright Owner

    The author and copyright owner are not always the same person.

    For example, a startup may hire a freelancer to create its website illustrations or source code. The business should review its contract to determine how ownership and rights have been addressed.

    Where intellectual property is created by founders, employees or contractors, a properly drafted IP assignment agreement can help document the intended transfer of rights.

    This issue is particularly important during investment or due diligence because investors may want evidence that the company actually owns the intellectual property it relies upon.

    Step 3: Prepare Form XIV

    Applications for copyright registration are made using Form XIV, together with the applicable Statement of Particulars and, where required, Statement of Further Particulars.

    The official Form XIV requires information about the applicant, the work, the copyright interest and the prescribed fee.

    You can review the official Form XIV issued by the Copyright Office.

    Step 4: Prepare the Work and Supporting Documents

    The material submitted depends on the category of work.

    Applicants should generally keep ready:

    • Details of the applicant
    • Details of the author, where different
    • Details of ownership or interest in the work
    • Copy or specimen of the work as applicable
    • Publication details, where applicable
    • Identity or other supporting documents where required
    • Power of Attorney or authorisation, where an agent is filing on behalf of the applicant

    The exact requirements should be checked against the current Copyright Office instructions before filing.

    Step 5: File the Application Online

    The Copyright Office provides an online filing system through which applicants can submit the application and supporting material.

    After submission and payment of the applicable fee, a Diary Number is generated. The Diary Number is useful for tracking the application and future correspondence.

    Use the official Copyright Office e-filing portal for the current filing process.

    Step 6: Wait Through the Objection Period

    After the application receives a Diary Number, there is a mandatory 30-day period during which objections may be filed against the application.

    If an objection is filed, the Registrar may give the concerned parties an opportunity of being heard before deciding whether the work should be registered.

    Step 7: Examination and Rectification

    If no objection is filed, the application proceeds to examination.

    If the examiner identifies a discrepancy, the applicant may be asked to address it. The official IP India FAQ states that an applicant is ordinarily given 45 days to remove discrepancies identified during examination.

    The overall timeline can therefore vary depending on the application, objections, discrepancies and the applicant’s response.

    Step 8: Copyright Registration Certificate

    If the Registrar is satisfied with the application and the applicable requirements are completed, the work can be entered in the Register of Copyrights.

    The applicant can then receive the copyright registration certificate. The registration record can be useful as documentary evidence concerning the registered work and recorded ownership particulars.

    Can I Register My Copyright Online in India?

    Yes. Online filing is available through the Copyright Office.

    The basic process involves:

    1. Creating or accessing an account on the Copyright Office portal.
    2. Selecting the relevant copyright registration option.
    3. Completing Form XIV and the applicable statements.
    4. Uploading the required material.
    5. Paying the prescribed government fee.
    6. Receiving the Diary Number.
    7. Responding to any objection or examination query, if applicable.

    Applicants should use the current official portal and instructions because filing requirements can change.

    If you prefer professional assistance, Lawizer’s Copyright Registration service provides online facilitation for the registration process.

    What Is the Cost of Copyright Registration in India?

    The government fee depends on the type of work. The Copyright Office’s current fee details list the following registration fees:

    Type of WorkGovernment Fee
    Literary, dramatic, musical or artistic work₹500 per work
    Literary or artistic work used or capable of being used in relation to goods or services₹2,000 per work
    Cinematograph film₹5,000 per work
    Sound recording₹2,000 per work

    These are statutory government fees. If you use a lawyer or legal service provider, professional or facilitation charges are separate.

    Always verify the current fee on the official Copyright Office fee page before filing.

    Can You Get Copyright for Free?

    There is an important difference between copyright protection and copyright registration.

    Copyright protection can arise automatically when an original eligible work is created. You do not have to pay a registration fee simply for copyright to come into existence.

    However, if you choose to register the work with the Copyright Office, the prescribed government fee applies.

    Therefore, copyright protection may arise without registration, but copyright registration is a paid statutory filing process.

    How Does Copyright Protect Your Work?

    Copyright gives the owner certain exclusive rights recognised by the Copyright Act. Depending on the type of work, these rights can include reproduction, issuing copies, communication to the public, adaptation and translation.

    For a business, these rights can have direct commercial value.

    For example:

    • A software company may own copyright in qualifying source code.
    • A publishing business may own rights in original written content.
    • A design studio may own rights in original artwork.
    • A production company may hold rights in audiovisual material.

    Registration does not automatically guarantee success in every infringement dispute. Instead, it can provide useful documentary evidence of the registered particulars and ownership claim.

    How Do I Protect My Book From Being Copied?

    A book can qualify as a literary work when it satisfies the requirements of copyright law.

    Authors can take several practical steps:

    • Keep dated drafts and manuscripts.
    • Preserve emails and files showing the development of the work.
    • Record who contributed to the work.
    • Use written agreements with publishers, editors and collaborators.
    • Clearly define ownership and licensing rights.
    • Consider copyright registration for commercially important work.

    If a publisher, freelancer or other third party is involved, the contract should clearly address intellectual property ownership.

    Lawizer also provides documentation support through its business legal services.

    Can I Publish My Book Without Copyright Registration?

    Yes. Copyright registration is not generally a prerequisite to publishing an original book.

    Copyright can arise automatically in an eligible original literary work.

    However, authors should make sure they have the necessary rights in all material included in the book. Photographs, illustrations, music, quotations and other third-party content may involve separate rights.

    Publishing without registration does not mean that someone else can lawfully copy the book. The important issue is whether the work is protected and who owns the relevant rights.

    Can I Print a Book and Sell It Without Copyright Registration?

    If you own the copyright or have the necessary rights to reproduce and distribute the book, registration is not generally a legal prerequisite to selling copies.

    The situation is different if the book belongs to someone else. Printing and selling another person’s copyrighted work without the required permission can amount to infringement.

    The absence of a registration certificate does not make another person’s protected work free to copy.

    Which Books Have No Copyright?

    Copyright protection has a limited statutory term. For many literary works, the general rule is the author’s lifetime plus 60 years, subject to the provisions and exceptions under the Copyright Act.

    After the applicable term expires, the work may enter the public domain.

    However, an old book is not automatically free to reproduce. You should consider the copyright status of the particular work, translation, adaptation, illustrations and edition before reproducing it commercially.

    What Author Was Rejected 23 Times?

    Frank Herbert’s Dune is commonly cited in publishing discussions as having faced 23 rejections before publication.

    This anecdote is unrelated to the legal requirements for copyright registration. A publisher’s rejection does not determine whether an author’s original work qualifies for copyright protection.

    An author can have copyright in an eligible original work even before finding a publisher.

    Copyright Registration vs Trademark Registration

    Copyright and trademark protection are different forms of intellectual property protection.

    CopyrightTrademark
    Protects qualifying original creative expressionProtects distinctive brand identifiers
    Can cover books, artwork, software, music and filmsCan cover names, logos, slogans and other marks
    Protection generally arises automatically for eligible original worksRegistration provides statutory rights in the registered mark
    Useful for creative and content assetsUseful for brand identity

    A startup may need both types of protection.

    For example, a fashion business may consider trademark protection for its brand name and logo while separately assessing copyright protection for its original photographs, website content and artwork.

    See Lawizer’s Trademark Registration service for more information about protecting a business brand.

    Common Copyright Registration Mistakes to Avoid

    Trying to Register an Idea

    Copyright protects qualifying expression, not an idea or concept by itself.

    Confusing Copyright With Trademark Protection

    A business name and an original creative work are different intellectual property assets. Depending on the circumstances, you may need copyright registration, trademark registration or both.

    Ignoring IP Ownership Agreements

    If a freelancer, employee, contractor or agency creates work for your business, do not assume that payment alone resolves every ownership question.

    Use appropriate written agreements that clearly address intellectual property ownership, assignment and permitted use.

    Lawizer’s guide to freelance contracts in India also explains why IP ownership clauses matter when founders work with freelancers.

    Submitting Incorrect or Incomplete Material

    Different categories of copyright works have different filing requirements. Review the current Copyright Office instructions before submitting the application.

    Assuming Registration Guarantees Every Dispute

    Registration can provide important evidence, but it does not eliminate the need to establish the relevant facts if a dispute arises.

    Frequently Asked Questions About Copyright Registration in India

    Is it mandatory to register copyright in India?

    No. Copyright generally arises automatically when an eligible original work is created. Registration is optional, although registration can provide useful documentary evidence of ownership.

    Can copyright be claimed without registration?

    Yes. Registration is not a prerequisite for acquiring copyright in an eligible original work. However, registration may provide additional evidentiary value.

    Can I register my copyright online in India?

    Yes. The Copyright Office provides an online e-filing facility. Applicants can complete the prescribed application, upload the required material, pay the applicable fee and receive a Diary Number.

    What are the five things that can be copyrighted?

    A simplified list often mentions literary, dramatic, musical, artistic and audiovisual works. Legally, the principal categories under Section 13 include literary, dramatic, musical and artistic works, cinematograph films and sound recordings.

    What is not allowed in copyright?

    Copyright does not generally protect ideas, procedures, methods of operation or mathematical concepts as such. It protects qualifying original expression.

    Which item is not protected by copyright?

    Ideas, facts, methods and procedures are generally not protected merely as such. Names, titles and short phrases also generally do not receive copyright protection on their own.

    How do I protect my book from being copied?

    Maintain evidence of creation and ownership, use appropriate contracts, consider registration and ensure that third-party content is used only with the necessary permission or licence.

    Can I publish my book without copyright registration?

    Yes. Registration is not generally required before publication. Copyright can arise automatically in an eligible original literary work.

    Can I just print a book and sell it?

    You can generally reproduce and sell a book if you own the relevant rights or have permission to do so. You cannot assume that another person’s work is free to reproduce simply because it has not been registered.

    Which books have no copyright?

    Books whose copyright term has expired may be in the public domain. However, the status of a particular translation, adaptation, edition or illustration should be checked separately.

    What author was rejected 23 times?

    Frank Herbert’s Dune is commonly cited as having been rejected 23 times before publication. The anecdote does not affect the copyright status of an author’s original work.

    How do I get a copyright registration certificate?

    File the prescribed application with the required work and supporting information, pay the applicable statutory fee and complete the examination process. If the application is approved, the work is entered in the Register of Copyrights and the registration certificate is issued.

    What is the cost of copyright registration in India?

    The government fee depends on the type of work. The current official schedule lists ₹500 for literary, dramatic, musical or artistic works, ₹2,000 for certain literary or artistic works used or capable of being used in relation to goods or services, ₹5,000 for cinematograph films and ₹2,000 for sound recordings.

    How long does copyright registration take?

    There is a mandatory 30-day period after the Diary Number during which objections may be filed. If there is no objection, the application proceeds to examination. The overall timeline can vary depending on discrepancies, objections and responses.

    The official IP India FAQ states that, in the normal course, registration may take around 2 to 3 months, although individual applications can take longer depending on the circumstances.

    Can software be registered under copyright law?

    Yes. Computer programmes are treated as literary works for copyright purposes. Applicants should follow the current Copyright Office requirements for submitting software and source-code material.

    Protect Your Creative Work With Lawizer

    Your intellectual property can become one of the most valuable assets of your business. Whether you are a founder, author, designer, software developer, musician or content creator, documenting ownership early can help reduce avoidable disputes later.

    Copyright registration is not mandatory for copyright to exist. However, registration can create an official record and provide useful evidence concerning the registered work and recorded ownership particulars.

    If you need help understanding eligibility, preparing documents or filing an application, explore Lawizer’s Copyright Registration service.

    If your business also needs brand protection, you can explore Trademark Registration.

    For agreements dealing with ownership, confidentiality and commercial use of intellectual property, explore Lawizer’s business documentation and legal services.

    You can also read more practical guidance in the Lawizer legal blog.

    Related Lawizer resources:

    Official Sources

    This article is provided for general informational purposes and does not constitute legal advice. Copyright law, government fees, forms and filing requirements may change. Always verify the latest requirements with the Copyright Office before filing.

  • Website Terms And Conditions : India Business Guide

    Website Terms And Conditions : India Business Guide

    website terms and conditions are the rules that explain how people may use a business website and, where relevant, how online purchases, accounts, subscriptions, content and services are governed. For Indian founders, they are not merely a footer page. A well-drafted set of website terms can clarify responsibilities, reduce avoidable disputes and create a clearer legal framework for the website.

    Whether you operate an ecommerce store, SaaS platform, consulting website, marketplace, educational platform or service business, your website may involve customers, payments, personal data, intellectual property and third-party services. Clear terms help bring these activities under one consistent framework.

    However, there is no universal document that works for every website. The right terms depend on what your business sells, who uses the website, how users interact with it and which laws apply.

    What Are website terms and conditions?

    Website terms and conditions are contractual rules governing the relationship between a website operator and its users or customers. They can explain permitted website use, account responsibilities, payment terms, intellectual property rights, cancellations, refunds, disclaimers, liability and dispute resolution.

    The document may also be called Terms of Use, Terms of Service or simply Website Terms. The title matters less than the substance and the way the terms are presented and accepted.

    For example, a content website may mainly need rules covering intellectual property, acceptable use and disclaimers. An ecommerce website may need much more detail about orders, payment, delivery, cancellation, returns, refunds and consumer rights.

    Lawizer provides Privacy Policy and Terms of Use documentation for businesses that need a tailored online legal-document framework.

    Why Do Businesses Need website terms and conditions?

    A website can create legal and commercial relationships even when customers never sign a traditional paper contract. Users may create accounts, place orders, subscribe to services, download content or agree to recurring payments.

    Clear terms help establish what the business offers and what users are expected to do.

    • They define the scope of products or services.
    • They explain user responsibilities.
    • They set expectations about payments and cancellations.
    • They protect intellectual property.
    • They establish rules for accounts and website use.
    • They explain how disputes may be handled.
    • They can reduce uncertainty when a disagreement arises.

    Lawizer’s recent guidance for Indian founders also highlights customer terms, privacy documentation and other consumer-facing policies as part of the legal foundation for online businesses.

    Read Lawizer’s guide on legal mistakes startups make in India for a broader startup compliance checklist.

    What Should website terms and conditions Include?

    The contents should match the business model. A simple brochure website does not necessarily need the same clauses as a marketplace or subscription-based SaaS platform.

    1. Business and Website Information

    Start by identifying the business operating the website. Depending on the structure, this may include the legal name, business address, contact information and other appropriate details.

    The terms should make it reasonably clear who users are contracting with and how they can contact the business.

    2. User Eligibility and Account Rules

    If users create accounts, explain who can register and what information they must provide. State that users are responsible for keeping their credentials secure and for activities carried out through their account, subject to applicable law.

    You can also explain when an account may be suspended or terminated, such as for serious misuse, fraud or material breach of the terms.

    3. Acceptable Website Use

    Set out activities that users may not perform. These may include unauthorised access, interfering with website security, copying protected material without permission, distributing malicious code or using the website for unlawful purposes.

    Keep these restrictions relevant. Overly broad provisions can make terms harder to understand and may not provide the protection a business expects.

    4. Products, Services and Orders

    If the website sells goods or services, describe the basic commercial relationship. This can cover product descriptions, service scope, order acceptance, availability, pricing and circumstances in which an order may be cancelled.

    For an ecommerce business, the terms should work consistently with the website’s actual checkout process and consumer-facing policies.

    5. Payment, Cancellation and Refund Terms

    Payment provisions should explain when payment is due, accepted payment methods and what happens if a transaction fails.

    Cancellation and refund terms should be equally clear. Do not promise refunds in the terms if your actual business process does not provide them. Similarly, do not attempt to remove rights that applicable consumer law may provide.

    Businesses selling online should also review the Consumer Protection Act and related rules and the Consumer Protection (E-Commerce) Rules where applicable.

    6. Intellectual Property Rights

    Your website may contain logos, text, photographs, videos, software, designs, databases and other protected material. The terms can explain who owns those materials and what limited permission, if any, users receive to access them.

    For brand protection, founders can also explore Lawizer’s trademark registration service.

    7. User-Generated Content

    If customers can submit reviews, comments, photographs or other content, include rules for that material.

    The terms can address ownership, permissions granted to the business, prohibited content, moderation and removal. The wording should reflect the actual product and the type of content users can upload.

    8. Third-Party Links and Services

    Many websites use payment gateways, analytics tools, social-media plugins, maps, hosting providers and other third-party services.

    Your terms can explain that third-party services may be governed by their own terms. However, this clause should not be used to avoid responsibilities that legally remain with your business.

    9. Disclaimers and Limitation of Liability

    These clauses explain the circumstances in which the business limits responsibility for certain losses or website-related issues, subject to applicable law.

    They should be drafted carefully. A statement saying that the business has “no liability whatsoever” does not automatically make every possible claim disappear.

    10. Governing Law and Dispute Resolution

    The terms can identify the governing law and establish an appropriate mechanism for resolving disputes. Depending on the business, this may involve negotiation, mediation, arbitration or court proceedings.

    The clause should be consistent with applicable law and the actual business relationship.

    What Are the Five Essentials of website terms and conditions?

    There is no single statutory five-item checklist that applies to every website. However, founders can use five practical essentials when reviewing their terms:

    1. Clear identification: Users should understand who operates the website.
    2. Clear user obligations: The rules should explain what users may and may not do.
    3. Commercial terms: Products, services, payments, cancellations and refunds should be addressed where relevant.
    4. Legal protections: Intellectual property, liability, termination and dispute clauses should reflect the business.
    5. Effective acceptance: Users should have a clear opportunity to see and agree to the terms where contractual acceptance is intended.

    The exact requirements can vary with the transaction. Indian contract law generally focuses on matters such as competent parties, free consent, lawful consideration and lawful object, along with other applicable requirements.

    The Indian Contract Act, 1872 is the primary statute to review for general contract principles.

    What Are the 7 Requirements of a Valid Contract?

    Search results often describe a “seven requirements” list. However, there is no universal seven-point formula that should be treated as the complete legal test for every contract.

    A practical review may consider:

    • Offer or proposal.
    • Acceptance.
    • Consideration, where required.
    • Competency of the parties.
    • Free consent.
    • Lawful object and lawful consideration.
    • The agreement must not be one that the law treats as void or unenforceable.

    For a website, there is an additional practical issue: the business should consider how users are shown the terms and how acceptance is recorded.

    How Do You Make Simple website terms and conditions?

    You do not need to begin with a fifty-page legal document. Start by understanding the actual relationship between your business and its users.

    Step 1: Identify Your Business Model

    Ask what the website actually does. Is it an ecommerce store, SaaS product, marketplace, consulting business, content platform or lead-generation website?

    This decision affects the clauses you need.

    Step 2: Identify Your Users

    Determine whether you serve consumers, businesses, subscribers, vendors, freelancers, students or multiple groups.

    Different user groups can create different contractual and regulatory considerations.

    Step 3: Map the User Journey

    List every important interaction:

    • Landing on the website.
    • Creating an account.
    • Submitting information.
    • Purchasing a product.
    • Starting a subscription.
    • Downloading content.
    • Submitting reviews.
    • Contacting customer support.

    This helps you identify where legal terms need to apply.

    Step 4: Draft Relevant Clauses

    Build the document around the actual risks and transactions. Avoid filling it with clauses that have no connection to your business.

    If your business regularly signs contracts with freelancers, consultants or vendors, Lawizer also offers business documentation services.

    Step 5: Create a Clear Acceptance Process

    Where contractual acceptance is intended, consider using a clear mechanism such as an unchecked “I agree” checkbox linked to the terms before registration, checkout or another relevant action.

    Businesses should also retain appropriate records showing what terms applied and how acceptance occurred.

    Indian law recognises contracts formed through electronic means. Section 10A of the Information Technology Act, 2000 addresses the validity of contracts formed through electronic means.

    See the Information Technology Act, 2000 on India Code for the statutory text.

    Step 6: Keep the Terms Accessible

    Users should be able to find the terms easily. A footer link can improve accessibility, but businesses should consider whether users are given a meaningful opportunity to review the terms at the point where agreement is intended.

    Can I Legally Write My Own Website Terms?

    Yes. A business can draft its own terms. There is no general rule requiring every website to purchase a pre-written template from a lawyer.

    The bigger question is whether the document accurately reflects the business and applicable law.

    A generic template may contain irrelevant clauses, omit important provisions or describe a business process that you do not actually follow. That can create confusion when a dispute arises.

    Professional review becomes particularly useful for:

    • Marketplaces.
    • SaaS and subscription businesses.
    • Websites selling to consumers.
    • Businesses collecting substantial personal data.
    • Platforms with user-generated content.
    • Businesses using third-party sellers or service providers.
    • Regulated or industry-specific businesses.

    Lawizer’s Privacy Policy and Terms of Use service can be considered when a business wants its website documentation reviewed against its actual operations.

    Website Terms vs Privacy Policy vs Disclaimer

    Terms of Use

    Terms of Use establish the rules governing website access, services, accounts, transactions and other user relationships.

    Privacy Policy

    A Privacy Policy explains how the business handles personal data, including relevant information about collection, use, storage, sharing and user rights.

    These documents should not simply be merged without considering their different purposes.

    The Digital Personal Data Protection Act, 2023 should also be considered where its provisions apply. Businesses should verify current commencement notifications, rules and sector-specific requirements before relying on a compliance position.

    Disclaimer

    A disclaimer can explain limitations concerning information, professional advice, third-party material or particular risks. It is not a substitute for properly drafted website terms or privacy documentation.

    Important Legal Considerations for Indian Websites

    The legal framework depends heavily on the type of website and its activities. Founders should avoid assuming that one website policy automatically satisfies every legal requirement.

    Indian Contract Law

    The Indian Contract Act, 1872 provides the general contractual framework. Section 10 is particularly important when considering whether an agreement qualifies as a contract under the Act, subject to other applicable laws and provisions.

    Electronic Contracts

    Online agreements can be formed electronically. The Information Technology Act, 2000 specifically contains Section 10A on contracts formed through electronic means.

    Lawizer also explains electronic agreements in its guide to virtual contracts and legal validity in India.

    Consumer Protection

    If you sell goods or services to consumers online, consumer protection rules can become relevant. The Consumer Protection Act, 2019 and Consumer Protection (E-Commerce) Rules, 2020 should be reviewed where applicable.

    The Department of Consumer Affairs publishes the Consumer Protection Act and related rules, including the E-Commerce Rules.

    Data Protection

    If the website collects personal data, privacy documentation and data-handling practices should match what the business actually does.

    Do not copy a privacy policy that promises practices your business does not follow. Your website forms, analytics tools, payment systems, CRM and support systems should be considered when preparing the documentation.

    Common Mistakes in Website Terms and Conditions

    Copying Another Company’s Terms

    Another business may operate differently from yours. Its refund rules, customers, technology and legal risks may not apply to your business.

    Using a Generic Template Without Reviewing It

    Templates can provide a starting point. They should not replace a review of your actual website and business model.

    Making the Terms Impossible to Understand

    Legal protection does not require unnecessarily complicated language. Clear drafting makes obligations easier for users and business teams to follow.

    Hiding the Terms

    If users cannot easily locate the terms, the business may face questions about whether and how users were informed of them.

    Not Recording Acceptance

    For important online transactions, businesses should consider maintaining appropriate evidence of acceptance, including the version of the terms that applied at the relevant time.

    Ignoring Refund and Cancellation Rules

    Do not draft terms separately from the actual checkout process. The terms, refund policy and customer communications should tell the same story.

    Never Updating the Terms

    Your business can change quickly. New payment methods, subscriptions, products, markets and data practices can make old terms incomplete.

    Lawizer’s annual compliance services can also be useful as part of a broader process of keeping business documentation and recurring obligations organised.

    website terms and conditions Checklist for Indian Founders

    Before publishing or updating your website terms, use this checklist:

    • Identify the website operator clearly.
    • Describe the scope of the terms.
    • Define important users and accounts.
    • Set acceptable-use rules.
    • Explain products or services.
    • Set out payment conditions.
    • Address cancellation and refund rules.
    • Protect intellectual property.
    • Address user-generated content if applicable.
    • Explain third-party services where relevant.
    • Include appropriate disclaimers.
    • Include a suitable liability clause.
    • Address termination or suspension.
    • Specify governing law and dispute resolution where appropriate.
    • Provide contact or grievance information where required.
    • State an effective or last-updated date.
    • Provide a suitable acceptance mechanism.
    • Keep the document consistent with your Privacy Policy.

    Frequently Asked Questions About Website Terms

    What should a website terms and conditions document include?

    It should cover the rules relevant to the website and business. Common areas include user eligibility, account rules, acceptable use, products or services, payments, refunds, intellectual property, liability, termination and dispute resolution.

    Ecommerce and subscription businesses may need additional clauses because their customer relationships involve transactions, recurring services or consumer rights.

    What are the five essentials of a contract?

    There is no universal five-word formula. A common practical explanation covers offer, acceptance, consideration, competent parties and free consent, together with a lawful object and other applicable requirements.

    For a website, founders must also think about how users are presented with the terms and how acceptance is recorded.

    What are the 7 requirements of a valid contract?

    A commonly used seven-part summary includes offer, acceptance, consideration, competent parties, free consent, lawful object and an agreement that is not expressly void. The precise legal analysis depends on the transaction and applicable law.

    Can I legally write my own contract?

    Yes. A business can draft its own contract. However, the document should be reviewed against the actual transaction and applicable law. Complex websites can benefit from professional drafting or review.

    How do I make a simple legal contract?

    Identify the parties, define the purpose, describe the obligations of each side, establish payment or consideration where applicable, address important risks and provide an appropriate dispute mechanism. Make sure the parties receive and accept the terms properly.

    Can I create my own terms and conditions?

    Yes. You can create your own terms, but copying a template without customising it can leave important gaps. The document should accurately reflect your products, users, payment process and data practices.

    What are the 7 rules of a contract?

    There is no single universal list called the “seven rules of a contract”. Online searches often use this phrase to refer to different summaries of contract principles. It is better to assess the actual agreement against the applicable law.

    What are the 7 essential elements of a contract?

    Common explanations refer to offer, acceptance, consideration, intention or enforceability, competent parties, free consent and lawful purpose. However, the exact legal test should not be reduced to a universal seven-item checklist.

    What are the 10 essentials of a valid contract?

    Some educational resources use ten-item lists to explain contracts. These may break broad principles into smaller components. For a business website, the more useful approach is to identify the actual contractual requirements and website-specific risks.

    What are the 5 essential elements of a contract?

    A simplified explanation often includes offer, acceptance, consideration, intention to create legal obligations and competent parties. The Indian Contract Act and other applicable laws should be considered for the specific transaction.

    What things are required for freelancing and online business?

    Depending on the business, founders may need appropriate contracts, invoices, tax registrations, privacy documentation, website terms, intellectual property protection and other compliance measures.

    If your business works with freelancers, read Lawizer’s freelance contract guide for Indian founders.

    What is the difference between a freelancer and an independent contractor?

    The terms can overlap in ordinary business language. The legal classification depends on the actual relationship, contractual terms, control, work arrangement and applicable law. Businesses should avoid relying on labels alone.

    Final Takeaway: Keep Your Website Terms Clear and Current

    Good website terms are not about making a website look more “legal”. They are about making the business relationship clearer.

    The best document reflects what your business actually does. It explains the rules in language users can understand and supports the way your website collects information, takes orders, processes payments and provides services.

    Indian founders should also remember that website terms are only one part of a wider legal framework. Depending on the business, you may also need privacy documentation, commercial contracts, intellectual property protection, consumer-facing policies and ongoing compliance.

    Lawizer can help businesses review and organise these legal requirements. You can explore business documentation services, GST registration support, trademark registration and other startup and business legal services.

    Need help with your website’s legal documents? Consult Lawizer to understand which terms, privacy documents and business agreements are appropriate for your specific business model.

    Disclaimer: This article provides general educational information and is not a substitute for legal, tax or professional advice. Applicable requirements can vary based on the business structure, state, industry, customer base, transactions and changes in law. Businesses should obtain professional advice for their specific circumstances and verify current requirements with the relevant government authorities.

    Official Legal References

    Relevant Tags: Website Terms and Conditions, Terms of Use, Terms of Service, Indian Business Law, Startup Legal Compliance, Online Business Legal, Privacy Policy, Ecommerce Compliance, Business Contracts, Legal Documents for Startups, Indian Startups, Small Business Legal

  • Freelance Contract Essentials :

    Freelance Contract Essentials :

    freelance contract essentials for Indian businesses and freelancers

    Hiring a freelancer can help an Indian startup or small business move faster without adding a full-time employee. However, a simple WhatsApp conversation about the work, fee and deadline may not cover what happens when the project changes. freelance contract essentials give both sides a clear written framework for the work, payment, intellectual property, confidentiality and other important terms.

    A well-drafted agreement can reduce misunderstandings before they become disputes. It can also make it easier to establish what each party agreed to do, what the freelancer must deliver and when payment becomes due.

    This guide explains the key clauses every Indian business should consider when engaging a freelancer. It also covers contract validity, taxes, intellectual property, termination, dispute resolution and common mistakes.

    What Is a Freelance Contract?

    A freelance contract is a written agreement between a business or client and an independent professional. It sets out the services to be provided, deliverables, fees, timelines and responsibilities of both parties.

    For example, a startup may hire a designer to create a brand identity, a developer to build software, or a writer to produce website content. The contract should explain exactly what the freelancer is expected to provide and what the business must provide in return.

    The agreement can also deal with matters that are easy to overlook, such as ownership of source files, confidentiality, revision limits, termination and dispute resolution.

    Why a Written Freelance Agreement Matters

    A written agreement is useful because it creates a clear record of the commercial arrangement. It can reduce arguments about what was promised and provide a reference if a disagreement occurs.

    Indian contract law recognises agreements that satisfy the applicable requirements for a valid contract. Section 10 of the Indian Contract Act, 1872 refers to free consent, competent parties, lawful consideration and a lawful object, subject to other applicable legal requirements.

    Businesses can also use electronic methods to form contracts. Section 10A of the Information Technology Act, 2000 recognises that a contract is not unenforceable merely because electronic records or electronic communication were used in its formation.

    Read the Indian Contract Act, 1872 and the Information Technology Act, 2000 for the statutory framework.

    freelance contract essentials: What Should a Freelance Contract Include?

    The right agreement depends on the project, parties and risks involved. However, most businesses should consider the following core clauses.

    1. Details of the Client and Freelancer

    Start by identifying both parties correctly. For a business, use the legal name of the company or other contracting entity rather than only a brand name.

    • Full legal name of the client or business
    • Registered or correspondence address, where relevant
    • Freelancer’s full name or business name
    • Contact details
    • PAN and GST details where relevant
    • Name and authority of the person signing for a company

    Correct identification matters because the agreement should clearly establish who has the contractual rights and obligations.

    If your business is still being structured, you can also explore Private Limited Company Registration or LLP Registration through Lawizer.

    2. Scope of Work and Deliverables

    The scope of work is one of the most important freelance contract essentials. A vague description such as “build a website” or “manage social media” can create different expectations.

    Instead, describe the deliverables as specifically as possible.

    • What services will be provided?
    • What files, reports or outputs will be delivered?
    • How many pages, designs or posts are included?
    • What formats must be supplied?
    • What is excluded from the project?
    • How many revisions are included?
    • What milestones and deadlines apply?

    For example, a design agreement could specify five website screens, desktop and mobile versions, two revision rounds and delivery of specified source and export files.

    3. Change Requests and Scope Creep

    Projects often change after work begins. Your contract should explain what happens when the client requests additional work.

    A useful clause can require written approval and a separate fee or revised timeline for work outside the original scope. This protects both parties from an assumption that every new request is included in the original price.

    Lawizer’s Service Agreement and Term Sheet drafting service focuses on defining scope, fees, deliverables, milestones and timelines.

    4. Payment Terms and Invoicing

    A contract should state how much the freelancer will be paid and when payment becomes due. Do not leave payment terms to an informal conversation.

    • Total professional fee
    • Fixed, hourly or milestone-based pricing
    • Advance payment, if applicable
    • Milestone payment dates
    • Invoice requirements
    • Payment method
    • Applicable taxes
    • Consequences of delayed payment

    If payment is milestone-based, identify each milestone clearly. This can prevent disagreements about whether the freelancer has completed enough work to raise the next invoice.

    Any late-payment interest should be drafted carefully and should comply with applicable law and the agreed commercial terms. Avoid inserting an arbitrary penalty simply because it appears in an online template.

    5. Intellectual Property Ownership

    Intellectual property is particularly important when a freelancer creates software, designs, photographs, videos, written content, branding or other creative work.

    Do not assume that paying an invoice automatically answers every question about ownership. The agreement should expressly address the intended ownership and rights in the work product.

    The IP clause can specify:

    • Which deliverables are covered
    • Whether rights are assigned or licensed
    • When the transfer or licence becomes effective
    • Whether source and working files are included
    • How pre-existing materials are treated
    • Whether the freelancer may display the work in a portfolio
    • How third-party materials and licences are handled

    For projects where a separate transfer document is appropriate, Lawizer offers an IP Assignment Agreement service.

    Businesses that create original software, written material, artwork or other copyrightable works can also consider Copyright Registration where appropriate.

    6. Confidentiality and NDA Protection

    Freelancers may receive access to confidential business information while working on a project. This may include customer information, pricing, source code, business plans, product roadmaps or internal documents.

    A freelance agreement can contain confidentiality obligations. For sensitive engagements, a separate Non-Disclosure Agreement (NDA) may provide a more detailed framework.

    A confidentiality clause should explain:

    • What information is confidential
    • How the information may be used
    • Who may receive it
    • What information is excluded
    • How long confidentiality obligations continue
    • What happens when the engagement ends

    Confidentiality should not be drafted so broadly that it creates unreasonable restrictions. The agreement should reflect the legitimate information the business actually needs to protect.

    7. Tax, TDS and GST Terms

    Tax treatment should be considered when drafting the payment clause. A business should not simply copy an old freelance contract that refers to outdated tax provisions.

    For payments or credits from 1 April 2026, TDS provisions are governed by the Income-tax Act, 2025. The Income Tax Department states that Section 393 contains the relevant TDS framework for payments other than salaries, with tables specifying the applicable payment categories, thresholds and rates.

    Therefore, instead of inserting an old section number or fixed rate without checking the transaction, the agreement can state that applicable TDS will be deducted in accordance with the law in force at the relevant time.

    You can verify current tax requirements through the Income Tax Department. Businesses can also explore Lawizer’s ITR filing services for applicable business and professional tax-return needs.

    GST should also be considered. Whether a freelancer must register, charge GST or comply with other GST requirements depends on the nature of the supply, turnover and applicable rules. The agreement should clarify whether quoted fees are inclusive or exclusive of applicable GST.

    For current registration rules, refer to the CBIC GST FAQs and consider GST Registration assistance where appropriate.

    8. Deadlines, Milestones and Acceptance

    A good freelance contract should make the delivery process easy to understand. State the project start date, milestones and expected completion dates.

    Also consider how the client will review the work. For example, the contract can establish a reasonable review period and explain how feedback should be provided.

    Where a delay is caused by the client’s failure to provide required information, approvals or materials, the agreement can explain how the deadline will be adjusted.

    9. Termination and Exit Terms

    Every project should have an exit mechanism. Termination provisions explain when either party can end the relationship and what happens afterwards.

    Consider including:

    • Termination for convenience, if appropriate
    • Termination for material breach
    • Notice requirements
    • Payment for completed work
    • Treatment of partially completed work
    • Return or deletion of confidential information
    • Delivery of completed files
    • Survival of confidentiality and other relevant clauses

    There is no universal notice period that applies to every freelance engagement. The appropriate period depends on the project, contract structure and commercial relationship.

    10. Dispute Resolution and Governing Law

    A dispute clause can explain what happens if the client and freelancer cannot resolve a disagreement.

    Depending on the arrangement, the contract may provide for negotiation, mediation or arbitration before court proceedings. It should also identify the governing law and, where appropriate, the jurisdiction or seat of arbitration.

    Do not choose a dispute mechanism simply because it appears in another agreement. Consider the value of the contract, location of the parties and practical cost of enforcement.

    freelance contract essentials: What Makes a Contract Valid?

    Searches about freelance agreements often lead to questions about the “five essentials” or “seven requirements” of a valid contract. These lists can vary because different sources group the legal principles differently.

    Under Section 10 of the Indian Contract Act, 1872, agreements are contracts when they are made with free consent by parties competent to contract, for lawful consideration and a lawful object, and are not expressly declared void.

    In practical terms, a freelance arrangement should therefore have clear agreement between the parties and lawful terms. The parties should also have the legal capacity to enter into the agreement.

    What Are the Five Essentials of a Contract?

    A simple way to understand the basic principles is to look at:

    1. Offer: One party proposes the arrangement.
    2. Acceptance: The other party accepts the relevant terms.
    3. Consideration: There is a lawful exchange of value, such as payment for services.
    4. Competent parties: The parties must be legally capable of contracting.
    5. Lawful object: The purpose of the agreement must be lawful.

    Free consent and other statutory requirements also matter. A practical freelance contract should therefore do more than merely mention the fee and service. It should record the commercial terms clearly.

    What Are the 7 Requirements of a Valid Contract?

    Different legal resources may present the list differently, but a practical checklist can include:

    • Offer and acceptance
    • Competent parties
    • Free consent
    • Lawful consideration
    • Lawful object
    • Certainty of important terms
    • Terms that are not expressly void or otherwise unenforceable

    The exact legal position can depend on the facts and the type of transaction. For an important or high-value agreement, professional legal review is preferable to relying on a generic checklist.

    Can I Legally Write My Own Freelance Contract?

    Generally, parties can prepare their own contracts. There is no universal rule requiring every freelance agreement to be drafted by a lawyer.

    However, preparing a document and preparing a suitable legal agreement are two different things. A generic template may leave out important commercial terms or contain provisions that do not fit the actual transaction.

    Professional review becomes more valuable when the engagement involves significant intellectual property, sensitive customer information, international payments, high-value work, complex milestones or substantial business risk.

    How to Make a Simple Legal Freelance Contract

    1. Identify the parties. Use the correct legal names.
    2. Describe the services. List specific deliverables.
    3. Set the price. State the fee and payment schedule.
    4. Set deadlines. Add milestones and acceptance requirements.
    5. Protect IP and confidential information. Explain ownership and permitted use.
    6. Add termination terms. Explain how the relationship can end.
    7. Set dispute terms. State the governing law and dispute mechanism.
    8. Sign the agreement. Keep the final signed version and relevant records.

    For a business service arrangement, Lawizer’s Service Agreement drafting service can be relevant when the engagement needs clearly defined scope, fees and timelines.

    Freelance Contract Essentials: Freelancer vs Independent Contractor

    The terms “freelancer” and “independent contractor” are often used interchangeably in everyday business discussions, but they can describe slightly different concepts.

    A freelancer commonly provides project-based or independent services to clients. An independent contractor is a broader description of someone engaged under a contract to provide services independently rather than as an employee.

    The actual legal relationship depends on the facts, the agreement and applicable law. Simply calling someone an “independent contractor” does not automatically determine their legal status.

    If a person is actually being engaged as an employee, an employment arrangement may be more appropriate. Lawizer also provides Employment Agreement drafting for employer-employee relationships.

    What Things Are Required for Freelancing?

    Freelancing requires more than a professional skill. A reliable business process helps the freelancer and client work together smoothly.

    • A marketable professional skill
    • A portfolio or evidence of previous work
    • Clear pricing and payment terms
    • A defined client onboarding process
    • A written service or freelance agreement
    • A reliable invoicing and record-keeping system
    • Appropriate tax and GST compliance where applicable
    • Secure handling of client information

    Freelancers earning professional income should also understand their income-tax filing obligations. Lawizer’s guide to ITR-3 for freelancers and business owners explains the return and expense considerations for applicable taxpayers.

    What Are 7 High-Paying Freelance Skills?

    Rates vary significantly by experience, industry, location and client. However, skills that can command strong professional fees may include:

    • Software development
    • AI and automation
    • Cybersecurity
    • UI/UX design
    • Digital marketing
    • Copywriting and content strategy
    • Business or financial consulting

    Whatever the skill, a written agreement helps define exactly what the client is paying for.

    Common Freelance Contract Mistakes to Avoid

    Even when a business uses a contract, certain drafting mistakes can reduce its practical value.

    1. Using a Vague Scope

    “Complete the project” is rarely enough. List the actual outputs, specifications, deadlines and exclusions.

    2. Leaving Payment Terms Unclear

    State the fee, payment milestones, invoice process and applicable tax treatment.

    3. Assuming Payment Automatically Settles IP Ownership

    Address IP rights expressly. Identify what is being transferred or licensed and when the relevant rights take effect.

    4. Ignoring Tax Requirements

    Tax provisions change. Do not copy an old contract containing outdated TDS references or thresholds. Check the law applicable when the payment or credit occurs.

    5. Allowing Unlimited Revisions

    Unlimited revisions can create uncertainty for both sides. Set a reasonable revision process and explain how additional requests will be handled.

    6. Forgetting Confidentiality

    If the freelancer can access sensitive information, include suitable confidentiality obligations or use a separate NDA.

    7. Having No Termination Clause

    Projects can change. A clear exit mechanism is better than trying to negotiate termination after a dispute begins.

    8. Starting Work Before Signing

    Ideally, finalise the commercial terms before substantial work begins or an advance is paid. This reduces uncertainty about what the parties actually agreed.

    Frequently Asked Questions About Freelance Contract Essentials

    What should a freelance contract include?

    A freelance contract should generally cover the parties, scope of work, deliverables, fees, payment schedule, deadlines, intellectual property, confidentiality, taxes where relevant, termination and dispute resolution. The exact clauses should reflect the project.

    What are the five essentials of a contract?

    A common simplified explanation includes offer, acceptance, consideration, competent parties and lawful object. Free consent and other legal requirements also matter under Indian contract law.

    What are the 7 requirements for a valid contract?

    A practical checklist includes offer and acceptance, competent parties, free consent, lawful consideration, lawful object, certainty of important terms and the absence of terms that are expressly void or otherwise unenforceable.

    How do I make a simple legal contract?

    Identify the parties, describe the services, agree on payment, set deadlines, address IP and confidentiality, add termination and dispute clauses, and sign the final document. Complex arrangements should be reviewed professionally.

    Can I legally write my own contract?

    Yes, parties can generally prepare their own agreements. However, a self-drafted contract may not address risks specific to the project. Professional review can be useful for high-value, complex or IP-heavy engagements.

    Can I create my own contract?

    Yes. You can create a contract yourself, provided the agreement complies with applicable law and accurately records the parties’ agreement. A generic template should be customised rather than copied without review.

    What are the 7 rules of a contract?

    There is no single universally accepted seven-rule list. Practical rules include clear agreement, lawful terms, competent parties, free consent, definite obligations, appropriate consideration and provisions that are not void or otherwise unenforceable.

    What things are required for freelancing?

    A freelancer generally needs a marketable skill, portfolio, clients, pricing and invoicing processes, suitable contracts, record keeping and compliance with applicable tax or GST requirements.

    Do I pay tax if I freelance?

    Freelance income can be taxable. The amount and method of taxation depend on the taxpayer’s income, nature of professional activity, applicable deductions, tax regime and other facts. Freelancers should assess their individual tax position rather than rely on a general rate.

    How much tax will I pay as a freelancer?

    There is no single freelancer tax rate. Tax liability depends on the applicable income-tax rules, total taxable income, deductions, regime and the nature of the income. Current rules should be checked for the relevant tax year.

    What’s the difference between a freelance and an independent contractor?

    A freelancer usually refers to an independent professional providing services, often on a project basis. Independent contractor is a broader contractual description. The legal relationship depends on the actual arrangement rather than the label alone.

    What are 7 high-paying freelance skills?

    Software development, AI and automation, cybersecurity, UI/UX design, digital marketing, copywriting and consulting can all be commercially valuable freelance skills. Actual earnings vary by expertise, demand and client.

    Freelance Agreement Checklist for Indian Businesses

    Before signing a freelance agreement, use this quick checklist:

    • Correct legal names of both parties
    • Clear scope of work
    • Specific deliverables
    • Revision limits
    • Milestones and deadlines
    • Fee and payment schedule
    • Applicable TDS and GST treatment
    • IP ownership or licensing terms
    • Confidentiality obligations
    • Termination procedure
    • Dispute resolution mechanism
    • Governing law and jurisdiction, where appropriate
    • Signatures and final copies

    Conclusion: Put the Agreement in Place Before Work Starts

    A freelance relationship works best when both parties understand their responsibilities from the beginning. The strongest freelance contract essentials are not complicated: define the work, agree on payment, protect intellectual property and confidential information, address taxes, and establish what happens if the project changes or ends early.
    Do not treat the agreement as paperwork to complete after a dispute appears. Put the important terms in writing before substantial work begins.

    If you are hiring a freelancer for software development, design, marketing, consulting, content or another professional service, Lawizer can help you choose and prepare the appropriate business documentation.

    Explore Lawizer’s Consultancy Agreement drafting, Service Agreement drafting, NDA drafting and IP Assignment Agreement drafting services for different business requirements.

    Need help with your agreement? Consult Lawizer for assistance with business contracts and legal documentation tailored to your situation.

    Disclaimer: This article is for general informational purposes and does not constitute legal, tax or professional advice. Contract, tax, GST, stamping, registration and enforcement requirements can depend on the facts, parties, state and applicable law. Obtain professional advice for a specific transaction.

  • Legal Mistakes Startups Make in India: 10 to Avoid :

    Legal Mistakes Startups Make in India: 10 to Avoid :

    Starting a business is exciting, but the legal mistakes startups make can quietly become expensive problems later. A founder may have a great product, paying customers and a strong growth plan, yet still face trouble because the company structure, contracts, intellectual property, tax records or statutory filings were not handled properly.

    For Indian founders, legal compliance is not something to think about only after receiving a notice. It starts with choosing the right business structure and continues through contracts, GST, tax filings, intellectual property protection, employment documentation and annual compliance.

    The good news is that many of these problems are preventable. A startup does not need a huge legal department to build a sound legal foundation. It needs the right documents, timely filings and a clear understanding of its obligations.

    In this guide, we cover the most common legal mistakes startups make in India, why they happen and what founders can do to avoid them.

    What Is the #1 Legal Mistake Startups Make?

    The biggest mistake is treating legal and compliance work as something that can be handled later.

    Founders understandably prioritise product development, sales, hiring and fundraising. Legal work can feel less urgent when everything is going well. The problem is that legal gaps often remain invisible until something goes wrong.

    A missing founder agreement may become important when two co-founders disagree. An unprotected brand may become a problem after a competitor files a trademark application. Incomplete corporate filings may surface during investor due diligence.

    Instead of waiting for a problem, founders should build a basic legal and compliance system from the beginning.
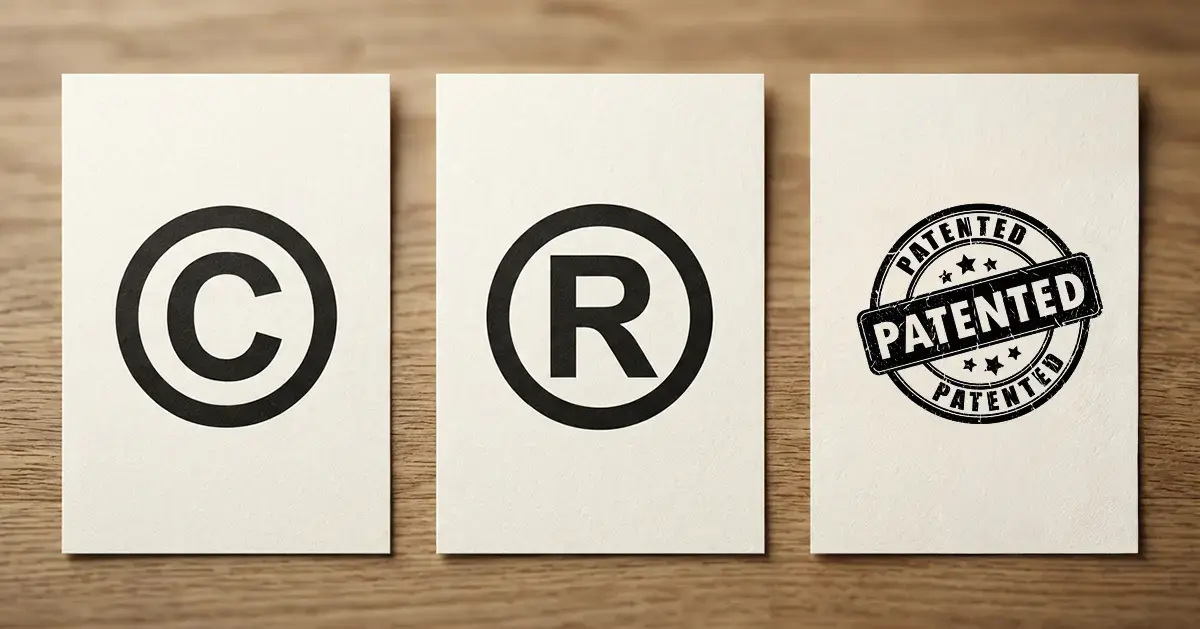
    That can include:

    • Choosing an appropriate business structure.
    • Documenting founder ownership and responsibilities.
    • Checking and protecting the business name and brand.
    • Using written contracts with employees, vendors and customers.
    • Reviewing GST and tax applicability.
    • Protecting intellectual property.
    • Tracking MCA, tax and other recurring compliance requirements.

    If you are still deciding how to structure your business, Lawizer’s Private Limited Company Registration service and guides on OPC vs LLP vs Private Limited Company can help you compare the available structures.

    10 Legal Mistakes Startups Make in India

    1. Choosing a Company Name Without Checking Trademark Availability

    One of the first legal mistakes startups make is assuming that a company name approved for incorporation is automatically protected as a brand.

    It is not.

    Company-name approval and trademark protection are separate matters. A name may appear acceptable for company incorporation while a similar or identical trademark already exists for relevant goods or services.

    Before committing significant money to branding, founders should check:

    • Existing company and LLP names.
    • Existing trademarks.
    • Relevant trademark classes.
    • Domain-name availability.
    • Potentially confusingly similar brands.

    The official IP India trademark search is a useful starting point.

    Registration of a trademark can provide stronger statutory protection for the brand. IP India explains that registered marks can provide exclusive rights in relation to the registered goods or services and can help protect against infringement.

    For founders who want professional assistance, Lawizer also provides Trademark Registration support.

    2. Choosing the Wrong Business Structure

    Another common mistake is selecting a business structure without considering the startup’s long-term plans.

    India offers several structures, including sole proprietorships, partnerships, LLPs, OPCs and private limited companies. Each has different legal, compliance, ownership and funding implications.

    A founder expecting venture capital investment may have different requirements from a consultant who plans to remain a one-person business. Similarly, a professional services firm may value operational flexibility differently from a technology startup planning to issue equity to investors and employees.

    Before incorporating, consider:

    • Number of founders.
    • Ownership and control.
    • Liability protection.
    • Expected investment.
    • Future fundraising.
    • Employee equity plans.
    • Compliance responsibilities.
    • Tax and accounting requirements.

    There is no single structure that is legally or commercially ideal for every business. Lawizer’s guide on Private Limited vs LLP vs Sole Proprietorship provides a useful comparison.

    3. Not Having a Proper Founders’ Agreement

    Two friends starting a company may agree verbally on who will do what and who will own what. That arrangement can feel perfectly fine during the early days.

    It becomes much less comfortable when the business starts making money.

    A founders’ agreement can document important expectations before disagreements arise. Depending on the circumstances, it may address:

    • Founder roles and responsibilities.
    • Shareholding and ownership.
    • Decision-making rights.
    • Founder exits.
    • Vesting arrangements.
    • Confidentiality.
    • Intellectual property ownership.
    • Restrictions on competing activities, where legally appropriate.
    • Dispute-resolution mechanisms.

    Founder relationships can change as the business grows. Putting important arrangements in writing makes the company’s position clearer.

    Lawizer offers a dedicated Co-Founder Agreement service, along with related shareholder documentation.

    4. Treating Equity and the Cap Table Casually

    Equity is one area where an informal promise can create a very formal problem.

    Founders should maintain accurate records of share ownership, allotments, transfers and other equity arrangements. The company’s statutory records and internal cap table should remain consistent.

    Before allocating equity, founders should understand:

    • Who owns the shares.
    • How many shares have been issued.
    • Whether investors will receive shares.
    • Whether an ESOP pool is planned.
    • How future fundraising may dilute existing shareholders.
    • Whether shares are subject to vesting or other arrangements.

    A founder should also be cautious about saying that someone will receive “1%” without defining what that percentage actually means, when it vests and how future dilution affects it.

    The percentage alone does not tell you whether an equity grant is financially attractive.

    5. Failing to Protect Intellectual Property

    For many startups, intellectual property is one of the most valuable assets on the balance sheet, even if it does not appear there in a simple way.

    IP can include a brand name, logo, software, source code, designs, written material, inventions, databases and proprietary business processes.

    A common mistake is assuming that the company automatically owns everything created by a freelancer, developer or agency simply because the company paid for the work.

    Founders should use appropriate written agreements that clearly address ownership and permitted use of work created for the business.

    Depending on the relationship, this may include:

    Brand protection is another part of IP planning. You can learn more through Lawizer’s guide to trademark registration in India.

    6. Ignoring GST, TDS and Income-Tax Compliance

    Tax compliance is another area where founders sometimes wait until the business becomes “big enough” to worry about it.

    That approach can be risky because GST registration and other tax obligations depend on the nature of the business, turnover, location, transactions and other applicable conditions.

    For GST, the general threshold rules are not the only consideration. Certain categories of taxpayers may have registration obligations regardless of ordinary turnover thresholds. The exact applicability should therefore be checked against the current GST law and the startup’s actual activities.

    The official GST registration guidance is a useful primary source for the registration process.

    Founders should also keep track of:

    • GST registration, where applicable.
    • GST returns.
    • Tax invoices and records.
    • Input Tax Credit requirements.
    • TDS obligations, where applicable.
    • Advance-tax requirements, where applicable.
    • Annual income-tax returns.

    Lawizer’s guide on GST Registration for Startups explains common registration and compliance considerations. For corporate income-tax compliance, founders can also review the guide to ITR-6 filing for private limited companies.

    7. Signing Contracts Without Understanding the Terms

    “It’s just a standard agreement” is not a legal strategy.

    Startups enter into contracts with customers, vendors, freelancers, employees, consultants, landlords, technology providers and investors. Each contract can create rights and obligations that affect the business.

    Important clauses may include:

    • Payment terms.
    • Scope of work.
    • Intellectual property ownership.
    • Confidentiality.
    • Termination rights.
    • Liability and indemnity.
    • Warranties.
    • Dispute resolution.
    • Governing law and jurisdiction.

    A contract downloaded from the internet may not reflect your business model or risk profile.

    Lawizer provides several forms of business documentation and contract support, including employment agreements, consultancy agreements, service agreements and SaaS agreements.

    8. Forgetting Post-Incorporation Compliance

    Receiving a Certificate of Incorporation can feel like the finish line. Legally, it is often the beginning of a company’s recurring compliance responsibilities.

    Depending on the company’s structure and circumstances, founders may need to deal with matters such as:

    • Commencement-related filings.
    • Share certificates and statutory records.
    • Board meetings and minutes.
    • Annual financial-statement filings.
    • Annual returns.
    • Director KYC requirements.
    • Income-tax returns.
    • GST returns, where applicable.

    For example, certain newly incorporated companies are required to file a declaration relating to commencement of business within the applicable statutory period before undertaking activities covered by the law.

    The exact compliance calendar depends on the company’s structure and circumstances, so founders should not rely on a generic checklist without checking applicability.

    Lawizer’s Annual Compliance service provides a useful overview of recurring company filings. You can also read the guide to INC-20A and commencement of business compliance.

    9. Ignoring Employment, Privacy and Consumer Compliance

    Legal risk grows as a startup grows.

    A business with one founder and no customers has a different compliance profile from a company with 50 employees, thousands of customers and a mobile application collecting personal information.

    As the business develops, founders should review areas such as:

    • Employment and consultancy agreements.
    • Confidentiality obligations.
    • Employee intellectual property.
    • Applicable labour-law requirements.
    • Customer terms and conditions.
    • Privacy documentation.
    • Data-security practices.
    • Industry-specific licences.

    For online businesses, appropriate Privacy Policy and Terms of Use documentation can be an important part of the legal foundation.

    The exact requirements depend on what data the business collects, how it processes that data and which laws apply to its activities.

    10. Waiting Until Funding to Clean Up Legal Problems

    Another major mistake is treating legal due diligence as something that begins one week before a funding round.

    Investors may examine corporate records, founder ownership, intellectual property, contracts, statutory filings, tax compliance and other legal matters during due diligence.

    Problems can include:

    • Unclear founder ownership.
    • Inconsistent cap-table information.
    • Missing IP assignments.
    • Unresolved trademark issues.
    • Incomplete statutory filings.
    • Tax or GST compliance gaps.
    • Undocumented employee equity arrangements.
    • Contracts containing unexpected liabilities.

    Cleaning everything up before fundraising can be more stressful and expensive than maintaining proper records from the beginning.
    Think of legal compliance as part of being investment-ready, not as paperwork that exists only for regulators.

    Is It True That 90% of Startups Fail?

    The statement that 90% of startups fail is widely repeated online, but it should not be treated as a universal statistic without context.

    Different studies use different definitions of “failure,” time periods, countries and types of startups. A startup that shuts down, becomes inactive, is acquired or simply stops pursuing rapid growth may be classified differently depending on the study.

    So the better question is not whether exactly 90% of startups fail. It is what founders can do to reduce avoidable risks.

    Legal compliance cannot guarantee business success. Product-market fit, cash flow, competition, execution and customer demand remain critical.

    But strong legal foundations can help prevent problems that are otherwise avoidable.

    Why Do 90% of Startups Fail?

    There is no single reason that explains startup failure.

    Common business challenges can include:

    • Lack of product-market fit.
    • Poor cash-flow management.
    • Insufficient funding.
    • Weak customer acquisition.
    • Pricing problems.
    • Strong competition.
    • Founder disagreements.
    • Operational problems.

    Legal mistakes can sometimes make these challenges worse. For example, a founder dispute can consume time and money, while an IP dispute can force an expensive rebrand.

    That is why legal planning should be viewed as risk management rather than a guarantee of success.

    What Is the 80/20 Rule for Startups?

    The 80/20 rule, commonly associated with the Pareto principle, suggests that a relatively small number of inputs can account for a large proportion of outcomes.

    For a startup, the principle can be useful for prioritisation. It is not an Indian legal rule and does not replace compliance requirements.

    From a legal perspective, founders can prioritise high-impact areas such as:

    • Business structure and ownership.
    • Founder agreements.
    • IP protection.
    • Important commercial contracts.
    • GST and tax compliance.
    • Recurring corporate filings.

    These areas do not cover every possible legal requirement, but they are often a sensible starting point for building a legal-risk checklist.

    How Legal Mistakes Can Contribute to Startup Failure

    Not every failed startup failed because of a legal issue. However, legal problems can turn manageable business problems into expensive ones.

    Consider a startup that spends two years building a brand without checking trademark conflicts. If the business later has to rebrand, it may lose marketing investment, customer recognition and valuable time.

    Similarly, a startup with unclear founder ownership may struggle when an investor asks for a clean cap table.

    The lesson is simple: legal hygiene does not create demand for a product, but it can prevent unnecessary friction while the business grows.

    Is 1% Equity in a Startup Good?

    There is no universal answer.

    One percent of a very early-stage company can represent a meaningful economic interest, while 1% of a later-stage company can have a very different value. The terms surrounding the equity can matter just as much as the headline percentage.

    Before accepting or granting equity, consider:

    • Current company valuation.
    • Expected future dilution.
    • Vesting conditions.
    • Exercise or purchase terms, where applicable.
    • Voting and other rights.
    • Existing and planned ESOP pools.
    • Investor rights.

    Founders and employees should understand the actual documentation rather than relying only on a percentage mentioned in a conversation.

    How Much Equity Should a CEO Get in a Startup?

    There is no fixed legal percentage that every startup CEO should receive.

    A founder-CEO and a professional CEO hired after the company has been established may have very different compensation arrangements.

    Equity negotiations can depend on factors such as:

    • Whether the CEO is a founder.
    • Company stage.
    • Cash compensation.
    • Experience and responsibilities.
    • Existing founder ownership.
    • Investor expectations.
    • Vesting and performance conditions.

    The important point is to document the arrangement properly and understand how future fundraising may change ownership percentages.

    A Simple Legal Checklist for an Indian Startup

    Instead of trying to solve every legal question on the first day, founders can work through their legal obligations in stages.

    Before Launch

    • Choose the appropriate business structure.
    • Check the proposed company and brand name.
    • Document founder ownership.
    • Define founder responsibilities.
    • Review GST and tax applicability.
    • Identify industry-specific registrations or licences.
    • Protect important intellectual property.

    Before Hiring or Signing Customers

    • Use suitable employment or consultancy agreements.
    • Document confidentiality obligations.
    • Clarify ownership of work created for the business.
    • Use appropriate customer and vendor agreements.
    • Review payment, termination and liability clauses.

    After Incorporation

    • Track MCA and ROC requirements.
    • Complete applicable post-incorporation filings.
    • Maintain statutory records.
    • Review GST and tax filings.
    • Maintain accurate accounting records.
    • Track director and shareholder changes.

    Before Raising Funding

    • Reconcile the cap table.
    • Confirm founder and shareholder documentation.
    • Review IP ownership.
    • Check trademark status.
    • Review material customer and vendor contracts.
    • Check pending statutory filings.
    • Review tax and GST compliance.

    Frequently Asked Questions About Legal Mistakes Startups Make

    What is the #1 mistake startups can make?

    One of the most serious mistakes is treating legal and compliance matters as an afterthought. Important ownership, IP, tax and contractual issues are easier to manage when they are addressed early.

    Why do 90% of startups fail?

    The 90% figure should not be treated as a universal failure rate. Startup failure can result from multiple factors, including weak product-market fit, cash-flow problems, competition, poor execution and founder disagreements.

    Is it true that 90% of startups fail?

    Not as a universal rule. The commonly quoted figure depends on the study and definition being used. Founders should focus on evidence-based risk factors rather than a single headline statistic.

    What is the 80/20 rule for startups?

    The 80/20 rule is a general prioritisation principle suggesting that a relatively small number of factors may produce a large share of results. It is not a legal requirement. Founders can use it to prioritise high-impact business and compliance tasks.

    Is 1% equity in a startup good?

    It depends on the company’s valuation, stage, dilution, vesting terms, rights and the person’s role. The percentage should always be evaluated together with the complete equity arrangement.

    How much equity should a CEO get in a startup?

    There is no fixed percentage. A founder-CEO and a hired CEO may have completely different arrangements. Compensation, experience, stage, responsibilities, existing ownership and investor expectations can all affect the appropriate structure.

    What are the top 10 failed startups in India?

    Lists of failed Indian startups vary because different sources use different definitions of failure. Rather than focusing only on company names, founders should study recurring failure patterns such as cash-flow problems, weak market demand, operational issues and governance failures.

    Who is considered the “bad boy” of Indian startups?

    “Bad boy” is an informal media label rather than a legal or official classification. Different publications may use the phrase for different entrepreneurs, so it should not be treated as an objective category.

    Who is the 27-year-old billionaire in India?

    Young billionaire claims can change as company valuations and ownership estimates change. This question is also separate from startup legal compliance, so founders should focus on ownership documentation, taxation and regulatory requirements rather than headline wealth rankings.

    Final Takeaway: Build the Legal Foundation Before You Scale

    The legal mistakes startups make are often not dramatic at the beginning. They are small gaps: a missing agreement, an unchecked brand name, an overlooked filing or an undocumented ownership arrangement.
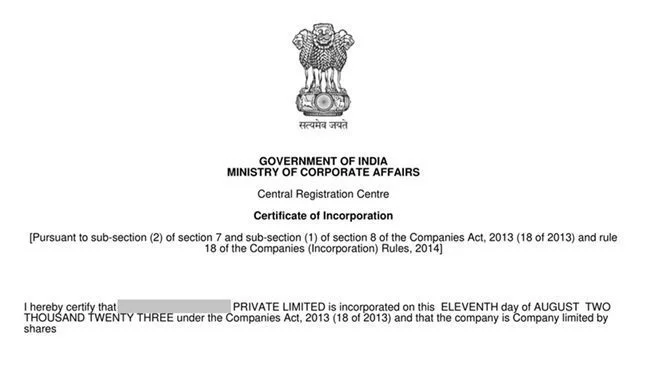
    Those small gaps can become much harder to fix once the company has employees, investors, customers and valuable intellectual property.

    A better approach is to build legal compliance into the startup’s operating routine from day one. Choose the right structure, document founder relationships, protect your IP, review contracts, monitor tax obligations and maintain recurring corporate filings.

    If you are unsure what your startup needs, you do not have to figure out the entire legal landscape alone.

    Need help reviewing your startup’s legal setup? You can explore Lawizer’s startup and business legal services for company registration, GST, trademark protection, documentation and compliance support.

    You can also review Lawizer’s annual compliance services or speak with the Lawizer team about your specific requirements.

    Disclaimer: This article is intended for general educational information and does not constitute legal, tax or professional advice. Startup obligations can vary based on the entity structure, business activity, turnover, state, transactions and changes in applicable law. Founders should obtain professional advice for their specific circumstances and verify current requirements with the relevant government authority.

  • Private Limited Company Registration: Process, Cost & FAQs

    Private Limited Company Registration: Process, Cost & FAQs

    Starting a business in India involves more than choosing a name and opening a bank account. The legal structure you choose can affect liability, taxation, fundraising, compliance and long-term growth. For many startups and growing businesses, a Private Limited Company offers a practical structure because it creates a separate legal entity and limits shareholder liability, subject to applicable law.

    Private limited company registration is completed through the Ministry of Corporate Affairs (MCA) under the prescribed incorporation process. This guide covers eligibility, documents, the MCA process, costs, taxation, GST, compliance and the differences between a Private Limited Company and an LLP.

    What Is a Private Limited Company?

    A Private Limited Company is a company incorporated under the Companies Act, 2013. It has a legal identity separate from its shareholders. The company can own property, enter contracts, open bank accounts and conduct business in its own name.

    A major benefit is limited liability. Generally, shareholders are liable only to the extent of their agreed contribution or unpaid amount on their shares, subject to the Companies Act and the facts of a particular case.

    Key Features of a Private Limited Company

    • It has a separate legal identity.
    • Shareholders generally receive limited liability protection.
    • An ordinary private company requires at least two members and two directors.
    • At least one director must satisfy the statutory residence requirement.
    • Ownership is represented through shares.
    • The company has perpetual succession.
    • Transfer of shares is subject to restrictions under applicable law and the Articles of Association.
    • A private company cannot invite the public to subscribe to its securities.

    This structure is often suitable for startups, growing businesses and founders who expect to raise equity investment or bring additional shareholders into the business.

    However, incorporation is not the only option. A founder with a different ownership or compliance requirement can also compare LLP registration or One Person Company registration.

    Who Is Eligible for Private Limited Company Registration?

    An ordinary private company generally requires at least two members and two directors. The members own shares in the company, while the directors manage its affairs within the framework of company law and the company’s constitutional documents.

    Minimum Requirements

    • Members: At least two.
    • Directors: At least two.
    • Resident director: At least one director must satisfy the statutory residence requirement.
    • Registered office: The company must have a registered office in India.
    • Company name: The proposed name must comply with applicable MCA naming rules.

    The same person can be both a shareholder and a director. Therefore, two founders can generally satisfy both roles without appointing four separate people.

    Can NRIs or Foreign Nationals Become Directors or Shareholders?

    NRIs and foreign nationals can participate in Indian companies, subject to applicable company law, foreign exchange regulations and documentation requirements.

    Additional formalities may apply to documents executed outside India. These can include notarisation, apostille or consularisation, depending on the country and circumstances. Foreign investment rules may also apply to the proposed business activity.

    Is There a Minimum Capital Requirement?

    There is no general minimum paid-up capital requirement for incorporating an ordinary private company. Founders should still decide the authorised capital and initial subscription based on the proposed ownership structure and funding needs.

    Capital planning is important because changes to share capital later may require additional corporate documentation and filings.

    Documents Required for private limited company registration

    Preparing accurate documents is one of the most important parts of incorporation. Incorrect names, mismatched addresses or incomplete proofs can result in queries or resubmission.

    Documents Required from Directors and Shareholders

    • PAN or applicable identity document.
    • Proof of residential address.
    • Recent photograph, where required.
    • Email address and mobile number.
    • Digital Signature Certificate, where required.
    • Additional documents for foreign subscribers or directors, where applicable.

    Documents Required for the Registered Office

    The exact documents depend on whether the premises are owned, rented, leased or being used with the owner’s consent.

    Common documents can include:

    • Proof of ownership or possession.
    • Recent utility bill or accepted address proof.
    • Rent or lease agreement, where applicable.
    • No-objection certificate from the owner, where required.

    A commercial office is not necessarily required simply because the business is incorporated as a private company. A residential or rented premises may be used as the registered office if the applicable requirements are satisfied.

    Founders can also review Lawizer’s company registration and incorporation guides for related documentation and compliance topics.

    How to Register a Private Limited Company in India

    The incorporation process is largely electronic. Applications are submitted through the MCA’s prescribed systems, with the exact forms and supporting requirements depending on the proposed company and its subscribers or directors.

    Step 1: Obtain the Required Digital Signatures

    Company incorporation documents are filed electronically. The individuals required to sign the relevant forms therefore need the appropriate digital signing facility.

    A Digital Signature Certificate, or DSC, is used to authenticate electronic documents. The exact DSC requirements depend on the filing.

    Step 2: Decide the Company’s Basic Structure

    Before filing, the founders should agree on the proposed name, business objects, registered office, directors, shareholders, authorised capital and initial shareholding.

    The shareholding ratio should be discussed carefully. A clear founder structure can prevent disagreements over ownership later.

    Where there are multiple founders, a founder-focused business legal service can also help identify related documentation needs.

    Step 3: Choose and Reserve the Company Name

    The proposed name must comply with the Companies Act and applicable incorporation rules. It should not be deceptively similar to an existing company or LLP, or improperly conflict with a protected trademark.

    Company-name approval and trademark registration are different processes. MCA approval does not by itself give the company exclusive trademark rights over a brand.

    Founders should therefore conduct both company-name and trademark checks before finalising a brand.

    Step 4: Prepare the MOA and AOA

    The Memorandum of Association, or MOA, sets out important details about the company’s constitution and objects. The Articles of Association, or AOA, contain rules governing internal management.

    These documents should reflect the actual business structure and the founders’ intended ownership arrangement.

    Step 5: File the Incorporation Application with MCA

    The SPICe+ system is used for company incorporation. The application captures information about the proposed company, subscribers, directors, registered office and other required particulars.

    Linked forms and electronic versions of the MOA and AOA may also form part of the incorporation process.

    Step 6: Respond to MCA Queries, If Any

    The MCA reviews the application. If there is an issue with the proposed name, documents, declarations or other information, the application may require clarification or resubmission.

    Careful preparation can reduce avoidable errors. Founders should ensure that names, addresses, identification documents and declarations are consistent across the application.

    Step 7: Receive the Certificate of Incorporation

    After approval, the company receives its Certificate of Incorporation and Corporate Identity Number, or CIN. PAN and TAN are also allotted through the integrated incorporation process where applicable.

    The Certificate of Incorporation confirms that the company has been incorporated as a legal entity.

    Step 8: Complete Post-Incorporation Formalities

    Incorporation does not end the company’s legal responsibilities. Depending on the company and its activities, founders may need to complete requirements concerning the bank account, share capital, commencement of business, GST, accounting and other registrations.

    Where Section 10A of the Companies Act applies, the company must also comply with the prescribed commencement-of-business declaration within the applicable statutory period.

    Can I Register a Pvt Ltd Company by Myself?

    Yes, founders can handle much of the incorporation process themselves because the MCA system is online. However, the process includes forms, declarations, electronic signatures and supporting documents.

    Some filings or documents may also require professional certification or involvement, depending on the circumstances. Therefore, DIY incorporation does not necessarily mean that professional involvement can be avoided in every case.

    DIY Registration vs Professional Assistance

    • DIY: potentially lower professional cost, but the founder manages documents, forms, payments and follow-ups.
    • Professional assistance: useful for document checks, filing, MCA queries and resubmissions.

    Professional assistance can be particularly useful where there are foreign shareholders, multiple founders, complex ownership arrangements or unusual business activities.

    Lawizer provides Private Limited Company incorporation support for founders who want assistance with the process.

    How Much Does Private Limited Company Registration Cost in India?

    The total cost is not identical for every company. It can include MCA filing fees, stamp duty, name-reservation charges where applicable, PAN and TAN-related charges, and professional or facilitation fees.

    MCA Name Approval Fees

    If a proposed company name is reserved separately through SPICe+ Part A, MCA’s published guidance specifies a ₹1,000 name-reservation fee.

    Government fees can change. Founders should verify the amount displayed on the MCA portal before making payment.

    Government Incorporation Fees

    MCA fees can depend on the authorised share capital and applicable rules. State stamp duty can also vary according to the state in which the company is incorporated.

    MCA guidance provides a zero filing-fee concession for eligible companies with authorised capital up to ₹15 lakh. Applicable stamp duty still needs to be considered.

    This is why a quoted incorporation package should not automatically be treated as the complete government cost for every company.

    Professional or Facilitation Fees

    Professional charges vary according to the service provider and the complexity of the incorporation.

    Before paying, check whether the quoted amount includes DSC, government charges, stamp duty, document preparation and post-incorporation assistance.

    Lawizer’s startup and business legal services cover incorporation and several related registrations.

    How Do I Pay MCA Fees?

    MCA fees are generally paid electronically during the filing process. A consolidated challan is generated for applicable charges.

    Founders should retain the payment acknowledgement and challan with the company’s incorporation records.

    Which Is Better: Pvt Ltd or LLP?

    There is no universal answer. The better structure depends on the founders, funding plans, ownership model, business activity and compliance requirements.

    When a Private Limited Company May Be Better

    • You plan to raise equity investment.
    • You need a clear shareholding structure.
    • You expect to add investors or shareholders.
    • You want a structure suited to a scalable startup.
    • You may introduce employee equity arrangements.

    When an LLP May Be Better

    • The business is partner-driven.
    • The founders prefer partnership-style operational flexibility.
    • The business does not currently require an equity-investment structure.
    • The founders want a different compliance framework.

    Lawizer also provides LLP registration services for businesses considering this alternative.

    Which Is Better: Pvt Ltd or LLC?

    “LLC” generally refers to a Limited Liability Company structure used in countries such as the United States. It is not the standard Indian equivalent of a Private Limited Company.

    For an Indian business, the more relevant comparison is usually between a Private Limited Company and an LLP. If the business will operate overseas, local legal and tax rules should be reviewed before selecting an entity.

    What Are the Disadvantages of a Private Limited Company?

    A private company offers useful benefits, but it also creates continuing compliance responsibilities.

    • More statutory compliance than informal business structures.
    • Annual corporate and financial filings.
    • Maintenance of statutory records and registers.
    • Professional accounting, audit and filing costs.
    • Formal procedures for changes in directors and shareholding.
    • Potential additional fees or penalties for missed compliance.

    These obligations may be worthwhile for a startup seeking investment or rapid growth. For a very small business with no plans for external investment, another structure may sometimes be more appropriate.

    How Much Income Tax Does a Pvt Ltd Company Pay?

    Incorporation does not itself create a fixed income-tax payment. The company is taxed on its taxable income under the applicable corporate tax provisions.

    For AY 2026-27, official Income Tax Department guidance lists different rates for domestic companies depending on the applicable regime and eligibility. These can include 22% under Section 115BAA, 25% in specified cases and 30% where the concessional provisions do not apply. Surcharge and health and education cess may also apply.

    The 22% Section 115BAA regime has conditions. A company should therefore evaluate its eligibility before choosing it.

    Company Tax and Founder Tax Are Different

    A company is a separate taxpayer. A founder may have separate tax consequences on salary, remuneration, interest, dividends or capital gains received from the company.

    Therefore, founders should not compare corporate tax with personal income tax by looking at one headline rate.

    Who Pays More Tax: Pvt Ltd or LLP?

    For AY 2026-27, an LLP is generally taxable at 30%, subject to applicable surcharge and cess. A domestic company can fall under different corporate tax regimes.

    This does not automatically mean that one structure is always more tax-efficient. The final outcome depends on profits, deductions, distributions, remuneration, compliance costs and the business model.

    Is GST Mandatory for a Private Limited Company?

    No. Incorporating a Private Limited Company does not automatically mean that GST registration is required.

    GST registration depends on factors such as aggregate turnover, the nature of supplies, the location of the business and situations where registration becomes compulsory under GST law.

    Who Is Eligible for GST Registration?

    Businesses that cross the applicable GST registration threshold may need to register. Certain categories can also require registration under compulsory-registration provisions even when turnover is below a normal threshold.

    Lawizer provides GST registration assistance for businesses that need help with the application and documentation.

    What Is the GST Turnover Threshold?

    The commonly quoted ₹20 lakh threshold should not be treated as a universal rule for every business.

    For many suppliers of services, the threshold is ₹20 lakh, subject to applicable rules. A higher ₹40 lakh threshold can apply to eligible suppliers of goods in specified states. Special-category states and compulsory-registration situations can have different rules.

    The nature of the supply matters. Founders should check the current GST provisions before relying on a threshold exemption.

    Do I Need to Pay GST If Turnover Is Below ₹20 Lakhs?

    Not necessarily. If the applicable threshold has not been crossed and no compulsory-registration provision applies, GST registration may not be required solely because the business is incorporated as a company.

    However, interstate supplies, specified categories of suppliers and other statutory conditions can change the position.

    Can I File GST Without a CA?

    Yes. A taxpayer can apply for GST registration through the GST portal without necessarily appointing a CA for the application.

    Professional assistance can still be useful when the business has complex transactions, multiple registrations, input-tax-credit questions or other compliance issues.

    How Much Does a CA Charge for GST Registration?

    There is no single government-fixed professional fee for GST registration. CA and other professional charges vary according to the provider, location, documentation and complexity.

    Before engaging a professional, ask for a clear breakdown of professional fees and government charges.

    How Much GST Is Applicable on ₹10 Lakhs?

    GST is not calculated from turnover alone. The applicable rate depends on the goods or services supplied and whether those supplies are taxable, exempt or zero-rated.

    For example, if ₹10 lakh represents taxable supplies that are entirely subject to an 18% GST rate and ₹10 lakh is exclusive of GST, the output GST would be ₹1.8 lakh before eligible input tax credit.

    If ₹10 lakh is already GST-inclusive at 18%, the GST component would be approximately ₹1.53 lakh. These are illustrations, not a calculation for every business.

    What Happens After Company Incorporation?

    Receiving the Certificate of Incorporation is the beginning of the company’s compliance journey. Founders should establish systems for accounting, tax, corporate records and statutory filings from the start.

    Important Post-Incorporation Tasks

    • Open and operate the company’s bank account.
    • Complete applicable share-capital formalities.
    • Complete commencement-of-business requirements where applicable.
    • Set up bookkeeping and accounting systems.
    • Apply for GST registration if required.
    • Consider Startup India registration if the business qualifies.
    • Consider MSME/Udyam registration if eligible.
    • Protect the business name and brand through trademark registration.

    Annual Compliance for a Private Company

    Private companies have continuing obligations under company law. These can include maintaining statutory records, holding required meetings, preparing financial statements, obtaining an audit where applicable and filing prescribed ROC forms.

    Companies also need to meet their applicable income-tax and GST obligations.

    Lawizer provides an annual compliance service for Private Limited Companies covering recurring corporate compliance and filing support.

    Frequently Asked Questions About Private Limited Company Registration

    Who Is Eligible for a Private Limited Company?

    Generally, at least two members and two directors are required for an ordinary private company. The company must also satisfy registered-office, name and documentation requirements.

    Can I Register a Pvt Ltd Company by Myself?

    Yes, founders can complete much of the online process themselves. However, certain filings may require professional certification or prescribed involvement. Professional assistance can also reduce documentation and filing errors.

    How Do I Register a Pvt Ltd Company on MCA?

    The process generally involves deciding the company structure, preparing the name and founder details, obtaining required digital signatures, filing the SPICe+ incorporation application, submitting supporting documents, responding to MCA queries if necessary and receiving the Certificate of Incorporation after approval.

    What Are the MCA Name Approval Fees?

    If a proposed name is reserved separately through SPICe+ Part A, MCA guidance specifies a ₹1,000 name-reservation fee. Always verify the current amount on the MCA portal before payment.

    Which Is Better: Pvt Ltd or LLP?

    A Pvt Ltd company is often suitable for startups seeking equity investment and a share-based ownership structure. An LLP may suit partner-driven businesses that prefer a different compliance and management framework.

    Which Is Better: Pvt Ltd or LLC?

    For an Indian business, LLP is generally the more relevant comparison. LLC is primarily a business structure used in jurisdictions such as the United States and has different legal and tax rules.

    What Are the Disadvantages of a Private Limited Company?

    The main disadvantages are higher compliance, annual filings, statutory records, audit requirements where applicable and ongoing accounting or professional costs.

    Who Pays More Tax: Pvt Ltd or LLP?

    There is no universal answer. For AY 2026-27, LLPs are generally taxed at 30%, while domestic companies may fall under different corporate tax regimes. The appropriate structure depends on the business’s circumstances.

    How Much Income Tax Does a Pvt Ltd Company Pay?

    For AY 2026-27, domestic companies can fall under rates such as 22% under Section 115BAA, 25% in specified cases or 30% under applicable general provisions, before surcharge and cess. Eligibility and conditions should be checked before selecting a regime.

    Is GST Mandatory for a Pvt Ltd Company?

    No. Incorporation does not automatically require GST registration. GST depends on turnover, the nature of supplies and other mandatory-registration provisions.

    Can I File GST Without a CA?

    Yes. A taxpayer can generally apply through the GST portal without appointing a CA. Professional help may still be useful for complex registrations and compliance.

    How Much Does a CA Charge for GST Registration?

    There is no universal CA fee. Professional charges vary according to the provider, location, documentation and complexity of the registration.

    Do I Need to Pay GST If Turnover Is Below ₹20 Lakhs?

    Not automatically. If the applicable threshold has not been crossed and no compulsory-registration rule applies, GST registration may not be required. The nature of the business and supplies must also be considered.

    How Much Turnover Is GST-Free?

    There is no single GST-free turnover limit for every business. Common thresholds include ₹20 lakh for many suppliers of services and, where applicable, ₹40 lakh for eligible suppliers of goods in specified states. Exceptions and compulsory-registration rules can apply.

    How Much GST Is Applicable on ₹10 Lakhs?

    The applicable GST depends on the rate for the relevant goods or services. At an illustrative 18% rate on ₹10 lakh of taxable value exclusive of GST, the output tax would be ₹1.8 lakh before eligible input tax credit.

    Ready to Register Your Company?

    Choosing the right legal structure at the beginning can help avoid unnecessary restructuring later. A Private Limited Company can be a strong option for founders who want limited liability, formal shareholding, investor readiness and a structure designed for growth.

    However, incorporation should be considered alongside taxation, GST, intellectual-property protection and ongoing compliance.

    Ready to start? Get assistance with Private Limited Company registration through Lawizer and get support with incorporation, documentation and related business registrations.

    You can also explore Lawizer’s startup and business legal services, annual compliance support, trademark registration and business-law guides as your company grows.

    Disclaimer: Company law, tax and GST rules can change. This article provides general educational information and should not be treated as personalised legal, tax or financial advice. Verify the current requirements applicable to your business before filing.

    Lawizer Private Limited Company Registration

    Lawizer Startup & Business Legal Services

    Lawizer Annual Compliance

  • How to register a trademark in India

    How to register a trademark in India

    Your brand name, logo or tagline can become one of your business’s most valuable assets. But using a brand in the market does not automatically give you the strongest statutory protection available under Indian trademark law. If you are a founder or small-business owner wondering how to register a trademark in India, the process involves more than simply filling out an online form.

    You need to select a distinctive mark, search existing trademarks, identify the correct class of goods or services, prepare the application, respond to any examination objections and monitor the application until registration. This guide explains each stage in clear language, along with the documents, government fees, timelines and common mistakes you should know about.

    The process is governed principally by the Trade Marks Act, 1999 and the Trade Marks Rules, 2017.

    What Is a Trademark in India?

    A trademark is a mark capable of distinguishing the goods or services of one person from those of others. Depending on the circumstances, it can include words, names, logos, symbols, slogans, shapes, colours and other distinctive elements.

    For a business, the important point is that trademark protection is linked to the mark and the goods or services for which it is registered. Registration does not give you ownership over an ordinary word in every possible context.

    For example, the same or similar word may potentially be used by different businesses operating in unrelated fields, depending on the facts and the applicable trademark classes.

    What Can Be Registered as a Trademark?

    • Brand or business names
    • Logos and device marks
    • Taglines and slogans
    • Letters and numbers
    • Distinctive combinations of words, designs or other elements
    • Other marks that satisfy the legal requirements for registration

    What Cannot Be Registered as a Trademark?

    Not every proposed brand is registrable. The Trade Marks Act contains absolute and relative grounds that can prevent registration.

    Problems may arise where a mark is non-distinctive, descriptive in a manner covered by the statutory restrictions, deceptive or likely to cause confusion, prohibited by law, or conflicting with an earlier trademark or other protected right. Sections 9 and 11 of the Act are particularly important when assessing registrability.

    This is why a trademark search should ideally happen before you spend heavily on packaging, advertising, websites or other brand assets.

    Who Can Register a Trademark in India?

    You do not need to incorporate a private limited company before applying for a trademark. Under Section 18 of the Trade Marks Act, a person claiming to be the proprietor of a trademark can apply for registration.

    Depending on the circumstances, applicants can include:

    • Individuals and freelancers
    • Sole proprietors
    • Startups
    • Small enterprises
    • Partnership firms
    • LLPs
    • Private or public companies
    • Other eligible applicants

    If your business is still being set up, it is therefore possible to consider trademark protection separately from your choice of business structure. If you are deciding whether you need a company, LLP or another structure, you can also explore Lawizer’s startup and business legal services.

    How to Register a Trademark in India: Step-by-Step Process

    The registration journey can be understood as a series of stages. The exact experience varies depending on the mark, class, examination objections and whether a third party opposes the application.

    Step 1: Choose a Distinctive Trademark

    Start by deciding exactly what you want to protect. This could be your brand name, logo, tagline or another distinctive element.

    A strong trademark is generally one that can distinguish your goods or services from those of competitors. Avoid choosing a mark solely because it describes what you sell. The more distinctive the mark, the stronger the starting point for registration.

    Also decide whether you need protection for a word mark, a logo or both. A business may ultimately want separate protection for different brand elements.

    Step 2: Conduct a Trademark Search

    Before filing, search the official trademark records to identify identical or deceptively similar marks. The IP India online trademark system provides the relevant government infrastructure for trademark applications and searches.

    Do not limit your search to an exact spelling. Consider:

    • Similar spellings
    • Phonetic similarities
    • Similar-looking marks
    • Existing applications as well as registrations
    • Marks in relevant and potentially related classes

    A search cannot guarantee registration, but it can reveal obvious conflicts before you spend more money building the brand.

    Step 3: Identify the Correct Trademark Class

    India uses the Nice Classification system for goods and services. The classification has 45 classes, with Classes 1–34 covering goods and Classes 35–45 covering services.

    Your application should identify the goods or services for which the mark is being used or proposed to be used. Choosing the wrong class can leave an important part of your business inadequately protected.

    For instance, a software business and a clothing business have very different commercial activities and may require different classes. A business operating across multiple product or service categories may need protection in more than one class.

    Do not select classes simply because another company used them. The correct classification depends on what your business actually offers.

    Step 4: Prepare the Trademark Application Documents

    The documents and information required will depend on the applicant and the nature of the application. Common requirements include:

    • Applicant’s name and address
    • Details identifying the applicant’s legal status
    • A clear representation of the trademark
    • Description of the relevant goods or services
    • Details of the class or classes
    • Information regarding use or proposed use of the mark
    • Supporting documents where a particular claim or applicant category requires them
    • Authorisation documents where an agent or attorney files on behalf of the applicant

    If prior use of the mark is claimed, the Trade Marks Rules require a statement regarding use and an affidavit with supporting documents in the circumstances prescribed by the Rules.

    Step 5: File Form TM-A

    The standard application for registration of a trademark is filed using Form TM-A. The application identifies the applicant, the mark, the relevant goods or services and the applicable class or classes.

    The application can be filed electronically through the IP India system. After filing, the application receives an application number that can be used to monitor its progress.

    For the current official fee schedule, see the IP India Forms and Official Fees page.

    Step 6: Monitor the Application Status

    Filing the application is not the final step. The applicant should monitor the status and communications issued by the Trade Marks Registry.

    The application may move through examination and other procedural stages before it reaches registration. If the Registry raises an objection or requires a response, failing to act within the applicable deadline can seriously affect the application.

    Step 7: Respond to a Trademark Examination Objection

    An examination report may raise objections concerning the registrability of the mark. Common issues include lack of distinctiveness, descriptiveness or similarity with an earlier mark.

    An objection is not the same thing as a final refusal. The applicant can respond with appropriate legal and factual submissions and supporting material. Depending on the case, a hearing may also be required.

    For businesses that receive an examination objection, Lawizer also provides a dedicated trademark registration and objection-support service.

    Step 8: Publication in the Trade Marks Journal

    Once the application reaches the relevant stage of acceptance, it may be advertised in the Trade Marks Journal. Publication provides an opportunity for third parties to oppose registration.

    Under Rule 42 of the Trade Marks Rules, a notice of opposition is generally filed within four months from the date of publication or re-publication of the application in the Trade Marks Journal.

    This is an important distinction: an examination objection comes from the Registry, while an opposition is brought by a third party.

    Step 9: Registration and Trademark Certificate

    If the application completes the relevant stages without a successful opposition preventing registration, the Registrar can enter the mark on the Register and issue the registration certificate in accordance with the Act and Rules.

    Once registered, the proprietor can use the ® symbol in connection with the registered mark. The symbol should not be used as though the mark were registered when it has not actually been registered.

    What Documents Are Required for Trademark Registration?

    There is no single document checklist that applies identically to every applicant. However, a typical application may involve:

    • Applicant identity and contact details
    • Address details
    • Trademark representation, particularly where a logo or device mark is involved
    • Goods or services specification
    • Details of proposed use or prior use
    • Affidavit and supporting evidence where prior use is claimed
    • Startup or small-enterprise documentation where the applicant is claiming the applicable fee category
    • Authorisation documents where filing is through an agent

    Applicants should provide accurate information because inconsistencies between the application and supporting material can create avoidable complications.

    How Much Does Trademark Registration Cost in India?

    The government filing fee depends on the applicant category, filing mode, number of classes and number of marks.

    As reflected in the current official IP India fee schedule, the online filing fee for a standard trademark application is:

    • ₹4,500 per class per mark for an Individual, Startup or Small Enterprise.
    • ₹9,000 per class per mark for other applicants.

    The corresponding physical filing fees are higher: ₹5,000 for an Individual/Startup/Small Enterprise and ₹10,000 for other applicants. These are government fees and are separate from professional or facilitation charges.

    If you file in multiple classes, the government fee applies according to the applicable fee structure for each class and mark. The total cost can therefore vary considerably between businesses.

    For context, Lawizer’s current trademark registration service lists its facilitation fee separately from government charges.

    How Long Does Trademark Registration Take in India?

    There is no single guaranteed timeline for every trademark application. A straightforward application may progress through the Registry without major disputes, while an application facing objections or opposition can take substantially longer.

    The timeline can be affected by:

    • Examination of the application
    • Objections and responses
    • Hearings, where applicable
    • Publication in the Trade Marks Journal
    • Third-party opposition
    • Procedural delays or additional requirements

    Lawizer currently describes the process as involving several stages and notes that an uncontested application can take approximately 6–12 months, while its broader educational material also cautions that contested matters can take longer. Treat any stated timeline as an estimate rather than a guarantee.

    Can You Use the ™ and ® Symbols?

    What Does ™ Mean?

    The ™ symbol is commonly used to indicate that a business is claiming a mark as its trademark. Registration is not required simply to use the symbol.

    When Can You Use ®?

    The ® symbol is associated with a registered trademark. A business should not represent an unregistered mark as registered.

    In practical terms, use ™ while your brand is being claimed as a trademark, and use ® after the relevant mark has actually been registered.

    What Happens If Your Trademark Is Objected To or Opposed?

    Trademark Objection vs Trademark Opposition

    These two terms are often confused.

    • Examination objection: raised by the Trade Marks Registry during examination of the application.
    • Opposition: initiated by a third party after the application is advertised in the Trade Marks Journal.

    An examination objection generally requires a written response addressing the grounds raised by the Examiner. Depending on the matter, the applicant may later be called for a hearing.

    An opposition is a separate proceeding. The applicant may need to file a counterstatement and participate in the subsequent evidentiary and hearing stages. The Rules prescribe specific forms and deadlines for these proceedings.

    If you receive an examination objection, you can review Lawizer’s startup and business legal services or its trademark-related support options before deciding how to proceed.

    Common Trademark Registration Mistakes to Avoid

    Small mistakes at the beginning can create significant problems later. Founders should watch out for these common issues:

    • Skipping the trademark search: A brand may look unique but still conflict with an earlier mark.
    • Choosing a weak mark: Highly descriptive or non-distinctive marks can face registration difficulties.
    • Choosing the wrong class: Registration only protects the mark in relation to the goods or services covered by the registration.
    • Claiming prior use without evidence: A prior-use claim should be supported in accordance with the Rules.
    • Ignoring application status: Important Registry communications can have deadlines.
    • Missing opposition or response deadlines: Trademark proceedings are deadline-driven.
    • Using ® too early: Do not present an unregistered mark as registered.
    • Assuming company registration equals trademark registration: A company name and a trademark are different forms of legal protection.

    Trademark Registration vs Company Registration: What Is the Difference?

    Company registration and trademark registration protect different things.

    • Company registration creates or registers a legal business entity under the applicable corporate framework.
    • Trademark registration protects a distinctive mark used to identify particular goods or services.

    Registering a company does not automatically mean that the company’s brand name is protected as a trademark. Likewise, a trademark can sometimes be owned by an individual or other eligible proprietor without first incorporating a private limited company.

    If you are still deciding on your business structure, Lawizer’s Private Limited Company registration service may be useful alongside its trademark services.

    Why Should Founders Register a Trademark Early?

    A brand often becomes more valuable as a business grows. Marketing, customer recognition, packaging, social media presence and goodwill can all become connected with the same name or logo.

    Filing early can therefore be strategically useful once you have settled on a brand. It can help establish an earlier filing position and reduce the risk of discovering a serious conflict after significant investment in branding.

    However, early filing does not eliminate every possible issue. Prior-user rights and other statutory considerations can remain relevant, so founders should not treat filing as a substitute for a proper clearance search.

    For a broader discussion of brand protection, see Lawizer’s guide on why your brand needs trademark registration in India.

    How to Register a Trademark in India: FAQ

    Can I register a trademark myself in India?

    Yes. An eligible applicant can file a trademark application without necessarily hiring a professional. However, professional assistance can be useful when the search is complex, multiple classes are involved, prior use is claimed, or an objection or opposition arises.

    Can an individual register a trademark in India?

    Yes. Section 18 permits a person claiming to be the proprietor of a trademark to apply for registration. The applicant does not have to be a private limited company.

    Is a trademark search compulsory before filing?

    A preliminary search is an important risk-reduction step, although it should not be confused with a separate mandatory filing document. Searching helps identify earlier marks that may create problems under the Act.

    How many trademark classes do I need?

    That depends on the goods and services your business actually provides or intends to provide. If your business operates across substantially different categories, more than one class may be appropriate.

    Can I register both my brand name and logo?

    Yes, but the protection sought should be planned carefully. A word mark and a logo/device mark are different representations of your brand and may require separate applications depending on what you want protected.

    How long is a registered trademark valid in India?

    A registered trademark is valid for 10 years and can be renewed for successive 10-year periods. Section 25 provides the statutory framework for renewal and restoration.

    Lawizer also provides a trademark renewal service for businesses approaching renewal.

    What happens after I file a trademark application?

    The application is examined by the Trade Marks Registry. Depending on the outcome, it may proceed toward acceptance and Journal publication, or the applicant may need to respond to an objection. After publication, third parties have the prescribed period to oppose the application. If the registration requirements are ultimately satisfied, the mark is entered on the Register.

    What if someone already has a similar trademark?

    Do not assume that changing one letter will solve the problem. Similarity can be assessed by appearance, sound, meaning and the commercial relationship between the relevant goods or services. An earlier mark may therefore affect your application even where the names are not identical.

    What if my trademark application is refused?

    The appropriate response depends on the reason for refusal and the procedural stage. Depending on the circumstances, an applicant may have opportunities to respond, attend a hearing or pursue an available legal remedy. A refusal should therefore be assessed on its specific grounds rather than treated as an automatic end to the matter.

    Final Checklist Before Filing Your Trademark

    • Choose a distinctive brand name or mark.
    • Search existing and pending marks.
    • Identify every relevant goods/services class.
    • Decide whether you need a word mark, logo mark or both.
    • Prepare accurate applicant information.
    • Collect prior-use evidence if claiming prior use.
    • Check whether you qualify for the applicable government fee category.
    • File the correct application and pay the applicable government fee.
    • Track the application after filing.
    • Respond to Registry communications within the applicable deadlines.

    Protect Your Brand With Lawizer

    A trademark can become a long-term business asset, so the filing decision deserves more care than simply choosing a name and submitting a form. A proper search, correct classification and accurate application can reduce avoidable complications later.

    If you want professional assistance with the process, you can explore Lawizer’s trademark registration service. Lawizer also provides support for related startup legal requirements, including company, GST, MSME and other business legal services.

    You can also explore Lawizer’s legal guides and business law blog for practical information on incorporation, compliance, intellectual property and other issues faced by Indian businesses.

    Important: This article is for general information and does not constitute legal advice. Trademark registrability, fees, procedural requirements and outcomes depend on the facts of each application. Always verify the applicable requirements with the Trade Marks Registry or a qualified professional before filing.

  • Trademark Renewal Process in India

    Trademark Renewal Process in India

    Building a strong brand takes time, money and consistent effort. Once your trademark is registered, keeping that protection active is equally important. The trademark renewal process allows a registered trademark to continue beyond its initial 10-year registration period.

    In India, a registered trademark is generally valid for 10 years and can be renewed for further 10-year periods. Businesses should therefore keep track of their trademark expiry dates and complete renewal within the prescribed period.

    Missing the deadline does not always mean that the trademark is permanently lost. However, renewal after expiry can involve an additional surcharge, while a trademark already removed from the Register may require restoration and renewal.

    This guide explains the trademark renewal process in India, including the renewal timeline, Form TM-R, government fees, renewal after expiry, restoration, self-filing and common mistakes that businesses should avoid.

    What Is Trademark Renewal?

    Trademark renewal is the process of extending an existing trademark registration for another period. Section 25 of the Trade Marks Act, 1999 provides for a 10-year registration period and allows the registration to be renewed from time to time.

    Renewal is different from applying for a trademark for the first time. During registration, the applicant seeks protection for a mark that has not yet been registered. During renewal, the proprietor maintains an existing registered trademark.

    This distinction is important for businesses because a registered brand can become a valuable intellectual property asset. The proprietor should therefore keep track of the registration’s expiry date instead of assuming that protection continues automatically.

    A registered trademark can generally be renewed repeatedly for further 10-year periods, subject to the applicable legal requirements and prescribed fees.

    If you have not registered your brand yet, you can first understand how trademark registration works in India before considering renewal.

    How Long Is a Trademark Valid in India?

    A registered trademark in India is generally valid for 10 years. Section 25 of the Trade Marks Act, 1999 provides for renewal for another 10 years from the expiry of the original registration or the last renewal.

    There is no fixed maximum number of renewals. A trademark can therefore continue to be renewed repeatedly as long as the proprietor complies with the applicable requirements.

    For example, once the initial 10-year registration period approaches its expiry, the proprietor can apply for renewal and extend the registration for another 10-year period.

    The same process can be repeated in subsequent 10-year periods.

    This is particularly important for established businesses. A brand name may become one of a company’s most valuable intangible assets over time. Allowing its registration to lapse unnecessarily can create avoidable legal and commercial risks.

    Do You Need to Renew Your Trademark Every Year?

    No. Trademark registration does not have to be renewed every year.

    A registered trademark is generally valid for 10 years. Renewal is required when that registration period approaches its expiry and the proprietor wants to continue the registration.

    However, businesses should review their trademark portfolio regularly. Checking expiry dates as part of an annual compliance review can help prevent a missed renewal deadline.

    For a company with several brands, it is useful to maintain a simple intellectual property register containing each trademark’s registration number, class, proprietor and renewal date.

    When Should You Start the Trademark Renewal Process?

    Under Rule 57 of the Trade Marks Rules, 2017, an application for renewal can be made in Form TM-R at any time not more than one year before the expiration of the last registration.

    This means that businesses do not have to wait until the final weeks before expiry. Starting early gives the proprietor time to check the registration details and complete the filing correctly.

    The safest approach is to identify the renewal date well in advance and begin preparing during the permitted renewal window.

    What Happens If You Miss the Trademark Renewal Date?

    Missing the expiry date does not necessarily mean that the trademark can never be renewed.

    Section 25 of the Trade Marks Act and the applicable Rules provide mechanisms for renewal after expiry and restoration in specified circumstances.

    Where the required application and surcharge are filed within six months from expiry, the law provides a route for renewal with the applicable surcharge.

    If the mark has already been removed from the Register, restoration and renewal may be available within one year from the expiration of the last registration, subject to the statutory requirements and the Registrar’s consideration.

    Because the procedure becomes more complicated after expiry, completing the renewal before the registration expires is generally preferable.

    Trademark Renewal Process in India: Step-by-Step

    The trademark renewal process is easier to manage when the registration details are accurate and the application is filed within the permitted period.

    Step 1: Check Your Trademark Registration Details

    Start by identifying the trademark registration that needs renewal.

    Check the following details:

    • Trademark registration number
    • Proprietor’s name
    • Registered class or classes
    • Date of registration
    • Expiry date
    • Current trademark status

    If your business owns several trademarks, check each registration separately. Different registrations may have different expiry dates and classes.

    You can use the official IP India trademark search and status system to review relevant trademark information.

    Step 2: Verify the Proprietor Details

    Before filing the renewal application, check whether the proprietor’s name and other registration details are accurate.

    If the business has undergone an assignment, transfer, merger, name change or another relevant change, do not assume that renewal itself will automatically update the trademark record.

    Depending on the circumstances, a separate filing may be necessary. Reviewing the record before renewal can therefore help identify issues before the application is filed.

    Step 3: Check the Registered Class or Classes

    Trademark rights are connected with the goods or services covered by the registration. Therefore, check the class or classes in which your trademark is registered.

    If the same brand is registered in several classes, renewal fees generally apply for each class.

    Businesses should also distinguish renewal from expansion into a new class. If you have started offering a completely different category of goods or services, simply renewing the existing registration may not provide protection for that new category.

    If you are considering protecting a new brand or expanding your trademark portfolio, explore Lawizer’s trademark registration service.

    Step 4: Prepare Form TM-R

    The prescribed form for trademark renewal is Form TM-R.

    Form TM-R covers applications relating to renewal and restoration of trademark registration, including payment of the applicable surcharge where relevant.

    The proprietor or authorised person should provide the required information accurately and select the appropriate filing category.

    You can review the official Form TM-R issued by IP India before filing.

    Step 5: Pay the Applicable Government Fee

    The applicable government fee depends on the type of renewal and filing method.

    For ordinary renewal under Section 25, the current official fee is:

    • ₹9,000 per class for e-filing.
    • ₹10,000 per class for physical filing.

    If the application is being made after expiry, the prescribed surcharge is additional to the renewal fee. Restoration and renewal also involve an additional prescribed fee.

    Always check the current IP India trademark fee schedule before making payment because official fees and procedures can be updated.

    Step 6: Submit the Renewal Application

    After checking the details and paying the applicable fee, submit Form TM-R through the prescribed filing system.

    Keep the filing acknowledgement and payment details safely. These records can help demonstrate when the renewal application was filed and can make future compliance easier.

    Step 7: Track the Trademark Status

    Filing the application is not the same as completing the entire process.

    Keep track of the trademark record and any communication from the Trade Marks Registry. If the Registry raises an issue or requires further action, responding appropriately can help prevent unnecessary complications.

    The official IP India trademark status system can be used to monitor relevant information.

    Once the renewal is processed, maintain the updated records with the company’s intellectual property documents.

    Can I Renew My Trademark Myself?

    Yes. A trademark proprietor can generally undertake the renewal filing themselves.

    For a straightforward renewal where the trademark is active, the proprietor’s details are correct and the application is being filed within the permitted period, self-filing may be practical.

    However, professional assistance can be useful where the trademark has expired, has been removed from the Register or involves ownership and record-related complications.

    When Should You Consider Professional Assistance?

    Professional assistance may be particularly useful when:

    • The trademark registration has already expired.
    • The trademark has been removed from the Register.
    • The matter requires restoration and renewal.
    • There has been an assignment or ownership change.
    • The proprietor’s details need to be changed or corrected.
    • The business owns multiple registrations or classes.
    • You are unsure which renewal option applies.
    • There is correspondence or an issue pending before the Trade Marks Registry.

    How Much Does It Cost to Renew a Trademark?

    Trademark renewal fees are prescribed by the Trade Marks Rules and the applicable official fee schedule.

    For a standard renewal under Section 25, the current official fee is:

    • ₹9,000 per class for e-filing
    • ₹10,000 per class for physical filing

    These are government fees. If you use a professional service, the service provider may charge a separate professional or facilitation fee.

    What If You Renew Your Trademark After Expiry?

    If the renewal is filed within six months after expiry, the applicable renewal fee is accompanied by the prescribed surcharge.

    The current official fee schedule provides a surcharge of:

    • ₹4,500 per class for e-filing
    • ₹5,000 per class for physical filing

    This is in addition to the applicable renewal fee.

    Therefore, delaying renewal can increase the overall cost.

    What If the Trademark Has Been Removed?

    Where restoration and renewal are sought after removal, an additional restoration-related fee applies.

    The current fee schedule provides a restoration and renewal fee of ₹9,000 for e-filing or ₹10,000 for physical filing per class, in addition to the applicable renewal fee.

    Because fees and filing requirements can change, always verify the amount on the current IP India official fees page before making payment.

    How Long Does the Trademark Renewal Process Take?

    There is no single guaranteed processing time that applies to every trademark renewal.

    The time involved can depend on:

    • Completeness of the application
    • Accuracy of the information provided
    • Payment of the correct fee
    • Registry processing
    • Any discrepancy in the records
    • Whether additional action is required

    A straightforward renewal filed within the permitted period is generally less complicated than a matter involving expiry, restoration, ownership changes or other issues.

    For this reason, businesses should avoid planning their compliance around a last-minute filing.

    The important deadline is the statutory expiry date, not an estimated processing date.

    What Happens If You Do Not Renew Your Trademark?

    If the prescribed renewal requirements are not completed, the Registrar may remove the trademark from the Register in accordance with Section 25.

    The Trade Marks Rules also provide procedures relating to removal and publication of the fact of removal, subject to the applicable statutory provisions.

    This is why allowing a registration to lapse can create unnecessary legal and administrative complications.

    A business may also have to consider additional fees and restoration procedures if it does not act within the relevant post-expiry period.

    Can You Restore an Expired Trademark?

    There are different situations to distinguish.

    First, a proprietor may seek renewal after expiry within the applicable six-month period by paying the renewal fee and prescribed surcharge.

    Second, where the trademark has been removed from the Register for non-payment, Section 25(4) provides for restoration and renewal after six months and within one year from the expiration of the last registration, subject to the statutory conditions.

    Rule 60 further provides for an application for restoration and renewal in Form TM-R within one year from the expiration of the registration, along with the prescribed fee.

    The Registrar must also consider the interests of other affected persons.

    Because restoration involves additional statutory requirements, businesses should not treat it as an equivalent substitute for timely renewal.

    Trademark Renewal vs Trademark Registration

    Renewal and registration are related but different legal processes.

    • Trademark registration: The initial process of seeking registration of a brand name, logo, symbol or another eligible mark.
    • Trademark renewal: The process of extending an existing registered trademark for another 10-year period.
    • Trademark restoration: A mechanism that may apply when a trademark has been removed from the Register for failure to renew within the applicable period.

    If you are researching the initial registration stage, Lawizer’s trademark registration guide for founders explains the broader registration journey.

    Common Mistakes to Avoid During Trademark Renewal

    1. Assuming Renewal Is Annual

    A registered trademark generally has a 10-year term.

    However, businesses should still review their trademark portfolio regularly so that expiry dates are not forgotten.

    2. Waiting Until After Expiry

    Post-expiry renewal can involve an additional surcharge.

    Waiting longer can also create restoration issues. Early action is therefore preferable.

    3. Checking Only the Brand Name

    Do not rely only on the spelling of the brand.

    Check the registration number, proprietor, class and other relevant particulars before filing.

    4. Ignoring Multiple Classes

    If your brand is registered in multiple classes, make sure the renewal covers the registrations that actually require renewal.

    Fees may apply separately to each class.

    5. Assuming Renewal Updates Ownership

    Renewal does not automatically resolve every ownership or record-related issue.

    If there has been an assignment or another change, the appropriate separate procedure may need to be followed.

    6. Forgetting to Maintain Records

    Keep the filing acknowledgement, payment details and updated trademark records together.

    This makes future renewals easier to manage.

    Trademark Renewal Checklist for Indian Businesses

    Before starting the renewal, check the following:

    • Trademark registration number
    • Expiry date
    • Proprietor’s name and details
    • Registered class or classes
    • Current trademark status
    • Any pending ownership or record changes
    • Whether the renewal is being filed before or after expiry
    • Correct Form TM-R
    • Current government fee
    • Filing acknowledgement
    • Payment receipt
    • Application status

    Once the renewal is completed, record the next renewal date in your business compliance calendar.

    Why Timely Trademark Renewal Matters for Founders

    A trademark is more than a registration number.

    For many businesses, it represents the name customers recognise, the reputation the company has built and the goodwill associated with its products or services.

    Keeping the registration active helps preserve the statutory rights associated with the registered mark.

    Section 28 of the Trade Marks Act provides, subject to the Act and applicable conditions, that registration gives the registered proprietor exclusive rights to use the trademark in relation to the registered goods or services and to seek relief for infringement.

    That makes trademark renewal an important part of long-term brand management.

    Founders should therefore treat trademark expiry dates as part of their intellectual property compliance calendar rather than as a task to remember only once every decade.

    Frequently Asked Questions About Trademark Renewal

    Can I renew my trademark myself?

    Yes. A proprietor can file the renewal application themselves.

    The process generally involves checking the registration, completing Form TM-R and paying the applicable government fee.

    Professional assistance may be useful for expired registrations, restoration or complicated record issues.

    How much does it cost to renew a trademark?

    The current official fee for ordinary renewal is ₹9,000 per class for e-filing and ₹10,000 per class for physical filing.

    Additional surcharge or restoration fees may apply where renewal is delayed or restoration is required.

    How long does it take to renew a trademark?

    There is no single guaranteed processing period for every case.

    A straightforward application may be simpler to process than a matter involving expiry, restoration, ownership changes or other issues.

    Businesses should therefore file well before the deadline.

    Do I need to renew my trademark every year?

    No.

    A registered trademark is generally valid for 10 years and can be renewed for further 10-year periods.

    Businesses should nevertheless monitor their portfolio regularly so that the renewal date is not missed.

    What happens if I miss my trademark renewal date?

    If the renewal deadline is missed, the law provides a limited post-expiry route involving the renewal fee and prescribed surcharge.

    If the mark has been removed from the Register, restoration and renewal may be available within the statutory period, subject to the applicable requirements.

    Can I renew my trademark after it expires?

    Yes, in specified circumstances.

    Section 25 and Rule 59 provide a route for renewal with surcharge where the required application is made within six months from expiry.

    If the mark has been removed, restoration and renewal may be sought within one year from expiry under the applicable provisions.

    How early can I renew my trademark?

    Under Rule 57 of the Trade Marks Rules, 2017, an application for renewal may be made at any time not more than one year before the expiration of the last registration.

    Which form is used for trademark renewal?

    Trademark renewal is filed using Form TM-R.

    The form also covers renewal after expiry and restoration and renewal, depending on the circumstances.

    Related Lawizer Resources

    If you are managing your brand’s wider legal protection, these Lawizer resources may also help:

    Keep Your Brand Protection Active

    The trademark renewal process is a recurring legal requirement that should not be overlooked simply because the renewal date may be many years apart.

    For most businesses, the safest approach is simple: know your expiry date, verify your registration details, file the appropriate Form TM-R, pay the correct fee and keep the renewal records safely.

    If your trademark has already expired, has been removed from the Register or has complicated ownership or record issues, the appropriate procedure may be different.

    In such cases, getting professional guidance can help you understand the available options.

    Need help with your trademark renewal? Lawizer can assist businesses with trademark-related legal processes and help you understand the appropriate next step for maintaining your brand protection.

    Explore Lawizer’s trademark services or visit Lawizer to explore legal services for startups and growing businesses.

    Disclaimer: This article is for general informational purposes and does not constitute legal advice. Trademark fees, forms, procedures and Registry requirements may change. Always verify the latest requirements and fees on the official IP India website before filing.

  • Trademark vs Copyright vs Patent

    Trademark vs Copyright vs Patent

    Trademark vs Copyright vs Patent: Key Differences

    Trademark vs copyright vs patent is an important distinction for Indian founders and small-business owners who want to protect their brand, creative work, product design or invention. Although all three are forms of intellectual property protection, they protect different kinds of assets and give different legal rights.

    A trademark generally protects a distinctive sign used to identify and distinguish goods or services. Copyright protects original creative expression, such as writing, artwork, music, films and computer programs. A patent protects a qualifying invention that satisfies the legal requirements for patentability.

    Understanding the difference before launching a product, building a brand or publicly disclosing an invention can help a business choose the right protection. In some cases, one business may need more than one form of intellectual property protection.

    Trademark vs Copyright vs Patent: What Is the Difference?

    The simplest way to understand the difference is to ask what exactly you are trying to protect.

    • Trademark: Protects distinctive signs that identify and distinguish goods or services.
    • Copyright: Protects original creative expression in qualifying works.
    • Patent: Protects qualifying inventions that meet the requirements of patent law.

    For example, if a startup creates a new brand name, the name may be considered for trademark protection. Its website articles, photographs, videos and original software may be protected by copyright if the statutory requirements are met. If the startup develops a genuinely new technical invention that satisfies patentability requirements, patent protection may also be relevant.

    These rights are not interchangeable. The appropriate protection depends on the nature of the intellectual property, how it is used and the legal requirements applicable to it.

    Trademark vs Copyright vs Patent in India

    In India, trademarks are primarily governed by the Trade Marks Act, 1999. Copyright is governed by the Copyright Act, 1957, while patents are governed by the Patents Act, 1970.

    The official IP India patent guidance explains the basic principles of patent protection. The official IP India trademark guidance provides information on trademarks and their renewal. For copyright matters, businesses can refer to the official Copyright Office website.

    While these laws all fall within the broader field of intellectual property, their objectives are different. A trademark is closely connected with commercial source identification. Copyright is concerned with original expression. Patent law is concerned with qualifying inventions and the temporary exclusive rights granted to their owners.

    What Does a Trademark Protect?

    A trademark helps distinguish the goods or services of one business from those of another. Depending on the circumstances and applicable law, a trademark can include a word, name, logo, symbol, slogan, shape or other distinctive sign.

    For a business, a trademark is closely connected to brand identity. Customers may recognise a company through its name, logo, tagline or other distinctive branding.

    Examples of Assets That May Need Trademark Protection

    • Business or brand names
    • Logos and distinctive symbols
    • Slogans and taglines
    • Distinctive marks used in relation to goods or services

    Trademark protection is connected to the goods or services for which the mark is registered. Choosing the appropriate class and describing the goods or services carefully are therefore important parts of a trademark application.

    If you are preparing to launch a new brand, consider conducting a trademark search before investing heavily in packaging, advertising, websites and other brand assets.

    Lawizer provides trademark registration services for businesses and founders looking to protect their brand identity.

    What Does Copyright Protect?

    Copyright protects original expression rather than an idea by itself. Under the Copyright Act, 1957, copyright can apply to original literary, dramatic, musical and artistic works, as well as cinematograph films and sound recordings.

    The Copyright Office also recognises computer programs within the statutory category of literary works. This can be particularly relevant to technology businesses, software developers, agencies and digital businesses.

    What Are Three Things That Can Be Copyrighted?

    There are many categories of copyrightable works. Three straightforward examples are:

    • Written content: Articles, books, reports and other original literary works.
    • Visual works: Original artwork, photographs, drawings and other artistic works.
    • Software: Computer programs and source code can qualify for copyright protection as literary works.

    Other examples include music, films and sound recordings, subject to the requirements of the Copyright Act.

    Copyright protection generally arises automatically when an original work is created. Registration is not a prerequisite for copyright to exist. However, registration can create an official record and may provide useful evidence in disputes concerning ownership.

    You can learn more about copyright registration through Lawizer.

    What Does a Patent Protect?

    A patent protects a qualifying invention. Under Indian patent law, an invention generally needs to satisfy requirements such as novelty, inventive step and industrial applicability, while also falling within patentable subject matter under the Patents Act.

    IP India describes a patent as an exclusive right granted for an invention. In India, the term of a patent is generally twenty years from the date of filing, subject to the provisions of the Patents Act and applicable renewal requirements.

    Examples of Things That May Be Considered for Patent Protection

    • A new technical product
    • A qualifying new manufacturing process
    • A technical improvement that satisfies patentability requirements
    • A technological solution to a technical problem

    Not every new idea qualifies for a patent. Patentability has to be assessed against the statutory requirements and exclusions under Indian patent law.

    Founders should also be careful about publicly disclosing a potentially patentable invention before obtaining appropriate advice. The timing of disclosure can be important to patent strategy.

    Trademark vs Copyright vs Patent: Comparison Table

    Feature Trademark Copyright Patent
    Main purpose Protects brand identifiers Protects original creative expression Protects qualifying inventions
    Typical examples Brand name, logo, slogan Writing, artwork, music, films, software New product or technical process
    Registration Registration provides statutory trademark rights Copyright exists automatically; registration is available Patent rights arise through the statutory grant process
    Indian law Trade Marks Act, 1999 Copyright Act, 1957 Patents Act, 1970
    General duration 10 years per registration period, renewable Varies according to the type of work Generally 20 years from filing
    Best suited for Brand identity Creative content and expression Qualifying technical inventions

    The exact scope and duration of protection can depend on the asset and applicable statutory provisions. The table is therefore a practical overview rather than a substitute for legal advice.

    Is Coca-Cola a Trademark or Copyright?

    A brand such as Coca-Cola illustrates why different intellectual property rights should not be confused.

    The brand name and distinctive branding are primarily relevant to trademark protection. At the same time, particular creative materials associated with a brand, such as original advertising artwork, photographs or videos, may attract copyright protection if the statutory requirements are satisfied.

    This means that one business can have several forms of intellectual property protection covering different assets. The trademark does not automatically protect every creative work produced by the business.

    What Is the Most Famous Trademark?

    There is no single legally defined “most famous trademark”. Many international and Indian businesses have highly recognisable marks.

    For a founder, however, fame is not the main issue. A more important question is whether the proposed mark is distinctive, available for registration and appropriate for the goods or services you provide.

    A strong trademark strategy begins before a brand becomes widely known. Searching for conflicting marks before filing can help identify potential problems at an early stage.

    Is McDonald’s a Registered Trademark?

    McDonald’s is a globally recognised brand and its name and other brand elements are associated with trademark protection in multiple jurisdictions.

    However, trademark protection is jurisdiction-specific. A business should not assume that a mark is protected everywhere simply because it is famous internationally. Registration details, classes and rights can differ between countries.

    For an Indian business, the relevant question is whether the proposed mark is protected or available under Indian trademark law and in the relevant classes.

    Do I Need Copyright If I Have a Trademark?

    Possibly. Trademark and copyright protect different things.

    Suppose a startup creates a logo. The logo may have relevance under both trademark and copyright law, depending on the circumstances. Trademark protection can help protect the logo as a brand identifier, while copyright may protect qualifying original artistic expression in the logo.

    Similarly, a business name may be relevant to trademark law, while the website articles, photographs, illustrations and software created by the business may raise separate copyright issues.

    Therefore, having a trademark does not automatically protect all of the company’s creative content.

    Can Someone Steal My Logo If It Is Not Trademarked?

    Trademark registration is not the only legal issue that can arise when someone copies a logo. Depending on the facts, a logo may also involve copyright, passing off or other legal rights.

    However, failing to register a valuable brand asset can make enforcement more complicated. Trademark registration can provide statutory rights and evidence of the registered proprietor’s rights.

    Before launching an important brand, businesses should consider both trademark availability and ownership of the underlying creative work.

    Which Is Cheaper: Trademark or Copyright?

    There is no single answer because costs depend on the type of protection, applicant category, number of classes or works and other factors.

    Copyright protection itself does not require registration to come into existence. A business may nevertheless choose to register important works for evidentiary and commercial reasons.

    Trademark registration involves an application and prescribed government fees. Professional service fees may also apply if an applicant uses a lawyer, agent or legal service provider.

    Instead of choosing purely on price, founders should first identify the asset they are trying to protect. The least expensive option is not necessarily the appropriate form of protection.

    How Do You File for Copyright in India?

    Copyright registration applications can be submitted through the prescribed process of the Copyright Office. The Copyright Office provides online filing facilities and requires applicants to provide relevant application details and supporting material.

    For example, a computer program has specific requirements concerning the work submitted for registration. The Copyright Office provides guidance for registration of computer programs as literary works.

    The process broadly involves:

    • Identifying the work and the relevant category.
    • Preparing the prescribed application.
    • Providing the required details and supporting documents.
    • Paying the applicable statutory fee.
    • Responding to any objection or procedural issue, if applicable.

    For current forms, procedures and fees, applicants should verify the latest information on the official Copyright Office website.

    How Much Does It Cost to Get a Trademark?

    Trademark registration costs are not identical for every applicant. Government fees depend on factors such as the applicant category and number of classes involved.

    Professional service fees may also apply if an applicant engages an attorney, agent or legal service provider.

    Because government fees and procedures can change, founders should verify the current fee schedule before filing. Lawizer’s trademark registration service can assist with the filing process and related documentation.

    Can You Lose Copyright If You Do Not Protect It?

    Copyright does not generally disappear simply because the owner has not registered the work. Under Indian law, copyright protection arises automatically when an original work satisfies the statutory requirements.

    However, failing to document ownership can create practical difficulties when a dispute arises. Businesses should maintain records showing when works were created, who created them and how ownership was transferred or assigned.

    For businesses working with employees, freelancers, designers or agencies, written agreements can also be important for establishing ownership and permitted use of intellectual property.

    What Are Three Things Not Protected by Copyright?

    Copyright protects expression, not every form of information or idea. Examples of material that generally falls outside copyright protection include:

    • Ideas by themselves: A general idea or concept is not the same as protected expression.
    • Methods or procedures: Copyright does not ordinarily give a monopoly over a method of operation.
    • Short names and titles by themselves: A short name or phrase may not qualify for copyright protection merely because it is written down.

    The Copyright Office explains that copyright does not protect ideas, procedures, methods of operation or mathematical concepts as such. Other forms of intellectual property protection may sometimes be relevant depending on the circumstances.

    What Are Five Things That Can Be Copyrighted?

    Five common examples of works that may qualify for copyright protection in India are:

    • Original articles and written content
    • Original photographs and artwork
    • Music and musical works
    • Films and videos
    • Computer programs and software code

    Copyright protection depends on the statutory requirements and the nature of the particular work. Simply putting information into a document does not automatically make every element of that document copyrightable.

    Can You Protect the Same Business Asset With More Than One IP Right?

    Yes. Intellectual property rights can overlap in some situations.

    Consider a technology startup that develops a smart device. Its brand name may be protected through trademark law. Original website content, photographs and software code may be protected by copyright. A qualifying technical invention may be considered for patent protection. The visual appearance of a product may also raise industrial design considerations.

    The key point is that intellectual property protection should be asset-specific. Instead of asking which single registration protects the entire business, founders should identify each important asset and consider the legal protection that may apply.

    Which IP Protection Does Your Business Need?

    • Brand name or logo – Trademark
    • Article, artwork, video or software – Copyright
    • New technical invention – Patent
    • Multiple assets – More than one IP right may apply

    This simple framework can help founders begin an intellectual property audit. The correct protection may depend on the asset, how it is used, whether it has already been disclosed and the commercial objectives of the business.

    How Should a Startup Protect Its Intellectual Property?

    IP protection should not begin only when a dispute arises. Founders can take practical steps from the early stages of the business.

    1. Identify Your IP Assets

    Make a list of your brand names, logos, content, software, designs, inventions, domain names and confidential information.

    This helps you identify which assets may need registration and which require contractual or confidentiality protection.

    2. Keep Ownership Clear

    If founders, employees or freelancers create intellectual property, ownership should be documented appropriately.

    Businesses should avoid assuming that paying a freelancer automatically resolves every ownership issue. Written agreements should clearly address ownership, licences, permitted use and delivery of source files where relevant.

    3. Search Before You File

    For trademarks and patents, searches can help identify existing rights and potential conflicts before substantial money is spent on a filing or product launch.

    4. Avoid Unnecessary Public Disclosure

    If an invention may be patentable, founders should obtain appropriate advice before publicly disclosing technical details. Patent strategy can be affected by what has already been made public.

    5. Maintain Evidence

    Keep dated drafts, source files, invoices, contracts, development records and other evidence showing how and when intellectual property was created and who owns it.

    Trademark vs Copyright vs Patent: Which One Should You Choose?

    There is no universal answer. The right choice depends on what your business has created.

    If your primary asset is a brand identity, trademark protection is likely to be important. If your business creates original content, artwork, photographs, music, films or software, copyright may be relevant. If your business has developed a new technical invention, patent protection may need to be considered.

    Many businesses need a combination rather than just one form of protection.

    For example, a software startup may need trademark protection for its product name, copyright protection for its source code and website content, and potentially patent advice if it has developed a patentable technical invention.

    Frequently Asked Questions

    Is trademark the same as copyright?

    No. A trademark protects a distinctive identifier used to distinguish goods or services, while copyright protects qualifying original creative expression.

    Is a patent the same as a trademark?

    No. A patent protects qualifying inventions. A trademark protects distinctive signs associated with goods or services.

    Is copyright automatic in India?

    Generally, yes. Copyright protection arises automatically when an original work satisfies the statutory requirements. Registration is available but is not a prerequisite for copyright to exist.

    Do I need to register my trademark?

    If you want the statutory benefits associated with registered trademark rights, registration is important. Unregistered marks may have other legal protection in appropriate circumstances, but the nature of those rights differs from registered trademark protection.

    Can software be copyrighted in India?

    Yes. Computer programs are included within the definition of literary work under the Copyright Act, 1957. The Copyright Office provides a registration route for computer programs.

    Can an idea be copyrighted?

    Copyright generally protects the expression of an idea, not the idea itself. Other forms of intellectual property protection may be relevant depending on the nature of the idea and the circumstances.

    Can one product have trademark, copyright and patent protection?

    Yes, potentially. Different aspects of the same product or business can qualify for different forms of intellectual property protection.

    Which is better for a startup: trademark, copyright or patent?

    It depends on the startup’s assets. A brand-focused business may prioritise trademark protection. A content or software business may need copyright protection. A technology business developing a qualifying invention may need patent advice as well.

    Protect Your Business With the Right IP Strategy

    Understanding trademark vs copyright vs patent is the first step. The next step is identifying which intellectual property assets matter most to your business and choosing protection accordingly.

    Lawizer can assist founders and businesses with intellectual property-related services, including trademark registration and copyright registration.

    You can also read Lawizer’s guide on trademark registration in India, including cost, process and timeline and its guide to filing a trademark objection reply in India.

    If your business is unsure whether it needs trademark, copyright, patent or a combination of protections, getting advice at an early stage can help prevent avoidable disputes and protect valuable business assets.

    Need help protecting your intellectual property? Consult Lawizer for practical legal support tailored to your business.

  • How to Protect Your Brand Name in India

    How to Protect Your Brand Name in India

    How to protect your brand name is an important question for every founder, business owner and creator building a long-term business in India. Your brand name may become one of your most valuable business assets. It helps customers identify your products or services and distinguishes your business from competitors.

    However, simply choosing a name, registering a domain or incorporating a company does not automatically give you comprehensive trademark protection. If another business adopts a similar name, you may face customer confusion, marketplace disputes or costly legal proceedings.

    The most practical way to protect a distinctive brand name in India is to consider trademark protection early. A proper search, correctly chosen trademark class, timely filing and continued monitoring can significantly reduce the risk of disputes.

    Why Should You Protect Your Brand Name?

    A brand name is more than a marketing asset. Over time, customers may associate the name with the quality, reputation and goodwill of your business. If another business uses a confusingly similar name, your customers may mistake one business for the other.

    Trademark law provides a framework for protecting distinctive marks used in connection with goods and services. The main legislation is the Trade Marks Act, 1999.

    Registering a trademark can provide important legal advantages, including stronger rights against infringement and clearer evidence of ownership.

    Before investing heavily in packaging, advertising, social media campaigns or a website, it is therefore sensible to determine whether the proposed brand name is available for protection.

    How to Protect Your Brand Name Before Launching

    Brand protection should ideally begin before you spend significant money building the brand. A basic pre-launch process can help you identify potential problems early.

    1. Choose a Distinctive Brand Name

    A strong brand name should be capable of distinguishing your goods or services from those of other businesses. Highly descriptive or generic terms can be difficult to protect as trademarks.

    For example, a highly distinctive coined word may generally have stronger trademark potential than a name that merely describes the product or service.

    When developing a name, consider:

    • Whether the name is distinctive.
    • Whether it is easy to remember and pronounce.
    • Whether similar names already exist in your industry.
    • Whether the name has unwanted meanings in important markets.
    • Whether the corresponding domain and social media handles are reasonably available.
    • Whether you intend to expand into additional products or services.

    Choosing a distinctive name at the beginning is usually easier than changing your brand after customers have already become familiar with it.

    2. Search Existing Trademarks

    One of the most important steps in protecting a new brand is conducting a trademark search before filing an application.

    The official IP India website provides a trademark search facility through which applicants can investigate existing marks.

    Do not search only for an exact spelling. A proper preliminary review should also consider marks that may be visually, phonetically or conceptually similar, particularly when they cover related goods or services.

    This is important because a brand name can face problems even when it is not identical to an existing trademark.

    Does Registering a Company Name Protect Your Brand?

    No. Company registration and trademark registration are separate forms of legal protection.

    For example, registering a company with a particular name through the Ministry of Corporate Affairs does not automatically give you exclusive trademark rights over the brand name for your products or services.

    This distinction is often misunderstood by new entrepreneurs.

    A company name primarily identifies the legal entity. A trademark identifies the source of particular goods or services and protects the brand used in commerce.

    Lawizer also explains this distinction in its guide on Private Limited Company Registration in India.

    If you are incorporating a business and have already selected your brand, consider checking trademark availability as part of the same early-stage legal process.

    How to Protect Your Brand Name Through Trademark Registration

    Trademark registration is one of the most important legal steps for businesses that want to establish stronger protection for their brand identity.

    The Trade Marks Registry administers trademark registration under the Trade Marks Act, 1999 and the Trade Marks Rules, 2017. The Registry maintains the Register of Trade Marks and examines applications that meet the legal requirements.

    You can review the official Trade Marks Act and related resources on the IP India website.

    Step 1: Conduct a Trademark Search

    Start by searching the proposed brand name and relevant similar marks.

    The search should be considered alongside the goods or services for which you intend to use the name. Trademark protection is connected to the goods or services covered by the registration.

    A name that appears available in one area may create problems in another if a similar mark already exists for related goods or services.

    Step 2: Identify the Correct Trademark Class

    Trademark applications are filed in relation to specific goods or services. India follows the international classification system for goods and services.

    Choosing the correct class is therefore an important part of the application.

    For example, a business selling clothing and a business providing software services may require protection in different classes. A business operating across multiple categories may need to consider more than one class.

    Do not select a class solely because another business has used it. The correct classification depends on the actual goods or services connected with your brand.

    Step 3: File the Trademark Application

    Once the name and applicable class or classes have been considered, a trademark application can be filed with the Trade Marks Registry.

    Trademark applications are generally filed using Form TM-A. The application contains information such as the applicant’s details, the mark and the goods or services covered by the application.

    The official IP India fee schedule currently lists different government filing fees depending on the applicant category. For e-filing, the listed fee is ₹4,500 per mark per class for individuals, startups and small enterprises, and ₹9,000 per mark per class for other applicants. Fees can change, so applicants should verify the current official trademark fees before filing.

    Lawizer’s Trademark Registration service separately lists its facilitation charges, with government charges additional.

    Step 4: Respond to Examination

    After filing, the application is examined by the Trade Marks Registry.

    An examiner may raise objections if the mark does not satisfy the legal requirements or if there are concerns relating to existing marks. Common issues may involve distinctiveness or similarity with an earlier mark.

    An objection does not necessarily mean that your trademark application has failed. The applicant may have an opportunity to respond to the examination report within the prescribed period and may also be required to attend a hearing.

    If your application receives an objection, Lawizer provides a dedicated Trademark Objection Reply service.

    You can also read Lawizer’s detailed guide on how to file a trademark objection reply in India.

    Step 5: Publication and Opposition

    If the application progresses beyond examination, it may be published in the Trade Marks Journal.

    Publication gives third parties an opportunity to oppose the registration within the period prescribed under the applicable law and rules.

    If no opposition is filed within the prescribed period, the application may proceed towards registration, subject to the applicable requirements.

    If an opposition is filed, the matter can involve pleadings, evidence and hearings. The timeline can therefore become considerably longer.

    Step 6: Registration and Renewal

    Once the application successfully completes the registration process, the Registrar issues the registration certificate.

    A registered trademark is generally valid for 10 years and can be renewed for further periods in accordance with the law.

    Businesses should therefore maintain a record of renewal deadlines and monitor the continued use of their trademark.

    Lawizer also provides a Trademark Renewal service for businesses that need assistance with maintaining their registration.

    How to Protect Your Brand Name Without Trademark Registration

    Trademark registration is usually the strongest practical route for protecting a brand name, but businesses should also take other preventive measures.

    These steps do not replace trademark registration, but they can strengthen your overall brand-protection strategy.

    • Use the brand consistently across your products and business communications.
    • Maintain dated records showing when you began using the brand.
    • Keep invoices, packaging, advertisements and promotional materials showing genuine commercial use.
    • Secure relevant domain names where commercially appropriate.
    • Reserve important social media handles where available.
    • Use written agreements with agencies, designers and freelancers dealing with your brand assets.
    • Monitor marketplaces and online platforms for potentially infringing uses.
    • Consider trademark registration before substantial investment in the brand.

    Evidence of use can become relevant in certain trademark disputes, particularly where questions of prior use or goodwill arise. However, relying solely on unregistered rights can be more complicated than having a registered trademark.

    Can Copyright Protect Your Brand Name?

    Copyright and trademark protection serve different purposes.

    A brand name itself is generally approached through trademark law rather than copyright law. However, the creative elements associated with a brand may raise separate copyright considerations.

    For example, original artwork, illustrations, photographs, written content or certain creative logo elements may qualify for copyright protection depending on the circumstances.

    Lawizer provides a separate Copyright Registration service for protecting eligible creative works.

    Businesses should therefore consider whether they need one form of intellectual property protection or a combination of protections.

    How to Protect Your Brand Name From Infringement

    Registration is only one part of brand protection. Once your trademark application or registration exists, you should continue watching for potentially confusing uses.

    Regular monitoring can help you identify:

    • New businesses using a similar name.
    • Similar trademark applications.
    • Counterfeit products.
    • Unauthorised use of your logo or brand identity.
    • Confusingly similar social media accounts.
    • Marketplace listings that appear to imitate your brand.

    Early action can be important. Depending on the facts, possible responses may include sending a legal notice, requesting removal from an online platform, opposing a conflicting trademark application or pursuing appropriate legal proceedings.

    The correct response depends on the nature of the infringement, the status of your trademark and the evidence available.

    What Happens If Someone Uses Your Brand Name?

    If another business starts using your brand name or a confusingly similar mark, do not immediately assume that registration guarantees an automatic result.

    The legal position depends on factors such as the marks involved, the goods or services, the nature of the use, the relevant dates, the strength of the mark and the evidence of confusion or goodwill.

    A registered proprietor may have remedies for trademark infringement under the applicable provisions of the Trade Marks Act, while unregistered marks may in appropriate circumstances be protected through the common-law action of passing off.

    Because trademark disputes can become fact-specific, businesses should obtain legal advice before sending threats or commencing proceedings.

    How Much Does It Cost to Protect a Brand Name?

    The total cost depends on the type of protection, applicant category, number of classes, professional or facilitation charges and whether the application faces objections or opposition.

    Government trademark fees are generally calculated per mark and per class. Additional professional costs may apply when a business uses legal or trademark filing assistance.

    For this reason, there is no single universal price for protecting every brand.

    Before filing, check the current official fee schedule and obtain a clear breakdown of government fees and professional or facilitation charges.

    How Long Does Brand Name Protection Take?

    Trademark registration is not an instant process. It involves filing, examination and, where applicable, publication and opposition proceedings before registration.

    An uncontested application may progress within several months, but actual timelines vary depending on examination, objections, hearings, opposition and the workload of the Registry.

    Applications facing objections or opposition can take substantially longer.

    Therefore, businesses should not make major commercial decisions based on an assumed fixed registration date.

    Common Mistakes When Protecting a Brand Name

    Using the Name Before Checking Availability

    Launching a brand without conducting a trademark search can lead to expensive rebranding if an earlier conflicting mark is discovered later.

    Assuming Company Registration Is Enough

    Registering a company or LLP name does not replace trademark registration. These are different legal processes with different purposes.

    Choosing the Wrong Trademark Class

    A trademark application must accurately identify the goods or services for which protection is sought. Incorrect classification can limit the practical value of the registration.

    Ignoring Similar Marks

    Searching only for identical names is not enough. Similarity can arise from spelling, pronunciation, appearance or the overall commercial impression.

    Forgetting to Monitor the Trademark

    Obtaining registration does not mean you should stop watching the market. Businesses should monitor potential conflicts and respond appropriately when necessary.

    Using the ® Symbol Too Early

    The ® symbol should not be used as though a mark is registered before registration has actually been obtained. Businesses using an unregistered mark commonly use the ™ symbol instead.

    Brand Protection Checklist for Indian Businesses

    • Choose a distinctive brand name.
    • Search existing trademarks.
    • Review similar marks, not only identical marks.
    • Identify the correct goods and services classes.
    • Consider whether the brand should be protected in more than one class.
    • Consider registering the word mark and relevant logo separately where appropriate.
    • File the trademark application as early as commercially sensible.
    • Keep evidence of genuine brand use.
    • Monitor applications and marketplace activity.
    • Respond promptly to objections or legal notices.
    • Track the trademark renewal date.

    Frequently Asked Questions About Protecting a Brand Name

    How do I legally protect my brand name in India?

    The main route is to seek trademark registration for the brand name in the relevant goods or services classes. Before filing, conduct a proper search and assess whether the mark is distinctive and conflicts with earlier marks.

    Can I trademark my business or brand name?

    Yes, a name may be eligible for trademark protection if it satisfies the legal requirements. The proposed mark must be considered in relation to the goods or services for which protection is sought.

    Is trademark registration mandatory to use a brand name?

    No. A business may use an unregistered mark, and certain rights may arise from use. However, registration can provide stronger and clearer statutory protection and is generally advisable for a brand that is intended to grow.

    Does registering a company name protect the brand?

    No. Company or LLP name registration and trademark registration are separate. Registering an entity name does not automatically provide comprehensive trademark rights over the brand.

    How can I check whether a brand name is already registered?

    You can use the official IP India trademark search facility to search existing marks. A professional search should also consider potentially similar marks and the relevant goods or services.

    How much does trademark registration cost in India?

    The government fee depends on the applicant category and the number of marks and classes involved. Professional or facilitation charges are separate. Always verify the current government fee schedule before filing.

    How long does trademark registration take?

    There is no guaranteed fixed timeline. The process may take several months and can take longer if an objection, hearing or opposition arises.

    What if my trademark application is objected to?

    A trademark objection is not necessarily a final rejection. The applicant can respond to the examination report within the prescribed period and may need to attend a hearing depending on the case.

    Can copyright protect my brand logo?

    Copyright and trademark law protect different interests. Original artistic or creative elements may qualify for copyright protection, while trademark registration is generally the principal form of protection for a brand identifier used to distinguish goods or services.

    Can I protect my brand name without registering a trademark?

    You can take practical measures such as maintaining evidence of use, securing domains and monitoring the market. In appropriate cases, unregistered marks may also receive protection through passing-off principles. However, these rights can be more difficult to establish and enforce than registered trademark rights.

    Protect Your Brand Before It Becomes a Problem

    Your brand may take years to build, but a trademark conflict can disrupt it much faster. The safest approach is to consider intellectual property protection before investing heavily in marketing, packaging and customer acquisition.

    Start with a trademark search, identify the right classes and assess whether registration is appropriate for your business. Once filed, keep track of the application and respond promptly to any objection or opposition.

    If you need help with the process, Lawizer can assist with trademark registration and brand protection, including filing and application support.

    Want to protect your brand name? Consult Lawizer to understand the appropriate trademark strategy for your business before you invest further in building the brand.

    Explore Lawizer’s legal services for businesses or get professional assistance with your trademark application.

    Useful Resources

  • Legal List for New Founders:

    Legal List for New Founders:

    Legal List for New Founders: What You Need to Know

    Starting a business in India involves more than choosing a name, building a product and finding customers. A new founder also needs to understand registration, taxation, contracts, intellectual property and ongoing compliance. This legal list for new founders brings the main requirements together in one practical guide.

    The right legal setup depends on your business model. A freelancer, a small shop, an LLP and a venture-backed technology company will not have exactly the same obligations. Therefore, founders should avoid treating every startup checklist as a universal legal rule.

    For company incorporation, founders can also review Lawizer’s startup and business legal services, which cover business structures, Startup India registration, GST, intellectual property and compliance.

    What Is the Legal List for New Founders in India?

    A startup legal checklist is a practical list of registrations, documents, contracts and recurring obligations that may apply to a new business. It is not one government form or a single statutory checklist.

    For most founders, the process can be divided into five stages:

    • Choose the appropriate business structure.
    • Complete the required registration and tax formalities.
    • Obtain licences and approvals relevant to the industry.
    • Protect the brand, intellectual property and business relationships.
    • Maintain tax, corporate and regulatory compliance after launch.

    Keeping these stages separate makes the process easier. For example, incorporating a private limited company does not automatically mean that GST registration, every industry licence or every employee-related registration becomes mandatory.

    Choose the Right Business Structure

    The first major decision is the legal form of the business. Common options include a sole proprietorship, partnership firm, LLP, OPC and private limited company.

    A Private Limited Company is often considered by founders who expect outside investment, equity-based ownership or significant scaling. It is a separate legal entity and provides limited liability, subject to applicable law.

    A Limited Liability Partnership can be suitable where founders want limited liability with a partnership-style structure.

    For an eligible solo founder, an One Person Company can provide a corporate structure with a single member.

    The best structure depends on funding plans, ownership, liability, tax considerations, compliance requirements and the founders’ long-term plans.

    Complete the Basic Registrations

    For a company incorporated through the Ministry of Corporate Affairs, the incorporation process uses the MCA’s SPICe+ system. SPICe+ Part A deals with name reservation, while Part B contains the remaining incorporation information and linked services.

    Depending on the structure, founders may receive or need documents such as the certificate of incorporation, PAN, TAN, DIN, DSC and constitutional documents.

    Founders should keep digital copies of these records in a secure business folder. They are frequently needed for banking, taxation, contracts, funding and later compliance.

    For a deeper explanation of director identification, see Lawizer’s guide to DIN and the director registration process.

    What Are the Legal Procedures to Start a Startup in India?

    The legal procedure depends on the entity and industry, but a typical founder journey follows a logical sequence.

    Step 1: Decide Who Owns and Controls the Business

    Before filing anything, decide who the founders are, how ownership will be divided and who will be responsible for key functions.

    Where there are multiple founders, do not rely only on verbal promises. A written agreement can clarify ownership, responsibilities, intellectual property, decision-making and what happens if someone leaves.

    Lawizer also provides a detailed guide to founders’ agreements for Indian startups.

    Step 2: Select the Business Structure

    Compare the available structures before incorporation. A high-growth startup seeking equity investment may have different requirements from a small professional business with two partners.

    Do not choose a structure only because it is cheaper to register. Consider the compliance burden and whether changing the structure later could create additional legal, tax or administrative work.

    Step 3: Register the Business

    For companies, incorporation is handled through the MCA framework. The exact documents and declarations depend on the proposed entity, directors, subscribers and registered office.

    For a private company, the incorporation documents generally include the company’s constitutional documents and identity/address documentation for the relevant individuals.

    For an LLP, the LLP agreement is an important document because it records the internal relationship between the partners.

    Step 4: Check GST and Other Tax Requirements

    GST registration is not automatically required merely because a business has been incorporated. GST applicability depends on factors such as the nature of supplies, turnover, location and specified categories under GST law.

    The GST portal provides the applicable registration process and allows a taxpayer to identify the date on which registration liability arises. Founders should check the current rules rather than relying on an old turnover figure.

    If GST registration applies to your business, Lawizer’s GST registration service can be considered as part of the startup setup process.

    Step 5: Check Industry-Specific Licences

    Some businesses need additional approvals because of what they sell, where they operate or how they operate.

    Depending on the business, founders may need to examine requirements relating to:

    • Food and beverage operations.
    • Import and export activities.
    • Manufacturing and environmental permissions.
    • Employment and labour requirements.
    • State or local business registrations.
    • Sector-specific financial, healthcare, education or other licences.

    Therefore, a startup legal checklist should always include an industry-specific compliance review.

    Step 6: Protect Intellectual Property

    Your business name, logo, software, designs, content and inventions can become valuable assets. Founders should identify which forms of intellectual property matter before investing heavily in a brand.

    A registered trademark can provide stronger and clearer protection for a distinctive brand. The official IP India guidance explains that trademarks can cover word marks, logos, shapes, colour combinations and sound marks, subject to the legal requirements.

    Lawizer offers trademark registration services for founders who want assistance with the filing process.

    Step 7: Put Contracts in Place

    Once the business starts dealing with employees, freelancers, customers, vendors or investors, written contracts become increasingly important.

    A contract should clearly establish what each party must do, how payment works, who owns intellectual property, how confidential information is handled and what happens when the relationship ends.

    What Legal Documents Should a Startup Have?

    There is no single set of documents that every startup must have. However, a well-organised founder should maintain several categories of records.

    Corporate and Registration Documents

    • Certificate of Incorporation or applicable registration certificate.
    • MOA and AOA, where applicable.
    • LLP agreement or partnership deed, where applicable.
    • PAN and TAN records.
    • DIN and DSC records for relevant directors.
    • Registered office documentation.
    • GST registration certificate, where applicable.

    Founder and Ownership Documents

    For a startup with more than one founder, ownership arrangements should be documented clearly.

    • Founders’ agreement.
    • Shareholders’ agreement, where appropriate.
    • Share subscription or transfer documents.
    • Founder vesting arrangements, where applicable.
    • Intellectual-property assignment documents.

    These documents can prevent misunderstandings about equity, responsibilities and decision-making later.

    Commercial Contracts

    Commercial documents should match the way the business actually operates. Depending on the startup, this can include:

    • Customer or service agreements.
    • Vendor and supplier agreements.
    • Consultancy agreements.
    • Employment agreements.
    • Non-disclosure agreements.
    • Licensing agreements.
    • Joint venture agreements.
    • Letters of intent and term sheets.

    Lawizer’s business documentation services cover several types of founder and commercial agreements.

    Online Business Documents

    If your startup operates a website, mobile application or online marketplace, consider the legal documents appropriate to the service and data you collect.

    These may include terms of use, privacy documentation, refund or cancellation policies and other consumer-facing notices. The exact requirements depend on the business model and applicable laws.

    What Is a Startup Legal Checklist?

    A useful startup legal checklist should not stop when the certificate of incorporation arrives. Instead, divide it into three phases.

    Before Launch

    • Choose the business structure.
    • Decide founder ownership and responsibilities.
    • Check the proposed brand name.
    • Register the business where required.
    • Arrange PAN, TAN and banking requirements.
    • Review GST applicability.
    • Identify industry-specific licences.
    • Protect important intellectual property.

    Before Hiring or Signing Customers

    • Use appropriate employment or consultancy agreements.
    • Document founder arrangements.
    • Use NDAs where confidentiality requires them.
    • Set out customer and vendor obligations in writing.
    • Clarify ownership of work created for the business.

    After Launch

    • Maintain accounting records.
    • File applicable GST and tax returns.
    • Complete required ROC filings.
    • Track director and other statutory compliance.
    • Renew licences and registrations where applicable.
    • Keep contracts and corporate records updated.

    For companies that have already been incorporated, Lawizer’s annual compliance service provides a useful starting point for understanding recurring ROC, tax and other compliance requirements.

    What Is the ₹20 Lakh Grant for Startups?

    The phrase “₹20 lakh startup grant” usually refers to a specific government funding opportunity rather than a universal grant available to every new business.

    One important example is the Startup India Seed Fund Scheme (SISFS). The official Startup India scheme information states that eligible startups can receive up to ₹20 lakh as a grant for activities such as proof-of-concept validation, prototype development or product trials. The scheme also provides a separate investment route for market entry, commercialisation or scaling, subject to its conditions.

    Eligibility matters. The scheme is aimed at eligible early-stage startups and is not simply a payment that every newly incorporated company can claim.

    The official Startup India scheme material should always be checked before applying because scheme windows, eligibility conditions and application arrangements can change.

    How Can Founders Get Money From the Government for a Startup?

    Government support can come in different forms. A founder should first identify the type of assistance that fits the business.

    • Startup grants for eligible innovation or development activities.
    • Seed funding through government-backed programmes.
    • State startup incentives.
    • Incubator-linked funding.
    • Credit-linked or subsidy-based programmes.
    • Government procurement opportunities.

    DPIIT recognition can also provide access to certain Startup India benefits. Current Startup India guidance says eligible recognised startups can access benefits including easier compliance, intellectual-property support and certain tax-related opportunities, subject to separate eligibility requirements.

    Founders should also remember that DPIIT recognition is not the same thing as receiving funding. Recognition may make a startup eligible for particular programmes, but funding normally involves a separate scheme and assessment.

    Lawizer provides Startup India registration assistance for founders seeking DPIIT recognition.

    What Is the 80/20 Rule for Startups?

    The 80/20 rule, also called the Pareto principle, is a business management idea rather than an Indian startup law.

    It suggests that a relatively small number of inputs can sometimes produce a disproportionately large share of results. For example, a founder may discover that a small group of customers generates most of the company’s revenue.

    The principle can help founders prioritise:

    • The most profitable customers.
    • The highest-performing marketing channels.
    • The products generating most revenue.
    • The operational problems causing most delays.
    • The compliance tasks carrying the greatest risk.

    However, 80/20 should be treated as a decision-making framework, not a guaranteed mathematical rule for every startup.

    Why Do 90% of Startups Fail in India?

    “90% of startups fail” is one of the most repeated claims in startup discussions. However, it should not be treated as a precise universal failure rate for Indian startups.

    Startup failure rates vary depending on the definition of failure, the period measured, the industry and the dataset used.

    Still, several recurring business problems can increase the risk of failure:

    • Poor product-market fit.
    • Insufficient or unpredictable cash flow.
    • Weak unit economics.
    • Scaling before demand is proven.
    • High customer acquisition costs.
    • Founder or team disputes.
    • Regulatory and compliance failures.
    • Inability to raise additional capital.

    Legal compliance cannot guarantee that a startup will succeed. It can, however, prevent avoidable problems and make the business easier to operate, fund and sell.

    For example, investors may investigate incorporation records, ownership, intellectual property, contracts and statutory filings during due diligence. Lawizer discusses these risks in its guide on startup compliance gaps that can affect funding rounds.

    Which Startups Are in Loss?

    There is no permanent list of “startups in loss.” A startup may report an accounting loss while still growing rapidly and investing heavily in technology, employees, marketing or market expansion.

    For private companies, detailed financial information may also not be as easily available to the public as it is for listed companies.

    Founders should therefore distinguish between:

    • Accounting loss: expenses exceed recognised revenue for the relevant period.
    • Cash burn: the business is consuming cash faster than it generates it.
    • Negative cash flow: cash outflows exceed cash inflows during a period.
    • Growth investment: spending is deliberately high because the company is trying to expand.

    A better way to evaluate a startup is to look at revenue growth, gross margin, burn rate, runway, customer acquisition cost, retention and contribution margins alongside profitability.

    Can You Provide a List of Registered Startup Companies in India?

    The phrase “registered startup” can mean different things.

    A business may be registered as a company or LLP with the MCA but may not have DPIIT startup recognition. Conversely, a DPIIT-recognised startup must satisfy the applicable Startup India eligibility requirements.

    Current Startup India guidance states that eligible entities can include private limited companies, registered partnership firms, LLPs and cooperative societies, subject to the applicable startup criteria. The current general recognition framework also uses a 10-year age limit and a ₹200 crore turnover ceiling, while separate DeepTech criteria provide different limits.

    Therefore, there is no single sensible list containing every “registered startup company” in India. Founders should first define whether they mean MCA-registered entities, DPIIT-recognised startups or startups registered under a particular state programme.

    Startup Legal Compliance After Registration

    Registration is the beginning of compliance, not the end.

    Tax and GST Compliance

    Businesses must identify the income-tax, GST, TDS and other tax obligations that apply to their activities and structure.

    GST-registered businesses may have recurring return and record-keeping obligations. The exact return pattern depends on the taxpayer’s circumstances and applicable scheme.

    For direct tax matters, founders should use the official Income Tax e-Filing portal for current filing and tax information.

    ROC and Corporate Compliance

    Companies and LLPs have continuing filing and record-keeping responsibilities. The exact forms and deadlines depend on the entity and circumstances.

    For example, certain companies incorporated with share capital may have post-incorporation requirements such as the declaration of commencement of business. Lawizer explains the relevant INC-20A compliance requirement in detail.

    MSME and Udyam Registration

    Udyam registration is separate from company incorporation and GST registration. Eligible businesses can consider it where the MSME framework applies.

    The official Udyam system provides the registration mechanism and eligibility framework. Founders should use the government portal for the latest requirements.

    Lawizer also provides MSME/Udyam registration assistance as part of its business services.

    Employment Compliance

    Once a startup hires employees, additional obligations may arise under applicable labour and employment laws. These can depend on the number of employees, location, wages, nature of work and other factors.

    Do not assume that every employment registration applies from the first hire. Instead, assess the applicable thresholds and state-specific requirements.

    Data and Online Business Compliance

    Consumer-facing startups should also consider privacy, data handling, terms of use and consumer-facing policies.

    These documents should reflect the actual way the business collects, uses, stores and shares information. A generic privacy policy copied from another website may not accurately describe your business.

    What Are the 7 Types of Startup Documents?

    There is no universal legal classification called the “seven types of startup documents.” However, founders can organise their records into seven practical categories:

    1. Registration documents: incorporation and registration certificates.
    2. Ownership documents: shareholder and founder records.
    3. Tax documents: PAN, TAN, GST and tax filings where applicable.
    4. Commercial contracts: customer, vendor and service agreements.
    5. Employment documents: employment and consultancy agreements.
    6. Intellectual-property documents: trademark, copyright, patent and IP assignment records.
    7. Compliance records: ROC filings, statutory registers and other regulatory records.

    This classification is useful because it makes due diligence easier. When an investor, lender, customer or regulator asks for documents, the founder can locate them quickly.

    What Is a List of Documents for a New Business?

    A practical document repository should contain more than incorporation papers.

    At a minimum, create separate folders for corporate records, tax, banking, contracts, employees, intellectual property and compliance.

    Use consistent file names and maintain the latest signed version of each agreement. Also keep evidence of filings and acknowledgements rather than retaining only draft forms.

    This becomes especially important when the business starts raising funds. Missing documents can slow legal due diligence and may create questions about ownership or compliance.

    What Are 10 Different Types of Business Documents?

    Ten common categories or examples include:

    • Certificate of Incorporation or business registration certificate.
    • MOA and AOA, where applicable.
    • Founder or shareholders’ agreement.
    • Customer or service agreement.
    • Vendor or supplier agreement.
    • Employment agreement.
    • Non-disclosure agreement.
    • Intellectual-property registration or assignment document.
    • Tax registration and filing records.
    • Statutory and regulatory compliance records.

    The exact document set should be tailored to the business. A SaaS company, restaurant, manufacturer and consulting firm can have very different legal requirements.

    Frequently Asked Questions About the Legal List for New Founders

    What are the legal procedures to start a startup in India?

    Choose the business structure, complete the applicable registration, obtain required tax registrations and licences, document founder and commercial relationships, protect intellectual property and establish an ongoing compliance process.

    What documents should a startup have?

    A startup should maintain registration records, ownership documents, tax records, contracts, employment documents, IP records and ongoing compliance documents relevant to its structure and activities.

    What is the ₹20 lakh grant for startups?

    The ₹20 lakh figure is associated with specific government funding programmes such as the Startup India Seed Fund Scheme. It is not a universal grant automatically available to every newly incorporated startup.

    How do I get money from the government for a startup?

    Check DPIIT recognition, central and state startup schemes, incubators and government-backed funding programmes. Each programme has its own eligibility criteria, funding structure and application process.

    What is the 80/20 rule for startups?

    It is the Pareto principle, a business prioritisation concept. It is not a statutory Indian startup rule.

    What is the 50/100/500 rule for startups?

    The phrase does not represent one universal Indian startup law. Different articles or programmes may use similar numbers for different metrics. Founders should identify the specific rule or scheme before relying on it.

    Is it true that 90% of startups fail?

    There is no single reliable universal 90% failure rate that applies to every Indian startup. Failure rates depend on the dataset, definition and period being measured.

    Which startups are in loss?

    Many startups can operate at a loss while investing in growth. For private companies, complete financial information may not always be publicly available, so a current universal list is not practical.

    What is a startup checklist?

    It is a practical list of incorporation, tax, licensing, contract, IP and ongoing compliance tasks that a founder can use to organise the business legally.

    Can a new startup get government funding immediately?

    Not automatically. Funding schemes generally have eligibility conditions, application processes and assessment criteria. Incorporation alone does not guarantee government funding.

    Final Legal Checklist for New Founders

    Building a business is exciting, but legal groundwork should not be treated as an afterthought. A strong foundation helps founders avoid preventable disputes and makes future fundraising, hiring and expansion easier.

    Before launching, review your business structure, ownership, registration, GST and tax position, licences, contracts and intellectual property. After launch, maintain your filings and records continuously.

    Because legal and tax requirements vary by entity, state, industry and business activity, this guide should be used as general information rather than a substitute for advice on your specific situation.

    If you are unsure where to begin, Lawizer’s startup and business legal team can help you review company registration, GST, Startup India, trademark, MSME and compliance requirements in one place.

    Ready to put your startup on a stronger legal footing? Start with the requirement that applies to your business today, then build your compliance system as the business grows.

  • Private Limited Registration in India: Complete Guide, Process, Documents & FAQs

    Private Limited Registration in India: Complete Guide, Process, Documents & FAQs

    Starting a business is exciting, but choosing the right legal structure is one of the first important decisions an entrepreneur has to make.

    For startups, growing businesses and founders who may want to raise investment in the future, private limited registration is one of the most popular business registration options in India.

    A Private Limited Company is a separate legal entity from its shareholders. It can own property, enter into contracts, open bank accounts, raise capital and conduct business in its own name. The Companies Act, 2013 permits two or more persons to form a private company by subscribing to its memorandum and complying with the applicable incorporation requirements.

    But how exactly does private limited registration work?

    What documents are required? How many directors and shareholders are needed? Is GST mandatory? Can you register the company yourself? And is a Private Limited Company better than an LLP or OPC?

    This guide explains the private limited registration process in India, the documents required, basic eligibility, costs, post-incorporation requirements and the most common questions founders ask before registering their company.

    What is a Private Limited Company?

    A Private Limited Company is a company incorporated under the Companies Act, 2013 and is treated as a separate legal entity from its members.

    The word “Private” means that the company’s shares are subject to restrictions prescribed by law and its Articles of Association, and the company does not invite the public to subscribe to its securities in the same manner as a public company.

    For entrepreneurs, one of the biggest advantages is limited liability. Generally, the liability of shareholders is limited to the amount unpaid on the shares held by them.

    A Private Limited Company can also provide a more structured ownership framework for businesses that intend to bring in co-founders, investors or employees through equity-based arrangements.

    Who Can Register a Private Limited Company?

    Generally, a Private Limited Company requires at least:

    • 2 shareholders
    • 2 directors
    • 1 resident director meeting the applicable residency requirement
    • A registered office address in India
    • A proposed company name
    • A lawful business object

    The shareholders and directors can be the same individuals.

    For example, two founders can incorporate a company where both founders are shareholders and both are appointed as directors.

    A person who wants to operate completely alone may instead consider an One Person Company (OPC), subject to the applicable eligibility requirements.

    Why Choose a Private Limited Company?

    Private limited registration is particularly popular among startups and businesses that expect to grow.

    1. Limited liability

    One of the primary advantages is limited liability protection for shareholders, subject to the applicable provisions of law.

    This creates a separation between the company’s liabilities and the personal assets of its shareholders in ordinary circumstances.

    2. Separate legal identity

    The company has its own legal identity.

    It can enter into agreements, own assets, borrow money and conduct business independently from its individual shareholders.

    3. Better structure for fundraising

    If your business plans to raise angel investment, venture capital or other equity funding, a Private Limited Company is often a suitable structure because ownership can be represented through shares.

    Investors can acquire shares in the company without the business necessarily having to change its fundamental legal structure.

    4. Easier ownership structuring

    A Private Limited Company allows founders to clearly document their ownership through shareholding.

    This can be particularly useful when there are multiple founders or when investors may join later.

    5. Professional credibility

    Registration as a company can provide a formal corporate structure when dealing with customers, vendors, banks, investors and other stakeholders.

    However, registration alone does not guarantee credibility. Proper accounting, taxation and annual compliance remain essential.

    6. Continuity

    A company has a legal existence independent of changes in its individual shareholders or directors, subject to applicable law.

    This makes the structure more suitable for businesses intended to continue beyond the involvement of one particular founder.

    Private Limited Registration: Basic Eligibility and Requirements

    Before starting the incorporation process, founders should check a few basic requirements.

    Minimum shareholders

    A Private Limited Company generally requires at least two members.

    There is no requirement that every shareholder must also be a director.

    Minimum directors

    A Private Limited Company generally requires at least two directors.

    The directors must satisfy the requirements under the Companies Act, 2013 and related rules.

    Resident director

    The company must have at least one director who satisfies the applicable requirement of staying in India for the prescribed period.

    Founders should check the residency requirement applicable to their incorporation circumstances rather than assuming that any director automatically qualifies.

    Registered office

    The company must have a registered office capable of receiving official communications.

    A residential property can potentially be used as the registered office if the relevant address and supporting documents satisfy the applicable requirements.

    Proposed name

    The company needs a name that complies with the naming requirements under the Companies Act and related rules.

    A proposed name may be rejected if it is too similar to an existing company or LLP, conflicts with a registered trademark or otherwise violates the applicable naming requirements.

    Documents Required for Private Limited Registration

    The exact documents can vary depending on the promoters, registered office and circumstances of incorporation.

    For Indian individual promoters, the commonly required documents include:

    For directors and shareholders

    • PAN card
    • Identity proof
    • Address proof
    • Recent photograph
    • Mobile number
    • Email address
    • Residential address details
    • Digital Signature Certificate where required

    Acceptable identity and address documents should be checked against the current MCA requirements before filing.

    For the registered office

    Commonly required documents may include:

    • Proof of ownership or authorised occupancy
    • Recent utility bill or other prescribed address proof
    • Rent or lease agreement, where applicable
    • No-objection certificate from the owner, where applicable

    The registered office documentation should match the address provided in the incorporation application.

    Step-by-Step Private Limited Registration Process

    The incorporation process is primarily completed through the MCA’s online incorporation framework.

    Step 1: Decide the business structure

    Before filing anything, decide whether a Private Limited Company is actually suitable for your business.

    Consider:

    • Number of founders
    • Planned investment
    • Ownership structure
    • Compliance requirements
    • Expected turnover
    • Future fundraising
    • Employee stock options
    • Whether outside investors may join

    A Private Limited Company is not automatically the best structure for every business.

    Step 2: Finalise the proposed company name

    Choose a suitable company name and check whether it is likely to be available.

    The name should comply with the applicable MCA naming rules and should also be checked from a trademark perspective.

    A company name being available on the MCA portal does not necessarily mean that the corresponding trademark is available.

    Step 3: Obtain Digital Signature Certificates

    Digital signatures are used for electronically signing incorporation documents and related filings.

    The applicable subscribers and directors may need valid DSCs depending on the filing structure.

    Step 4: File SPICe+ Part A

    SPICe+ is the MCA’s electronic incorporation framework.

    Part A is used for name reservation.

    The applicant provides details such as the proposed company name and business activity/NIC classification.

    Where applicable, supporting documents may also need to be submitted.

    Step 5: Complete SPICe+ Part B

    Once the incorporation application proceeds to Part B, detailed information regarding the proposed company is submitted.

    This can include:

    • Company structure
    • Registered office
    • Subscribers
    • Directors
    • Share capital
    • PAN and TAN information
    • Other incorporation details
    • Required declarations and attachments

    The MCA’s SPICe+ documentation divides Part B into multiple sections covering company structure, address, subscribers/directors, stamp duty, PAN/TAN, attachments and declarations.

    Step 6: File linked forms

    Depending on the company and its circumstances, linked forms can include:

    • e-MOA
    • e-AOA
    • AGILE-PRO-S
    • INC-9, where applicable

    The MCA’s current SPICe+ FAQs specify the sequence for uploading the relevant linked forms.

    Step 7: Pay government fees and stamp duty

    The applicable government fees and stamp duty depend on factors such as the company’s authorised capital and the state in which the registered office is situated.

    Therefore, there is no single government fee applicable to every Private Limited Company.

    Step 8: MCA examination and approval

    After submission, the Registrar of Companies examines the incorporation application.

    If the application satisfies the applicable requirements, the company is incorporated.

    If there are deficiencies, the application may require correction or resubmission.

    Step 9: Receive the Certificate of Incorporation

    Once approved, the company receives its Certificate of Incorporation (COI).

    The company is then legally incorporated and receives its Corporate Identity Number (CIN).

    PAN and TAN are also integrated into the incorporation process where applicable.

    How Much Does Private Limited Registration Cost?

    The cost of private limited registration generally consists of several components rather than one universal amount.

    These can include:

    • Government filing fees
    • State stamp duty
    • Digital Signature Certificate charges
    • Professional or facilitation fees
    • Any additional services requested by the founders

    The government component can vary depending on factors such as authorised capital and the state of incorporation.

    Therefore, founders should compare the total cost, not just an advertised professional fee.

    It is also important to check whether government charges, DSC charges and additional services are included in a quoted package.

    Is GST Mandatory for a Private Limited Company?

    No. GST registration is not automatically mandatory simply because a business is incorporated as a Private Limited Company.

    GST applicability depends on the nature of the business, turnover, supplies, state and other conditions prescribed under GST law.

    For example, a newly incorporated company may exist without immediately becoming liable for GST registration if the applicable conditions for mandatory registration are not triggered.

    However, certain businesses may require GST registration even in circumstances where the general turnover threshold would otherwise be relevant.

    Therefore, GST should be evaluated separately after incorporation rather than treating it as an automatic consequence of company registration.

    Can I Register a Private Limited Company Myself?

    Yes, it is possible to initiate and complete incorporation through the MCA’s online system if you understand the applicable requirements and can correctly prepare the forms and supporting documents.

    However, incorporation involves more than simply filling out an online form.

    You need to correctly handle:

    • Name selection
    • Business activity classification
    • Share capital
    • Director details
    • Registered office documentation
    • MOA and AOA
    • Digital signatures
    • Linked forms
    • Declarations
    • Government fees
    • Resubmission, if required

    A mistake in the incorporation application can result in rejection, resubmission or unnecessary delays.

    For founders unfamiliar with MCA filings, professional assistance can simplify the process and reduce documentation errors.

    Private Limited Company vs LLP: Which is Better?

    There is no universally better structure. The right choice depends on your business model.

    Private Limited Company

    Generally more suitable when you:

    • Want to raise equity investment
    • Expect multiple investors
    • Want a share-based ownership structure
    • Plan to build a scalable startup
    • May consider ESOPs
    • Want a conventional corporate structure

    LLP

    An LLP can be attractive where:

    • Partners want operational flexibility
    • The business is professional or partnership-oriented
    • Equity investment is not the immediate objective
    • The founders prefer an LLP structure

    If your long-term plan includes venture capital or significant equity fundraising, a Private Limited Company is often the more practical structure to evaluate.

    Private Limited Company vs OPC

    An OPC is designed for a single-member structure, while a Private Limited Company generally requires at least two members.

    An OPC can be useful for a solo entrepreneur who wants a corporate form without immediately bringing in another shareholder.

    A Private Limited Company may be more suitable where:

    • There are two or more founders
    • You expect investors
    • You want multiple shareholders
    • You may issue or transfer shares
    • You expect the business to scale significantly

    The decision should be based on the founder’s current structure as well as future plans.

    Private Limited Company vs Limited Company

    A “Limited Company” can refer broadly to a company with limited liability, but in common Indian business usage, entrepreneurs often use “Private Limited Company” to distinguish it from a public limited company.

    A Private Limited Company generally has restrictions on the transfer of shares and does not invite the public to subscribe to its securities.

    A public company has a different legal and regulatory framework and may be more appropriate for businesses that require access to public capital markets, subject to the applicable requirements.

    For most early-stage startups and privately held businesses, Private Limited registration is generally the more relevant structure to consider.

    What Happens After Private Limited Registration?

    Getting the Certificate of Incorporation is not the end of the compliance process.

    It is the beginning.
    After incorporation, founders should consider:

    1. Open the company’s bank account

    The company should operate through its own bank account rather than mixing company transactions with personal accounts.

    2. Bring in subscribed capital

    The subscribers should contribute the capital they have agreed to contribute to the company.

    3. Check commencement requirements

    Companies having share capital are required to comply with the applicable declaration regarding commencement of business and exercising borrowing powers under Section 10A and the prescribed form.

    The MCA’s INC-20A framework provides for the commencement declaration and specifies the applicable filing timeline.

    4. Appoint the first auditor

    The company must comply with the applicable requirements relating to appointment of its auditor.

    5. Maintain statutory records

    Companies need to maintain appropriate registers, books and corporate records.

    6. Complete annual ROC compliance

    Private Limited Companies have continuing annual compliance obligations.

    Depending on the company and its circumstances, these can include financial statement filing, annual return filing, income-tax compliance, auditor-related compliance and other applicable filings.

    Incorporation is therefore not a one-time compliance event.

    Common Mistakes to Avoid During Private Limited Registration

    Choosing a name without checking trademarks

    MCA name approval and trademark protection are separate issues.

    Before finalising your company name, conduct an appropriate trademark search.

    Using incorrect registered office documents

    An incorrect address, outdated proof or missing consent documentation can create problems during incorporation.

    Selecting the wrong business activity

    The company’s business activity and NIC classification should accurately reflect its proposed operations.

    Ignoring post-incorporation compliance

    Some founders believe that receiving the Certificate of Incorporation means all legal work is finished.

    It does not.

    A company must continue complying with applicable corporate, tax and regulatory requirements.

    Looking only at the cheapest registration package

    The lowest advertised incorporation fee may not represent the lowest total cost.

    Always check what is included and whether government charges, DSCs and post-incorporation assistance are covered.

    Frequently Asked Questions

    Who is the owner of a Private Limited Company?

    A Private Limited Company is owned by its shareholders.

    The shareholders own shares in the company, while directors are responsible for managing the company’s affairs in accordance with the Companies Act, the Articles of Association and applicable decisions of the company.

    The person running the company is therefore not necessarily its “owner”.

    For example, a founder may be both a shareholder and director, but the legal ownership of the company is represented through shareholding.

    Can one person start a Private Limited Company?

    A conventional Private Limited Company generally requires at least two members.

    If an individual wants to establish a company alone, an OPC may be an alternative subject to applicable eligibility requirements.

    Is GST mandatory for a Private Limited Company?

    No.

    Private limited registration by itself does not automatically make GST registration mandatory.

    GST registration depends on the applicable GST provisions, including turnover, nature of supply and other prescribed conditions.

    Can I register a Private Limited Company myself?

    Yes.

    The MCA provides an online incorporation mechanism through SPICe+.

    However, the process requires careful preparation of company details, documents, declarations and linked forms.

    Professional assistance can be useful if you are unfamiliar with MCA incorporation procedures.

    Who is eligible to register a Private Limited Company?

    Generally, two or more persons can form a Private Limited Company subject to the requirements of the Companies Act, 2013 and applicable rules.

    The proposed directors and shareholders must satisfy the relevant legal and documentation requirements.

    Which is better: LLP or Private Limited Company?

    It depends on the business.

    An LLP may be suitable for businesses seeking partnership-style flexibility, while a Private Limited Company is often preferred by startups expecting equity investment, multiple shareholders or significant scaling.

    Which company is better: Limited or Private Limited?

    The answer depends on your objectives.

    A Private Limited Company is generally suitable for privately held startups and growing businesses, whereas a public company follows a different regulatory framework and may be appropriate for businesses seeking public investment, subject to eligibility.

    How many members are there in a Private Limited Company?

    A Private Limited Company generally requires at least two members.

    The maximum number of members is generally 200, subject to the applicable provisions of the Companies Act, 2013.

    Is a Private Limited Company better than an OPC?

    Not necessarily.

    An OPC can be appropriate for a single founder, while a Private Limited Company can be more suitable when there are multiple founders or when the business expects to bring in investors and shareholders.

    Can a Private Limited Company become an OPC?

    A company cannot simply be treated as an OPC whenever it wants.

    The applicable conversion and eligibility provisions must be examined based on the company’s circumstances and the Companies Act and rules in force at that time.

    What is the difference between an LLC and a Private Limited Company?

    LLC generally refers to a Limited Liability Company, a business structure commonly associated with jurisdictions such as the United States.

    India has its own corporate structures, including Private Limited Companies and LLPs.

    Therefore, an entrepreneur in India should generally compare a Private Limited Company with an LLP or other Indian business structures rather than treating an American LLC and an Indian Private Limited Company as identical entities.

    What are the disadvantages of a Private Limited Company?

    Some common disadvantages include:

    • More compliance than an informal business structure
    • Annual ROC filings
    • Maintenance of corporate records
    • Accounting and audit-related obligations
    • Restrictions and procedures around share transfers
    • Additional professional and compliance costs

    For a business intending to scale, however, these obligations may be justified by the benefits of the corporate structure.

    Final Thoughts

    Private limited registration can provide a strong legal foundation for entrepreneurs who want to build a scalable and professionally structured business.

    It offers limited liability, separate legal identity and a share-based ownership structure that can be useful for bringing in co-founders and investors.

    But incorporation should not be treated as merely obtaining a Certificate of Incorporation.

    The right company name, correct documentation, appropriate business structure, accurate incorporation forms and post-incorporation compliance all matter.

    If you are unsure whether a Private Limited Company, LLP or OPC is right for your business, it is better to evaluate your business model and future plans before filing.

    Start Your Business With Lawizer

    From choosing the right business structure to incorporation and ongoing compliance, Lawizer helps entrepreneurs navigate the legal side of starting and growing a business.

    Need help with Private Limited Company registration?

    Get professional assistance with the incorporation process and start your business on a stronger legal foundation.

    Get Started with Private Limited Company Registration →

    Disclaimer: This article is intended for general informational purposes and does not constitute legal, tax or professional advice. Company incorporation requirements, fees, forms and regulatory requirements may change. Always verify the current requirements applicable to your company before filing.

  • GST, MSME & Trademark Together: The Founder’s Compliance Bundle :-

    GST, MSME & Trademark Together: The Founder’s Compliance Bundle :-

    Most Indian founders register their GST when they have to, file for MSME when someone tells them to, and think about trademark “later.” By the time “later” arrives, a competitor has already filed your brand name. In 2024 alone, India saw over 5.4 lakh trademark applications — a 9.3% jump year-on-year — and a growing share of those are from D2C brands and small businesses who finally woke up to brand theft.

    Here’s what nobody tells you: GST registration, MSME Udyam registration, and trademark filing aren’t three separate tasks. They’re one bundle — and doing them together saves you money, time, and a whole lot of future pain.

    📌 TL;DR: Indian founders who complete GST registration, MSME Udyam registration, and trademark filing together unlock a 50% discount on trademark government fees (₹4,500 per class instead of ₹9,000), reduced GST thresholds, and full legal protection for their brand from day one. This GST-MSME-trademark compliance bundle is the smartest first move any startup founder can make in India — and Lawizer helps you do all three online without a CA visit.

    What You’ll Learn

    • Why GST, MSME, and trademark work better as a bundle than as separate registrations
    • The exact 50% trademark fee concession you get as an MSME — and how to claim it
    • Step-by-step: what to do first, second, and third
    • The real costs involved in 2025, with no surprises
    • Answers to the most common founder questions about this compliance bundle

    Why These Three Registrations Belong Together

    Let’s break this down. Most founders treat compliance as a checklist — get GST when the accountant says so, register MSME someday, trademark when the budget allows. That approach costs you more in the long run.

    Here’s the thing: your MSME Udyam Registration Certificate is the key that unlocks a 50% discount on trademark government fees. Without it, a private limited company pays ₹9,000 per trademark class. With a valid Udyam certificate, that drops to ₹4,500 per class.

    File two classes for your brand name and logo — which most founders need — and you’ve saved ₹9,000 in government fees alone, just by getting MSME done first.

    GST registration matters too, not just for tax compliance. When you file for MSME Udyam registration, the portal asks for your GSTIN (GST Identification Number). It isn’t always mandatory for businesses below the threshold, but having it makes the Udyam process smoother and positions your business as a credible, tax-compliant entity — something that matters when you’re applying for loans, government tenders, or payment gateway accounts with platforms like Razorpay.

    The three registrations also reinforce each other for brand protection. Your GST certificate proves business existence. Your MSME certificate reduces your trademark filing cost. Your trademark protects the brand you’ve built. That’s the full compliance bundle — and it’s most powerful when done in order.

    Step 1: GST Registration — What You Actually Need to Know

    GST (Goods and Services Tax) is India’s unified indirect tax, introduced on 1 July 2017, replacing a maze of earlier taxes including VAT, service tax, and excise duty. If you’re selling goods or services in India beyond a certain threshold, you need to register on the GSTN (GST Network) portal.

    As of 2025, the GST Council revised the mandatory registration threshold upward: ₹50 lakhs annual turnover for goods (previously ₹40 lakhs) and ₹25 lakhs for services (previously ₹20 lakhs). This change is expected to benefit over 1.2 million small businesses that previously had to comply unnecessarily.

    That said, voluntary registration is often smart — it lets you claim input tax credit and signal credibility to B2B clients.

    What most founders miss: even if you’re below the threshold, registering voluntarily gives your business a GSTIN, which makes the Udyam registration process cleaner, and signals to larger buyers and marketplaces that you’re a formal business.

    You’ll need your PAN, Aadhaar, proof of business address, and bank account details to apply through the GST portal.

    The Composition Scheme is also worth knowing: businesses with turnover up to ₹2 crore can now file returns annually instead of quarterly, reducing compliance load significantly. If you’re an early-stage founder in Bengaluru or Mumbai running a product business, this can save you hours every quarter. Lawizer’s compliance team handles GST registration and filing — from application to return filing — fully online.

    How to Register a Startup in India: Step-by-Step Guide

    Step 2: MSME Udyam Registration — Your Compliance Multiplier

    MSME stands for Micro, Small, and Medium Enterprise — a classification under the MSMED Act, 2006. As of 1 April 2025, the revised thresholds under Notification S.O. 1364(E) are as follows:

    • Micro Enterprise: Investment up to ₹2.5 crore and annual turnover up to ₹10 crore
    • Small Enterprise: Investment up to ₹25 crore and annual turnover up to ₹100 crore
    • Medium Enterprise: Investment up to ₹125 crore and annual turnover up to ₹500 crore

    Both the investment and turnover conditions must be met at the same time. Exceed either, and you lose MSME classification — along with its benefits. Registration happens through the Udyam Registration portal and is completely free of cost. You’ll need your Aadhaar, PAN, and GSTIN. The certificate is valid indefinitely and doesn’t need annual renewal.

    A quick example: a D2C skincare startup in Kolkata with ₹15 lakh investment and ₹60 lakh annual turnover qualifies as a Micro Enterprise. Registering takes under 30 minutes online and immediately unlocks priority lending from banks, protection against delayed payments under the MSMED Act, and — crucially — the 50% trademark fee concession.

    What most founders miss: Udyog Aadhaar (the older system, discontinued in 2020) does not qualify for the trademark fee concession. You need the Udyam Registration Certificate specifically. If you registered under the old system, migrate on the Udyam portal before you file your trademark. You can complete your MSME Udyam registration through Lawizer’s guided process — document collection, form filling, and certificate in hand, fully online.

    Step 3: Trademark Registration — Protect What’s Yours at Half the Cost

    A trademark is the exclusive legal right to your brand name, logo, tagline, or any unique identifier — granted under the Trade Marks Act, 1999 and regulated by the CGPDTM (Controller General of Patents, Designs and Trade Marks) through the IP India portal. Here’s where your MSME certificate earns its keep.

    Trademark Fee: MSME vs. Non-MSME (2025)

    • With MSME/Udyam certificate: ₹4,500 per class (e-filing)
    • Without MSME (Pvt Ltd, LLP, Partnership): ₹9,000 per class (e-filing)

    That’s a straight 50% saving on government fees — applied at the time of filing, not as a reimbursement. You simply attach your Udyam certificate when submitting Form TM-A on the IP India portal. Let’s say you’re a food brand in Delhi filing under Class 29 (processed foods) and Class 30 (spices). With MSME: ₹4,500 × 2 = ₹9,000 in government fees. Without MSME: ₹9,000 × 2 = ₹18,000. Same protection, half the cost.

    The TM symbol (™) can be used from the day you file. The ® symbol is only permitted after the registration certificate is issued — typically 18 to 24 months after filing under 2025 timelines, subject to examination and opposition. Note: professional fees charged by trademark agents are subject to 18% GST. Always confirm whether a service provider’s quoted price is GST-inclusive or GST-exclusive. For end-to-end filing, explore Lawizer’s trademark registration service — class selection, filing, and objection response included.

    Trademark Registration in India

    The Right Order: What to Do First, Second, Third

    Sequence matters. Here’s the order that makes the most financial and legal sense:

    • First — Get GST registration. Even if voluntary, your GSTIN is needed for cleaner Udyam filing and signals business formality to banks and buyers.
    • Second — Get MSME Udyam registration. Free, takes under 30 minutes, and unlocks your 50% trademark fee concession. You need this certificate in hand before you file your trademark.
    • Third — File your trademark. With your Udyam certificate attached, you file at ₹4,500 per class instead of ₹9,000. Legal protection for your brand name dates back to the day of filing.

    The entire bundle — GST + MSME + Trademark — can be completed in under a week if your documents are in order. Documents you’ll need across the three: PAN card, Aadhaar card, bank account details, proof of business address, and a clear JPEG or PNG of your logo (for trademark filing).

    Frequently Asked Questions

    Q: Do I need GST registration before I can apply for MSME Udyam?

    A: GST registration is not strictly mandatory for Udyam registration, especially if your turnover is below the GST threshold of ₹50 lakhs (goods) or ₹25 lakhs (services). However, having a GSTIN makes the Udyam application smoother and more complete. Voluntarily registering for GST before filing Udyam is strongly recommended, especially if you plan to file a trademark next.

    Q: How much does the MSME trademark fee discount actually save me?

    A: The discount cuts the government filing fee from ₹9,000 to ₹4,500 per trademark class for MSME-registered businesses. If you’re filing in two classes — which most brands need for their name and logo — that’s a direct saving of ₹9,000. The concession is applied at the time of filing Form TM-A by attaching your Udyam Registration Certificate.

    Q: Can a private limited company get the MSME trademark fee discount?

    A: Yes — if the company holds a valid Udyam Registration Certificate and its investment and turnover fall within the MSME classification thresholds. Entity type alone doesn’t determine eligibility; the Udyam certificate does. A private limited company that qualifies as a small enterprise under the MSMED Act 2006 is entitled to the ₹4,500 e-filing rate per class.

    Q: What happens if I file a trademark without MSME registration?

    A: You pay the full ₹9,000 government fee per class instead of ₹4,500. There’s no way to claim a retroactive refund on this difference after filing. Get your Udyam certificate first — it’s free, fast, and the savings on trademark fees alone justify the effort.

    Q: How long does the entire GST + MSME + Trademark bundle take?

    A: GST registration typically takes 7–10 working days after document submission. Udyam registration is almost instantaneous — the certificate is generated on the same day in most cases. Trademark filing can be done within a day of Udyam certificate receipt. The TM symbol is available from the day you file. Full trademark registration takes 18–24 months depending on examination and opposition, but your legal rights date back to the filing date.

    Q: Is there any government subsidy for MSME trademark fees beyond the 50% discount?

    A: Yes. The MSME IPR (Intellectual Property Rights) scheme provides reimbursement of 50% of the official filing fee actually paid, up to a specified ceiling. This is separate from the reduced fee concession and is not automatic — you need to submit a separate application with your fee receipt. Many founders miss this because they aren’t aware it exists. Check the MSME Ministry’s current scheme notifications for the latest ceiling amounts.

    Ready to complete your compliance bundle in one go?
    Lawizer’s experts handle everything — GST registration, MSME Udyam filing, and trademark registration — fully online, starting at just ₹999. No CA visit needed.

    Get your GST + MSME + Trademark bundle done today →

  • How to Register a Startup in Kolkata & West Bengal: Local Guide

    How to Register a Startup in Kolkata & West Bengal: Local Guide

    West Bengal now has over 5,240 DPIIT-recognised startups — including 2,728 women-led ones — and Kolkata is at the centre of it all. But most founders waste weeks asking the wrong questions: “Do I need a trade licence first?” “Will SPICe+ work for a Kolkata address?” “What’s Startup Bengal and do I actually need it?” This guide answers all of that, in order.

    Skip the generic advice. Here’s exactly how startup registration works when your office is in Salt Lake, Park Street, or Howrah.

    📌 TL;DR: Startup registration in Kolkata follows the national SPICe+ route on MCA21, but West Bengal adds its own layer — Startup Bengal recognition, Professional Tax enrolment, a trade licence from KMC (Kolkata Municipal Corporation), and Shops & Establishments registration if you have employees. Most founders can complete the full stack in 15–20 business days. Lawizer handles the entire process online, without a single CA visit.

    What You’ll Learn

    • Which business structure suits your Kolkata startup (Private Limited, LLP, or OPC)
    • How to use SPICe+ on MCA21 to incorporate your company with a West Bengal address
    • How to get DPIIT recognition and unlock Startup India tax benefits
    • West Bengal-specific registrations — trade licence, Professional Tax, Startup Bengal
    • The exact document checklist for Kolkata founders

    Step 1: Choose the Right Business Structure for Your Kolkata Startup

    Here’s the thing — the structure you pick on Day 1 affects your taxes, your ability to raise funding, and your compliance burden for years. Most Kolkata founders building scalable, investor-ready ventures go with a Private Limited Company under the Companies Act 2013. It’s the gold standard if you plan to onboard co-founders with equity, approach VCs, or eventually list. You can incorporate your startup online through Lawizer without visiting a CA’s office in Dalhousie.

    Let’s break this down by the three most common choices:

    • Private Limited Company: Best for funded startups, tech ventures, and businesses expecting external investors. Requires minimum 2 directors and 2 shareholders. Kolkata-based examples: Wow! Momo, SastaSundar.
    • LLP (Limited Liability Partnership): Good for professional service firms, consultancies, and small creative agencies. Lower compliance burden than a Pvt Ltd, but VCs generally won’t invest in an LLP.
    • OPC (One Person Company): Ideal for solo founders with revenue under ₹2 crore. Only one director and shareholder required — a solid choice for freelancers formalising into a company.

    What most founders miss: your registered office address must be a valid Kolkata or West Bengal address from Day 1. A utility bill or rent agreement in the company’s name (or a NOC from the property owner) is mandatory for MCA21 filing.

    Step 2: Incorporate via SPICe+ on MCA21 (The National Route)

    SPICe+ (Simplified Proforma for Incorporating Company Electronically Plus) is the Ministry of Corporate Affairs online form that handles company incorporation, DIN (Director Identification Number), PAN, TAN, EPFO, ESIC, and GST registration — all in one integrated filing. It’s the same portal whether you’re in Bengaluru or Bowbazar.

    Here’s what you need before you start the SPICe+ filing for a Kolkata company:

    • DSC (Digital Signature Certificate) for all proposed directors — obtain from MCA-empanelled agencies, typically takes 1–2 days
    • DIN for each director (generated automatically through SPICe+ if directors are new)
    • Proposed company name — run a name availability check on MCA21 first; avoid names similar to existing registered companies
    • MoA (Memorandum of Association) and AoA (Articles of Association) — your CA or Lawizer drafts these
    • Proof of registered office in West Bengal — electricity bill, rent agreement, or NOC from owner
    • PAN and Aadhaar of all directors and subscribers

    The short answer on timelines: a Kolkata Private Limited Company typically gets its Certificate of Incorporation within 8–10 business days of complete SPICe+ submission, per standard MCA processing.

    SPICe plus form vs SPICe: Key Differences & Benefits | LegalWiz.in

    Step 3: Get DPIIT Recognition Under Startup India

    Incorporation makes you a company. DPIIT (Department for Promotion of Industry and Internal Trade) recognition makes you a startup — legally. And the difference matters. Startup India’s DPIIT recognition unlocks a 3-year income tax exemption under Section 80-IAC of the Income Tax Act, exemption from Angel Tax under Section 56(2)(viib), faster patent filing at 80% reduced fee, and self-certification under six labour laws.

    To qualify, your company must: be incorporated as a Private Limited Company, LLP, or Partnership Firm; be less than 10 years old; have annual turnover not exceeding ₹100 crore in any prior year; and be working toward innovation, development, or improvement of a product or service. Apply directly on the Startup India portal — it’s free and typically processed within 2–5 business days.

    Documents needed for DPIIT recognition

    • Certificate of Incorporation from MCA
    • PAN of the entity
    • Brief description of the business and innovation (written in the application form)
    • Website URL or pitch deck (optional but recommended)

    West Bengal-Specific Registrations You Can’t Skip

    This is where Kolkata founders get tripped up. The national SPICe+ process gives you a company — but West Bengal has its own layer of state-level compliance that’s mandatory the moment you hire staff or operate from a physical office.

    1. Trade Licence from KMC or Local Body

    If your office is within Kolkata Municipal Corporation limits (most of central and south Kolkata), you need a trade licence from KMC before commencing operations. Apply online through the KMC e-portal. The licence fee varies by business type and premises size. Failure to obtain one can result in notices and fines during inspections.

    2. West Bengal Shops and Establishments Act Registration

    Any startup with employees working from a West Bengal office must register under the West Bengal Shops and Establishments Act. Apply through the state labour department’s online portal. This registration governs working hours, leave policies, and employee welfare — inspectors do check for it.

    3. Professional Tax (PT) Enrolment

    Professional Tax is a state-level tax levied on salaried employees and self-employed professionals in West Bengal. Once your startup has employees drawing salaries above the prescribed threshold, you must enrol as an employer with the West Bengal PT authority and deduct PT from employee salaries monthly. Enrolment is done via the state’s online portal.

    4. Startup Bengal Recognition

    Startup Bengal — an initiative of the Government of West Bengal — operates a State Startup Resource Centre in Kolkata and 23 Acceleration Centres across districts. Registering with Startup Bengal gives you access to incubation space, seed funding, mentorship networks, and state-level angel investor connections. It’s separate from DPIIT recognition and free to apply for.

    5. GST Registration

    GST registration is mandatory if your annual turnover exceeds ₹20 lakh (₹10 lakh for certain special category states — West Bengal is not one). It’s also required immediately if you sell products across state lines or operate on marketplaces like Flipkart, Meesho, or Amazon India. Apply on the GSTN portal — your GSTIN will carry the state code 19 for West Bengal.

    6. MSME Udyam Registration

    Even if your startup qualifies as a micro, small, or medium enterprise under the MSMED Act 2006, MSME Udyam registration is free and unlocks priority sector lending, government tender preference, and protection against delayed payments. Most early-stage Kolkata startups qualify. The Udyam portal is entirely self-service and needs only your Aadhaar and PAN.

    Complete Document Checklist for Kolkata Founders

    A quick example of how delays happen: one missing utility bill — or a bill in the landlord’s name without a NOC — stalls your entire SPICe+ submission. Keep this list ready before you begin.

    • PAN card and Aadhaar of all directors/subscribers
    • Passport-size photographs of all directors
    • Address proof of all directors (Aadhaar / voter ID / passport)
    • Proof of registered office in Kolkata/West Bengal — electricity bill (not older than 2 months) plus either a rent agreement or NOC from the property owner
    • DSC (Class 3) for all directors — obtained before filing
    • Proposed company name (1st and 2nd preference)
    • Brief description of business activity and main object clause for MoA
    • Authorised capital amount and shareholding split among subscribers
    Startup India Registration: Step-by-Step Guide to Eligibility, Documents & More

    Frequently Asked Questions

    Q: How long does startup registration in Kolkata actually take?

    A: Company incorporation via SPICe+ on MCA21 takes 8–10 business days once all documents are submitted correctly. DPIIT recognition under Startup India takes an additional 2–5 business days. State-level registrations like trade licence and Professional Tax enrolment add another 3–7 days. In total, a fully compliant Kolkata startup — company + DPIIT + GST + trade licence — can be set up in 15–20 business days.

    Q: Do I need a physical office in Kolkata to register my company there?

    A: Yes — MCA21 requires a valid registered office address in West Bengal at the time of SPICe+ filing. You need either a rent agreement plus NOC from the owner, or an electricity/utility bill showing the address. Many early-stage founders use a co-working space address in Salt Lake or New Town; this is fully acceptable as long as you have a written agreement from the co-working operator.

    Q: Is Startup Bengal registration the same as DPIIT recognition?

    A: No — these are two separate registrations. DPIIT recognition is a central government program run through the Startup India portal and unlocks national benefits like income tax exemption and Angel Tax exemption. Startup Bengal is a West Bengal state government initiative that provides access to state-level incubation centres, seed funding, mentorship, and local investor networks. Both are free to apply for and both are worth doing.

    Q: Does a Kolkata startup need to pay Professional Tax?

    A: Yes, if you have employees drawing salaries in West Bengal. Professional Tax is a state-level levy and West Bengal is among the states that enforce it actively. As an employer, you must enrol with the West Bengal PT authority, deduct the applicable PT from employee salaries, and remit it monthly. The company itself may also be liable for a nominal annual PT as a registered entity operating in the state.

    Q: Can I register a company in Kolkata if I’m based in another city?

    A: Yes. Directors do not need to be physically present in Kolkata — but at least one director must be a resident of India (resident means spending 182 days or more in India in the previous calendar year, not necessarily in Kolkata). The registered office address, however, must be a verifiable West Bengal address. Foreigners can also be directors as long as one resident Indian director is on the board.

    Q: What are the main costs of registering a Private Limited Company in Kolkata?

    A: Government fees on MCA21 depend on your authorised capital — companies with authorised capital up to ₹15 lakh pay nominal stamp duty and ROC filing fees under West Bengal’s stamp duty schedule. DSC procurement for two directors typically costs ₹1,000–₹2,000. Professional or platform fees vary. Lawizer offers end-to-end Private Limited Company registration fully online, including DIN, DSC, PAN, TAN, and incorporation certificate.

    Ready to register your Kolkata startup — the right way?
    Lawizer’s experts handle everything — company incorporation, DPIIT recognition, GST registration, and MSME Udyam — fully online, starting at just ₹1,499. No CA visit needed.

    Start Your Startup Registration on Lawizer →

  • MSME Udyam Registration: Benefits, Eligibility & How to Register Free?

    MSME Udyam Registration: Benefits, Eligibility & How to Register Free?

    Over 7.30 crore enterprises have registered on the Udyam platform since July 2020 — and the ones that haven’t are leaving collateral-free loans, government tenders, and tax benefits on the table. MSME Udyam Registration is free, paperless, and takes under 30 minutes. Yet thousands of small business owners in Mumbai, Kolkata, Bengaluru, and beyond still skip it, either because they think they don’t qualify or assume the process is complicated.

    It isn’t. Here’s everything you need to know.

    📌 TL;DR: MSME Udyam Registration is the Government of India’s free, online process for recognising Micro, Small, and Medium Enterprises under the MSMED Act, 2006. As of April 2025, revised limits now qualify more businesses than ever — Micro up to ₹10 crore turnover, Small up to ₹100 crore, Medium up to ₹500 crore. Registered businesses get access to collateral-free loans, priority government tenders, trademark and patent subsidies, and protection against delayed buyer payments. You can complete the entire process at udyamregistration.gov.in at zero cost. Lawizer’s experts can guide you through the process if you need help.

    What You’ll Learn

    • Who qualifies for Udyam Registration under the revised 2025 limits
    • The full list of financial and legal benefits for registered MSMEs
    • A step-by-step walkthrough of the registration process on the official portal
    • What documents you need and common mistakes to avoid

    What Is MSME Udyam Registration and Why Does It Exist?

    Udyam Registration is the official government process — managed by the Ministry of Micro, Small and Medium Enterprises (MSME) — through which a business gets formally recognised as a Micro, Small, or Medium Enterprise under the MSMED Act, 2006 (the Micro, Small and Medium Enterprises Development Act).

    It replaced the older Udyog Aadhaar system in July 2020, and the upgrade was significant: the new system integrates your Aadhaar and PAN directly with government databases, meaning no document uploads, no physical visits, and no fees.

    Here’s the thing: MSME status isn’t just a label. It is a legal identity that unlocks a specific set of rights — from priority bank lending to protection against buyers delaying payments beyond 45 days. Without it, you’re running your business with one hand tied behind your back.

    Whether you’re a manufacturer in Pune, a service provider in Chennai, or a trader in Delhi, if your business falls within the defined limits, you qualify. And since July 2021, even retailers and wholesalers are eligible.


    Revised MSME Classification Limits: Are You Eligible?

    The Union Budget 2025 made the single biggest revision to MSME definitions since the system launched. Effective 1 April 2025, investment limits were increased by 2.5 times and turnover limits were doubled. This means lakhs of businesses that previously didn’t qualify now do — and existing registrations were upgraded automatically without any re-registration.

    Here’s how the three categories break down under the revised classification (both conditions — investment AND turnover — must be satisfied):

    Micro Enterprise: Investment up to ₹2.5 crore AND annual turnover up to ₹10 crore
    Small Enterprise: Investment up to ₹25 crore AND annual turnover up to ₹100 crore
    Medium Enterprise: Investment up to ₹125 crore AND annual turnover up to ₹500 crore

    What most founders miss: the classification uses composite criteria. If your turnover crosses the ceiling for your category — even if your investment hasn’t — you automatically move up. All units operating under a single PAN are aggregated when calculating these thresholds, so if you run multiple businesses, plan accordingly.

    A quick example: a Bengaluru-based SaaS firm with ₹8 crore invested in servers and ₹40 crore annual turnover qualifies as a Small Enterprise — eligible for the full suite of MSME benefits, including the enhanced credit guarantees introduced in Budget 2025-26.

    All business types are eligible: proprietorships, partnership firms, LLPs, private limited companies, public limited companies, HUFs, co-operative societies, trusts, and producer companies. Manufacturing, services, trading — all covered. The only entities that don’t qualify are those that exceed the Medium Enterprise ceilings (investment above ₹125 crore or turnover above ₹500 crore) and non-business entities like NGOs or government departments.

    New MSME classification criteria announced in Union Budget 2025-26 | Current Affairs | Vision IAS

    Key Benefits of MSME Udyam Registration in 2025–26:

    This is where registration pays for itself many times over. Let’s break this down by category.

    Financial and Credit Benefits

    The biggest draw for most businesses is access to institutional credit they’d otherwise struggle to get. Udyam-registered MSMEs are eligible for the Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE) — the government’s flagship scheme that allows banks to extend collateral-free loans up to ₹5 crore for micro and small enterprises, with the credit guarantee cover for micro enterprises doubled to ₹10 crore in Budget 2025.

    Loans under the MUDRA scheme (Micro Units Development and Refinance Agency) are also accessible, and banks are mandated to offer concessional interest rates to registered MSMEs. The new ME-Card — a customised credit card with a ₹5 lakh limit for Udyam-registered Micro Enterprises — was introduced in Budget 2025, with 10 lakh cards planned in the first year.

    Government Procurement Advantages

    Under the Public Procurement Policy, 25% of all Central Government procurement must come from MSMEs, with an additional 4% reserved for SC/ST-owned enterprises and 3% for women-owned enterprises. On GeM (Government e-Marketplace), Udyam-registered businesses get preferential access, exemption from Earnest Money Deposits (EMD), and are shortlisted for MSE-specific tenders with relaxed eligibility criteria.

    For any business wanting to supply to government departments, PSUs, railways, or defence establishments, Udyam registration is the baseline requirement.

    IP and Certification Subsidies

    This one surprises most founders. Registered MSMEs are eligible for up to 80% subsidy on patent filing fees and significant reimbursements on trademark registration and ISO certification costs. If you’re building a brand or a product and haven’t registered as an MSME, you’re paying full price for protections the government wants to help you afford. You can explore trademark registration for your startup through Lawizer’s MSME registration services.

    Protection Against Delayed Payments — Section 43B(h)

    The MSMED Act gives registered MSMEs a legal shield that unregistered businesses simply don’t have. Buyers are legally required to pay registered Micro and Small Enterprises within 45 days of delivery (or within the agreed credit period, whichever is shorter). If they don’t, the overdue amount attracts compound interest at three times the RBI’s bank rate.

    Under Section 43B(h) of the Income Tax Act (as amended), buyers cannot claim a tax deduction on payments to MSMEs made beyond 45 days — giving you real negotiating power. This protection is only available to registered businesses.

    Tax and Compliance Benefits

    Registered MSMEs get extended carry-forward of Minimum Alternate Tax (MAT) credit — up to 15 years instead of the standard 10. Several state governments offer additional incentives: electricity tariff subsidies, stamp duty exemptions on property transactions, and interest subvention schemes. These vary by state, so it’s worth checking with your state’s Directorate of Industries.

    Udyam Registration Kaise Kare? Full Step-by-Step Guide - FormSamajh

    How to Register for Udyam Online — Step by Step

    The registration process is entirely self-declaration based. You don’t upload any documents. The portal pulls your investment and turnover data directly from your Income Tax and GST filings. Here’s the complete process:

    Step 1 — Visit the Official Portal
    Go to udyamregistration.gov.in — the only government-authorised portal for Udyam Registration. Be careful: dozens of private websites charge fees for this process. The official portal is free.

    Step 2 — Choose the Right Application Type
    If you’re a new enterprise with no prior registration: select “For New Entrepreneurs who are not Registered yet as MSME or those with EM-II.”
    If you had a prior Udyog Aadhaar or EM-II registration: select the migration option to convert it.

    Step 3 — Enter Your Aadhaar Details
    The applicant’s Aadhaar number and name (as on the Aadhaar card) are required. For proprietorships, use the owner’s Aadhaar. For companies, partnerships, or LLPs, use the authorised signatory’s Aadhaar. OTP verification via registered mobile completes this step.

    Step 4 — Fill in PAN and Business Details
    Enter your PAN, business name, type of organisation, date of commencement, bank account details, and your main business activity (manufacturing or services). Select the appropriate NIC (National Industry Classification) 2008 code that matches your core business.

    Step 5 — Submit Investment and Turnover Details
    Enter investment in plant and machinery (or equipment) and annual turnover. The portal cross-verifies this against your ITR and GST filings automatically. No proof needs to be uploaded.

    Step 6 — Submit and Receive Your Udyam Registration Certificate
    After submission, you receive a unique 12-digit Udyam Registration Number (URN) and a digital e-certificate with a QR code. This certificate has lifetime validity — no renewal required. You can also store it in DigiLocker, and it’s legally recognised under the IT Act, 2000.

    What most founders miss: your Udyam classification is auto-recalculated every financial year based on the ITR and GST data you file. If your turnover grows and you cross a category ceiling, reclassification happens automatically. You don’t need to re-register, but you should check your Udyam portal status annually.


    Common Mistakes to Avoid

    • Let’s be direct about what goes wrong most often.
    • Registering on a private paid portal instead of udyamregistration.gov.in — the government portal is free, and there is no official fee whatsoever.
    • Entering NIC codes incorrectly — mismatched activity codes can cause verification issues when applying for tenders or schemes that require specific sector codes.
    • Mixing up Udyam with Udyog Aadhaar — if you have an old Udyog Aadhaar registration (valid till March 2021), it must be migrated to Udyam to continue accessing benefits. Unmigrated registrations are now considered inactive.
    • Not updating annually — failure to update your turnover and investment details on the Udyam portal can result in your status being marked inactive, cutting off access to schemes.
    • If you want a professional to handle the application and verify all details are accurate, Lawizer’s team can assist with your MSME Udyam Registration fully online — no CA visit required.

    Frequently Asked Questions

    Q: Is Udyam Registration really free, or are there hidden charges?

    A: Udyam Registration is completely free on the official government portal at udyamregistration.gov.in. There are no government fees, no charges for the certificate, and no renewal costs. The certificate has lifetime validity. If any website is asking you to pay for Udyam Registration, it is a private consultancy, not the government. You are not required to use any paid service for this process.

    Q: What documents do I need to register on the Udyam portal?

    A: You don’t upload any documents. The Udyam Registration process is entirely self-declaration based, and the portal cross-verifies your data directly against your Aadhaar, PAN, ITR, and GST records. You will need your Aadhaar number (with OTP access on the linked mobile), PAN card, business bank account details, and your approximate investment in plant and machinery or equipment. That’s it.

    Q: I already had Udyog Aadhaar. Do I need to re-register on Udyam?

    A: Yes, you need to migrate. Udyog Aadhaar registrations became invalid after March 31, 2021. To continue accessing MSME benefits — including loans, government tenders, and subsidies — you must migrate your registration to the Udyam portal. The migration option is available on udyamregistration.gov.in and the process is straightforward. Existing registrations that were migrated also automatically benefit from the revised 2025 limits without re-registration.

    Q: Can a private limited company or LLP register as an MSME?

    A: Yes. Any business entity — proprietorship, partnership firm, LLP, private limited company, public limited company, HUF, co-operative society, or trust — that falls within the investment and turnover limits can register under Udyam. For companies and LLPs, the authorised signatory’s Aadhaar is used for the application. All units of the same enterprise operating under a single PAN are treated as one entity when calculating the thresholds.

    Q: What is Section 43B(h) and how does it protect registered MSMEs?

    A: Section 43B(h) of the Income Tax Act (effective from April 1, 2024) disallows buyers from claiming a tax deduction on payments made to Micro and Small Enterprises beyond 45 days. This means that if your buyer delays payment, they lose their tax deduction — giving registered MSMEs significant legal and financial leverage over large buyers and corporates. This protection applies only to businesses registered under Udyam as Micro or Small Enterprises. Unregistered businesses have no such recourse.

    Q: What happens if my business grows and crosses the MSME limits?

    A: Your Udyam classification is automatically recalculated every financial year based on the ITR and GST returns you file. If your investment or turnover crosses the ceiling for your current category — say you cross ₹100 crore turnover as a Small Enterprise — you’re automatically reclassified as a Medium Enterprise. If you eventually cross the Medium ceiling (₹500 crore turnover or ₹125 crore investment), your MSME status lapses and you lose access to MSME-specific schemes going forward. You don’t need to manually update this; the portal handles it automatically.


    Ready to Get Your Udyam Certificate?

    Lawizer’s experts handle everything — MSME Udyam Registration, compliance filing, and GST registration — fully online, starting at just ₹499. No CA visit needed.

    Get Your MSME Registration Done Today →

  • Trademark Registration in India: Cost, Process, and Timeline.

    Trademark Registration in India: Cost, Process, and Timeline.

    Over 5.5 lakh trademark applications were filed in India in FY 2024–25 — a 20% jump from the previous year, according to the CGPDTM’s own Annual Report. That number tells you something: founders across Bengaluru, Mumbai, Delhi, and Kolkata have figured out that a brand without a registered trademark is a brand anyone can copy.

    Here’s the thing. Most founders assume trademark registration is expensive, slow, or something to sort out “later.” This guide will show you exactly why later is the wrong answer — and precisely what it costs, how the process works, and how long you’re actually looking at.

    📌 TL;DR: Trademark registration in India costs ₹4,500 per class for individuals and startups, and ₹9,000 per class for companies and LLPs, under the Trade Marks Act, 1999. The full process — from filing on the CGPDTM portal to receiving your registration certificate — takes 12 to 18 months under standard examination, or under a year with expedited processing. Lawizer’s trademark service handles the entire filing and follow-up online, with no CA visit required.

    What You’ll Learn

    • Exactly what trademark registration costs in 2025, broken down by applicant type
    • The step-by-step process from trademark search to certificate issuance
    • How long each stage takes — and how to speed things up
    • What TM ™ vs ® actually means for your brand legally
    • The most common mistakes founders make when filing

    [H2] What Is a Trademark — and Why Does Registration Matter?

    A trademark is any mark — a name, logo, slogan, colour, or even a sound — that distinguishes your goods or services from someone else’s. Think of the word “Swiggy,” the orange of Zomato’s branding, or the tagline “Daag Acche Hain.” These aren’t just design choices; they’re legally protected assets.

    Under the Trade Marks Act, 1999 (the primary statute governing trademarks in India), registration gives you exclusive rights to use that mark for the goods or services in the class you’ve registered it under. Without registration, you technically have some common law rights if you’ve been using the mark long enough — but enforcing them is expensive, uncertain, and practically very difficult. A registered trademark, on the other hand, lets you sue for infringement directly, seek damages, and even have customs authorities block counterfeit imports at the border.

    What most founders miss: the TM symbol (™) you see on unregistered marks is just a claim of ownership — it has no legal backing. The ® symbol, which stands for “Registered Trademark,” is what you’re entitled to use only after your mark is officially registered by the Registrar of Trade Marks under the CGPDTM (Controller General of Patents, Designs and Trade Marks). Using ® before registration is actually a criminal offence under Section 107 of the Trade Marks Act.

    Another thing worth knowing: trademark protection lasts 10 years from the date of filing and is renewable indefinitely every decade. It doesn’t expire the way some founders assume it does.


    Trademark Registration Cost in India (2025)

    Let’s break this down. The government fee structure is straightforward — it’s the professional fee that varies depending on who you go to.

    Government Fees (Official, 2025)

    For Individuals, Startups, and Small Enterprises (proprietorships, partnership firms, or companies registered under the Startup India scheme): ₹4,500 per class, per application, when filed online. The physical filing fee is ₹5,000.

    For Companies, LLPs, and other entities that don’t qualify as startups or small enterprises: ₹9,000 per class, per application, when filed online. The physical filing fee is ₹10,000.

    The word “class” here is important. Trademarks in India are categorised into 45 classes under the Nice Classification system — Classes 1 to 34 cover physical goods, and Classes 35 to 45 cover services. If your business spans multiple categories — say, you sell clothing (Class 25) and also run an online retail platform (Class 35) — you need separate applications and separate fees for each class.

    Professional Fees

    Professional fees from trademark agents or online legal services typically range from ₹1,500 to ₹8,000 per application, depending on the complexity of your case and the service provider. Adding professional fees to the government fee, most founders registering a single-class trademark end up paying between ₹6,000 and ₹17,000 all-in.

    A quick example: a Bengaluru-based SaaS startup registering its brand name under Class 42 (software services) through Lawizer’s online trademark registration service would pay the ₹4,500 government fee plus a professional fee — no office visits, no notarised affidavits required upfront.

    It’s worth noting that some services advertise very low prices by separating out “additional” fees — always check whether the quoted price includes the government fee or is over and above it.

    How to Start a Startup in India: Step-by-Step Guide for New Entrepreneurs

    The Trademark Registration Process in India — Step by Step

    The entire process runs through the CGPDTM’s online portal at ipindia.gov.in. Here’s what each stage looks like.

    Step 1: Trademark Search

    Before you file, you need to check whether a similar or identical mark already exists in your class. You can do this for free on the Trade Marks Registry’s public search tool at ipindiaonline.gov.in. Search for your proposed name, logo, or tagline across the relevant class. This step saves you from filing an application that’s likely to be rejected at examination. A professional trademark search also looks for phonetically similar marks — not just exact matches — which is where most amateur searches fall short.

    Step 2: Filing the Application

    Applications are filed online via the CGPDTM portal using Form TM-A. You’ll need to provide the applicant’s details, a representation of the mark (logo file in JPEG format if it’s a device mark), the relevant class or classes, and a description of the goods or services. For startups, you’ll also need a certificate or declaration confirming your startup status to access the lower government fee. Once the application is submitted and the fee is paid, you receive an official filing receipt with your application number. From this point, you’re entitled to use the TM symbol next to your brand.

    Step 3: Examination

    After filing, the application is assigned to a trademark examiner at one of the five Trade Marks Registry offices — Mumbai (the head office), Delhi, Kolkata, Chennai, or Ahmedabad. The examiner reviews the mark for absolute grounds of refusal (marks that are descriptive, generic, or offensive) and relative grounds (conflict with existing registered or pending marks). An examination report is typically issued within a few months. If the examiner raises objections, you have one month to file a written reply. If the reply doesn’t satisfy the examiner, a hearing is scheduled.

    Step 4: Publication in the Trade Marks Journal

    If the mark clears examination (or after objections are resolved), the application is published in the Trade Marks Journal — the official weekly gazette of the Trademark Registry. This is a public notice period. Any third party who believes your mark conflicts with theirs has four months from the date of publication to file a Notice of Opposition.

    Step 5: Opposition (if any)

    If an opposition is filed, the Registry initiates opposition proceedings, which can be lengthy. Both parties submit evidence, file counter-statements, and may be called for hearings. Opposed applications can add a year or more to the overall timeline. If no opposition is filed within the four-month window, the application proceeds automatically.

    Step 6: Registration

    Once the opposition window passes without challenge (or if any challenge is successfully defeated), the Registrar issues the Registration Certificate. Your mark is now a registered trademark, indicated by the ® symbol, valid for 10 years from the original application date.


    Trademark Registration Timeline — What to Realistically Expect

    Here’s where a lot of founders get frustrated. The formal timeline sounds short on paper; the practical reality is longer.

    Under standard processing, the total time from filing to registration is typically 12 to 18 months if the application is uncomplicated — no objections at examination, no opposition during publication.

    In 2024 and 2025, however, the Trade Marks Registry faced significant staff shortages and administrative backlogs, which pushed examination timelines out considerably. Many applications filed in 2024 are still at the examination stage as of mid-2026.

    The good news: there’s a legal mechanism to speed this up. Under Rule 39 of the Trade Marks Rules, 2017, you can file for expedited examination by paying an additional fee. With expedited processing, examination typically happens within a few weeks — sometimes under a month — and the overall timeline to registration can come down to under a year, assuming no opposition.

    Let’s break this down stage by stage:

    • Trademark Search: 1 to 3 days (you can do it yourself for free, or get a professional search report within 24–48 hours)
    • Filing and receipt of application number: Same day (online filing is instant on the CGPDTM portal)
    • Examination and issuance of examination report: 3 to 6 months under standard processing; a few weeks under expedited
    • Response to examination objections (if raised): 1 month from date of report, extendable in some cases
    • Publication in the Trade Marks Journal: 1 to 3 months after acceptance
    • Opposition window: 4 months from the date of publication (mandatory waiting period)
    • Registration and certificate issuance: 1 to 2 months after the opposition window closes without a challenge
    • Total (uncomplicated application, standard processing): 12 to 18 months
    • Total (expedited, no opposition): 6 to 10 months

    One important point: from the moment you file, your trademark protection is backdated to the filing date. Even if registration takes 18 months, your rights are counted from Day 1. This is why filing early matters — and filing with accurate details matters even more.

    Document legalisation and certification - Lawfinity Solicitors

    Documents Required for Trademark Registration

    The documentation list for online trademark filing is shorter than most founders expect.

    For all applicants: a clear representation of the trademark (a JPEG file of the logo, or the word mark written out), the list of goods or services the mark covers, and the applicant’s name and address.

    For individuals and sole proprietorships: a copy of the applicant’s identity proof (Aadhaar, PAN, or passport).

    For companies and LLPs: incorporation certificate and authorisation letter or board resolution authorising the filing.

    For startups claiming the concessional ₹4,500 fee: a DPIIT (Department for Promotion of Industry and Internal Trade) recognition certificate under the Startup India scheme, or an MSME Udyam Registration Certificate.

    If you’re appointing a trademark agent or legal service to file on your behalf, you’ll also need to sign a Power of Attorney (Form TM-48), which is a straightforward one-page document.

    No notarisation is required for online filings, and you don’t need to submit original documents — scanned copies are accepted on the portal.


    Common Mistakes Founders Make — and How to Avoid Them

    Choosing a descriptive mark. A mark like “BestShoes.in” or “QuickDeliver” will almost certainly be rejected at examination because it merely describes the product or service. A trademark needs to be distinctive — either invented (like “Infosys” or “Flipkart”) or suggestive in a non-obvious way. If your proposed brand name describes exactly what you do, consider modifying it before filing.

    Filing in the wrong class. This is a costly error. If you run a food delivery platform and only register in Class 30 (food products) but not Class 43 (restaurant services) or Class 35 (advertising and business services), you’re not fully protected. Worse, you’ll have to file fresh applications and pay fresh fees to cover the missed classes — and competitors could potentially register in those classes before you do.

    Not filing early enough. Some founders wait until their business is generating revenue before registering. This is backwards. The earlier you file, the earlier your protection date. A competitor who files the same mark a week before you does gets priority, even if you’ve been using the name longer (with some common law exceptions).

    Ignoring the examination report. The Registry doesn’t chase you. If you miss the one-month window to respond to an examination report, your application is treated as abandoned. Set calendar reminders from the day you file — or work with a service provider who tracks this on your behalf.

    Filing without a prior art search. Skipping the search and filing directly is a gamble. A conflict with an existing mark doesn’t just result in rejection — it can also mean an opposition proceeding if the existing mark holder files against you, which can be expensive to defend.


    Frequently Asked Questions

    Q: How much does trademark registration cost in India in 2025?

    A: The government fee for trademark registration in India is ₹4,500 per class for individuals, startups, and small enterprises when filing online, and ₹9,000 per class for companies and LLPs. Adding professional or service fees, the all-in cost typically ranges from ₹6,000 to ₹17,000 per class depending on the service provider you use. Startups recognised under the DPIIT’s Startup India programme and MSME Udyam holders are eligible for the lower ₹4,500 rate.

    Q: How long does trademark registration take in India?

    A: Trademark registration in India takes 12 to 18 months under standard processing, assuming no examination objections and no opposition during the public notice period. With expedited examination (available under Rule 39 of the Trade Marks Rules, 2017), the overall timeline can be reduced to 6 to 10 months. Complications like an examiner’s objection or a third-party opposition can extend the timeline significantly — in some contested cases, the process can take 2 to 3 years.

    Q: Can I use the ™ symbol before my trademark is registered?

    A: Yes — you can use the TM (™) symbol as soon as you file your trademark application, or even if you’re simply claiming ownership of an unregistered mark. However, you can only use the ® (Registered Trademark) symbol after your application has been fully processed and a registration certificate has been issued by the Trade Marks Registry. Using ® before registration is an offence under Section 107 of the Trade Marks Act, 1999.

    Q: What classes should I register my trademark under?

    A: The class you register under depends on the nature of your business. Trademarks in India follow the Nice Classification system, which divides goods and services into 45 classes. Software and technology companies typically file under Class 42, retail businesses often need Class 35, food businesses may need Classes 29, 30, or 43, and apparel brands typically use Class 25. Many businesses need protection in more than one class. A trademark agent can help you identify the right classes for your specific business model before you file.

    Q: What happens if someone opposes my trademark application?

    A: If a third party files a Notice of Opposition within four months of your trademark’s publication in the Trade Marks Journal, the Registry initiates opposition proceedings. Both sides submit evidence, file counter-statements, and attend hearings before the Registrar. If your mark successfully survives the opposition, registration proceeds. If not, you may need to file a fresh application with amendments. Legal representation is strongly advisable in opposition proceedings.

    Q: Is trademark registration the same as copyright registration in India?

    A: No — trademark and copyright are different forms of intellectual property. A trademark protects brand identifiers like names, logos, and slogans in a specific class of goods or services. Copyright automatically subsists in original creative works (like written content, music, or software code) from the moment of creation, but registration under the Copyright Act, 1957 creates an official record of ownership and is useful in infringement proceedings. Most businesses need both — trademark protection for their brand identity and copyright protection for their creative output.


    Ready to protect your brand with a registered trademark?

    Lawizer’s experts handle the entire trademark registration process — from prior art search and application filing to examination responses and status tracking — fully online, starting at just ₹4,500 in government fees. No CA visit needed.

    👉 Start your trademark registration with Lawizer →

  • Private Limited vs LLP vs Sole Proprietorship: Which Is Best for Your Startup?

    Private Limited vs LLP vs Sole Proprietorship: Which Is Best for Your Startup?

    Over 1.38 lakh new companies were incorporated in India between April 2024 and March 2025 alone — and most of those founders had to make one decision before anything else: what kind of business should I actually register? The wrong answer doesn’t just cost you money. It can block investor funding, expose your personal assets to business debt, and make compliance a nightmare for years.

    Here’s the thing. Private Limited vs LLP vs Sole Proprietorship isn’t just a legal checkbox — it’s a strategic call that shapes how your startup grows, borrows, and gets valued.

    📌 TL;DR: In India, choosing between a Private Limited Company, LLP, and Sole Proprietorship comes down to three things — liability protection, funding eligibility, and compliance appetite. Private Limited Companies (registered under the Companies Act, 2013) are best for startups seeking investment and scale. LLPs (governed by the LLP Act, 2008) suit professional firms and small co-founders wanting lower compliance. Sole Proprietorships are fastest to set up but carry unlimited personal liability. Lawizer can help you register the right structure fully online.


    What You’ll Learn

    • The real legal and tax differences between all three structures
    • Which structure is eligible for Startup India benefits and VC funding
    • How annual compliance costs compare — with actual figures
    • A simple decision framework to pick the right structure for your business stage

    What Is a Sole Proprietorship — And When Does It Make Sense?

    A Sole Proprietorship is the simplest business form in India: one person owns and runs the business, and legally, the owner and the business are the same entity.

    There’s no separate registration process under a single law — you may register under Shops and Establishments Act, get a GST number, or simply operate with a trade licence depending on your state and business type. No MCA filing, no incorporation certificate.

    That simplicity is the appeal. A freelance designer in Bengaluru, a home-baker in Kolkata, or a neighbourhood retailer in Pune can start operating within days. Tax is filed on the owner’s personal ITR (Income Tax Return), and there are no mandatory audits if turnover stays within basic thresholds.

    What most founders miss: a Sole Proprietorship gives you zero liability protection. If your business is sued or runs up debt, creditors can come after your personal bank accounts, property, and savings.

    The business also has no “perpetual succession” — it doesn’t legally exist without you. And banks are often reluctant to extend significant credit without corporate-level documentation. This structure works fine for small freelancers and local traders, but it’s not a launchpad for a scalable startup.


    What Is an LLP — And Why Are More Founders Choosing It?

    An LLP — Limited Liability Partnership — is a hybrid structure introduced in India through the LLP Act, 2008, governed by the Ministry of Corporate Affairs (MCA). It blends the operational flexibility of a traditional partnership with the liability protection of a private company. Each partner’s liability is capped at their capital contribution, so personal assets are protected.

    LLP registration numbers jumped 40% to 86,476 in 2025-26, according to MCA data — a clear signal that founders are moving away from informal structures. And it’s easy to see why. An LLP is a separate legal entity, meaning it can hold assets, sign contracts, and sue or be sued in its own name.

    Annual compliance is lighter: no mandatory audit is required until turnover crosses ₹40 lakh, and annual filings to the MCA are simpler than those for a Private Limited Company. Maintenance cost runs roughly ₹10,000–₹20,000 per year.

    Let’s break this down further. An LLP needs a minimum of two Designated Partners, at least one of whom must be a resident of India. Profit-sharing is governed by the LLP Agreement, which gives partners enormous flexibility compared to the rigid share-structure of a company.

    However, LLPs cannot issue equity shares — which means venture capital and angel investment are essentially off the table. They also aren’t currently eligible for DPIIT recognition under the Startup India scheme, which limits tax exemption benefits.

    Best suited for: professional services firms (law, consulting, architecture), small co-founder teams, family businesses, and any setup where low compliance overhead matters more than fundraising.


    What Is a Private Limited Company — And Why Do Most Funded Startups Use It?

    A Private Limited Company (often called Pvt Ltd) is a separate legal entity registered under the Companies Act, 2013 with the Ministry of Corporate Affairs via the SPICe+ form (Simplified Proforma for Incorporating Company Electronically Plus — MCA’s online incorporation portal). It requires a minimum of two directors and two shareholders, though both roles can be held by the same individuals.

    The numbers tell the story. As of March 2025, over 1.73 million active private limited companies operate in India — and private limited companies account for more than three-fourths of all funded startups registered under DPIIT.

    Over 60% of the USD 64 billion in private equity and venture capital that flowed into India in FY 2024-25 went into private limited companies. The reason is structural: a Pvt Ltd can issue equity shares, which is the currency of startup investment.

    A quick example: if a Mumbai-based SaaS founder wants to raise a seed round from an angel network, only a Private Limited Company structure allows her to issue shares in exchange for capital. An LLP can’t do that. A Sole Proprietorship certainly can’t.

    The Ministry of Corporate Affairs officially lists Private Limited Companies as eligible for DPIIT recognition, which unlocks Startup India benefits including a three-year income tax holiday under Section 80-IAC and access to the Fund of Funds for Startups (FFS) managed through SIDBI.

    Annual compliance is more demanding — statutory audit regardless of turnover, annual ROC filings, board meeting minutes, and more — with maintenance costs typically between ₹30,000 and ₹50,000 per year.

    But for a startup that plans to raise money, hire, and scale, this is the structure built for growth. You can register your company with Lawizer’s company incorporation service fully online, without visiting a CA.

    Private Ltd vs LLP vs Sole Proprietorship India Guide

    Side-by-Side: The Key Differences That Actually Matter

    Let’s put the three structures next to each other on the points founders actually lose sleep over.

    Legal Identity: A Sole Proprietorship has no separate legal identity — you are the business. An LLP and a Private Limited Company are both separate legal entities, which means the law treats them independently from their founders.

    Liability Protection: Sole Proprietorship — unlimited personal liability. LLP — liability limited to capital contribution. Private Limited — liability limited to shareholding. This distinction matters enormously if you’re in a business with any contractual or financial risk.

    Funding Eligibility: Sole Proprietorships and LLPs cannot raise equity capital. Only a Private Limited Company can issue shares to investors, making it the only viable structure for startups planning to raise angel or VC funding. Foreign investment into an LLP also requires prior RBI approval, whereas most sectors allow FDI into a Private Limited Company through the automatic route.

    Compliance Cost Per Year: Sole Proprietorship — minimal (GST return, ITR). LLP — approximately ₹10,000–₹20,000. Private Limited — approximately ₹30,000–₹50,000.

    Startup India / DPIIT Recognition: Only Private Limited Companies and Registered Partnerships are currently eligible for DPIIT recognition and associated tax benefits. LLPs are not currently included.

    Taxation: Sole Proprietors pay tax at individual slab rates. LLPs pay a flat 30% on profit (plus surcharge). Private Limited Companies pay 22% (existing) or 15% (new manufacturing companies) under concessional tax regimes, plus they can structure ESOP (Employee Stock Option Plan) benefits for talent retention.


    Which Structure Should You Actually Choose?

    The short answer: it depends on where you’re going, not just where you are.

    Choose a Sole Proprietorship if you’re testing a business idea, freelancing, or running a hyperlocal service with no employees, no co-founder, and no plans to raise external capital. Keep in mind you’ll want to revisit this choice as soon as you scale.

    Choose an LLP if you have two or more co-founders, you’re in a professional services business (consulting, design, legal, architecture), your turnover is unlikely to cross the audit threshold in the near term, and you don’t need equity investment. The lower compliance burden is a real advantage for lean, bootstrapped operations.

    Choose a Private Limited Company if you want to raise investment at any stage, plan to hire employees under ESOP, want DPIIT recognition and Startup India tax benefits, need to build credibility with enterprise clients or government tenders, or are planning to scale across cities. This is the default structure for the overwhelming majority of Indian tech and product startups.

    What most founders miss: you can always convert. An LLP can be converted into a Private Limited Company under the Companies Act, 2013 — but the process involves time, legal fees, and MCA approvals.

    Starting right is almost always cheaper than converting later. Lawizer’s legal experts can help you evaluate and register the right structure for your stage, including MSME/Udyam Registration if you qualify.

    Startup India Registration: Eligibility, Process, and Benefits

    Frequently Asked Questions

    Q: What is the main difference between a Private Limited Company and an LLP in India?

    A: A Private Limited Company is registered under the Companies Act, 2013 and can issue equity shares, making it eligible for VC and angel funding and DPIIT recognition under Startup India. An LLP, governed by the LLP Act, 2008, offers more flexibility and lower compliance costs but cannot raise equity capital. The right choice depends on whether you plan to seek external investment — if yes, a Private Limited Company is generally the better fit.

    Q: Is a Sole Proprietorship good for a startup in India?

    A: A Sole Proprietorship is quick and cheap to set up, but it offers no liability protection — your personal assets are at risk if the business incurs debt or gets sued. It also can’t raise equity investment or get DPIIT recognition. For most startups with growth ambitions, a Sole Proprietorship is a starting point at best, not a long-term structure.

    Q: Can an LLP get Startup India recognition from DPIIT?

    A: Currently, only Private Limited Companies and Registered Partnership Firms are eligible for DPIIT recognition under the Startup India scheme, which includes benefits like a three-year income tax holiday under Section 80-IAC and access to the Fund of Funds via SIDBI. LLPs are not included in the current framework, which is a key limitation for founders considering that structure.

    Q: How much does it cost to maintain a Private Limited Company vs an LLP in India per year?

    A: Annual compliance costs for a Private Limited Company typically range from ₹30,000 to ₹50,000, covering statutory audit, ROC filings, and related fees. An LLP costs considerably less — around ₹10,000 to ₹20,000 per year — with no mandatory audit required until turnover exceeds ₹40 lakh. A Sole Proprietorship’s ongoing cost is mainly limited to GST return filing and the owner’s personal ITR.

    Q: Can I convert my LLP into a Private Limited Company later?

    A: Yes, an LLP can be converted into a Private Limited Company under the provisions of the Companies Act, 2013. However, the process requires MCA approval, legal documentation, and takes time. It’s almost always more cost-effective to incorporate as a Private Limited Company from the start if you’re planning to raise funding or scale in the near future.

    Q: Which business structure is best for a two-person startup in India that isn’t raising funding yet?

    A: For a bootstrapped two-person startup, an LLP often makes the most practical sense — it provides limited liability protection for both partners, a separate legal identity, lower compliance overhead, and a formal structure without the annual audit burden of a Private Limited Company. If external funding or DPIIT recognition becomes a goal later, converting to a Private Limited Company remains an option.


    Ready to register the right business structure?

    Lawizer’s experts handle everything — company incorporation, LLP registration, and MSME/Udyam registration — fully online, starting at just ₹999. No CA visit needed.

    Get Started with Lawizer →
    https://lawizer.com/startup-businesslegal

  • GST Registration for Startups: Who Needs It and How to Apply

    GST Registration for Startups: Who Needs It and How to Apply

    GST registration for startups in India trips up more founders than almost any other compliance step. Turnover thresholds, mandatory categories, e-commerce exceptions — there’s a lot to unpack, and the penalty for getting it wrong starts at ₹10,000.

    Here’s the thing: not every startup needs to register for GST immediately. But some do, regardless of how much revenue they’ve made. Knowing which camp you’re in is the first call to make.


    📌 TL;DR: GST registration for startups in India is mandatory once your annual turnover crosses ₹40 lakhs (goods) or ₹20 lakhs (services) in most states — but certain startups, including those selling interstate or through e-commerce platforms, must register regardless of turnover. The application is filed online through the GSTN portal (gstn.gov.in) and typically processed within 3–7 working days. Lawizer helps startups complete the entire registration process without a CA visit.

    What You’ll Learn

    • Exactly when GST registration becomes mandatory for your startup
    • Which categories must register even before crossing the turnover limit
    • The documents you need and the step-by-step application process
    • Why voluntary registration sometimes makes more financial sense than waiting

    What Is GST Registration and Why Does It Matter for Startups

    GST — Goods and Services Tax — is India’s unified indirect tax on the supply of goods and services, introduced through the CGST Act, 2017 (Central Goods and Services Tax Act). Before GST, businesses had to navigate VAT, service tax, and excise duty separately. GST replaced all of that with a single, destination-based tax collected at each stage of the supply chain.

    For startups, GST registration does more than make you tax-compliant. It gives you a GSTIN (GST Identification Number), a 15-digit tax identity that signals legitimacy to clients, vendors, and banks. Registered businesses can issue tax invoices, collect GST from customers, and — crucially — claim Input Tax Credit (ITC), which means the GST you paid on your purchases offsets the GST you owe on your sales. That’s real money back in your working capital.

    The GSTN portal (gstn.gov.in) is the government’s centralised platform where all registration, return filing, and payment happens. The Central Board of Indirect Taxes and Customs (CBIC) oversees administration. Every startup founder should know both.

    What most founders miss: being unregistered when you should be registered isn’t just a compliance gap — under Section 122 of the CGST Act, it’s listed as one of 21 chargeable offences, with penalties starting at 10% of the tax due or ₹10,000, whichever is higher.


    Who Needs GST Registration: The Turnover-Based Rule

    Section 22 of the CGST Act lays down the baseline: if your aggregate annual turnover crosses the prescribed threshold, registration is mandatory. The short answer on thresholds is this — it depends on what you sell and where you’re based.

    For goods-only businesses in most Indian states: mandatory once turnover exceeds ₹40 lakhs per financial year. For service-based startups — SaaS companies, consulting firms, digital agencies, freelancers — the threshold is lower at ₹20 lakhs. For startups operating out of special category states (Arunachal Pradesh, Manipur, Meghalaya, Mizoram, Nagaland, Sikkim, Tripura, and Uttarakhand), the thresholds drop further: ₹20 lakhs for goods and ₹10 lakhs for services.

    One point founders often overlook: aggregate turnover is calculated on a PAN-India basis, not state by state. If you have operations in Mumbai and Bengaluru, you add those revenues together. GST taxes, cess collected from customers, and non-GST supplies are excluded from the calculation — only your actual sales income counts.

    A quick example: a Kolkata-based software consultancy billing ₹18 lakhs this year is below the ₹20 lakh services threshold and technically doesn’t need to register. But if it crosses ₹20 lakhs mid-year, it must apply for registration within 30 days of the date it crossed the limit.

    GST Registration for Startups in India: Process, Benefits (2025 Guide)

    Mandatory Registration Regardless of Turnover: Section 24 Categories

    Here’s where many startups get blindsided. Under Section 24 of the CGST Act, certain businesses must register for GST the moment they commence operations — turnover limits simply don’t apply to them.

    The categories most relevant to Indian startups are:

    Interstate supply of goods or services: If your startup sells across state lines — a Delhi-based D2C brand shipping to Maharashtra, or a Bengaluru SaaS firm billing a client in Hyderabad — you must register, even if your total revenue is ₹5 lakhs. This is one of the most commonly missed triggers.

    E-commerce sellers: Selling through Amazon, Flipkart, Meesho, or any other e-commerce operator? Mandatory registration applies from your first sale, regardless of revenue. The platform itself needs your GSTIN to process payments correctly and deduct Tax Collected at Source (TCS).

    E-commerce operators: If you run a marketplace or aggregator platform, you must register separately as an operator under GST.

    Importers of services (Reverse Charge Mechanism): Startups using international SaaS tools — AWS, Google Workspace, Zoom, Salesforce — may be liable to pay GST under the Reverse Charge Mechanism (RCM), where the recipient, not the supplier, pays the tax. This triggers mandatory registration.

    Casual taxable persons: If your startup participates in trade fairs or exhibitions in states where you don’t have a permanent office, you need to register as a Casual Taxable Person before each such event.

    For a full list of mandatory categories and how they apply to DPIIT-recognised startups, the CBIC’s official guidance on gstn.gov.in remains the most reliable reference.


    Why Voluntary GST Registration Often Makes Business Sense

    Voluntary registration — choosing to register even when you’re below the threshold — is more than just an option. For many early-stage startups, it’s a financially intelligent move.

    The primary reason is Input Tax Credit. Every rupee of GST you pay on office rent, cloud subscriptions, equipment, and professional services can be claimed back against your GST liability. If you’re purchasing extensively to build your product but aren’t yet registered, that credit is simply lost.

    Beyond ITC, there’s the matter of B2B credibility. Most corporate clients and government procurement systems require vendors to be GST-registered. Without a GSTIN, you’re locked out of a large segment of potential revenue. Banks and NBFCs also treat GST returns as a proxy for financial health — your GSTR-3B filings often form part of loan assessment at platforms like Razorpay Capital or traditional lenders.

    A quick example: a two-person UX design studio in Pune, billing ₹15 lakhs annually, is below the threshold. But their biggest prospective client — a fintech company in Mumbai — insists on a tax invoice with GSTIN. Voluntary registration solves that immediately, and the studio starts recovering ITC on software subscriptions at the same time.

    If your startup is at a stage where you’re actively pitching enterprise clients or seeking funding, voluntary GST registration via Lawizer’s startup legal and compliance services is a step worth taking early.


    Documents Required for GST Registration

    Let’s break this down. The document list for GST registration isn’t long, but every item needs to be accurate — mismatches between your PAN, Aadhaar, and incorporation documents are the most common reason applications get rejected or delayed.

    For a Private Limited Company or LLP:

    Business PAN card (mandatory for all entities — individual PAN won’t work for a company). Certificate of Incorporation or LLP Agreement. PAN and Aadhaar of all directors or designated partners. Proof of the principal place of business — a rent agreement plus an electricity bill, or property tax receipt if the premises are owned. Bank account details — a cancelled cheque or bank statement with the account number and IFSC. Board Resolution or Authorisation Letter designating the authorised signatory. Photographs of directors and the authorised signatory. Digital Signature Certificate (DSC) for companies.

    For a Sole Proprietorship or Partnership, the documents are simpler: individual PAN, Aadhaar, business address proof, and bank account details.

    One thing that catches founders off guard: the proof of business address must match your registered office address exactly. If you’re operating from a co-working space in Bengaluru or Delhi, you’ll typically need an NOC (No Objection Certificate) from the space provider alongside your rental agreement.


    How to Apply for GST Registration: Step-by-Step

    The entire process runs on the GSTN portal — no physical visits, no intermediary required. Here’s how it works.

    • Step 1 — Visit gstn.gov.in and navigate to Services > Registration > New Registration. Select “Taxpayer” as the registration type.
    • Step 2 — Fill Part A of Form GST REG-01. Enter your PAN, mobile number, and email. An OTP will be sent to both for verification. Once verified, you’ll receive a Temporary Reference Number (TRN).
    • Step 3 — Log in with your TRN and complete Part B of the application. This is where you upload all the documents listed above, provide details of your business activity, and select the correct commodity or service codes (HSN codes for goods, SAC codes for services).
    • Step 4 — Submit the application. For companies, this requires signing with a DSC. For proprietorships, an Aadhaar-based e-signature suffices.
    • Step 5 — You’ll receive an Application Reference Number (ARN). The GST officer reviews your application. If documents are complete and consistent, registration is approved and a GSTIN is issued — typically within 3–7 working days. If the officer raises queries, you’ll receive a notice in Form GST REG-03 and must respond within 7 working days.

    The GSTN portal now runs an automated approval system that can issue registration significantly faster in straightforward cases. That said, any mismatch in documents resets the clock.

    If you’d prefer to skip the back-and-forth and get it right the first time, you can use Lawizer’s online compliance platform to complete GST registration with expert guidance — fully online.


    Frequently Asked Questions

    Q: Does my startup need GST registration before it starts earning revenue?

    A: Not necessarily based on turnover rules — but yes, if you fall under a mandatory category. If you plan to sell through an e-commerce platform like Amazon or Meesho, or if you’ll be supplying goods or services across state lines from day one, you must register for GST before your first transaction. If you’re a service-based startup operating locally and expect to stay below ₹20 lakhs for the first year, you can defer registration until you cross the threshold.

    Q: What is the GST registration threshold for service startups in India?

    A: For service-based startups operating in most Indian states, GST registration becomes mandatory once annual aggregate turnover exceeds ₹20 lakhs in a financial year. In special category states (Arunachal Pradesh, Manipur, Meghalaya, Mizoram, Nagaland, Sikkim, Tripura, and Uttarakhand), the threshold is ₹10 lakhs. Turnover is calculated on a PAN-India basis under Section 22 of the CGST Act, 2017.

    Q: Can I sell on Flipkart or Amazon without a GST number?

    A: No. Selling through any e-commerce operator in India — Amazon, Flipkart, Meesho, Zomato, Swiggy, or similar platforms — requires mandatory GST registration under Section 24(ix) of the CGST Act, regardless of your revenue. The platform deducts Tax Collected at Source (TCS) and needs your GSTIN to process payouts. Your seller account cannot be activated without one.

    Q: What is the penalty if a startup operates without GST registration when it’s mandatory?

    A: Under Section 122 of the CGST Act, failure to obtain mandatory GST registration is a listed offence. The penalty is 10% of the tax amount due, with a minimum of ₹10,000. In cases where the non-registration was deliberate and involved tax evasion, the penalty can be 100% of the tax evaded, and prosecution including imprisonment becomes possible for larger amounts.

    Q: Is voluntary GST registration worth it for a startup below the threshold?

    A: Yes, in most cases. Voluntary registration lets you claim Input Tax Credit (ITC) on GST paid on purchases — software subscriptions, office equipment, professional services — reducing your net tax burden. It also signals credibility to B2B clients, many of whom require a tax invoice with a valid GSTIN to process vendor payments. The trade-off is the compliance burden: you’ll need to file GSTR-1 and GSTR-3B returns monthly or quarterly.

    Q: How long does GST registration take in India?

    A: Once you submit a complete application on the GSTN portal, registration is typically processed within 3 to 7 working days. The automated approval system introduced in late 2025 can issue a GSTIN faster in cases where documents are clean and consistent. If the GST officer raises a query (Form GST REG-03), you have 7 working days to respond, which extends the timeline. Using a service like Lawizer reduces the risk of errors that trigger queries.


    Ready to Get GST-Registered Without the Back-and-Forth?

    Lawizer’s compliance experts handle your GST registration end-to-end — document prep, GSTN portal filing, officer queries — fully online. No CA visit needed. You can also explore our full range of startup legal and compliance services covering company incorporation, trademark registration, MSME/Udyam, and more.

    Get GST-registered today →

  • Documents Required for Company Registration in India: Complete Checklist

    Documents Required for Company Registration in India: Complete Checklist

    Documents Required for Company Registration in India: Complete Checklist

    India registered over 1,85,000 new companies in 2024 alone — an all-time high. Yet every single day, founders in Bengaluru, Kolkata, and Delhi get their MCA applications sent back for resubmission because of one mismatched name on a PAN card or an expired utility bill.

    Getting the documents required for company registration in India right is not optional — it’s the difference between launching in 10 days and waiting 6 weeks.

    Here’s exactly what you need — broken down by document type, business structure, and who it applies to.

    📌 TL;DR: The documents required for company registration in India include PAN card, Aadhaar card, address proof (utility bill not older than 2 months), Digital Signature Certificate (DSC), Director Identification Number (DIN), Memorandum of Association (MOA), Articles of Association (AOA), and registered office proof — all submitted through the SPICe+ form on MCA21. The exact list varies slightly by structure (Private Limited, LLP, OPC). Lawizer’s experts help you prepare and file the correct documents the first time, fully online.

    What You’ll Learn

    • The complete document checklist for Private Limited Company, LLP, and OPC registration in India
    • Which documents apply to directors, shareholders, and the registered office — and what formats MCA actually accepts
    • The most common document mistakes that cause MCA rejections, and how to avoid every one of them
    • Special requirements for NRIs and foreign nationals incorporating a company in India

    Startup India Registration Certificate online by Gov Portal

    Why Your Document Checklist Can Make or Break Registration

    The Ministry of Corporate Affairs (MCA) processes every incorporation application through its MCA21 portal using the SPICe+ (Simplified Proforma for Incorporating Company Electronically Plus — MCA’s integrated online incorporation form) system.

    Here’s the thing: MCA does not call you when something is wrong. It marks your application for “resubmission,” and the clock resets. In May 2025, new company registrations grew 29% year-on-year to 20,718 in a single month — meaning MCA reviewers are handling massive volumes. Clean, complete documents move faster through this queue.

    What most founders miss: every document must carry matching details across all identity proofs. If your PAN says “Rahul Kumar” and your Aadhaar says “R. Kumar,” that mismatch alone triggers a rejection. Plan your paperwork with this in mind before you upload anything.


    Documents Required for Directors and Shareholders

    A Private Limited Company requires a minimum of 2 directors and 2 shareholders under the Companies Act 2013 (India’s primary legislation governing company formation and management). Directors and shareholders can be the same individuals. Let’s break this down into what each person must submit.

    Identity Proof (Any One)

    • PAN Card — mandatory for all Indian nationals; the name must match exactly across all other documents
    • Passport — mandatory for foreign nationals and NRIs; must be valid and notarised if issued outside India

    Address Proof (Any One)

    • Aadhaar Card
    • Voter ID
    • Driving Licence
    • Passport (can double as address proof if it carries current address)

    Residential Proof (Any One — must not be older than 2 months)

    • Bank statement
    • Electricity bill
    • Mobile or telephone bill
    • Gas bill

    Every director also needs a Digital Signature Certificate (DSC) — an encrypted electronic key used to sign MCA forms online — and a Director Identification Number (DIN), a unique 8-digit government-issued ID for every company director in India.

    The DSC is obtained from MCA-approved certifying authorities. For those with an Aadhaar linked to a mobile number, DSC issuance is significantly faster through OTP-based verification.

    You’ll also need 2–3 recent passport-sized photographs per director and shareholder. Keep digital scans ready in JPEG format under 1MB — MCA portals have strict upload size limits.


    Registered Office Documents: What MCA Actually Wants

    Every company registered in India must have a registered office address within the country — and MCA accepts both residential and commercial properties. The documents you need depend on whether the property is rented or owned. This is one of the most common stumbling blocks for first-time founders, so get it right from the start.

    For a Rented Property

    • Rent agreement or lease deed (signed by both landlord and tenant)
    • No Objection Certificate (NOC) from the property owner — a written letter saying the owner permits the premises to be used as a registered office
    • Latest utility bill (electricity, water, or gas) in the owner’s name — not older than 2 months

    For an Owned Property

    • Ownership deed or sale deed
    • Latest utility bill in the owner’s name — not older than 2 months

    A quick example: if you’re using your parent’s home in Mumbai as your registered office, you’ll need an NOC signed by your parent (the owner), your rent agreement or a simple permission letter, and a recent utility bill from that address. Many founders in Bengaluru and Delhi use co-working spaces as their registered office — that’s valid too, but get the NOC and utility bill from the co-working company on their letterhead.


    Incorporation Documents: MOA, AOA, and SPICe+ Forms

    Beyond identity and address, you need a set of constitutional and statutory documents that formally define your company. These are drafted and filed as part of the SPICe+ process on MCA21.

    Memorandum of Association (MOA)

    The MOA is the charter document of your company. It defines what your company is — its name, registered state, the liability of members, authorised share capital, and most critically, its objects clause (what your business will actually do).

    Under the Companies Act 2013, your company can only legally carry out activities described in the MOA’s objects clause. If you plan to do e-commerce and also provide software services, both need to be captured. It is filed as INC-33 (eMoA) as part of the SPICe+ linked form set.

    Articles of Association (AOA)

    The AOA is your company’s internal rulebook. It governs how the company is managed — how directors are appointed, how shares are transferred, how meetings are conducted, and how decisions are made. It is filed as INC-34 (eAoA). Both MOA and AOA must be digitally signed by all subscribers (founding members).

    Other Statutory Forms Filed via SPICe+

    • INC-9 — Declaration by each proposed director and subscriber confirming they are not disqualified under the Companies Act 2013
    • DIR-2 — Consent to act as director
    • AGILE-PRO-S — Linked form for simultaneous GST registration, EPFO/ESIC registration, and bank account opening (filed together with SPICe+)

    Once all forms and documents are filed correctly, MCA issues a Certificate of Incorporation (COI) along with the company’s CIN (Corporate Identity Number — a 21-digit alphanumeric code that uniquely identifies your company), PAN, and TAN. The typical timeline, as per registrar data, is 7–15 working days for complete applications.


    Document Checklist by Business Structure

    The core documents remain consistent, but each business structure has a few specific requirements. Here’s a quick comparison before you decide which structure to register under.

    Private Limited Company (Pvt Ltd)

    • Minimum 2 directors’ KYC documents (PAN, address proof, residential proof, photographs)
    • DSC for each director
    • DIN (auto-generated through SPICe+ if not already held)
    • MOA (INC-33) + AOA (INC-34)
    • INC-9 declarations from all subscribers and directors
    • Registered office proof (rent agreement / NOC / utility bill)

    One Person Company (OPC)

    • Same as Pvt Ltd but only 1 director and 1 shareholder required
    • Nominee’s PAN and consent (filed via Form INC-3) — the nominee takes over if the sole member becomes incapacitated

    Limited Liability Partnership (LLP)

    • Minimum 2 Designated Partners’ documents (same KYC as above)
    • Filed through FiLLiP (Form for Incorporation of Limited Liability Partnership) on MCA21
    • LLP Agreement — must be executed and filed within 30 days of incorporation

    Documents for NRIs and Foreign Nationals

    Foreign nationals and NRIs can incorporate a Private Limited Company in India under the FDI (Foreign Direct Investment) policy through the automatic route in most sectors. The document requirements differ in one key area: notarisation and apostille.

    • Passport — valid, and notarised by a Notary Public in the country of residence; if from a Hague Convention country, it also needs an Apostille stamp
    • Address proof — overseas bank statement or utility bill, notarised and apostilled
    • Visa copy and date-of-entry stamp — if the foreign national is currently in India at the time of signing
    • DSC — obtainable in India from MCA-empanelled agencies even for foreign nationals

    The short answer: if even one director is a foreign national, plan for an extra 2–3 weeks for notarisation and apostille. Use that time to draft your MOA and AOA carefully.


    5 Document Mistakes That Cause MCA Rejections

    These are the actual reasons applications get sent back. Each one is avoidable if you know what to check.

    • Name mismatch — PAN says one thing, Aadhaar says another. MCA treats even minor abbreviation differences as discrepancies.
    • Expired utility bill — address proof for registered office and residential proof for directors must not be older than 2 months from the date of filing.
    • Missing NOC from property owner — especially common when founders use a home address; the landlord or parent’s NOC is non-negotiable.
    • Wrong objects clause in MOA — a fintech startup that lists only “software development” in its MOA cannot legally collect payments. The objects clause must match your actual business model.
    • DSC not linked to Aadhaar — if your DSC is not Aadhaar-linked and your OTP verification fails, the entire submission is held up.
    Importance of Certificate of Incorporation for New Businesses | Ebizfiling

    Frequently Asked Questions

    Q: What is the most important document for company registration in India?

    A: The PAN card is the most critical identity document for Indian nationals registering a company in India, as it links all tax filings to your company and directors. Without a valid PAN for each director and shareholder, the MCA will not process your SPICe+ application. For foreign nationals, a notarised and apostilled passport serves this function.

    Q: Can I use a residential address as a registered office for my company in India?

    A: Yes, MCA allows a residential address as the registered office of a company. You’ll need a No Objection Certificate (NOC) from the owner of the property, a rent agreement or permission letter, and a utility bill in the owner’s name not older than 2 months. Many early-stage founders in cities like Bengaluru and Mumbai use their home addresses before moving to commercial office space.

    Q: How long does company registration take in India if all documents are correct?

    A: When all documents are complete, correctly formatted, and names match across all proofs, most Private Limited Company registrations are approved by MCA within 7–15 working days. Incomplete applications or those flagged for resubmission can take significantly longer — sometimes 4–6 weeks. Submitting a clean, verified application the first time is the single biggest factor in a fast registration.

    Q: What documents does a foreign national need to register a company in India?

    A: A foreign national needs a valid passport (notarised and apostilled if from a Hague Convention country), overseas address proof (bank statement or utility bill — also notarised), and a Digital Signature Certificate. If the foreign national is in India at the time of signing, a visa copy and entry stamp are also required. At least one director of the company must be an Indian resident under the Companies Act 2013.

    Q: Is Aadhaar mandatory for company registration in India?

    A: Aadhaar is not strictly mandatory, but it significantly speeds up the process. An Aadhaar linked to a registered mobile number allows OTP-based DSC generation and simplifies KYC verification on the MCA21 portal. Without Aadhaar, directors must submit alternative address proofs (Voter ID, Driving Licence, Passport) and the DSC process may take longer through biometric verification.

    Q: What is the difference between MOA and AOA in company registration?

    A: The Memorandum of Association (MOA) is your company’s external-facing charter — it defines the company’s name, registered state, business objectives, and authorised share capital. The Articles of Association (AOA) is your internal rulebook — it governs how the company is run, how directors are appointed, and how decisions are made. Both are mandatory for Private Limited Company registration and must be filed as digitally signed documents on the MCA21 portal via the SPICe+ form.

    Q: Do I need a separate document for GST registration when incorporating a company?

    A: Not necessarily. The AGILE-PRO-S form, filed as part of the SPICe+ bundle, allows you to apply for GST registration simultaneously with company incorporation. This means the same set of KYC and address documents you submit for MCA can be used for GST registration as well, avoiding duplicate paperwork. However, if your business is not yet liable for GST at incorporation time, you can skip this and register for GST separately once your turnover crosses the applicable threshold.


    Ready to register your company without the document headache? Lawizer’s experts handle everything — document verification, DSC procurement, SPICe+ filing, and MCA follow-ups — fully online, starting at just ₹1,499. No CA visit needed.

    Start Your Company Registration with Lawizer → lawizer.com/startup-businesslegal

  • Private Limited Company Registration Cost in India: Full Breakdown

    Private Limited Company Registration Cost in India: Full Breakdown

    Over 2.8 million companies are registered in India — and a huge chunk of founders still don’t know what they actually paid for. The private limited company registration cost in India isn’t a single fixed number. It’s a stack of four completely different charges, and most service providers quote only one of them upfront.

    Here’s the thing: if you don’t understand the breakdown, you will get surprised — every single time.

    📌 TL;DR: The private limited company registration cost in India typically falls between ₹10,000 and ₹35,000 all-in. For startups with authorised capital up to ₹15 lakh, the MCA government fee on SPICe+ is currently zero — your actual costs are stamp duty (₹400–₹2,000 depending on state), Digital Signature Certificates (₹1,500–₹2,500 per director), and professional fees (₹5,000–₹18,000). Lawizer handles the entire SPICe+ process transparently, fully online, with no hidden charges.

    What You’ll Learn

    • The four cost components that make up your total private limited company registration cost — and how to read any service provider’s quote
    • Exact MCA government fees, stamp duty rates by state, DSC costs, and professional fee ranges for 2025
    • A worked cost example for Delhi, Maharashtra, and West Bengal so you can budget before you file
    • Post-incorporation costs most founders completely miss (and what they’ll cost you if you ignore them)
    • Common billing mistakes that quietly inflate your total registration bill

    Why the “One Number” Quote Always Misleads Founders

    Ask ten consultants what private limited company registration costs in India, and you’ll get ten different answers — anywhere from ₹5,000 to ₹50,000. That’s not because anyone is lying. It’s because every quote slices the cost differently. Some include government fees. Some don’t. Some quote professional fees exclusive of GST. Some bury DSC costs inside a “convenience charge.” The only way to audit any quote is to separate the four buckets before you hand over a rupee.

    Let’s break this down. Every pvt ltd registration bill has four distinct components: MCA government fees, state stamp duty, Digital Signature Certificate fees, and professional fees. They’re governed by different rules, payable to different authorities, and they vary for completely different reasons. Treating them as one lump sum is exactly how founders get overcharged — or underprepared when the final invoice arrives.

    The Four Cost Buckets at a Glance

    • MCA Government Fees: Paid to the Ministry of Corporate Affairs (MCA) via the SPICe+ (Simplified Proforma for Incorporating Company Electronically Plus — MCA’s integrated online incorporation form) portal. Currently zero for companies with authorised capital up to ₹15 lakh.
    • Stamp Duty: Levied by your state government on the MOA (Memorandum of Association) and AOA (Articles of Association). Collected digitally through the MCA portal. Varies significantly state to state.
    • DSC Fees: Each proposed director needs a Class 3 Digital Signature Certificate from a CCA-licensed authority before any form can be filed. Costs ₹1,500–₹2,500 per person.
    • Professional Fees: What a CA, CS, or legaltech platform like Lawizer charges to handle name reservation, MOA/AOA drafting, SPICe+ filing, and post-incorporation support. This is the most variable item — and the one most worth comparing carefully.
    Startup India Registration | DPIIT Registration for Startups

    MCA Government Fees: The SPICe+ Slab Structure (2025)

    Here’s the short answer most founders don’t expect: if you’re registering a private limited company with authorised share capital up to ₹15 lakh, the MCA filing fee on SPICe+ is currently zero.

    The government progressively reduced these fees to encourage formalisation of Indian businesses, and for the overwhelming majority of early-stage startups — whether in Bengaluru, Kolkata, Mumbai, or Delhi — the statutory MCA charge is nil. PAN and TAN are issued alongside your Certificate of Incorporation at no additional cost. Director Identification Numbers (DINs) for up to three proposed directors are also allotted free within SPICe+.

    What most founders miss: the fee kicks in only once authorised capital crosses ₹15 lakh. A quick example: incorporate with ₹25 lakh authorised capital and you pay ₹2,000 in MCA fees. Push it to ₹50 lakh and fees scale further per the Companies (Registration Offices and Fees) Rules, 2014. The practical implication?

    Start with ₹1 lakh authorised capital — which is the minimum and the most common choice for Indian startups — and pay zero to the MCA. You can always pass a board resolution to increase authorised capital later via Form SH-7 when you actually need it.

    SPICe+ Fee Slabs (Companies Act 2013)

    Authorised Share CapitalMCA Filing Fee (SPICe+)
    Up to ₹15,00,000Nil
    ₹15,00,001 to ₹25,00,000₹2,000
    ₹25,00,001 to ₹1,00,00,000₹2,000 + ₹200 per ₹10,000 above ₹25 lakh
    Above ₹1,00,00,000As per graduated slab (Schedule X, Fees Rules)

    Stamp Duty: The Most Misunderstood Cost in Pvt Ltd Registration

    Stamp duty is where your state of registered office has the biggest impact on your total private limited company registration cost — and it’s the line item most online cost calculators quietly understate. It’s levied on your MOA and AOA under the respective State Stamp Act or the Indian Stamp Act, 1899 (as applicable in Union Territories).

    The good news: since MCA V3 launched, stamp duty is collected digitally through the MCA portal at the time of SPICe+ submission. The portal detects your registered office state, calculates the applicable duty, and collects it in a single payment. No Sub-Registrar visit. No physical stamp paper. No separate queue.

    The not-so-good news: stamp duty varies widely. Delhi charges roughly ₹400 total on MOA and AOA for a ₹1 lakh authorised capital company. Maharashtra charges ₹1,500–₹2,000 for the same structure. Punjab is among the highest-duty states in the country.

    If you genuinely have flexibility on your registered office location — say you’re a remote-first startup — this is worth calculating before you file, because a ₹1,500 difference is real money at the seed stage.

    Indicative State-Wise Stamp Duty (₹1 Lakh Authorised Capital, Pvt Ltd)

    StateApprox. Stamp Duty (MOA + AOA)
    Delhi (UT)~₹400
    Haryana~₹1,000
    Karnataka~₹1,500
    Maharashtra~₹1,500–₹2,000
    Tamil Nadu~₹1,500
    West Bengal~₹1,000–₹1,200
    Punjab~₹5,000–₹8,000 (significantly higher)

    Note: Figures are indicative for the most common scenario (₹1 lakh authorised capital, private company limited by shares). Verify exact rates on the MCA portal during SPICe+ filing, as state schedules are revised periodically.

    Company Registration Cost in India (2026 Guide). Private Limited, LLP & OPC  Fees Explained | ArthSetu Blog

    DSC and Professional Fees: The Real Variables in Your Budget

    Every proposed director needs a Class 3 DSC (Digital Signature Certificate — a government-recognised electronic signature used to sign MCA filings, issued by a CCA-licensed Certifying Authority under the Information Technology Act 2000).

    Class 2 DSCs were discontinued with effect from January 2021 and are invalid for MCA filings. Budget ₹1,800–₹2,500 per director for a two-year DSC. A typical two-director startup needs two DSCs — so ₹3,600–₹5,000 total for this line item.

    Always buy a two-year validity certificate. The marginal cost difference over a one-year DSC is ₹200–₹500, but it saves you the hassle of renewal before your first ROC (Registrar of Companies) annual filing cycle completes.

    Professional fees are the most variable component — and the one most worth scrutinising. A standard end-to-end service that covers name search, MOA/AOA drafting, SPICe+ filing, PAN/TAN, and Certificate of Incorporation typically ranges from ₹5,000 to ₹18,000 depending on the provider, complexity, and the number of directors.

    Platforms like Lawizer’s company incorporation service handle this fully online, giving you a transparent fixed quote rather than per-form pricing.

    One critical thing to ask every provider: is GST included? Professional service fees attract 18% GST — that’s an additional ₹900–₹3,240 on a ₹5,000–₹18,000 professional fee, and it’s legally non-negotiable. Government fees and DSC costs do not attract GST.

    Professional Fee Ranges by Service Tier

    • Budget / DIY-Assist (₹3,000–₹6,000): You handle document drafting; the service provider only files. High risk of MCA queries and rejection if MOA/AOA are thin or incorrect.
    • Standard End-to-End (₹8,000–₹18,000): Covers name reservation, MOA/AOA drafting, SPICe+ filing, PAN/TAN, Certificate of Incorporation, and basic post-incorporation support.
    • Premium Bundled (₹18,000–₹35,000+): Includes trademark availability search, bank account assistance, MSME/Udyam registration, GST registration, and 6–12 months of compliance support.

    Complete Cost Examples: Delhi, Maharashtra, and West Bengal

    What most founders miss: seeing the full four-component bill laid out in one place before they commit to a service provider. Here are three worked examples for the most common startup scenario — a private limited company with ₹1 lakh authorised capital and two directors, using a standard end-to-end professional service.

    Delhi (UT) — ₹1 Lakh Authorised Capital, 2 Directors

    Cost ComponentAmount
    MCA SPICe+ Filing Fee (capital ≤ ₹15 lakh)₹0
    Stamp Duty — MOA + AOA (Delhi)~₹400
    2 × Class 3 DSC (2-year)~₹4,000
    Professional Fee (end-to-end SPICe+, MOA/AOA drafting)~₹10,000
    GST on Professional Fee @ 18%~₹1,800
    Estimated Total~₹16,200

    Maharashtra — ₹1 Lakh Authorised Capital, 2 Directors

    Cost ComponentAmount
    MCA SPICe+ Filing Fee₹0
    Stamp Duty — MOA + AOA (Maharashtra)~₹1,500–₹2,000
    2 × Class 3 DSC (2-year)~₹4,000
    Professional Fee~₹12,000
    GST on Professional Fee @ 18%~₹2,160
    Estimated Total~₹19,660–₹20,160

    West Bengal — ₹1 Lakh Authorised Capital, 2 Directors

    Cost ComponentAmount
    MCA SPICe+ Filing Fee₹0
    Stamp Duty — MOA + AOA (West Bengal)~₹1,000–₹1,200
    2 × Class 3 DSC (2-year)~₹4,000
    Professional Fee~₹10,000
    GST on Professional Fee @ 18%~₹1,800
    Estimated Total~₹17,000–₹17,200

    Post-Incorporation Costs Most Founders Forget to Budget

    Registration is the start, not the finish. The SPICe+ form — through its sub-form AGILE-PRO-S — integrates GSTIN, EPFO, ESIC, and even bank account opening at zero additional government fee. Use it. But there are several costs that kick in soon after incorporation that most founders only discover when they get an email they didn’t expect.

    Within 30 days of incorporation, you must appoint a statutory auditor and file Form ADT-1 with the ROC. Within 60 days, directors must deposit subscribed share capital into the company bank account and issue share certificates — delays attract penalties under the Companies Act 2013.

    Annual compliance (Form AOC-4 for financial statements and Form MGT-7 for annual return) must be filed every year; late filing attracts ₹100 per day per form with no upper limit, which is a genuinely painful penalty that catches new founders off-guard.

    If you plan to protect your brand, trademark registration costs ₹4,500–₹9,000 per class depending on applicant type. And if you qualify as a micro or small enterprise, MSME Udyam registration is completely free and unlocks priority lending, government tender eligibility, and reduced trademark fees — do it on Day 2.

    Key Post-Incorporation Costs at a Glance

    • GST Registration: Free on the GSTN portal. Mandatory once turnover crosses ₹20 lakh (services) or ₹40 lakh (goods), or from Day 1 for inter-state supply.
    • Trademark Registration: ₹4,500 per class (MSME/startup/individual applicants), ₹9,000 per class (others). File early — trademark priority runs from the filing date.
    • MSME (Udyam) Registration: Zero cost. Takes 20 minutes online at udyamregistration.gov.in.
    • Statutory Audit: Budget ₹5,000–₹15,000 per year for early-stage companies, plus monthly accounting/bookkeeping of ₹3,000–₹8,000/month from Month 1.
    • Annual Compliance (ROC Filing): AOC-4 + MGT-7 filings. Late filing penalty is ₹100/day per form — no cap. File on time, every time.

    5 Common Mistakes That Inflate Your Registration Bill

    A quick example: a Bengaluru founder once incorporated with ₹10 lakh authorised capital because the consultant said “more capital looks credible.” The MCA fee was still zero, but the stamp duty on the AOA — which scales with authorised capital in Karnataka — was meaningfully higher than it would have been at ₹1 lakh. That’s a completely avoidable expense.

    Here are the five mistakes that consistently inflate the private limited company registration cost in India.

    • Over-capitalising at incorporation: Start with ₹1 lakh authorised capital. Increase it later via Form SH-7 only when you actually need it. Inflating capital upfront raises stamp duty and serves no practical purpose for a seed-stage company.
    • Accepting per-form billing: Once you’re in the MCA system, unscrupulous consultants can raise separate invoices for each form — DIN, SPICe+, MOA/AOA, PAN/TAN. Insist on a single fixed, itemised quote before you begin.
    • Ignoring GST on professional fees: An ₹8,000 professional fee quote that doesn’t mention GST is actually a ₹9,440 outflow. Always ask: inclusive or exclusive of GST?
    • Buying Class 2 DSCs from outdated resellers: Class 2 DSCs are invalid for MCA filings since January 2021. Confirm you’re buying a Class 3, IND (Individual) DSC with a USB token, valid for at least two years.
    • Not registering MSME on Day 2: MSME (Udyam) registration is free, takes 20 minutes, and unlocks meaningful benefits — including a reduced trademark fee of ₹4,500 per class vs ₹9,000. Most founders delay this for months and pay full trademark fees unnecessarily.

    Frequently Asked Questions

    Q: What is the total cost to register a private limited company in India in 2025?

    A: The total private limited company registration cost in India typically ranges from ₹10,000 to ₹35,000 all-in, covering MCA government fees (currently zero for authorised capital up to ₹15 lakh), state-specific stamp duty (₹400–₹2,000 for most states on ₹1 lakh capital), Class 3 Digital Signature Certificates for each director (₹1,500–₹2,500 per person), and professional fees for drafting and filing (₹5,000–₹18,000). GST at 18% applies on professional fees only. Government fees and DSC costs are GST-exempt.

    Q: Is there any government fee to register a pvt ltd company in India?

    A: For companies with authorised share capital up to ₹15 lakh, the MCA filing fee on the SPICe+ form is currently zero under the government’s startup-friendly fee structure. Stamp duty on the MOA and AOA still applies and varies by state — it ranges from roughly ₹400 (Delhi) to ₹8,000+ (Punjab) for a ₹1 lakh capital company. PAN, TAN, and DINs for up to three directors are allotted free within SPICe+.

    Q: Does stamp duty differ from state to state for company registration?

    A: Yes, significantly. Stamp duty on the MOA and AOA is governed by each state’s Stamp Act and varies by both state and authorised capital amount. It’s collected automatically through the MCA V3 portal at the time of filing — you don’t visit a stamp office. Delhi charges around ₹400, Karnataka around ₹1,500, Maharashtra around ₹1,500–₹2,000, and Punjab significantly more, all for the same ₹1 lakh authorised capital structure. Founders with a choice of registered office location should factor this in.

    Q: What is a DSC and why is it required for company registration?

    A: A DSC, or Digital Signature Certificate, is a government-recognised electronic signature issued by a Certifying Authority (CA) licensed under the Information Technology Act 2000. Every proposed director and subscriber to the MOA must hold a valid Class 3 DSC before any SPICe+ form can be filed with the MCA. Class 2 DSCs were discontinued in January 2021. A Class 3 individual DSC costs ₹1,500–₹2,500 depending on validity period and issuing authority. A two-year certificate is recommended to avoid renewal before your first annual ROC filing.

    Q: Can I register a private limited company without a CA or CS?

    A: Technically yes — the MCA21 portal is publicly accessible. But incorrectly drafted MOA/AOA, wrong object clauses, or mismatched DIN details are the most common reasons SPICe+ forms get rejected or raise MCA queries, which means resubmissions and delays. A rejected or defective application doesn’t mean a refund of government fees already paid. Most founders find that a professional platform handling the end-to-end process is significantly cheaper than fixing a self-filed mistake after the fact.

    Q: What happens if I don’t file annual compliance on time after registration?

    A: Every private limited company must file Form AOC-4 (financial statements) and Form MGT-7 (annual return) with the Registrar of Companies each year. Missing these deadlines triggers a penalty of ₹100 per day per form — with no upper limit under the Companies Act 2013. A 60-day delay on both forms costs ₹12,000 in late fees alone. Persistent non-compliance can also result in director disqualification and notices from the ROC, which are significantly more expensive to resolve.

    Ready to register your private limited company?
    Lawizer’s experts handle everything — company incorporation, MSME/Udyam registration, trademark filing — fully online, with a transparent fixed quote. No CA visit needed.

    Start Your Company Registration with Lawizer →

  • How to Register a Private Limited Company in India (2026): Step-by-Step Guide.

    How to Register a Private Limited Company in India (2026): Step-by-Step Guide.

    Over 1.12 lakh companies were incorporated in India in just the first eight months of FY 2024–25 — and private limited companies made up over 95% of that number. If you’re building something serious in India, there’s one structure most founders, investors, and banks trust above all others: the Private Limited Company.

    Getting it wrong costs months. Getting it right takes about 7 working days — if you know exactly what to do.

    📌 TL;DR: Private Limited Company registration in India is a fully online process under the Companies Act, 2013, handled via the MCA21 portal using the SPICe+ form. You need a minimum of 2 directors and 2 shareholders, a DSC, DIN, name reservation, MoA and AoA filing, and can expect your Certificate of Incorporation in 5–7 working days. Lawizer’s experts handle the entire process end-to-end, starting at just ₹1,499.

    What You’ll Learn

    • Who qualifies to register a Private Limited Company in India in 2026
    • Every step of the SPICe+ registration process — from DSC to Certificate of Incorporation
    • What documents you actually need (and common mistakes that delay approval)
    • Costs, timelines, and what happens after registration
    • How to stay compliant once your company is live

    What Is a Private Limited Company — and Why Do Founders Choose It?

    A Private Limited Company (Pvt. Ltd.) is a business entity incorporated under the Companies Act, 2013 and regulated by the Ministry of Corporate Affairs (MCA).

    The defining feature: your personal assets are legally separate from your company’s liabilities. If the business runs into debt, your personal savings, home, or car are not at risk.

    Here’s the thing — this structure is not just about protection. It’s about credibility. Banks, venture capitalists, and institutional clients in Bengaluru, Mumbai, and Delhi instinctively trust a Pvt. Ltd. entity over a sole proprietorship or partnership. It signals permanence, governance, and scalability.

    Key features at a glance:

    • Minimum 2 directors (at least one must be a resident Indian) and minimum 2 shareholders
    • Maximum 200 shareholders — shares cannot be listed on a public stock exchange
    • Separate legal identity — the company can own property, enter contracts, and sue or be sued in its own name
    • Perpetual succession — the company continues to exist even if directors or shareholders change
    • No minimum paid-up capital required since the Companies (Amendment) Act, 2015

    What most founders miss: a Pvt. Ltd. structure is almost mandatory if you’re planning to apply for DPIIT Startup India recognition, raise angel or VC funding, or issue ESOPs to your team.


    Eligibility and Pre-Registration Requirements

    Before you touch the MCA21 portal, there are a few boxes to check. Getting these right upfront prevents 80% of rejection delays.

    Director and Shareholder Requirements

    • Minimum 2 directors; maximum 15 directors
    • At least one director must be a resident Indian (stayed in India for at least 182 days in the previous calendar year)
    • Directors and shareholders can be the same individuals
    • Foreign nationals can be directors — they need a valid passport and address proof
    • A director must not be an undischarged insolvent or convicted of any offence involving moral turpitude
    Startup India Certificate 2026: Download & Verify Online

    Registered Office

    Your company needs a registered office address in India within 30 days of incorporation. This can be a home address, a co-working space, or a rented commercial property. You’ll need an NOC (No Objection Certificate) from the property owner plus a utility bill not older than 2 months.


    Step-by-Step: How to Register a Private Limited Company in India

    The entire process runs through the MCA21 portal — India’s Ministry of Corporate Affairs digital gateway. Let’s break this down step by step.

    Step 1: Obtain a Digital Signature Certificate (DSC)

    A DSC (Digital Signature Certificate) is your legal electronic signature. It’s mandatory for all proposed directors and shareholders (subscribers) who will sign the incorporation forms. You can apply through government-approved agencies like eMudhra or Sify. Expect a turnaround of 1–2 working days. Carry your PAN, Aadhaar, and a passport-size photo.

    Step 2: Reserve Your Company Name via SPICe+ Part A

    SPICe+ (Simplified Proforma for Incorporating Company Electronically Plus — MCA’s single-window incorporation form) has two parts. Part A handles name reservation. You can propose up to 2 names in order of preference. The name must end with “Private Limited” and must not be identical or confusingly similar to an existing company or trademark. MCA typically approves or rejects within 1–3 working days.

    A quick example: “Zelta Tech Solutions Private Limited” would pass if no similar name exists on the MCA database. “Reliance Innovations Private Limited” would almost certainly be rejected.

    Step 3: Apply for Director Identification Number (DIN)

    A DIN (Director Identification Number) is a unique 8-digit number issued by the MCA to every person who wants to become a director of a company. The good news: you don’t file a separate DIN application anymore. DIN allotment for up to 3 directors is integrated directly into SPICe+ Part B — it’s done in the same form as incorporation.

    Step 4: Draft MoA and AoA

    Two critical constitutional documents go into every incorporation filing:

    • MoA (Memorandum of Association — INC-33): Defines your company’s objectives and the scope of business activities it can undertake
    • AoA (Articles of Association — INC-34): Lays down the internal rules and regulations governing the company’s management

    These are drafted as e-MoA and e-AoA on the MCA portal and must be signed digitally by all subscribers. Getting the objects clause in your MoA right is critical — a narrowly drafted MoA can restrict future business activities. This is where professional help pays for itself.

    Step 5: File SPICe+ Part B and AGILE-PRO

    SPICe+ Part B is where everything comes together. This single integrated form covers: company incorporation, DIN allotment, PAN application, TAN application, EPFO registration, ESIC registration, and professional tax registration (in applicable states). Alongside Part B, you’ll file AGILE-PRO (INC-35) for GST registration and a bank account opening request.

    Supporting documents to attach: e-MoA, e-AoA, Form INC-9 (declaration by directors and subscribers), Form DIR-2 (consent to act as director), identity and address proofs for all directors and subscribers, and registered office proof.

    Step 6: Receive Your Certificate of Incorporation (CoI)

    Once the Registrar of Companies (ROC) processes and approves your application, you receive a digitally signed Certificate of Incorporation (CoI). This document contains your CIN (Corporate Identity Number — a 21-character alphanumeric identifier assigned to every registered company), PAN, and TAN. Typical timeline: 5–7 working days from a clean submission.

    How to Register a Private Limited Company in India: Complete MCA Portal Guide [2026]

    Documents Required for Private Limited Company Registration

    The short answer: documents fall into three categories — for directors, for shareholders, and for the registered office. All documents must be self-attested; foreign nationals must get their documents notarised and apostilled.

    For Directors and Shareholders (Subscribers)

    • PAN card (mandatory for Indian nationals)
    • Aadhaar card / Passport / Voter ID (identity proof)
    • Bank statement / Utility bill / Rent agreement not older than 2 months (address proof)
    • Recent passport-size photograph
    • Email address and mobile number (for DSC and DIN)

    For Registered Office

    • Utility bill (electricity / telephone) not older than 2 months
    • NOC (No Objection Certificate) from property owner if rented
    • Rent agreement or ownership proof

    Cost of Registering a Private Limited Company in India (2026)

    Here’s the thing that surprises most first-time founders: government fees for companies with an authorised capital up to ₹15 lakh are zero, following MCA’s initiative to reduce the cost of starting a business. What you actually pay includes the professional fee for filing, DSC cost, and stamp duty — which varies by state.

    • DSC (per person): ₹1,000–₹2,000
    • Government stamp duty: Varies by state — approximately ₹500 in Delhi, higher in Maharashtra
    • Professional / service fees: ₹1,500–₹8,000 depending on provider
    • Total out-of-pocket (typical): ₹3,000–₹12,000 all-inclusive

    With Lawizer’s company incorporation service (https://lawizer.com/startup-businesslegal), you get end-to-end expert handling — name approval, DSC, DIN, SPICe+ filing, MoA and AoA drafting, PAN, TAN, and your Certificate of Incorporation — fully online, no CA visit required.


    Post-Registration Compliance: What Happens After You Get Your CoI

    Incorporation is day one, not the finish line. A Private Limited Company carries mandatory annual compliances under the Companies Act, 2013. Missing these attracts penalties — and the MCA has been tightening enforcement through its Companies (Filing of Documents and Forms in XBRL) Amendment Rules, 2025.

    • Open a current bank account in the company’s name within 30 days
    • File INC-20A (Declaration of Commencement of Business) within 180 days of incorporation if you have share capital
    • GST registration once your turnover crosses ₹20 lakh (₹10 lakh for special category states)
    • Annual Return (Form MGT-7): filed within 60 days of AGM
    • Financial Statements (Form AOC-4): filed within 30 days of AGM
    • DIR-3 KYC: every director must complete KYC annually
    • Income Tax Return: mandatory regardless of profit or loss

    If you’re also registering your brand, getting your trademark registered through Lawizer (https://lawizer.com/startup-businesslegal/protectbusiness/TrademarkRegistrationPage) alongside incorporation is a smart move — it protects your company name and logo from day one.

    Understanding Private Limited Companies in India's Startup Ecosystem | Brand Stories (HT Tech)

    Frequently Asked Questions

    Q: How long does it take to register a Private Limited Company in India?

    A: With all documents in order, Private Limited Company registration in India typically takes 5–7 working days from the date of SPICe+ form submission to receipt of the Certificate of Incorporation from the Registrar of Companies. Delays usually occur due to name rejection, document errors, or ROC workload. Using a professional service like Lawizer significantly reduces the chances of resubmission.

    Q: What is the minimum capital required to start a Private Limited Company in India?

    A: There is no minimum paid-up capital requirement for a Private Limited Company in India since the Companies (Amendment) Act, 2015. You can incorporate with as little as ₹1 in authorised capital, though most founders choose ₹1 lakh as a practical starting point. Government fees for companies with authorised capital up to ₹15 lakh are zero.

    Q: Can I register a Private Limited Company with only one person?

    A: No — a Private Limited Company requires a minimum of 2 directors and 2 shareholders. If you want a single-person structure with limited liability, the correct option is an OPC (One Person Company), also registered under the Companies Act, 2013. However, OPCs cannot issue ESOPs or raise external equity funding, which makes them unsuitable for startups seeking investor capital.

    Q: Can a foreign national be a director or shareholder in an Indian Private Limited Company?

    A: Yes. Foreign nationals can be directors and shareholders in a Private Limited Company in India, subject to FDI (Foreign Direct Investment) regulations under FEMA (Foreign Exchange Management Act). At least one director must be a resident Indian — meaning they must have stayed in India for at least 182 days in the preceding calendar year. Foreign directors need a notarised and apostilled passport copy and address proof.

    Q: What is the difference between MoA and AoA?

    A: The MoA (Memorandum of Association) defines the company’s objectives — what business activities it is permitted to carry out. The AoA (Articles of Association) lays down the internal governance rules — how meetings are held, how shares are transferred, and how directors are appointed or removed. Both are constitutional documents filed at incorporation and can only be changed through special resolutions approved by shareholders.

    Q: Do I need a CA or lawyer to register a Private Limited Company in India?

    A: You are not legally required to hire a CA or lawyer — the MCA portal is accessible directly. However, errors in SPICe+ filing, MoA drafting, or document preparation are the primary cause of rejections and resubmissions, adding days or weeks to the process. Most founders use a professional incorporation service to get it done right the first time. Lawizer offers end-to-end Private Limited Company registration fully online, starting at ₹1,499.

    Q: Is GST registration mandatory at the time of company incorporation?

    A: GST registration is not mandatory at incorporation unless your business is in a sector where GST applies from the first transaction (such as e-commerce operators) or your projected turnover exceeds ₹20 lakh in a year (₹10 lakh for special category states). However, the SPICe+ AGILE-PRO form allows you to apply for GST simultaneously with incorporation — a practical move for most businesses.


    Ready to incorporate your Private Limited Company?

    Lawizer’s experts handle everything — name reservation, SPICe+ filing, MoA and AoA drafting, PAN, TAN, and your Certificate of Incorporation — fully online, starting at just ₹1,499. No CA visit needed.

    Start Your Company Registration Today → https://lawizer.com/startup-businesslegal


  • Freelance Contracts in India: What Founders Must Include to Avoid Disputes?

    Freelance Contracts in India: What Founders Must Include to Avoid Disputes?

    India now has over 11.2 million gig workers — and that number is climbing fast. Yet most founders who hire freelancers do it on a WhatsApp message and a handshake. When things go wrong — missed deadlines, stolen designs, unpaid invoices — there’s nothing to stand on. A proper freelance contract in India is the only thing that changes that.

    No contract means no leverage. Here’s exactly what to put in one.

    📌 TL;DR: A freelance contract in India is a legally enforceable agreement under the Indian Contract Act, 1872. Every founder hiring a freelancer must include scope of work, payment terms, IP ownership, confidentiality, TDS obligations, and a dispute resolution clause. Lawizer can help you draft or review a watertight freelancer agreement online — without a lawyer visit.

    What You’ll Learn

    • Why a freelance contract in India is a legal document — not just a formality
    • The 8 clauses every founder must include before work begins
    • How to handle tax, IP, and dispute clauses the right way under Indian law
    • Common mistakes founders make — and how to avoid them

    Why a Freelance Contract Is a Legal Document, Not a Formality

    Here’s the thing. A freelance contract in India isn’t just paperwork you send out of habit — it’s a binding agreement governed by the Indian Contract Act, 1872. The moment both parties agree on consideration (the payment), scope, and deliverables, that contract becomes enforceable in an Indian court. That means if your UI designer walks off mid-project with your brand assets, or if a client in Mumbai refuses to pay after 3 months of work, you have legal recourse — but only if you have a signed agreement.

    What most founders miss: verbal agreements and Slack confirmations count for almost nothing when there’s a real dispute. The Code on Social Security, 2020 — which came into force in November 2025 — formally defines “gig workers” for the first time in Indian law, but it primarily protects platform workers, not direct freelance hires. For the Bengaluru design agency that hires a Kolkata-based content writer directly, the contract is still the only safety net.

    If you’re still building the legal groundwork for your startup, getting your freelance agreements in order is as foundational as your incorporation documents.

    Freelancing Agreement Drafting Services - Legal AT India

    Clause 1 & 2: Scope of Work and Deliverables

    Let’s break this down. The most common reason freelance disputes happen in India is not money — it’s vagueness. “Build me a website” means completely different things to a founder and a developer. Your contract must define deliverables with surgical precision: how many pages, which features, what tech stack, how many revision rounds.

    The scope of work clause should answer these questions without ambiguity:

    • What exactly will be delivered? Name every output — files, formats, dimensions, word counts
    • What is explicitly excluded? If SEO isn’t included in a content project, say so
    • How many revision rounds are included? Unlimited revisions = unlimited scope creep
    • What are the project milestones and deadlines? Include specific dates, not “ASAP”

    A quick example: a Delhi-based D2C brand hiring a Figma designer should state “5 screens, mobile + desktop, 2 rounds of revisions, delivered as .fig and .png files by [date]” — not just “design the app.”

    Clause 3 & 4: Payment Terms and Late Payment Penalties

    The short answer: always define payment structure, due dates, and what happens when payment is late — all in the contract itself. According to Razorpay’s freelancer agreement guide, a freelance contract must include the compensation amount, payment schedule, any additional service fees, and a late payment clause. Skipping any one of these is how founders end up chasing invoices for months.

    Here’s what your payment clause should cover:

    • Payment structure: Fixed fee, milestone-based, or hourly — pick one and commit
    • Advance payment: Asking for 25–50% upfront is standard practice and protects both sides
    • Payment due date: “Net 15” or “Net 30” from invoice date — never “when convenient”
    • Late payment penalty: A monthly interest rate (typically 1.5–2%) kicks in after the due date passes
    • Payment method: Bank transfer, Razorpay, or UPI — and the currency (INR vs USD for cross-border)

    One thing many Mumbai-based startups hiring international freelancers overlook: if payment is in foreign currency, you’ll need to factor in FEMA (Foreign Exchange Management Act) compliance for outward remittances above certain thresholds.

    Clause 5: Intellectual Property and Ownership Rights

    This is the clause that founders get wrong most often — and it can cost the most. By default under Indian law, the creator of a work owns it. That means if your contract is silent on IP, the logo your designer made, the code your developer wrote, and the copy your writer produced could technically belong to them — not you. Ownership transfers to the client only when the contract explicitly says so, and typically only after full payment.

    Your IP clause needs to spell out:

    • When does ownership transfer? Specify it’s upon receipt of final payment
    • What’s included? All source files, working files, and final deliverables
    • Can the freelancer showcase the work? Define portfolio rights explicitly
    • What about pre-existing IP? If the freelancer uses their own templates or code libraries, state that clearly

    What most founders miss: even if you’ve paid in full, if your contract doesn’t include an IP assignment clause, proving ownership in a dispute is complicated. Get this in writing before work starts.

    Co-founder Agreement

    Clause 6: Confidentiality (NDA) and Non-Compete

    If your freelancer is working on an unreleased product, accessing customer data, or seeing your pricing models — you need a confidentiality clause. This is essentially a lightweight NDA (Non-Disclosure Agreement) built into the freelance contract. It prevents the freelancer from sharing your business information with competitors, discussing project details publicly, or using proprietary information to pitch to your rivals.

    The confidentiality clause should define what counts as confidential (business plans, source code, client lists, financial data), how long the obligation lasts (usually 2–3 years after project end), and what the consequences of a breach are.

    A quick note on non-competes: Indian courts have historically been reluctant to enforce overly broad non-compete clauses for freelancers, since Section 27 of the Indian Contract Act, 1872 restricts agreements that restrain trade. Keep any non-compete narrow — specific client names or a defined geographic region — rather than a blanket “you can’t work in this industry.”

    Clause 7: Tax Obligations — TDS and GST

    Tax is where Indian freelance contracts quietly fall apart. There are two key obligations founders must address: TDS (Tax Deducted at Source) and GST (Goods and Services Tax). Getting either wrong exposes both the founder and the freelancer to compliance issues.

    TDS Under Section 194J

    Under Section 194J of the Income Tax Act, if you’re paying a freelancer for professional or technical services and the total payment exceeds ₹50,000 in a financial year, you must deduct TDS — typically at 10%. The contract should state which party is responsible for TDS, and the freelancer’s PAN must be collected for compliance. If you’re filing ITR filing for your business, TDS deducted on freelance payments must be reported correctly.

    GST Registration Threshold

    If a freelancer’s annual turnover exceeds ₹20 lakh (₹10 lakh in some special category states), they must register for GST and charge 18% GST on services. Your contract should state whether the quoted fee is inclusive or exclusive of GST, and if it’s exclusive, who bears that cost. Always ask for the freelancer’s GSTIN before signing.
    Clause 8: Termination and Dispute Resolution

    Projects go sideways. Founders change direction. Freelancers disappear. Your termination clause should cover what happens in each scenario — who keeps what money, who owns partially completed work, and how much notice either side must give. A standard notice period of 7–14 days is common for short projects; 30 days for longer retainers.

    The dispute resolution clause is equally critical. Define:

    • Jurisdiction: Which city’s courts govern the contract (e.g., “Courts in Bengaluru shall have exclusive jurisdiction”)
    • Arbitration first: Many contracts include a clause requiring arbitration before litigation — it’s faster and cheaper
    • Governing law: Always “Laws of India” — important for cross-border freelance arrangements

    A quick example: if your startup is in Hyderabad but the freelancer is in Pune, pick one city as the jurisdiction — don’t leave it blank and fight over it later.

    Frequently Asked Questions

    Q: Is a freelance contract legally valid in India?

    A: Yes. A freelance contract is legally enforceable in India under the Indian Contract Act, 1872, provided it meets the basic requirements of a valid contract — offer, acceptance, lawful consideration, and competent parties. A written and signed agreement (including digitally signed ones under the IT Act, 2000) carries strong evidentiary weight in Indian courts and can be used to claim payment or seek damages for breach.

    Q: Do I need to deduct TDS when I pay a freelancer in India?

    A: If you’re paying a freelancer for professional or technical services and the total payment crosses ₹50,000 in a financial year, you must deduct TDS at 10% under Section 194J of the Income Tax Act. You’ll need the freelancer’s PAN to do this, and you must deposit the deducted amount with the government and issue a TDS certificate (Form 16A) to the freelancer.

    Q: Who owns the work a freelancer creates — the founder or the freelancer?

    A: Under Indian copyright law, the creator of a work is the default owner. Unless your contract explicitly includes an intellectual property assignment clause, the freelancer technically retains ownership of what they create — even if you’ve paid for it. Always include a clause stating that IP transfers to you upon full payment, and list all deliverables (including source files) within the scope of that transfer.

    Q: Can a freelance contract be signed digitally in India?

    A: Yes. Digital signatures are legally valid in India under the Information Technology Act, 2000 (IT Act). You can use tools like DocuSign, Adobe Sign, or even a scanned signature on a PDF for standard freelance agreements. For high-value contracts, a digitally signed document with a trusted third-party certificate adds extra enforceability.

    Q: What happens if a freelancer doesn’t deliver and refuses to return the advance?

    A: If your contract includes a clear scope of work, payment terms, and a termination clause, you have grounds to pursue recovery through a civil court or consumer forum, or through arbitration if the contract specifies it. Without a written contract, proving the terms of the arrangement becomes very difficult. This is why drafting the agreement before any advance is paid is non-negotiable.

    Q: Does a freelancer in India need to charge GST?

    A: A freelancer must register for GST and charge 18% GST on services only if their annual turnover exceeds ₹20 lakh (₹10 lakh in special category states like Manipur, Mizoram, and Nagaland). Below this threshold, GST registration is optional. Your contract should always clarify whether fees are GST-inclusive or exclusive, and request the freelancer’s GSTIN if they are registered.

    Ready to draft a legally sound freelance agreement?
    Lawizer’s experts handle everything — contract drafting, legal review, and startup compliance — fully online, starting at just ₹999. No CA visit needed.

    Get Your Freelance Contract Drafted →

  • Legal Audit for Startups: What to Check Every Quarter

    Legal Audit for Startups: What to Check Every Quarter

    Most Indian startups get hit with MCA penalties, GST mismatches, or investor red flags not because they ignored compliance — but because they checked it once and never came back. A quarterly legal audit for startups costs a few hours every 90 days. The alternative can cost ₹50,000 to over ₹10 lakh in late fees, compounding penalties, and reinstatement costs.

    Here’s exactly what to review every quarter — so legal problems don’t ambush you at the worst possible time.

    📌 TL;DR: A quarterly legal audit for startups in India covers four core areas: MCA/ROC filings, GST and TDS compliance, contract and IP health, and HR/labour law status. Running this check every 90 days prevents director disqualification, investor due diligence failures, and penalty accumulation under the Companies Act 2013. Lawizer’s startup legal services can help you run and fix each of these areas entirely online.

    What You’ll Learn

    • Which MCA and ROC filings to verify every quarter — and what happens if you miss them
    • The GST and TDS checks that catch 90% of tax compliance gaps before they become notices
    • Contract, IP, and HR items most founders overlook until due diligence knocks
    • A simple 4-area framework you can run in-house or hand to your CA in under a day

    Why Quarterly — Not Annual — Is the Right Cadence

    Annual compliance reviews made sense when businesses moved slowly. Startups don’t. A new co-founder joins in March, a contractor agreement expires in June, your GST turnover crosses ₹10 crore in September — and none of these trigger automatic alerts. By the time your annual audit flags the gap, the deadline has passed and the penalty clock has been running for months.

    Here’s the thing: MCA charges ₹100 per day of delay on most ROC forms — with no upper cap on penalties for forms like MGT-7 (Annual Return). Miss a quarterly TDS return and you’re looking at ₹200 per day as a delay fee, plus interest on the unpaid amount. These aren’t theoretical risks. Every year, thousands of MSME and startup directors across India receive MCA strike-off notices that are entirely preventable with a basic 90-day review cycle.

    The quarterly rhythm also aligns naturally with India’s GST filing calendar (monthly GSTR-1 and GSTR-3B), TDS return quarters (April–June, July–September, October–December, January–March), and advance tax payment installments. Reviewing compliance once a quarter means you’re never more than 90 days away from catching a problem early.

    Check #1 — MCA and ROC Filings Status

    Start every quarterly audit on the MCA21 portal — the Ministry of Corporate Affairs’ online compliance hub. Log in and pull your company’s master data. Check that your registered office address is current, all directors have active DIN (Director Identification Number) status, and no forms are showing as “pending” or “under processing” without a valid reason.

    What most founders miss: the DIR-3 KYC (Director KYC form) deadline falls on September 30 every year. Miss it and your DIN gets deactivated — you can’t sign any company documents until you pay a ₹5,000 reactivation fee and file. If you have multiple directors, make sure every single one has completed their KYC for the current year before Q2 ends.

    Key forms to check each quarter

    • ADT-1 — Auditor appointment form. Must be filed within 15 days of the first board meeting. If your startup is in its first year and this hasn’t been done, fix it immediately.
    • MGT-7 / MGT-7A — Annual Return. Due 60 days after AGM (Annual General Meeting). Small companies file the simplified MGT-7A. Late filing penalty: ₹100 per day, no cap.
    • AOC-4 — Financial Statements. Due 30 days after AGM. Same per-day penalty applies.
    • DPT-3 — If your company has received any loans or deposits. Due June 30 annually. Non-filing penalty: up to ₹1 crore or twice the deposit amount, whichever is lower.
    • MSME-1 — If you owe money to MSME vendors for over 45 days. Filed half-yearly. Investors check this closely.
    Legal Compliances for Startups in India: A Practical Checklist for Founders

    Check #2 — GST and TDS Compliance Health

    GST compliance is a monthly obligation — but the quarterly audit is where you catch the mismatches that build up. Pull your GSTR-2B (auto-populated Input Tax Credit statement) for the last three months and reconcile it against your purchase register. From 2026, the GSTN (Goods and Services Tax Network) flags supplier-recipient mismatches in real time, so any unreconciled difference shows up as a risk during an inspection or investor data room review.

    A quick example: if your supplier filed their GSTR-1 late and you’ve already claimed the ITC (Input Tax Credit — the GST you paid on purchases, which you can offset against your GST liability), that claim will be reversed in your next GSTR-3B. You’ll owe the tax plus interest. Catching this quarterly means you can chase the vendor before the reversal hits.

    On the TDS side, verify that deductions are current for all qualifying payment categories. Let’s break this down: TDS (Tax Deducted at Source) must be deducted on professional fees above ₹30,000 at 10%, contractor payments above ₹30,000 per transaction at 2%, and rent above ₹2,40,000 per year at 10%. Quarterly TDS returns are due on July 31, October 31, January 31, and May 31. A missed quarterly return attracts ₹200 per day as a late fee — plus interest at 1.5% per month on unpaid TDS from the date it was due to be deposited.

    E-invoicing threshold: are you caught yet?

    From April 1, 2026, e-invoicing is mandatory for businesses with turnover above ₹5 crore. If your startup has crossed this threshold and you haven’t enabled e-invoice generation through your billing software or the GSTN portal, every B2B invoice you’ve raised without it is technically non-compliant. Check your last four quarters of turnover and confirm your e-invoicing status every time you run a legal audit.

    Check #3 — Contracts, IP, and Cap Table Hygiene

    This is the area that trips up investor due diligence most often — and it has nothing to do with ROC deadlines. Every quarter, pull up a simple register of your active contracts and check three things: expiry dates, IP assignment clauses, and unsigned documents sitting in email threads.

    A vendor SLA that expired six months ago but is still being performed is legally murky territory. A freelance developer who built your core product but never signed an IP assignment agreement means your company doesn’t cleanly own the code — something any serious investor or acquirer will catch immediately. These aren’t edge cases. They’re among the most common closing conditions flagged in investor due diligence of Indian startups.

    ESOP and cap table: reconcile every quarter

    If you’ve granted ESOPs (Employee Stock Ownership Plans — equity option grants to employees), the ESOP pool on your cap table must match the scheme document and every PAS-3 filing (a form filed with the ROC whenever shares are allotted). Granted but unvested options must be disclosed separately from vested-but-unexercised options. Investors and acquirers will reconcile this in the data room — mismatches add weeks to closing timelines. Run this check once a quarter, not once a year.

    Also verify your trademark status if you’ve filed one. The trademark registration process in India can take 18–24 months, and objections or oppositions during examination require a response within 30 days. Missing that window means abandonment. Set a quarterly reminder to check your application status on the CGPDTM (Controller General of Patents, Designs and Trade Marks) portal.

    Legal Compliances for Startups in India: A Practical Checklist for Founders

    Check #4 — HR, Labour Law, and Data Privacy Status

    If your headcount has changed in the last quarter, your labour law registrations may need updating. PF (Provident Fund) registration is mandatory once you cross 20 employees; ESIC (Employees’ State Insurance Corporation) kicks in at 10 employees in most states. Both have state-level Shops & Establishment Act registrations that require amendment when headcount, address, or working hours change.
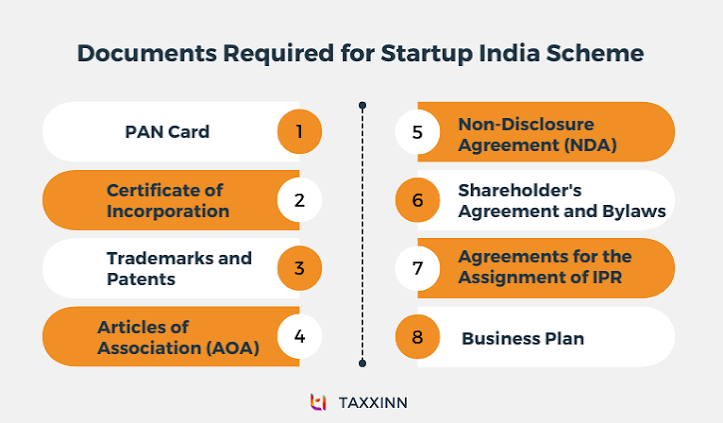
    The POSH Act (Sexual Harassment of Women at Workplace Act, 2013) requires every company with 10 or more employees to have a constituted Internal Complaints Committee (ICC). The ICC must submit an annual report to the district officer — but quarterly is a good time to confirm your ICC is still validly constituted, especially if a member has resigned or changed roles. Investors and large enterprise clients increasingly ask for proof of POSH compliance before signing.
    On data privacy: if your startup collects personal data from Indian users, the Digital Personal Data Protection Act 2023 (DPDPA) is already in play. Investors are treating DPDPA readiness as a legal due diligence item, particularly for B2C, SaaS, healthtech, and edtech startups. Each quarter, verify that your privacy policy reflects current data processing practices, your consent mechanisms are active and explicit, and any data processor agreements (DPAs — contracts with third-party vendors who handle your users’ data) are in place.
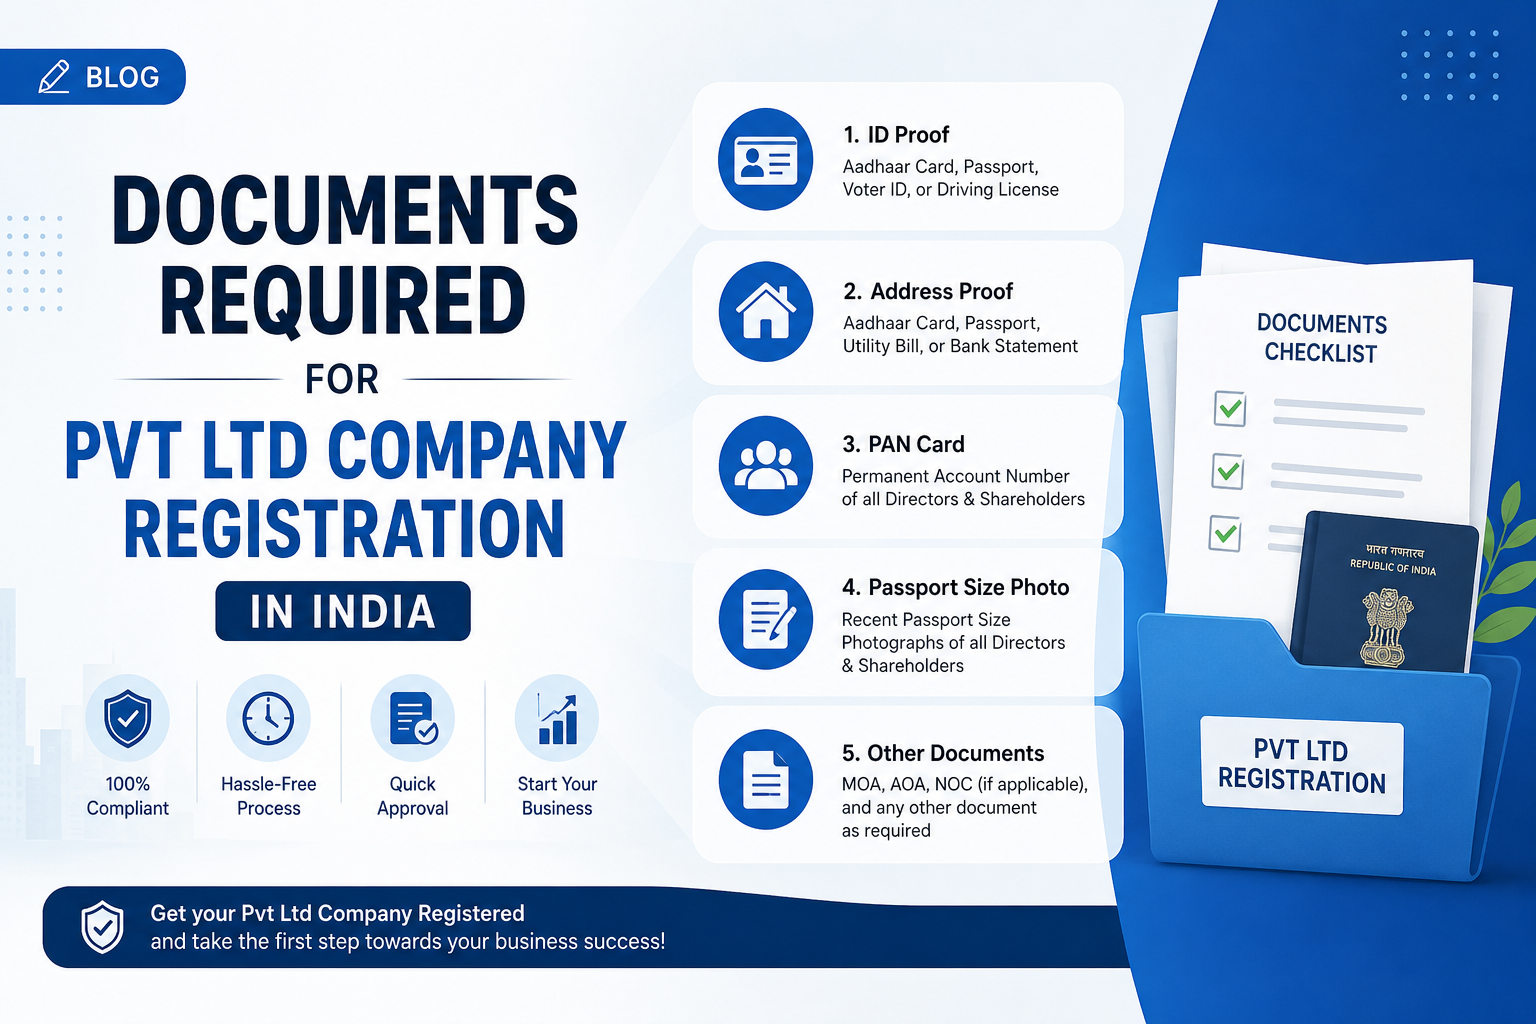
    If your business qualifies as an MSME, check that your MSME Udyam registration reflects your current NIC code, turnover, and investment in plant and machinery. An outdated Udyam certificate can cause you to miss government scheme benefits or create misrepresentation issues during tenders and bank loan applications.

    Frequently Asked Questions

    Q: Is a quarterly legal audit mandatory for startups in India?

    A: A quarterly legal audit is not mandated by law, but many of the compliance deadlines it tracks — TDS returns, e-invoicing, DIR-3 KYC, and POSH reporting — fall at quarterly or semi-annual intervals. Running a structured 90-day review ensures no deadline is missed between annual statutory audits. For funded startups, most investor agreements include a covenant requiring the company to remain in good regulatory standing, which effectively makes quarterly monitoring necessary.

    Q: What happens if a startup misses an ROC filing deadline?

    A: The MCA charges ₹100 per day of delay on most ROC forms including MGT-7 and AOC-4, with no upper cap. If a company fails to file annual returns for two consecutive years, the Registrar of Companies can initiate a strike-off under the Companies Act 2013, which leads to the company being removed from the register. Directors of struck-off companies can be disqualified from holding directorships in any Indian company for five years under Section 164(2).

    Q: How is a quarterly legal audit different from a statutory audit?

    A: A statutory audit is a mandatory annual financial review conducted by an independent chartered accountant under the Companies Act 2013 — it looks at whether your financial statements are accurate. A quarterly legal audit is an internal or advisor-led compliance review that checks whether all filings, registrations, contracts, and regulatory obligations are current and complete. The two serve different purposes and should both be in your compliance calendar.

    Q: Do DPIIT-recognised startups get any compliance exemptions?

    A: DPIIT (Department for Promotion of Industry and Internal Trade) recognition under the Startup India scheme unlocks three consecutive years of income tax exemption under Section 80-IAC, angel tax exemption under Section 56(2)(viib) for allotments after April 1, 2024, and self-certification under six labour laws. However, core MCA filings — AOC-4, MGT-7, GST returns, and TDS obligations — are not waived. A DPIIT-recognised startup that has crossed the ₹100 crore turnover threshold without updating its status creates a misrepresentation risk that any investor will flag.

    Q: What should I check in a legal audit before raising a funding round?

    A: Before opening a data room for investors, run a pre-due diligence legal audit covering: clean MCA filing history with no pending defaults, all director DINs active and KYC current, ESOP pool reconciled to PAS-3 filings, all founding IP assigned to the company (not held personally by founders), GST registration active with no unreconciled GSTR-2B mismatches, valid DPIIT recognition if applicable, and POSH compliance documented. Catching and fixing these items before the term sheet is signed prevents costly closing conditions that delay and sometimes kill funding rounds.

    Q: Can I do a legal audit myself or do I need a CA or lawyer?

    A: Founders can run the MCA portal checks, GSTR-2B reconciliation, and contract expiry reviews themselves with a structured checklist. However, TDS return verification, statutory audit coordination, ESOP scheme compliance, and DPDPA readiness typically require a CA or legal professional for accuracy. Many startups use a combination — founders track the calendar and flag items, while a CA or compliance platform handles the actual filing and remediation. The goal of a quarterly audit is early detection, not necessarily self-filing.

    Ready to clean up your startup’s compliance gaps?
    Lawizer’s experts handle everything — MCA and ROC filings, GST registration and returns, trademark registration, and MSME Udyam registration — fully online, starting at just ₹999. No CA visit needed.

    Start your compliance review on Lawizer →

  • Running a Business With a Friend? Read This Before You Make Them a Director:

    Running a Business With a Friend? Read This Before You Make Them a Director:

    Most Indian startup disputes don’t start with money. They start with a handshake — the moment you decided your friend would be a good person to build this with, and skipped the paperwork that would have protected both of you.

    Under the Companies Act, 2013, appointing a director isn’t a casual decision. It’s a legal act with consequences that outlast the friendship, and in some cases, outlast the company.


    TL;DR: Making someone a director gives them legal standing to act on behalf of your company — signing contracts, accessing bank accounts, voting on resolutions. Without a co-founder agreement and a well-drafted AOA, a falling-out can lock you out of your own business. This post covers exactly what rights a director gets, what liabilities come with the role, and how to structure the appointment so you stay protected.


    Founders Agreement in India (2026): Free Template, Key Clauses & Legal Guide

    What You’ll Learn

    • What legal rights a director gets the moment they’re appointed
    • What liabilities attach to a director — including ones most founders don’t expect
    • How director removal actually works under the Companies Act, 2013
    • Why a co-founder agreement is non-negotiable, and what it must cover
    • A checklist for appointing a co-founder director the right way

    What Happens the Moment You Appoint Someone a Director

    When your friend gets a DIN (Director Identification Number) and signs Form DIR-2, they become a director of record at the MCA. That’s not symbolic — it’s legal standing.

    From that point, your new director can:

    • Execute contracts and agreements on behalf of the company
    • Access company bank accounts (if authorised by the board)
    • Vote on board resolutions — including ones that affect your own position
    • Be held personally liable by regulators and creditors for the company’s defaults

    That last point is where most first-time founders are caught off guard. Under Section 166 of the Companies Act, 2013, every director owes a fiduciary duty to the company — not to you personally, and not to your friendship. They must act in the best interest of the company as defined by law, even when that conflicts with what you want.


    The Liabilities Your Friend Is Signing Up For

    This is the conversation most co-founders skip. A director in India can be personally liable for:

    • Tax defaults: Under Section 179 of the Income Tax Act, directors of a private company can be held personally liable for unpaid tax dues if the company’s assets are insufficient to cover them.
    • GST non-compliance: The GST Act allows recovery from directors personally if the company fails to deposit collected GST.
    • ROC filing defaults: Directors named in a company are responsible for ensuring annual filings — AOC-4, MGT-7, ADT-1 — are submitted on time. Defaults attract penalties starting at ₹100 per day per form, with no upper cap in many cases.
    • FEMA violations: For startups taking foreign investment, directors can face FEMA proceedings if filings to the RBI are missed.

    None of these liabilities disappear just because the directorship was informal or the company was small. Your friend needs to understand what they’re signing before they sign it.

    Duties & liabilities of director - Law Times Journal

    How Director Removal Actually Works (And Why It’s Harder Than You Think)

    Here’s the scenario nobody wants to think about until it’s too late: the partnership sours, and you want them out.

    Under Section 169 of the Companies Act, 2013, a director can be removed by an ordinary resolution at a general meeting — but the process has teeth:

    1. Special notice (28 days before the meeting) must be given to all members.
    2. The director being removed has the right to make a representation to the shareholders, which must be circulated before the vote.
    3. If the director also holds shares, their shareholding is completely unaffected by their removal as a director. They remain a shareholder.

    That last point is where co-founder disputes get expensive. You can remove someone from the board, but if they hold 25% of your company’s equity, they can still block special resolutions, access financial information as a member, and, depending on your AOA, may have pre-emption rights on share transfers.

    This is exactly why a co-founder agreement — drafted before any appointment — is not optional.


    What a Co-Founder Agreement Must Cover

    A co-founder agreement (sometimes structured as a Shareholders’ Agreement or SHA) is a private contract between founders. It doesn’t get filed with the MCA, but it is legally enforceable. At a minimum, it should address:

    • Equity split and vesting schedule: How much each founder holds, and whether shares vest over time (typically 4 years with a 1-year cliff). Vesting protects the company if a co-founder exits early.
    • Roles and decision-making authority: Which decisions require unanimity, which require majority, and who has operational authority over what.
    • IP assignment: All IP created by a co-founder must be formally assigned to the company — not left in their personal name.
    • Exit and buyout mechanics: What happens if a co-founder wants to leave, is removed, or dies — including a right of first refusal on their shares.
    • Non-compete and non-solicitation clauses: Standard protections for a defined period post-exit.

    Setting up your business registration properly from day one — with the right AOA provisions and a co-founder agreement locked in — is far cheaper than unwinding a badly structured partnership later.


    The Checklist: Appointing a Co-Founder Director the Right Way

    Before you file DIR-2 and DIR-12 with the MCA, work through this:

    • [ ] Co-founder agreement drafted and signed (before any MCA filing)
    • [ ] Equity split agreed in writing, with a vesting schedule if applicable
    • [ ] AOA reviewed — ensure it reflects your actual governance intentions (quorum rules, reserved matters, removal procedure)
    • [ ] DIN obtained for all new directors (apply via DIR-3 on MCA V3 portal)
    • [ ] DSC (Digital Signature Certificate) obtained — required for all MCA filings
    • [ ] DIR-2 (consent to act as director) signed and collected
    • [ ] DIR-12 (intimation of appointment) filed with the MCA within 30 days of appointment
    • [ ] Board resolution passed approving the appointment
    • [ ] New director added to company’s Register of Directors (Section 170)

    If your company takes any foreign investment now or in the future, also ensure your co-founder agreement and SHA are compatible with your cap table structure and FEMA requirements. A trademark registration for your brand, done early, also ensures that IP is in the company’s name before a co-founder dispute ever arises.


    Frequently Asked Questions

    Q: Can I appoint a friend as a director without giving them shares? A: Yes. Directorship and shareholding are legally separate under the Companies Act, 2013. You can appoint someone as a director with zero equity — they get governance rights but no ownership stake. Document this clearly in the co-founder agreement to avoid future claims.

    Q: What is the minimum number of directors for a private limited company? A: A private limited company requires a minimum of 2 directors and can have up to 15 (extendable by special resolution). At least one director must be ordinarily resident in India — meaning they have stayed in India for at least 182 days in the previous calendar year.

    Q: If my co-founder leaves, are they still liable for company defaults that happened while they were a director? A: Yes, in most cases. Liability under Section 179 of the Income Tax Act and equivalent provisions attaches to the period during which a person served as director. Filing Form DIR-11 (resignation) and DIR-12 (intimation) promptly limits exposure for future defaults, but past-period liabilities can survive a resignation.

    Q: Does a director removal affect their shareholding? A: No. Removal under Section 169 only ends their directorship. Their equity stake remains intact. If you want them out of the cap table as well, the co-founder agreement’s buyout clause — triggered by the removal — is the mechanism that handles that.

    Q: What happens if we never signed a co-founder agreement and the partnership breaks down? A: Without a co-founder agreement, disputes fall back on the Companies Act, the AOA, and general contract law — a much slower and more expensive resolution path. Courts have held that oral agreements among founders carry weight but are notoriously hard to prove. Get it in writing before the problem, not after.

    Q: Can a director be appointed without their knowledge? A: No. Form DIR-2 — the written consent to act as director — is mandatory and must be signed by the incoming director before DIR-12 is filed. Fraudulent appointment of directors without consent is a criminal offence under the Companies Act, 2013.


    Making someone a director is one of the most consequential decisions in your startup’s early life. Lawizer helps founders structure co-founder agreements, draft director appointment documents, and stay compliant with MCA filings — fully online, starting at ₹4,999. Get started →

  • Building a D2C Brand in India? Here Are the 6Legal Boxes You Must Tick First:

    Building a D2C Brand in India? Here Are the 6Legal Boxes You Must Tick First:


    India’s D2C market crossed $60 billion in 2025. Mamaearth, boAt, Lenskart — the proof of concept is well-established. What’s less discussed is the compliance stack sitting beneath every one of those brands, and what happens when a new founder skips it.

    The answer: seized shipments, forced rebrands, marketplace de-listings, and penalty notices that arrive long after your first sale. The six requirements below aren’t optional extras — they’re the legal floor your D2C brand must be built on before the first order ships.


    📌 TL;DR: Every D2C brand operating in India needs a registered business entity, GST registration, a trademark application, product-specific licences (FSSAI, BIS, or CDSCO depending on your category), Legal Metrology-compliant labelling, and Consumer Protection E-Commerce Rules compliance. Miss any one of these and you’re trading on borrowed time. Lawizer helps D2C founders get all of it done — fully online, from incorporation to trademark — without needing a CA in the room.


    What You’ll Learn

    • Why GST registration is mandatory even if your turnover is ₹0
    • What the Legal Metrology Act means for your product packaging and your website listing
    • Which product-specific licence your category actually needs
    • How the DPDP Act, 2023 changes what your checkout page must look like
    Is Direct-to-Consumer (D2C) the only way to go in 2024? -

    Box 1: Register the Right Business Entity

    Most D2C founders start as sole proprietors and immediately run into a wall — payment gateways require a registered entity, marketplace onboarding is smoother with a PAN in the company’s name, and investors won’t touch a proprietorship.

    A Private Limited Company is the recommended structure for any D2C brand with growth ambitions. It gives you limited liability, a clean cap table for future fundraising, and immediate credibility with marketplace category managers.

    If you’re a bootstrapped solo founder testing a single SKU category, an LLP is a leaner starting point — lower compliance cost than a Pvt Ltd, more structure than a proprietorship. Either way, registration happens through the MCA’s SPICe+ form and typically takes 10–15 working days. This is always Step 1 because every subsequent registration — GST, trademark, bank account, payment gateway — flows from your Certificate of Incorporation and company PAN.

    Lawizer handles startup and business legal registration end-to-end, including entity structuring advice if you’re undecided between Pvt Ltd and LLP.


    Box 2: GST Registration — Mandatory from Sale Day One

    Here’s the rule most D2C founders get wrong: the ₹40 lakh turnover threshold that exempts small businesses from GST does not apply to e-commerce sellers. Under Section 24 of the CGST Act, 2017, every person supplying goods through an e-commerce operator must register for GST regardless of turnover. If you’re selling on Amazon, Flipkart, Nykaa, or Meesho — even if you’ve made zero sales — you need a GSTIN before your first listing goes live.

    If you sell only through your own D2C website with turnover under the threshold, the exemption technically applies — but the moment you list on any third-party marketplace, that window closes. Given that most D2C brands use a mix of owned and marketplace channels, the practical answer is: register for GST immediately after incorporation.

    Your ongoing GST obligations include filing GSTR-1 (outward supply details), GSTR-3B (monthly summary return), and GSTR-9 (annual return), plus reconciling platform TCS (Tax Collected at Source) deductions from marketplaces against your actual liability. If your D2C brand stores inventory in warehouses across multiple states, you’ll also need GST registrations in each of those states — a requirement that catches fast-scaling brands off-guard.


    Box 3: File Your Trademark Early

    A trademark is the cheapest insurance a D2C brand can buy. At ₹4,500 per class for small enterprises (under the current fee schedule), it protects your brand name and logo from being registered by a competitor — and in the D2C world, copycats move fast. Beyond legal protection, a registered trademark (or even a pending application with an acknowledgment number) is required for Amazon Brand Registry, which unlocks A+ content, brand analytics, and counter-counterfeiting tools that directly affect your conversion rate.

    File in the right classes from day one. Common classes for D2C brands: Class 25 (clothing and footwear), Class 30 (food and beverages), Class 3 (cosmetics and personal care), Class 35 (online retail services). Most D2C brands need at least two classes — one for the product category and one for retail services. Registration takes 6–18 months from filing, but your protection date runs from the application date, not the registration date. File now.

    Trademark Registration in India

    Box 4: Product-Specific Licences — FSSAI, BIS, CDSCO

    This is where D2C founders most often underestimate their compliance surface area.

    FSSAI licence — mandatory for any brand selling food, beverages, dietary supplements, protein powders, health drinks, nutraceuticals, or even pet food. The licence tier depends on your annual turnover: registration for businesses up to ₹12 lakh turnover, state licence for ₹12 lakh to ₹20 crore, and central licence for above ₹20 crore or cross-state e-commerce. Operating without an FSSAI licence attracts a penalty of up to ₹5 lakh under Section 63 of the Food Safety and Standards Act, 2006. The 14-digit FSSAI licence number must appear on every product label and your website.

    BIS certification — required for electronics, electrical goods, and certain consumer products covered under mandatory BIS product orders. If your D2C brand sells LED lights, power banks, helmets, or kitchen appliances, BIS certification (and the ISI mark) is non-negotiable before you list a single unit.

    CDSCO approval — required for cosmetics under the Drugs and Cosmetics Act, 1940, as amended by the Cosmetics Rules, 2020. The key risk here: the moment your product makes a therapeutic claim (“reduces melanin production,” “treats acne”), it crosses from cosmetic to drug territory — triggering stricter regulations, and penalties including product seizure and imprisonment up to one year for misclassification.


    Box 5: Legal Metrology Act Compliance — The One Every Category Misses

    Most D2C founders associate compliance with the licences above. The Legal Metrology (Packaged Commodities) Rules, 2011 apply to every pre-packaged product sold in India — food, skincare, electronics, clothing, home décor, stationery, pet products. There are no exceptions for small businesses or D2C brands.

    Every product package must display: product name, net quantity in standard units, MRP inclusive of all taxes (preceded by “MRP ₹”), manufacturer or packer name and registered address, month and year of manufacture, consumer care contact details (name, address, phone, and email), and country of origin for imported goods.

    Critically, for e-commerce sellers, these declarations must appear not just on the physical packaging but also on the product listing page itself. Non-compliance carries a penalty of ₹25,000 to ₹50,000 per offence — and legal metrology officers can and do inspect marketplace listings.

    One additional obligation that’s quietly become an enforcement focus in 2025: Extended Producer Responsibility (EPR) registration under plastic and e-waste rules. If your D2C brand uses plastic packaging, your EPR registration number must appear on the packaging. Failure to register is treated as a serious violation under solid waste and plastic management rules.


    Box 6: Consumer Protection E-Commerce Rules, 2020 — and the DPDP Act, 2023

    The Consumer Protection (E-Commerce) Rules, 2020 apply to every D2C brand selling online. Your website or app must display: complete product details with a total price breakdown (no hidden fees), your return and refund policy, cancellation terms, delivery timelines, and seller identity.

    You are required to appoint a Grievance Officer, display that officer’s name and contact details on your platform, and resolve consumer complaints within 30 days. Violation attracts penalties under the Consumer Protection Act, 2019.

    Layered on top of this is the Digital Personal Data Protection (DPDP) Act, 2023 — which changes what your checkout and data collection flows must look like. D2C brands collect significant customer data: names, addresses, payment information, browsing behaviour.

    Under the DPDP Act, you must collect only what is necessary, provide a clear privacy policy, obtain explicit consent before collecting data, and enable customers to request data deletion. The penalty for non-compliance scales up to ₹250 crore — which is why building DPDP-compliant data practices into your website from launch is far cheaper than retrofitting them after a notice.

    MSME or Udyam registration is also worth completing at this stage — it’s quick, free, and unlocks priority credit, marketplace benefits, and government tender eligibility as your brand scales.

    Top D2C ECommerce Brands In India - A Case Study

    How Long Does This All Take?

    Company incorporation, GST, and Udyam registration can run in parallel — typically 15–20 working days combined. File your trademark application the same week as incorporation. Product-specific licences (FSSAI, BIS) run concurrently but may take longer depending on your category.

    Total time from zero to first compliant sale: 30–60 days, with a total compliance cost typically between ₹15,000 and ₹50,000 depending on the entity structure and licences required.

    The brands that build this foundation correctly don’t just avoid penalties — they get marketplace approvals faster, onboard payment gateways without delays, and walk into investor conversations with clean corporate records.


    Frequently Asked Questions

    Q: Is GST registration mandatory for a D2C brand that hasn’t made any sales yet? A: Yes, if you intend to sell through any third-party e-commerce platform. Section 24 of the CGST Act removes the turnover exemption for e-commerce sellers entirely. You need a GSTIN before your first listing goes live on any marketplace, regardless of whether any sales have occurred.

    Q: Do I need a trademark even if I’m just starting out and unsure the brand will succeed? A: Yes — and the earlier the better. Trademark protection dates back to your application date, not your registration date. Filing early costs the same as filing later, but protects you from a copycat who registers your brand name while you’re waiting to see traction. An acknowledgment number from the IP India portal is also sufficient for Amazon Brand Registry.

    Q: My D2C brand sells skincare. Do I need CDSCO approval or FSSAI? A: CDSCO (under the Drugs and Cosmetics Act, 1940 and Cosmetics Rules, 2020) governs cosmetics like serums, creams, and shampoos. FSSAI governs edible products. The critical line: if your skincare product makes a therapeutic claim (treats a condition, alters a biological process), it shifts from cosmetic to drug regulation — with significantly higher compliance requirements and penalties for misclassification.

    Q: Does the Legal Metrology Act apply to my D2C website listing, or just the physical packaging? A: Both. Under amendments to the Legal Metrology (Packaged Commodities) Rules, e-commerce entities must display all mandatory declarations — MRP, net quantity, manufacturer details, and consumer care contacts — on the product listing page itself, not just on the physical label. Marketplace listings that omit these are actively flagged during inspections.

    Q: What does the DPDP Act, 2023 require from a D2C brand’s website? A: The Digital Personal Data Protection Act, 2023 requires D2C brands to collect only data that is necessary for the stated purpose, display a clear and accessible privacy policy, obtain explicit consent before collecting personal data, and provide customers with a mechanism to request correction or deletion of their data. Non-compliance penalties scale up to ₹250 crore — making early implementation far more cost-effective than corrective compliance after a notice.

    Q: Can Lawizer handle all six of these registrations as a single project? A: Yes. Lawizer handles company incorporation, GST registration, trademark filing, FSSAI licensing, and Udyam registration — fully online, with no CA visit required. Starting your business registration correctly from day one means you’re eligible for marketplace onboarding, payment gateway integration, and investor due diligence from launch.


    Ready to launch your D2C brand on solid legal ground? Lawizer gets your company registered, GST filed, trademark applied, and sector licences in place — fully online, starting at ₹4,999. No office visits, no missed boxes.

    Start your D2C brand registration →

  • Section 8 Company vs NGO vs Trust: Which
Structure Is Right for Social Startups?

    Section 8 Company vs NGO vs Trust: Which Structure Is Right for Social Startups?

    Out of India’s roughly 1.87 lakh registered NGOs, only about 11,000 are Section 8 companies — the rest are trusts and societies. So if you’re picking a legal structure for your social startup, the popular choice isn’t always the right one for you.

    Get this wrong and you’ll either drown in compliance you didn’t need, or hit a funding wall you didn’t see coming.

    TL;DR: Choosing between a Section 8 company, a Trust, and a Society comes down to three things — how much compliance you can handle, how big your funding ambitions are, and how much control you want to keep. Trusts are cheapest and simplest, Societies suit membership-driven groups, and Section 8 companies win on credibility for CSR and foreign funding. Lawizer helps social founders register and stay compliant with all three structures under one roof.


    What You’ll Learn

    • The real difference between a Section 8 company, a Trust, and a Society
    • Which structure costs less to run every year
    • How the new Income Tax Act 2025 changes tax treatment for all three
    • A simple decision framework based on your startup’s scale and funding goals

    Section 8 Company, Trust, and Society: What Each One Actually Is

    Here’s the thing: “NGO” isn’t a legal structure at all. It’s an umbrella term. Every NGO in India is registered as one of three things — a Trust, a Society, or a Section 8 Company — and each answers to a different law.

    A Trust is created under the Indian Trusts Act, 1882 (or your state’s public trust law), through a Trust Deed. A trustee holds assets on behalf of beneficiaries. You need just 2 trustees, there’s no elected body, and once trustees are in, they typically stay for life unless the deed says otherwise.

    A Society is registered under the Societies Registration Act, 1860, and needs a minimum of 7 members plus a governing body that’s usually elected. It’s the go-to structure for membership-driven groups — alumni associations, cultural bodies, community welfare organisations.

    A Section 8 Company is registered with the Ministry of Corporate Affairs (MCA) under the Companies Act, 2013. It functions like a private limited company — directors, MOA, AOA — except profits can never be distributed to members and must go back into the company’s charitable objects.


    Cost and Compliance: The Number That Actually Matters

    What most founders miss: the registration fee is a one-time cost. The compliance bill is the one that decides whether your structure survives year three.

    A Trust’s annual compliance typically runs ₹5,000–₹15,000 — basic bookkeeping and an income tax filing, with no regulator breathing down your neck beyond that.

    A Section 8 Company, on the other hand, usually costs ₹25,000–₹75,000 a year to keep compliant: statutory audits, annual ROC filings (AOC-4, MGT-7), board meeting records, and adherence to accounting standards.

    A quick example: if your social startup runs on an annual budget under ₹25 lakh with two or three people managing it, that compliance overhead can eat a real chunk of your funds before a single rupee reaches your beneficiaries.

    • Trust — cheapest, minimal ongoing paperwork, no regulator beyond Income Tax
    • Society — moderate compliance, needs annual general meetings and elected renewals
    • Section 8 Company — highest compliance, mandatory audits, ROC filings every year

    Funding and Credibility: Where Section 8 Pulls Ahead

    The short answer: if your growth plan involves corporate CSR money or foreign donors, a Section 8 Company gives you a real edge. Companies collectively spent over ₹1,84,222 crore on CSR between 2014 and 2023, and most large corporates prefer routing that money to Section 8 entities because their filings sit publicly on the MCA portal — donors can verify legitimacy without asking.

    Trusts and Societies aren’t shut out of CSR or 80G benefits, but they lean on informal trust and local reputation rather than a public paper trail. That works well for grassroots and community-level work, but it slows you down the moment you’re pitching a national foundation or an overseas funder for a six-figure grant.

    Setting up your business registration the right way from day one also makes it easier to layer on 12A and 80G approvals later, regardless of which structure you pick.


    Income Tax Act 2025: The Rule That Changes Everything

    Let’s break this down, because this is the part most 2024-era comparisons still get wrong. From 1 April 2026, the Income Tax Act 2025 introduces a unified “Registered Non-Profit Organisation” (RNPO) framework under its Chapter on non-profits — and it applies identically to Trusts, Societies, and Section 8 Companies.

    Under this framework, all three structures file the same Form 10A for provisional registration (valid 3 years) and Form 10AB for regular registration (valid 5 years, or 10 years if income stays under ₹5 crore for two preceding years). The 85% income-application rule and cancellation grounds are also now identical across structures.

    What this means practically: your choice of structure no longer changes your tax exemption eligibility. It only changes your governance model, your compliance workload, and how easily you can raise institutional money — which is exactly why the cost and credibility factors above matter more than ever.


    So Which Structure Should Your Social Startup Pick?

    Here’s a simple way to decide, based on where your startup actually is today — not where you hope it’ll be in five years.

    • Choose a Trust if you’re a small, family-led, or founder-controlled initiative with a budget under ₹25 lakh and no near-term plans for CSR or foreign funding.
    • Choose a Society if your work is membership-based — think alumni networks, cultural collectives, or community welfare groups that want democratic, elected leadership.
    • Choose a Section 8 Company if you’re building for scale — planning to approach corporate CSR desks, apply for government grants, or eventually register under MSME as your social enterprise grows commercially alongside its charitable arm.

    One more thing worth knowing: you can start as a Trust and move to a Section 8 Company later once you have traction — you can’t directly “convert” a Trust into one, but you can incorporate the Section 8 entity fresh and transfer operations across, subject to legal formalities.


    Frequently Asked Questions

    Q: Which is better, Trust or Section 8 company, for a small NGO?

    A: For a small, founder-run NGO with a limited budget, a Trust is usually better because it costs less to set up and maintain every year. Move to a Section 8 Company once you’re actively pursuing CSR funding or foreign donations that require higher transparency.

    Q: Can a Section 8 company have just 2 people running it?

    A: Yes. A Section 8 Company needs a minimum of 2 directors and 2 subscribers, and the same two people can hold both roles. You’ll need Digital Signature Certificates (DSC) and Director Identification Numbers (DIN) for both, which adds roughly ₹2,000–₹4,000 to setup costs.

    Q: Does the Income Tax Act 2025 change which structure I should pick?

    A: Not directly on tax grounds. From 1 April 2026, Trusts, Societies, and Section 8 Companies all follow the identical RNPO registration process for tax exemption. Your structure choice should now be based on governance style, compliance capacity, and funding goals rather than tax benefits.

    Q: Is a Section 8 company the same as an NGO?

    A: A Section 8 Company is one type of NGO, not a synonym for it. NGO is the broad category; Trust, Society, and Section 8 Company are the three specific legal structures you can register an NGO under in India.

    Q: Can I convert my existing Trust into a Section 8 company?

    A: You cannot directly convert a Trust into a Section 8 Company under current law. Instead, you register a new Section 8 Company and transfer the Trust’s assets and operations to it, following the applicable legal and tax procedures.


    Ready to register your social startup the right way? Lawizer’s experts handle Trust, Society, and Section 8 Company registration — plus 12A, 80G, and FCRA guidance — fully online, starting at just ₹4,999. No CA visit needed.

  • India’s New Income Tax Act 2025Key Changes Startup
Founders Must Know  :

    India’s New Income Tax Act 2025Key Changes Startup Founders Must Know :

    Six decades. That’s how long the Income Tax Act, 1961 governed every rupee of business income in India — and on April 1, 2026, it got replaced. If you’re running a startup, this isn’t a “read it later” compliance update. Your ESOP grant letters, TDS filings, and advance tax workings are already operating under a different rulebook.

    Here’s the part that trips up most founders: you’re currently filing your FY 2025-26 return under the old 1961 Act, even though your business has been operating under the new 2025 Act since April 1. Two legal frameworks, running in parallel, for at least one filing cycle. Let’s break this down.

    📌 TL;DR: The Income Tax Act, 2025 replaced the Income Tax Act, 1961 with effect from April 1, 2026, cutting the law down from roughly 819 sections to 536 and introducing a single “Tax Year” concept that replaces the old Financial Year/Assessment Year split. For startups, the core benefits — the Section 80-IAC tax holiday, angel tax exemption, and loss carry-forward protection — continue under renumbered sections, but ESOP deferral windows, TDS section numbers, and compliance documentation all need updating.


    What You’ll Learn

    • Why the government replaced a 64-year-old tax law and what actually changed
    • What “Tax Year” means and why it replaces Financial Year and Assessment Year
    • How your startup’s 80-IAC tax holiday, angel tax exemption, and ESOP terms carry over
    • What TDS and compliance changes to prepare for right now

    Why the Old Act Got Replaced

    The Income-tax Act, 1961 was built for a paper-based economy with face-to-face assessments. Over six decades, patchwork amendments pushed it past 800 sections spread across 47 chapters. That overgrowth raised compliance costs and fuelled disputes with multi-year case backlogs. It also never sat comfortably with e-commerce, platform income, or cross-border digital transactions — problems that simply didn’t exist when the law was written.

    The government’s response was structural, not cosmetic. The new Act reduces provisions from 819 sections to 536, received Presidential assent in 2025, and came into force on April 1, 2026, applicable from Tax Year 2026-27 onwards. The reassuring part for founders: the core scheme and fundamental principles of the old Act largely remain intact. This is a rewrite for clarity, not a redesign of how tax is calculated.


    “Tax Year” Replaces Financial Year and Assessment Year

    This is the single change every founder will notice on every form, notice, and Form 16 going forward.

    Under the old system, income earned in one year — called the Previous Year or Financial Year — was assessed in the following year, called the Assessment Year. So income from FY 2024-25 was taxed in AY 2025-26. This dual-reference system was unique to India and created confusion that persisted for 64 years. Tax professionals estimated that selecting the wrong Assessment Year was among the top five reasons for defective return notices across the country.

    The new Act scraps both terms. A single “Tax Year” now covers both the earning and assessing of income under one label — defined simply as the 12-month period from April 1 to March 31. No more one-year lag, no more juggling two different year labels for the same income.

    What most founders miss: this change doesn’t alter when you file or how much you owe. It only removes the confusion. If you incorporate mid-year, your first Tax Year runs from your incorporation date to the following March 31, exactly as the old Previous Year rules worked for new businesses.

    The short answer for your filing this July: you’re still submitting an AY 2026-27 return under the old 1961 Act for income earned in FY 2025-26. The new Act only governs income earned from April 1, 2026 onwards. Your first Tax Year 2026-27 return under the new law isn’t due until mid-2027.


    7 Legal Tax-Saving Strategies Every Startup Founder Should Use (2026)

    What Happens to Section 80-IAC, Angel Tax, and Your Startup Benefits

    If your company has DPIIT (Department for Promotion of Industry and Internal Trade) recognition, the benefits you’ve been counting on don’t disappear — they move.

    The 100% profit deduction for any three consecutive years out of your first ten, formerly under Section 80-IAC, now sits under Section 140 of the new Act. Angel tax — the provision that once taxed share premiums above fair market value as “income from other sources” — was already abolished with effect from April 1, 2025 under Finance Act 2024, and that relief carries forward cleanly into the new framework. Section 79’s protection of carried-forward losses through funding rounds also continues, so a fresh priced round won’t wipe out your accumulated losses, as long as original promoters retain control.

    Here’s the thing founders keep getting wrong: DPIIT recognition alone still doesn’t activate the tax holiday. You need a separate Inter-Ministerial Board (IMB) certificate obtained by filing Form 1 with the Income Tax Department. As of early 2026, only around 3,700 startups had received IMB approval out of over 2.07 lakh DPIIT-recognised companies. Most founders hold the DPIIT certificate, assume they’re covered, and quietly miss out on a benefit worth lakhs in saved tax.

    On ESOPs, pay close attention. The eligible-startup ESOP tax deferral mechanism moves to Section 392 of the new Act. Allotments made from April 1, 2026 onwards now carry a 60-month deferral window — up from the earlier 48 months — before perquisite tax becomes due. But this extended window only applies if your company holds the IMB certificate, not just DPIIT recognition. Every grant letter, ESOP scheme document, and board resolution still citing 1961-Act section numbers needs to be re-papered for allotments dated April 1, 2026 onwards. It’s a paperwork task, not a legal overhaul, but skipping it creates filing inaccuracies your company is responsible for correcting.

    Latest TDS Rates Chart Tax Year 2026-27 | Effective April 2026

    TDS Compliance: Fewer Sections, But a Documentation Overhaul

    TDS (Tax Deducted at Source) is where founders feel the new Act most directly, because it touches every vendor payment, contractor invoice, rent cheque, and salary run.

    Under the old Act, businesses navigated roughly 37 separate TDS sections — Section 194A through 194T — each with different thresholds, rates, and filing requirements. The new Act consolidates these into around 20 sections. Section 393 is now the primary TDS provision, with related payment categories grouped as subsections rather than standalone sections.

    Fewer sections should mean fewer thresholds to memorise. But the documentation overhaul that comes with this is non-trivial. Here’s what your team needs to update before your Tax Year 2026-27 compliance work begins:

    Chart of accounts: Remap all entries from old section numbers to new equivalents

    TDS rate schedules: Update internal rate cards and accounting software configs

    Payroll configurations: Reflect the current standard deduction under the new Act

    Vendor contracts and SOPs: Any reference to old section numbers in payment terms or vendor agreements needs updating

    ESOP documentation: As noted above — grant letters, board resolutions, and scheme documents

    A quick example: if your Bengaluru startup pays a Razorpay or Meesho integration partner, the TDS deduction on that payment now references a different section number. Your accountant may already know this, but your internal finance team’s SOP likely doesn’t. The correction obligation sits with your company, not your CA firm.


    Frequently Asked Questions

    Q: Does the Income Tax Act 2025 apply to my ITR filing this year?

    No, not yet. If you’re filing your return in July 2026 for income earned in FY 2025-26, you’re still governed by the Income Tax Act, 1961. The new Act only applies to income earned from April 1, 2026 onwards. Your first return under it isn’t due until mid-2027.

    Q: Will my startup’s tax holiday under Section 80-IAC still apply?

    Yes. The three-year, 100% profit deduction benefit continues under the new Act, now positioned under Section 140. Eligibility rules remain the same — you need both DPIIT recognition and a separate IMB certificate obtained by filing Form 1 with the Income Tax Department.

    Q: What is a “Tax Year” and how is it different from Financial Year?

    Tax Year is a single 12-month period from April 1 to March 31 that replaces both the old Financial Year (when income was earned) and Assessment Year (when it was taxed and filed). Under the new Act, the year you earn income and the year you report it share the same label, removing the one-year offset that caused decades of confusion.

    Q: Do I need to update my ESOP grant letters?

    Yes, if they reference 1961-Act section numbers and cover allotments dated April 1, 2026 or later. Those allotments fall under Section 392 of the new Act. If your company holds an IMB certificate, the perquisite tax deferral window on new allotments also extends from 48 months to 60 months.

    Q: Is angel tax really gone for good?

    The provision taxing share premiums above fair market value was abolished from April 1, 2025 and doesn’t reappear anywhere in the new Act. If you raised funding before that date, it’s worth checking with your CA whether any prior assessments remain open.

    Q: How many TDS sections do we need to track now?

    Roughly 20, down from about 37 under the old Act. Section 393 is now the primary TDS provision, with payment categories grouped as subsections rather than separate standalone sections.


    Ready to get your startup compliant under the new Act?

    Lawizer’s experts handle Income Tax Act 2025 transition reviews, DPIIT and IMB certification, and ongoing ITR filing — fully online, starting at just ₹999. No CA visit needed.

    Talk to a Lawizer expert → lawizer.com/startup-businesslegal

  • POSH Compliance for Indian Startups: The Complete Founder’s Guide

    POSH Compliance for Indian Startups: The Complete Founder’s Guide

    A CEDA study surveying 200 senior HR officers found that 59% of Indian organisations had not set up an Internal Complaints Committee — the single most critical requirement under the POSH Act 2013. For startups hiring their 10th employee this month in Bengaluru or Pune, that statistic is a legal liability, not just a data point. POSH compliance for startups India isn’t optional. It’s a statutory obligation with a penalty of ₹50,000 on the first offence, escalating to licence cancellation on repeat violations.

    The MCA made it even harder to ignore: from July 14, 2025, every company must now disclose POSH complaint data inside its Board Report. Founders who treat POSH as an HR afterthought are about to face audit tables, District Officer surveys, and Supreme Court-directed district-level verification checks. Here’s everything you need to set it up correctly — before a complaint forces you to.

    TL;DR: Every Indian startup with 10 or more employees must comply with the Sexual Harassment of Women at Workplace (Prevention, Prohibition and Redressal) Act, 2013 — commonly called the POSH Act. POSH compliance for startups India requires constituting an Internal Complaints Committee (ICC), drafting and displaying a POSH policy, conducting annual awareness training, and filing an ICC Annual Report by January 31 each year. Non-compliance attracts a fine of up to ₹50,000 (with licence cancellation for repeat offences), plus mandatory Board Report disclosures under the MCA’s July 2025 amendment. Lawizer can help you set up the full POSH framework — policy, ICC, and filings — entirely online.

    What You’ll Learn

    — When exactly the POSH Act applies to your startup and who it covers — How to constitute a legally valid ICC under Section 4 of the POSH Act — What your POSH policy must include, how to display it, and annual filing requirements — Penalties your startup faces for non-compliance in 2025 and 2026 — The 2025 MCA amendment and SHe-Box registration — what changed and what you must do now

    When Does the POSH Act Apply to Your Startup?

    The Sexual Harassment of Women at Workplace (Prevention, Prohibition and Redressal) Act, 2013 kicks in the moment your organisation crosses 10 employees. And the headcount isn’t restricted to permanent staff on payroll. Interns, contractual workers, freelancers, consultants, and even gig workers attached to your business all count toward the threshold. A Bengaluru SaaS startup with 8 full-time engineers and 3 contract QA testers? That’s 11 people. POSH applies immediately.

    Here’s the thing: the Act covers every kind of workplace. Remote employees, hybrid setups, client sites, co-working spaces like WeWork or IndiQube — all fall under ICC jurisdiction. A 2024 advisory from the Ministry of Women and Child Development explicitly extended POSH obligations to remote and work-from-home arrangements, making digital workplace conduct — Slack messages, Zoom calls, email — covered behaviour. “PoSH will stop being location-related and become behaviour-oriented,” as one HR professional put it. Startups that scaled fast through the pandemic and never addressed POSH are now operating in a high-risk grey zone.

    What most founders miss: if your startup has fewer than 10 employees, you don’t need an ICC — but you must ensure your team is aware of the Local Complaints Committee (LCC) constituted by the District Officer under Section 6. Once you cross 10, the ICC obligation is immediate. There’s no grace period in the Act.

    How to Constitute a Valid ICC Under Section 4

    The Internal Complaints Committee (ICC) — the body mandated under Section 4 of the POSH Act to receive, investigate, and resolve workplace sexual harassment complaints — is the structural backbone of your entire POSH framework. Get the composition wrong and every inquiry the ICC conducts can be legally challenged. District Officer surveys and the Supreme Court’s August 2025 direction in Aureliano Fernandes v. State of Goa have placed incorrectly constituted ICCs directly in the crosshairs of enforcement.

    A legally valid ICC must have at minimum four members. Here’s the exact composition:

    Presiding Officer: A senior woman employee. She chairs the ICC and signs off on the Annual Report.

    Two internal members: Employees committed to the cause of women’s rights or with experience in social work. At least one must be from the same establishment.

    One external member (mandatory): A person from an NGO or association committed to women’s rights, or a lawyer or advocate with relevant expertise. This is not optional. An ICC without an external member is improperly constituted and its findings are voidable.

    At least 50% of ICC members must be women. Members serve a maximum term of 3 years, after which the ICC must be reconstituted or members renewed. The founding document — an ICC constitution order signed by the CEO or authorised signatory — must be issued, appointment letters sent, and ICC details published on your intranet and displayed on notice boards. This is the paperwork most early-stage founders in Delhi and Mumbai skip entirely.

    A Quick Example: How a 15-Person Startup Should Structure Its ICC

    Say you’re a 15-person fintech in Hyderabad. Your Presiding Officer could be your senior woman engineer or a woman co-founder. Two internal members — one from ops, one from product. Your external member could be empanelled through a POSH compliance services firm or sourced from a local NGO working on women’s issues. Issue appointment letters, fix a small honorarium for the external member, and document the constitution order. That’s your ICC. Simple — but you have to actually do it.

    startup support and compliance - Company Registration Trivandrum | GST Trivandrum | Trademark | Partnership | LLP | Project Report Thiruvananthapuram | Startup

    Drafting Your POSH Policy: What Must Actually Be in It

    Under Section 19 of the POSH Act read with Rule 13 of the POSH Rules, 2013, every employer must formulate a written POSH policy and disseminate it widely. A generic template downloaded from the internet is not enough — courts have held that a boilerplate policy that employees have never seen is no different from having no policy at all. Your POSH policy must include at minimum:

    — A clear definition of sexual harassment with workplace-specific examples (physical, verbal, non-verbal, digital) — The complete complaint procedure — how to file, timelines, and what happens after — Protections for complainants, witnesses, and ICC members against retaliation — Confidentiality obligations — breaching these attracts a separate fine of ₹5,000 — ICC member names, contact details, and the external member’s credentials — Penal consequences of sexual harassment under both the POSH Act and the Bharatiya Nyaya Sanhita, 2023 (which replaced the IPC)

    Once drafted, the policy must be displayed prominently — both physically (notice boards, breakrooms) and digitally (company intranet, onboarding portal). Every new hire must be oriented on the policy. Annual awareness training for all employees is mandatory, not just for ICC members. If your startup uses Zoho People or Darwinbox, embed the POSH policy acknowledgement into the onboarding flow — that creates a documented paper trail if a complaint is ever raised. You can get expert help structuring a watertight compliance framework through Lawizer’s startup legal services (https://lawizer.com/startup-businesslegal), which covers POSH policy drafting alongside incorporation, IP, and employment contracts.

    Statutory Timelines: What Happens After a Complaint Is Filed

    Let’s break this down. Once a complaint lands with the ICC, the POSH Act prescribes a strict inquiry timeline that cannot be ignored. Missing these deadlines exposes the employer — not just the ICC — to legal liability.

    7 days: Complaint copy must be sent to the respondent after ICC receives it 10 working days: Respondent must submit reply with evidence and witnesses 90 days: Full inquiry must be completed 10 days post-inquiry: ICC must issue its report to employer and both parties 60 days post-report: Employer must act on ICC recommendations 90 days: Window for either party to appeal before a Labour Court or tribunal

    What most founders miss: an internal POSH inquiry does not bar criminal action. A complainant can simultaneously file under the Bharatiya Nyaya Sanhita or pursue civil damages. The two tracks run in parallel. This is why thorough ICC documentation — verbatim interview notes, evidence chain of custody, reasoned findings — matters far more than founders realise. One poorly documented ICC inquiry can turn into a High Court writ petition under Article 226 citing natural justice violations.

    HR Policy Template for Small Businesses

    Annual Filings, MCA 2025 Amendment, and SHe-Box Registration

    POSH compliance isn’t a one-time setup. There are recurring annual obligations that every startup must calendar. Under Section 21 of the POSH Act, the ICC must submit an Annual Report to both the employer and the District Officer — typically by January 31 each year (some states like Gurugram have moved this to February 28). The report must capture the number of complaints received, disposed of, and pending beyond 90 days, along with details of awareness training conducted.

    The July 2025 MCA amendment — through the Companies (Accounts) Second Amendment Rules, 2025, effective July 14, 2025 — added a significant new layer. Every company must now disclose inside its Board Report: the number of POSH complaints received, disposed of, and pending beyond 90 days, plus the gender composition of the workforce. Missing these disclosures can attract penalties up to ₹5 lakh under the Companies Act, 2013. This means POSH data is now part of your ROC filing — a hard deadline item alongside AOC-4 and MGT-7 for your Private Limited Company.

    Additionally, the SHe-Box (Sexual Harassment Electronic Box) portal — run by the Ministry of Women and Child Development — now requires IC registration. The Delhi government directed all entities to register their internal committees on SHe-Box in June 2025, following the Supreme Court’s directive. Protecting your startup legally from multiple fronts — from POSH to trademark disputes — is best handled end-to-end; Lawizer’s business protection services (https://lawizer.com/startup-businesslegal/protectbusiness/TrademarkRegistrationPage) cover both legal compliance and IP protection in one place.

    Penalties for POSH Non-Compliance: What Your Startup Actually Risks

    The short answer: the consequences are real, escalating, and now harder to ignore than ever. Under Section 26 of the POSH Act, failure to constitute an ICC, failure to act on ICC recommendations, or failure to file annual reports are all punishable offences. Here’s how the penalty structure breaks down:

    First offence: Fine up to ₹50,000 Repeat offence: Double penalty (₹1,00,000+) and potential cancellation of business licence or startup registration Board Report non-disclosure (Companies Act 2013): Penalties up to ₹3,00,000 to ₹5,00,000 for false or missing statements in Directors’ Report Confidentiality breach by ICC members: Fine of ₹5,000

    The enforcement environment has also sharpened dramatically. In August 2025, the Supreme Court in Aureliano Fernandes v. State of Goa directed all States and Union Territories to conduct district-wise surveys within six weeks to verify whether ICs had been constituted. Non-compliance during those surveys could result in regulatory action including refusal of licence renewals. For a DPIIT-recognised startup or a company seeking government tenders, a POSH non-compliance flag is an existential risk — not just a fine.

    Frequently Asked Questions

    Q: Does POSH apply to my startup if I have only 10 employees?

    A: Yes. Section 4 of the POSH Act mandates ICC constitution at every establishment with 10 or more employees. This count includes permanent, contractual, intern, and freelance workers. The obligation kicks in from the day your headcount crosses the threshold — there is no grace period, and “10 employees” is a hard statutory trigger, not a guideline.

    Q: What happens if my startup doesn’t have a single woman employee — do I still need an ICC?

    A: Yes. The POSH Act’s protective scope covers all women who interact with your workplace — clients, vendors, delivery partners, women visiting the office. The ICC obligation is tied to the employer’s headcount, not to whether you currently have women on staff. Additionally, future hiring will almost certainly bring women employees, and setting up the ICC proactively avoids scrambling later when a complaint actually lands.

    Q: Can a co-founder or director serve as the Presiding Officer of the ICC?

    A: A woman co-founder or senior woman employee can serve as Presiding Officer, provided she meets the requirement of being a “senior woman employee” as per Section 4 of the POSH Act. However, she must not have a conflict of interest with either the complainant or respondent in any inquiry. For very small startups where all senior women are founders, engaging an external POSH consultant to play a structured advisory role alongside internal members is a sensible approach.

    Q: What changed with the MCA July 2025 amendment and how does it affect my annual filing?

    A: The Companies (Accounts) Second Amendment Rules, 2025, effective July 14, 2025, require every company to include detailed POSH disclosures in its Board’s Report — the number of complaints received, disposed of, and pending beyond 90 days, plus the gender composition of the workforce. These disclosures become part of your ROC annual filing under the Companies Act, 2013. Missing or inaccurate disclosures can attract penalties up to ₹5 lakh on the company and its directors.

    Q: Do I need to file a POSH Annual Report even if there were zero complaints during the year?

    A: Yes. The ICC Annual Report must be filed with the District Officer by January 31 (or your state’s applicable deadline) regardless of whether any complaints were received. A zero-complaint year still requires reporting on ICC constitution details, awareness training conducted, and overall compliance status. Filing demonstrates your prevention framework is active — and that itself is what regulators and auditors look for.

    Q: What is the SHe-Box portal and is registration mandatory for startups?

    A: SHe-Box (Sexual Harassment Electronic Box) is the central complaint portal run by the Ministry of Women and Child Development. It allows any woman to file a workplace sexual harassment complaint online, routed to the appropriate IC or LC. Following the Supreme Court’s directive and the Delhi government’s June 2025 order, all entities — including private startups — are required to register their Internal Committees on SHe-Box. Non-registration is increasingly treated as evidence of POSH non-compliance during District Officer surveys.

    Ready to set up POSH compliance for your startup? Lawizer’s experts handle everything — ICC constitution, POSH policy drafting, annual report preparation, and SHe-Box registration — fully online, starting at just ₹2,999. No lengthy back-and-forth with compliance consultants needed.

    Get Your POSH Framework Set Up → https://lawizer.com/startup-businesslegal


  • MCA V3 Portal: What’s New, What Broke, and How to File Without Errors?

    MCA V3 Portal: What’s New, What Broke, and How to File Without Errors?

    Over 23,000 companies registered on the MCA V3 portal in September 2025 alone — nearly double the figure from the same month the year before. The Ministry of Corporate Affairs has fully shut down V2 and moved every statutory filing to MCA21 V3. If your team is still working off V2 muscle memory, your next AOC-4 or MGT-7 submission is going to bounce.

    Here’s everything that changed, what’s still breaking, and the exact steps to file clean the first time.

    📌 TL;DR: MCA V3 portal replaced V2 permanently on June 18, 2025, with all 38 e-forms now mandatory on V3 from July 14, 2025. Key changes include web-based filing, linked form structures for AOC-4 and MGT-7, mandatory absolute rupee figures, and a new “My Application” dashboard. MCA V3 portal filing errors most commonly stem from DSC mismatches, wrong filing sequence, and rounded-off financials. Lawizer’s compliance team can handle your ROC filings end-to-end so you don’t miss a deadline.

    Annual Report Pictures | Download Free Images on Unsplash

    What You’ll Learn

    • What actually changed from V2 to V3 and why V2 filings no longer work
    • The new linked filing structure for AOC-4, MGT-7, and CSR-2
    • The most common MCA V3 errors and exactly how to fix each one
    • Penalties under the Companies Act 2013 for late or rejected filings
    • A pre-filing checklist so you file clean, the first time

    What Changed: V2 Is Gone, V3 Is Mandatory

    The MCA21 V3 portal (mca.gov.in) didn’t arrive overnight. MCA rolled it out in phases starting 2022. But the hard deadline came fast: V2 was permanently discontinued on June 18, 2025. The final batch of 38 e-forms — covering annual returns, financial statements, XBRL filings, CSR reporting, and audit forms — migrated exclusively to V3 from July 14, 2025. Any SRN created on V2 and left incomplete had to be refiled from scratch on V3.

    Here’s the thing. This isn’t just a cosmetic upgrade. V3 is a fundamentally different system. V2 ran on downloadable PDF forms you’d fill offline and upload. V3 is entirely web-based — you fill forms directly in your browser, with real-time validation, smart pre-filling from company master data, and a linked filing architecture that connects forms to each other automatically.

    Your CIN auto-populates your company name, address, and registered directors. If you’re filing AOC-4 after MGT-7, the portal pulls financial data from your annual return without you re-entering it.

    The new “My Application” dashboard is genuinely useful. You can track every form you’ve ever filed, see its current status — Draft, Uploaded, Under Processing, Pending DSC Upload, Resubmission Required — and pick up where you left off.

    This alone reduces the chaos of filing season for companies managing multiple ROC submissions.

    Two login modes now exist: OTP-based (email or mobile) and DSC-based. For signing and submitting statutory forms, DSC login remains mandatory.

    The New Linked Filing Structure (And Why Sequence Matters)

    This is where most MCA V3 portal filing errors actually begin. V3 introduced a linked filing architecture — certain forms must be filed before others, and the portal uses data from parent forms to auto-populate dependent ones.

    The most important sequence to know: file AOC-4 (annual financial statements) before MGT-7 (annual return). If you reverse this, the portal will reject MGT-7 because it cannot pull the financial data — paid-up capital, turnover — that AOC-4 is supposed to supply. This is a system enforcement, not a suggestion.

    Under V3, CSR-2 (Corporate Social Responsibility report) is no longer an independent filing from FY 2024–25 onwards. It must be filed as a linked form attached to AOC-4. Similarly, AOC-1 (statement on subsidiaries), AOC-2 (related party contracts), and the Extract of Board’s Report are now linked web forms that you attach at the time of AOC-4 submission. Six forms that never existed in V2 appear in V3 as entirely new linked submissions, including standalone and consolidated Auditor’s Report extracts.

    One more change that catches people off guard: MGT-8 is no longer a separate attachment. For listed companies and companies above the Section 92(2) threshold (paid-up share capital of ₹10 crore or more, or turnover of ₹50 crore or more), MGT-8 is now embedded directly inside MGT-7 with an optional qualifying remarks field.

    The filing process itself works like this. You enter your CIN. Master data auto-fills. You complete the online form or download the Excel offline utility for complex forms like AOC-4. You attach linked forms and supporting documents. You validate. You apply DSC. You pay — one consolidated payment covers the entire linked bundle.

    What’s Still Breaking: Known Issues on MCA V3

    Let’s be direct here. MCA V3 has improved significantly since its rocky 2024 launch, but the portal still has real problems — enough that ICAI, ICSI, and ICAI-CMA collectively wrote to MCA flagging persistent technical failures during the December 2025 annual filing season.

    The most reported issues professionals and founders encountered:

    DSC authentication failures. This is the single biggest problem on MCA V3 portal filing. The portal often fails to display the green tick mark for a registered DSC, even when the certificate is valid. The emSigner plugin needs to be updated to the latest version. The name on your DSC must match your MCA registration record exactly — even one character difference triggers rejection. Directors who updated their name or spelling anywhere outside MCA can run into this. Use Chrome or Edge; other browsers have compatibility issues with emSigner.

    Portal slowdowns during peak hours. The portal becomes slow, unresponsive, or inaccessible during the 3 PM to 8 PM window, especially in October and November when annual filing volumes spike. MCA asked its service provider LTI Mindtree to review server capacity, and some fixes were deployed. The practical answer: file early in the morning or late at night. Never file on the last day.

    Attachments disappearing after upload. Several users reported that attachments — Board’s Report, Auditor’s Report — uploaded successfully but then vanished from the form. Use the “Save Draft” button frequently. Preview all attachments before final DSC signing.
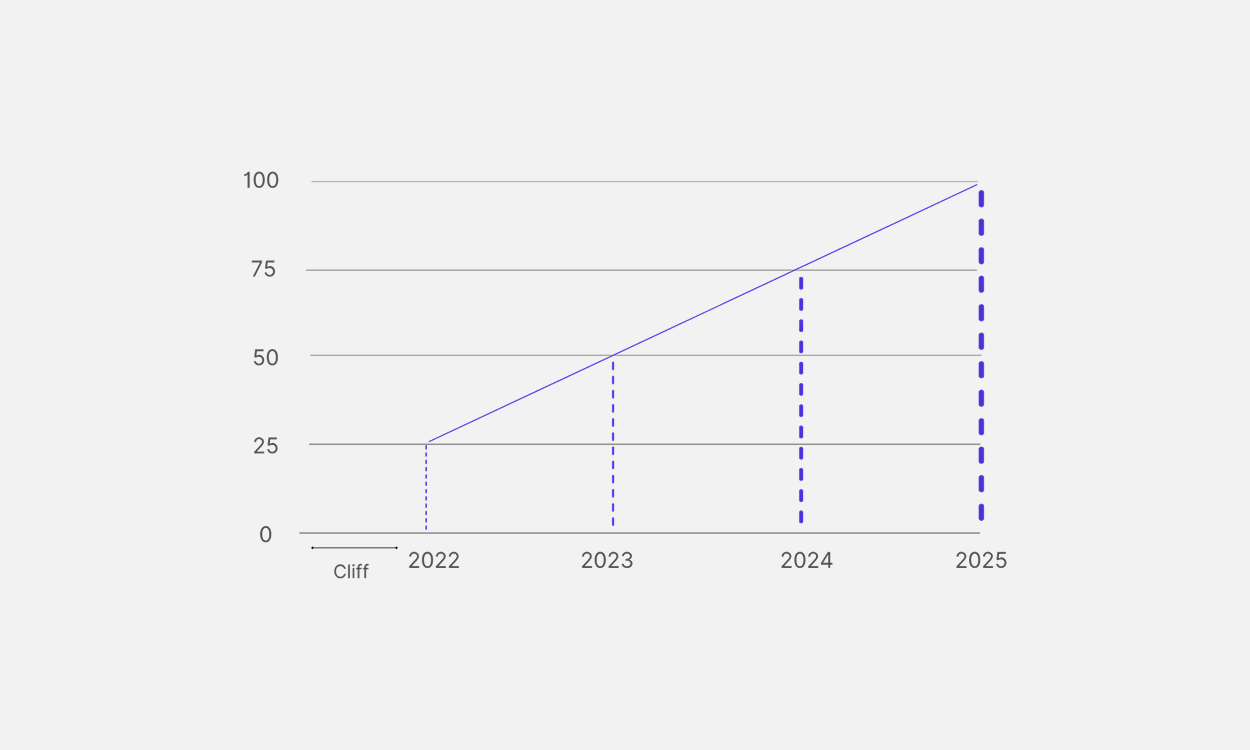
    Dropdown fields not loading. Particularly in AOC-4 and MGT-7A, dropdown options sometimes fail to populate. Refreshing the page loses unsaved data. Workaround: use the offline Excel utility for complex forms, and upload the filled file rather than relying on the live web form.
    The “Save” button not working. This forces users to refill the entire form. Again, the offline utility mode is the safer route for lengthy forms.
    Common MCA V3 Filing Errors — And Exact Fixes :

    What most founders miss is that many V3 rejections are preventable. Here are the errors that show up most often, and what to do about them.

    Error 1: Figures entered in lakhs or crores. V3 requires all financial figures in absolute rupees — no rounding off in thousands, lakhs, crores, or millions. If your paid-up capital is ₹10,00,000, enter 1000000, not 10 or 10.00. This applies to AOC-4, MGT-7, and every linked form.

    Error 2: Wrong filing sequence. As explained above — file AOC-4 before MGT-7. The system will catch this, but you’ll lose time and may face late penalties. The sequence for a standard annual filing: ADT-1 → AOC-4 (with CSR-2, AOC-2, Board’s Report linked) → MGT-7/MGT-7A.

    Error 3: DIN KYC not updated. Any director with a lapsed DIR-3 KYC causes the form to bounce. Check all directors’ KYC status before initiating any filing. This is a common root cause that delays the entire submission chain.
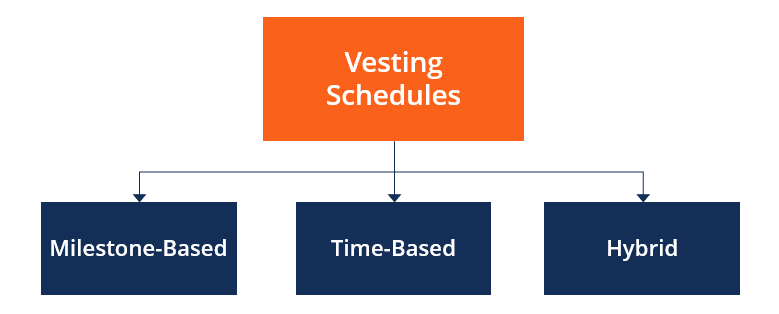
    Error 4: DSC name mismatch. The name on the DSC must match the MCA portal record character by character. One space, one spelling variation, one initial missing — the portal rejects it. Update DSC records or MCA records so both are identical.

    Error 5: Missing POSH and maternity disclosures in AOC-4. From FY 2024–25, AOC-4 mandates disclosures under the Sexual Harassment of Women at Workplace (Prevention, Prohibition and Redressal) Act, 2013 (POSH Act), as well as Maternity Benefits Act compliance and employee count including transgender employees. Missing these fields generates a validation error. Prepare these disclosures before opening the form.

    Error 6: Using the wrong Excel template. MCA V3 uses its own pre-defined Excel utility for shareholder and debenture holder uploads in MGT-7. External or modified sheets are rejected. Always download the template fresh from the MCA portal before filling it.

    Penalties for Getting It Wrong:

    The Companies Act 2013 doesn’t offer much grace for late or rejected filings. Know the numbers.

    For AOC-4 (financial statements): a penalty of ₹10,000 plus ₹100 per day of continuing default, up to ₹2,00,000 for the company. Officers in default face ₹10,000 which may extend to ₹50,000. This penalty has no cap on the per-day portion under Section 137.

    For MGT-7 (annual return): same structure — ₹10,000 plus ₹100 per day, up to ₹2,00,000 for the company and ₹50,000 for officers.

    Beyond money, non-compliance for three consecutive years disqualifies directors under Section 164(2) of the Companies Act 2013, blocking them from sitting on any company’s board. A filing error today can create a governance problem for years.

    For companies that missed filings during the V2-to-V3 transition window (June 18–July 31, 2025), MCA issued a waiver on additional fees until August 15, 2025. That window is closed. Late filers now face the full penalty structure.

    Your Pre-Filing Checklist for MCA V3

    Before you open a single form on the portal, run through this list.

    Check all directors’ DSC validity and ensure emSigner is updated to the latest version. Verify DIR-3 KYC is completed for every director for the current financial year. Confirm company master data on MCA matches your internal records — registered office address, paid-up capital, director details. Prepare all financial figures in absolute rupees, not in rounded-off form. Have the Board’s Report, Auditor’s Report, POSH disclosure, CSR data, and registered office photograph ready before starting. Download the latest Excel utility from the MCA portal if filing AOC-4 offline. File in sequence: ADT-1, then AOC-4 with linked forms, then MGT-7. File before peak hours — morning or after midnight. Do not attempt any annual filing in the last 48 hours before a deadline.

    If you find ROC compliance management is consistently eating into founder time, Lawizer’s startup legal services team handles MCA filings, ROC compliance calendars, and DSC coordination so your team doesn’t have to manage this every filing season.

    Company Incorporation Under MCA Portal: Updated Process 2026

    Frequently Asked Questions

    Q: Is the MCA V2 portal still accessible for filings?

    A: No. The V2 portal was permanently shut down on June 18, 2025. All statutory filings — including AOC-4, MGT-7, MGT-7A, and all 38 Lot 3 forms — must now be filed exclusively on the MCA21 V3 portal at mca.gov.in. Any SRN started on V2 that was not completed before shutdown must be refiled from scratch on V3.

    Q: Why is my MGT-7 getting rejected when I file it first?

    A: MCA V3 requires AOC-4 to be filed before MGT-7. The system pulls paid-up capital, turnover, and other financial data from a filed AOC-4 to auto-populate MGT-7. If you file MGT-7 first, the system cannot source that data and rejects the submission. Always file AOC-4 before MGT-7 in every annual compliance cycle.

    Q: My DSC is valid but the portal keeps showing an error. What should I do?

    A: First, check that the name on your DSC matches your MCA registration exactly — even a single character mismatch will cause authentication failure. Second, update your emSigner plugin to the latest version and use Chrome or Edge as your browser. Third, clear your browser cache and try again. If the issue persists, raise a support ticket from your MCA V3 dashboard under the grievance redressal system.

    Q: Can I enter financial figures in lakhs in AOC-4 on MCA V3?

    A: No. MCA V3 requires all figures in absolute rupees. Entering values in rounded-off thousands, lakhs, crores, or millions will trigger a validation error and prevent submission. If your paid-up capital is ₹50 lakh, you must enter 5000000 in the form field.

    Q: What are the new disclosure requirements added to AOC-4 from FY 2024–25?

    A: From FY 2024–25, AOC-4 mandates three new categories of disclosure: compliance under the POSH Act (Sexual Harassment of Women at Workplace Act 2013), compliance with the Maternity Benefits Act, and the total count of employees including transgender employees at the end of the financial year. Missing any of these will generate a form validation error. Prepare these disclosures before starting your AOC-4 session on the portal.

    Q: What happens if I miss the AOC-4 or MGT-7 deadline?

    A: Late filing attracts a penalty of ₹10,000 plus ₹100 per day of continuing default under the Companies Act 2013, with the company liable for up to ₹2,00,000 and officers facing up to ₹50,000. Directors who default for three consecutive years are disqualified under Section 164(2) from holding any board position. There is no grace period currently — the transition waiver that ran until August 15, 2025 has expired.

    Ready to get your ROC filings done without the back-and-forth?

    Lawizer’s experts handle everything — AOC-4, MGT-7, DSC coordination, and ROC compliance calendars — fully online, with zero CA office visits. Starting at just ₹999.

    Get your MCA filings done on Lawizer → https://lawizer.com/startup-businesslegal


  • Online Legal Services in India: What to Check Before You Pay Anyone?

    Online Legal Services in India: What to Check Before You Pay Anyone?

    Online Legal Services in India: What to Check Before You Pay

    Over 1.7 lakh consumer complaints were officially filed in India in a single year — and a growing chunk of them involve online service providers, including legal platforms. Founders in Bengaluru, Delhi, and Mumbai have paid anywhere from ₹1,500 to ₹30,000 to online legal services, only to receive silence, stalled filings, or demands for more money mid-process. Online legal services in India have genuinely improved access to compliance help — but not every platform operating in this space deserves your trust or your money.

    Before you pay anyone to handle your company registration, GST filing, trademark, or startup compliance, run through this checklist. It takes ten minutes and could save you months of grief.

    📌 TL;DR: Online legal services in India range from highly professional legaltech platforms to outright scams. Before paying any provider for company incorporation, GST registration, trademark filing, or compliance work, verify their Bar Council affiliation or MCA empanelment, check for a written service agreement, confirm government fee breakdowns, and look for real reviews beyond their own website. Lawizer operates transparently with fixed pricing and qualified professionals — so you know exactly what you’re paying for.

    What You’ll Learn

    — The 7 things to verify before paying any online legal service in India
    — Red flags that signal a platform is more sales machine than legal service
    — What a legitimate service agreement for legal work should include
    — How to separate government fees from professional fees — so you’re never overcharged
    — Your legal rights under the Consumer Protection Act, 2019 if something goes wrong


    Legal Services for Startups in Kolkata | Increeda Law Firm

    Why This Matters More Than You Think

    India’s legaltech sector has grown rapidly. You can now get a private limited company incorporated, file a trademark application with the CGPDTM (Controller General of Patents, Designs and Trade Marks), or register for GST — all without visiting a government office. That’s genuinely useful for early-stage founders who don’t have time to navigate multiple portals. But this convenience has also attracted platforms that prey on founders who don’t know what the process actually costs or involves.

    Here’s the thing: the government fees for most startup compliance tasks are fixed and publicly available on MCA.gov.in. Company incorporation via SPICe+ (Simplified Proforma for Incorporating Company Electronically Plus — MCA’s online incorporation form) can be done for a few thousand rupees in government fees alone. The moment a platform quotes you ₹25,000 for a service and won’t break down what’s government fee versus professional fee, that’s your first red flag. Real legal platforms have nothing to hide about their fee structure.


    Check 1: Are They Actually Qualified to Do This Work?

    Legal work in India is regulated. Company incorporation requires a practising Company Secretary (CS) or Chartered Accountant (CA) with MCA21 credentials. Trademark filing involves the Intellectual Property India portal and should ideally be handled by a registered trademark attorney. Contract drafting and legal notices technically require an advocate enrolled with the Bar Council of India under the Advocates Act, 1961. So the first thing to check: who is actually doing your work?

    A legitimate online legal platform will tell you — either on their website or when you ask directly — whether the work is being handled by empanelled CAs, CS professionals, or advocates. If you get a vague answer like “our team of experts,” push harder. Ask for the name or registration number of the professional handling your file. A trustworthy platform will not hesitate to answer.


    Check 2: Is There a Written Service Agreement Before You Pay?

    Under the Indian Contract Act, 1872, a valid service contract requires offer, acceptance, and consideration — but more practically, you need the terms in writing before money changes hands. What most founders miss: paying an online platform without a written agreement leaves you almost no recourse if they delay, do incomplete work, or quietly close shop. A written service agreement should specify the exact scope of work, the timeline, what happens if the government rejects an application, and the refund policy.

    If a platform’s “agreement” is buried in three-point font at the bottom of a checkout page, that’s deliberate. Look for platforms that send you a clear scope document before payment. Lawizer clearly states what’s included in each service package — so there’s no dispute later about what was promised.


    Check 3: Can They Show You the Government Fee Separately?

    Every legal filing in India involves two types of cost: the government fee (paid to MCA21, GSTN, CGPDTM, or the relevant authority) and the professional or platform fee (paid to the service provider). These are non-negotiable, public figures set by law. The government stamp duty and MCA fee for company incorporation depends on your authorised share capital and state — and is publicly listed on the MCA portal. Similarly, the official fee for a trademark application in one class is ₹4,500 for an individual or startup.

    A quick example: if a platform quotes you ₹15,000 for trademark registration in one class but won’t tell you that ₹4,500 of that is the official government fee, they’re being deliberately opaque. The professional fee charged on top of government fees is legitimate — but you have every right to know the split. Ask. If they won’t tell you, walk away.


    Check 4: Look for Reviews — But Not on Their Own Website

    Almost every legal platform in India has five-star testimonials on their homepage. Ignore these entirely. What you want are reviews on neutral platforms: Google Maps (search the company name), Trustpilot, Reddit’s r/india or r/LegalAdviceIndia communities, and Quora threads where real users discuss their experience. A pattern of complaints about non-delivery, upselling after payment, or refund refusals is a serious warning sign — and this information is usually publicly available if you spend five minutes searching.

    Let’s break this down with a real pattern founders encounter: a platform calls you urgently, creates a 30-minute discount deadline, takes payment, then immediately calls back asking for more money for “mandatory” add-on services like bookkeeping or compliance retainers. This is a documented upsell tactic. The short answer: any service that pressures you to pay within 30 minutes is not a professional legal platform.


    Check 5: Verify the Refund and Escalation Policy

    Under the Consumer Protection Act, 2019 — India’s primary law protecting buyers from deficient services — you have the right to seek a refund and compensation if an online platform fails to deliver what was promised. But enforcing this right is far easier when you have a clear refund policy in writing before you pay. Ask the platform: what happens if MCA rejects my application? What if the trademark objection isn’t handled? What’s the refund timeline?

    Platforms that are confident in their work will answer these questions clearly. If the refund policy says “no refunds once work begins” but there’s no clarity on what “work begins” means or how you’ll be notified — that’s a trap. You can escalate to the National Consumer Helpline (1800-11-4000) or file on the e-Daakhil portal (edaakhil.nic.in) if a platform refuses a legitimate refund. But it’s always better to choose a platform where this situation doesn’t arise. Working with Lawizer’s startup legal services means you’re covered by transparent, pre-defined service commitments from the start.


    Check 6: Does the Platform Have a Real Address and Contact Number?

    This sounds obvious, but many founders skip it. A legitimate legaltech company operating in India should have a verifiable registered office address (cross-checkable via MCA21 company search), a working phone number, and an email domain that matches their website. A platform that only communicates via WhatsApp or a personal Gmail address — especially for services involving your company’s legal documents — is not a professional operation.

    What most founders miss: some platforms use celebrity brand ambassadors and heavy advertising to create an impression of legitimacy. That’s not the same thing. An ad campaign doesn’t mean the company is solvent, staffed by qualified professionals, or capable of delivering what it promises. Check their company registration on MCA21, and verify that the entity you’re paying is the one actually responsible for the work.


    Check 7: Is the Scope of Work Specific — Or Dangerously Vague?

    The final check is about specificity. “We’ll handle your company registration” means nothing without defining what’s included. Does it cover the DIN (Director Identification Number) application? The DSC (Digital Signature Certificate)?

    MOA (Memorandum of Association) and AOA (Articles of Association) drafting? The SPICe+ filing? PAN and TAN applications? Bank account setup guidance? Each of these is a distinct step — and if any one of them gets stuck, your incorporation stalls.

    A well-structured platform will give you a step-by-step list of exactly what’s covered, the expected timeline for each step, and the documents required from your end. If you’re also looking to protect your brand alongside your incorporation, it’s worth handling trademark registration in India early — before someone else files your brand name first.

    The scope of your trademark service should be equally clear: how many classes are covered, what happens if there’s an objection, and whether the objection reply is included or billed separately.

    Person Holding a Document while Using Laptop · Free Stock Photo

    Frequently Asked Questions

    Q: How do I verify if an online legal service in India is legitimate?

    A: Start by checking whether the platform’s company is registered on the MCA21 portal — search their name under company search at mca.gov.in. Then look for professional credentials: who are the CAs, CS professionals, or advocates on their team? Check independent review platforms like Google Maps, Trustpilot, and Reddit for real user feedback. Finally, look for a working phone number, a physical office address, and a clear written service agreement before you pay anything.

    Q: What’s the difference between government fees and professional fees in legal services?

    A: Government fees are fixed amounts paid to official authorities — like MCA21 for company incorporation or CGPDTM for trademark registration — and are set by law. Professional or platform fees are what you pay the service provider for handling the paperwork and filing. Any reputable online legal platform should be willing to show you both amounts separately. If a platform bundles everything into one opaque price and refuses to break it down, treat that as a red flag.

    Q: Can I get a refund from an online legal service if they don’t deliver?

    A: Yes — under the Consumer Protection Act, 2019, you have the right to seek a refund and compensation for deficient services. If the platform refuses, you can file a complaint on the e-Daakhil portal (edaakhil.nic.in) or contact the National Consumer Helpline at 1800-11-4000. The stronger your position, the more documentation you have: keep all payment receipts, WhatsApp messages, emails, and any written promises made by the platform before you paid.

    Q: Is it safe to do trademark registration through an online legal platform in India?

    A: It can be — provided the platform has a qualified trademark attorney handling the filing and provides a clear breakdown of the ₹4,500 official government fee (for individuals and startups) versus their professional fee. Confirm the platform will handle any objection raised by the trademark examiner, and check whether their service agreement covers objection replies or charges extra for them. Transparent platforms will answer all of this upfront without hesitation.

    Q: What should a proper service agreement from an online legal service include?

    A: A proper service agreement should spell out the exact scope of work, the expected timeline, the professional and government fee amounts separately, what happens if there is a government rejection or query, the refund policy with specific conditions, and the escalation process if you’re unsatisfied. It should be provided in writing before you pay — not after. If any of these elements are missing, request them before proceeding.

    Q: Why do so many online legal platforms in India push for payment within 30 minutes?

    A: Time-pressure tactics are a well-documented sales method used by platforms that rely on impulse purchases rather than client confidence. A legitimate legal service provider does not need you to pay in 30 minutes — government filing processes are not that time-sensitive in most standard cases. If a platform creates false urgency through a countdown timer or expiring discount, that’s a signal they’re prioritising revenue over your outcome. Professional platforms let you ask questions, review agreements, and pay when you’re ready.


    Ready to work with a legal platform you can actually trust? Lawizer’s qualified professionals handle everything — company incorporation, GST registration, trademark filing, and MSME/Udyam registration — fully online, with fixed transparent pricing. No hidden fees. No upselling after payment. Starting at just ₹999.

    Start Your Legal Service With Lawizer → https://lawizer.com/startup-businesslegal


  • Can AI Replace a CA or CS for Indian Startups? The Honest Answer :

    Can AI Replace a CA or CS for Indian Startups? The Honest Answer :

    Over 95,000 companies were incorporated in India in FY 2024–25 alone. And almost every founder, at some point, has asked the same question: “Do I really need a CA and CS, or can an AI tool just handle this?” It’s a fair question — especially when you’re bootstrapped and watching every rupee.

    The honest answer? AI can do more than you think. But it also cannot do several things that could land you in serious legal trouble if skipped. Let’s break this down properly.

    📌 TL;DR: AI tools can meaningfully automate routine legal drafting, compliance reminders, contract review, and GST reconciliation for Indian startups — but they cannot replace a CA for statutory audits or a CS for ROC filings, both of which are legally mandated under the Companies Act 2013. The smartest move for Indian founders is using AI-powered platforms like Lawizer alongside qualified professionals, not instead of them.

    What You’ll Learn:

    • Exactly which compliance tasks AI tools can genuinely handle for Indian startups
    • Where Indian law requires a licensed CA or CS — and the penalties for skipping them
    • The five things AI still consistently gets wrong in an Indian regulatory context
    • How to build a hybrid CA + AI workflow that cuts costs without cutting corners

    Top Indian Startup Founders: Real Success Stories to Inspire You

    What AI Tools Can Actually Do for Indian Startup Compliance

    Here’s the thing — AI-powered legaltech has come a long way. The India AI LegalTech market is valued at approximately USD 1.8 billion in 2025, and the tools available to founders today are genuinely impressive.

    AI platforms can draft NDAs, founder agreements, employment contracts, and IP assignment clauses in minutes. They can scan contracts for clause deviations, flag unusual terms, and send deadline alerts for upcoming GST return dates, board meeting requirements, and DIN KYC deadlines.

    For a seed-stage startup in Bengaluru or Kolkata that can’t yet afford a full-time legal team, this is genuinely useful. Some Indian legaltech platforms report that AI tools reduce research time for routine compliance questions by as much as 70%. Contract automation, GST reconciliation, and GSTR-3B draft generation are all areas where AI delivers real, measurable value.

    What most founders miss, though, is the distinction between assisted compliance and statutory compliance. The former is where AI thrives. The latter is where Indian law draws a hard line — and where no AI tool, however sophisticated, can legally stand in for a human professional.


    Where Indian Law Mandates a CA — No Exceptions

    Let’s be direct about this. Section 139 of the Companies Act 2013 mandates that every registered company in India appoint a statutory auditor — who must be a practising CA or CA firm. This isn’t optional, and it doesn’t matter whether you’re a bootstrapped SaaS startup with zero revenue or a Series A company. Your audited financial statements, filed via Form AOC-4 with the MCA21 portal, must be signed off by a licensed Chartered Accountant.

    The stakes for missing this are real. Late ROC filings attract a penalty of ₹100 per day per form with no upper cap for AOC-4 and MGT-7. A company that files nine months late could face penalties of ₹54,000 or more — per form.

    If directors fail to file annual returns for three consecutive years, they face disqualification under Section 164 of the Companies Act 2013, which bars them from any directorship anywhere for five years. That’s a founder nightmare scenario.

    Beyond audits, a CA is also required for GST audit (if applicable thresholds are met), income tax filings, transfer pricing reports, and any statutory certification that banks or investors require during due diligence. No AI platform generates a digitally signed CA certificate that the MCA or Income Tax Department will accept. Period.


    Why Legal Compliance is Important for Industries | ISO vs EHS Compliance India - Sheel Technologies

    Where Indian Law Mandates a CS — And What Founders Often Get Wrong

    A Company Secretary — a professional certified by the Institute of Company Secretaries of India (ICSI) — is legally required for companies with a paid-up capital of ₹5 crore or more under the Companies Act 2013. But even for startups below that threshold, the secretarial workload is significant. Filing Form MGT-7, the annual return containing director and shareholding details due within 60 days of the AGM, maintaining statutory registers, recording board meeting minutes, and filing event-based forms like DIR-12 for director changes or PAS-3 for share allotments — all of these carry strict deadlines with ₹100/day penalties for late submission.

    Here’s what most founders get wrong: they assume this is just paperwork and try to handle it themselves or with a generic AI tool. The problem is that an error in a PAS-3 filing (share allotment) or a missed ADT-1 (auditor appointment) can make the underlying corporate action legally questionable — not just expensive. Investor diligence teams look at MCA21 filing histories carefully. A messy secretarial record has killed fundraising rounds at the term sheet stage.

    A quick example: if your startup issues ESOPs, the allotment must be reported to the ROC within 30 days. Miss that window and the shares are technically unregistered. No AI tool currently generates, validates, and submits e-forms on MCA V3 with the required Digital Signature Certificates on behalf of your directors. That chain of human accountability is still legally essential.


    The Five Things AI Still Gets Wrong in India’s Regulatory Context

    AI legaltech tools are genuinely good. But they carry specific failure modes that Indian founders need to understand before putting too much trust in them.

    First, hallucinating Indian law. General AI models frequently confuse Indian legal provisions with UK or US equivalents. A chatbot may cite a provision that doesn’t exist in the Companies Act 2013 or quote an outdated CGPDTM (Controller General of Patents, Designs and Trade Marks) circular. Indian-trained models have significantly lower hallucination rates, but the risk doesn’t disappear.

    Second, missing state-level variations. GST composition scheme limits, stamp duty rates, and shop-and-establishment registration rules vary by state. An AI tool trained primarily on central law may give you advice that’s wrong for Maharashtra but right for Karnataka.

    Third, no DSC or digital signing authority. MCA V3 filings, GST registrations, and patent applications require a valid Digital Signature Certificate. AI cannot hold or use a DSC. A human professional must always be in the loop for any submission to a government portal.

    Fourth, the professional liability gap. If your CA gives wrong advice and you suffer a penalty, you have legal recourse against them. If an AI tool gives you wrong advice, the liability is yours. This matters enormously when investors or banks rely on compliance certificates.

    Fifth, interpretation of fact-specific tax positions. Whether a particular SaaS subscription attracts 18% GST or qualifies for a lower rate, or whether your co-founder’s salary qualifies as a deductible business expense — these involve judgment calls that require someone who knows your specific business model, not pattern-matching against generic data.


    The Smart Hybrid Model: AI + CA/CS Working Together

    The founders who are managing compliance costs most effectively aren’t choosing between AI and professionals — they’re using both deliberately. The model looks like this: AI handles the operational layer (drafting routine contracts, sending compliance deadline alerts, generating GSTR-3B drafts, flagging unusual clauses in vendor agreements), while your CA and CS handle the statutory layer (signing off on audits, filing ROC forms with valid DSCs, advising on non-routine tax positions, and maintaining the statutory registers that investors and banks will eventually scrutinise).

    Platforms like Lawizer’s startup legal services are built around exactly this hybrid model. Instead of paying a retainer to a CA firm for work that can be standardised and automated, you use a platform that combines AI-powered document generation with qualified professionals who handle the pieces that require statutory sign-off. This keeps your compliance costs predictable and your legal house in order — without over-spending in the early stages when every rupee counts.

    What most founders miss: the hybrid model also makes your CA or CS more effective. When AI tools handle routine drafting and deadline tracking, your professional can spend their time on higher-value advisory work — structuring your ESOP pool, advising on a GST audit response, or preparing your company for Series A due diligence. That’s where a good CA or CS truly earns their fees.


    What This Means for Your Startup Right Now

    If you’re pre-incorporation, AI-assisted platforms can get you through the SPICe+ (Simplified Proforma for Incorporating Company Electronically Plus — MCA’s online incorporation form) process, help you draft a founders’ agreement, and set up your initial MSME Udyam registration. You don’t need to sit across a desk from a CA to get started. But the moment your company is incorporated, the statutory clock starts ticking — and some of those obligations begin on day one.

    If you’re already incorporated, run a quick health check on three things: Is your statutory auditor formally appointed and ADT-1 filed? Is your INC-20A (commencement of business declaration) filed within 180 days of incorporation? Are your DIR-3 KYC filings for all directors current? These are the three most commonly missed post-incorporation requirements that AI tools alone cannot resolve. You can protect your business proactively through Lawizer’s complete startup compliance services — managed entirely online with qualified CA and CS professionals.

    And if your brand is still unprotected, don’t overlook trademark registration. AI can help you search for conflicts, but the filing strategy and responding to CGPDTM objections requires professional judgment. Lawizer’s trademark registration service handles this end to end — so your brand is protected before someone else files first.


    Frequently Asked Questions

    Q: Can I use ChatGPT or an AI tool to file my GST returns in India?

    A: AI tools can help you draft and review GSTR-3B and GSTR-1 data before filing, but they cannot file on your behalf on the GSTN (Goods and Services Tax Network) portal. GST filings require valid login credentials and OTP authentication by an authorised signatory. Most founders use AI tools for pre-filing reconciliation and a CA or GST practitioner for the actual submission and any advisory on input tax credit claims.

    Q: Is a statutory audit mandatory for my startup even if we have zero revenue?

    A: Yes, completely. Under Section 139 of the Companies Act 2013, every company registered in India must appoint a statutory auditor regardless of turnover, profit, or activity level. Even a dormant startup with zero revenue must get its financial statements audited by a practising CA and file Form AOC-4 with the MCA21 portal annually. There are no exemptions for early-stage startups on this requirement.

    Q: What happens if I skip ROC filing and rely only on an AI compliance tool?

    A: AI compliance tools can remind you of deadlines and help you prepare documents, but they cannot submit filings to the Registrar of Companies on your behalf. If ROC filings like MGT-7 or AOC-4 are missed, your company faces penalties of ₹100 per day per form with no upper cap. If annual returns go unfiled for three consecutive years, directors face disqualification under Section 164 of the Companies Act 2013, barring them from any directorship for five years.

    Q: Which AI tools are actually useful for Indian startup compliance right now?

    A: Several Indian legaltech platforms are worth exploring. SpotDraft is well-regarded for contract lifecycle management. NYAI is a compliance-native platform trained on Indian legal documents including MCA, tribunal, and High Court data. Simpliance handles labour law compliance tracking. For incorporation, GST, trademark, and ongoing ROC compliance, Lawizer provides an AI-assisted platform backed by qualified CA and CS professionals — so you get the speed of automation with the statutory sign-off Indian law requires.

    Q: Can AI help with trademark registration for my Indian startup?

    A: AI tools can run trademark availability searches and flag conflicting marks, which saves real time. However, filing with the CGPDTM and — critically — responding to any examination report or opposition requires professional judgment about trademark class selection, distinctiveness arguments, and evidentiary strategy. Platforms like Lawizer combine AI-powered search with professional representation so you’re not navigating the CGPDTM process alone.

    Q: How much can a startup realistically save by using AI tools alongside a CA instead of a full retainer?

    A: Early-stage startups that previously budgeted ₹1–2 lakh annually for basic compliance retainers are finding that AI-assisted platforms can deliver comparable coverage at a fraction of the cost, while still involving a licensed professional for the statutory filings that Indian law mandates. The savings compound as you scale, because AI handles the growing volume of routine tasks while your CA’s time stays focused on the judgment-intensive work that genuinely requires it.


    Ready to get your startup legally sorted — without overpaying? Lawizer’s experts handle everything — ROC filings, statutory audits, GST registration, trademark protection — fully online, starting at just ₹999. No CA office visits needed.

    Start your compliance review today → https://lawizer.com/startup-businesslegal


  • Freelance Contracts in India: What Founders Must Include to Avoid Disputes

    Freelance Contracts in India: What Founders Must Include to Avoid Disputes

    One unpaid invoice. One “that wasn’t in scope” argument. One freelancer who walks off mid-project with your source files. A weak freelance contract in India turns into exactly that — and founders usually find out the hard way, after the money’s already gone.

    Here’s the good news: almost every one of these fights is preventable with five clauses, written correctly, before work starts.

    📌 TL;DR: A legally sound freelance contract in India must cover scope of work, payment terms with TDS/GST clarity, IP ownership, confidentiality, and dispute resolution. Under the Indian Contract Act, 1872, even an email exchange can form a binding contract — but without these five clauses spelled out in writing, founders are left arguing over interpretation instead of terms. Lawizer helps founders draft and review these agreements before they’re signed, not after a dispute starts.

    What You’ll Learn

    • Why a written contract matters even for a two-week project
    • How to write a scope clause that actually stops scope creep
    • The TDS and GST details most founders get wrong
    • How to lock down IP ownership and confidentiality
    • What a fair termination and dispute clause looks like

    Why a Handshake Deal Isn’t Enough

    Here’s the thing: a freelance contract in India doesn’t need a fancy format to be enforceable. Under the Indian Contract Act, 1872, any agreement with free consent, lawful consideration, and a lawful object is binding — even an exchange of emails can count as a concluded contract.

    That sounds reassuring, until you realise it also means a vague WhatsApp “sounds good, let’s start” can be legally binding too, with none of the protection a proper agreement gives you.

    What most founders miss: enforceable and easy-to-enforce are two different things. An email thread rarely has a payment schedule, an IP clause, or a jurisdiction for disputes.

    When the freelancer disappears mid-project or a client refuses to pay the final milestone, that’s exactly what you need in writing — not reconstructed from old chat messages.

    Freelancing in India isn’t a fringe arrangement anymore. Independent, project-based work has grown fast enough that most founders will hire a freelancer before they hire their first full-time employee — which makes a reusable, solid contract template one of the highest-leverage documents in a startup’s early life. Getting your business legal documentation right from the first hire avoids rework later.

    Scope of Work: Killing Scope Creep Before It Starts

    The single most common freelance dispute isn’t about payment — it’s about what “the project” actually included. A scope clause should specify the deliverables, define the number of included revisions, and clearly list any exclusions. “Website redesign” is not a scope. “5 pages, 2 rounds of revisions, content upload not included” is.

    The short answer is simple: if it isn’t written down, the freelancer and the client will likely remember it differently.

    Add a change-order line — any request outside the listed scope needs written approval and a separate quote before work begins on it. This single sentence prevents most “can you also just add…” arguments from turning into unpaid extra work or a refused invoice.

    • List deliverables individually, not as a bundle
    • Name the exact number of revisions included
    • State explicitly what’s out of scope
    • Require written approval for any scope addition

    Payment Terms, TDS & GST: Where Money Fights Start

    Payment clauses fail founders in two ways: they’re either too vague to enforce, or they skip the tax details entirely. Let’s break this down. A proper payment clause needs the total fee, the schedule (say, 40% upfront and 60% on delivery), accepted payment methods, and a late-payment penalty — commonly 1.5–2% monthly interest on overdue invoices.

    Then there’s tax. If you’re paying a resident freelancer for professional services, you must typically deduct TDS (Tax Deducted at Source — the tax a business deducts before paying certain vendors) under Section 194J once payments exceed the threshold notified for the financial year. Check the current limit on the Income Tax Department portal before finalising the clause, as the government revises thresholds periodically.

    Separately, GST rules apply if the freelancer crosses the GST registration threshold. Your contract should state who is GST-registered. It should also explain how invoices will reflect GST. Confirm the current registration limits on the  GST portal.

    For example, if your contract doesn’t mention TDS, the freelancer may invoice you for the full amount and you may pay it in full. Months later, you could discover that the law required you to deduct tax before making the payment, creating a reconciliation headache for both sides.

    One line fixes this. Add the following clause: “Payments will be made after deducting applicable TDS under the Income Tax Act, 1961. The freelancer will provide a valid PAN for TDS purposes.”

    IP Ownership & Confidentiality: Who Owns the Work

    Most freelance disputes over intellectual property happen because founders assume ownership transfers automatically once they pay. It doesn’t. Your contract needs an explicit IP assignment clause stating that all rights in the work product transfer to the client upon full and final payment — not upon delivery, and not upon signing.

    Add a confidentiality clause covering any business data, product plans, or customer information the freelancer accesses during the project, and how long that obligation survives after the contract ends — typically one to three years.

    For technical freelancers, also include an IP indemnity clause. It ensures their work doesn’t infringe another person’s copyright or trademark, protecting you from legal liability if it does. If your work touches a registered mark or brand name, pairing this with a proper trademark registration closes the loop on ownership.

    Termination & Dispute Resolution: Your Exit Ramp

    What most founders miss until it’s too late: a contract with no exit clause traps both sides. Include a termination-for-convenience clause with a notice period (commonly 15–30 days), and specify what happens to work-in-progress and partial payments if either side ends the engagement early.

    For dispute resolution, name a mechanism upfront — negotiation first, then mediation or arbitration — and fix the jurisdiction (which city’s courts or arbitration seat applies). Skipping this doesn’t avoid disputes; it just means you’ll be arguing about where to argue, on top of the original disagreement.

    If your business is registered under a specific legal structure, make sure the entity name in the contract matches your incorporation documents exactly, since a mismatch can complicate enforcement later.

    Frequently Asked Questions

    Q: Is a freelance contract legally valid in India without a lawyer drafting it?

    A: Yes. Under the Indian Contract Act, 1872, an agreement is enforceable once it has free consent, lawful consideration, and a lawful object — a lawyer isn’t legally required to draft it. That said, for high-value or complex projects, a legal review helps catch gaps before they become disputes.

    Q: Can I sue a freelancer or client based only on WhatsApp or email messages?

    A: Possibly — Indian courts have held that a concluded contract can arise from correspondence alone, even without a signed document. However, email-only agreements usually lack payment terms, IP clauses, and a dispute mechanism, which makes proving your case slower and harder. A signed written agreement is the safer default.

    Q: Do I need to deduct TDS when paying an Indian freelancer?

    A: In most cases, yes — TDS applies to payments for professional services under Section 194J once you cross the threshold notified for the financial year. Confirm the current limit on the Income Tax Department portal before finalising your payment clause, since thresholds change periodically.

    Q: When does IP ownership transfer from the freelancer to my company?

    A: Only when your contract says so explicitly — ownership does not transfer automatically just because you paid. Most Indian freelance contracts state that all rights transfer to the client upon full and final payment, so this line needs to be written into the agreement, not assumed.

    Ready to get your freelance contracts dispute-proof?
    Lawizer’s experts handle contract drafting, GST registration, and MSME registration — fully online, starting at just ₹999. No CA visit needed.

    Get Your Freelance Contract Reviewed →

  • India’s Creator Economy and the Law: What YouTubers and Influencers Must Register

    India’s Creator Economy and the Law: What YouTubers and Influencers Must Register

    India added roughly 4 million creators between 2020 and 2024. That marks a 322% increase. Many learned about their legal obligations the hard way. Some received GST notices. Others found TDS mismatches in Form 26AS. Many also saw brand deals stall because they had no invoice to raise.

    Creator economy law in India isn’t optional paperwork anymore. It’s the difference between a channel that scales and one that gets an income tax notice mid-growth.

    Here’s the thing: nobody hands new creators a checklist. Brands, MCNs, and even CAs assume you already know what to register. You don’t have to guess.

    📌 TL;DR: Under creator economy law in India, YouTubers and influencers must register for GST once turnover crosses ₹20 lakh (₹10 lakh in special category states), file ITR-3 or ITR-4 using profession code 16021, and follow ASCI disclosure rules on every paid post. Brands also deduct TDS under Sections 194R, 194J, or 194C depending on the deal structure. Lawizer handles GST, MSME (Udyam), and trademark registration for creators end-to-end, online.

    What You’ll Learn

    • When GST registration becomes mandatory for creators, and how the 18% rate applies
    • How TDS under Sections 194R, 194J, and 194C hits your brand deal payouts
    • Why trademarking your channel name protects your personal brand
    • When Udyam (MSME) registration and even a Private Limited company make sense

    GST Registration: The First Real Compliance Trigger

    The moment your annual turnover from brand deals, ad revenue, affiliate income, and even bartered products crosses ₹20 lakh (₹10 lakh in special category states like Assam or Himachal Pradesh), GST registration under the GSTN portal stops being optional. Content creation is classified as a supply of service under the CGST Act, and it attracts 18% GST — same rate as most professional services.

    Most founders overlook one important rule. GST turnover includes non-cash income. A ₹2 lakh gadget hamper counts at its market value. It counts even if no money changes hands. That value also contributes to your GST registration threshold.

    That value contributes to your GST registration threshold. After registering, you must issue GST-compliant tax invoices for every brand collaboration. Many brands now require these invoices before releasing payment.

    • Brand deals with foreign companies can qualify as “export of services” — zero-rated GST, if you file a Letter of Undertaking (LUT)
    • Once registered, you can claim Input Tax Credit (ITC) on equipment, software, and studio expenses.
    • Missing GST invoices on brand collaborations risks penalties during scrutiny

    Founders juggling multiple income streams — YouTube AdSense, Instagram deals, coaching — often set up their business registration at the same time as GST, since lenders and brands both ask for it.

    TDS: What Gets Deducted Before You See the Money

    The short answer: it depends on how the brand structures the deal. Section 194J applies 10% TDS on professional fees — the most common category for sponsored posts and endorsements. Section 194C applies a lower 1-2% TDS when you’re treated as a contractor executing a defined project.

    Section 194R is the one that catches creators off guard: if a brand gives you products, hotel stays, or gadgets worth more than ₹20,000 in a year, they must deduct 10% TDS on the fair market value — even though you never received cash.

    Profession Code 16021 in ITR Filing: How to Choose the Right ITR Form

    From FY 2024-25 (Assessment Year 2025-26) onward, the Income Tax Department introduced a dedicated profession code — 16021 — specifically for social media influencers and content creators. If you’re filing under this code with detailed books of accounts, ITR-3 is the correct form.

    If you’d rather declare a fixed percentage of income under presumptive taxation instead of maintaining detailed books, ITR-4 (Sugam) applies.

    What most founders miss here: mixing personal and business expenses is the fastest way to draw scrutiny. Only expenses directly tied to content creation — camera gear, editing software, internet bills, studio rent — qualify as deductions. A family vacation dressed up as a “travel content shoot” won’t survive an audit.

    • Foreign income (YouTube AdSense in USD, international brand deals) must be reported under Schedule FA
    • Late filing attracts a flat ₹5,000 penalty under Section 234F
    • Under-reported income can attract a 50-200% penalty under Section 270A

    Creators who also run e-commerce alongside content — merch, digital courses — often benefit from lining up their income tax return filing with proper business registration from the start, rather than retrofitting compliance after brands start asking for GSTINs and PANs.

    Trademark Your Channel Name Before Someone Else Does

    Here’s what catches creators off guard: your channel name, logo, or catchphrase isn’t automatically yours in law just because you built the audience.

    Anyone can file for trademark registration with the CGPDTM (Controller General of Patents, Designs and Trademarks) on an identical or similar name, and if they register first, you could be the one forced to rebrand — after years of building recognition.

    This matters more once merchandise, digital products, or a personal app enters the picture. A registered trademark also strengthens your position in brand negotiations and licensing deals, since it proves exclusive ownership over your name and likeness in commerce.

    Creators expanding into merch or courses typically pair trademark registration with their channel launch rather than waiting until a copycat account forces the issue.

    MSME (Udyam) Registration and When to Incorporate

    Once you’re running a studio, employing editors, or operating as a small media business rather than a solo creator, Udyam (MSME) registration opens up collateral-free loans, priority payment protections against brands, and government tender eligibility. It’s free, done entirely online through the Udyam portal, and takes minutes once your PAN and Aadhaar are ready.

    When creators should consider incorporating a company

    What most founders miss: at a certain income level, operating as an individual professional starts costing more in tax than incorporating a Private Limited company or LLP under the Companies Act, 2013. Incorporation also separates personal liability from business liability — useful once you’re signing large brand contracts, hiring a team, or bringing in investors for a media business.

    • Udyam registration: ideal for solo creators scaling into a small studio or team
    • Private Limited/LLP: better once annual income consistently crosses ₹50-75 lakh or you’re hiring full-time staff

    Founders scaling past solo-creator income levels often register through MSME Udyam registration before they need it, so brand contracts and bank credit lines aren’t held up later.

    ASCI Disclosure Rules: Compliance Requirements for Brands

    The Advertising Standards Council of India (ASCI) processed over 1,400 influencer violations through November 2025, with 94% involving disclosure failures — undisclosed paid posts hidden behind a dozen unrelated hashtags.

    ASCI’s April 2025 update tightened these rules across all categories. The Consumer Protection Act now enforces them with government penalties, not just industry warnings.

    Let’s break this down: if you receive cash, free products, travel, or even an affiliate commission for content, disclosure is mandatory — prominent, immediate, and impossible to miss, not buried in a caption.

    Finance and health creators face an even stricter Addendum 2: finfluencers must display SEBI registration or CA credentials, and health influencers must show their medical qualifications, or stick to personal experience with a clear disclaimer.

    Non-compliance carries serious risks. Brands may withhold payment or end contracts. They may also flag violations, making future partnerships harder to secure.

    Frequently Asked Questions

    Q: Do I need GST registration if I only make money from YouTube AdSense?

    A: Yes, once your total annual turnover — including AdSense, brand deals, and affiliate income combined — crosses ₹20 lakh (₹10 lakh in special category states). AdSense income counts toward this threshold the same as any other revenue stream.

    Q: What happens if a brand sends free products instead of paying cash?

    A: If the products are worth more than ₹20,000 in a financial year, the brand must deduct 10% TDS under Section 194R based on the fair market value. You’ll also need to declare this as taxable income, even though you didn’t receive cash.

    Q: Which ITR form should influencers file?

    A: Most creators file ITR-3 using profession code 16021, especially if they maintain detailed books of accounts. If you prefer the presumptive taxation scheme under Section 44AD instead of maintaining full books, ITR-4 (Sugam) applies.

    Q: Can someone else trademark my channel name if I haven’t registered it?

    A: Yes. Trademark rights in India generally go to whoever files first, not whoever built the audience first. Registering early with the CGPDTM protects your channel name, logo, and tagline from being claimed by someone else.

    Q: Do I need to disclose every sponsored post, even small gifting collaborations?

    A: Yes. Under ASCI guidelines, disclosure is required whenever you receive any benefit — cash, free products, travel, or affiliate commission — in exchange for content, regardless of follower count or the size of the deal.

    Ready to formalize your creator business?
    Lawizer’s experts handle everything — GST registration, MSME Udyam registration, and trademark filing for your channel — fully online, starting at just ₹999. No CA visit needed.

    Get Your Creator Compliance Sorted →

  • Solopreneur to Startup: When Exactly Should You Formally Incorporate?

    Solopreneur to Startup: When Exactly Should You Formally Incorporate?

    Most Indian freelancers cross ₹20 lakh in billings before they’ve even opened a current account for the business. That’s the exact point the law starts asking questions — and it’s usually the point founders start googling “when to incorporate company in India” at 1 a.m.

    Here’s the thing. Incorporating too early wastes money on compliance for a business that hasn’t proven itself. Incorporating too late costs you a client, a co-founder, or an investor. There’s a narrow window where it actually makes sense — and it’s rarely “day one.”

    📌 TL;DR: You don’t need to incorporate on day one — a sole proprietorship is legal, requires no registration, and works fine until you hit specific triggers: ₹20 lakh in annual turnover (GST becomes mandatory), an investor writing a cheque, a co-founder wanting a formal equity split, or an enterprise client demanding a company PAN. Below that point, incorporating a private limited company just adds ₹35,000–₹60,000 a year in compliance cost for a business that hasn’t earned it yet. Lawizer can set up the right structure — Pvt Ltd, OPC, or LLP — once you actually hit one of these signals.

    What You’ll Learn

    • Why registering a Pvt Ltd too early actually costs you money
    • The exact revenue, client, and funding signals that mean it’s time
    • Sole proprietorship vs OPC vs LLP vs Pvt Ltd — which fits your stage
    • Where GST and MSME registration fit into this timeline

    The Real Cost of Incorporating Too Early

    A lot of first-time founders register a Private Limited Company (a separate legal entity recognised by the Ministry of Corporate Affairs, or MCA) in their very first month, often because a CA friend suggested it or a WhatsApp forward made proprietorships sound risky.

    What most founders miss: a Pvt Ltd requires a statutory auditor from day one, annual ROC filings, ITR-6 returns, and DIN renewal — regardless of whether the company made ₹5 lakh or ₹0 in revenue that year.

    Realistic annual compliance for a small Pvt Ltd runs close to ₹35,000–₹60,000, even before you’ve validated whether anyone wants what you’re building. Compare that to a sole proprietorship, which needs no formal registration at all — you can start invoicing clients under your own PAN the same day you decide to freelance seriously.

    The short answer: build first, prove the business works, then incorporate. A structure doesn’t make a business real — revenue does.

    The Signals That Actually Mean It’s Time

    Instead of a calendar date, use triggers. Here’s what most founders who incorporate at the right time have in common:

    • You’re nearing ₹20 lakh in annual turnover. That’s the GST registration threshold for service providers in most states (₹40 lakh for goods, ₹10 lakh in special category states). Past this point, you’re a taxable entity whether or not you’ve incorporated.
    • A co-founder wants a documented equity split. You can’t issue shares without a company. This is the single most common reason two-person teams incorporate earlier than solo founders.
    • An investor is ready to wire money. Angel or institutional investors need a company bank account and a cap table — neither exists without incorporation.
    • An enterprise client’s procurement team asks for a “company PAN.” Large B2B buyers frequently can’t onboard an individual vendor, regardless of your Udyam or GST status.
    • You’re hiring employee #1 and want to offer ESOPs. Employee stock options only exist within a company structure.

    Notice what’s not on this list: having an idea, building an MVP, or making your first few sales. None of that requires a registered entity yet.

    Sole Proprietorship, OPC, LLP, or Pvt Ltd — Which Fits Your Stage

    Let’s break this down by what you’re actually doing right now, not what you plan to do eventually.

    Solo, under ₹20 lakh, no funding plans

    Stay a sole proprietor. You pay tax under your individual slab rate, not a flat corporate rate, and there’s no separate compliance calendar to track. A Udyam (MSME) registration is worth getting even at this stage — it costs almost nothing, helps you open a current account, and qualifies you for priority-sector lending later.

    Solo, corporate or international clients, liability-sensitive work

    Consider a One Person Company (OPC) — a company structure built specifically for single founders that still gives you limited liability and a distinct legal identity. IT consultants, SaaS builders, and agency owners working with larger clients often move here before they ever bring on a co-founder.

    Two or more founders, no funding yet

    An LLP (Limited Liability Partnership) is usually the better first move. It gives you a formal ownership split and limited liability without the statutory audit requirement that applies to Pvt Ltds from day one — LLPs only need an audit once turnover crosses ₹40 lakh.

    Raising money or planning to issue ESOPs

    This is when a Private Limited Company earns its cost. It’s the only structure investors will fund, the only one that supports employee stock options cleanly, and it comes with a genuine tax upside: domestic companies opting for the concessional regime under Section 115BAA of the Income Tax Act pay an effective rate of 25.17%, against individual slab rates that hit 30% plus cess well before ₹15 lakh in profit.

    Where GST and MSME Registration Fit In

    Incorporation and tax registration aren’t the same decision, and mixing them up is where a lot of founders get confused. You need GST registration once your turnover crosses ₹20 lakh (₹10 lakh in special category states) for services, regardless of whether you’re a proprietor, an LLP, or a Pvt Ltd.

    MSME (Udyam) registration is separate again — it’s not mandatory, but it’s fast, free, and worth doing early since it plugs into your income tax filings automatically.

    If you’re planning to apply for DPIIT recognition under the Startup India scheme — for the three-year tax exemption under Section 80IAC, or access to the Seed Fund Scheme — note that only Private Limited Companies and LLPs are eligible.

    Sole proprietorships and OPCs don’t qualify for this particular benefit, which is worth factoring in if government schemes are part of your growth plan.

    Making the Switch Without Losing Time

    Once you’ve hit a genuine trigger, converting from proprietor to a registered company isn’t a same-day process — it typically takes 7 to 21 business days depending on name approval and documentation.

    The company needs to formally take over your existing contracts, assets, and client relationships through a business transfer agreement, and your GST, PAN, and bank accounts all need updating to the new entity’s name.

    What most founders miss here: starting this conversion a few weeks before you actually need it — before the investor’s cheque is due, before the enterprise contract’s start date — saves you from scrambling. A company incorporation that’s rushed under deadline pressure is where documentation errors creep in.

    Frequently Asked Questions

    Q: Do I need to register my business before I start freelancing in India?

    A: No. You can invoice clients, accept payments, and pay income tax under your own PAN as a sole proprietor without any formal registration. You only need to register for GST once your turnover crosses ₹20 lakh a year (₹10 lakh in a few special category states).

    Q: What’s the minimum revenue before I should think about a Pvt Ltd?

    A: There’s no fixed number, but most founders find it makes sense once they’re consistently earning ₹1–1.5 lakh a month, are approaching the ₹20 lakh GST threshold, or have a specific trigger like investor funding or an enterprise contract. Below that, a Pvt Ltd’s compliance cost usually outweighs the benefit.

    Q: Can I convert my sole proprietorship into a private limited company later?

    A: Yes. You incorporate a new Pvt Ltd and then transfer the existing business’s assets, liabilities, and contracts to it through a business transfer agreement. The process usually takes 7–21 business days, and losses from the proprietorship generally can’t be carried forward into the new company.

    Q: Is a one person company (OPC) better than a sole proprietorship?

    A: An OPC gives you limited liability and a separate legal identity, which a sole proprietorship doesn’t — useful if you work with corporate clients or carry contractual risk. But it comes with more compliance than a proprietorship, so it’s usually a step you take once liability protection actually matters to your business.

    Ready to incorporate at the right time?
    Lawizer’s experts handle Pvt Ltd, OPC, and LLP incorporation, GST registration, and MSME/Udyam registration — fully online, starting at just ₹1,999. No CA visit needed.

    Get your business incorporated →

  • What Happens Legally If Your Startup Misses Payroll?

    What Happens Legally If Your Startup Misses Payroll?

    ₹20,722.5 crore. That’s the combined FY25 loss reported by 45 loss-making Indian startups so far. When the runway gets short, payroll is often the first casualty. Missing even one salary cycle may seem like a temporary cash-flow issue to a founder. Legally, however, it isn’t.

    The moment payday passes without payment, the issue goes beyond a simple delay. You begin accumulating legal liability under at least three separate laws.

    📌 TL;DR: Delaying or skipping employee salaries in India isn’t just a cash-flow issue — it’s a compliance breach under the Payment of Wages Act, and in serious cases can trigger criminal proceedings, Companies Act liability, or an insolvency petition under the IBC. Founders who act early — with written communication, structured settlement plans, and proper documentation — significantly reduce their legal exposure. Lawizer helps startups stay compliant on payroll, ROC filings, and labour law so a rough quarter never becomes a legal crisis.

    What You’ll Learn

    • Whether delaying salary is actually illegal in India, and by how many days
    • The specific laws that apply — Payment of Wages Act, IPC/BNS, Companies Act, IBC
    • What your employees can legally do if you miss payroll
    • How unpaid salaries can escalate into an insolvency petition against your company
    • Practical steps to protect the company (and yourself, personally) before it gets there

    Is It Actually Illegal to Delay Employee Salaries?

    Yes — and most founders underestimate by how much. Employers must pay wages before the 7th day of the following month in smaller establishments and before the 10th day in larger ones, as required by the Payment of Wages Act, 1936. There’s no grace period for “waiting on the next funding tranche.”

    Here’s the thing: this Act currently covers employees earning up to ₹24,000 a month, which includes the vast majority of early-career hires at most startups — support staff, junior developers, sales executives, and operations teams.

    Employees who earn above that threshold still receive legal protection and can pursue civil recovery through a summary suit or, in senior roles, file a straightforward money recovery claim.

    What most founders miss: a company doesn’t need to formally “refuse” to pay to be in breach. Simply missing the statutory deadline — even by a few days, even with a WhatsApp message promising payment “next week” — is a compliance violation the moment it happens.

    The Laws That Kick In When Payroll Is Missed

    Salary non-payment in India isn’t governed by one law — it’s a stack of them, and each one gets more serious than the last.

    1. Payment of Wages Act, 1936 — the civil layer

    This is the first trigger point. Delayed wages entitle the employee to file a claim with the labour authority, and courts have the power to order payment of the dues plus compensation, on top of the original amount owed.

    2. Criminal liability for intentional non-payment

    For example, if a startup records salaries as “paid” in its books but never transfers the money to employees, it does more than delay payment—it misrepresents the facts. Authorities can prosecute this conduct as cheating or criminal breach of trust under criminal law, in addition to any labour-related claims.

    3. Companies Act, 2013 — fraud provisions

    If a company combines unpaid salaries with falsified financial records—for example, by recording payroll as disbursed in books submitted for audit or fundraising while employees remain unpaid—Section 447 of the Companies Act treats the conduct as corporate fraud. This offence carries far more severe consequences than a simple wage dispute.

    4. The new Labour Codes

    India’s four consolidated labour codes came into force on November 21, 2025, replacing 29 older laws.

    Under the new framework, authorities continue to penalize payment delays, and employers can no longer use payroll structures that artificially reduce statutory contributions. Basic pay must now account for at least 50% of total compensation, directly increasing gratuity and provident fund (PF) liability calculations.

    What Employees Can Legally Do If You Miss Payroll

    The short answer: more than most founders assume, and faster than most founders expect. A typical sequence looks like this:

    • Send a formal legal notice demanding payment within a fixed window, usually 7–15 days
    • File a complaint with the jurisdictional Labour Commissioner, who can summon the employer for reconciliation
    • Escalate to the Labour Court if the complaint isn’t resolved, with claims filed within one year of default
    • Pursue a civil recovery suit for managerial or senior staff not covered under the Payment of Wages Act
    • File as an operational creditor under the Insolvency and Bankruptcy Code if dues cross ₹1 lakh

    Let’s break this down further with the piece founders underestimate most: once a legal notice lands, the clock is already running publicly. A response — or lack of one — becomes evidence in any future proceeding.

    This is exactly the kind of documentation gap that proper business compliance support is built to close before it becomes a liability.

    How Missed Salaries Can Trigger Insolvency Proceedings

    Here’s the escalation path founders genuinely don’t see coming. Under the Insolvency and Bankruptcy Code, an employee owed ₹1 lakh or more in unpaid wages qualifies as an “operational creditor” — the same legal category as an unpaid vendor.

    The process starts with a demand notice. If the company doesn’t respond or settle within the specified period, employees can collectively petition the NCLT, which can trigger appointment of a resolution professional and formation of a creditors’ committee.

    If the company fails to resolve the issue, creditors can push it into liquidation—a legal outcome that began with a missed payday.

    A quick example shows why documentation matters: courts have repeatedly ruled that employers cannot arbitrarily withhold earned wages, and employees remain entitled to recover them even when the employment arrangement contains procedural irregularities.

    Clean records protect both the company and the employee. Clean records protect the company as much as they protect the employee.

    How Founders Can Protect Themselves Before It Escalates

    The good news: almost every escalation on this list is avoidable with early, documented communication. What actually works:

    • Communicate delays in writing before the due date, not after — silence is what triggers legal notices
    • Never show salary as “paid” internally or to auditors if it hasn’t actually been disbursed
    • Prioritise partial payments over zero payments — courts and employees respond very differently to good-faith effort
    • Put a written settlement plan in place with dates, even if amounts are staggered
    • Keep statutory filings — PF, ESIC, TDS on salary — current even when gross pay is delayed, since these carry separate penalties

    If your startup is also behind on tax filings or MSME-linked payment obligations during a cash crunch, those compliance gaps compound fast — each one is a separate legal exposure, not a single combined problem.

    Frequently Asked Questions

    Q: Is it illegal for a startup to delay salary by a few days?

    A: Yes. Under the Payment of Wages Act, 1936, employers must pay wages within 7 days after the wage period ends for smaller establishments and within 10 days for larger ones.Any delay beyond this, even without malicious intent, is technically a violation founders should treat seriously.

    Q: Can an employee file a criminal case against a startup for not paying salary?

    A: Yes, in cases involving intentional deception — such as salary shown as disbursed in records but never actually transferred. Authorities can pursue this as cheating or criminal breach of trust, separately from the labour claim for the unpaid amount.

    Q: Can unpaid employee salary lead to my startup being taken to insolvency court?

    A: Yes. Under the IBC, an employee owed ₹1 lakh or more can file as an operational creditor. If the company doesn’t respond to a demand notice, employees can collectively petition the NCLT, which can ultimately lead to liquidation proceedings.

    Q: What should a founder do first if the company genuinely can’t make payroll?

    A: Communicate the delay in writing before the due date, offer a partial payment if possible, and put a dated settlement plan on record.
    The law treats documented, proactive communication very differently from silence that forces employees to escalate the issue on their own.

    Q: Do the new labour codes change the penalties for salary delays?

    A: Yes. India’s four consolidated labour codes took effect on November 21, 2025, and payment delays remain fully punishable under the new framework.
    Additionally, employers must keep basic pay at or above 50% of total compensation, changing how they calculate PF and gratuity liabilities even before a payment delay occurs.

    Ready to get your startup’s payroll and compliance airtight?
    Lawizer’s experts handle payroll compliance reviews, statutory filings, and labour law documentation — fully online, starting at just ₹1,999. No CA visit needed.

    Talk to a Lawizer compliance expert →

  • Why Compliance Gaps Kill Startup Funding Rounds in India

    Why Compliance Gaps Kill Startup Funding Rounds in India

    A 2025 study on Indian fintech due diligence found that 73% of failed deals traced back to regulatory gaps — missed licences, KYC lapses, and messy cross-border filings. If you’re heading into a funding round, compliance gaps are the single most preventable reason term sheets fall apart.

    Investors don’t walk away because your product is weak. They walk away because your paperwork doesn’t match your story.

    📌 TL;DR: Indian startups routinely lose funding rounds over compliance gaps like missed MCA filings, unassigned IP, undocumented ESOPs, and a cap table that doesn’t match the Registrar of Companies’ records. Investors treat these as governance red flags, not paperwork errors, and they either cut valuation, add protective clauses, or exit the deal entirely. Lawizer helps founders fix these gaps — incorporation, GST, MSME, and ROC filings — before an investor’s lawyer finds them first.

    What You’ll Learn

    • The specific compliance gaps that most often derail Indian startup funding rounds
    • Why investors treat small filing lapses as governance red flags, not clerical mistakes
    • A practical checklist to get your startup diligence-ready before term sheet stage

    Why Investors Treat Compliance Gaps as Deal-Breakers

    Here’s the thing: investors aren’t auditing your paperwork for fun. A missed filing tells them something bigger — that operational discipline is missing somewhere else too.

    Legal due diligence reports from Indian VC-backed deals show that more than half of failed rounds involve issues around revenue recognition, burn-rate reporting, or undocumented liabilities, not just product or market concerns.

    What most founders miss: compliance records aren’t a formality you clean up before a round. They’re evidence. When your Ministry of Corporate Affairs (MCA) filings, GST returns, and internal cap table all line up without explanation, it shortens diligence timelines and protects your valuation. When they don’t, investors either delay closing, demand indemnities, or walk.

    The Five Compliance Gaps That Kill Indian Funding Rounds

    The short answer: most funding rounds don’t die over one catastrophic issue. They die over a pattern of small, avoidable gaps that pile up in the data room. These are the ones that show up again and again in Indian startup due diligence.

    • Missed ROC filings: AOC-4, MGT-7, and DIR-3 KYC are annual, non-negotiable filings under the Companies Act, 2013. Recent MCA data shows nearly 18% of active startups missed at least one annual form in FY 2024–25, and each miss adds daily penalties plus a red flag in your compliance history.
    • Cap table mismatches: If your internal cap table doesn’t match the Register of Members filed in Form MGT-7, investors treat it as a serious discrepancy — not a typo.
    • Unassigned IP: Under Indian law, intellectual property created by a founder or freelancer belongs to the creator unless it’s formally assigned to the company. Missing IP assignment agreements are one of the most common reasons diligence stalls.
    • Undocumented ESOPs: An ESOP scheme approved informally, without a shareholder special resolution filed via Form MGT-14, is technically unauthorised — and investors will ask you to fix it as a closing condition.
    • GST and TDS mismatches: Delayed GST returns or input tax credit discrepancies trigger automated notices, and investors now expect at least two years of clean tax filing history before they commit.

    How Compliance Gaps Actually Cost You Money and Time

    Let’s break this down. A single missed DPT-3 filing or a deactivated Director Identification Number (DIN) from a skipped DIR-3 KYC doesn’t just cost a penalty. It stalls the entire round while your lawyers scramble to fix it mid-negotiation — and every week of delay is a week where the investor can renegotiate terms or lose interest.

    A quick example: founders preparing for Series A routinely discover, right in the middle of diligence, that unpaid vendor dues weren’t reflected in the books, or that a director loan was never reported on Form DPT-3. Each of these is fixable on its own.

    Together, three or four of them signal weak financial control, and that’s what actually erodes valuation — not the individual filing.

    This is also where MSME Udyam registration matters more than founders expect — investors check it as part of vendor payment compliance, since companies with unresolved MSME dues beyond 45 days face mandatory half-yearly disclosure under Form MSME-1.

    Building a Diligence-Ready Compliance Spine

    What separates startups that close rounds smoothly from those that don’t isn’t luck — it’s a compliance routine that runs quietly in the background, independent of fundraising timelines. Founders who pass due diligence on the first attempt tend to share the same habits.

    Quarterly, not annual, compliance check-ins

    Waiting until a term sheet lands to review your MCA and GST status means you’re fixing years of gaps under time pressure. A quarterly review catches issues while they’re still cheap to correct.

    Every founder and freelancer signs an IP assignment

    This should happen at the point of hiring, not right before a data room goes out. It’s a one-page fix that removes one of the most common deal-breakers investors flag.

    Trademark and brand protection early

    Investors also check whether your core brand assets are actually yours to defend. A trademark registration filed early, through the IP India portal, signals that your intangible assets are protected — something diligence teams increasingly flag when it’s missing.

    Clean, filed tax history

    Investors typically review at least two years of income tax filings during due diligence. Keeping your ITR filings current, alongside GST returns on the GSTN portal, removes an entire category of objections before they surface.

    What to Fix Before Your Next Funding Conversation

    If a round is even loosely on your roadmap for the next six months, start with the three areas that carry the most weight in diligence: your cap table, your IP assignments, and your top statutory filings. These are where ownership and control actually sit, and they’re where investors look first.

    Founders who go through company incorporation and compliance the right way from day one rarely face this scramble. If you incorporated quickly and deferred the paperwork, now is the point to close the gap — before an investor’s counsel finds it for you.

    Frequently Asked Questions

    Q: Can a startup really lose a funding round just because of missed MCA filings?

    A: Yes. Missed filings like AOC-4 or DIR-3 KYC signal weak governance to investors, and combined with other gaps, they can lead to reduced valuation, added protective clauses, or a walked deal. Investors view MCA filing history as a direct proxy for how disciplined a founding team is.

    Q: What compliance documents do investors ask for first?

    A: Investors typically start with MCA incorporation and filing records, the cap table with supporting Form PAS-3 filings, board meeting minutes, IP assignment agreements, and GST or income tax filing history. These form the baseline before deeper legal and financial due diligence begins.

    Q: How early should we start compliance clean-up before raising funds?

    A: Most advisors recommend starting three to six months before you plan to raise, since fixing statutory gaps, reconciling cap tables, and completing IP assignments takes time. Startups that maintain investor-ready records year-round avoid this scramble entirely.

    Q: Is an unregistered trademark actually a funding risk?

    A: Yes, especially for consumer or brand-led startups. Investors want assurance that your core brand identity is legally defensible, and an unregistered trademark leaves your most valuable intangible asset exposed to disputes or copycats after the round closes.

    Q: Do informal ESOP promises to early employees cause problems during diligence?

    A: Yes. ESOP grants issued without a shareholder-approved scheme filed with the MCA are technically unauthorised, and investors will require you to ratify or restructure them before closing, which adds time and legal cost to the round.

    Ready to make your startup diligence-ready?
    Lawizer’s experts handle company incorporation, GST filing, MSME registration, and trademark protection — fully online, starting at just ₹1,999. No CA visit needed.

    Get your compliance in order →

  • ESOP for Startup Employees: Set It Up the Right Way

    ESOP for Startup Employees: Set It Up the Right Way

    78% of Indian startups now offer ESOPs, up from just 59% in 2021. And yet, most founders get the paperwork wrong on the first try. Common mistakes include choosing the wrong pool size, skipping the cliff clause, or filing Form SH-6 months late.

    An ESOP helps startups retain employees only when founders structure it correctly from day one.

    Get it wrong, and you could dilute the founders more than necessary. You might also give your best engineer an ESOP grant with a weak legal foundation. Here’s how to build it properly.

    📌 TL;DR: Setting up an ESOP for startup employees in India means creating a pool (typically 10–15% of equity), getting board and shareholder approval under Section 62(1)(b) of the Companies Act 2013, and drafting a scheme with a clear vesting schedule — usually 4 years with a 1-year cliff. Lawizer handles the drafting, filings, and compliance so founders don’t lose deals or grants to paperwork errors.

    What You’ll Learn

    • How to size and create your ESOP pool without over-diluting founders
    • How vesting, cliffs, and exercise price actually work in practice
    • Which MCA filings and board resolutions you cannot skip
    • How Employees Pay Tax on ESOPs and What Founders Should Explain Upfront

    What Is an ESOP and Why Indian Startups Use It

    An ESOP (Employee Stock Option Plan) gives an employee the right — not the obligation — to buy company shares at a fixed price in the future. It’s not ownership on day one. It’s a promise: stay, contribute, and you’ll earn the right to buy in at today’s price, even if the company’s value climbs many times over by the time you exercise.

    Here’s the thing. Cash-strapped early-stage startups in Bengaluru, Mumbai, and Delhi cannot always match the salaries offered by large tech companies. Instead, they use ESOPs to attract the same engineers and product professionals. They offer equity instead of, or alongside, cash compensation.

    Under the Companies Act, 2013 (Section 62(1)(b)), private limited companies can issue ESOPs following Ministry of Corporate Affairs rules, and DPIIT-recognised startups get added flexibility, including the ability to grant options to promoters and directors, which other private companies can’t do.

    What most founders miss: an ESOP works as a retention tool only if employees actually understand it. A grant letter full of jargon with no explanation of vesting or tax impact does very little for morale, however generous the number of options looks on paper.

    How to Set Up an ESOP Pool the Right Way

    An ESOP pool is a portion of the company’s equity that founders reserve specifically for employees. Most Indian startups create the pool before a funding round so founders absorb most of the dilution instead of incoming investors. Investors also expect startups to follow this approach.

    • Seed stage: around 10% of fully diluted equity
    • Series A and beyond: 12–15%, and growing further at later stages as senior hires join
    • Approval needed: board resolution plus special resolution from shareholders

    A quick example: if you set a 10% pool pre-Series A and the new investor takes a 25% stake, your pool dilutes proportionally too. Founders often “top up” the pool back to the original target right after the round closes, so there’s enough room for the next 18–24 months of hiring.

    If you’re incorporating your startup and structuring equity at the same time, handle company incorporation and compliance together. This approach lets you build the ESOP pool into your cap table from the start instead of adding it later.

    Vesting Schedule, Cliff, and Exercise Price

    This is where most ESOP confusion lives, both for founders drafting the scheme and employees trying to figure out what they actually own. The standard structure across Indian startups is a 4-year vesting period with a 1-year cliff.

    In simple terms, employees do not receive any vested options during the first 12 months. Leave before that, and the entire grant lapses — this is the cliff, and Indian rules treat one year as the minimum. Cross the cliff, and 25% vests immediately.

    The remaining 75% typically vests monthly or quarterly over the next three years, allowing the employee to become fully vested by month 48.

    Exercise price, explained

    The exercise price (also called strike price) is what an employee pays per share when they exercise vested options — locked in at the Fair Market Value (FMV) on the grant date, determined by a registered valuer. If the company’s FMV rises later, the employee still pays the old, lower price. That gap is the wealth-creation part of the deal.

    • Vested options: employee CAN exercise, hasn’t yet
    • Exercised options: employee has paid and now holds shares
    • Post-termination exercise window: Employees usually have 90 days after leaving the company to exercise their vested options. Most people consider a window of less than 30 days unfair to employees.

    The Legal Documents and MCA Filings You Cannot Skip

    Let’s break this down. An ESOP isn’t a verbal promise or a line in an offer letter — it needs a documented, board-and-shareholder-approved scheme to hold up legally and to survive due diligence at your next funding round.

    • ESOP scheme document: objective, eligibility, pool size, vesting terms, exercise price formula, and what happens on termination or acquisition
    • Board and shareholder resolutions: approving the scheme and each subsequent grant
    • Individual grant letters: signed by company and employee, specifying number of options and vesting schedule
    • File Form SH-6: within 60 days of shareholder approval to disclose the ESOP scheme.
    • Register of Employee Stock Options: maintained by the company for every grant issued

    Founders who skip the SH-6 filing or fail to keep grant letters signed often find out the hard way — during Series A due diligence, when the investor’s legal team flags every gap and stalls the term sheet until it’s fixed.

    How ESOPs Are Taxed in India

    ESOP taxation catches almost every first-time recipient off guard, so it’s worth explaining to your team before they exercise, not after. Tax hits at two separate points.

    At exercise: the difference between the FMV on the exercise date and the exercise price is treated as perquisite income and taxed as salary, at the employee’s slab rate. At sale: any further gain is taxed as capital gains — short-term or long-term depending on the holding period.

    DPIIT-recognised startups get a meaningful exception here: eligible employees can defer the perquisite tax until they sell the shares, leave the company, or five years pass from allotment, whichever comes first. That removes the cash-flow problem of owing tax on shares you haven’t sold yet.

    If your startup qualifies, this deferral is worth building into how you communicate ESOP value at the offer stage — and it’s worth getting your tax filing and compliance sorted around it so neither the company nor the employee gets caught off guard at assessment time.

    Common ESOP Mistakes Founders Make

    A few patterns show up again and again in early-stage Indian startups, and they’re avoidable with a bit of planning upfront.

    • Creating a pool without a hiring plan — leads to either an underused pool or a mid-year restructuring scramble
    • No clawback clause — makes it hard to recover unvested equity when someone exits early
    • Arbitrary exercise price — not backed by a re
    • istered valuer’s FMV report, which creates tax and compliance risk
    • Over-diluting too early — giving away a large pool before the company has proven traction, which complicates future rounds
    • Poor communication — employees who don’t understand vesting or tax rarely value the grant the way founders expect them to

    The upside of getting this right is real: over a dozen Indian startups ran ESOP buybacks in 2025, helping more than 9,200 employees unlock actual wealth from options that were structured, documented, and communicated properly from the start.

    Frequently Asked Questions

    Q: How much equity should a startup set aside for ESOPs in India?

    A: Most Indian startups reserve 10–15% of fully diluted equity for their ESOP pool. Seed-stage companies typically start around 10%, increasing to 12–15% by Series A as leadership hires join. The right number depends on your hiring plan for the next 18–24 months.

    Q: What happens to my ESOP if I leave before one year?

    A: If you leave before completing the one-year cliff, all granted options lapse and you receive nothing. This is standard under Indian ESOP practice and exists to protect the company from granting equity to employees who don’t stay long enough to contribute meaningfully.

    Q: Can the exercise price be changed after the grant is made?

    A: No. The exercise price is fixed at the Fair Market Value on the grant date and cannot be reduced or altered retroactively without triggering tax complications. This is exactly why the exercise price should be based on a formal valuer’s report, not an internal estimate.

    Q: Are ESOPs taxed twice in India?

    A: Yes. Tax applies once at exercise, when the gap between FMV and exercise price is taxed as salary income, and again at sale, when further gains are taxed as capital gains. DPIIT-recognised startups can offer eligible employees a deferral on the exercise-stage tax.

    Q: Do I legally need board approval to grant ESOPs, or can I just issue them informally?

    A: Board approval, and in most cases shareholder approval, is mandatory under Section 62(1)(b) of the Companies Act, 2013. Grants made without proper resolutions and Form SH-6 filings can be challenged later and often surface as red flags during investor due diligence.

    Q: Can promoters or founders receive ESOPs too?

    A: Generally, promoters and directors holding over 10% equity are excluded from ESOP eligibility. DPIIT-recognised startups get an exception for the first 10 years from incorporation, allowing them to grant ESOPs to promoters and directors as well.

    Ready to set up your ESOP the right way?
    Lawizer’s experts handle ESOP scheme drafting, board and shareholder resolutions, and Form SH-6 filing — fully online, starting at just ₹4,999. No CA visit needed.

    Set Up Your ESOP with Lawizer →

  • SEBI’s New ESOP Rules for Founders: 2025 Update

    SEBI’s New ESOP Rules for Founders: 2025 Update

    On September 8, 2025, SEBI quietly rewrote the rules on founder ESOPs (Employee Stock Option Plans). These plans let founders buy company shares at a fixed price after a vesting period. The change could save you crores if you’re heading toward an IPO. Founder Vijay Shekhar Sharma had already learned this the hard way, surrendering ESOPs worth over ₹1,800 crore months earlier.

    Hold founder stock options? If your startup has even a remote chance of going public, this regulatory change could significantly impact your personal wealth.

    📌 TL;DR: SEBI’s new ESOP rules for founders (Regulation 9A of the SBEB Regulations, effective September 8, 2025) allow founders reclassified as promoters ahead of an IPO to keep and exercise ESOPs, provided those options were granted at least one year before the draft offer document was filed. Earlier, promoters had to surrender or exercise all ESOPs before listing. Lawizer helps founders and startups stay compliant with these evolving SEBI and Companies Act requirements.

    What You’ll Learn

    • Why founders were losing their ESOPs right before an IPO
    • What Regulation 9A actually says, in plain English
    • How the Paytm case pushed SEBI to act
    • Who qualifies for this exception — and who doesn’t
    • What founders should do differently starting now

    The Problem: Why Founders Were Losing Their ESOPs Before an IPO

    Here’s the thing. The Companies Act, 2013, and SEBI’s earlier SBEB (Share Based Employee Benefits and Sweat Equity) Regulations, 2021, prohibit promoters from receiving or holding ESOPs. The reasoning is straightforward: ESOPs exist to reward employees, not founders or owners who already control the company.

    But most Indian founders don’t start out as “promoters.”In the early, cash-strapped years, startups often grant founders ESOPs because they work as employees, long before anyone considers taking the company public. The trouble starts when the company files its DRHP (Draft Red Herring Prospectus — the preliminary IPO document filed with SEBI) and the founder gets reclassified as a promoter based on their shareholding or board control.

    At that point, the old rules forced founders to either exercise or forfeit all the ESOPs they had earned. In some cases, years of unrealised compensation disappeared overnight.

    What most founders miss: this wasn’t a hypothetical risk. It was a real, recurring problem that made IPOs financially painful for the very people who built the company.

    What Changed: Regulation 9A, Explained Simply

    SEBI’s board approved the fix at its 210th board meeting on June 18, 2025, and formally notified it through the SEBI (Share Based Employee Benefits and Sweat Equity) (Amendment) Regulations, 2025 on September 8, 2025. This inserted a brand-new Regulation 9A into the SBEB framework.

    The short answer is yes. You can retain and exercise your ESOPs, Stock Appreciation Rights (SARs), or other equity benefits if your company’s DRHP identifies you as a promoter or member of the promoter group, provided the company granted those benefits at least one year before filing the DRHP.

    • ESOPs granted more than 12 months before your DRHP filing → protected, you keep them
    • ESOPs granted less than 12 months before your DRHP filing → still at risk
    • Fresh ESOPs after you’re classified as promoter → still not allowed, this hasn’t changed

    This one-year look-back period isn’t arbitrary. It’s SEBI’s way of drawing a line between genuine, long-term employee compensation and last-minute grants dressed up to dodge the promoter restriction just before going public.

    The Paytm Case: Why SEBI Finally Acted

    A quick example makes this real. Ahead of Paytm’s 2021 IPO, founder Vijay Shekhar Sharma transferred his shares to a family trust and secured non-promoter status in the DRHP. This restructuring allowed him to retain ESOPs that the regulations would otherwise have barred. SEBI later alleged this violated the SBEB Regulations.

    The dispute ended in a settlement in May 2025. Sharma surrendered 21 million unvested ESOPs worth over ₹1,800 crore. He also accepted a three-year ban on receiving fresh ESOPs from any listed company. The case exposed the ambiguity that SEBI needed to address. It also directly influenced the one-year cooling-off requirement in Regulation 9A.

    Who Actually Qualifies for This Exception?

    Let’s break this down into plain conditions. You qualify under Regulation 9A only if all of these are true:

    • You’re named as a promoter or promoter-group member in your company’s DRHP
    • Your ESOPs, SARs, or other benefits were granted while you were still classified as an employee
    • Those grants happened at least one year before the DRHP filing date
    • You continue holding or exercising them strictly on their original grant terms

    It’s worth separating this from a different, older provision. Under the Companies (Share Capital and Debentures) Rules, 2014, DPIIT-recognised startups (registered under the government’s MSME and startup recognition schemes) can issue ESOPs to promoters for up to 10 years from incorporation. That’s a pre-listing exemption. Regulation 9A is different — it specifically protects what happens after the DRHP is filed and the company is heading toward listing.

    What This Means If You’re Planning an IPO

    If your startup is even two to three years away from a possible listing, this changes how you should structure ESOP grants today. Founders and CFOs now have a real incentive to formalise ESOP grants early, document grant dates clearly, and avoid any last-minute stock option decisions once IPO conversations start internally.

    This change also matters for startups planning a reverse flip. A reverse flip shifts the holding structure from Delaware or Singapore back to India before an IPO on Indian exchanges. Founders in these companies were among the most affected by the old rule. The combination of restructuring and an IPO often required promoter reclassification twice.

    One thing hasn’t changed: once you’re classified as a promoter, you still cannot receive fresh ESOP grants. This protects only what you already earned, not what comes next. Founders in Bengaluru, Mumbai, and Delhi startup circles structuring their next funding round should factor this into their company incorporation and cap table planning well before any IPO discussion begins.

    Frequently Asked Questions

    Q: What is Regulation 9A of the SEBI SBEB Regulations?

    A: Regulation 9A is a September 2025 amendment to SEBI’s SBEB Regulations that lets founders retain and exercise ESOPs even after being classified as promoters in their company’s IPO documents. It applies only to ESOPs granted at least one year before the DRHP filing date.

    Q: Can a promoter still get new ESOPs after this change?

    A: No. Regulation 9A only protects ESOPs granted before the founder was classified as a promoter. Fresh ESOP grants to promoters are still restricted under both the Companies Act, 2013 and the SBEB Regulations.

    Q: Why did SEBI bring in this ESOP rule change in 2025?

    A: SEBI acted after cases like Paytm’s, where founder Vijay Shekhar Sharma had to surrender ESOPs worth over ₹1,800 crore due to unclear rules around promoter reclassification. The new rule closes that regulatory gap while keeping a one-year cooling-off period to prevent misuse.

    Q: Does this rule apply to private startups that haven’t filed for an IPO?

    A: No. Regulation 9A only becomes relevant once a company files its DRHP with SEBI for a public listing. Private, unlisted startups continue to follow the Companies Act provisions, including the DPIIT startup exemption allowing promoter ESOPs for up to 10 years from incorporation.

    Q: What happens if my ESOPs were granted less than a year before my company’s DRHP filing?

    A: Those ESOPs are not protected under Regulation 9A and remain subject to the older restriction, meaning they may need to be exercised or forfeited before the company lists. This is exactly the scenario the one-year cooling-off period was designed to prevent.

    Q: Where can founders get help structuring ESOPs correctly before an IPO?

    A: A company secretary or legaltech platform experienced in SEBI and Companies Act compliance can review your ESOP scheme, grant dates, and cap table to confirm you qualify for protection under Regulation 9A well before your IPO timeline begins.

    Ready to get your startup’s compliance IPO-ready?
    Lawizer’s experts handle everything — ESOP scheme structuring, company incorporation, and MSME registration — fully online, starting at just ₹999. No CA visit needed.

    Talk to a Lawizer compliance expert →

  • DPDP Act 2023 + Rules 2025: What Startups Must Do by 2027

    DPDP Act 2023 + Rules 2025: What Startups Must Do by 2027

    May 13, 2027 isn’t a suggestion. It’s the hard deadline for full DPDP Act compliance, and unlike most Indian regulatory rollouts, there’s no extended grace period baked in this time. If your startup collects a customer’s email, phone number, or even a device ID, this law already applies to you — whether you’ve got 200 users or 2 lakh.

    Most founders think this is a “big company” problem. It isn’t. Penalties run up to ₹250 crore per violation, and they stack.

    📌 TL;DR: The Digital Personal Data Protection (DPDP) Act 2023 and its Rules 2025 apply to every Indian startup that processes personal data, with full compliance mandatory by May 13, 2027. There’s no revenue or size exemption — a two-person SaaS team has the same core obligations as a listed company. Lawizer helps founders build DPDP-ready consent flows, privacy notices, and grievance mechanisms before the deadline hits.

    What You’ll Learn

    • What the DPDP Act and DPDP Rules 2025 actually require of startups
    • The exact phased timeline — November 2025, November 2026, and May 2027
    • What “Significant Data Fiduciary” means and whether it applies to you
    • A practical, founder-friendly compliance checklist

    What Is the DPDP Act 2023 and Why the Rules 2025 Change Everything

    The Digital Personal Data Protection Act, 2023 (DPDP Act) is India’s first comprehensive data privacy law, rooted in the Supreme Court’s Puttaswamy judgment that recognised privacy as a fundamental right. For years it sat unenforced because the government hadn’t notified the operational rules.

    That changed on November 13, 2025, when the Ministry of Electronics and Information Technology (MeitY) notified the final DPDP Rules 2025, which convert the Act’s broad principles into specific, enforceable obligations.

    Here’s the thing: the Act calls your startup a Data Fiduciary the moment you decide why and how personal data is collected — even if a third-party tool actually stores it.

    Your users are Data Principals, and any vendor processing data on your behalf (your CRM, your analytics tool, your cloud host) is a Data Processor. You stay accountable for what they do with that data, not them.

    The Compliance Timeline: Three Phases Every Founder Should Have on Their Calendar

    What most founders miss: the DPDP rollout isn’t a single deadline — it’s a phased 18-month clock that started ticking the day the Rules were notified

    • Phase 1 — November 13, 2025 (already live): The Data Protection Board of India (DPB) is operational and accepting complaints. Procedural provisions are in force.
    • Phase 2 — November 13, 2026: Consent Manager registration opens. If you plan to rely on a third-party consent platform, vendor due diligence needs to start well before this.
    • Phase 3 — May 13, 2027 (the real deadline): Every remaining obligation kicks in at once — consent notices, breach reporting, data principal rights, retention and erasure rules, and grievance redressal.

    The short answer: 2026 is your build year. Waiting until early 2027 to start means compressing a 12–18 month compliance programme into a few months — and rebuilding consent flows or data architecture under pressure rarely goes well.

    What Your Startup Must Actually Do Before May 2027

    Let’s break this down into what actually needs building, not just legal language.

    1. Redesign your consent flow

    Consent under DPDP must be free, specific, informed, and given through a clear affirmative action — not inferred from continued app use. A standalone privacy notice separate from your Terms of Service is mandatory, and withdrawing consent must be as easy as giving it.

    2. Map every place personal data flows through your systems

    You can’t protect what you haven’t inventoried. Map every entry point — signup forms, payment gateways, support tickets, analytics SDKs — and log which vendors touch that data.

    3. Build breach notification protocols

    Under Section 8(6) of the Act and Rule 7 of the Rules, a breach must be reported to the Data Protection Board without unreasonable delay, followed by a detailed report within 72 hours. If your startup doesn’t have an incident response checklist today, this is the moment to write one.

    4. Set retention and erasure policies

    Data must be deleted once its purpose is served or consent is withdrawn. Erasure requests must be honoured within 90 days, and this applies to data sitting with your processors too — not just your own servers.

    5. Handle children’s data with extra care

    If your product could reasonably be used by anyone under 18, verifiable parental consent is required, and behavioural tracking or targeted advertising to minors is prohibited outright.

    If your startup is still setting up its legal foundation, organize your core business legal documentation first. A clear entity structure and well-drafted contracts make it much easier to create privacy policies and consent frameworks.

    Penalties: What Happens If You Don’t Comply

    The short answer: this isn’t a slap-on-the-wrist regime. Failure to maintain reasonable security safeguards can attract penalties up to ₹250 crore. Delayed breach notification and violations involving children’s data can each attract penalties up to ₹200 crore.

    General non-compliance can still cost up to ₹50 crore. Since penalties are imposed per violation, a single incident can trigger multiple penalty categories at the same time.

    For example, a startup that suffers a data breach may delay reporting it. If it also has weak security safeguards, one incident could lead to three separate penalty categories. There’s no small-business carve-out in the fine structure — the DPB assesses based on the violation, not your headcount.

    Does “Significant Data Fiduciary” Status Apply to You?

    What most founders miss here: the Act distinguishes between ordinary Data Fiduciaries and Significant Data Fiduciaries (SDFs), a tier the government notifies based on the volume of data you process, its sensitivity, and potential for harm.

    SDFs carry heavier obligations — appointing a Data Protection Officer based in India, conducting annual Data Protection Impact Assessments, and independent audits.

    Most early-stage startups won’t be classified as SDFs at launch. But if you’re scaling fast — particularly in fintech, healthtech, or any platform handling sensitive personal data at volume — it’s worth tracking MeitY notifications closely, since SDF status can change your compliance obligations overnight.

    Startups formalising their MSME registration as they scale should build this monitoring into their broader compliance calendar.

    A Practical DPDP Compliance Checklist for Indian Startups

    • Appoint a privacy lead or focal point, even if it’s a founder wearing multiple hats
    • Map all personal data flows across your product, team, and vendors
    • Draft a standalone privacy notice, separate from your Terms of Service
    • Rebuild consent capture so it’s affirmative, specific, and easily withdrawable
    • Set up a grievance redressal mechanism with a published contact point
    • Encrypt stored and transferred data, and review access controls
    • Review every vendor contract for DPDP-compliant data processing clauses
    • Define retention and deletion timelines for every data category you hold

    India’s startup ecosystem is already responding — as Inc42 reported, a wave of privacy-tech startups and platforms are building consent management and compliance tooling specifically for this law, which tells you how seriously the market is treating the May 2027 deadline.

    Frequently Asked Questions

    Q: Is my small startup exempt from the DPDP Act if we only have a few hundred users?

    A: No. There is currently no statutory revenue or user-count exemption for startups or MSMEs under the DPDP Act. If you collect personal data such as names, emails, or phone numbers, core compliance obligations apply regardless of your size.

    Q: What is the actual deadline for DPDP compliance in India

    A: May 13, 2027 is the full compliance deadline, 18 months after the DPDP Rules were notified on November 13, 2025. Some provisions, like Consent Manager registration, become active earlier, in November 2026.

    Q: What happens if my startup doesn’t comply by the deadline?

    A: The Data Protection Board of India can impose penalties of up to ₹250 crore depending on the violation, and these penalties can stack if a single incident breaches multiple provisions. There is no grace period built into the penalty framework after May 2027.

    Q: Do I need a Data Protection Officer for my startup?

    A: Only if the government designates your startup as a Significant Data Fiduciary. Other Data Fiduciaries need a grievance redressal mechanism and a clear contact point for data principals, but not a formally appointed DPO.

    Q: Does the DPDP Act apply if my startup is based outside India but has Indian users?

    A: Yes. The Act has extra-territorial application and covers any organisation processing personal data in connection with offering goods or services to individuals located in India, regardless of where the company itself is incorporated.

    Q: Can cookies count as personal data under DPDP?

    A: Neither the Act nor the Rules explicitly mention cookies, but personal data is defined broadly enough to include any data relating to an identifiable individual. Where cookies can be linked back to a person, directly or combined with other data, they likely fall within scope.

    Ready to get DPDP-ready before the 2027 deadline?
    Lawizer’s experts handle everything — privacy policy drafting, consent framework design, and compliance documentation — fully online, starting at just ₹4,999. No CA visit needed.

    Start your DPDP compliance review →

  • India’s Legaltech Boom: What $793M in Funding Means for You

    India’s Legaltech Boom: What $793M in Funding Means for You

    India’s legaltech sector has attracted $793 million in cumulative funding. In 2025, the industry recorded a 781% year-on-year increase, marking the largest single-year funding surge in its history. That’s not a rounding error. That’s investors betting big money that Indian founders are done doing legal paperwork the old way.

    If you’re a founder who still emails PDFs back and forth with a CA for GST filing or MSME registration, things are about to change. This legaltech boom is redefining what “normal” looks like for business compliance.

    📌 TL;DR: India’s legaltech industry has raised $793 million across roughly 960 companies, with 2025 funding up 781% year-on-year — the sector’s biggest jump on record. For founders, this means faster, cheaper, more reliable online options for company incorporation, GST, trademark, and MSME compliance instead of slow offline processes. Platforms like Lawizer are part of this shift, handling incorporation and compliance fully online so founders can skip the CA-office runaround.

    What You’ll Learn

    • Why $793 million is flowing into Indian legaltech right now
    • What’s actually driving the 781% funding surge in 2025
    • How this changes company incorporation, GST, and compliance for founders
    • What to watch for before picking a legaltech platform

    The Numbers Behind India’s Legaltech Boom

    Here’s the thing. Legaltech used to be the sleepy corner of Indian startup investing — the sector fintech and edtech investors barely glanced at. That’s flipped.According to data from Tracxn’s startup database, India is home to around 960 legaltech companies. Among them, 86 have secured funding, and one has achieved unicorn status.

    The real story is the pace. Legaltech funding in India has grown from about $107 million to a cumulative $793 million. In 2025, the sector recorded a 781% year-on-year increase, marking its highest annual investment to date.

    A quick example: SpotDraft, a contract automation platform, alone raised over $113 million across multiple rounds, including backing from Qualcomm Ventures. That’s the scale of confidence investors now have in Indian legal technology.

    Why Now?

    • India’s regulatory load keeps growing — DPDPA, GST updates, Companies Act 2013 amendments, and sector-specific rules all add compliance work
    • AI-powered document review and drafting cut turnaround time dramatically, making automation commercially viable
    • Millions of MSMEs and startups need affordable, scalable legal access that traditional law firms and CAs can’t deliver at volume

    What This Means for Company Incorporation

    Let’s break this down. Company incorporation in India runs through SPICe+ (Simplified Proforma for Incorporating Company Electronically Plus — MCA’s online incorporation form), filed on the MCA21 portal.

    On paper, it’s already digital. In practice, most founders still end up stuck answering DIN queries, chasing digital signature certificates, or waiting on a CA who’s juggling twenty other clients.

    What most founders miss: the legaltech money isn’t just building flashy AI tools for law firms. A meaningful chunk is going into founder-facing platforms that handle the entire incorporation-to-compliance journey — private limited company registration, LLP setup, GST registration, and ongoing filings — without the founder ever stepping into a CA’s office. That’s the direct benefit of this funding wave reaching your desk.

    If you’re incorporating a company or setting up your compliance stack from scratch, Lawizer’s business registration services are built exactly for this shift — online-first, no repeated office visits, transparent pricing

    GST, Trademark, and MSME: The Everyday Wins

    The short answer: automation is finally reaching the parts of compliance founders actually dread — recurring GST filings, trademark status tracking, and MSME/Udyam renewals. These aren’t glamorous problems, but they’re the ones that eat a founder’s Tuesday afternoon every single month.

    GST compliance, tracked through GSTN’s own systems, has traditionally meant founders relying on their CA to remember filing deadlines. As more legaltech investment flows into compliance automation, platforms now send proactive reminders. They also auto-populate returns and flag mismatches before they turn into legal notices.

    A trademark filed through the Controller General of Patents, Designs and Trademarks (CGPDTM) can now be tracked in real time. Founders no longer need to call their lawyer every few weeks to ask, “Any update?”

    Same logic applies to brand protection and MSME benefits. If you have not registered your trademark yet, do it early to protect your brand name. Early registration also reduces the risk of a competitor claiming it first. Lawizer’s trademark registration service handles the entire CGPDTM filing process from start to finish.

    And if you qualify for MSME status, Udyam registration through Lawizer unlocks collateral-free loans, delayed payment protection, and tender benefits that most founders don’t even know exist.

    What to Watch Before You Pick a Legaltech Platform

    A funding boom brings good tools — and also a lot of noise. Not every platform that raised money is built for a first-time founder in Bengaluru registering a two-person startup, versus an enterprise legal team in Mumbai managing thousand-contract portfolios. Here’s what actually matters when you’re evaluating options:

    • Does it handle India-specific requirements — MCA21 filings, state-wise GST rules, Aadhaar-based e-sign — or is it a generic tool adapted for India?
    • Is pricing transparent upfront, or do “starting from” prices balloon once you add government fees and follow-up filings?
    • Can you actually talk to a real compliance expert when something goes wrong, or is it a chatbot loop?

    What most founders miss: the platform’s funding size says nothing about whether it fits your stage. A well-capitalized enterprise CLM (Contract Lifecycle Management) tool is overkill if all you need is to file your first ITR (Income Tax Return). For income tax filing done right the first time, Lawizer’s ITR filing service keeps it simple and founder-focused.

    Where This Is Headed

    A quick example of the trajectory: the Indian legaltech market is projected to cross $1.28 billion in 2026, growing at roughly 15.2% CAGR — a pace faster than the global average. That growth is driven by a simple fact — India’s regulatory load isn’t shrinking.

    Between DPDPA, evolving GST rules, and Companies Act compliance, founders will need more automated help, not less.

    Here’s the thing: this isn’t really about the funding number. It’s about what it buys founders — faster incorporation, fewer missed deadlines, and compliance that doesn’t require a law degree to understand. That’s the actual dividend of $793 million landing in this sector.

    Frequently Asked Questions

    Q: How much funding has India’s legaltech sector raised so far?

    A: India’s legaltech sector has raised a cumulative $793 million in venture capital and private equity across roughly 960 companies. 2025 alone saw a 781% year-on-year rise in funding compared to the previous year, marking the highest annual investment the sector has recorded so far.

    Q: Does the legaltech boom actually help small founders, or just big law firms?

    A: Both, but founder-facing platforms are a major part of the investment. A large share of legaltech funding is going into tools for company incorporation, GST filing, trademark tracking, and MSME registration — the everyday compliance work small founders deal with, not just enterprise contract management.

    Q: Is online company incorporation in India actually reliable now?

    A: Yes. Company incorporation runs through MCA’s SPICe+ form on the MCA21 portal, and legaltech platforms have built layers on top of it to handle document prep, DIN and DSC processing, and follow-up queries without the founder needing to visit an office. This is one of the most mature use cases in the current funding wave.

    Q: What should I check before choosing a legaltech platform for my startup?

    A: Check whether the platform handles India-specific requirements like state-wise GST rules and Aadhaar e-sign, confirm pricing is transparent with no hidden government-fee markups, and make sure you can reach a real compliance expert if an issue comes up. A platform’s total funding doesn’t tell you whether it’s built for your specific stage or need.

    Q: Why is India’s legaltech funding growing faster than other sectors right now?

    A: Growth is driven by increasing regulatory complexity — DPDPA, GST updates, and Companies Act compliance all create continuous demand — combined with AI tools that make automated drafting and review commercially viable at scale. India’s legaltech market is projected to grow faster than the global average through 2030.

    Ready to skip the compliance runaround?
    Lawizer’s experts handle everything — company incorporation, GST registration, trademark filing — fully online, starting at just ₹1,999. No CA visit needed.

    Start your registration with Lawizer →

  • How AI Is Reviewing Contracts Faster Than Lawyers in India

    How AI Is Reviewing Contracts Faster Than Lawyers in India

    A LawGeex benchmark compared AI with 20 experienced lawyers reviewing five NDAs. The AI matched the top lawyer’s accuracy and finished the task in just 26 seconds. The lawyers took an average of 92 minutes combined. This performance gap explains why AI contract review India searches have surged over the past year. That gap is exactly why AI contract review India searches have spiked over the past year.

    If you’re a founder who has waited four days for a vendor agreement to return with redlines, this changes the equation entirely.

    📌 TL;DR: AI contract review tools use natural language processing to scan agreements, flag risky clauses, and check terms against Indian regulations like the Indian Contract Act, 1872 in minutes instead of days. They don’t replace lawyers — they handle the first-pass scan so a human only needs to review what actually matters. Lawizer pairs this speed with real legal sign-off for Indian startups and MSMEs who can’t afford either slow contracts or unreviewed ones.

    What You’ll Learn

    • How AI contract review actually works under the hood
    • Where AI genuinely beats manual review — and where it doesn’t
    • The Indian-specific risks AI tools need to catch (Contract Act, arbitration clauses, sector rules)
    • How founders and MSMEs can use AI review without skipping legal judgment

    How AI Contract Review Actually Works

    AI contract review tools run on natural language processing (NLP — software that reads and interprets human language rather than just matching keywords).

    Upload a contract, and the model breaks it into clauses, compares each one against a playbook of acceptable terms, and flags anything that deviates: a one-sided indemnity clause, a missing termination notice period, an arbitration seat that favours the other party.

    Here’s the thing. A Legal On industry survey found that legal teams spend roughly three hours reviewing a single contract. A team handling 500 contracts a year spends about 188 working days on contract review alone. AI significantly reduces the time needed for the first review pass. Most platforms report a 70–85% cut in review time per contract. The tool isn’t replacing legal judgment — it’s clearing the repetitive scanning so a lawyer spends time on the clauses that actually need a human call.

    Why It’s Faster Than a Lawyer Reading Line by Line

    A lawyer reads sequentially and gets fatigued after the tenth NDA of the day. AI doesn’t tire, doesn’t skim, and applies the exact same standard to contract one and contract one hundred. That consistency is what closes the speed gap — not magic, just no fatigue curve.

    Where AI Genuinely Outperforms Manual Review

    The numbers aren’t marketing fluff. In the LawGeex study, AI matched the best-performing lawyer’s accuracy on NDA risk-spotting, while the lawyers’ average accuracy sat around 85% with the lowest at 67%. Separately, Virtasant reported an AI contract tool hitting 94% accuracy against a 85% average for human reviewers on a similar task.

    • Consistency across hundreds of contracts — no variation in standards between reviewers
    • Speed on routine, high-volume agreements: vendor contracts, NDAs, freelance agreements
    • Cross-referencing clauses against past contracts instantly, instead of manually digging through old files

    What most founders miss: speed gains compound. A faster first pass means sales contracts close quicker, vendor onboarding doesn’t stall procurement, and employment offers don’t sit in legal limbo while a candidate is deciding between you and a competitor.

    The India-Specific Risks Generic AI Tools Miss

    This is where most off-the-shelf AI tools — built for US or EU contract law — fall short for Indian businesses. Every Indian contract still has to survive the Indian Contract Act, 1872, which sets out what makes an agreement enforceable in the first place: free consent, lawful consideration, and a lawful object under Section 10.

    A quick example: Section 27 of the Act voids most non-compete clauses once an employee or founder exits — yet generic AI templates routinely insert broad post-exit non-competes that simply won’t hold up in an Indian court. A founder relying on a US-trained tool could ship a contract that looks airtight and is legally toothless. AI tools built for the Indian market also need to check terms against sector regulators — RBI for fintech, SEBI for listed entities, TRAI for telecom — and against the tax and compliance obligations a growing business is already juggling

    What Most Founders Get Wrong About Vendor Contracts

    The short answer: they sign the vendor’s template as-is. Most commercial disputes in India don’t come from bad intent — they come from unclear payment terms, vague deliverables, or a missing dispute resolution clause. An arbitration clause that names the wrong seat, or skips the Arbitration and Conciliation Act, 1996 entirely, turns a small disagreement into a multi-year court fight.

    Where You Still Need a Human Lawyer

    AI is strong at pattern recognition — spotting a missing clause, an unusual indemnity cap, an inconsistent definition. It’s weaker at reading commercial intent: why a term sheet investor wants a particular liquidation preference, or how a negotiation history should shape this specific redline. Let’s break this down further — AI flags the anomaly; a lawyer decides whether the anomaly is actually a problem for your specific deal.

    That’s also why founder agreements, shareholder agreements, and company incorporation documents still warrant a human review pass, even with AI doing the first scan. The stakes — equity splits, IP ownership, exit terms — are too high to leave entirely to pattern-matching.

    How to Use AI Contract Review Without Cutting Corners

    Start with your highest-volume, lowest-complexity contracts — NDAs, standard vendor agreements, freelance contracts. These are repetitive enough that AI’s consistency advantage matters most, and low-stakes enough that an occasional miss won’t sink the business. Once that workflow is stable, expand to more complex agreements with mandatory human sign-off built in.

    • Build a clause playbook first — AI needs a defined standard to flag deviations against
    • Always route flagged risks and high-value contracts to a qualified lawyer for final sign-off
    • Keep an unedited original alongside the AI-annotated version for audit purposes
    • Check that the tool is updated for Indian-specific law — the Contract Act, DPDPA, and sector regulations don’t sit still

    For MSMEs juggling vendor agreements alongside Udyam/MSME registration and a growing list of compliance deadlines, this hybrid approach — AI for speed, a lawyer for the calls that matter — is usually the realistic middle ground, not full automation and not full manual review either.

    Frequently Asked Questions

    Q: Can AI replace a lawyer for contract review in India?

    A: No. AI handles the first-pass scan — flagging missing clauses, inconsistent terms, and known risk patterns — but a qualified lawyer should still review high-stakes agreements like shareholder agreements, founder agreements, and complex commercial contracts. Most legaltech platforms in India position AI as an accelerator for lawyers, not a substitute.

    Q:Is an AI-reviewed contract legally valid in India?

    A: Yes — AI tools don’t change a contract’s enforceability. A contract is valid under the Indian Contract Act, 1872 as long as it satisfies Section 10: free consent, lawful consideration, competent parties, and a lawful object, regardless of whether AI or a human drafted or reviewed it.

    Q:How accurate is AI at spotting risky clauses?

    A: In a widely cited LawGeex benchmark, an AI tool matched the accuracy of the top-performing lawyer in a group of 20 experienced reviewers, while the lawyers’ average accuracy was lower. Accuracy still depends heavily on whether the tool is trained on Indian contract law and kept updated as regulations change.

    Q:What kinds of contracts should I start with for AI review?

    A: Start with high-volume, lower-complexity agreements — NDAs, standard vendor contracts, and freelance agreements. These benefit most from AI’s speed and consistency, while complex agreements like shareholder or founder agreements should still go through full legal review.

    Q:Do AI contract tools check for Indian regulatory compliance?

    A: Only if the tool is built or configured for the Indian market. Generic global tools often miss India-specific issues like Section 27 non-compete restrictions, RBI or SEBI sector rules, or DPDPA data protection requirements, so it’s worth confirming Indian-specific training before relying on the output.

    Ready to get your contracts reviewed properly?
    Lawizer’s experts handle vendor agreement review, founder agreement drafting, and trademark filings — fully online, starting at just ₹999. No CA visit needed.

    Get your contract reviewed today →

  • Why Company Name Gets Rejected by MCA — And How to Fix It

    Why Company Name Gets Rejected by MCA — And How to Fix It

    The MCA sends back roughly one in three company name applications filed through its portal on the first attempt. If the MCA rejected your company name, you are not alone—you likely ran into one of the common, predictable mistakes that founders make every day.

    The good news? Every single rejection reason is fixable in five minutes once you know what the Central Registration Centre (CRC) is actually checking for.

    📌 TL;DR: A company name gets rejected by MCA mainly for four reasons — it’s too similar to an existing company, LLP, or trademark; it uses a restricted word like Bank or India without approval; it’s too generic to have any distinct identity; or it doesn’t match the business activity stated in the application. Run a name search on the MCA and trademark portals before filing, and most rejections are entirely avoidable. Lawizer’s incorporation team checks all three layers — MCA database, trademark register, and Companies Act compliance — before you ever submit.

    What You’ll Learn

    • The exact rules MCA uses to approve or reject a name (Rule 8 and Rule 8A)
    • The five most common rejection triggers, with real examples
    • How to pick a name that survives the SPICe+ Part A or RUN check on the first try

    How MCA Actually Decides — Rule 8 and Rule 8A

    When you submit a company name through SPICe+ (Simplified Proforma for Incorporating Company Electronically Plus — MCA’s online incorporation form) or RUN (Reserve Unique Name — the standalone name reservation service), the Ministry of Corporate Affairs (MCA) screens it against the Companies (Incorporation) Rules, 2014. Specifically, Rule 8 and Rule 8A of the MCA framework lay out what makes a name “undesirable.”

    Here’s the thing: this isn’t a human reviewer making a judgment call on vibes. It’s a rules-based check against three databases — existing companies, existing LLPs, and the trademark register — plus a list of restricted words. If your name trips any one of these, it gets flagged for resubmission or outright rejection.

    Reason 1: Your Name Is Too Similar to an Existing One

    This is the single biggest reason names bounce back. MCA doesn’t just block identical names — it blocks names that “too nearly resemble” an existing company, LLP, or registered trademark. That includes phonetic similarity. If “TechVista Private Limited” already exists, “TekVista” or “TechVysta” will likely be rejected even though the spelling is different.

    What most founders miss: changing the prefix isn’t enough if the core distinctive word is identical. “New TechVista” or “TechVista India” still carries a high rejection risk because the dominant, memorable part of the name hasn’t actually changed.

    • Search the exact name on MCA’s Company/LLP Master Data tool
    • Search variations and phonetic near-matches, not just the exact spelling
    • Cross-check the same name against the trademark register, since a clean MCA search doesn’t mean a clean trademark search

    Reason 2: You Used a Restricted or Regulated Word

    Certain words trigger an automatic flag unless you have prior regulatory approval attached to your application. Government-sounding words — National, Central, Union, Federal, President, Parliament — imply state patronage and get rejected outright.

    Regulated-sector words — Bank, Insurance, Mutual Fund, Stock Exchange, Securities — need a no-objection from RBI, IRDAI, or SEBI before MCA will even look at the name.

    A quick example: scale-implying words also have capital thresholds attached. Words like International, Continental, or Hindustan require at least ₹1 crore in authorised capital, while India, Indian, or Corporation need a minimum of ₹5 lakh. Use these words without meeting the threshold, and rejection is close to guaranteed.

    Reason 3: The Name Is Too Generic

    The short answer: if your name doesn’t have a distinctive word, MCA will reject it for lacking identity. “Super Enterprises Private Limited” or “Best Business Private Limited” tell the registrar nothing about who you are — they’re generic enough to apply to thousands of companies, which is exactly the problem.

    Words like Industry, Udyog, Enterprises, Products, or Manufacturing are only allowed when your business genuinely spans multiple activities. A single-product company using “Manufacturing” in its name without a broad object clause is an easy rejection.

    A simple fix

    Add a brand-specific, invented, or coined word as your prefix — something that wouldn’t show up in a dictionary search. It’s the fastest way to clear the “distinctive identity” bar.

    Reason 4: Your Name Doesn’t Match Your Business Activity

    Let’s break this down: when you file SPICe+ Part A, you also declare your main business objects. If the name and the objects contradict each other, the CRC flags it. A company named “ABC Manufacturing Private Limited” that lists business consultancy as its main activity is a textbook example — the object word “Manufacturing” misleads anyone reading the name.

    This trips up a lot of first-time founders registering a private limited company who pick an aspirational name before finalising what the company actually does. Lock in your business objects first, then build the name around them.

    Reason 5: You Skipped the Trademark Check

    What most founders miss: a name can be completely free on the MCA database and still get rejected because it’s registered as a trademark in a relevant class. The CRC cross-checks proposed names against the trademark register maintained by CGPDTM (Controller General of Patents, Designs and Trademarks)

    If you genuinely want to use a name that’s trademarked by someone else, you’ll need the trademark owner’s consent — typically a board resolution and KYC documents if the owner is a company. Without that, don’t bother filing; it’s an automatic rejection. Before you commit to a brand name, it’s worth running it through a proper trademark registration search alongside your MCA check.

    What Happens After a Rejection

    If both names in your SPICe+ Part A application get rejected, you typically get one free resubmission opportunity with corrected names — no extra fee, as long as you resubmit within the allowed window. If the second attempt also fails, you’ll need to file a fresh application with new fees.

    Under RUN, the process is similar but slightly more forgiving on resubmission. Either way, the CRC’s rejection remarks tell you exactly which rule you broke — read them carefully instead of guessing at a new name.

    Frequently Asked Questions

    Q: Why did MCA reject my company name even though it wasn’t identical to any existing company?

    A: MCA rejects names that are phonetically similar, not just identical ones. If your proposed name sounds like an existing company or LLP name when spoken aloud, the CRC treats it as too close and rejects it under Rule 8.

    Q: How many times can I resubmit a rejected company name?

    A: You generally get one free resubmission after an initial rejection in SPICe+ Part A. If the resubmitted names are also rejected, you’ll need to file a completely new application with fresh fees.

    Q: Can I use the word “India” or “Bharat” in my company name?

    A: Yes, but only if your authorised capital meets the minimum threshold, generally ₹5 lakh for words like India or Indian, and only if the scale of your business genuinely justifies it. MCA rejects these words for small-scale companies that don’t meet the threshold.

    Q: Does a clean MCA name search guarantee approval?

    A: No. A name can be completely unused on the MCA database and still get rejected if it matches a registered trademark in a relevant class. You need to check both the MCA database and the trademark register before filing.

    Ready to register your company without the name-rejection headache?
    Lawizer’s experts handle everything — MCA name search, SPICe+ filing, and full incorporation — fully online, starting at just ₹1,499 + Govt. Fee. No CA visit needed.

    Start Your Company Registration →

  • The Founder’s Guide to Vesting Schedules: Protecting Your Equity the Right Way

    The Founder’s Guide to Vesting Schedules: Protecting Your Equity the Right Way

    📌 TL;DR: A founder vesting schedule in India means promoters earn their shares over time — typically 4 years with a 1-year cliff — instead of receiving 100% ownership on day one. It protects the company from “dead equity” if a co-founder exits early, signals discipline to investors, and is enforced through a shareholders’ agreement rather than directly under the Companies Act, 2013. Lawizer drafts founders’ agreements with vesting built in from incorporation, not retrofitted after a dispute.

    What You’ll Learn

    • What founder vesting actually means and why it differs from employee ESOP vesting
    • The standard 4-year, 1-year cliff structure Indian investors expect to see
    • How reverse vesting works for founders who already hold shares
    • Which clauses your founders’ agreement or SHA must include
    • What happens to unvested equity when a co-founder leaves

    What Is a Founder Vesting Schedule?

    A vesting schedule is the timeline over which a founder “earns” full legal ownership of the shares allotted to them, rather than owning everything outright the moment the company incorporates. Here’s the key point: once a company allots shares under the Companies Act, 2013, the shareholder becomes their legal owner.

    Vesting does not change ownership directly. Instead, it operates through a contractual mechanism in the founders’ agreement or Shareholders’ Agreement (SHA). This provision requires a departing founder to sell back any unvested shares.

    The term “reverse vesting” refers to an arrangement where the founder already holds the shares and must transfer the unearned portion back if they exit early. Unlike an employee, who earns options that vest over time, the founder starts with the shares and gives back the unearned portion if they leave before the vesting period ends.

    Many founders believe vesting only benefits investors. In reality, it also protects co-founders from day one. It safeguards both the founders and the company’s cap table. A four-year vesting period with a one-year cliff is now the standard in India and globally. A cliff is the initial period during which no equity vests.

    Why Indian Founders Can’t Afford to Skip It

    What’s the real cost of skipping vesting? Picture an equal three-way split with no agreement. One founder leaves after eight months. The remaining two now need that person’s consent for almost every shareholder-level decision — share issuance, a new funding round, even routine governance — because they still legally hold their full stake.

    This isn’t a rare scenario. Disputes over undocumented equity promises and dormant cap table entries are among the most common founder-side legal issues Indian startups bring to law firms once a funding round is in motion. A co-founder who went passive — moved abroad, became inactive, or simply stopped contributing — can still hold pre-emptive and anti-dilution rights that block a Series A from closing on time.

    The short answer: A founder vesting schedule turns a potential equity dispute into a pre-agreed contractual outcome. Without it, founders often face legal disputes later. These cases may end up before the National Company Law Tribunal (NCLT) under Sections 241–242 of the Companies Act, 2013.

    The Standard Structure: 4-Year Vesting, 1-Year Cliff

    Let’s break this down. The structure almost every Indian startup and investor expects looks like this:

    • Year 0–1 (the cliff):No shares vest. If a founder leaves before the 12-month mark, they walk away with nothing.
    • End of Year 1: 25% of the founder’s shares vest in one go.
    • Year 1–4: The remaining 75% vests monthly, in equal instalments — roughly 1/36th each month.
    • Year 4 : The founder becomes fully vested and owns their entire allotted stake outright.

    Founders who complete significant pre-incorporation work can negotiate vesting credit, allowing them to start partially vested on day one instead of beginning at zero. This is reasonable when documented, but it should be the exception, agreed in writing, not assumed.

    Acceleration Clauses Worth Knowing

    Acceleration speeds up vesting if a specific event occurs, usually an acquisition. Double-trigger acceleration offers a more balanced approach because it requires both an acquisition and a termination without cause before equity accelerates. This structure prevents founders from cashing out immediately after a deal closes and walking away, while still protecting them if the new owner later terminates them without cause.

    Drafting It Right: What Your Founders’ Agreement Must Cover

    A vesting clause that’s vague is almost as risky as having none. A quick example: an agreement that says shares vest “over time” without defining the cliff, the monthly schedule, or what counts as a “good leaver” versus a “bad leaver” leaves every term open to dispute later.

    At minimum, your founders’ agreement or SHA should define:

    • Exact vesting schedule: cliff length, total vesting period, and vesting frequency (monthly is most common).
    • Good Leaver vs. Bad Leaver: The company repurchases unvested shares at fair value when a founder qualifies as a good leaver (for example, due to resignation, health reasons, or mutual agreement). However, the company repurchases those shares at face value or nil value when a founder becomes a bad leaver because of termination for cause or a breach of the agreement.
    • Valuation mechanism for buyback: who values the unvested shares, and by when. Without this, parties default to Rule 11UA of the Income Tax Rules, 1962 — a method built for tax compliance, not equitable founder buyouts.
    • IP assignment: a separate but related clause ensuring all IP built by founders, including pre-incorporation work, sits with the company, not the individual.
    • Deadlock resolution: what happens if co-founders can’t agree on a reserved matter, including a forced transfer trigger for serious breaches.

    Getting these clauses drafted correctly at incorporation is far cheaper than fixing them later. Lawizer’s company incorporation services include founders’ agreement drafting with vesting built in from day one, so you’re not retrofitting protection after a co-founder relationship has already gone sideways.

    Founder Vesting vs ESOP Vesting: Don’t Confuse the Two

    Here’s a distinction that trips up a lot of founders. Section 62(1)(b) of the Companies Act, 2013, along with Rule 12 of the Companies (Share Capital and Debentures) Rules, 2014, governs Employee Stock Option Plans (ESOPs) in India.

    Rule 12 generally prohibits promoters and directors holding more than 10% equity from receiving ESOPs. However, companies recognised as startups under the Startup India initiative by DPIIT can grant ESOPs to these individuals, as the exemption remains available for up to 10 years from the date of incorporation.

    In contrast, founder vesting does not operate under an ESOP scheme. Instead, founders receive their shares through a separate ownership arrangement. It’s a contractual obligation in the founders’ agreement or SHA that applies to shares already allotted to promoters at incorporation. The two mechanisms achieve a similar goal — earning equity over time — but they sit in completely different legal frameworks, and confusing them in your documentation is a common drafting mistake.

    If you’re also setting up an employee option pool alongside founder vesting, make sure your MSME and compliance registrations are in place first — investors will check both during diligence.

    What Happens When a Co-Founder Leaves Early

    A quick example to make this concrete: a founder holding 30% equity leaves at the end of Year 2, with a standard 4-year/1-year-cliff schedule in place. They’ve vested 25% (the cliff) plus 12 months of monthly vesting — roughly 50% of their total grant.

    The other 50% reverts to the company, typically at face value or nil consideration as specified in the buyback clause, and can be reallocated to a replacement co-founder, added to the ESOP pool, or held by the company.

    What most founders miss: if the agreement is silent on the buyback price for unvested shares, the default valuation route is Rule 11UA — net asset value or discounted cash flow — which was designed for income tax compliance, not for a fair founder exit. Specifying the valuation method and timeline in writing at the start avoids a costly negotiation later.

    When Should You Set Up Vesting?

    The short answer: at incorporation, before any institutional money comes in. Investors increasingly check for a vesting schedule and a documented founders’ agreement during diligence, and discovering its absence mid-term-sheet negotiation is a red flag that can delay or derail a round.

    If you’ve already incorporated without one, it’s not too late — but it does require every co-founder to agree to retroactively place their existing shares under a vesting arrangement, which is a harder conversation than setting it up on day one. Either way, this sits alongside your other founder-stage filings, including your company’s annual income tax return filing and trademark protection for your brand.

    Frequently Asked Questions

    Q: Is founder vesting legally required in India?

    A: No, the Companies Act, 2013 does not mandate founder vesting. It’s a contractual protection built into your founders’ agreement or SHA, not a statutory requirement. However, most institutional investors will insist on it before closing a funding round.

    Q: What’s the difference between vesting and reverse vesting?

    A: Vesting typically refers to options or shares granted to employees that they earn over time before receiving them. Reverse vesting applies to founders who already hold their shares; if they leave early, the unvested portion is sold back to the company. Founder agreements almost always use reverse vesting.

    Q: Can founders negotiate a shorter vesting period than 4 years?

    A: Yes. A 2-3 year vesting schedule with a shorter cliff is more founder-friendly and is sometimes accepted by early-stage investors, especially if the founder has already demonstrated significant traction. The 4-year, 1-year-cliff structure remains the default investors expect, so any deviation should be clearly justified and documented.

    Q: What happens to unvested shares if a co-founder is asked to leave for cause?

    A: This depends entirely on your “bad leaver” clause. Most agreements specify that unvested shares are forfeited at nil or face value in a for-cause termination, while vested shares may still be repurchased at fair value or retained, depending on the agreement’s terms. Without this clause defined in writing, the company has no automatic right to claw back shares.

    Q: Does vesting reset when the startup raises a new funding round?

    A: Generally no — founder equity is diluted as new shares are issued, but the original vesting timeline continues unchanged unless all parties specifically negotiate otherwise. Series A investors sometimes ask for renegotiated or restarted vesting as a condition of the round, which founders should review carefully before agreeing.

    Q: Can a solo founder skip vesting entirely?

    A: A solo founder has no co-founder to protect against, but investors will still often require founder vesting before funding, since it protects them against the founder leaving the company early post-investment. It’s worth setting up even for a single-founder startup if outside funding is on the roadmap.

    Ready to protect your founder equity the right way?
    Lawizer’s experts handle everything — founders’ agreement drafting, vesting schedule structuring, and full company incorporation — fully online, starting at just ₹1,499. No CA visit needed.

    Get Your Founders’ Agreement Drafted →

    Three founders. One equal 33% split. No vesting schedule. Eighteen months later, one co-founder stops contributing but still owns one-third of the company. Many founders make the mistake of skipping a founder vesting schedule. At Lawizer, we have seen this happen often. This single document helps prevent future ownership disputes.

    Eighteen months later, one co-founder stops contributing. However, they still own one-third of the company. Many founders make the mistake of skipping a founder vesting schedule.cision you make.

    📌 TL;DR: A founder vesting schedule in India means promoters earn their shares over time — typically 4 years with a 1-year cliff — instead of receiving 100% ownership on day one. It protects the company from “dead equity” if a co-founder exits early, signals discipline to investors, and is enforced through a shareholders’ agreement rather than directly under the Companies Act, 2013. Lawizer drafts founders’ agreements with vesting built in from incorporation, not retrofitted after a dispute.

    What You’ll Learn

    • What founder vesting actually means and why it differs from employee ESOP vesting
    • The standard 4-year, 1-year cliff structure Indian investors expect to see
    • How reverse vesting works for founders who already hold shares
    • Which clauses your founders’ agreement or SHA must include
    • What happens to unvested equity when a co-founder leaves

    What Is a Founder Vesting Schedule?

    A vesting schedule is the timeline over which a founder “earns” full legal ownership of the shares allotted to them, rather than owning everything outright the moment the company incorporates. Here’s the key point: once a company allots shares under the Companies Act, 2013, the shareholder becomes their legal owner.

    Vesting does not change ownership directly. Instead, it operates through a contractual mechanism in the founders’ agreement or Shareholders’ Agreement (SHA). This provision requires a departing founder to sell back any unvested shares.

    The term “reverse vesting” refers to an arrangement where the founder already holds the shares and must transfer the unearned portion back if they exit early. Unlike an employee, who earns options that vest over time, the founder starts with the shares and gives back the unearned portion if they leave before the vesting period ends.

    Many founders believe vesting only benefits investors. In reality, it also protects co-founders from day one. It safeguards both the founders and the company’s cap table. A four-year vesting period with a one-year cliff is now the standard in India and globally. A cliff is the initial period during which no equity vests.

    Why Indian Founders Can’t Afford to Skip It

    What’s the real cost of skipping vesting? Picture an equal three-way split with no agreement. One founder leaves after eight months. The remaining two now need that person’s consent for almost every shareholder-level decision — share issuance, a new funding round, even routine governance — because they still legally hold their full stake.

    This isn’t a rare scenario. Disputes over undocumented equity promises and dormant cap table entries are among the most common founder-side legal issues Indian startups bring to law firms once a funding round is in motion. A co-founder who went passive — moved abroad, became inactive, or simply stopped contributing — can still hold pre-emptive and anti-dilution rights that block a Series A from closing on time.

    The short answer: A founder vesting schedule turns a potential equity dispute into a pre-agreed contractual outcome. Without it, founders often face legal disputes later. These cases may end up before the National Company Law Tribunal (NCLT) under Sections 241–242 of the Companies Act, 2013.

    The Standard Structure: 4-Year Vesting, 1-Year Cliff

    Let’s break this down. The structure almost every Indian startup and investor expects looks like this:

    • Year 0–1 (the cliff):No shares vest. If a founder leaves before the 12-month mark, they walk away with nothing.
    • End of Year 1: 25% of the founder’s shares vest in one go.
    • Year 1–4: The remaining 75% vests monthly, in equal instalments — roughly 1/36th each month.
    • Year 4 : The founder becomes fully vested and owns their entire allotted stake outright.

    Founders who complete significant pre-incorporation work can negotiate vesting credit, allowing them to start partially vested on day one instead of beginning at zero. This is reasonable when documented, but it should be the exception, agreed in writing, not assumed.

    Acceleration Clauses Worth Knowing

    Acceleration speeds up vesting if a specific event occurs, usually an acquisition. Double-trigger acceleration offers a more balanced approach because it requires both an acquisition and a termination without cause before equity accelerates. This structure prevents founders from cashing out immediately after a deal closes and walking away, while still protecting them if the new owner later terminates them without cause.

    Drafting It Right: What Your Founders’ Agreement Must Cover

    A vesting clause that’s vague is almost as risky as having none. A quick example: an agreement that says shares vest “over time” without defining the cliff, the monthly schedule, or what counts as a “good leaver” versus a “bad leaver” leaves every term open to dispute later.

    At minimum, your founders’ agreement or SHA should define:

    • Exact vesting schedule: cliff length, total vesting period, and vesting frequency (monthly is most common).
    • Good Leaver vs. Bad Leaver: The company repurchases unvested shares at fair value when a founder qualifies as a good leaver (for example, due to resignation, health reasons, or mutual agreement). However, the company repurchases those shares at face value or nil value when a founder becomes a bad leaver because of termination for cause or a breach of the agreement.
    • Valuation mechanism for buyback: who values the unvested shares, and by when. Without this, parties default to Rule 11UA of the Income Tax Rules, 1962 — a method built for tax compliance, not equitable founder buyouts.
    • IP assignment: a separate but related clause ensuring all IP built by founders, including pre-incorporation work, sits with the company, not the individual.
    • Deadlock resolution: what happens if co-founders can’t agree on a reserved matter, including a forced transfer trigger for serious breaches.

    Getting these clauses drafted correctly at incorporation is far cheaper than fixing them later. Lawizer’s company incorporation services include founders’ agreement drafting with vesting built in from day one, so you’re not retrofitting protection after a co-founder relationship has already gone sideways.

    Founder Vesting vs ESOP Vesting: Don’t Confuse the Two

    Here’s a distinction that trips up a lot of founders. Section 62(1)(b) of the Companies Act, 2013, along with Rule 12 of the Companies (Share Capital and Debentures) Rules, 2014, governs Employee Stock Option Plans (ESOPs) in India.

    Rule 12 generally prohibits promoters and directors holding more than 10% equity from receiving ESOPs. However, companies recognised as startups under the Startup India initiative by DPIIT can grant ESOPs to these individuals, as the exemption remains available for up to 10 years from the date of incorporation.

    In contrast, founder vesting does not operate under an ESOP scheme. Instead, founders receive their shares through a separate ownership arrangement. It’s a contractual obligation in the founders’ agreement or SHA that applies to shares already allotted to promoters at incorporation. The two mechanisms achieve a similar goal — earning equity over time — but they sit in completely different legal frameworks, and confusing them in your documentation is a common drafting mistake.

    If you’re also setting up an employee option pool alongside founder vesting, make sure your MSME and compliance registrations are in place first — investors will check both during diligence.

    What Happens When a Co-Founder Leaves Early

    A quick example to make this concrete: a founder holding 30% equity leaves at the end of Year 2, with a standard 4-year/1-year-cliff schedule in place. They’ve vested 25% (the cliff) plus 12 months of monthly vesting — roughly 50% of their total grant.

    The other 50% reverts to the company, typically at face value or nil consideration as specified in the buyback clause, and can be reallocated to a replacement co-founder, added to the ESOP pool, or held by the company.

    What most founders miss: if the agreement is silent on the buyback price for unvested shares, the default valuation route is Rule 11UA — net asset value or discounted cash flow — which was designed for income tax compliance, not for a fair founder exit. Specifying the valuation method and timeline in writing at the start avoids a costly negotiation later.

    When Should You Set Up Vesting?

    The short answer: at incorporation, before any institutional money comes in. Investors increasingly check for a vesting schedule and a documented founders’ agreement during diligence, and discovering its absence mid-term-sheet negotiation is a red flag that can delay or derail a round.

    If you’ve already incorporated without one, it’s not too late — but it does require every co-founder to agree to retroactively place their existing shares under a vesting arrangement, which is a harder conversation than setting it up on day one. Either way, this sits alongside your other founder-stage filings, including your company’s annual income tax return filing and trademark protection for your brand.

    Frequently Asked Questions

    Q: Is founder vesting legally required in India?

    A: No, the Companies Act, 2013 does not mandate founder vesting. It’s a contractual protection built into your founders’ agreement or SHA, not a statutory requirement. However, most institutional investors will insist on it before closing a funding round.

    Q: What’s the difference between vesting and reverse vesting?

    A: Vesting typically refers to options or shares granted to employees that they earn over time before receiving them. Reverse vesting applies to founders who already hold their shares; if they leave early, the unvested portion is sold back to the company. Founder agreements almost always use reverse vesting.

    Q: Can founders negotiate a shorter vesting period than 4 years?

    A: Yes. A 2-3 year vesting schedule with a shorter cliff is more founder-friendly and is sometimes accepted by early-stage investors, especially if the founder has already demonstrated significant traction. The 4-year, 1-year-cliff structure remains the default investors expect, so any deviation should be clearly justified and documented.

    Q: What happens to unvested shares if a co-founder is asked to leave for cause?

    A: This depends entirely on your “bad leaver” clause. Most agreements specify that unvested shares are forfeited at nil or face value in a for-cause termination, while vested shares may still be repurchased at fair value or retained, depending on the agreement’s terms. Without this clause defined in writing, the company has no automatic right to claw back shares.

    Q: Does vesting reset when the startup raises a new funding round?

    A: Generally no — founder equity is diluted as new shares are issued, but the original vesting timeline continues unchanged unless all parties specifically negotiate otherwise. Series A investors sometimes ask for renegotiated or restarted vesting as a condition of the round, which founders should review carefully before agreeing.

    Q: Can a solo founder skip vesting entirely?

    A: A solo founder has no co-founder to protect against, but investors will still often require founder vesting before funding, since it protects them against the founder leaving the company early post-investment. It’s worth setting up even for a single-founder startup if outside funding is on the roadmap.

    Ready to protect your founder equity the right way?
    Lawizer’s experts handle everything — founders’ agreement drafting, vesting schedule structuring, and full company incorporation — fully online, starting at just ₹1,499. No CA visit needed.

    Get Your Founders’ Agreement Drafted →

  • Shareholders’ Agreement for Startups: 8 Clauses You Cannot Afford to Skip

    Shareholders’ Agreement for Startups: 8 Clauses You Cannot Afford to Skip

    India now has over 1.64 lakh DPIIT-recognised startups — yet most founders spend more time debating their pitch deck font than reading the one document that decides who controls their company when things go wrong. A shareholders’ agreement (SHA) is that document. And a poorly drafted one has ended more promising Indian startups than bad markets ever have.

    Eight clauses. Get them right, and your startup has a rulebook that works for you at every stage — from first hire to first exit

    📌 TL;DR: A shareholders’ agreement (SHA) for startups in India is a private, legally binding contract between company shareholders that governs equity, voting rights, exits, and dispute resolution — separate from the publicly filed Articles of Association (AoA). The 8 non-negotiable SHA clauses include vesting schedules, anti-dilution protection, ROFR, drag-along and tag-along rights, reserved matters, IP ownership, non-compete, and dispute resolution. Lawizer’s legal experts can draft a founder-ready SHA fully online, without a single CA visit.

    ↓

    What You’ll Learn

    • What a shareholders’ agreement is and why it’s different from your AoA
    • The 8 clauses every Indian startup SHA must include — and what each one actually protects
    • Common mistakes Indian founders make and how courts in India have ruled on SHA disputes
    • What to do before your next funding round to make sure your SHA holds up legally

    What Is a Shareholders’ Agreement — and Why It’s Not the Same as Your AoA

    A Shareholders’ Agreement (SHA) is a private, confidential contract between the shareholders of a company. It’s governed by the Indian Contract Act, 1872, and typically signed after the company is incorporated under the Companies Act, 2013.

    Unlike the Articles of Association (AoA) — which is a public document filed with the Registrar of Companies — the SHA stays between the parties. Nobody outside your shareholder group needs to see it.

    Here’s the thing: the AoA and SHA often overlap, and that overlap can get you into trouble. The Supreme Court of India ruled in V.B. Rangaraj v. V.B. Gopalakrishnan that SHA clauses are only enforceable against the company if they’re also reflected in the AoA.

    In other words, a beautifully drafted SHA that contradicts or isn’t backed up by your AoA can be legally worthless when you need it most. Always ensure both documents are harmonised — this is step one before any investor signs.

    What most founders miss: the SHA isn’t just an investor protection tool. It’s the founders’ rulebook too. It decides how equity is split, who can vote on what, what happens when a co-founder wants to leave, and who gets paid first when the company exits. Skipping it — or copying a template from the internet — is how co-founder disputes become courtroom dramas.

    Clause 1 & 2: Vesting Schedule and Anti-Dilution Protection

    These two clauses do the heavy lifting in every early-stage SHA, and they’re almost always the ones founders regret skipping.

    1)Vesting Schedule

    A vesting schedule is a timeline over which a founder or employee earns their equity. The standard in India’s startup ecosystem is a 4-year vesting period with a 1-year cliff — meaning no equity is earned in the first year, and after that, shares vest monthly or quarterly. If a co-founder leaves in month eight, they walk away with nothing. Without a vesting clause? They keep 100% of their shares and potentially block your next funding round.

    A quick example: two Bengaluru-based SaaS founders split equity 50-50 on Day 1 with no vesting. Six months later, one leaves for a corporate job. The remaining founder has to raise a Series A with a co-founder who’s no longer involved holding half the company. Most investors in India will simply walk away from that table. Vesting prevents this scenario entirely.

    2)Anti-Dilution Protection

    Anti-dilution clauses protect early investors (and sometimes founders) if the company raises a future round at a lower valuation — what’s called a “down round.” There are two main types: full ratchet (the investor’s price resets entirely to the new lower price — aggressive, investor-friendly) and weighted average (a proportionate adjustment based on the amount of new capital raised — fairer for founders). Always negotiate for weighted average. Full ratchet can wipe out a founder’s stake overnight after one bad quarter.

    Clause 3 & 4: Right of First Refusal (ROFR) and Share Transfer Restrictions

    Imagine waking up to discover that your co-founder sold their stake to a competitor. This isn’t a hypothetical — it’s happened to real Indian startups, and it’s exactly what ROFR and share transfer restrictions are designed to prevent. According to Bridge Counsels’ analysis of Indian SHA disputes, share transfer clauses are among the most heavily negotiated provisions in early-stage agreements.

    A Right of First Refusal (ROFR) means that if a shareholder wants to sell their shares, they must first offer them to existing shareholders at the same price being offered by an external buyer. If existing shareholders decline, the seller can go to the third party — but on terms no more favourable than what was offered internally.

    A closely related mechanism, the Right of First Offer (ROFO), flips this slightly: the seller must first approach existing shareholders before even approaching external parties. ROFO is generally more seller-friendly; ROFR is more buyer-friendly. Your SHA should specify which applies, and in what sequence.

    Let’s break this down. Share transfer restrictions serve a second purpose beyond just keeping competitors out: they let you control who becomes a shareholder. New shareholders change the dynamics of board votes, information rights, and exit decisions. Including a clause that requires written consent from existing shareholders (or a defined percentage of them) before any transfer happens is standard practice for any well-structured Indian startup.

    Clause 5 & 6: Drag-Along and Tag-Along Rights

    These two clauses sound similar but protect completely different parties — and both need to be in your SHA

    1)Drag-Along Rights (Investor/Majority Protection)

    A drag-along clause allows majority shareholders (typically investors or founders with large stakes) to force minority shareholders to join in a sale of the company under the same terms. Why does this matter?

    Because if a strategic acquirer wants to buy 100% of your startup, a minority shareholder who refuses to sell can kill the entire deal. Drag-along rights eliminate that veto. They’re standard in Companies Act, 2013-governed private limited companies and are explicitly negotiated in almost every VC-backed Indian startup’s SHA.

    2)Tag-Along Rights (Minority Protection)

    Tag-along rights work in reverse — they protect minority shareholders. If a majority shareholder agrees to sell their stake to a third party, tag-along rights allow minority shareholders to “tag along” and sell their shares on the same terms.

    Without this, a new majority owner could walk in, change the board, and effectively strand early investors or employee shareholders who had no say in the transaction. In Mumbai and Delhi-NCR where PE and VC activity is highest, tag-along clauses are non-negotiable from an investor’s perspective.

    Clause 7: Reserved Matters and Board Governance

    Not every business decision should be made by whoever has the most shares. Reserved matters are a list of decisions that require approval beyond a simple majority — often unanimous consent or a supermajority (say, 75% or more).

    Think of it as a veto list for important decisions. Common reserved matters in Indian startup SHAs include: changes to the AoA, issuing new shares, taking on debt above a specified threshold, acquiring or merging with another company, changing the core business, and winding up the company.

    Board governance clauses go hand in hand with this. Your SHA should clearly specify: how many board seats exist, who appoints them (founders vs. investors), what constitutes a quorum for board meetings, and how decisions are made when there’s a deadlock.

    Speaking of deadlocks — include a deadlock resolution mechanism. “Texas Shoot-Out” (where one party names a price and the other must buy or sell at that price) and “Russian Roulette” provisions are recognised in Indian commercial contracts and give both parties a clean exit from a governance stalemate.

    You can structure your entire startup legal foundation — from incorporation to SHA — online, without ever visiting a CA’s office. Getting the governance structure right from Day 1 saves months of renegotiation later.

    Clause 8: IP Ownership, Non-Compete, and Dispute Resolution

    These three provisions often get lumped into a “miscellaneous” section and under-negotiated. That’s a mistake — especially for tech startups in Bengaluru, Hyderabad, or Chennai where intellectual property (IP) is the company’s primary asset.

    1)IP Ownership

    Every piece of technology, code, brand, design, or process created by founders or employees must be assigned to the company — not remain with the individual. Your SHA should explicitly state this.

    Without a clear IP assignment clause, a departing co-founder could legally claim ownership of the core product they built. If you’re building a tech startup and haven’t yet protected your brand, trademark registration should run parallel to your SHA drafting.

    2)Non-Compete and Non-Solicit

    A non-compete clause restricts departing shareholders from starting or joining a competing business for a defined period (typically 1–2 years after exit). A non-solicit clause prevents them from poaching employees or clients. In a July 2025 ruling — Paul Deepak Rajaratnam & Ors. v. Surgeport Logistics Pvt. Ltd. 

    The Delhi High Court upheld the enforceability of restrictive covenants in SHAs, confirming that interim injunctions can be granted to prevent breaches of non-compete terms under Section 27 of the Indian Contract Act, 1872.

    3)Dispute Resolution

    Litigation in Indian courts is expensive and slow. Almost every well-drafted SHA in India includes an arbitration clause — specifying that disputes will be resolved through private arbitration under the Arbitration and Conciliation Act, 1996, rather than civil court proceedings.

    Specify the seat of arbitration (Mumbai and Delhi are most common), the governing law (Indian law), the number of arbitrators, and the language. This one clause can save years and crores in legal fees if a dispute escalates.

    Frequently Asked Questions

    Q: Is a shareholders’ agreement mandatory for Indian startups?

    A: No, a shareholders’ agreement (SHA) is not mandatory under Indian law. However, it is strongly advisable for any startup with more than one shareholder. Without an SHA, disputes over equity, exits, and governance are governed only by the Articles of Association and the Companies Act, 2013 — which often don’t reflect what founders and investors actually agreed upon verbally or informally.

    Q: What is the difference between an SHA and the Articles of Association in India?

    A: The Articles of Association (AoA) is a public document filed with the Registrar of Companies and governs the company’s internal affairs. The SHA is a private, confidential contract between shareholders that covers rights and obligations in more detail. Under Indian law, any SHA clause that conflicts with the AoA may be unenforceable against the company — which is why lawyers always recommend aligning both documents when drafting an SHA.

    Q: When should a startup sign its shareholders’ agreement?

    A: Ideally, before the first external investment is brought in — or at the time of incorporating the company if there are multiple co-founders. Waiting until the first VC term sheet arrives means you’ll be negotiating SHA terms under time pressure and with far less leverage. The earlier you formalise equity, vesting, and governance, the cleaner your cap table looks to investors.

    Q: Can a shareholders’ agreement override the Companies Act, 2013?

    A: No. An SHA must comply with the Companies Act, 2013, and any provision that contradicts a statutory requirement will be void. For example, the Act sets minimum requirements for holding AGMs, maintaining registers, and filing returns with the MCA — none of these can be contracted away through an SHA. The SHA works within the statutory framework, not around it.

    Q: Does a shareholders’ agreement need to be stamped in India?

    A: Yes. Under applicable stamp laws in India, an SHA must be duly stamped before or at the time of execution to be admissible as evidence in court. Stamp duty rates vary by state — Maharashtra, Karnataka, and Delhi each have different rates. An unstamped or under-stamped SHA can be challenged in legal proceedings, so always stamp it correctly before any party signs.

    Q: What happens if a co-founder leaves without a vesting clause in the SHA?

    A: Without a vesting clause, a departing co-founder retains 100% of their equity regardless of how early they leave. This can make your startup uninvestable — most VC and angel investors in India will not fund a company where a non-contributing ex-founder holds significant equity. Worse, that founder still has shareholder rights, including voting rights and the right to information. A vesting schedule with a cliff period prevents exactly this scenario.

    Ready to protect your startup with a legally sound SHA?
    Lawizer’s experts handle everything — shareholders’ agreement drafting, company incorporation, and trademark registration — fully online, starting at just ₹1,999. No CA visit needed.Get Your Startup Legal Documents Sorted →

  • Legaltech in India: How AI Is Making Compliance Cheaper for Startups:-

    Legaltech in India: How AI Is Making Compliance Cheaper for Startups:-

    A typical Indian private limited company must navigate filings across at least five regulatory authorities — MCA21, GSTN (Goods and Services Tax Network), the Income Tax Department, EPFO, and state-specific labour portals — before it completes its first full financial year.

    Miss a single ROC (Registrar of Companies) filing and the penalty runs at ₹100 per day, uncapped. Miss a GST return and it costs ₹50 per day plus interest. Miss DIR-3 KYC and your DIN (Director Identification Number) gets deactivated on October 1 with a ₹5,000 reinstatement fee.

    Most founders didn’t build their startups to become full-time compliance managers. That’s exactly the gap that legaltech — and increasingly AI — is closing.


    📌 TL;DR: India’s AI-powered legaltech and compliance market is valued at USD 1.8 billion and growing, driven by the sheer complexity of managing GST, MCA, TDS, and ROC filings simultaneously. AI tools now automate document drafting, flag missed deadlines, reconcile GSTR-2B data, and generate board resolutions — cutting compliance time by up to 80% for early-stage startups. Platforms like Lawizer put this capability in founders’ hands without a CA visit, starting at ₹1,499. This is what Indian startup compliance looks like in 2025 and beyond.


    What You’ll Learn

    • What legaltech actually means and why India’s regulatory complexity made it inevitable
    • How AI is automating the five most painful compliance tasks for Indian startups
    • The real cost of compliance for a Pvt Ltd startup — and how technology changes that math
    • Which AI-driven tools are doing what, and where platforms like Lawizer fit
    • What founders should still never fully hand to automation
    • Answers to the most common founder questions about AI and compliance

    What Is Legaltech — and Why Did India Need It So Badly?

    Legaltech (short for legal technology) refers to the use of software, automation, artificial intelligence, and digital workflows to make legal and compliance work faster, cheaper, and less error-prone. It covers everything from document drafting and contract review to e-filing, deadline alerts, and AI-assisted legal research.

    India needed this more urgently than most countries. Here’s why.

    India has over 70 active regulatory bodies. The introduction of GST in 2017 alone created an entirely new compliance universe — GSTR-1, GSTR-3B, GSTR-2B, GSTR-9, the QRMP scheme — layered on top of an already demanding framework of Companies Act, 2013 filings, TDS (Tax Deducted at Source) obligations, EPFO and ESIC requirements, and sector-specific rules for fintech, healthtech, and food businesses.

    Over 60 lakh cases are pending in India’s 25 High Courts, partly because compliance failures generate litigation that clogs a system already under extreme load.

    For an early-stage startup in Bengaluru or Kolkata with 5 employees and a ₹30,000/month compliance budget, keeping up with all of this manually — across spreadsheets, calendar reminders, and email threads with a CA — is both expensive and genuinely risky.

    One missed deadline doesn’t just cost a penalty. It can deactivate a director’s DIN, block the company from filing its annual return, or create a compliance gap that an investor’s due diligence team flags as a red flag two years later during a Series A.

    The India AI-powered legaltech and compliance market is currently valued at USD 1.8 billion, with the legal AI segment specifically projected to reach USD 106.3 million by 2030, growing at a 23% CAGR. Global legaltech funding jumped 44% year-on-year to USD 3.56 billion in the first half of 2025 alone — a signal that capital is catching up with a problem that has existed for decades.


    The 5 Compliance Tasks AI Is Automating for Indian Startups

    1. GST Filing and Reconciliation

    GST compliance is the most time-consuming recurring obligation for most Indian startups. Every month, a GST-registered company must file GSTR-1 (outward supply details), reconcile GSTR-2B (auto-drafted inward supply statement from vendor filings), and file GSTR-3B (summary return with tax payment) — in that order, in that sequence, before the respective deadlines.

    Doing this manually means downloading bank statements, cross-referencing vendor invoices, hunting for mismatches, and then logging into the GSTN portal to enter data that your accounting software already has. AI systems now handle all of this.

    Smart OCR (Optical Character Recognition) reads invoices and bank statements, extracting vendor names, amounts, and tax rates automatically. Machine learning models classify transactions, suggest GST codes, and flag GSTR-2B mismatches before the filing date — not after. Startups using AI compliance agents report saving up to 80% of their monthly GST compliance time.

    The downstream impact matters as much as the time saving. A mismatch between GSTR-1 and GSTR-3B doesn’t just invite scrutiny — it can block Input Tax Credit (ITC), effectively making a startup pay GST twice on the same transaction. AI catches this proactively.

    2. MCA and ROC Annual Filings

    Every private limited company must file its Annual Return (MGT-7 or MGT-7A for small companies and OPCs), financial statements (AOC-4), and director KYC (DIR-3) with the Ministry of Corporate Affairs through the MCA21 V3 portal every year. Missing any of these creates compounding penalties and, in cases of three consecutive years of default, can lead to director disqualification under the Companies Act, 2013.

    AI-powered compliance platforms now integrate directly with the MCA21 portal, pulling existing company data, auto-populating forms, and maintaining a live compliance calendar that flags deadlines 30–60 days in advance. They draft board resolutions, notices of meetings, and directors’ reports from templates that are updated in real time as MCA circulars and Companies Act amendments are notified.

    The result: a task that previously required a CS (Company Secretary) to spend 2–3 days on preparation now takes a fraction of that time, with the professional’s role shifting from data entry to review and certification.

    3. TDS Calculations and Quarterly Returns

    TDS (Tax Deducted at Source) is one of the most penalty-prone compliance areas for Indian startups. Every payment above a threshold — salaries, contractor fees, rent, professional charges — requires the company to deduct tax at source, deposit it with the Income Tax Department by the 7th of the following month, and file quarterly TDS returns (Form 24Q for salaries, 26Q for non-salary payments).

    A failure to deduct TDS attracts interest at 1% per month from the date of deduction. A failure to deposit it attracts 1.5% per month. These aren’t one-time penalties — they compound.

    AI systems connected to payroll and accounting software (Tally, Zoho Books, Razorpay Payroll) now calculate TDS automatically on every transaction type, flag edge cases where the applicable rate is ambiguous, and schedule deposits well before the 7th of each month. Quarterly return generation — previously a 3–4 day exercise involving pulling payment records, matching PAN numbers against challan details, and reconciling 26AS — is compressed into hours.

    4. Contract Drafting and Document Automation

    Generative AI (GenAI) has created the most visible transformation in this category. Indian legaltech startups like SpotDraft and Leegality now use AI to draft initial versions of employment agreements, vendor contracts, NDAs (Non-Disclosure Agreements), shareholders’ agreements, and founders’ agreements — drawing from templates aligned with Indian Contract Act, 1872 provisions and updated case law.

    What most founders miss: the value isn’t just in drafting speed. It’s in the consistency and completeness of the output. A manually drafted NDA by a busy founder often omits governing law clauses, is silent on jurisdiction, or uses a non-compete that Indian courts will not enforce.

    An AI-generated draft from a trained model surfaces these gaps before they become problems. Generative AI for legal drafting is now one of the fastest-growing sub-segments of India’s legaltech market.

    This is also exactly where platforms like Lawizer operate — providing legally sound startup documentation and compliance services to founders across India, entirely online, without the friction of scheduling CA appointments or paying per-document legal fees.

    5. Compliance Monitoring and Deadline Alerts

    This is the least glamorous category and the most practically impactful one for early-stage startups. The single biggest source of preventable compliance cost for Indian startups is missing a deadline they knew about but didn’t track systematically.

    AI-driven compliance dashboards now give founders a single pane of glass across MCA, GSTN, Income Tax, and state labour portals — showing upcoming deadlines, filing status, and outstanding requirements in one place. Unlike a spreadsheet or a CA’s WhatsApp message, these dashboards update automatically as regulatory changes are notified.

    When MCA extended the DIR-3 KYC deadline for FY 2024-25 to October 31, platforms with live regulatory monitoring updated their alerts within hours. A founder relying on a manually maintained calendar — or on a CA who missed the circular — was still preparing for the old September 30 date.


    The Real Cost of Compliance — and How AI Changes the Math

    Let’s put numbers to this. A realistic annual compliance bill for a pre-revenue or early-stage Pvt Ltd startup in India looks like this:

    A basic annual compliance package — covering accounting, GST filings, TDS returns, income tax return, ROC filing, statutory audit, and advisory — typically costs between ₹30,000 and ₹60,000 for pre-revenue startups and ₹60,000 to ₹1,20,000 for those with turnover up to ₹50 lakh.

    This is the base. Add event-based filings (change of director costs ₹3,000–₹8,000 at a CA firm), DSC maintenance (₹800–₹1,500 per director annually), and the occasional compliance health check before a fundraising round (₹10,000–₹30,000), and the number climbs.

    None of that includes penalties from missed filings, which compound silently. An uncapped ₹100/day ROC penalty across 6 missed months is ₹18,000. A deactivated DIN costs ₹5,000 to reactivate, plus every MCA filing that director needed to sign during the deactivation window gets blocked. These are not edge cases — they are routine outcomes for startups that manage compliance reactively.

    Here’s the thing. Legaltech doesn’t eliminate the need for a CA or CS. Indian law requires a qualified professional to certify specific MCA forms, conduct statutory audits under the Companies Act, and sign off on FEMA (Foreign Exchange Management Act) filings. What legaltech does is make the professional’s time go further — dramatically reducing the hours billed for data entry, form preparation, and deadline tracking, while concentrating their expertise on judgment calls that actually require it.

    The net result for a founder: smaller bills, fewer penalties, and less mental overhead.


    What You Should Still Not Fully Automate

    Legaltech is powerful. It is not a replacement for human legal judgment in areas where the stakes are high and the facts are specific to your situation.

    Statutory audits under the Companies Act, 2013 require a practicing Chartered Accountant. Transfer pricing documentation for related-party international transactions requires a CA with FEMA expertise. DPDP (Digital Personal Data Protection) Act compliance, especially for startups handling sensitive user data, involves legal interpretation that a generic AI system will get wrong. And for structuring a fundraising round — SHA (Shareholders Agreement) terms, ESOP pools, anti-dilution provisions — you want a lawyer who has reviewed dozens of term sheets, not a template.

    A quick example: A Bengaluru SaaS startup used an AI-generated employment agreement template that correctly handled TDS on salary but had a vague IP assignment clause — because the model drew from a generic template rather than one calibrated for a company where all value sits in proprietary code. The fix took 30 minutes with a lawyer. Had it reached a Series A due diligence uncorrected, it would have been a deal blocker.

    Use AI for the repeatable, deadline-driven, data-heavy tasks. Use professionals for the interpretive, high-stakes, and one-time structural decisions. The startup legal services on Lawizer are designed around exactly this division — AI-assisted preparation, professionally verified output.

    And if your startup is at the stage where brand protection matters alongside compliance — which is most founders by the time they have paying customers — trademark registration through Lawizer is a 3-step online process tracked through CGPDTM (the Controller General of Patents, Designs and Trade Marks).


    What India’s Legaltech Landscape Looks Like Right Now

    India’s legaltech ecosystem is concentrated in Bengaluru, Mumbai, and Delhi — the same cities that dominate the broader startup ecosystem. The market includes both horizontal compliance platforms (covering GST, MCA, and tax filings) and specialist tools for contract lifecycle management (CLM), e-discovery, and dispute resolution.

    Notable Indian players include SpotDraft (AI-powered contract management), CaseMine (legal research), Leegality (e-signatures and document workflows), Presolv360 (online dispute resolution), and Simpliance (labour law compliance).

    Most Indian legaltech startups are currently bootstrapped or backed by early-stage angel money — a reflection of both the opportunity and the early maturity of the sector. Jhana.ai, an AI-powered legal research and drafting tool, raised USD 1.6 million in 2024. DecoverAI secured USD 2 million in a seed round the same year.

    The government’s Digital India initiative and the e-Courts Phase III programme (which spent ₹1,029 crore in FY 2024-25 on court digitisation) are building the infrastructure layer on which legaltech can operate. As MCA21 V3 matures and GSTN improves its API ecosystem, the integration points for AI compliance tools multiply.

    What’s still missing: proprietary AI models trained specifically on Indian legal data — the Indian Penal Code, GST council circulars, Companies Act 2013 amendments, SEBI regulations. Most current tools use general-purpose LLMs fine-tuned on Indian legal text, which works well for document drafting but less reliably for nuanced regulatory interpretation. This is where the next wave of Indian legaltech investment is likely to go.


    Legal Innovation In India

    Frequently Asked Questions

    Q: What exactly does legaltech do for a startup — is it just templates?

    A: Modern legaltech is far beyond templates. AI-powered platforms now reconcile GST data across GSTR-1, GSTR-2B, and GSTR-3B; auto-populate and schedule MCA filings; calculate TDS on every transaction type; draft contextually appropriate contracts; and maintain a live compliance calendar that updates as regulations change. Templates are a starting point. The AI layer on top is what produces speed, accuracy, and proactive deadline management.

    Q: Can AI fully replace a CA or CS for startup compliance in India?

    A: No, and it shouldn’t. Indian law legally requires a qualified CA to conduct statutory audits and certify specific MCA forms, and a CS for certain ROC filings and company secretarial functions. What AI does is dramatically reduce the hours a CA or CS spends on data entry, reconciliation, and form preparation — making professional services faster and cheaper for founders. Think of it as AI handling the repeatable 80% so that the professional can focus on the judgment-intensive 20%.

    Q: How much does AI-based compliance cost compared to a traditional CA?

    A: A full annual compliance package at a CA firm for an early-stage Pvt Ltd startup runs ₹30,000–₹60,000 per year before event-based costs. AI-assisted platforms and services like Lawizer significantly reduce this by automating preparation, reducing billable hours, and eliminating penalty costs from missed deadlines. The exact saving depends on your filing complexity, but founders consistently report both lower bills and fewer compliance surprises.

    Q: Which compliance tasks carry the highest penalty risk if missed?

    A: ROC filings (MGT-7, AOC-4) carry an uncapped ₹100/day late fee. GST returns attract ₹50/day plus interest at 18% per annum on the unpaid tax. DIR-3 KYC carries a flat ₹5,000 penalty and DIN deactivation. TDS non-deduction attracts interest at 1% per month and TDS non-deposit at 1.5% per month, with prosecution risk in severe cases. These are the four highest-penalty areas where automated reminders and AI-assisted preparation deliver the fastest ROI.

    Q: Is it safe to use AI-generated legal documents for a startup?

    A: For standard, recurring documents — NDAs, employment agreements, vendor contracts, board resolutions — AI-generated drafts from well-maintained platforms are generally reliable starting points, especially when professionally reviewed before execution. For high-stakes, one-time structural documents — founders’ agreements with complex vesting structures, SHA terms during a fundraising round, FEMA filings — professional legal review is not optional. The risk in AI-generated legal documents is usually in what the model omits, not what it includes.

    Q: How does the Digital Personal Data Protection (DPDP) Act affect startup compliance?

    A: The DPDP Act, 2023 introduces data protection obligations for any startup that collects, stores, or processes personal data of Indian users — which is essentially every consumer-facing startup and many B2B ones. It requires consent management, data breach notification protocols, and defined data retention and deletion policies. AI compliance tools are beginning to add DPDP modules, but this is an evolving area where professional legal review of your data flows is still strongly advisable. Non-compliance carries significant penalties under the Act.


    Ready to Cut Your Compliance Costs Without Cutting Corners?

    Lawizer’s AI-assisted platform handles company incorporation, GST registration, ROC filings, trademark protection, and ongoing compliance — entirely online, without a CA visit, starting at ₹1,499.

    Explore Lawizer’s startup legal services →

    Already incorporated and need your brand protected? Register your trademark online with Lawizer and track your application through CGPDTM in real time.

  • Co-Founder Disputes: How to Legally Protect Yourself
Before They Happen?

    Co-Founder Disputes: How to Legally Protect Yourself Before They Happen?

    Over 11,000 Indian startups shut down in 2025 alone. That’s more than 30 closures every single day. CB Insights research consistently finds team and co-founder conflict among the top reasons startups fail — and in India’s high-stakes ecosystem, it shows up in boardroom battles, equity freezes, and IP ownership wars that end careers and companies alike.

    The painful truth? Most of those disputes were entirely preventable. The problem wasn’t the fight — it was the absence of a written agreement before the fight arrived.


    📌 TL;DR: Co-founder disputes are one of the leading causes of Indian startup failure, yet most founding teams sign nothing before they start building. The fix is a legally binding Co-Founders Agreement — executed under the Indian Contract Act, 1872 — that locks in equity splits, vesting schedules, IP ownership, roles, exit terms, and a dispute resolution mechanism before money or conflict enters the picture. Lawizer helps you draft and execute this document fully online, so your startup is protected from Day 1.


    What You’ll Learn

    • Why co-founder disputes are so destructive — and why they’re almost always preventable
    • The 5 legal protections every Indian founding team must put in place at formation
    • How equity vesting and “reverse vesting” actually work in Indian company law
    • What an IP assignment agreement covers and why it matters more than most founders think
    • How to resolve deadlocks before they become courtrooms
    • Answers to the questions founders search for but rarely ask their lawyers

    Why Co-Founder Disputes Are Deadlier Than Market Failure

    India is the world’s 3rd largest startup ecosystem, with nearly 1.97 lakh DPIIT-registered startups as of late 2025. And yet 90% of Indian startups fail within five years — a rate worse than the United States (80%) and far worse than the United Kingdom (60%).

    Team conflict — co-founder disputes, cultural misalignment, and governance breakdowns — is consistently listed among the top causes.

    The pattern is almost always the same. Two or three founders start with goodwill, a shared vision, and a verbal understanding of who does what and who owns what. The company grows. Stakes increase. One founder works longer hours. Another pivots priorities. A third wants to exit. Suddenly, the absence of a written framework is not an inconvenience — it is catastrophic.

    India has seen this publicly. When a property-listing unicorn’s board removed a co-founder in 2015, the governance terms were thin enough to turn a business disagreement into a public battle. When a fintech lender’s co-founder exited in 2022 amid a governance review, the dispute turned on vesting and what a departing founder was entitled to keep.

    These are the cases that made headlines. Thousands more play out quietly every year — in Bengaluru co-working spaces, Mumbai offices, and Hyderabad tech parks — and they never get written up.

    Here’s the thing. A verbal agreement between co-founders may technically be enforceable under the Indian Contract Act, 1872 — if it satisfies the basic requirements of offer, acceptance, and consideration. But enforcing it in practice is nearly impossible. Equity splits, IP ownership, and exit rights require written, signed documentation to be actionable in any Indian court or investor due diligence process.

    The solution isn’t pessimism about your co-founder. It’s the same kind of clear documentation that every serious business relationship deserves.


    Legal Protection #1 — The Co-Founders Agreement

    A Co-Founders Agreement (also called a Founders Agreement) is a private contract between the founding team that fixes — before money or conflict arrives — how equity is split, how shares vest, who does what, who owns the intellectual property, and what happens when a founder exits.

    It is enforceable as a contract under Section 10 of the Indian Contract Act, 1872. It should be executed on stamp paper appropriate for the state of execution (Maharashtra, Karnataka, Delhi, and Tamil Nadu each have different stamp duty rates for agreements). While registration is not mandatory, it adds evidentiary weight.

    What most founders miss: the agreement should be signed before incorporation or within the first 30 days after incorporating. Waiting until investors arrive forces retroactive structuring — and sophisticated investors will demand it anyway, often at terms that no longer favour the founders.

    The agreement needs to cover nine core areas. Every other clause is a sub-point of these nine:

    Equity split — the percentage each founder holds and on what basis (capital, idea, work, or a combination).

    Vesting and leaver provisions — how and when shares are earned over time, and what happens when someone leaves (more on this in the next section).

    Roles, responsibilities, and time commitment — who is CEO, CTO, or CMO; what each founder is expected to contribute; and whether this is a full-time engagement or part-time.

    Decision-making and deadlock — how day-to-day and strategic decisions are made, including voting thresholds, reserved matters, and what happens when founders cannot agree.

    IP assignment — that all intellectual property created by founders belongs to the company, not to the individual.

    Confidentiality — what information is confidential and what the obligations are after a founder exits.

    Non-compete and non-solicitation — reasonable restrictions on joining competitors or poaching employees. Under Indian law, overly broad non-competes are often unenforceable; keep them to 12–24 months and limit the scope to the company’s specific business area.

    Exit and termination — the conditions for a voluntary or involuntary exit and the consequences for each.

    Dispute resolution — the agreed mechanism for resolving disagreements (discussed separately below).


    Legal Protection #2 — Equity Vesting (And How It Works in India)

    Equity vesting is the mechanism that makes co-founder equity a reward for ongoing contribution rather than a windfall for showing up early. It is the single most protective clause in any founders agreement.

    A quick example: Suppose a two-founder startup splits equity 50-50 at incorporation. One founder departs after six months, keeping all 50%. The remaining founder now runs the entire company — and owns only half of it. Every investor they pitch will see this as a structural problem. That’s the scenario vesting prevents.

    The standard structure used by Indian startups (aligned with global investor expectations) is a four-year vesting schedule with a one-year cliff. This means:

    • No shares vest in the first twelve months (the cliff period)
    • On the one-year anniversary, 25% of the founder’s shares vest at once
    • The remaining 75% vest in monthly or quarterly installments over the next three years

    Here’s the thing about Indian company law: unlike US-style stock options, Indian private companies issue shares at formation rather than granting them over time. Vesting is therefore implemented through a contractual mechanism called reverse vesting — written into the Co-Founders Agreement or Shareholders Agreement. A founder who exits before their shares fully vest must transfer the unvested portion back to the company or remaining founders at nominal value.

    Good leaver vs bad leaver clauses go one step further. A good leaver — someone who resigns in good faith, retires, or leaves due to serious illness — typically gets to retain their vested shares at fair market value.

    A bad leaver — someone terminated for cause or a breach of the agreement — may be required to sell back shares at a discount or forfeit unvested equity entirely. These distinctions must be drafted with legal precision, because “cause” is exactly the word both sides will dispute in court.

    Investors — especially early-stage VCs and angels on platforms like Mumbai-based early-stage funds — routinely ask for vesting provisions during due diligence. A founding team without vesting structures signals governance risk before the first term sheet is issued.


    Legal Protection #3 — IP Assignment Agreement

    This is the most underestimated document in any early-stage startup, and the one that causes the most damage when it’s missing.

    Let’s break this down. Before a company is incorporated, founders typically spend months — sometimes years — building the core product, writing code, designing the brand, developing the algorithm.

    All of that work is done by individuals, not by a legal entity. Unless there is a written IP Assignment Agreement transferring ownership of that pre-incorporation work to the company, the intellectual property belongs to the individual who created it.

    What that means in practice: if that individual later leaves the company — voluntarily or otherwise — they may be able to claim ownership of the core technology, the codebase, or the brand that the entire business is built on. No investor will fund a company where the key IP is not clearly owned by the company. Many early-stage due diligence processes in India begin with exactly this question.

    An IP Assignment Agreement should cover: all pre-incorporation work transferred to the company at or before incorporation, all future work created by founders in connection with the business, proprietary algorithms, source code, designs, domain names, trademarks, and trade secrets, and a specific clause on AI-generated work (increasingly relevant for tech startups in 2025–26).

    This agreement is separate from the Co-Founders Agreement, though the two are typically executed together at formation. It should be signed by every founder and every early employee, contractor, or advisor who contributes to the product. Lawizer’s startup legal services include IP assignment as part of a complete legal protection package for founders — entirely online, without a CA or lawyer visit.

    If you’re building a product with any kind of brand identity, you should also think about trademark registration at the earliest stage. The Trademark Registration service on Lawizer lets you file online and tracks your application through CGPDTM (the Controller General of Patents, Designs and Trade Marks).


    Legal Protection #4 — Decision-Making Rules and Deadlock Resolution

    Two founders with equal equity and no decision-making framework is a recipe for paralysis. Every significant decision — a new hire, a pivot, accepting a term sheet, changing the product roadmap — can become a standoff.

    What most founders miss: the time to agree on how you’ll disagree is before you actually disagree. Once a deadlock happens, neither side wants to give ground. The agreement you signed when you trusted each other completely is the only mechanism that works.

    Decision-making provisions in a founders agreement typically operate in tiers:

    Day-to-day operational decisions fall within each founder’s defined role and don’t require a vote. Significant business decisions — hiring above a certain salary threshold, entering new markets, spending above a defined amount — require a simple majority of founders.

    Reserved matters — issuing new shares, amending the articles of association, acquiring or selling the business — require unanimous consent or a supermajority.

    For deadlocks on reserved matters, the agreement should specify a resolution mechanism. Common options include: a structured mediation process using a mutually agreed neutral party; escalation to an independent third-party expert; and finally, arbitration under the Arbitration and Conciliation Act, 1996. An arbitration clause in a founders agreement should specify the seat (typically Delhi, Mumbai, or Bengaluru), the institutional rules (DIAC, MCIA, or ad hoc), the number of arbitrators, and the language of proceedings.

    Arbitration keeps disputes confidential — critical for startups where public litigation damages investor confidence and press coverage. Under Section 11 of the Arbitration and Conciliation Act, 1996, if the agreed appointment process fails, a High Court can appoint an arbitrator on application.


    Legal Protection #5 — Exit and Termination Clauses

    Every co-founder will eventually exit. The only question is whether the terms are agreed in advance or fought over in real time.

    Exit clauses must address three situations:

    Voluntary resignation — the process by which a founder can leave, the notice period required, transition obligations, and how their shares are handled depending on good leaver or bad leaver status.

    Involuntary removal — the conditions under which co-founders can remove one another from their role or directorship, including the threshold required (typically a majority of founders), the procedures to follow under the Companies Act, 2013, and the share consequences that follow.

    Death or incapacity — what happens to a founder’s shares if they pass away or are unable to continue. This should align with the company’s Articles of Association (AoA), since share-related provisions bind the company only when written into the AoA as well as the founders agreement.

    A lock-in provision is also worth considering — a minimum period during which founders may not transfer their shares to third parties without the consent of remaining founders. This protects the founding team from having an unknown third party inherit a founder’s equity stake through a personal transaction.

    The short answer on timing for all of this: sign everything before you raise your first rupee of external funding. Once investors are at the table, the dynamics shift. They will negotiate from a position of leverage, and the terms they impose will reflect their interests, not yours.


    Common Mistakes Founding Teams Make

    Treating the agreement as a formality. Many founders sign a boilerplate template without walking through it clause by clause. If every founder can’t explain what their own agreement says about exit terms and IP ownership, it won’t guide behaviour when it matters.

    Assuming friendship is enough. The most destructive co-founder disputes in India have happened between people who were college friends, siblings, or long-time colleagues. Goodwill doesn’t survive equity fights. A written agreement does.

    Delaying until “after we’ve figured things out.” The longer you wait, the more each founder has invested — emotionally and financially — in their interpretation of the implicit deal. Sign when you still agree on everything.

    Ignoring the Articles of Association. Share-related vesting and transfer provisions in a founders agreement are enforceable as contract terms between founders. But they only bind the company itself when they’re also reflected in the company’s AoA, filed with the Registrar of Companies (ROC). This is a step most founders miss entirely.

    Broad non-competes. Indian courts regularly refuse to enforce non-compete clauses that are unreasonably wide in scope, geography, or duration. A clause preventing a departing founder from working in “technology” for five years anywhere in India is likely unenforceable. Keep it specific: 12–24 months, limited to the company’s direct business area.


    Frequently Asked Questions

    Q: Is a verbal co-founders agreement enforceable in India?

    A: Technically, a verbal agreement may satisfy the basic requirements of a contract under the Indian Contract Act, 1872 — offer, acceptance, and consideration. But in practice, enforcing it is extremely difficult. Equity splits, IP ownership, vesting schedules, and exit rights all require written, signed documentation to be actionable in court or during investor due diligence. A verbal agreement is effectively no agreement at all when a dispute arises.

    Q: When is the right time to sign a co-founders agreement?

    A: Before incorporation, or within the first 30 days after incorporating. Founders tend to agree most easily before funding pressure, user growth, or operational stress sets in. Waiting until investors arrive forces retroactive structuring — at terms investors control. Waiting until conflict arises defeats the purpose entirely. Sign when you still agree on everything.

    Q: What is reverse vesting and how does it work in India?

    A: Reverse vesting is the contractual mechanism through which Indian startups implement equity vesting. Because Indian company law issues shares at formation rather than granting them over time, vesting is structured as an obligation for a departing founder to transfer unvested shares back to the company or remaining founders at nominal value. It is implemented through the Co-Founders Agreement or Shareholders Agreement and must be drafted carefully to be enforceable.

    Q: What happens to IP if there’s no assignment agreement?

    A: Without a written IP Assignment Agreement, intellectual property created by an individual founder — including code, designs, algorithms, and brand elements — belongs to that individual, not to the company. If that founder exits, they can potentially claim ownership of the technology the business runs on. No serious investor will fund a company where IP ownership is unclear. This is why an IP assignment must be executed at or before incorporation.

    Q: Is a founders agreement different from a shareholders agreement?

    A: Yes. A Co-Founders Agreement is an early, personal document between the founding team — typically signed before or at incorporation — covering roles, equity, vesting, IP, and exit terms. A Shareholders Agreement (SHA) comes later, usually when external investors join, and governs the relationship between all shareholders including those investors. The two documents should be consistent with each other and with the company’s Articles of Association.

    Q: Can a co-founders agreement be amended after signing?

    A: Yes. A founders agreement can be amended at any time by mutual written consent of all founders. It’s a good practice to revisit the agreement at each major milestone — a funding round, a significant pivot, or a change in a founder’s role. The agreement should be treated as a living document, not a one-time formality.


    Ready to Protect Your Startup From Day 1?

    Lawizer’s experts handle your complete startup legal foundation — co-founders agreement, IP assignment, trademark registration, and company incorporation — all online, starting at just ₹1,499. No CA visits, no confusing paperwork.

    Get your startup legally protected today →

    Building a brand alongside your company structure? Protect your trademark with Lawizer before someone else files it first.

  • Director Identification Number (DIN): What It Is and How to Get One Fast?

    Director Identification Number (DIN): What It Is and How to Get One Fast?

    Over 1.5 million active companies are registered on India’s MCA21 portal — and every single director behind each one holds a Director Identification Number. Without it, you legally cannot sign a board resolution, file an MCA form, or be appointed to any company’s board. Not even for a day.

    Miss this step and your entire incorporation grinds to a halt.


    📌 TL;DR: A Director Identification Number (DIN) is a mandatory, lifelong 8-digit ID issued by the Ministry of Corporate Affairs (MCA) to every company director in India. If you’re incorporating a new company, you get it automatically through SPICe+ (Simplified Proforma for Incorporating Company Electronically Plus). If you’re joining an existing company’s board, you apply separately via Form DIR-3 on MCA21. Annual DIR-3 KYC filing keeps it active. Lawizer handles the entire process — from DSC to DIN — fully online.


    What You’ll Learn

    • What a DIN is and why every Indian company director must have one
    • The two routes to getting a DIN — SPICe+ vs Form DIR-3 — and which applies to you
    • Exactly which documents you need and common mistakes that cause rejection
    • How to keep your DIN active with annual DIR-3 KYC and what happens if you miss it
    • Answers to the most common founder questions about DIN in plain language

    What Is a Director Identification Number (DIN)?

    A DIN is a unique 8-digit identification number that the Central Government of India assigns to anyone who is — or intends to become — a director of an Indian company. It’s governed by Section 153 of the Companies Act, 2013 and administered by the Ministry of Corporate Affairs (MCA) through the MCA21 portal.

    Think of it as a permanent corporate PAN card for directors. Once allotted, your DIN stays with you for life. It tracks your involvement across every company where you serve or have served as a director, and links to all your MCA filings.

    Here’s the thing: DIN isn’t just a formality. The MCA uses it to maintain a nationwide database of directors — cross-referencing filings, flagging potential duplicates, and identifying directors of shell or non-compliant companies. In 2017, the MCA mass-disqualified tens of thousands of directors of defaulting companies in a single enforcement sweep, deactivating their DINs overnight.

    The DIN also carries a limit: under Section 165 of the Companies Act, 2013, one person cannot simultaneously hold directorships in more than 20 companies (with a sub-limit of no more than 10 public companies). All of this is tracked through the DIN-linked database on MCA21.


    Who Needs a DIN — and When?

    If you’re planning to be a director of any company registered in India — private limited, public limited, One Person Company (OPC), or Section 8 — you need a DIN before your appointment is formalised. This applies equally to Indian nationals, NRIs, and foreign nationals.

    Let’s break this down by situation:

    Situation 1 — You’re incorporating a new company: DINs for up to 3 proposed directors are allotted automatically as part of the SPICe+ incorporation process. You don’t file separately. The DIN is generated once your incorporation application is approved.

    Situation 2 — You’re joining an existing company’s board: You must apply for a DIN in advance using e-Form DIR-3 on the MCA21 portal. The company must pass a board resolution intending to appoint you before you can file DIR-3.

    Situation 3 — You already have a DIN but your details have changed: File e-Form DIR-6 (no government fee) to update your information, such as address, email, or mobile number. Changes must be attested by a practicing CA, CS, or Cost Accountant.

    One important rule: you can hold only one DIN. If a duplicate is accidentally issued, you’re legally required to surrender the extra one via e-Form DIR-5.


    Documents Required for DIN Application

    Getting your documents right the first time saves you the most time. Mismatched names, blurry scans, and expired proofs are the top reasons DIR-3 applications get sent back for resubmission.

    For Indian nationals, you’ll need:

    • PAN card (mandatory — it’s your primary identity proof)
    • One additional identity proof: Aadhaar card, passport, voter ID, or driving licence
    • Address proof not older than 2 months: Aadhaar, bank statement, utility bill, or driving licence
    • A recent passport-size photograph (JPEG format)
    • Digital Signature Certificate (DSC) — Class 2 or Class 3, linked to your PAN
    • Declaration by the applicant (included in DIR-3 form)
    • Professional certification: the form must be verified digitally by a practising CA, CS, or Cost and Works Accountant (CWA)

    For foreign nationals and NRIs (resident outside India for more than 182 days): All documents must be notarised and apostilled by the Indian Embassy in the country of residence. Nationals of countries sharing a land border with India (as per MCA’s 2022 amendment) must also attach a security clearance from the Ministry of Home Affairs.

    A quick example: A co-founder in Bengaluru applying for DIR-3 submitted her Aadhaar as both identity and address proof but used a PDF downloaded from DigiLocker without self-attestation. Her form was sent back for resubmission. The fix: self-attested, clearly scanned individual documents — not a combined PDF.


    and Digital Signature Certificate (DSC ...

    Step-by-Step: How to Apply for DIN via Form DIR-3

    This route applies when you’re joining an existing company’s board. Here’s exactly what to do on the MCA21 portal (mca.gov.in):

    Step 1 — Register on MCA21: Create a Business User account at mca.gov.in if you don’t already have one.

    Step 2 — Download and fill Form DIR-3: Access it under MCA Services → Director Services. Fill in your full name (exactly as on PAN), father’s name, date of birth, nationality, occupation type, address, mobile number, and email ID. Every starred field is mandatory.

    Step 3 — Attach documents: Upload self-attested copies of your identity proof, address proof, and photograph. Make sure the PAN name matches across all documents — even a middle name discrepancy causes rejection.

    Step 4 — Get professional certification: Have a practising CA, CS, or CWA digitally sign and certify the form. Without this, the form won’t process.

    Step 5 — Apply DSC and pay the fee: Sign the form electronically using your own DSC. Pay the prescribed government fee online.

    Step 6 — Submit and receive SRN: On submission, you’ll receive a Service Request Number (SRN). Track your application status at any time on the MCA portal.

    Step 7 — Receive DIN allotment letter: Once MCA approves your application, you’ll receive your DIN via email. Inform all companies where you act as director within 15 days, and ensure each company notifies its Registrar of Companies (ROC) within a further 15 days.

    What most founders miss: if MCA identifies your application as a potential duplicate, it goes to the DIN cell for manual back-office review, which can add time. Accurate documents from the start prevent this.

    If you’d rather skip the portal entirely, Lawizer’s team handles startup legal and company incorporation services end-to-end — DSC procurement, DIR-3 filing, and DIN tracking included.


    Keeping Your DIN Active: Annual DIR-3 KYC

    Getting your DIN is step one. Keeping it active is equally important — and many founders discover this only when their DIN gets deactivated mid-compliance cycle.

    Every DIN holder must file e-Form DIR-3 KYC annually by 30 September of each financial year. This KYC confirms your PAN, Aadhaar, address, email, and mobile on record with MCA. Filing before the deadline costs ₹0 in government fees.

    Miss the 30 September deadline and the consequences kick in immediately:

    • MCA’s automated system deactivates your DIN on 1 October
    • Status changes to: “Deactivated due to non-filing of DIR-3 KYC”
    • You cannot sign any MCA form until the DIN is reactivated
    • Your company cannot file its annual returns or any compliance form requiring your digital signature
    • Reactivation requires filing the full DIR-3 KYC eForm with a ₹5,000 penalty fee

    If you’ve missed multiple years, each year needs a separate filing and separate ₹5,000 payment. Missing FY 2023–24 and FY 2024–25 means paying ₹10,000 to get back on track.

    The short answer on timing: file in April, May, or June when the MCA portal is running smoothly. Every year in September, server loads spike as millions of directors file simultaneously, causing OTP delays and payment gateway failures. There’s no advantage to waiting.

    Note: As of December 2025, the MCA announced a shift from annual KYC filing to a three-year cycle, effective from FY 2025–26 onwards, while still requiring immediate updates for any changes in key personal details. Verify the latest directive on mca.gov.in before filing.


    Common Mistakes That Delay Your DIN

    Most DIN rejections and resubmission requests are entirely avoidable. Here are the ones that come up again and again:

    Name mismatch across documents: Your name in DIR-3 must match your PAN exactly — including initials and spelling. A difference of even one character between your PAN and Aadhaar triggers rejection.

    Expired or outdated address proof: Address proof documents must not be older than 2 months from the date of filing. Utility bills, bank statements, and Aadhaar updates must be current.

    Missing DSC: You cannot submit DIR-3 without your own valid Digital Signature Certificate. This is separate from the CA or CS who also signs the form.

    Filing combined documents: Uploading a multi-page combined PDF instead of individual self-attested scans for each document type is a common cause of resubmission.

    Checking DIN status only after rejection: Always verify your DIN status at mca.gov.in under Director Services → Check DIN Status before initiating any MCA compliance filing. A deactivated DIN will cause the form to fail at portal level.


    Frequently Asked Questions

    Q: Is DIN mandatory for all company directors in India?

    A: Yes, without exception. Section 153 of the Companies Act, 2013 makes it mandatory for every individual to obtain a Director Identification Number before they can be appointed as a director in any Indian company — private limited, public limited, OPC, or LLP. Acting as a director without a valid DIN can attract penalties and imprisonment of up to 6 months.

    Q: What is the difference between getting a DIN through SPICe+ vs Form DIR-3?

    A: SPICe+ is used when you’re incorporating a new company — DINs for up to 3 proposed directors are generated as part of the incorporation filing itself, with no separate application needed. Form DIR-3 is used when you want to join an existing company’s board and don’t yet have a DIN. The right route depends entirely on your situation.

    Q: How long does it take to get a DIN after submitting Form DIR-3?

    A: In most cases where all documents are in order, MCA allots a provisional DIN almost immediately after submission. Final approval and the allotment letter typically follow within a few working days. Applications flagged as potential duplicates go to manual review, which can take up to 1 month. Accuracy at submission is the single biggest factor controlling your timeline.

    Q: What happens if my DIN gets deactivated?

    A: A deactivated DIN means you cannot sign any MCA form, be appointed as a director in any company, or help your company file its annual returns. To reactivate, file e-Form DIR-3 KYC on the MCA21 portal and pay the ₹5,000 late fee. Once MCA processes the form (Straight Through Processing), your DIN status reverts to “Approved.”

    Q: Can I hold more than one DIN?

    A: No. Each individual is permitted only one DIN for life. If you accidentally end up with a duplicate, you’re legally required to surrender it using Form DIR-5 on MCA21. Retaining a duplicate DIN is a violation under the Companies Act, 2013.

    Q: Does DIN expire or need renewal?

    A: Your DIN itself has lifetime validity and does not expire. What requires annual action is the DIR-3 KYC filing, which keeps your DIN in active status with MCA. Failing to file by 30 September each year results in automatic deactivation.


    Ready to Incorporate and Get Your DIN Sorted?

    Lawizer’s experts handle everything — company incorporation via SPICe+, DSC procurement, DIR-3 filings, and annual DIR-3 KYC compliance — fully online, starting at just ₹1,499. No CA visit needed.

    Start your incorporation today →

    Already incorporated and need trademark protection alongside your directorship setup? Register your trademark with Lawizer in 3 simple steps.

  • How Indian Founders Are Building ₹10Cr Businesses Without a CA:

    How Indian Founders Are Building ₹10Cr Businesses Without a CA:

    India crossed 180,000 DPIIT-recognised startups by mid-2025. A large chunk of those founders — from Bengaluru SaaS builders to Kolkata D2C sellers — never had a CA on retainer. And their companies are alive, compliant, and scaling.

    The assumption that you need a Chartered Accountant to start or run a business in India is one of the most expensive myths in the startup world. Let’s break it down.


    📌 TL;DR: Most early-stage Indian founders can handle core compliance — GST registration, ROC filings, DPIIT recognition, and MSME registration — without a full-time CA, using government portals and legaltech platforms like Lawizer. A CA becomes mandatory only for statutory audits (once paid-up capital crosses ₹1 crore), FEMA filings, and transfer pricing. Lawizer’s expert-assisted plans let you stay compliant fully online, starting at a fraction of traditional CA retainer fees.


    What You’ll Learn

    • Which compliance tasks founders can legally handle themselves (or via legaltech platforms)
    • Where the MCA21, GSTN, and Startup India portals make DIY compliance genuinely possible
    • The exact three scenarios where a CA is legally mandatory — and what happens if you skip them
    • How to build a lean compliance system that keeps VCs happy and penalties at zero

    The Old Model Is Broken — Here’s Why Founders Are Moving On

    For decades, a CA retainer was treated as a fixed cost of doing business in India. Monthly fees ranging from ₹5,000 to ₹25,000, manual document handoffs, and a relationship where the founder rarely understood what was being filed or why.

    Then the government digitised everything. The MCA21 portal (Ministry of Corporate Affairs’ digital filing platform) now handles company incorporation via SPICe+ (Simplified Proforma for Incorporating Company Electronically Plus), director KYC through DIR-3 filings, and annual returns through AOC-4 and MGT-7 forms — all online.

    The GSTN (Goods and Services Tax Network) portal lets any registered user file GSTR-1 and GSTR-3B returns directly. The Startup India portal issues DPIIT recognition certificates within 48 hours of verified application, as confirmed by official government updates in 2025.

    Here’s the thing: these portals were designed to reduce dependence on intermediaries. A founder who spends two hours understanding the MCA21 interface can file most routine compliances without professional help.

    What most founders miss: “doing compliance without a CA” doesn’t mean doing it alone. It means using platforms — legaltech tools and expert-assisted online services — that bundle the expertise without the retainer.


    What You Can Absolutely Do Without a CA

    Let’s be specific. The following tasks have no legal requirement for a CA to be involved:

    Company Incorporation via SPICe+

    You can incorporate a Private Limited Company entirely through the MCA21 portal using the SPICe+ form. The form bundles PAN, TAN, GSTIN, EPFO, and ESIC registrations into a single application. No CA signature is required at the incorporation stage for most company types.

    What you do need: a Company Secretary (CS) for the MOA/AOA drafting, or a legaltech platform that bundles this into one package. Lawizer’s startup legal services cover SPICe+ incorporation end-to-end, online.

    DPIIT / Startup India Recognition

    The DPIIT (Department for Promotion of Industry and Internal Trade) recognition application is filed directly on the Startup India portal. A founder fills in the company details, explains the innovation, and uploads documents. No CA attestation is required.

    GST Registration and Regular Filing

    GST registration is done on the GSTN portal. Monthly or quarterly GSTR-1 (outward supply statement) and GSTR-3B (summary return) filings are rule-based — if you understand your invoices and HSN codes, you can file these yourself or use an automated platform. Budget 2024 also confirmed that startups with sub-₹40 lakh revenue remain exempt from GST registration.

    MSME / Udyam Registration

    The Udyam Registration portal (udyamregistration.gov.in) is entirely self-service. It uses your Aadhaar and PAN to auto-populate business details and issues the Udyam certificate immediately. There is zero requirement for a CA. Lawizer’s MSME Udyam Registration service gets this done quickly if you’d rather not navigate the portal yourself.

    Trademark Registration

    Trademark filing on the CGPDTM (Controller General of Patents, Designs & Trade Marks) portal can be done by the applicant directly. You don’t need a CA — though a trademark attorney or agent can help with class selection and objection handling.

    A quick example: Rohit, a Pune-based SaaS founder, incorporated his company via SPICe+, got DPIIT recognition, filed his GSTR-3B monthly, and registered his brand trademark — all without a CA retainer. His total spend in Year 1: under ₹15,000 on platform fees.


    The Three Places Where a CA Is Non-Negotiable

    Here’s the short answer: there are only three categories of compliance where Indian law or practical risk makes a CA mandatory.

    1. Statutory Audit under the Companies Act 2013

    Every Private Limited Company in India must get its accounts audited annually by a practising Chartered Accountant. This is mandated under Section 139 of the Companies Act 2013 and is non-negotiable regardless of your revenue.

    This is not the same as filing your returns yourself — the audit report (Form ADT-1) must carry a CA’s signature and membership number. Miss this, and the penalty under the Companies Act runs to ₹25,000 minimum, with potential prosecution of directors.

    2. FEMA Filings for Foreign Investment

    If your startup has received Foreign Direct Investment (FDI) or issued shares to non-resident investors, you’re required to file Form FC-GPR with the Reserve Bank of India. This falls under the FEMA (Foreign Exchange Management Act) framework. A CA or FEMA-specialised consultant is practically essential here — errors in FDI filings can attract compounding penalties from RBI. As the startup-movers.com guide on Startup India rules notes, non-compliance under FEMA can result in serious regulatory exposure.

    3. Transfer Pricing Documentation

    If your startup has international transactions with related parties — say, a parent company in Singapore or a subsidiary in the US — the Income Tax Act requires a Transfer Pricing study certified by a CA. This is technical, jurisdiction-specific, and genuinely requires professional input.

    What most founders miss: these three categories affect early-stage companies far less than they think. If you’re pre-revenue or at the seed stage, you can go months — sometimes an entire financial year — without hitting any of these triggers.


    How New-Age Indian Founders Are Actually Running Compliance

    The playbook has changed. Founders building ₹10 crore businesses aren’t winging it — they’re systematic about it. Here’s what the compliance stack looks like for a lean early-stage startup in 2025:

    The Compliance Calendar

    The best founders, as the Startup India post-incorporation guide notes, build a shared document or Notion page that maps ROC deadlines (AOC-4 in November, MGT-7 in November), GST filing dates (GSTR-1 by the 11th, GSTR-3B by the 20th of each month), and director KYC (DIR-3 by 30 September each year). One missed DIR-3 KYC deactivates the Director Identification Number, and restoration costs ₹5,000 per director.

    The Platform Layer

    Legaltech platforms — including Lawizer — replace the CA retainer for everything that doesn’t legally require one. India’s legaltech sector was valued at over ₹8,500 crore in 2024 and is projected to reach ₹20,700 crore by 2030, growing at 16.2% annually, according to Grand View Research data cited by RegisterKaro. That growth is driven by founders like you who’ve realised that platform fees are a fraction of a CA retainer.

    The Expert-on-Demand Model

    For the statutory audit and anything FEMA-related, smart founders don’t keep a CA on retainer — they hire one for the specific task, annually. A statutory audit for a small company costs ₹8,000–₹20,000. That’s a one-time annual fee, not a monthly retainer.


    Common Mistakes Founders Make Trying to Go CA-Free

    Getting the model wrong can cost you more than a retainer ever would.

    Skipping the statutory audit because “we’re too small”: Size doesn’t exempt you. Every Private Limited Company needs an annual audit. Full stop.

    Filing GSTR-1 without reconciling with your invoices: GST mismatches between GSTR-1 (what you said you sold) and your actual invoices trigger notices from the GSTN. This is one of the most common compliance pitfalls flagged by Indian startup compliance guides.

    Missing ROC annual filing deadlines: The penalty is ₹100 per day per form. It compounds quietly. Founders who raise their first institutional round often discover their MCA21 filing history for the first time — during due diligence. Non-filing on your MCA record is a term-sheet killer.

    Assuming trademark registration is optional: Your brand name is an asset. Unregistered trademarks are not protected under the Trade Marks Act 1999. Filing early costs ₹4,500 per class for a startup. Fighting infringement later costs ten times that. Lawizer’s trademark registration service covers filing, class selection, and objection handling.

    DIY-ing FEMA filings: This is where founders get into real trouble. FC-GPR and other RBI filings have strict formats, timelines, and documentation requirements. A ₹2,000 platform fee mistake here can become a ₹5 lakh compounding penalty. This is one area to always use a professional.


    Frequently Asked Questions

    Q: Can I incorporate a Private Limited Company in India without a CA?

    A: Yes, you can. Company incorporation via the SPICe+ form on the MCA21 portal does not legally require a CA. You will need a Company Secretary (CS) for the Memorandum and Articles of Association, but legaltech platforms like Lawizer bundle this into their incorporation packages. Most founders complete the process fully online without retaining a CA.

    Q: Is a statutory audit mandatory even if my startup has zero revenue?

    A: Yes. Under Section 139 of the Companies Act 2013, every Private Limited Company must have its accounts audited by a practising Chartered Accountant every financial year, regardless of revenue or size. The audit report must carry the CA’s membership number and is submitted via Form ADT-1 on the MCA21 portal. Skipping this attracts a minimum penalty of ₹25,000.

    Q: Can I file GST returns myself as a startup founder in India?

    A: Yes. GST registration and regular filing — GSTR-1 and GSTR-3B — are done directly on the GSTN portal and require no CA involvement. The key is understanding your invoice data, HSN/SAC codes, and filing deadlines. Many founders use legaltech platforms or accounting software to automate this. Note: startups with annual turnover below ₹40 lakh are exempt from GST registration altogether.

    Q: What happens if I miss the ROC annual filing deadline?

    A: The Registrar of Companies (ROC) charges ₹100 per day per delayed form under the Companies Act 2013. For a form like AOC-4 (financial statements) or MGT-7 (annual return), delays running into months can result in penalties of several lakhs. Beyond the financial cost, missed filings are visible on the MCA21 public database and can flag compliance issues during investor due diligence.

    Q: When does a startup in India actually need a CA?

    A: There are three non-negotiable triggers: (1) the annual statutory audit under the Companies Act 2013, which every Private Limited Company must complete regardless of revenue; (2) FEMA-related filings like Form FC-GPR when you receive foreign investment; and (3) transfer pricing documentation if you have international transactions with related parties. Outside these, most compliance tasks can be handled via government portals or legaltech platforms.

    Q: Is DPIIT/Startup India recognition something I can apply for myself?

    A: Yes. The DPIIT recognition application is filed directly on the Startup India portal at startupindia.gov.in. No CA signature or involvement is required. In 2025, the government updated the portal so that DPIIT certificates can be issued within 48 hours for verified applications, and startups can now auto-link their GST and PAN data with MCA for faster processing.


    Ready to set up your startup’s compliance the right way?

    Lawizer’s experts handle everything — company incorporation via SPICe+, GST registration, trademark filing, and MSME Udyam registration — fully online, starting at just ₹999. No CA visit needed.

    Get your startup compliant today →

  • NDA for Startups: When You Need One, What It Should Say, and What It Can’t Do

    NDA for Startups: When You Need One, What It Should Say, and What It Can’t Do

    NDA for Startups: When You Need One, What It Should Say, and What It Can’t Do

    Every week, somewhere in Bengaluru, Mumbai, or Delhi, a founder shares their product roadmap with a potential investor — without an NDA. Sometimes nothing happens. Sometimes that “investor” builds the same product six months later. An NDA won’t guarantee you never face that situation, but signing one correctly — before the conversation — means you have legal standing if things go wrong. Not signing one means you don’t.

    Here’s the thing: most startup NDAs in India are either never signed, signed too late, or drafted so vaguely they wouldn’t survive a courtroom. This guide fixes all three problems.

    📌 TL;DR: An NDA (Non-Disclosure Agreement) is a legally binding contract under the Indian Contract Act, 1872 that prevents the receiving party from disclosing or misusing your confidential information. For Indian startups, NDAs are essential before sharing details with employees, contractors, vendors, co-founders, or potential investors. A valid NDA must clearly define what counts as confidential, set a reasonable duration, include exclusions, and specify dispute resolution. Critically, an NDA cannot protect information already in the public domain, stop a genuine whistleblower, or substitute for broader IP protection like patents or trademarks. Lawizer can draft a watertight, India-specific NDA for your startup quickly and affordably.

    Legal Checklist for Founders Before ...

    What You’ll Learn

    • What an NDA actually is under Indian law — and the two main types startups use
    • Exactly when your startup needs one, and with whom
    • Every clause a strong, India-specific NDA must include to be enforceable
    • What an NDA legally cannot do — the limits most founders don’t know about
    • Common NDA drafting mistakes that make the agreement worthless in court

    What Is an NDA and How Does It Work Under Indian Law?

    An NDA — Non-Disclosure Agreement — is a legally binding contract between two or more parties that establishes a confidential relationship. The receiving party agrees not to disclose or misuse specific information shared by the disclosing party. In India, NDAs are governed primarily by the Indian Contract Act, 1872 — which means for your NDA to hold up in court, it must satisfy the basic conditions of a valid contract under Section 10: a clear offer and acceptance, lawful consideration (can be a simple promise of mutual benefit), free consent from all parties, and a legal purpose.

    Indian courts do uphold NDAs — but only when the terms are specific, reasonable, and don’t restrain trade. This is where Section 27 of the Indian Contract Act comes in. It prohibits agreements that unreasonably restrain a person’s right to carry on a trade or profession. So an NDA that says “you can never work in fintech again” will likely be struck down. An NDA that says “you cannot share our proprietary payment algorithm with third parties for three years” stands on much firmer ground. The distinction matters enormously when drafting.

    Unilateral vs. Mutual NDA — Which One Does Your Startup Need?

    A unilateral NDA (one-way) binds only one party — typically used when a startup shares information with an employee, contractor, or vendor. A mutual NDA (bilateral) binds both parties — used when two startups are exploring a partnership, merger, or collaboration and both sides are sharing sensitive information. For most early-stage Indian startups, unilateral NDAs cover the majority of situations: hiring, freelancer engagements, vendor negotiations, and early investor conversations.


    When Does Your Startup Actually Need an NDA?

    Not every conversation requires an NDA. But there are specific situations where skipping one is a serious legal risk. Let’s break this down by relationship type.

    Employees and Co-Founders

    Every full-time employee who will have access to your codebase, customer data, pricing models, or business strategy should sign an NDA before or on their first day — ideally as part of their employment agreement. Co-founders are trickier. Many founders assume trust eliminates the need for a formal agreement. What most founders miss: if a co-founder exits and later joins a competitor, a signed NDA is the only instrument that legally prevents them from taking your trade secrets with them. Pair the NDA with a solid founders’ agreement and legal structure from day one.

    Freelancers and Contractors

    A Bengaluru-based startup that hires a Mumbai freelancer to build their MVP is sharing source code, architecture decisions, and possibly user data. NDAs signed with freelancers or contractors in India are legally enforceable if the terms are clear and signed digitally or physically. One important addition: for contractors who are creating work for you, add an IP assignment clause alongside the NDA — clarifying that all work product belongs to your startup. Without it, the contractor could legally retain IP rights to code they wrote for you.

    Vendors and Third-Party Service Providers

    If a vendor — say, a payment gateway integration partner or a data analytics firm — will access your backend systems or customer data, an NDA is necessary. This is also relevant when you’re onboarding accounting firms, HR consultants, or legal advisors who will see sensitive financial information. The NDA in these cases should define exactly what data is being shared, for what purpose, and what happens to it after the engagement ends.

    Investors — With an Important Caveat

    Here’s an honest reality most legal blogs won’t tell you: most early-stage investors — angels and VCs in India — will refuse to sign an NDA at the pitch stage. They receive hundreds of pitches and signing individual NDAs for each creates legal liability. Pushing for an NDA before a first meeting can signal inexperience and may cost you the conversation. The practical approach: share only what you’re comfortable making public at the pitch stage, keep your “secret sauce” out of the first deck, and introduce an NDA once due diligence begins and a term sheet is on the table.

    Legal Compliances for Startups in India ...

    What a Strong NDA Must Include: Clause by Clause

    A vague NDA is nearly useless. Indian courts have struck down confidentiality agreements where terms were ambiguous, the duration was unreasonable, or the definition of confidential information was too broad to be meaningful. Here is every clause your NDA needs to be enforceable.

    1. Identification of Parties
    State the full legal names and addresses of both the Disclosing Party (your startup) and the Receiving Party. If your startup is a Private Limited Company, use the exact registered name as it appears in your Certificate of Incorporation. Mismatches between the NDA and your company registration documents create grounds for challenging enforceability.

    2. Definition of Confidential Information
    This is the most critical clause — and the one most often drafted poorly. A good definition should include: business plans and financial projections, software source code and technical architecture, customer and vendor lists, proprietary processes and formulas, and marketing strategies. Specify how information can be marked as confidential — in writing, verbally (confirmed in writing within 30 days), or by its nature. If it isn’t defined, it isn’t protected.

    3. Exclusions from Confidentiality
    Every enforceable Indian NDA must list what is not covered: information already in the public domain through no fault of the receiving party; information the receiving party already knew before signing; information independently developed by the receiving party; information received from a third party without restriction; and information that must be disclosed under a court order or law. These exclusions are what make the NDA reasonable.

    4. Obligations of the Receiving Party
    Specify what the receiving party must do: keep the information confidential, use it only for the agreed purpose, limit internal access to those who need to know, and apply the same standard of care they would use to protect their own confidential information. For tech startups, also prohibit reverse engineering or using the information to develop a competing product.

    5. Duration
    The standard duration for most startup NDAs is 2 to 5 years. For trade secrets specifically, you can specify that confidentiality obligations survive “for as long as the information remains a trade secret.” Keep this distinction explicit in the agreement.

    6. Consequences of Breach and Dispute Resolution
    Include the right to seek an injunction, monetary damages, and recovery of legal costs. Include an arbitration clause — governed by the Arbitration and Conciliation Act, 1996 — which is faster and more private than going to court.

    7. Governing Law and Jurisdiction
    Specify that the agreement is governed by the laws of India, and name the specific city where disputes will be adjudicated. Also ensure that digital signatures are treated as valid execution under the IT Act, 2000.


    What an NDA Cannot Do — The Limits Founders Must Understand

    This is the section most NDA guides skip. An NDA is a powerful tool — but treating it as a complete shield is a dangerous mistake.

    • It cannot protect information already public. Once information is in the public domain, an NDA cannot put it back. Courts will not enforce confidentiality over publicly accessible information.
    • It cannot stop a genuine whistleblower. If an employee discloses information to expose fraud or illegal activity within your startup, Indian law protects that disclosure. An NDA clause attempting to silence a whistleblower will be unenforceable.
    • It cannot replace a patent, trademark, or copyright. An NDA protects confidential information between specific parties. It does not give you ownership over an invention, brand, or creative work. Trademark and patent registrations are separate instruments — and the strongest protection combines both.
    • It cannot prevent someone from using general skills and knowledge. Your ex-CTO can go work at a competing startup. What they cannot do is take your specific codebase or client list with them.
    • It cannot protect what you failed to keep secret internally. Courts have declined to enforce NDAs where the startup had poor internal data controls — no access restrictions, unencrypted storage, or unrestricted internal sharing of the “confidential” information.

    Common NDA Mistakes Indian Startups Make

    • Signing after the conversation: An NDA only covers information shared after it is signed. Always execute the NDA before any sensitive disclosure.
    • Using a generic international template: A US or UK NDA template may not align with the Indian Contract Act, the Specific Relief Act, 1963, or the IT Act, 2000. Jurisdiction clauses, consideration structures, and enforcement mechanisms differ significantly.
    • Confusing NDA with non-compete: An NDA restricts disclosure. A non-compete restricts who someone can work for. Post-employment non-compete clauses are extremely difficult to enforce under Indian law. Don’t bundle them into your NDA expecting the non-compete to hold.
    • No return or destruction clause: When an employee leaves or a contractor’s engagement ends, your NDA should specify that all confidential materials — including digital copies — must be returned or destroyed.

    Frequently Asked Questions

    Q: Is an NDA legally enforceable in India?
    Yes, NDAs are legally enforceable in India under the Indian Contract Act, 1872, the Specific Relief Act, 1963, and — in cases involving digital data — the IT Act, 2000. Courts uphold NDAs when the terms are specific, the duration is reasonable, and the agreement does not unreasonably restrain trade under Section 27. Vague definitions of confidential information and overly broad restrictions are the most common reasons Indian courts decline to enforce an NDA.

    Q: Should I ask investors to sign an NDA before my pitch?
    In most cases, no — not at the very first meeting. Early-stage investors in India typically decline to sign NDAs at the pitch stage because they review hundreds of decks across similar sectors. The practical approach is to share only high-level information in the initial pitch, reserve proprietary details for due diligence, and introduce a mutual NDA once a term sheet or letter of intent is on the table.

    Q: Can I use a digital signature on an NDA in India?
    Yes. Digital signatures are legally valid for NDAs in India under the IT Act, 2000. A digitally signed NDA carries the same legal weight as a physically signed one, provided the signature is applied through a recognized e-signature platform. The NDA should explicitly state that electronic execution is valid and binding, and platforms using a Digital Signature Certificate (DSC) provide an audit trail useful in any future dispute.

    Q: How long should an NDA last for a startup in India?
    For most startup relationships — contractors, vendors, early employees — a duration of 2 to 5 years is standard and likely to be upheld by Indian courts. For trade secrets, you can specify that confidentiality obligations last “for as long as the information remains a trade secret.” Indefinite NDAs covering general business information are viewed with suspicion by courts and should be avoided.

    Q: Does an NDA protect my startup idea from being stolen?
    An NDA protects specific confidential information shared with a named party — it does not protect an idea in the abstract. Under Indian law, ideas alone cannot be patented or fully protected; only their concrete implementation can be. If a third party independently develops the same idea without access to your confidential information, an NDA gives you no claim against them. For stronger protection, pair an NDA with appropriate IP registration such as a patent or trademark.

    Q: What happens if someone breaches an NDA in India?
    You have two primary legal remedies. First, you can seek an injunction under the Specific Relief Act, 1963 — a court order directing the other party to stop the disclosure or use of your confidential information. Indian courts are generally quicker to grant injunctions than to award damages, making this the more immediate remedy. Second, you can sue for monetary damages. Including a pre-agreed penalty clause in your NDA and an arbitration clause speeds up the entire process significantly.


    Ready to protect your startup’s confidential information?
    Lawizer’s legal experts draft India-specific NDAs, employment confidentiality agreements, and full startup legal packages — fully online, starting at just ₹999. No CA visit, no lengthy back-and-forth.
    Get Your Startup NDA Drafted by Lawizer → lawizer.com/startup-businesslegal

  • Startup India Registration: Who Qualifies, What You Get, and How to Apply:

    Startup India Registration: Who Qualifies, What You Get, and How to Apply:


    Over 2.23 lakh startups have now been officially recognized under Startup India — and in FY 2025–26 alone, more than 55,200 new startups received DPIIT recognition, the highest ever in a single year. That’s not a coincidence. That’s founders discovering what this registration actually unlocks.

    Three years of zero income tax. An 80% cut on patent fees. Angel tax protection. Government tender access without prior experience. And it’s completely free to apply. If you haven’t filed for Startup India registration yet, you may be leaving a serious amount of money and credibility on the table.

    📌 TL;DR: Startup India registration — officially called DPIIT recognition — is a free, fully online certification for eligible Indian startups. To qualify, your entity must be a Private Limited Company, LLP, or Partnership Firm, less than 10 years old, with annual turnover under ₹100 crore, and engaged in an innovative product or scalable business model. Key benefits include a 3-year income tax holiday under Section 80IAC, 80% rebate on patent fees, self-certification under labour laws, and access to the Startup India Seed Fund Scheme. Lawizer can help you prepare and file your application without errors or delays.

    StartupIndia Registration Service in Kolkata - West Bengal | DPIIT ...

    What You’ll Learn

    • Exactly which businesses qualify for Startup India registration under DPIIT norms
    • Every benefit you get after recognition — tax, funding, IP, compliance, and tenders
    • The step-by-step application process on the Startup India portal, including documents needed
    • What mistakes commonly delay or reject applications — and how to avoid them
    • How to claim the Section 80IAC tax exemption after getting your DPIIT certificate

    What Is Startup India Registration and Why Does It Matter?

    Startup India registration refers to the DPIIT recognition process under the Startup India initiative, launched on 16th January 2016 by the Government of India. When DPIIT — the Department for Promotion of Industry and Internal Trade, the central government body under the Ministry of Commerce and Industry — certifies your business as a startup, it’s not just a badge. It’s your official entry pass into India’s innovation ecosystem.

    Here’s the thing: most founders assume Startup India registration is for big-ticket VC-funded companies in Bengaluru or Mumbai. It’s not. Over 51% of DPIIT-recognized startups now come from non-metro cities, and recognition is available to businesses across all sectors — from agritech in Nagpur to edtech in Kochi. What matters is that you meet the eligibility criteria, not where you’re located.

    The recognition is also completely free. There are no government fees to apply. DPIIT reviews your application and, if approved, issues a Recognition Certificate — typically within 2 to 7 working days. That certificate then unlocks a stack of benefits that would otherwise cost your startup lakhs of rupees.


    Who Qualifies? The Exact DPIIT Eligibility Criteria

    Not every new business is a “startup” under the law. DPIIT follows the definition laid down in G.S.R. Notification 127(E) dated 19th February 2019, and your entity must satisfy all five conditions simultaneously. Let’s break this down.

    1. Entity Type You must be incorporated as one of the following: a Private Limited Company (under the Companies Act, 2013), a Limited Liability Partnership (LLP), or a Registered Partnership Firm. Sole proprietorships, trusts, and public limited companies are not eligible. If you’re currently a sole proprietor, you’d need to convert to a Pvt. Ltd. or LLP first.

    2. Age of Entity Your business must not be more than 10 years old from the date of incorporation. DeepTech startups recognized under the DeepTech policy get an extended window of 20 years. The clock starts from your Certificate of Incorporation date — not from when you launched your product.

    3. Annual Turnover Your startup’s annual turnover must not have exceeded ₹100 crore in any financial year since incorporation. Pre-revenue startups are eligible — you don’t need to be generating income to apply. DPIIT assesses innovation potential, not current revenue.

    4. Original Formation Your entity must not have been formed by splitting or reconstructing an existing business. This is designed to prevent established companies from rebranding themselves as startups to claim benefits. If you’re genuinely a new venture, this criterion won’t affect you.

    5. Innovation or Scalability This is the criterion that trips up most applicants. DPIIT requires that your entity works towards the development, improvement, or innovation of a product, process, or service — OR that it operates on a scalable business model with high potential for employment or wealth generation. What most founders miss: your product doesn’t need to be entirely novel, but your application must clearly articulate how it solves a problem differently. Vague descriptions like “we provide software services” are the #1 reason for rejection.


    What You Actually Get: Benefits of DPIIT Recognition

    Once DPIIT issues your Recognition Certificate, a set of benefits kicks in — some automatically, some requiring a separate application. Here’s a complete breakdown of what’s on the table.

    Income Tax Holiday — Section 80IAC Eligible DPIIT-recognized startups — only Private Limited Companies and LLPs incorporated after 1st April 2016 — can apply for a 100% income tax exemption for 3 consecutive financial years within the first 10 years of incorporation, under Section 80IAC of the Income Tax Act. This isn’t automatic; you apply separately to the Inter-Ministerial Board (IMB) for approval. If your startup earns ₹1 crore in annual profit, this exemption saves you approximately ₹27–30 lakh in taxes each year during those three years.

    Angel Tax Protection Angel Tax (Section 56(2)(viib) of the Income Tax Act) was a provision that taxed the portion of investor funding exceeding your startup’s fair market value. The Union Budget 2024 abolished angel tax entirely for all investor classes — a major win for the ecosystem. DPIIT recognition still provides additional documentation and credibility that makes fundraising smoother, especially when dealing with institutional investors or structuring your legal setup for growth.

    IPR Benefits: 80% Off Patent Fees Filing a patent normally costs ₹8,000 as the base government fee. With DPIIT recognition, it drops to ₹1,600 — an 80% rebate. Similarly, trademark registration fees drop by 50% for recognized startups. Beyond cost savings, your patent application is fast-tracked through the examination queue — so you’re not waiting years for IP protection that your product needs now.

    Compliance Relief and Labour Law Self-Certification DPIIT-recognized startups can self-certify compliance under several labour laws — including the EPF Act, ESI Act, and Payment of Gratuity Act — for a period of 3 to 5 years. This means no routine government inspections during that window. You’re also exempt from filing cash flow statements, can conduct board meetings with greater flexibility, and can issue sweat equity up to 50% of paid-up capital. For an early-stage team in Delhi or Bengaluru trying to move fast, this compliance breathing room is genuinely valuable.

    Government Tenders Without Prior Experience Normally, government procurement requires vendors to demonstrate prior experience and submit an Earnest Money Deposit (EMD — a security amount bid to show seriousness). DPIIT-recognized startups are exempt from both requirements. Central ministries and departments are specifically directed to relax these conditions. This opens up a large procurement market to new ventures that would otherwise be shut out.

    Funding Schemes Access Recognition unlocks access to government-backed funding channels: the Startup India Seed Fund Scheme (SISFS), which has committed over ₹605 crore to more than 3,400 startups through 219 incubators; the Fund of Funds for Startups (FFS), which has disbursed more than ₹7,000 crore to over 135 Alternative Investment Funds (AIFs); and the expanded Credit Guarantee Scheme for Startups (CGSS), with a guarantee cover of up to ₹20 crore per borrower. These are not easily accessible without DPIIT recognition.


    How to Apply: Step-by-Step Process

    The entire Startup India registration process is online, through the official Startup India portal at startupindia.gov.in. Here’s exactly what you do.

    Step 1 — Incorporate your entity first: Your business must already be registered as a Pvt. Ltd., LLP, or Partnership Firm before you can apply. If you haven’t done this yet, Lawizer’s incorporation service gets this done fully online, without a CA visit.

    Step 2 — Register on the Startup India portal: Go to startupindia.gov.in, click “Register”, create your account, and verify your email ID.

    Step 3 — Apply for DPIIT Recognition: After logging in, navigate to the “Recognition” tab and select “Apply for DPIIT Recognition”. You’ll fill out a form with details about your entity, business model, and what problem you’re solving.

    Step 4 — Upload documents: You’ll need your Certificate of Incorporation or Partnership Registration, a brief description of your innovation (this is critical — write clearly), and details of all directors or partners. An authority letter authorizing the applicant to file on behalf of the company is also required.

    Step 5 — Submit and wait: DPIIT reviews the application and issues the Recognition Certificate within 2 to 7 working days if everything is in order.

    Step 6 — Apply for 80IAC tax exemption separately: After getting your DPIIT certificate, file a separate application with the Inter-Ministerial Board (IMB) for the income tax exemption under Section 80IAC. This process takes 3 to 9 months and requires additional documentation.

    A quick example: a Bengaluru-based SaaS startup with 3 co-founders applied in early 2025. They had their Certificate of Incorporation ready, wrote a specific 400-word innovation description explaining how their AI-based HR tool reduced hiring time by 40% for SMEs, and got their DPIIT certificate within 4 working days. That clarity of description made all the difference.


    Common Reasons Applications Get Rejected — and How to Avoid Them

    What most founders miss: over 40% of Startup India applications face delays or rejections due to documentation errors or weak innovation descriptions. DPIIT is not evaluating your revenue or team size. It is evaluating whether your application convincingly demonstrates innovation, scalability, and a potential to create employment or wealth.

    • Vague product descriptions: Writing “we offer IT services” or “we develop mobile apps” is not sufficient. Describe the specific problem, your unique approach, and the scale of impact — in concrete terms.
    • Wrong entity type: Sole proprietorships, public limited companies, and non-profits cannot apply. Check your registration structure before filing.
    • Missing or mismatched documents: The name on your Certificate of Incorporation must exactly match what you enter on the portal. Any mismatch causes rejection.
    • Reconstructed business claims: If DPIIT finds that your “new” entity is a restructuring of an existing business — same directors, same clients, same product — the application will be denied.

    The short answer: spend at least as much time on your innovation description as you do on the paperwork. It is the most heavily weighted part of the review.


    StartupIndia Registration 2026 Quickly ...

    Frequently Asked Questions

    Q: Is Startup India registration mandatory for my business? No, Startup India registration is not mandatory. A business can legally operate in India without DPIIT recognition. However, not registering means you miss out on the 3-year income tax exemption under Section 80IAC, the 80% rebate on patent fees, self-certification under labour laws, and access to government seed funding schemes. For most early-stage startups looking to reduce costs or raise funding, registration is strongly advisable.

    Q: Can a sole proprietorship apply for Startup India DPIIT recognition? No, sole proprietorships are not eligible for DPIIT recognition under the Startup India initiative. Only Private Limited Companies, Limited Liability Partnerships (LLPs), and Registered Partnership Firms qualify. If you’re currently operating as a sole proprietor, you would need to convert to one of these entity types — after which recognition may be available from the original date of commencement of business, subject to DPIIT guidelines.

    Q: How long does the Startup India registration process take? The DPIIT Recognition Certificate is typically issued within 2 to 7 working days after you submit a complete application with all required documents. However, if your innovation description is vague or documents are mismatched, the application can be returned for revision, which adds weeks to the process. The separate Section 80IAC tax exemption application, filed after recognition, takes between 3 and 9 months for Inter-Ministerial Board approval.

    Q: Can a startup with no revenue yet apply for DPIIT recognition? Yes. Pre-revenue startups are fully eligible to apply for Startup India registration. DPIIT evaluates your innovation potential and business model, not your current income. As long as you can demonstrate through your pitch deck or product description that your startup addresses a real problem through an innovative approach and has the potential to scale, generate employment, or create wealth, you can qualify for recognition even before your first rupee of revenue.

    Q: What documents do I need to apply for Startup India registration? The primary documents required are your Certificate of Incorporation (for a Pvt. Ltd. or LLP) or Partnership Registration Certificate, a description of your startup’s innovative product or service, details of all directors or partners, and an authority letter authorising the applicant to file on behalf of the company. Additional documents — such as a pitch deck, demo video, or URL of your live product — may strengthen your application, especially for startups in early stages without a live product yet.

    Q: Is the income tax exemption under Section 80IAC automatic after DPIIT recognition? No, it is not automatic. DPIIT recognition is the first step — it makes you eligible to apply for the Section 80IAC exemption, but you must separately file an application with the Inter-Ministerial Board (IMB). Only Private Limited Companies and LLPs incorporated after 1st April 2016 are eligible for this exemption. The IMB reviews the application and, if approved, grants a 3-year income tax holiday on profits, claimable within the first 10 years of the startup’s life.


    Ready to get your DPIIT Recognition Certificate? Lawizer’s experts handle everything — company incorporation, Startup India registration filing, and Section 80IAC tax exemption applications — fully online, starting at just ₹999. No CA visit needed. Start Your Startup India Registration with Lawizer → lawizer.com/startup-businesslegal

  • How to File a Trademark Objection Reply in India: A Founder’s Walkthrough

    How to File a Trademark Objection Reply in India: A Founder’s Walkthrough

    Your trademark application status just flipped to “Objected” on the IP India portal. Your stomach drops. You’ve spent months building this brand — now what?

    Here’s the thing: a trademark objection is not a rejection. It’s the examiner asking you to make your case. And if you respond well within the deadline, your mark moves forward.


    📌 TL;DR: A trademark objection reply in India must be filed within 30 days of receiving the Examination Report on the IP India portal. Objections arise under Section 9 (absolute grounds like lack of distinctiveness) or Section 11 (relative grounds like similarity to existing marks) of the Trade Marks Act, 1999. A well-drafted reply with evidence, affidavits, and legal arguments can get your application accepted — and Lawizer’s trademark experts can handle the entire reply process for you online.

    Founder reviewing trademark examination report on laptop — trademark objection reply India

    What You’ll Learn

    • Why trademark objections are raised and what the two main grounds mean
    • The exact 4-step process to file your objection reply online
    • What documents you need to attach with your reply
    • What happens after you file — hearings, journal publication, and beyond
    • How to avoid common mistakes that lead to trademark abandonment

    What Is a Trademark Objection — and Why Shouldn’t You Panic?

    A trademark objection is a formal concern raised by the Trademark Examiner following the review of your application. It is not a dismissal — it’s a request to make your application clearer or change it. Think of it as the examiner putting up a hand and saying: “Convince me.”

    The trademark examination report is a critical document issued after a thorough review of your application. It highlights any objections found. You’ll find this report on the IP India portal under your application number. Once you see the “Objected” status, your clock starts ticking.

    What most founders miss: trademark objections are very common and most applications face them. However, trademark objections are not always fair. The registry sometimes raises them in a mechanical manner. That means a solid, well-argued reply often overturns the objection entirely. Don’t abandon your application without fighting for it.


    The Two Grounds Under Which Objections Are Raised

    Understanding why the examiner raised the objection determines your entire strategy. There are exactly two categories under the Trade Marks Act, 1999:

    Section 9 — Absolute Grounds for Refusal

    These objections come up when the trademark, in itself, doesn’t fulfil the basic requirements. Lack of distinctiveness means the mark is so common it doesn’t differentiate your goods or services from others. Descriptive or generic terms — words that just point out the quality, kind, or purpose of the product — are also flagged.

    A quick example: if you try to register “Fresh Juice” for a juice brand, expect a Section 9 objection. The phrase describes the product, not a unique brand identity.

    Section 11 — Relative Grounds for Refusal

    These objections arise when the new trademark is found to be in conflict with an existing registered one. Similarity to existing marks — where the proposed name, logo, or style is found to be very close to a trademark already registered — is the primary trigger. Likelihood of confusion is also grounds: the products would be seen as related, and customers may be misled.

    Let’s break this down with an example: applying for “Microma” when “Micromax” is already registered in a related category would almost certainly attract a Section 11 objection.


    Step-by-Step: How to File Your Trademark Objection Reply Online

    You have to file your response against the objection within one month from the date of the examination report. It is a written submission where you convince the examiner that your mark is distinct. Here’s the exact process:

    Step 1 — Read the Examination Report Carefully

    Download the full report from the IP India portal. Identify precisely which section — 9 or 11 — has been invoked, and what specific grounds are cited. The report will refer to specific sections of the Trademarks Act. Understanding the exact reason for the objection determines your entire reply strategy.

    Step 2 — Draft a Persuasive Reply

    The reply must contain reasons, facts, supporting rules of law, judgments supporting the case, and evidence along with other supporting documents that validate the response. An affidavit stating the usage of the trademark in the applicant’s website and social media network, advertisements, and availability of trademarked products on e-commerce sites should also be included.

    Step 3 — File Online via the IP India Portal

    Log in to the IP India Filing Portal. Select the option to upload a reply to the examination report. Attach your response as a PDF with supporting documents. No physical copies need to be submitted — it’s entirely online.

    Step 4 — Wait for the Registry’s Response

    In case the response is accepted, objections can be waived on the basis of the applicant’s response and the registry will allow the trademark application to be advertised before registration in the Trademark Journal. The registry may also require additional clarifications, in which case a trademark show cause hearing will be scheduled and the applicant will be notified with a notice.


    Documents You Must Attach With Your Reply

    Don’t file a bare-bones reply. Supporting documents are what convince examiners. Here’s what you’ll typically need:

    • Affidavit of use — on Rs. 100 stamp paper, stating how long and how widely you’ve used the mark
    • Invoices and purchase orders bearing the trademark, showing commercial use
    • Website and social media screenshots showing the mark in active use
    • Advertising materials — print, digital, or outdoor — featuring the trademark
    • Sales data or turnover figures to establish market reputation (especially useful for Section 9 replies)
    • Relevant case laws — precedents from Indian courts where similar marks were allowed

    If you’re fighting a Section 11 objection, you’ll also want to build an argument around how your mark is visually, phonetically, and conceptually distinct from the cited mark. This is where legal expertise genuinely pays off. Lawizer’s trademark registration and reply services cover exactly this — online, without a CA visit.


    What Happens After You File: Hearings and Beyond

    Filing your reply doesn’t always close the matter. Here’s what can follow:

    If the reply is accepted: After the hearing, if the outcome is positive, the mark will be accepted and ordered to be published in the Trademark Journal. From there, there’s a four-month opposition window for third parties to challenge — but you’re essentially on the final stretch.

    If a hearing is called: There are some instances when the Examiner requests a hearing. You must go to the hearing well-prepared with your evidence, clarifications, and arguments. This is your opportunity to present your case in person before the Trademark Registrar. You can also send an authorised representative or a legal expert on your behalf.

    If the reply is rejected: In case there is a negative outcome at the hearing, a Refusal Order will be passed by the registry along with a statement of reasons for such refusal. You can then approach the Intellectual Property Appellate Board (IPAB) for a further appeal.

    What most founders miss: even a refusal at the hearing stage isn’t final. Appeals are possible, and many marks do get registered after the appellate process.


    Common Mistakes That Kill Trademark Applications

    Avoid these — they’re entirely preventable:

    • Missing the 30-day deadline. If you don’t file a reply, your trademark application will be treated as abandoned by the Registry. There’s no grace period built in automatically.
    • Filing a vague reply. A one-paragraph reply with no evidence and no case law is worse than no reply at all — it signals to the examiner that your case is weak.
    • Not checking the portal regularly. Always keep a track on the trademark examination report. The trademark inspector may call you in person to clear any doubts.
    • Confusing objection with opposition. An objection is raised by the authorities internally, not by a third party. When a third party challenges a trademark after publication, that process is referred to as trademark opposition. These are two entirely different proceedings with different timelines and processes.
    • Filing without doing a prior art search. A trademark public search should always be done before the application is filed — it would greatly reduce the chances of objections occurring.

    If you’re an MSME founder who’s already registered under Udyam, you have additional protections worth leveraging. Make sure your MSME registration is in order — it adds credibility to your trademark reply in terms of establishing business identity.

    Trademark Registration in India

    Frequently Asked Questions

    Q: What does “Objected” status mean on the IP India trademark portal?

    A: When your trademark application shows “Objected” on the IP India portal, it means the Trade Marks Examiner has reviewed your application and raised one or more formal concerns in an Examination Report. This is not a rejection — it’s an invitation to respond and defend your mark. You must download the Examination Report from the portal and file a reply within 30 days.

    Q: How long do I have to reply to a trademark objection in India?

    A: A reply to the trademark objection is required to be filed within 30 days of the date of the objection in the trademark examination report. Missing this window risks your application being treated as abandoned. If the status still shows “awaiting reply” after 30 days, you may still be able to file — but don’t rely on this.

    Q: Can I file a trademark objection reply myself, without a lawyer?

    A: Yes, you can file the TM objection reply on your own, but hiring a trademark attorney will always help as these people have the experience of drafting replies to the point. For straightforward Section 9 objections where your mark has clear distinctiveness, a self-filed reply with strong evidence can work. For Section 11 objections involving similarity to cited marks, expert legal help is strongly recommended.

    Q: What happens if my trademark objection reply is rejected?

    A: If the Examiner is not satisfied with your written reply, a Show Cause Hearing will be scheduled. You (or your representative) can appear before the Trademark Registrar and present your arguments in person. If the hearing outcome is also negative, a Refusal Order is issued — but you retain the right to appeal before the Intellectual Property Appellate Board (IPAB).

    Q: What is the difference between a trademark objection and a trademark opposition in India?

    A: A trademark objection is raised by the Trade Marks Examiner during the examination stage — it’s an internal proceeding between you and the registry. Trademark opposition, on the other hand, is raised by any person who has an issue with the trademark filed after it has been advertised in the Trademarks Journal for a period of four months. Opposition involves a third party; objection does not.

    Q: How long does it take for a trademark objection to be resolved after I file my reply?

    A: It generally takes 3–6 months for a reply to a trademark objection to be processed. If a hearing is scheduled, the timeline extends further depending on the registry’s backlog. The entire trademark registration process in India — from application to registration — can take 18–24 months in total, with objection resolution being one step along the way.


    Ready to fight your trademark objection — and win? Lawizer’s trademark experts handle the entire reply process for you — drafting the legal response, preparing affidavits, filing on the IP India portal — fully online, starting at just ₹1,499. No lawyer visit needed.

    File Your Trademark Objection Reply with Lawizer →


    Approximate word count: ~1,550 words

    Internal links used:

    1. https://lawizer.com/startup-businesslegal/protectbusiness/TrademarkRegistrationPage — anchor: “trademark registration and reply services” — Section: Documents You Must Attach
    2. https://lawizer.com/startup-businesslegal/growbusiness/MSMEUdhyamRegistrationPage — anchor: “MSME registration” — Section: Common Mistakes

    External links used:

    1. https://ipindiaonline.gov.in — IP India Portal (official government trademark portal)
    2. Quora community data — for founder pain points on deadline and reply format

    Schema: Add Article schema (auto via RankMath/Yoast) + FAQPage schema using all 6 Q&A blocks above. Images needed: 2 — recommended search: “trademark registration India startup” on Unsplash. Size: 1024×669px. Place after Section 2 and Section 4.

  • GST Composition Scheme: Is It Right for Your SmallBusiness in India?

    GST Composition Scheme: Is It Right for Your SmallBusiness in India?

    Over 14.79 lakh small businesses in India are already enrolled in the GST Composition Scheme — and paying tax at just 1% of their turnover instead of the standard 18%. If your annual sales are under ₹1.5 crore and monthly GST returns feel like a second job, you need to know about this option.

    The question isn’t whether the GST Composition Scheme exists. It’s whether it’s right for your business — right now.

    📌 TL;DR: The GST Composition Scheme is a simplified GST option for small businesses in India with annual turnover up to ₹1.5 crore (goods) or ₹50 lakh (services). Instead of regular monthly returns and complex ITC calculations, composition dealers pay a flat rate — 1% for traders/manufacturers, 5% for restaurants, 6% for service providers — and file just one annual return (GSTR-4). The trade-off: you can’t claim Input Tax Credit (ITC) and can’t sell inter-state. Lawizer can help you evaluate your eligibility and handle the opt-in process online in minutes.

    What You’ll Learn

    • What the GST Composition Scheme actually is and how it works under the CGST Act, 2017
    • Who is eligible — and who is specifically excluded from the scheme
    • The exact tax rates, filing forms, and deadlines for FY 2025–26
    • The real benefits and the hidden drawbacks founders often miss
    • How to decide if the Composition Scheme is right for your business

    What Is the GST Composition Scheme? A Plain-English Explanation

    Let’s break this down. The GST Composition Scheme is a simplified tax-paying mechanism introduced under Section 10 of the CGST (Central Goods and Services Tax) Act, 2017. It lets small, eligible businesses pay GST at a fixed, lower rate on their total turnover — instead of calculating tax on every individual transaction and dealing with monthly return filings on the GST portal (gst.gov.in).

    Here’s the thing: under the regular GST regime, a business files GSTR-1 (outward supplies) and GSTR-3B (summary return) every single month. That’s 24 returns a year, minimum. Under the Composition Scheme, you file CMP-08 (a quarterly tax payment challan) four times a year and GSTR-4 (annual return) once. That’s five filings total. For a kirana store in Kolkata or a textile trader in Surat, this reduction in paperwork is genuinely significant.

    The scheme has been available since GST launched in July 2017, but it was expanded in 2019 to include service providers as well — a move that opened it up to a much wider group of small businesses across India.

    GST Composition Scheme Eligibility: Who Can and Cannot Opt In

    Not every business qualifies. The eligibility rules under the Composition Scheme are specific, and getting this wrong can attract penalties. Here’s who can opt in for FY 2025–26.

    Who Is Eligible

    • Manufacturers and traders of goods — annual aggregate turnover up to ₹1.5 crore (₹75 lakh for special category states like Arunachal Pradesh, Manipur, Meghalaya, Mizoram, Nagaland, Sikkim, Tripura, and Uttarakhand)
    • Restaurants not serving alcohol — turnover up to ₹1.5 crore
    • Service providers (introduced in 2019) — annual turnover up to ₹50 lakh
    • Business must operate within a single state (intra-state supply only)

    Who Is NOT Eligible

    • Businesses making inter-state outward supplies of goods
    • Businesses selling through e-commerce platforms that collect Tax at Source (like Amazon, Flipkart, or Meesho)
    • Manufacturers of ice cream, pan masala, tobacco, and notified goods
    • Businesses supplying non-taxable goods under GST
    • Any business registered under GST in multiple states — if one registration is ineligible, all are

    What most founders miss: if you sell even one interstate order — say, a Delhi manufacturer shipping to a client in Pune — you lose eligibility for the scheme entirely for that financial year. So think carefully about your supply chain before opting in.

    Small business owner in India at shop checking GST composition scheme eligibility on laptop

    [NOTE TO INTERN: Replace REPLACE_WITH_IMAGE_URL with actual uploaded image URL from WordPress Media Library. Recommended size: 1024×669px. Search “small business owner India shop GST” on Unsplash/Pexels.]

    GST Composition Scheme Tax Rates for FY 2025–26

    The short answer: composition dealers pay far less than regular GST rates — and pay it out of their own pocket (not charged to customers). Here’s the full breakdown of rates applicable for FY 2025–26.

    • Manufacturers and Traders of Goods: 1% of turnover (0.5% CGST + 0.5% SGST)
    • Restaurants not serving alcohol: 5% of turnover (2.5% CGST + 2.5% SGST)
    • Service Providers (and mixed supply businesses): 6% of turnover (3% CGST + 3% SGST)

    A quick example: if you’re a saree trader in Varanasi with an annual turnover of ₹80 lakh, your GST liability under the Composition Scheme is just ₹80,000 per year (1% of ₹80 lakh). Under the regular 12% GST rate on textiles, your liability would have been far higher depending on your margins and ITC claims. That’s a real saving, especially if your input tax credit is low because you source from unregistered local suppliers.

    One critical note: composition dealers cannot charge GST from customers. You must issue a “Bill of Supply” instead of a tax invoice, and the tax comes out of your own margin. You must also display “Composition Taxable Person, not eligible to collect tax on supplies” on all invoices and at your place of business — this is a legal requirement under GST rules.

    Filing Requirements: What Forms Do You Actually Need to File?

    This is where the Composition Scheme genuinely saves time. The compliance calendar is dramatically simpler than the regular GST regime. Here’s exactly what you need to file and when.

    CMP-08 — Quarterly Tax Payment

    CMP-08 is a quarterly challan for self-assessed tax payment. You file it four times a year — by the 18th of the month following each quarter (so April 18, July 18, October 18, and January 18). This is not a full return; it simply captures your outward supplies and the tax due for that quarter. Payment is made directly via the GST portal under Services → Payments → Create Challan. Critically: you cannot revise CMP-08 after submission, so double-check your turnover figures before filing.

    GSTR-4 — Annual Return

    GSTR-4 is your annual return summarising all outward supplies, inward supplies attracting reverse charge, and consolidated tax paid for the year. For FY 2025–26, GSTR-4 is due by April 30, 2026. This single annual return replaces the 24 monthly returns that regular GST taxpayers file. File it late and you face penalties — and repeated late filings can even result in loss of scheme eligibility.

    ITC-03 — One-Time ITC Reversal When You Switch In

    When you first opt into the Composition Scheme from the regular GST regime, you must file ITC-03 within 60 days to reverse any input tax credit (ITC) you had accumulated. This is a one-time requirement, but it’s non-negotiable. Failing to file ITC-03 on time is a common mistake that catches first-time composition taxpayers off guard.

    GST filing calendar India composition scheme CMP-08 GSTR-4 deadlines small business

    [NOTE TO INTERN: Replace REPLACE_WITH_IMAGE_URL with actual uploaded image URL from WordPress Media Library. Recommended size: 1024×669px. Search “India tax filing compliance calendar” on Unsplash/Pexels.]

    Real Benefits of the GST Composition Scheme for Small Businesses

    It’s not just about lower tax rates. The Composition Scheme changes the day-to-day compliance reality for small businesses. Here’s what you actually gain.

    • Drastically fewer filings: 5 filings per year instead of 24+ under the regular regime. That’s hours of saved time and lower CA fees annually.
    • Predictable tax outflow: Because you pay a fixed percentage of turnover — not a variable margin-based calculation — cash flow planning becomes straightforward. No nasty surprises at return time.
    • No ITC reconciliation headaches: Regular GST filers spend significant effort matching GSTR-2B with purchase records to claim ITC. Composition dealers skip this entirely.
    • Lower compliance costs: Less CA or tax consultant time means real money saved — particularly relevant for micro-businesses in cities like Coimbatore, Jaipur, or Indore where margins are already thin.
    • January 2025 relief: The GST Council’s 55th meeting (December 2024) excluded composition dealers from Reverse Charge Mechanism (RCM) liability on renting of commercial properties from unregistered persons — a meaningful compliance relief that took effect from January 16, 2025.

    If you’re also registered as an MSME, combining the Composition Scheme with your MSME Udyam Registration gives you access to priority lending, government tenders, and protection under the MSMED Act — all while keeping your GST compliance lean.

    The Drawbacks You Must Know Before Opting In

    Here’s where most articles go soft. The Composition Scheme has real limitations — and for certain businesses, they’re dealbreakers. Be honest with yourself about whether these apply to you.

    • No Input Tax Credit (ITC): You cannot claim GST paid on your purchases as credit. If your suppliers charge 18% GST on raw materials or goods, that cost sits in your books with no offset. For businesses with high-value taxable inputs, this can wipe out the benefit of the lower output tax rate.
    • No inter-state sales of goods: You cannot supply goods outside your state. One interstate order disqualifies you. This is a serious constraint for businesses looking to grow nationally.
    • No e-commerce sales (for goods): Selling on Meesho, Amazon, or Flipkart? If these platforms collect Tax Collected at Source (TCS), you’re automatically ineligible. This blocks a huge growth channel for many small product businesses.
    • Can’t issue tax invoices: Your B2B buyers cannot claim ITC on purchases from you. Large corporate buyers almost always want a tax invoice for ITC. This makes composition dealers unattractive suppliers in the B2B supply chain — a major competitive disadvantage if your customers are GST-registered businesses.
    • Compliance penalties still apply: The scheme is simpler — but not penalty-free. Over ₹500 crore in penalties were levied on composition dealers for non-compliance in FY 2024–25. Missing CMP-08 or GSTR-4 deadlines has real consequences.

    What most founders miss: if your business primarily sells to other businesses (B2B), the Composition Scheme can actually hurt your competitiveness. Your buyers can’t claim ITC on your invoices, which effectively makes you a more expensive supplier compared to a regular GST dealer — even if your prices are the same. Think carefully about your customer profile before making this decision. If you need help understanding which GST structure suits your business, Lawizer’s business compliance experts can walk you through the right options.

    How to Opt Into the GST Composition Scheme: Step by Step

    The opt-in process is entirely online through the GSTN (Goods and Services Tax Network) portal. Here’s exactly how it works.

    For Existing GST Taxpayers Switching to the Composition Scheme

    • Step 1: Log in to the GST portal at gst.gov.in using your GSTIN and credentials.
    • Step 2: Go to Services → Registration → Application to Opt for Composition Levy.
    • Step 3: Fill and submit Form CMP-02 — this is the formal opt-in form. You must do this before the start of the financial year (i.e., by March 31 to opt in for the following FY).
    • Step 4: Within 60 days of opting in, file ITC-03 to reverse any accumulated Input Tax Credit from your previous regular GST registration.

    For New GST Registrations

    If you’re registering for GST for the first time, you can opt for the Composition Scheme at the time of registration itself by selecting the appropriate option in the GST registration form. You don’t need to separately file CMP-02 in this case. If you need help with a fresh GST registration, Lawizer handles the entire process online — no CA visit needed.

    To opt out — either voluntarily or because your turnover crossed the threshold — file Form CMP-04 and then switch to the regular GST regime from the next day onwards.

    Should Your Business Actually Opt for the Composition Scheme?

    Let’s be direct. The Composition Scheme is a strong fit for some businesses and completely wrong for others. Here’s a quick decision framework.

    The Composition Scheme is likely RIGHT for you if:

    • You’re a local retailer, kirana store, or small manufacturer selling entirely within your state
    • Most of your customers are end consumers (B2C) who don’t need a tax invoice for ITC
    • You have low taxable inputs — i.e., your purchases attract little or no GST (e.g., you source from unregistered farmers or small suppliers)
    • Your annual turnover is comfortably below the threshold (no risk of crossing ₹1.5 crore mid-year)
    • You value simplicity and predictability over maximising every possible tax credit

    The Composition Scheme is likely WRONG for you if:

    • You sell B2B and your clients need ITC-eligible tax invoices from you
    • You sell through e-commerce platforms (Meesho, Amazon, Flipkart) that deduct TCS
    • You plan to expand to customers in other states
    • You have significant GST-paid inputs where ITC would meaningfully reduce your tax bill
    • Your turnover is growing fast and might cross ₹1.5 crore within the year

    Frequently Asked Questions

    Q: What is the turnover limit for the GST Composition Scheme in 2025?

    A: For manufacturers and traders of goods, the annual aggregate turnover limit is ₹1.5 crore (₹75 lakh for special category states including Arunachal Pradesh, Manipur, Meghalaya, Mizoram, Nagaland, Sikkim, Tripura, and Uttarakhand). For service providers who opt under the composition scheme (introduced in 2019), the turnover limit is ₹50 lakh. These thresholds are based on turnover in the preceding financial year and are verified at the time of opting in.

    Q: Can I sell on Amazon or Flipkart if I’m under the GST Composition Scheme?

    A: No. If you sell goods through e-commerce operators like Amazon, Flipkart, or Meesho that collect Tax Collected at Source (TCS), you are not eligible for the GST Composition Scheme. This is one of the most important restrictions, especially for small product businesses. If you operate through your own website or sell directly to customers offline, the e-commerce restriction does not apply.

    Q: What happens if my turnover crosses ₹1.5 crore mid-year while I’m on the Composition Scheme?

    A: If your aggregate turnover exceeds the applicable threshold during a financial year, you become ineligible for the Composition Scheme from the very day the limit is breached. You must file Form CMP-04 to opt out and then register under the regular GST regime from that date onwards. You’ll also need to start issuing tax invoices, file regular returns, and comply with normal GST requirements going forward. It’s important to monitor your turnover closely throughout the year.

    Q: Can a service provider opt for the GST Composition Scheme in India?

    A: Yes, service providers can opt for the Composition Scheme, but with a lower turnover threshold of ₹50 lakh (not ₹1.5 crore). Under this option — sometimes called the “composition scheme for service providers” — eligible businesses pay GST at a flat rate of 6% of turnover and file CMP-08 quarterly and GSTR-4 annually. This was introduced via a notification in 2019. However, service providers supplying services through e-commerce operators or making inter-state supplies are still excluded.

    Q: How do I opt into the GST Composition Scheme for the next financial year?

    A: To opt into the Composition Scheme for a new financial year, you need to file Form CMP-02 on the GST portal (gst.gov.in) before March 31 of the current financial year. Go to Services → Registration → Application to Opt for Composition Levy and submit the form online. Within 60 days of opting in, you must also file ITC-03 to reverse any Input Tax Credit previously accumulated. New registrants can opt for the scheme directly at the time of GST registration without needing a separate CMP-02 filing.

    Q: Can a composition dealer claim Input Tax Credit (ITC) on purchases?

    A: No. One of the fundamental conditions of the GST Composition Scheme is that registered composition dealers cannot claim Input Tax Credit on any purchases. This means the GST you pay on raw materials, goods, or services purchased for your business cannot be offset against your output tax liability. This is the single biggest financial consideration when deciding whether the scheme is right for your business — if your input GST is significant, the regular regime with ITC may work out cheaper overall.

    Ready to sort your GST compliance the right way?
    Lawizer’s experts handle everything — GST registration, Composition Scheme opt-in, MSME Udyam registration — fully online, starting at just ₹499. No CA visit needed.

    Get started with Lawizer

  • Udyam Registration: MSME Benefits, Eligibility & How to Apply Online

    Udyam Registration: MSME Benefits, Eligibility & How to Apply Online

    India has 7.86 crore registered MSMEs employing over 34 crore people — and yet thousands of eligible business owners still haven’t claimed their Udyam Registration. That one free certificate unlocks collateral-free loans up to ₹5 crore, government tender preferences, tax exemptions, and legal protection against delayed payments.

    If your business qualifies and you haven’t registered yet, you’re leaving real money — and real protection — on the table.

    📌 TL;DR: Udyam Registration is a free, fully online MSME certification issued by the Government of India that gives your business access to collateral-free loans, priority government tenders, tax benefits, and payment protection under the MSMED Act 2006. Any micro, small, or medium enterprise in manufacturing or services can apply in under 15 minutes at udyamregistration.gov.in — all you need is your Aadhaar and PAN. Lawizer can help you complete and verify the process without errors.

    What You’ll Learn

    • What Udyam Registration is and how it replaced Udyog Aadhaar
    • Exact MSME eligibility criteria and classification limits (updated April 2025)
    • Every major benefit your business gets after registration
    • Step-by-step process to apply online and get your certificate instantly
    • Common mistakes founders make and how to avoid them

    What Is Udyam Registration? (And Why Udyog Aadhaar No Longer Counts)

    Udyam Registration is the official government certification that recognises your business as an MSME — a Micro, Small, or Medium Enterprise — under the MSMED Act, 2006 (Micro, Small and Medium Enterprises Development Act).

    The Ministry of Micro, Small and Medium Enterprises launched the Udyam portal on July 1, 2020, replacing the older Udyog Aadhaar Memorandum (UAM) system entirely. If you registered under UAM before July 2020, that certificate is no longer valid for most benefits — you need to migrate to Udyam.

    Here’s the thing. Udyam isn’t just a piece of paper. It’s your business’s formal identity in India’s lending, procurement, and compliance ecosystem. Banks verify your Udyam Registration Number (URN) before approving priority-sector loans

    . Government departments check it before issuing tender preferences. And the MSME Samadhaan portal — the government’s delayed payment dispute system — requires a valid URN before you can file a complaint against a buyer who hasn’t paid. Without it, none of that is accessible.

    The registration is completely free, paperless, and self-declaration based. You don’t upload any physical documents. The system cross-verifies your details automatically using your PAN and GST data linked to Income Tax records.

    What most founders miss: the certificate has lifetime validity, so you register once and you’re covered as long as you update your details annually.

    MSME Eligibility: Who Can Apply for Udyam Registration?

    Any business in India — manufacturing or services — can apply for Udyam Registration if it falls within the classification limits set by the government. The criteria were updated effective April 1, 2025, expanding the thresholds to reflect how businesses actually scale today.

    Retail and wholesale traders were also made fully eligible from July 2021 onward, which was a major change that most small shop owners in cities like Kolkata, Mumbai, and Chennai are still unaware of.

    Updated MSME Classification Limits (w.e.f. April 1, 2025)

    Enterprise Type Investment in Plant & Machinery Annual Turnover
    Micro Up to ₹1 crore Up to ₹5 crore
    Small Up to ₹10 crore Up to ₹50 crore
    Medium Up to ₹50 crore Up to ₹250 crore

    A quick example: a Bengaluru-based SaaS service firm with ₹8 crore in equipment investment and ₹40 crore in annual turnover qualifies as a Small Enterprise. It can register on Udyam and access enhanced credit guarantees introduced under Budget 2025.

    Note that export turnover is excluded when calculating your threshold — only domestic turnover counts. And if your business grows and crosses limits, reclassification happens automatically — no penalty, as long as you’ve been reporting honestly.

    Any business structure is eligible — sole proprietorships, partnerships, LLPs, private limited companies, OPCs, and even Hindu Undivided Families (HUFs). The only businesses that can’t apply are those exceeding the medium enterprise limits, non-profits, government departments, and fully informal freelancers with no structured operations.

    If you want to structure your business correctly before applying, Lawizer’s startup and business legal services can help you pick the right entity type first.

    Key Benefits of Udyam Registration for Your Business

    Let’s break this down. Once you have your Udyam certificate, you’re not just “registered” — you get access to a stack of financial, legal, and market benefits that most unregistered businesses have zero access to.

    🏦

    1. Collateral-Free Loans Under CGTMSE

    The Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE) allows registered MSMEs to access collateral-free loans up to ₹5 crore, with guarantee coverage of up to 85% for eligible categories. Since inception, over ₹9.80 lakh crore in credit guarantees have been approved — and in FY 2024-25 alone, the government extended ₹3 lakh crore worth of guarantees. For a small founder who can’t mortgage property, this is transformative.

    📉

    2. Priority Sector Lending and Lower Interest Rates

    Banks are mandated by the Reserve Bank of India to lend to the MSME sector as part of Priority Sector Lending (PSL) requirements. This means registered MSMEs often get faster loan approvals, lower interest rates, and a 1% exemption on interest for bank overdraft (OD) facilities. Under the Pradhan Mantri Mudra Yojana (PMMY), over ₹33.65 lakh crore has been sanctioned across 52.37 crore Mudra loans since inception.

    ⚖️

    3. Protection Against Delayed Payments

    The MSMED Act gives you a legal right to receive payments within 45 days of delivering goods or services. If a buyer delays, they owe you compound interest at three times the bank rate. You can file a complaint on the MSME Samadhaan portal — routed to a Micro and Small Enterprises Facilitation Council (MSEFC) in your state. This protection is only available to Udyam-registered businesses.

    📋

    4. Government Tender Preferences

    No global tenders are invited for government procurement contracts valued up to ₹200 crore — reserving a huge pool of contracts exclusively for Indian MSMEs. Registered businesses also get a price preference of up to 15% in government procurement under the Public Procurement Policy. If your business sells products or services that government departments buy, this single benefit can transform your revenue pipeline.

    💸

    5. Tax Benefits and Subsidies

    Udyam-registered businesses are eligible for subsidies on patent registration, trademark fees, and industrial promotion. Several state governments also offer reduced electricity tariffs and stamp duty exemptions. If you’ve already registered your trademark, Lawizer’s trademark registration services can help you combine those savings with your MSME status for maximum benefit.

    How to Apply for Udyam Registration Online: Step-by-Step

    The good news: the entire process takes 10–15 minutes and is completely free on the official Udyam Registration Portal (udyamregistration.gov.in). Here’s exactly how it works.

    Documents You’ll Need (Keep These Ready)

    • Aadhaar number of the proprietor, managing partner, or authorised director (linked to a working mobile number for OTP)
    • PAN card of the business or individual
    • GSTIN (mandatory if your turnover exceeds the GST threshold)
    • Bank account details and NIC (National Industrial Classification) code for your business activity

    Step-by-Step Application Process

    1. 1
      Visit the Portal Go to udyamregistration.gov.in and click “For New Entrepreneurs who are not Registered yet as MSME”
    2. 2
      Aadhaar Validation Enter your Aadhaar number and name, then validate via OTP sent to your Aadhaar-linked mobile
    3. 3
      PAN Verification Enter your PAN — the system auto-verifies with the Income Tax database instantly
    4. 4
      Fill Enterprise Details Business name, activity type (manufacturing/service/trade), address, bank details, investment amount, turnover, employee count, and 2-digit NIC code
    5. 5
      Submit The portal cross-verifies your data with GST and ITR records automatically — no manual upload needed
    6. 6
      Download Certificate Your Udyam Registration Certificate with unique URN and QR code is issued instantly

    Common Mistakes to Avoid During Udyam Registration

    Most errors during Udyam registration come from small oversights — but they can delay benefits or cause classification mismatches. Here are the ones that come up most often.

    ❌ Using an unlinked Aadhaar: Your Aadhaar must be linked to your current mobile number. If it’s not, update your mobile at the nearest Aadhaar Seva Kendra before starting the application.
    ❌ Entering wrong investment figures: Investment refers to the value of plant, machinery, or equipment — not land or buildings. Many applicants accidentally include property values and get classified in a higher tier.
    ❌ Including export turnover: Export sales must be excluded from your annual turnover calculation. Including them inflates your figure and may push you into a higher MSME category unnecessarily.
    ❌ Registering through paid agents on unofficial portals: The government process is 100% free. Many third-party websites charge ₹500–₹2,000 for a form you can fill in 10 minutes on the official portal. Always use udyamregistration.gov.in.
    ❌ Not updating figures annually: If your investment or turnover has grown, failing to update means you’re in the wrong MSME category — which can affect your benefit eligibility.

    Frequently Asked Questions

    Q) Is Udyam Registration free or do I need to pay a government fee?

    Udyam Registration is completely free on the official government portal at udyamregistration.gov.in. There is no government fee at any stage of the application. If any website is charging you for registration, it is a private agent — not the official process. You only pay if you choose to hire a professional to assist with the filing.


    Q) Can a private limited company or LLP apply for Udyam Registration?

    Yes. Any business entity — sole proprietorship, partnership firm, LLP, private limited company, OPC, or HUF — can apply for Udyam Registration, provided it falls within the investment and turnover limits for micro, small, or medium enterprises. The Aadhaar used for verification should belong to the authorised signatory — the proprietor, a managing partner, or a director — depending on the business structure.

    Q) What is the difference between Udyam Registration and Udyog Aadhaar?

    Udyog Aadhaar (UAM) was the older MSME registration system discontinued on July 1, 2020. It has been fully replaced by Udyam Registration. Businesses that registered under UAM must migrate to the new Udyam portal to continue receiving MSME benefits. The Udyam system is more robust — it cross-verifies data with PAN, GST, and Income Tax records automatically, making classification more accurate and fraud-resistant.

    Q) Does Udyam Registration need to be renewed every year?

    No. Udyam Registration has lifetime validity — there is no annual renewal required. However, you are expected to update your investment and turnover figures on the Udyam portal at the end of each financial year to ensure your MSME classification remains accurate. Failing to update does not cancel your registration, but it may result in incorrect classification over time.


    Q) Can retail and wholesale traders apply for Udyam Registration?

    Yes. Since July 2, 2021, retail and wholesale traders have been eligible to register under Udyam, provided their investment and turnover fall within MSME classification limits. This change opened access to MSME benefits — including priority sector lending and payment protection — to a much larger group of businesses that was previously excluded from the scheme

    Q) How long does it take to get the Udyam Registration Certificate after applying?

    The certificate is issued instantly after successful submission of the application on the Udyam portal. Once your Aadhaar is verified via OTP and the system validates your PAN and GST data, your Udyam Registration Number (URN) and downloadable certificate are generated immediately. You can download and reprint the certificate at any time by logging in with your URN and Aadhaar OTP.

    Ready to get your Udyam Registration done right?

    Lawizer’s experts handle everything — MSME registration, business incorporation, and startup compliance — fully online, starting at just ₹499. No CA visit needed.

    Get Your Udyam Certificate Today →

  • Trademark Registration in India: A No-Jargon Guide for First-Time Founders

    Trademark Registration in India: A No-Jargon Guide for First-Time Founders

    ndia filed over 5.5 lakh trademark applications in FY 2024–25. This reflects a 20% jump compared to the previous year, according to the CGPDTM Annual Report 2024–25.

    Yet most first-time founders still don’t know whether their brand name is even available. Many also have no idea how the registration process actually works.

    If you’ve built something worth protecting, this guide gives you the full picture — no legalese, no guesswork.

    📌 TL;DR: Trademark registration in India protects your brand name, logo, or tagline from being copied or misused. You file the application through the IP India portal (ipindia.gov.in). The process is governed by the Trade Marks Act, 1999.It typically takes 12–18 months. For individuals and startups, the cost is ₹4,500–₹5,000 per class Lawizer helps founders complete the entire trademark registration process online — from availability search to filing — starting at ₹1,499.

    What You’ll Learn

    • What a trademark actually protects — and what it doesn’t
    • The step-by-step trademark registration process in India
    • How to pick the right trademark class (this is where most founders go wrong)
    • Exact fees, realistic timelines, and what TM™ vs ® actually means
    • What happens if you get an objection or opposition

    What Is a Trademark — And What Exactly Does It Protect?

    A trademark is any mark — a word, name, logo, slogan, colour, or even a sound — that distinguishes your goods or services from everyone else’s.

    Under the  Trade Marks Act, 1999, registering a trademark gives you exclusive rights to use it.
    You can use that mark only for your registered category of business.

    Here’s the thing: trademark protection is narrow by design. It doesn’t protect your entire business — it protects a specific mark in a specific category of goods or services.

    That’s why a clothing brand and a software company can both use the same word as their name.
    They just need to operate in different trademark classes.

    What a trademark does protect you against is someone else in your industry riding on your brand’s goodwill — copying your logo, launching a near-identical name, or confusing your customers. Once you register, you can sue for infringement, seek damages, and get counterfeit products seized at customs.

    TM™ vs ® — What’s the Difference?

    This confuses a lot of founders. The ™ symbol means you’re claiming rights over the mark — anyone can use it, even without registration.

    The ® symbol is legally reserved for marks that have received a registration certificate from the CGPDTM (Office of the Controller General of Patents, Designs and Trade Marks — the government body that manages all IP filings in India). Using ® before your registration is complete is actually a punishable offence under the Trade Marks Act.

    Step-by-Step: How Trademark Registration in India Works

    Let’s break this down. The process runs through five broad stages, and knowing each one helps you avoid the delays that catch most first-time applicants off guard.

    Step 1: Trademark Search

    Before you file anything, run a search on the IP India public search portal to check if your mark — or anything confusingly similar — is already registered or pending.

    What most founders miss: searching for an identical name isn’t enough. The Trade Marks Act also blocks marks that are “deceptively similar,” so a slight spelling variation or phonetically similar name can still get your application rejected.

    Step 2: Choose Your Trademark Class

    India follows the Nice Classification system — an international framework that divides all goods and services into 45 classes (Classes 1–34 for goods, Classes 35–45 for services). You must file your application under the specific class that covers what your business sells.

    A quick example: a SaaS startup would typically file under Class 42 (software and technology services), while a food brand would file under Class 30 or Class 43. Getting this wrong means your trademark won’t protect you where it actually matters.

    Step 3: File Your Application

    Applications are filed online through the IP India portal using Form TM-A. You’ll need your applicant details, a clear representation of the mark, the class(es) you’re applying under, and a list of goods or services.

    The fee is paid at the time of filing. The moment you submit, you receive an allotment number — this lets you track your application status online, and from this date, your trademark rights are considered to have priority.

    Step 4: Examination by the Trade Marks Registry

    An examiner at the Trade Marks Registry reviews your application. They may raise objections — called an Examination Report — if the mark is too generic, descriptive, or conflicts with an existing mark.

    You have one month from receiving the report to file a reply. If you respond well, the examiner accepts the application. If not, a hearing is scheduled.

    Step 5: Publication in the Trademark Journal

    Once accepted, the mark is published in the official Trademark Journal. This opens a 4-month window for third parties to oppose your registration.

    If no opposition is filed (or if opposition is overcome), you receive your registration certificate and can legally use the ® symbol.

    Trademark Registration Fees in India (2025)

    The short answer: it’s more affordable than most founders assume. The official government fee structure is tiered based on applicant type. Here’s what you’ll pay per class:

    • Individuals, Startups, and Small Enterprises: ₹4,500 per class (online filing)
    • Companies, LLPs, and Partnerships: ₹9,000 per class (online filing)
    • Physical filing (all applicants): Higher fees apply — online is always recommended

    Add professional fees (₹3,000–₹8,000 if you use an agent or service), and the total typically lands between ₹7,500 and ₹18,000 for a single-class application. With Lawizer’s trademark registration service, you get expert filing support starting at ₹1,499, so you’re not paying CA-level fees for something that can be handled online.

    How Long Does Trademark Registration Take in India?

    Realistically, 12–18 months for an uncontested application — and longer if there’s an objection or opposition. The good news: you don’t have to wait for registration to use your brand commercially.

    The moment you file and receive your allotment number, your priority date is established — meaning you have legal standing to challenge anyone who files a similar mark after you.

    A quick example: two startups both want to register “Zelo” as a brand name. Startup A files in January, Startup B files in March. Even if Startup A’s registration takes 18 months, their January filing date gives them priority over Startup B — regardless of who gets the certificate first.

    What Happens If You Get a Trademark Objection?

    Don’t panic — it’s more common than you think. An Examination Report (objection) from the Trade Marks Registry typically flags one of two things: the mark is too descriptive or generic, or it’s confusingly similar to an existing mark.

    Here’s the thing: an objection is not a rejection. You have one month to file a detailed written reply explaining why your mark is distinctive and should be registered.

    If the examiner isn’t satisfied with the written response alone, they’ll call for a hearing. Founders who work with experienced IP professionals at this stage have significantly better outcomes.

    If a third party files an opposition during the 4-month Trademark Journal publication window, that’s a separate (and more serious) proceeding. Both sides present evidence and arguments to the Trade Marks Registry.

    Opposition proceedings can add 1–3 years to the timeline, which is why a thorough search before filing is non-negotiable.

    Who Needs Trademark Registration — And When Should You File?

    The honest answer is: if you’re building a brand you plan to grow, register as early as possible. India is a first-to-file system, which means the person who files first generally wins the rights — not the person who used the name first (unlike the US, which has a first-to-use system).

    A competitor, copycat, or even a trademark troll can file your brand name before you do and create a legal headache that costs far more to resolve than the original registration would have.

    Practically speaking, you should consider filing your trademark when you’ve finalised your brand name or logo, even before your product launches. You can file as an individual, a startup, an MSME (under the Udyam Registration framework), an LLP, or a private limited company.

    Startups registered under the Startup India scheme also get a 50% concession on official trademark fees — a significant saving worth claiming.

    If you’re also thinking about protecting your business structure itself — like choosing between an OPC, LLP, or Pvt Ltd — the Lawizer startup legal hub covers all of that in one place.

    Frequently Asked Questions

    Q: How many trademark classes do I need to register under?

    A: It depends on your business. India follows the 45-class Nice Classification system, and your trademark only protects you within the classes you’ve registered under. If your startup sells both a physical product and a software service, you’ll likely need two separate class filings — each with its own fee. A trademark agent or legal service like Lawizer can help you identify the right class(es) based on what your business actually does

    Q: What if someone copies my brand name before I register?

    A: Without a registered trademark, your legal options are limited to a “passing off” claim — a common law remedy that requires you to prove established goodwill, misrepresentation, and damage. It’s expensive and difficult to win. With a registered trademark, you have much stronger grounds: you can file an infringement suit, seek an injunction, and claim damages.

    Q: How long is a registered trademark valid in India?

    A: A registered trademark in India is valid for 10 years from the date of application. It can then be renewed indefinitely for successive 10-year periods by paying the renewal fee. If you miss the renewal deadline, there’s a 6-month grace period with a surcharge — but after that, the mark can lapse and become available for others to register.

    Q: Can a freelancer or individual (not a company) register a trademark in India?

    A: Yes, absolutely. Under Section 18 of the Trade Marks Act, 1999, any person claiming to be the proprietor of a trademark can file an application — this includes individuals, freelancers, sole proprietors, startups, and companies. Individuals and startups also pay the lower government fee of ₹4,500 per class (online), compared to ₹9,000 for companies.

    Q: What documents do I need to file a trademark application in India?

    A: For most applicants, the core documents are: a clear image of the trademark (JPG format, under 500KB), the applicant’s name and address, a list of goods or services under the chosen class, and identity/address proof. If you’re a startup claiming the 50% government fee concession, you’ll also need your DPIIT Startup India recognition certificate.

  • What Happens If You Miss Your ROC Annual Filing Deadline?

    What Happens If You Miss Your ROC Annual Filing Deadline?

    ₹100 per day. No upper cap. The MCA (Ministry of Corporate Affairs) charges this late fee on every form filed after the ROC annual return deadline. The clock starts ticking the very next day. Miss AOC-4 and MGT-7 by just 78 days. The MCA will charge over ₹12,400 in penalties before you even factor in legal fees.

    And that’s just the financial hit. If you miss your filings for three consecutive years, the MCA can deactivate your directors’ DINs and prevent them from serving in any company for five years.

    📌 TL;DR: Missing your ROC annual filing deadline triggers an automatic penalty of ₹100 per day per form — with no maximum cap — under the Companies Act 2013. For a private limited company in India, this means AOC-4 and MGT-7 penalties compound simultaneously.

    If filings are missed for three consecutive financial years, directors face disqualification under Section 164(2) and lose their DIN across all companies. Lawizer can help you file late returns, clear penalties, and get your company back to compliant status — fully online.

    What You’ll Learn

    • Exact due dates for AOC-4, MGT-7, and MGT-7A — and when the penalty clock starts
    • How the ₹100/day penalty compounds across multiple forms and multiple years
    • What director disqualification under Section 164(2) actually means for you
    • The risk of company strike-off and how MCA initiates it
    • Steps to fix late filings and get back to compliance fast

    First, Let’s Get the Deadlines Straight

    Here’s the thing — most founders don’t miss the deadline deliberately. They miss it because they don’t know exactly when it falls.

    ROC filing deadlines are pegged to your AGM (Annual General Meeting) date, not a fixed calendar date, which trips up a lot of first-time company owners. Under MCA’s compliance framework, every private limited company must hold its AGM by September 30 each financial year.

    Once your AGM date is set, here’s exactly how the filing windows work:

    • Form AOC-4 (financial statements — balance sheet, P&L, auditor’s report): due within 30 days of the AGM. For a September 30 AGM, that’s October 29.
    • Form MGT-7 (annual return — shareholding, director details, compliance summary): due within 60 days of the AGM. For a September 30 AGM, that’s November 28.
    • Form MGT-7A (for OPCs and small companies): same 60-day window as MGT-7, but a simplified format.

    What most founders miss: even if your company had zero revenue, zero transactions, or zero employees, you still have to file. There are no exemptions for dormant or “inactive” companies under the Companies Act 2013. A NIL return is still a required return.

    The ₹100/Day Penalty — And Why It Adds Up Faster Than You Think

    The moment your filing window closes, the late fee kicks in automatically. The MCA charges ₹100 per day per form, with no ceiling. Let’s break this down with a real example.

    Say your AGM was on September 30, 2025. Your AOC-4 deadline is October 29, and your MGT-7 deadline is November 28. If you file both on January 15, 2026:

    AOC-4 — 78 days late

    MGT-7 — 48 days late

    Total late fees

    How to Calculate Your Penalty on the MCA Portal

    You don’t have to guess. The MCA21 portal has a built-in fee calculator. Go to MCA Services → Fee & Payment Services → Calculate Fee, select your form and the date you plan to file, and it will show you the exact late fee before you proceed.

    Director Disqualification Under Section 164(2) — The Real Danger

    Paying a penalty is painful but recoverable. Director disqualification is a different beast entirely. Under Section 164(2)(a) of the Companies Act 2013, if your company fails to file its financial statements or annual returns for any continuous period of three financial years, every director of that company gets disqualified — automatically, without a hearing.

    Here’s what disqualification actually means. Your DIN (Director Identification Number — your unique director identity issued by the MCA) gets deactivated. You can’t be appointed as a director in that company or any other company for five years. In 2017, over 3.09 lakh directors across India were disqualified in a single sweep.

    A quick example: a Mumbai-based founder running three companies — one dormant, two active — who forgot to file for the dormant entity found himself locked out of all three companies. No board resolutions, no bank account signings, no compliance filings. For five years.

    Which Financial Years Put You in the Danger Zone Right Now?

    In 2026, companies that missed filings for FY 2022-23, FY 2023-24, and FY 2024-25 are entering the three-year non-compliance window. If your company is in this group, you need to act before the ROC acts.

    What Happens to the Company Itself — Strike-Off Risk

    Beyond director-level consequences, the company itself faces a serious threat: strike-off from the MCA register. Under Section 248 of the Companies Act 2013, the Registrar of Companies can remove a company’s name from the register if it’s in default of filing requirements.

    • Bank accounts can be frozen after the company is flagged as a defaulter by the ROC
    • Investors and banks check MCA21 compliance status before approving funding or loans
    • A non-compliant MCA record makes due diligence fail — fatal for startups in fundraising mode
    • Revival via NCLT petition is possible but involves legal fees, time, and court appearances

    How to Fix a Missed Filing — Your Step-by-Step Recovery Plan

    The short answer: file now, even if you’re late. Every day you wait adds ₹100 to each outstanding form, and you inch closer to the disqualification threshold

    Step 1

    Check pending years on MCA21

    Step 2

    Get financials audited by a CA

    Step 3

    File AOC-4 before MGT-7

    Step 4

    Pay late fees & submit

    Log into the MCA21 portal using your CIN (Corporate Identity Number) and check your filing history. If it’s two or more years pending, engage a CA immediately — the form sequencing gets complicated across multiple years. Always file AOC-4 (financial statements) before MGT-7 (annual return). Filing out of order can cause rejection on the portal.

    If you’d rather not navigate MCA21, form codes, and late fee calculations yourself, Lawizer’s compliance team handles the entire ROC annual filing process — from audit coordination to MCA submission — fully online, without a physical CA visit.

    Frequently Asked Questions

    Q: What is the penalty if I miss the ROC annual filing deadline in India?

    A: The MCA charges an additional fee of ₹100 per day per form from the date the filing was due until the date you actually file. There is no upper cap on this penalty. For a private limited company filing both AOC-4 and MGT-7 late, the penalties compound on both forms separately — even a 60-day delay on both forms means ₹12,000 in late fees, plus the standard government filing charges.

    Q: My company had no business activity last year. Do I still need to file ROC returns?

    A: Yes, absolutely. Every company registered under the Companies Act 2013 must file annual returns and financial statements — even if it had zero revenue, zero transactions, or no employees. Dormant companies must file NIL returns. Failure to file on the grounds of inactivity is not an accepted excuse by the MCA, and penalties apply equally.

    Q: Can a director be barred from other companies because of one company’s filing default?

    A: Yes, and this is one of the most misunderstood aspects of ROC compliance. Under Section 164(2)(a) of the Companies Act 2013, if any company you’re a director of fails to file for three consecutive financial years, your DIN gets deactivated and you’re disqualified from holding directorship in that company and every other company for five years.

    Q: How do I check if my company is at risk of being struck off by the ROC?

    A: Log into the MCA21 portal at mca.gov.in and search your company by name or CIN. The company master data page shows the filing history and current status. If your company is marked “Active (Non-compliant)” or you see missing entries for consecutive years, consult a CA immediately.

    Q: Is there a way to waive or reduce the ROC late filing penalty?

    A: There is no standard process to waive ROC late fees — the ₹100/day penalty is automatically calculated by the MCA system and cannot be negotiated. Historically, the MCA has occasionally introduced amnesty schemes (such as the CFSS — Companies Fresh Start Scheme) at reduced or waived penalties, but these are time-limited. File as soon as possible to stop the clock.

    Q: I missed ROC filings for two years. Can I still fix this without going to court?

    A: Yes — two years means you haven’t crossed the three-year disqualification threshold under Section 164(2), so you can still file late returns directly through the MCA21 portal by paying accumulated late fees. Work with a CA or a compliance platform like Lawizer to ensure the filing sequence and form data are accurate.

  • GST Registration for Startups: Everything Founders Wish They Knew Earlier

    GST Registration for Startups: Everything Founders Wish They Knew Earlier

    India now has over 1.97 lakh DPIIT-recognised startups — and a surprising number of them get hit with GST penalties in their first two years, not because they ignored the law, but because nobody explained it clearly from the start.

    GST registration for startups isn’t just a tax formality. It’s what separates a business that can legally invoice clients, claim input credits, and sell across state lines from one that can’t.

    Miss the window, and you’re looking at penalties of up to 10% of the tax due — or 100% if the GST officer decides non-payment was intentional. Here’s everything you need to know before that happens to you.

    📌 TL;DR: GST registration for startups in India is mandatory once your annual turnover crosses ₹40 lakhs (goods) or ₹20 lakhs (services) — but if you sell online, supply interstate, or want to claim Input Tax Credit, you need it from Day 1 regardless of turnover.

    The process is fully online via the GST portal (gst.gov.in) and typically takes 7–10 working days. Lawizer handles end-to-end GST registration for startups so you can stay focused on building your product.

    What you’ll learn

    • Exactly when your startup must register for GST
    • Documents needed and mistakes that cause rejections
    • Step-by-step registration process on the GST portal
    • Post-registration compliance — returns, ITC, e-invoicing
    • The Composition Scheme — should your startup opt in?

    Who actually needs GST registration? (The real answer)

    Let’s break this down. Most founders assume GST registration is only needed once you’re “big enough.” That’s partly right — and partly what gets startups into trouble. Under the CGST Act, registration becomes mandatory when your aggregate turnover crosses ₹40 lakhs for goods or ₹20 lakhs for services. For special category states like Manipur, Mizoram, Tripura, and Nagaland, the limit drops to ₹10 lakhs.

    Here’s the thing — turnover thresholds are only one trigger. Several startup scenarios make GST registration mandatory from the very first sale:

    • Interstate supply: Selling to customers in another state? You need a GSTIN immediately — no turnover limit applies.
    • E-commerce sellers: Listing on Amazon, Flipkart, or Meesho? GST registration is compulsory before your first order ships.
    • E-commerce operators: Running a marketplace platform? Also covered under mandatory registration rules.
    • Reverse charge mechanism: Purchasing services from unregistered vendors where you’re liable to pay GST directly.
    • Casual taxable persons: Taking a contract in a state where you don’t have a fixed place of business.

    What most founders miss: even if none of the above apply, voluntary GST registration lets you issue proper tax invoices, claim ITC on purchases, and appear credible to B2B clients who won’t work with unregistered vendors.

    Documents required — the complete checklist

    For Private Limited companies and LLPs

    • PAN card of the company or LLP
    • Certificate of Incorporation from MCA
    • MOA/AOA for Pvt Ltd; LLP Agreement for LLPs
    • PAN and Aadhaar of all directors or designated partners
    • Board resolution authorising the signatory
    • Proof of principal place of business — rent agreement + electricity bill
    • Bank account details — cancelled cheque or bank statement
    • DSC or Aadhaar-based e-sign for authentication

    For sole proprietorships and partnerships

    • PAN and Aadhaar of proprietor or all partners
    • Partnership deed (for partnership firms)
    • Proof of business address
    • Bank account proof

    A quick example: if your startup is in a co-working space in Bengaluru, you’ll also need an NOC from the operator along with their rent agreement and electricity bill.

    How to register for GST: step-by-step

    1. Generate a TRN — Go to gst.gov.in → Services → Registration → New Registration. Enter PAN, email, and mobile. Verify OTPs to receive your Temporary Reference Number. Valid for 15 days.
    2. Fill Part B — Log in with TRN. Complete all 10 sections: business details, promoter info, authorised signatory, business address, goods/services (HSN/SAC codes), and bank details. Save after each section.
    3. Submit with DSC or Aadhaar e-sign — Companies and LLPs must use a DSC. Proprietors and partnerships can use Aadhaar OTP. You’ll receive an ARN confirming your application is under review.
    4. Receive your GSTIN — Approved within 7 working days if the application is complete. Your 15-digit GSTIN and Form GST REG-06 are issued. Queries come via Form GST REG-03 with 7 days to respond.

    The Composition Scheme: should your startup opt in?

    The Composition Scheme is a simplified tax option — flat rate on turnover, quarterly filing, lower compliance burden. But it comes with a major trade-off.

    Who can opt in?

    • Turnover up to ₹1.5 crore (goods) or ₹50 lakhs (services)
    • Flat tax rates: 1% traders, 2% manufacturers, 5% restaurants, 6% service providers
    • File CMP-08 quarterly and GSTR-4 annually

    The big trade-off

    Composition dealers cannot issue tax invoices or collect GST from customers. Your B2B clients can’t claim ITC on what they pay you — making you less attractive as a vendor. You also can’t make interstate supplies. For a SaaS startup in Mumbai selling to enterprise clients in Delhi, Composition Scheme is a non-starter.

    Post-registration compliance: what comes next

    GST return filing schedule

    • GSTR-1 (outward supplies): Monthly by 11th, or quarterly under QRMP scheme (turnover ≤ ₹5 crore)
    • GSTR-3B (summary return + tax payment): Monthly or quarterly
    • GSTR-9 (annual return): Due December 31st of following financial year

    Input Tax Credit (ITC) — the real financial benefit

    ITC lets you offset the GST paid on purchases against GST collected from clients. A quick example: ₹18,000 GST paid on purchases + ₹30,000 collected from clients = only ₹12,000 remitted to the government. You can only claim ITC if your supplier has filed their own GSTR-1 correctly.

    E-invoicing requirements

    Mandatory if your turnover exceeds ₹5 crore. Every B2B invoice must go through the Invoice Registration Portal (IRP) and carry an IRN and QR code. Invoices without a valid IRN can’t be used for ITC claims.

    Common mistakes that get startups into trouble

    • Registering too late: Must register within 30 days of crossing the threshold. Penalty: ₹10,000 minimum or 100% of tax due.
    • Wrong business address: Virtual office without proper NOC documentation triggers rejection or cancellation.
    • Wrong HSN/SAC codes: Picking the wrong code means charging the wrong GST rate — creating a liability later.
    • Ignoring nil returns: Even zero-sales months require a nil GSTR-3B. Missing it attracts ₹20/day late fee.
    • Not updating after changes: New director, new office, new branch — update on GST portal within 15 days via Form GST REG-14.

    Frequently asked questions

    Q: My startup’s turnover is below ₹20 lakhs. Do I still need GST registration?

    A: Not necessarily — but it depends on how you operate. If you only sell within your state to end consumers, you can legally operate without it. However, if you sell to B2B clients who need ITC, supply interstate, or sell through any e-commerce platform, registration is compulsory regardless of turnover.

    Q: How long does GST registration take in India?

    A: If your application is complete, the GST officer approves it within 7 working days. End-to-end with professional help typically takes 7–10 business days. Incomplete applications can push this to 3–4 weeks.

    Q: Can I get GST registration if my startup operates from a co-working space?

    A: Yes. You’ll need an NOC from the operator, plus their electricity bill or rent agreement as address proof. Make sure the name and address on the NOC exactly match what you submit — any mismatch is a common rejection trigger.

    Q: What happens if I don’t file GST returns after registration?

    A: Late fees apply immediately — ₹50/day for returns with tax liability, ₹20/day for nil returns. Consistent non-filing can lead to GSTIN suspension, meaning you can no longer legally collect GST or issue tax invoices.

    Q: Is GST registration the same as DPIIT Startup India recognition?

    A: No — they are separate. GST registration gives you a GSTIN for tax compliance. DPIIT recognition provides access to tax exemptions under Section 80IAC, self-certification under labour laws, and easier public procurement access. Many founders benefit from having both.

    Q: Can I cancel my GST registration if my startup shuts down?

    A: Yes, via Form GST REG-16 on the portal. The officer processes cancellation within 30 days. All pending returns must be filed and outstanding dues cleared before cancellation is approved.

  • OPC vs LLP vs Private Limited: Which Structure is Right for Your Startup?

    OPC vs LLP vs Private Limited: Which Structure is Right for Your Startup?

    Entrepreneurs registered over 1.12 lakh new companies in India in just the first eight months of FY 2024–25—and many of those founders agonized over the same question you’re wrestling with right now: OPC, LLP, or Private Limited?

    Choosing the wrong business structure can increase your tax burden, discourage potential investors before your first pitch, and create unnecessary compliance challenges while your business is still in its early stages.

    The good news? You can easily avoid these problems once you understand how each structure affects your finances, liability, and growth potential.

    📌 TL;DRChoosing between OPC vs LLP vs Private Limited Company in India comes down to three things — how many founders you have, whether you plan to raise external funding, and how much compliance you can handle.

    Solo founders with no immediate investor plans: go OPC. Service businesses with two or more partners: go LLP. Growth-focused startups targeting VC or angel investment: go Private Limited. Lawizer can help you register the right structure fully online, without a CA visit.

    What You’ll Learn

    • What OPC, LLP, and Private Limited actually mean — in plain language
    • How each structure compares on compliance, tax, funding, and costs
    • Exactly which structure fits your startup situation in 2025
    • Common mistakes founders make when choosing a business structure

    What Each Structure Actually Means

    Let’s break this down. The Ministry of Corporate Affairs (MCA) registers all three structures—OPC, LLP, and Private Limited—and each one gives you something a sole proprietorship doesn’t: limited liability. That means if your business hits a financial wall, your personal savings, house, and car stay protected. But that’s roughly where the similarities end.

    One Person Company (OPC)

    An OPC was introduced under the Companies Act 2013 specifically for solo entrepreneurs. You are the sole shareholder and director — both roles in one person. It gives you corporate credibility without needing a co-founder.

    One catch: you must nominate a second person who takes over if something happens to you, and there are turnover-based conversion thresholds to be aware of.

    Limited Liability Partnership (LLP)

    An LLP is governed by the Limited Liability Partnership Act 2008. Think of it as a partnership firm that’s been upgraded — partners get limited liability protection, but you keep the operational flexibility of a traditional partnership.

    It needs a minimum of 2 designated partners, at least one of whom must be an Indian resident. LLPs don’t issue equity shares, which is both their biggest strength (less complexity) and their biggest weakness (can’t raise VC money directly).

    Private Limited Company (Pvt Ltd)

    A Private Limited Company under the Companies Act 2013 requires at least 2 directors and 2 shareholders. It’s the structure that investors — angel networks, VCs, and most banks — are most comfortable with.

    Private limited companies make up 96% of all companies registered in India, and that number reflects a clear market preference. You can issue equity shares, bring on investors via convertible notes or SAFEs, and eventually IPO if you scale that far.

    Compliance and Annual Filing: The Real Ongoing Cost

    Here’s the thing — the registration fee is a one-time hit. What founders routinely underestimate is the annual compliance cost. This is where LLP, OPC, and Private Limited diverge most sharply.

    An LLP has the lightest compliance load. You file Form 11 (Annual Return) and Form 8 (Statement of Accounts) with the Registrar of Companies (ROC) each year.

    Statutory audit is only mandatory if your turnover crosses ₹40 lakh or contribution exceeds ₹25 lakh — which makes LLP incredibly cost-effective for early-stage service businesses.

    An OPC sits somewhere in the middle. Like a Private Limited company, it must hold board meetings and file annual returns with MCA21 (the government’s online company filing portal). However, the compliance is slightly simpler since there’s only one shareholder. Audits are mandatory regardless of turnover size.

    A Private Limited Company has the heaviest compliance requirements. You need to hold Annual General Meetings (AGMs), file financial statements (Form AOC-4) and annual returns (Form MGT-7) with ROC every year, maintain statutory registers, and get a statutory audit done regardless of revenue.

    What most founders miss: this burden is manageable if you’re growing, because the infrastructure you’re building also signals credibility to banks and investors.

    • LLP: Lowest compliance. Audit only if turnover exceeds ₹40 lakh. Best for bootstrapped service businesses.
    • OPC: Medium compliance. Mandatory audit, but simpler than Pvt Ltd due to single-member structure.
    • Private Limited: Highest compliance. Mandatory AGMs, ROC filings, and annual statutory audit — but also comes with investor-ready credibility.

    Funding and Investment: Who Can Actually Raise Money?

    If raising money from angel investors, venture capitalists, or institutional funds is part of your long-term vision, the choice becomes simple: go with a Private Limited Company.

    Investors typically provide funding in exchange for equity (shares), and a Private Limited Company allows businesses to issue shares while offering the legal framework, governance standards, and exit opportunities that investors generally expect.

    An LLP, on the other hand, cannot issue equity shares. Although partners can contribute capital to an LLP, the structure does not support traditional startup fundraising effectively. As a result, most funded Indian startups choose to incorporate as Private Limited Companies.

    OPCs face another challenge. Since an OPC can have only one shareholder, bringing in investors requires converting it into a Private Limited Company first. If fundraising is likely within the next 12–18 months, starting as a Private Limited can save valuable time and effort later.

    Think of it this way: A Bengaluru-based D2C founder preparing to pitch at an angel investor demo day in six months would be far better off incorporating as a Private Limited Company from day one rather than dealing with conversion formalities during a crucial fundraising phase.

    Taxation: Which Structure Saves You More?

    Both LLPs and Private Limited Companies pay taxes as separate legal entities, but they face different tax rates.

    A Private Limited Company pays a flat corporate tax rate of 22% under the new regime (Section 115BAA of the Income Tax Act). Newly incorporated manufacturing companies may qualify for a lower 15% tax rate. In contrast, an LLP pays a flat 30% tax on its total income. A surcharge also applies when its profit exceeds ₹1 crore.

    Many founders overlook this advantage. Private Limited Companies have better access to startup tax exemptions. These include the 3-year tax holiday available under Section 80-IAC for startups recognised by the DPIIT..

    LLPs can also obtain DPIIT recognition, but many startup schemes and incentives focus primarily on companies registered under the Companies Act, 2013 rather than the LLP Act. As a result, Private Limited Companies often find it easier to access certain startup benefits and funding opportunities.

    An OPC follows the same tax structure as a Private Limited Company and pays a 22% corporate tax rate under the applicable tax regime. LLPs look attractive for simplicity but can end up paying more tax at higher profit levels.

    If your projected annual profit is above ₹15–20 lakh, this difference is worth calculating carefully with a CA.

    Which Structure Fits Your Situation — A Decision Framework

    Solo founder, no co-founder, not planning to fundraise immediately

    Go OPC. You get limited liability, a corporate identity (useful for opening a business bank account, signing contracts, and building client credibility), and lower complexity than a Pvt Ltd. You can always incorporate and convert to Private Limited later when you’re ready to scale.

    Two or more founders, service business, want to keep things lean

    Go LLP. This is the sweet spot for CA firms, consulting practices, IT service providers, and design studios. Low compliance, flexible profit-sharing, and no pressure to maintain complex corporate governance. Many thriving businesses in Delhi, Pune, and Kolkata run successfully as LLPs for years without needing to convert.

    Building a product startup, plan to raise funding, or want ESOP flexibility

    Go Private Limited. Full stop. Private limited companies can issue ESOPs (Employee Stock Ownership Plans) to attract talent, take angel or VC money, and eventually list on Indian stock exchanges. If your startup is in fintech, SaaS, edtech, or D2C — this is your structure.

    Already running a proprietorship, want to formalise on a budget

    An LLP or OPC is often the right first step. Both are cheaper to register and maintain than a Private Limited Company. Once your revenue stabilises, conversion is available — and it’s a solved process, not a reinvention.

    Quick Comparison: OPC vs LLP vs Private Limited

    Factor OPC LLP Private Limited
    Founders needed 1 2+ 2+
    Can raise VC/Angel funding? No (needs conversion) No Yes
    Tax rate 22% (corporate) 30% flat 22% (corporate)
    Compliance burden Medium Low High
    Mandatory audit Always Only if turnover > ₹40L Always

    Frequently Asked Questions

    Q: Can I convert my OPC to a Private Limited Company later?

    A: Yes, you can convert an OPC to a Private Limited Company through MCA21 procedures under the Companies Act 2013. The process involves adding at least one more shareholder and director, filing the relevant forms with the Registrar of Companies, and amending your Memorandum of Association (MOA). It typically takes 4–8 weeks and involves legal costs. If you expect to fundraise within a year, it’s usually more efficient to start as a Private Limited directly.

    Q: Which structure is cheapest to register and maintain in India?

    A: LLP is generally the most cost-effective structure to register and maintain over the long term, particularly for businesses with turnover below ₹40 lakh (which are exempt from mandatory statutory audit). OPC registration is similarly affordable upfront, but ongoing compliance costs are higher because audits are mandatory regardless of revenue. Private Limited Companies have the highest annual compliance cost due to mandatory audits, AGMs, and multiple ROC filings.

    Q: Can an LLP get MSME registration in India?

    A: Yes, an LLP is eligible to register as an MSME (Micro, Small and Medium Enterprise) on the Udyam Registration portal, as long as it meets the investment and turnover thresholds defined by the MSMED Act. MSME status gives you access to priority sector lending, government scheme benefits, and collateral-free loans. The registration applies equally to LLPs, OPCs, and Private Limited Companies.

    Q: Do I need a physical office address to register a company in India?

    A: Yes, all three structures require a registered office address in India at the time of incorporation. This can be your home address, a co-working space, or a rented office. Many founders in cities like Bengaluru, Mumbai, and Hyderabad use their residential address initially and update it later as the business grows.

    Q: Is Private Limited always better than LLP for a startup in India?

    A: Not always — it depends entirely on your business goals. If you’re building a funded, equity-driven, high-growth startup, then yes, Private Limited is the clear choice. But for a consulting firm, boutique agency, or professional practice where founders want to split profits flexibly and keep compliance simple, an LLP can be a smarter long-term choice. The “best” structure is the one that matches your actual business model and growth plan.

    Q: What is SPICe+ and how does it work for company registration?

    A: SPICe+ (Simplified Proforma for Incorporating Company Electronically Plus) is MCA’s integrated online form for registering a company in India. It combines multiple applications into one — Director Identification Number (DIN), company name reservation, PAN, TAN, GSTIN application, and EPFO/ESIC registration. It covers OPC and Private Limited Company registration. LLPs are incorporated through a separate FiLLiP form on the same MCA portal.

  • How to Register a Private Limited Company in India in 2025: Step-by-Step

    How to Register a Private Limited Company in India in 2025: Step-by-Step

    Over 1.38 lakh new companies were incorporated in India between April 2024 and March 2025 alone — and 96% of all active Indian companies are private limited companies.

    That’s not a coincidence. Private limited company registration gives founders limited liability, a separate legal identity, and instant credibility with investors, banks, and enterprise clients.

    But here’s the thing — most founders either overpay a CA, get stuck in document loops, or miss critical post-incorporation steps that cause compliance headaches later. This guide fixes all of that.

    📌 TL;DR: Private limited company registration in India is done entirely online through the MCA21 portal using the SPICe+ integrated form.

    You need at least 2 directors, 2 shareholders, a DSC, and a DIN — and the whole process takes 7–15 working days. Lawizer handles the end-to-end registration so you can focus on building your business, not filing forms.

    What You’ll Learn

    • The exact eligibility conditions and documents you need before you begin
    • Every step in the MCA SPICe+ registration process — in the correct sequence
    • Government fees, realistic timelines, and common mistakes that delay approval
    • What you must do immediately after getting your Certificate of Incorporation

    Why Register as a Private Limited Company? The Real Advantages

    Before getting into steps, it’s worth being clear about why Pvt Ltd is the default choice for serious founders.

    A private limited company is a separate legal entity under the Companies Act, 2013 — meaning the company can own assets, sign contracts, open bank accounts, and take on liabilities completely independently of its founders. Your personal savings aren’t on the line if the business goes under.

    What most founders miss: Pvt Ltd status is a hard prerequisite for most institutional investors. VC firms, angel networks, and accelerators like Y Combinator or 100X.VC will not write a cheque to an unincorporated entity or a proprietorship.

    And if you’re selling to enterprise clients in Bengaluru or Mumbai — or planning to raise foreign capital — a Pvt Ltd structure is essentially non-negotiable.

    There’s also the trust factor. Customers, vendors, and even potential hires perceive an incorporated company differently. A “Pvt Ltd” at the end of your business name signals permanence. And once incorporated, the company enjoys perpetual succession — it continues to exist even if directors change.

    Eligibility Checklist: What You Need Before You Apply

    Let’s break this down before touching the MCA portal. Getting these basics wrong wastes days. Here’s what’s mandatory under the Companies Act, 2013:

    • Minimum 2 directors — at least one must be an Indian resident (present in India for 182+ days in the previous calendar year)
    • Minimum 2 shareholders — directors and shareholders can be the same people
    • Maximum 200 shareholders — beyond this, you’d need a public limited structure
    • Registered office address in India — can be a rented space or a virtual office; a residential address works too
    • No minimum paid-up capital — the earlier ₹1 lakh requirement was removed by the Companies Amendment Act, 2015. You can start with ₹10,000 or less

    Documents you’ll need for each director and shareholder: PAN card, Aadhaar or passport, a recent bank statement or utility bill (address proof), and passport-size photographs. For the registered office: a utility bill of the premises plus a No Objection Certificate (NOC) from the owner if it’s rented.

    Step-by-Step: The Private Limited Company Registration Process in 2025

    In 2025, the entire process runs through the MCA21 portal — India’s unified corporate registry managed by the Ministry of Corporate Affairs. Gone are the days of courier-filing physical documents. Here’s the exact sequence:

    Step 1: Obtain a Digital Signature Certificate (DSC)

    A DSC — Digital Signature Certificate — is your e-signature for signing all MCA forms. Every proposed director and subscriber to the Memorandum of Association (MOA) must have one.

    You get it from government-approved agencies like eMudhra or Sify. Expect to submit ID proof, address proof, and a selfie or video for verification. This typically takes 1–2 days and costs ₹1,000–₹2,000 per DSC depending on validity (1 or 2 years).

    Step 2: Name Reservation via SPICe+ Part A

    SPICe+ (Simplified Proforma for Incorporating Company Electronically Plus) is MCA’s integrated web form — it handles incorporation, PAN, TAN, GST, EPFO, and ESIC registration all in one submission.

    Part A is just for name reservation. You can propose up to 2 names. The name must end with “Private Limited” and can’t conflict with existing trademarks or company names. Use the MCA Name Search tool to check availability before applying. Name approval typically takes 1–3 working days.

    A quick example: If you want “TechNova Solutions Private Limited,” search “TechNova” on the MCA portal first. If it’s taken or flagged as similar to a registered trademark, have a backup ready. Two rejections and you’ll need to refile, losing time and money.

    Step 3: File SPICe+ Part B — The Core Incorporation Form

    This is where the actual incorporation happens. Part B of SPICe+ asks for director details, registered office address, share capital structure, and other company particulars. It’s filed along with these key attachments:

    • MOA (Memorandum of Association) — defines the company’s objectives and scope of business; filed via eForm INC-33
    • AOA (Articles of Association) — the internal rulebook for governance; filed via eForm INC-34
    • AGILE-PRO-S — the linked form for simultaneous GST registration, EPFO (Employees’ Provident Fund Organisation), ESIC (Employees’ State Insurance Corporation), and a bank account opening request

    Director Identification Number (DIN) — a unique ID number issued by MCA to track an individual’s directorships — is auto-generated during the SPICe+ Part B filing process. You don’t need to apply separately.

    Step 4: Pay Government Fees and Stamp Duty

    Government fees depend on your authorised share capital. For a company with ₹1 lakh authorised capital, the total MCA fee is typically in the range of ₹3,000–₹7,000. Stamp duty varies by state

    — for example, it’s approximately ₹500 in Delhi but higher in Maharashtra. All payments are made online through the MCA portal. There are no offline payment options.

    Step 5: Certificate of Incorporation — You’re Live

    Once the Registrar of Companies (ROC) approves your application, you receive a digitally signed Certificate of Incorporation (COI) via email. The COI includes your CIN (Corporate Identity Number), and PAN and TAN are auto-issued in collaboration with the Income Tax Department.

    The short answer on timeline: 7–15 working days from the date of SPICe+ submission, assuming clean documentation and no name objections.

    Critical Post-Incorporation Steps (Most Founders Skip These)

    Getting the COI is not the finish line — it’s the starting gun. Here’s what must happen in the weeks after incorporation:

    • Open a current bank account in the company’s name within 30 days. Take your COI, MOA, AOA, PAN, and board resolution to any scheduled commercial bank.
    • File INC-20A (Commencement of Business Declaration) — this is mandatory within 180 days of incorporation. Directors must deposit the paid-up share capital into the company’s bank account before filing. Skipping this attracts a ₹50,000 penalty and can result in the company being struck off.
    • Issue share certificates to all subscribers within 60 days of incorporation.
    • Apply for GST registration if your turnover will exceed ₹40 lakh (₹20 lakh for service-only businesses or special category states). This can be done via the AGILE-PRO-S form at the time of incorporation itself, or later through the GSTN portal.
    • Protect your brand — company registration does NOT protect your brand name from being used by others. You’ll need a separate trademark registration for that.

    If your business qualifies as a Micro, Small, or Medium Enterprise under the MSMED Act, 2006, you should also consider an MSME Udyam registration — it unlocks priority sector lending, government scheme benefits, and faster payment protections from buyers.

    What Does It Cost? A Realistic Breakdown

    Here’s what the full cost looks like for a standard Pvt Ltd with ₹1 lakh authorised capital:

    • DSC (per director): ₹1,000–₹2,000
    • MCA government fees: ₹3,000–₹7,000 (varies by state and capital)
    • Stamp duty: ₹500–₹2,000 (varies by state)
    • Professional service fee: ₹5,000–₹15,000 if using a platform or CA

    Total: expect to spend ₹8,000–₹25,000 depending on the service provider and your state. Platforms like Lawizer keep the professional fee transparent and fixed — no surprise billings halfway through the process. You can see all business legal services at Lawizer’s startup legal hub.

    Common Mistakes That Delay Your Application

    Based on real founder experiences on forums and Q&A platforms, these are the errors that cause rejections and refilings:

    • Name conflicts: Proposing names too similar to existing brands or companies. Always search both the MCA database and the trademark registry before committing.
    • Address proof mismatch: The utility bill for the registered office is older than 2 months, or the address on the NOC doesn’t exactly match the address proof submitted.
    • DSC issues: Using an expired DSC or a DSC that isn’t mapped to your PAN correctly on the MCA portal.
    • MOA objects clause: Drafting overly broad or vague business objectives. The ROC can raise queries if the object clause isn’t specific enough to your business activity.
    • Forgetting INC-20A: Many founders think they’re done after the COI arrives. Skipping the Commencement of Business declaration is a serious non-compliance that attracts heavy penalties.

    Frequently Asked Questions

    Q: How long does it take to register a private limited company in India in 2025?

    A: The complete process — from DSC to Certificate of Incorporation — typically takes 7 to 15 working days in 2025. The name approval stage takes 1–3 days, DSC procurement takes 1–2 days, and the SPICe+ Part B processing takes 3–7 working days after submission.
    If documents are clean and the name is approved without objection, some incorporations are completed in as few as 7 working days. Errors in forms or name disputes can add a week or more.

    Q: What is the minimum capital required to register a private limited company in India?

    A: There is no minimum paid-up capital requirement. The Companies Amendment Act, 2015 removed the earlier mandatory ₹1 lakh minimum, so you can incorporate with as little as ₹10,000 or even less.
    That said, you should set an authorised capital that reflects your realistic fundraising needs — since increasing it later involves additional MCA fees and ROC filings.

    Q: Can a single person register a private limited company?

    A: No — a private limited company requires a minimum of 2 directors and 2 shareholders.
    If you’re a solo founder, you have two options: bring in a co-founder or family member as the second director/shareholder, or register as a One Person Company (OPC) instead. OPC is a separate legal structure under the Companies Act, 2013 designed for sole entrepreneurs and has its own eligibility conditions.

    Q: Is it mandatory to have a physical office to register a private limited company?

    A: You need a registered office address in India, but it doesn’t have to be a commercial space. A residential address works — many founders use their home address for early-stage companies. Virtual office addresses from co-working providers are also accepted, provided you can furnish a valid NOC from the building owner and a recent utility bill of the premises.

    Q: What is the SPICe+ form and do I need to fill it myself?

    A: SPICe+ (Simplified Proforma for Incorporating Company Electronically Plus) is MCA’s master incorporation form that handles company registration, PAN, TAN, GST, EPFO, and ESIC all in one linked application. It has two parts — Part A for name reservation and Part B for the full incorporation filing. While technically anyone can file it, the form is complex and errors cause rejections. Most founders use a legal platform or professional to prepare and file it correctly the first time.

    Q: Does registering a company name also protect it as a trademark?

    A: No — company registration and trademark registration are completely separate. Registering “XYZ Solutions Private Limited” with the MCA only prevents another company from using the exact same registered name. It does not stop someone from using “XYZ Solutions” as a brand name for products or services. To protect your brand, logo, or slogan against infringement, you need to file a separate trademark application with the CGPDTM (Controller General of Patents, Designs and Trade Marks).

  • INC-20A: The Post-Incorporation Form Most Founders Have Never Heard OfS

    INC-20A: The Post-Incorporation Form Most Founders Have Never Heard OfS

    You just got your Certificate of Incorporation. You’re celebrating. But there’s a mandatory MCA form sitting on a 180-day countdown clock — and most new founders don’t even know it exists. It’s called INC-20A, the Declaration for Commencement of Business, and skipping it can freeze your company’s operations, trigger a ₹50,000 penalty, and get your company struck off the register entirely.

    This is one of the most overlooked post-incorporation compliance steps in India. Let’s fix that right now.

    📌 TL;DR: INC-20A (Declaration for Commencement of Business) is a mandatory MCA filing under Section 10A of the Companies Act, 2013 for every company incorporated in India on or after 2nd November 2018 with share capital. It must be filed within 180 days of incorporation. Without it, your company legally cannot conduct any business or borrow funds — and risks a ₹50,000+ penalty or strike-off. Lawizer helps founders file INC-20A quickly and correctly, fully online.

    What You’ll Learn

    • What INC-20A is and why the MCA introduced it in 2018
    • Which companies must file it, who is exempt, and the exact 180-day deadline
    • The documents you need, the step-by-step filing process on MCA21, and the penalties for missing the deadline
    • The one pre-condition most founders forget before they can even file

    What Is INC-20A and Why Does It Exist?

    INC-20A — officially the Declaration for Commencement of Business — was introduced through the Companies (Amendment) Ordinance, 2018, which inserted a new Section 10A into the Companies Act, 2013. It came into effect on 2nd November 2018.

    Before this change, a company could technically open its doors, sign contracts, and borrow money the day after getting its CIN (Corporate Identity Number). That loophole led to thousands of shell companies being registered with no real capital ever deposited.

    Here’s the thing. The MCA’s solution was elegant: make every new company formally declare, before doing anything, that its subscribers have actually paid up their share capital into the company’s bank account. That declaration is Form INC-20A.

    Think of it as your company’s “permission to operate” stamp — without it, your incorporation certificate is essentially incomplete from a business-operations standpoint.

    This form is filed under Rule 23A of the Companies (Incorporation) Rules, 2014, and needs to be certified by a practising Chartered Accountant (CA), Company Secretary (CS), or Cost Accountant before submission on the MCA21 portal.

    Who Must File INC-20A — and Who Gets a Pass?

    Not every registered entity needs to file this form. Here’s a clear breakdown so you know exactly where you stand.

    Companies Required to File

    • Any company incorporated on or after 2nd November 2018 with a share capital — this includes Private Limited Companies, Public Limited Companies, and One Person Companies (OPCs)
    • Companies that need regulatory approvals from sectoral bodies like RBI, SEBI, or IRDAI must also attach proof of that approval along with INC-20A

    Companies Exempt from Filing

    • Companies incorporated before 2nd November 2018
    • Companies incorporated without share capital (such as Section 8 companies — non-profits)
    • LLPs (Limited Liability Partnerships) and Partnership Firms — these have separate governance structures and this form does not apply to them

    What most founders miss: if you registered your startup as a Private Limited Company in, say, Bengaluru or Delhi after November 2018 — which accounts for the vast majority of new incorporations today — you are legally required to file INC-20A before you send your first invoice or sign your first client contract.

    The One Thing You Must Do Before Filing INC-20A

    Let’s break this down, because this is the step that trips up most founders. Before you can even open the INC-20A form on the MCA21 portal, you must complete one prerequisite: deposit the subscription money into your company’s bank account.

    When you incorporated your company, each founder (subscriber) agreed in the Memorandum of Association (MOA) to take a certain number of shares at a specified value. The entire purpose of INC-20A is to confirm that all of that agreed share capital has actually been transferred into the company’s official current account.

    For example, if your company’s paid-up capital is ₹1,00,000, each subscriber must have deposited their proportionate share into the company bank account before the form is filed.

    A quick example: suppose two co-founders each hold 50% of a company incorporated with ₹1,00,000 paid-up capital. Each one must deposit ₹50,000 into the company’s current account. Only after both transfers appear on the bank statement can you attach that statement to INC-20A and certify it.

    This is why opening the company’s current account immediately after incorporation — not weeks later — is so critical. Don’t wait for your accountant to remind you.

    Need help with the full incorporation and post-incorporation compliance checklist? The Lawizer business legal services page covers everything from SPICe+ filing to post-registration steps like INC-20A, GST registration, and MSME enrolment.

    Documents Required for INC-20A Filing

    Filing INC-20A on the MCA21 Version 3 portal is straightforward once you have all your documents in order. Here’s everything you’ll need:

    • Company Bank Statement — showing all credit entries, specifically the receipt of subscription money from each shareholder. This is the most critical document.
    • Photographs of the Registered Office — one showing the external building and one showing the interior of the office, with at least one Director or KMP (Key Managerial Personnel) visible in the photo.
    • Board Resolution — authorising a specific director to file the INC-20A form on behalf of the company.
    • Proof of regulatory approval — required only if your company’s business is regulated by RBI, SEBI, IRDAI, or another sectoral body.
    • Digital Signature Certificate (DSC) — of the director who will be signing and submitting the form on the MCA21 portal.

    The form itself must be certified by a practising CA, CS, or Cost Accountant before it’s uploaded. Once submitted, the MCA typically processes it and issues acknowledgement. There’s no separate “certificate” issued — successful filing and its SRN (Service Request Number) confirmation is your proof of compliance.

    Incorporation Compliance Checklist India | Complete Guide

    The 180-Day Deadline and What Happens If You Miss It

    The deadline is firm: INC-20A must be filed within 180 days from the date of incorporation. So if your company was incorporated on 1st January 2025, the last date to file INC-20A is 30th June 2025.

    The MCA’s e-filing portal accepts INC-20A filings throughout this window, and it’s strongly advisable to file well before the last 30 days.

    The short answer on penalties: they’re steep and they escalate. Here’s exactly what non-compliance triggers under Section 10A of the Companies Act, 2013:

    • Penalty on the company: ₹50,000 (one-time flat penalty)
    • Penalty on every officer in default (each director who was responsible): ₹1,000 per day for every day the default continues, capped at ₹1,00,000 per officer
    • Company strike-off: If the Registrar of Companies (RoC) has reasonable cause to believe the company is inactive — no bank account, no assets, no business — it can initiate action to remove the company’s name from the Register of Companies entirely

    These aren’t theoretical. The MCA has actively penalised companies for non-compliance — in one documented case, the RoC Hyderabad imposed a total penalty of ₹2.5 lakh on a company and its directors for failing to file INC-20A.

    Directors must pay penalties from their personal income, not company funds. That’s a personal financial hit that no early-stage founder should have to absorb for a form that takes a few days to file correctly.

    If your company has already missed the deadline, there’s still a path forward. Late filing is accepted on the MCA portal with additional fees, and in some cases, founders can file a condonation application explaining the reasons for delay. But do not wait. Each additional day adds ₹1,000 to every director’s personal liability.

    Step-by-Step: How to File INC-20A on MCA21

    Here’s the complete process, simplified for founders who want to understand what their CA or Lawizer’s team is doing on their behalf:

    • Step 1 — Open the Company’s Bank Account: Do this immediately after incorporation. Deposit the subscription amounts from all shareholders as per the MOA.
    • Step 2 — Collect Documents: Gather the bank statement, registered office photographs, board resolution, and director DSC.
    • Step 3 — Download the Form: Log into the MCA21 Version 3 portal using the company’s CIN and director credentials. Access the INC-20A e-form.
    • Step 4 — Fill and Certify: Complete all mandatory fields — CIN, registered office address, and the declaration. Have a practising CA, CS, or Cost Accountant digitally certify the form.
    • Step 5 — Attach and Upload: Attach all supporting documents and upload the certified form on the MCA21 portal.
    • Step 6 — Pay Fees and Get SRN: Pay the prescribed filing fee online. The portal generates an SRN (Service Request Number) as proof of submission. Save this.

    Once filed successfully, your company is legally authorised to commence business operations, exercise borrowing powers, and enter into contracts. Until then — even if you’ve been operating informally — you are technically in default under the Companies Act, 2013.

    Lawizer’s compliance experts handle this entire process end-to-end, so you don’t have to track down a CA and navigate MCA21 on your own.

    INC-20A vs SPICe+: Understanding the Difference

    A lot of founders confuse INC-20A with SPICe+. They’re entirely different. SPICe+ (Simplified Proforma for Incorporating Company Electronically Plus) is the form you file to incorporate your company — it’s the form through which MCA assigns your CIN and issues your Certificate of Incorporation. INC-20A is the form you file after incorporation, to declare that business can now commence.

    Think of it this way: SPICe+ is the birth certificate of your company. INC-20A is the clearance certificate that says your company is funded, operational, and ready to engage with the world. You need both.

    One without the other leaves your company legally incomplete for business purposes. If you’re also planning to register for MSME Udyam registration or GST, those processes can run in parallel with INC-20A — but don’t start billing clients until INC-20A is filed and confirmed.

    Frequently Asked Questions

    Q: Is INC-20A mandatory for all private limited companies in India?

    A: Yes, INC-20A is mandatory for every company incorporated in India on or after 2nd November 2018 that has a share capital. This includes Private Limited Companies, Public Limited Companies, and One Person Companies (OPCs). Companies incorporated before that date, companies without share capital (like Section 8 non-profits), LLPs, and partnership firms are not required to file this form.

    Q: What is the deadline to file INC-20A after company incorporation?

    A: INC-20A must be filed within 180 days from the date of incorporation of the company. For example, if your company was incorporated on 1st January 2025, the deadline to file INC-20A is 30th June 2025. Missing this deadline attracts a ₹50,000 penalty on the company and ₹1,000 per day on each defaulting director, up to a maximum of ₹1,00,000 per officer.

    Q: Can my company start business before filing INC-20A?

    A: No. Under Section 10A of the Companies Act, 2013, a company cannot commence any business activity or exercise any borrowing powers until INC-20A has been filed with the Registrar of Companies (RoC). Operating without filing INC-20A makes the company and its directors liable to penalties, and the Registrar can initiate proceedings to strike off the company’s name from the register.

    Q: What documents are needed to file Form INC-20A?

    A: To file INC-20A, you’ll need the company’s bank statement showing receipt of subscription money from all shareholders, photographs of the registered office (exterior and interior with a director or KMP visible), a board resolution authorising the filing, and the Director’s Digital Signature Certificate (DSC). The form must be certified by a practising Chartered Accountant, Company Secretary, or Cost Accountant before submission on the MCA21 portal.

    Q: What happens if INC-20A is not filed within 180 days?

    A: If INC-20A is not filed within 180 days of incorporation, the company faces a flat penalty of ₹50,000. Each director in default is additionally liable to pay ₹1,000 per day of continued non-compliance, up to ₹1,00,000 per director — and this penalty must be paid from personal funds, not company accounts. In serious cases, the Registrar of Companies can also initiate action to strike off the company’s name from the Register of Companies entirely.

    Q: Who certifies the INC-20A form before filing?

    A: Form INC-20A must be verified and certified by a practising professional — either a Chartered Accountant (CA), Company Secretary (CS), or Cost Accountant — before it is uploaded to the MCA21 portal. Directors cannot self-certify this form. The certifying professional confirms that the information provided, including the proof of share capital receipt, is accurate and complete.

    Q: Does INC-20A need to be filed every year?

    A: No, INC-20A is a one-time filing. It is required only once, immediately after incorporation and before the company commences business. It is not an annual compliance requirement. However, companies must continue to file their annual returns, financial statements, and other periodic MCA forms as required under the Companies Act, 2013.

    Ready to file INC-20A and get your company legally operational?
    Lawizer’s experts handle everything — INC-20A filing, post-incorporation compliance, GST registration, and MSME Udyam enrolment — fully online, starting at just ₹999. No CA visit needed.

    Start Your INC-20A Filing with Lawizer →

  • 7 Mistakes Founders Make During Private Limited Company Registration in India

    7 Mistakes Founders Make During Private Limited Company Registration in India

    India registered 21,737 new private limited companies in April 2026 alone. Yet thousands of those applications faced delays, resubmissions, or outright rejection — not because the businesses weren’t viable, but because of avoidable paperwork mistakes.

    If you’re about to register your startup, this guide will save you weeks of back-and-forth with the MCA.

    📌 TL;DR: Private limited company registration in India is faster than ever thanks to SPICe+, but most rejections happen due to wrong name selection, incorrect documents, and missing post-incorporation compliance. Avoid these 7 mistakes and you’ll be incorporated in under 10 working days.

    What You’ll Learn

    • The most common SPICe+ filing mistakes that cause MCA rejection
    • Why your company name is the single biggest bottleneck
    • What happens after incorporation — and what most founders miss

    Why Private Limited Company Registration Goes Wrong

    The Ministry of Corporate Affairs (MCA) has made company incorporation largely digital through the SPICe+ (Simplified Proforma for Incorporating Company Electronically Plus) form. In theory, a founder can go from zero to incorporated in 7–10 working days.

    In practice? Most first-time founders hit at least one snag. Here’s what actually goes wrong — and how to fix it before you file.

    Mistake #1 — Choosing a Company Name Without Checking MCA First

    Name rejection is the single most common reason SPICe+ Part A gets rejected. The MCA checks your proposed name against:

    • Existing registered company names (even partial matches)
    • Trademarked words via the IP India trademark database
    • Restricted words like “Bank”, “Stock Exchange”, “Government”, “National”
    • The Emblems and Names (Prevention of Improper Use) Act, 1950

    What most founders miss: You can’t use “Tech Solutions India Pvt Ltd” if a company named “Tech Solutions Pvt Ltd” already exists. The similarity threshold is stricter than you’d expect.

    Fix: Before filing, run a free name check on the MCA Master Data portal. Pick a distinctive, specific name — the more unique, the faster your approval.

    Mistake #2 — Using the RUN Service for a New Company

    Many founders Google “how to reserve a company name India” and land on the Reserve Unique Name (RUN) service. Here’s the thing — as of 2025, RUN is exclusively for name changes in already-incorporated companies.

    New incorporations must use SPICe+ Part A for name reservation. Filing a RUN request for a fresh incorporation wastes your time and filing fees.

    Once your name is approved via SPICe+ Part A, you have 20 days to complete and submit Part B. Don’t let it lapse.

    Mistake #3 — Submitting Wrong or Outdated Documents

    Incorrect documentation is the second most common reason for resubmission requests. Common document errors include:

    • Electricity bills or bank statements older than 2 months (for address proof)
    • PAN cards with name mismatches vs. Aadhaar
    • Passport photos that don’t meet MCA specifications
    • Registered office address proof not matching the state of incorporation

    Every director needs a valid Digital Signature Certificate (DSC) and a Director Identification Number (DIN) before filing. Missing either one stops the entire process cold.

    Document Checklist for Directors

    • PAN card (mandatory for Indian nationals)
    • Aadhaar card (address proof)
    • Passport-size photograph
    • DSC (Class 3) — valid and activated
    • DIN — applied via SPICe+ or DIR-3 form

    Mistake #4 — Writing Vague or Overly Broad MOA Objects

    The Memorandum of Association (MOA) defines what your company is legally allowed to do. Many founders copy-paste generic object clauses thinking broader is better.

    The MCA has specific guidelines on MOA drafting. If your primary business activity isn’t clearly mentioned, you could face legal restrictions on operations — or worse, MCA rejection.

    A quick example: A SaaS founder building a B2B invoicing tool filed MOA objects for “general trading and IT services.” Six months later, when approaching investors, the MOA had to be amended — a process that takes another 30+ days and costs additional filing fees.

    Write specific, accurate objects that match your actual business. You can always add more later through an EGM resolution, but it costs time and money.

    Mistake #5 — Ignoring Post-Incorporation Compliance

    Getting your Certificate of Incorporation feels like the finish line. It’s actually the starting gun.

    Within 30 days of incorporation, you must:

    • Open a current bank account in the company name
    • Obtain GST registration if your turnover crosses ₹20 lakh (₹10 lakh for special category states) — or immediately if you’re doing interstate supply. Lawizer handles GST registration starting at ₹999
    • File INC-20A (Declaration of Commencement of Business) within 180 days
    • Issue share certificates to all shareholders
    • Hold the first Board Meeting within 30 days of incorporation

    Missing INC-20A alone attracts a penalty of ₹50,000 on the company and ₹1,000 per day on each defaulting officer. Most first-time founders have never heard of it.

    Mistake #6 — Adding Directors Without Checking Eligibility

    Every director has legal obligations and potential personal liability under the Companies Act, 2013. Adding someone as a director simply to meet the minimum two-director requirement — without checking eligibility — is a serious mistake.

    Directors must:

    • Be at least 18 years old
    • Not be disqualified under Section 164 of the Companies Act
    • Have a valid DIN
    • At least one director must be a resident of India (stayed in India for at least 182 days in the previous calendar year)

    Also: equity allocation to co-founders must be documented in a board resolution at the time of share allotment. Sorting this out later creates disputes that can derail funding rounds.

    Mistake #7 — Not Protecting the Brand Before or After Incorporation

    Your company name registration with MCA does NOT protect your brand name or logo. These are two completely separate legal protections.

    Dozens of founders have incorporated successfully, built a product, run ads — and then received a cease and desist from a brand that trademarked the same name earlier. By then, rebranding costs lakhs.

    File for trademark registration at the same time as company incorporation — or immediately after. At ₹999, it’s the most affordable brand insurance you’ll ever buy. Register your trademark with Lawizer here.

    Frequently Asked Questions

    Q: How long does private limited company registration take in India in 2025?

    A: With all documents correct and DSC activated, SPICe+ Part A name approval takes 1–3 working days. Part B (full incorporation) takes another 5–7 working days. Total: 7–10 working days if everything is in order. Mistakes or resubmissions can extend this to 3–4 weeks.

    Q: What is the minimum capital required to register a private limited company in India?

    A: There is no minimum paid-up capital requirement for private limited company registration in India. The earlier ₹1 lakh minimum was removed. You can incorporate with ₹10,000 or even ₹1,000 as authorised capital, though most professionals recommend ₹1 lakh to keep future share allotments clean.

    Q: Can a single person register a private limited company in India?

    A: No. A private limited company requires a minimum of 2 directors and 2 shareholders. If you want to be the sole owner, you should register a One Person Company (OPC) instead. Lawizer offers OPC registration starting at ₹999.

    Q: What is SPICe+ and why does it matter for company registration?

    A: SPICe+ (Simplified Proforma for Incorporating Company Electronically Plus) is the MCA’s integrated incorporation form that simultaneously handles company name reservation, DIN allotment, PAN, TAN, EPFO, ESIC, Profession Tax, and bank account opening — all in one filing. Understanding its two-part structure (Part A for name, Part B for full incorporation) is essential to avoid delays.

    Q: What happens if I miss filing INC-20A after incorporation?

    A: INC-20A is the Declaration of Commencement of Business that must be filed within 180 days of incorporation. Missing this deadline attracts a penalty of ₹50,000 on the company and ₹1,000 per day on each defaulting officer. The company also cannot commence business or borrow money without filing this form.

    Ready to register your private limited company the right way?
    Lawizer’s experts handle everything — name check, DSC, DIN, SPICe+ filing, and post-incorporation compliance — fully online, starting at just ₹1,499. No CA visit needed.

    Start your company registration with Lawizer →

  • Cryptocurrency and Tax in India: The Definitive 2026 Guide

    Cryptocurrency and Tax in India: The Definitive 2026 Guide

    Introduction

    The Indian crypto landscape has traveled a long road from the uncertainty of 2018 to the structured—yet stringent—regulatory framework of 2026.

    As Virtual Digital Assets (VDAs) become a mainstay in the portfolios of Indian retail investors and institutional players alike, staying compliant is no longer just about avoiding penalties; it is about protecting your digital wealth.

    With the Union Budget 2026 introducing refined definitions for Decentralized Finance (DeFi) and cross-border transactions, the tax authorities are watching more closely than ever.

    This guide breaks down everything you need to know about navigating crypto taxes in India this year.


    The Core Tax Architecture: The 30% Rule

    Since the introduction of Section 115BBH in the Income Tax Act, the fundamental rule for crypto taxation in India has remained consistent.

    The Flat Tax Rate

    Income from the transfer of any Virtual Digital Asset is taxed at a flat rate of 30%, regardless of your income tax slab.

    • No Deductions: Only the cost of acquisition is allowed. Expenses like electricity or platform fees cannot be claimed.
    • No Loss Set-off: Losses from one crypto asset cannot be adjusted against gains from another.

    The 1% TDS Mandate

    A 1% Tax Deducted at Source (TDS) under Section 194S is applicable on transactions exceeding ₹50,000 annually for specified persons.


    New for 2026: The Global Reporting Standard

    India has integrated with the Crypto-Asset Reporting Framework (CARF).

    The Income Tax Department now receives transaction data from international exchanges.

    This means offshore holdings are no longer invisible to regulators, and global compliance is now mandatory.


    Classifying Different Crypto Activities

    Taxation varies depending on how you engage with crypto assets:

    • Staking & Yield Farming: Taxed as “Income from Other Sources” at the time of receipt.
    • Airdrops & Gifts: Taxable if value exceeds ₹50,000.
    • Mining: Cost of acquisition is considered zero, making full sale value taxable.

    Why Compliance is Getting Complex: The PMLA Factor

    Crypto transactions now fall under the Prevention of Money Laundering Act (PMLA).

    Investors must maintain detailed records, including wallet addresses and transaction logs, for at least six years.


    How Lawizer Simplifies Crypto Compliance

    Tracking crypto transactions across exchanges and DeFi platforms can be overwhelming.

    Lawizer provides a streamlined solution for managing crypto tax compliance and audit readiness.

    Why Choose Lawizer?

    1. Automated Audit Trails: Generates tax-ready reports based on latest compliance rules.
    2. PMLA Compliance Support: Ensures AML and KYC adherence.
    3. Legal Review: Helps ensure tokens and smart contracts align with regulatory guidelines.

    Filing Your Returns: ITR-2 and ITR-3

    When filing your Income Tax Returns (AY 2026–27), ensure accurate reporting:

    • Schedule VDA: Report acquisition and transfer details.
    • Schedule FA: Mandatory for foreign-held crypto assets.

    Failure to disclose foreign assets may attract penalties up to ₹10 lakh under applicable laws.


    The Road Ahead: Regulation vs Innovation

    India is moving toward a “Regulate to Protect” approach under global frameworks like the G20 coordination model.

    The Reserve Bank of India (RBI) is also advancing its Digital Rupee initiative, which will further define the future of digital assets.


    Conclusion: Don’t Trade in the Dark

    In 2026, transparency is essential for crypto investors. Compliance is no longer optional—it is critical for protecting your assets.

    Using platforms like Lawizer ensures that your crypto investments remain legally secure and audit-ready.


    Frequently Asked Questions

    Is the 30% tax on crypto profits still mandatory in 2026?

    A: Yes. Under Section 115BBH, crypto income is taxed at 30% plus surcharge and cess.

    Can I offset losses between different cryptocurrencies?

    A: No. Losses cannot be set off against gains from other VDAs.

    What is the purpose of 1% TDS?

    A: It helps the government track transactions and can be claimed as tax credit.

    Do I need to report crypto held on foreign exchanges?

    A: Yes. It must be disclosed in Schedule FA to avoid heavy penalties.

    How is staking income taxed?

    A: It is taxed at receipt as income and again at sale under capital gains rules.

    Are crypto-to-crypto swaps taxable?

    A: Yes. They are treated as transfers and taxed accordingly.

  • The Rise of Green Credits: New Tax Incentives for India’s Eco-Startups in 2026

    The Rise of Green Credits: New Tax Incentives for India’s Eco-Startups in 2026

    Introduction

    The global shift toward sustainability is no longer a corporate social responsibility (CSR) footnote—it is a core economic driver. In India, the year 2026 marks a defining moment for the Green Economy.

    With the operationalization of the Green Credit Program (GCP) and new tax incentives introduced in the Union Budget, eco-startups are moving to the center of institutional investment.


    Defining the Green Credit Program (GCP)

    Unlike traditional carbon credit systems that focus only on emissions reduction, the Green Credit Rules, 2023 take a broader approach to environmental impact.

    Green Credits are awarded for the following activities:

    • Tree Plantation: Increasing green cover through afforestation.
    • Water Management: Conservation and wastewater treatment.
    • Sustainable Agriculture: Promoting organic farming and land restoration.
    • Waste Management: Recycling initiatives and circular economy models.

    How the Ecosystem Functions

    The system is administered by the Indian Council of Forestry Research and Education (ICFRE).

    Startups must register projects on the Green Credit Portal and undergo verification before credits are issued.


    Tax Incentives: The 2026 Fiscal Push

    The Union Budget 2026 introduces strong financial incentives to support green businesses.

    Section 80-IBA Extension for Green Housing

    Startups working on green buildings certified by the Bureau of Energy Efficiency (BEE) can claim extended tax benefits.

    This includes eligibility for 100% profit deductions for sustainable infrastructure projects.

    Accelerated Depreciation on Green Technology

    Under the Income Tax Act, eco-startups can claim up to 40% accelerated depreciation on green equipment.

    Angel Tax Exemptions

    Investments in DPIIT-recognized startups focused on climate solutions are exempt from Angel Tax if used for green capital expenditure.


    The Tradability of Impact: ESG and Green Credits

    Demand for Green Credits is driven by large listed companies in India.

    Under the SEBI BRSR framework, companies must disclose environmental performance.

    • Marketplace: Startups can sell Green Credits to corporations.
    • Revenue Stream: Provides additional and stable income.
    • Compliance Tracking: Monitor disclosures via the Ministry of Corporate Affairs.

    Navigating the Regulatory Framework

    To qualify for Green Credits and incentives, startups must comply with strict regulations.

    1. Verification: Conducted by the Central Pollution Control Board (CPCB) and auditors.
    2. Digital Tracking: Credits are digitally recorded to prevent misuse.
    3. FEMA Compliance: Required for foreign funding under RBI guidelines.

    Challenges in the Green Credit Market

    Despite growth, eco-startups face key challenges:

    • Price Volatility: Credit values fluctuate based on demand.
    • Verification Delays: Credit issuance may take 6–12 months.

    The Future of Green Credits

    The government is working on integrating Green Credits with global carbon markets.

    Under Article 6 of the Paris Agreement, startups may soon convert Green Credits into Carbon Credits for international trade.


    Strategic Checklist for Eco-Founders

    • DPIIT Recognition: Register on Startup India.
    • BEE Certification: Obtain energy efficiency certifications.
    • Audit Trail: Maintain digital environmental records.

    How Lawizer Powers Your Green Startup

    Managing environmental compliance and tax regulations can be complex. Lawizer simplifies this process through advanced legal-tech solutions.

    It helps automate registration, manage documentation, and track compliance requirements across multiple government frameworks.

    Why Choose Lawizer?

    • Automated Compliance: Reduces manual effort.
    • Regulatory Tracking: Stay updated with policy changes.
    • Documentation Support: Ensure accuracy and compliance.
    • Centralized Dashboard: Manage everything in one place.

    Build a sustainable business with confidence using Lawizer.


    Conclusion: Scalability Through Sustainability

    Green Credits are emerging as a key asset in India’s startup ecosystem.

    The future belongs to businesses that not only generate profits but also contribute to environmental restoration.


    Frequently Asked Questions

    What is the difference between Carbon Credits and Green Credits?

    A: Carbon Credits focus on emission reduction, while Green Credits reward broader environmental actions like water conservation and waste management.

    Can startups claim both tax benefits and Green Credits?

    A: Yes. Startups can earn Green Credits while also claiming tax incentives under relevant provisions.

    How can Green Credits be monetized?

    A: Verified credits can be sold to corporations that need them for ESG compliance.

    Are eco-startups exempt from Angel Tax?

    A: Yes, DPIIT-recognized startups working on green initiatives are generally exempt.

    What are FEMA requirements for green funding?

    A: Foreign investments must comply with RBI guidelines, including rules for external borrowings.

    Who verifies environmental impact?

    A: Agencies like CPCB and authorized auditors verify environmental claims.

  • Self-Certification for Labor Laws: How to Simplify Your Compliance in 2026

    Self-Certification for Labor Laws: How to Simplify Your Compliance in 2026

    Introduction

    For the modern Indian entrepreneur, “Labor Law Compliance” often evokes images of dusty registers, surprise inspections, and mountain-high paperwork.

    However, as India moves toward a more digitized and pro-business regulatory environment, the Self-Certification Scheme has emerged as a game-changer.

    In 2026, self-certification is no longer just an alternative; it is the gold standard for startups and MSMEs looking to scale without the friction of traditional inspections.

    This guide explains how you can leverage self-certification to simplify your compliance roadmap.


    What is the Self-Certification Scheme?

    Self-certification is a simplified compliance mechanism that allows employers to certify their own adherence to various labor laws through an online portal.

    Instead of routine physical inspections by labor officers, businesses provide a legal undertaking confirming that they comply with statutory requirements.

    The Startup India Advantage

    Under the Startup India Action Plan, recognized startups can self-certify compliance for 9 labor laws and 3 environmental laws.

    For the first 3 to 5 years, startups are exempt from inspections unless a credible written complaint is filed.


    Key Labor Laws Covered Under Self-Certification

    The central framework generally covers the following major labor laws:

    • The Building and Other Construction Workers Act, 1996: Regulates safety and welfare of construction workers.
    • The Inter-State Migrant Workmen Act, 1979: Protects rights of workers employed across states.
    • The Payment of Gratuity Act, 1972: Governs employee retirement benefits.
    • The Employees’ Provident Funds Act, 1952: Managed by the EPFO.

    The Shift to the Shram Suvidha Portal

    The Shram Suvidha Portal, launched by the Ministry of Labour & Employment, acts as a unified compliance platform.

    It provides a single window for multiple labor law requirements.

    1. LIN Generation: Every business gets a unique Labour Identification Number.
    2. Online Returns: File a unified annual return covering multiple laws.
    3. Transparent Inspections: Inspections are randomized through a system-based algorithm.

    How to Apply for Self-Certification

    Step 1: DPIIT Recognition

    Startups must obtain DPIIT recognition to access self-certification benefits and inspection exemptions.

    Step 2: Register on Shram Suvidha Portal

    Register using your PAN and business details on the Shram Suvidha Portal and activate your LIN.

    Step 3: File Unified Annual Return

    Submit the Unified Annual Return (UAR) instead of filing multiple returns for EPF, ESI, and other laws.


    Why Self-Certification is the Best Strategy in 2026

    The shift from “Inspector Raj” to “Self-Regulation” offers significant advantages:

    • Cost Efficiency: Reduces reliance on manual compliance consultants.
    • Risk Control: Encourages internal audits and reduces violations.
    • Investor Confidence: Clean compliance history improves due diligence outcomes.

    How Lawizer Simplifies the Process

    Managing multiple compliance portals can be complex. Lawizer simplifies this through an automated legal-tech platform.

    It integrates with government systems to track deadlines, auto-fill returns, and maintain audit-ready records.

    Why Choose Lawizer?

    • Automated Compliance: Reduces manual effort.
    • Deadline Tracking: Never miss filings.
    • Audit-Ready Records: Maintain digital registers.
    • Centralized Dashboard: Manage all compliance in one place.

    Simplify compliance and scale your business with Lawizer.


    Conclusion: The Era of Informed Compliance

    Self-certification represents a shift toward trust-based governance and digital compliance.

    By adopting modern tools and government platforms, businesses can focus on growth rather than administrative burden.


    Frequently Asked Questions

    Does self-certification eliminate inspections?

    A: No. Routine inspections are removed, but complaint-based inspections can still occur.

    Is self-certification available for all industries?

    A: Most service-based and non-hazardous businesses qualify. Hazardous industries may still require inspections.

    Can EPF and ESI be self-certified?

    A: Yes. Compliance can be managed through the unified portal, though contributions must be paid regularly.

  • Navigating the New GST E-Invoicing Limits for 2026: A Roadmap for Compliance

    Navigating the New GST E-Invoicing Limits for 2026: A Roadmap for Compliance

    Introduction

    In the world of Indian indirect taxation, the “Paperless Revolution” has reached its final frontier.

    As of 2026, the Goods and Services Tax (GST) framework has shifted from an optional digital convenience to a mandatory real-time reporting requirement for almost the entire organized sector.

    The latest lowering of e-invoicing turnover thresholds has brought lakhs of small and medium enterprises (SMEs) into the digital net.

    In 2026, compliance is no longer a monthly filing task—it is a live, transaction-by-transaction responsibility.


    What are the New E-Invoicing Limits for 2026?

    The phased implementation of e-invoicing started in 2020 for large corporations. Since then, the GST Council has systematically lowered this threshold to digitize the supply chain and curb tax evasion.

    The 2026 Threshold Shift

    Starting in the 2026 fiscal year, any business with an aggregate turnover exceeding ₹2 Crores in any preceding financial year (from 2017-18 onwards) is now mandated to generate e-invoices for all B2B transactions and exports.

    Why This Matters for Your Business

    • Universal Digitization: This pulls in almost every stable SME and high-growth startup in India.
    • Input Tax Credit (ITC): Customers cannot claim ITC unless you provide a valid e-invoice with a unique Invoice Reference Number (IRN).

    Understanding the E-Invoicing Workflow

    E-invoicing does not mean generating an invoice directly on the GST portal. Instead, invoices are created in your accounting system and reported to the Invoice Registration Portal (IRP).

    The Step-by-Step Process

    1. Generation: Create the invoice in your ERP or accounting software.
    2. Reporting: Upload the invoice JSON file to the IRP.
    3. Validation: The IRP validates and generates a unique 64-character IRN and QR Code.
    4. Auto-Population: Data is pushed to GSTR-1 and the buyer’s GSTR-2B.

    The Risks of Non-Compliance

    In 2026, the Central Board of Indirect Taxes and Customs (CBIC) has tightened oversight on GST compliance.

    • Invalid Invoices: Without an IRN, invoices are not legally valid.
    • Heavy Penalties: 100% of tax due or ₹10,000 per invoice (whichever is higher).
    • Blocked Logistics: Without e-invoicing, generating an E-Way Bill becomes difficult.
    • Loss of Business: Buyers prefer compliant vendors to secure ITC benefits.

    How Lawizer Simplifies E-Invoicing

    For businesses crossing the ₹2 Crore threshold, technical integration can be complex. Lawizer provides a seamless solution to simplify compliance.

    Why Choose Lawizer?

    • One-Click IRN Generation: Direct invoice generation from your dashboard.
    • Error Validation: AI-based checks prevent GSTIN and HSN errors.
    • ITC Reconciliation: Auto-match vendor invoices with purchase records.
    • GSTN Integration: Smooth connectivity with the GST network.

    Stay compliant and scale your business effortlessly with Lawizer.


    Conclusion: Compliance as a Competitive Edge

    The 2026 e-invoicing mandate signals a shift toward real-time tax transparency in India.

    While initial adaptation may seem complex, benefits like faster ITC claims and reduced audits make it worthwhile.

    With expert support from Lawizer, businesses can remain compliant, efficient, and growth-focused.


    Frequently Asked Questions

    Does the ₹2 Crore limit apply to current turnover?

    A: No. It applies if turnover exceeded ₹2 Crores in any previous financial year since 2017-18.

    Is e-invoicing required for B2C transactions?

    A: No. It is currently mandatory only for B2B, B2G, and export transactions.

    Can an e-invoice be canceled?

    A: Yes, but only within 24 hours on the IRP. After that, a credit note must be issued.

  • Union Budget 2026: The Strategic “Operating System” for Indian Tech Startups

    Union Budget 2026: The Strategic “Operating System” for Indian Tech Startups

    Introduction

    The Union Budget 2026-27 has officially signaled the end of the “quick-fix” subsidy era.

    Finance Minister Nirmala Sitharaman has instead unveiled a structural “Operating System” for the Indian tech ecosystem—focusing on long-term infrastructure, tax predictability, and a massive bet on the Orange Economy.

    For the Indian tech ecosystem, this isn’t just another fiscal plan; it’s a strategic blueprint for the next decade of innovation.

    As India marches toward Viksit Bharat 2047, the 2026 budget provides the “predictable rails” necessary for startups to transition from disruptors to national infrastructure.

    In this guide, we break down the key takeaways every founder, investor, and tech professional must understand.


    Startup India Fund of Funds (FFS) 2.0 Boost

    The government has approved Startup India Fund of Funds 2.0 with a fresh corpus of ₹10,000 crore.

    This version prioritizes DeepTech, AI, and SpaceTech, aiming to reduce risks for investors in high-gestation sectors.

    • Impact: Increased domestic venture capital with government acting as an anchor investor.
    • Next Step: Founders should align their pitch decks with national priority sectors via Startup India.

    Tax Reforms and Startup Benefits

    The budget brings major clarity and incentives for startups under tax laws.

    Extension of Section 80-IAC Tax Holiday

    Startups incorporated until March 31, 2030 can claim 100% tax deduction for three consecutive years.

    The turnover eligibility limit has increased to ₹150 crore, allowing scaling startups to benefit longer.

    Check eligibility through Lawizer.

    New Income Tax Act (Effective April 1, 2026)

    • Share Buybacks: Now taxed as capital gains, improving employee and investor returns.
    • MAT Reduction: Lowered to 14%, allowing better reinvestment capacity.

    Safe Harbour for SaaS and ITeS

    A new Global SaaS Safe Harbour reduces transfer pricing disputes.

    • Threshold: Increased to ₹2,000 crore.
    • Benefit: Fixed 15.5% margin reduces litigation and encourages reverse flipping.

    This reform addresses long-standing concerns with the Income Tax Department.


    Growth of the Orange Economy (AVGC)

    The government has recognized the AVGC sector (Animation, VFX, Gaming, Comics) as a major growth engine.

    Plans include setting up creator labs in 15,000 schools to build a future-ready workforce.

    This creates opportunities for startups in EdTech, MediaTech, and Gaming via institutions like Indian Institute of Creative Technologies.


    DeepTech and Semiconductor Push

    The India Semiconductor Mission (ISM) 2.0 has been allocated ₹40,000 crore.

    • Data Centers: Tax holiday until 2047 for global cloud providers.
    • R&D Incentives: Reduced tax friction for research-driven startups.

    E-commerce Export Boost (D2C)

    The removal of the ₹10 lakh export cap simplifies global shipping for startups.

    D2C brands can now scale exports seamlessly via logistics partners.

    The ONDC network will enable global storefront access for Indian businesses.


    Simplified Export Returns and Compliance

    The government introduced a Digital Export Feedback Loop through the DGFT portal.

    This allows duty-free re-import of returned goods, protecting margins for exporters.


    Focus on AI Skills and Employability

    The budget shifts focus from job creation to skill development.

    A new committee aims to bridge gaps between education and employment in AI-driven industries.

    Support is enhanced through the Anusandhan National Research Foundation (ANRF).


    Ease of Doing Business Improvements

    The government has decriminalized minor compliance defaults to promote a trust-based system.

    • Tax Disputes: Pre-deposit reduced from 20% to 10%.
    • TReDS Mandate: Faster payments for startups via receivable discounting systems.

    Conclusion: Building for 2047

    The Union Budget 2026 integrates startups into India’s long-term economic infrastructure.

    Build for the world, solve for India, and growth will follow.

    By aligning with Viksit Bharat 2047, founders can unlock significant opportunities.


    Frequently Asked Questions

    What is the new Safe Harbour threshold for SaaS startups?

    A: The threshold has been increased to ₹2,000 crore, allowing companies to opt for a fixed 15.5% margin and avoid transfer pricing disputes.

    How does the cloud tax holiday work?

    A: Foreign cloud providers using Indian data centers get a tax holiday until 2047, with domestic compliance requirements.

    What are the benefits for D2C startups?

    A: Removal of export caps and simplified logistics enable easier global expansion via DGFT.

    What is the Orange Economy?

    A: It refers to AVGC sectors like animation, gaming, and media, now supported by government initiatives.

    How is the AI talent gap addressed?

    A: Through education reforms and a dedicated committee aligning curriculum with AI and deep-tech needs.

    Is there support for startup liquidity?

    A: Yes, TReDS ensures faster payments to startups, improving cash flow cycles.

  • Drafting Virtual Contracts: Legal Validity in the Indian Market (2026)

    Drafting Virtual Contracts: Legal Validity in the Indian Market (2026)

    Introduction

    In the rapid-fire world of the Indian startup ecosystem, the traditional “wet ink” signature is fast becoming a relic of the past. From SaaS subscriptions to high-stake founder agreements, the Virtual Contract is now the primary vehicle for commerce.

    However, as we move through 2026, a critical question remains: Is a digital agreement truly as enforceable as a paper one in an Indian court?

    The answer is a resounding yes, provided you navigate the specific intersection of the IT Act and the Indian Evidence Act correctly.


    The Legal Pillars: IT Act, 2000 and Beyond

    The bedrock of virtual contracting in India is the Information Technology Act, 2000. Section 10A of the Act specifically grants legal recognition to contracts formed through electronic means.

    What Constitutes a Valid Virtual Contract?

    Under Indian law, a contract is formed when an offer is made and accepted with lawful consideration. In the digital realm, this typically happens through:

    • Click-wrap Agreements: The ubiquitous “I Agree” checkboxes.
    • Browse-wrap Agreements: Terms linked at the footer of a website.
    • E-Signatures: Documents signed via Aadhaar-based eSign or digital signature certificates (DSC).

    The Admissibility of Electronic Records

    In 2026, judicial scrutiny of digital evidence is highly sophisticated. For a virtual contract to hold up during litigation, it must comply with Section 65B of the Indian Evidence Act, 1872 (now integrated into the Bharatiya Sakshya Adhiniyam).

    The Certificate Requirement

    To present a virtual contract as evidence, a business must produce a Section 65B Certificate. This document certifies the authenticity of the computer output and ensures the electronic record has not been tampered with.

    Pro Tip: Courts now demand “Audit Trails”—digital logs showing the exact timestamp, IP address, and device ID of the signer.


    The “Stamping” Hurdle: Can Digital Be Stamped?

    A common pitfall in drafting virtual contracts is the payment of Stamp Duty. Under the Indian Stamp Act, 1899, an unstamped contract is generally inadmissible in court.

    E-Stamping in 2026

    Most Indian states have now integrated e-Stamping services. For a virtual contract to be “bulletproof,” the digital document should be associated with an e-Stamp certificate. Failing to do this can lead to penalties—often up to 10 times the original stamp duty amount.


    Specific Exclusions: When Digital is Not Enough

    Despite the digital push, certain documents cannot be executed virtually in India:

    1. Negotiable Instruments: Such as Promissory Notes (excluding cheques).
    2. Power of Attorney: Generally requires physical execution.
    3. Trust Deeds and Wills: These necessitate physical “wet” signatures.
    4. Real Estate Transfers: Sale deeds still require physical registration at the Sub-Registrar’s Office.

    How Lawizer Secures Your Virtual Agreements

    Drafting a contract is only half the battle; ensuring its “evidentiary weight” is the other half. Lawizer, a premier legal-tech firm, transforms your digital workflow into a secure legal asset.

    Lawizer’s “Smart-Contract” Suite Offers

    • Automated Audit Trails: Captures comprehensive metadata for every signature, auto-generating required legal certificates.
    • Integrated E-Stamping: Seamlessly procure and attach e-Stamps within the platform.
    • Aadhaar e-Sign Integration: Uses the UIDAI framework for secure authentication.

    Make your digital agreements legally strong and court-ready with Lawizer.


    Conclusion: Designing for Defensibility

    In 2026, the validity of a virtual contract depends on the infrastructure behind it.

    By combining sound legal drafting with robust technical verification, businesses can significantly reduce litigation risk.

    Partnering with tech-legal platforms like Lawizer ensures your digital agreements are as enforceable as traditional contracts.


    Frequently Asked Questions

    Is an email exchange a valid contract in India?

    A: Yes, provided essential contract elements exist. However, proving identity is harder without formal e-signature tools.

    Are “I Agree” checkboxes legally binding?

    A: Yes, click-wrap agreements are valid if terms are clearly communicated.

    What is the difference between an E-signature and a Digital Signature?

    A: An E-signature is a broad category (like Aadhaar eSign), while a Digital Signature (DSC) is a secure, certificate-based signature issued by a Certifying Authority (CA).

  • What to Do If Your Cheque Bounces: Legal Steps Under Section 138 NI Act

    What to Do If Your Cheque Bounces: Legal Steps Under Section 138 NI Act

    Introduction

    Dealing with a bounced cheque can be a highly frustrating experience. Whether you are a business owner waiting on a critical client payment, a landlord collecting rent, or an individual expecting the repayment of a friendly loan, an unpaid cheque disrupts your cash flow and breaches your trust.

    However, Indian law provides a robust mechanism to protect payees and penalize defaulters.

    If you are wondering exactly what to do if your cheque bounces, the Negotiable Instruments (NI) Act, 1881, specifically Section 138, is your primary legal weapon.

    Navigating this process requires strict adherence to timelines and procedures.

    In this article, we will discuss everything related to cheque bounce cases and how Lawizer helps simplify this process, making it easier for you to draft your legal notice and take swift action.


    What is Cheque Dishonour and Why is it a Criminal Offence in India?

    A cheque is said to be “dishonoured” or “bounced” when a bank refuses to pay the amount mentioned on the cheque to the payee.

    The bank returns the cheque along with a “Cheque Return Memo” stating the specific reason for the bounce. Common reasons include:

    • Insufficient funds
    • Signature mismatch
    • Account closed
    • Payment stopped by the drawer

    Historically, cheque bounce cases were treated as civil disputes, leading to long delays in recovery.

    To address this, Section 138 of the Negotiable Instruments Act was introduced, making cheque dishonour a criminal offence under specific conditions.


    Why is Cheque Bounce a Criminal Offence?

    The objective behind criminalizing cheque bounce is to maintain trust in financial transactions and ensure smooth business operations.

    The law imposes strict liability, meaning the burden of proof lies on the drawer if the cheque bounces due to insufficient funds.

    This discourages misuse of cheques and ensures accountability in financial dealings.


    The 30-15-30 Rule You Must Follow

    Time is critical in cheque bounce cases. Missing deadlines can weaken your case significantly.

    1. 30-Day Notice Period

    You must send a legal notice within 30 days from receiving the cheque return memo.

    2. 15-Day Payment Window

    The drawer gets 15 days to make payment after receiving the notice.

    3. 30-Day Court Filing Window

    If payment is not made, you must file a case within 30 days after the 15-day period expires.


    Example Timeline

    • March 1: Return memo received
    • March 20: Legal notice sent
    • March 25: Notice received
    • April 9: Payment deadline ends
    • May 9: Last date to file case

    How to Draft a Legal Notice for Cheque Bounce

    A legal notice is the foundation of your case. Any error can weaken your claim.

    Key Elements to Include

    • Transaction details
    • Cheque details
    • Reason for dishonour
    • Demand for payment
    • Legal warning

    How to Send the Notice

    Always send the notice via Registered Post or Speed Post to ensure proof of delivery.


    Filing a Case Under Section 138

    If payment is not made, you can file a criminal complaint before the Magistrate.

    Jurisdiction

    The case must be filed where your bank branch is located.

    Required Documents

    • Original cheque
    • Cheque return memo
    • Legal notice copy
    • Proof of delivery
    • Supporting documents

    What Relief Can You Get?

    • Imprisonment: Up to 2 years
    • Fine: Up to twice the cheque amount
    • Interim Compensation: Up to 20% during trial

    Out-of-Court Settlement Options

    Cheque bounce cases can be settled outside court as they are compoundable offences.

    • Mediation and Lok Adalat settlements
    • Mutual agreement between parties
    • Payment with interest or legal costs

    How Lawizer Helps You

    Lawizer simplifies cheque bounce cases by connecting you with verified legal professionals.

    Why Choose Lawizer?

    • Expert legal notice drafting
    • Verified lawyers
    • End-to-end case support
    • Affordable pricing
    • Quick turnaround

    Take action today and recover your money faster.


    Conclusion

    A bounced cheque is not just an inconvenience—it is a serious financial issue.

    By following the legal process and acting within deadlines, you can effectively recover your money.

    Taking timely legal action ensures accountability and protects your financial interests.

    Take control of the situation and act swiftly with Lawizer.


    Frequently Asked Questions

    Is Lawizer a legit company?

    A: Yes, Lawizer is a legitimate legal-tech platform in India.

    Is Lawizer a law firm?

    A: No, it is a legal-tech platform connecting users with lawyers.

    Can I file a case if I miss the 30-day notice deadline?

    A: No, but you can still pursue a civil case for recovery.

    What if partial payment is made?

    A: You can proceed legally for the remaining amount.

    Will the bank take legal action for me?

    A: No, you must initiate legal proceedings yourself.

    Will the defaulter go to jail immediately?

    A: No, imprisonment happens only after trial and conviction.

  • How to Recover Money from a UPI Scam in India: A Step-by-Step Guide

    How to Recover Money from a UPI Scam in India: A Step-by-Step Guide

    Introduction

    India’s rapid adoption of digital payments has made transferring money as easy as sending a text. Unfortunately, scammers have also levelled up their game.

    If you have just realized that you are the victim of a UPI fraud, take a deep breath. Panic is a natural reaction, but acting swiftly and methodically is your best weapon.

    Time is the most critical factor in recovering stolen funds. Here is a complete guide on what to do, your rights under the law, and how to navigate the recovery process with the help of Lawizer.


    How Common UPI Scams Work

    Scammers constantly invent new ways to trick victims, but most UPI frauds fall into common patterns:

    • Fake QR Codes: Fraudsters send QR codes claiming money will be credited. In reality, scanning it initiates a payment.
    • Rule of Thumb: You never need to scan a QR code or enter your UPI PIN to receive money.
    • Screen Sharing Apps: Scammers posing as customer support ask you to install apps like AnyDesk or TeamViewer, gaining access to OTPs and sensitive data.
    • Vishing (Voice Phishing): Fraudsters impersonate bank officials or authorities to trick you into revealing your UPI PIN or OTP.

    Immediate Steps to Take Within the First Hour

    The first 60 minutes after a scam are often referred to as the “Golden Hour.” Acting quickly significantly improves your chances of recovery.

    1. Block Your Account: Contact your bank immediately to freeze your account and disable your UPI ID.
    2. Call the Helpline (1930): Report the fraud to the national cybercrime helpline. Authorities may freeze the scammer’s account if the funds are still in transit.
    3. Seek Immediate Guidance: Use the Lawizer SOS button for instant legal and financial assistance.


    How to File a Complaint on the Cybercrime Portal

    Once your accounts are secure, filing an official complaint is essential.

    1. Visit the official portal: cybercrime.gov.in.
    2. Create an account using your mobile number.
    3. Provide detailed information including transaction ID (UTR), date, time, and supporting evidence.
    4. Submit the complaint and save the acknowledgment number.

    RBI Guidelines on Fraud Liability

    The Reserve Bank of India (RBI) provides protection for victims of unauthorized electronic transactions.

    If you report fraud within 3 working days, your liability is zero, and the bank must compensate the loss.

    If reported within 4 to 7 working days, liability is limited (typically ₹10,000–₹25,000 depending on account type).


    Filing an FIR: What to Include and Why it Matters

    In addition to the cybercrime portal, filing an FIR at your local police station or cyber cell strengthens your case.

    Include the following details:

    • Timeline of events
    • Transaction IDs and bank details
    • Scammer’s phone number or UPI ID
    • Screenshots and supporting evidence

    A well-drafted FIR ensures your complaint is taken seriously and avoids delays.


    How to Escalate if the Bank Doesn’t Cooperate

    If your bank fails to resolve the issue within 30 days or rejects your complaint unfairly, you can escalate the matter.

    File a complaint with the RBI Banking Ombudsman through the CMS portal.


    How Lawizer Helps with Cybercrime Complaints

    Navigating police procedures and bank systems can be overwhelming. Lawizer simplifies the process by providing expert legal assistance.

    Why Choose Lawizer?

    • 24/7 SOS Emergency Support
    • Free Initial Legal Consultation
    • Expert FIR & Complaint Drafting
    • Digital Case Tracking Dashboard
    • Verified Legal Experts
    • Transparent Pricing

    Get expert help and improve your chances of recovering lost funds.


    Conclusion

    Losing money to a UPI scam is stressful, but quick action can significantly improve recovery chances.

    By securing your accounts, reporting immediately, leveraging RBI protections, and seeking professional support, you can take control of the situation.

    With the right steps and tools, fighting back against fraud is possible.


    Frequently Asked Questions

    What exactly is Lawizer?

    A: Lawizer is a legal-tech platform that helps individuals handle legal issues like cyber fraud with expert support.

    Is Lawizer a legitimate platform?

    A: Yes, it is a reliable and transparent legal-tech solution.

    Is Lawizer a law firm?

    A: No, it is a technology platform that simplifies legal processes.

    How do I reset a forgotten UPI PIN?

    A: Use your UPI app to reset your PIN via debit card or Aadhaar authentication with OTP verification.

  • Loan Agreement in India: Key Clauses Every Borrower Must Read Before Signing

    Loan Agreement in India: Key Clauses Every Borrower Must Read Before Signing

    Introduction

    Getting approved for a loan—whether it is for a new home, a car, or scaling your business—is an exciting milestone. However, the excitement often overshadows the most critical step of the process: reading the fine print.

    Borrowers in India frequently sign lengthy legal documents without reviewing them carefully, assuming they are standard non-negotiable templates. This can lead to serious financial and legal consequences later.

    Here is a comprehensive guide to understanding your loan agreement and the key clauses you must review before signing.


    Why a Loan Agreement is Legally Binding

    A loan agreement is not just a document issued by a bank—it is a legally binding contract governed by the Indian Contract Act, 1872.

    Once signed, it binds both the borrower and the lender. While you are obligated to repay the loan, the bank must also follow the agreed terms.

    This means lenders cannot arbitrarily change core conditions without adhering to the contract, giving you legal grounds to hold them accountable.


    Key Clauses You Must Always Read

    Do not let legal jargon overwhelm you. Focus on these critical clauses:

    • Interest Rate (Fixed vs Floating): Check whether your rate is fixed or fluctuates with market conditions and how often it resets.
    • Prepayment & Foreclosure Charges: Some banks charge penalties for early repayment, although RBI restricts this for certain loans.
    • Default Clause: Understand what qualifies as a default, including cross-default triggers linked to other loans.

    What is the MITC Document?

    The RBI requires lenders to provide a Most Important Terms and Conditions (MITC) document.

    This is a simplified summary of your loan’s key aspects such as interest rates, penalties, and charges.

    Always review the MITC carefully—it is designed for transparency and quick understanding.


    Hidden Charges You Must Watch Out For

    The advertised interest rate is not the only cost. Pay attention to:

    • Processing Fees: One-time non-refundable charges.
    • Penal Charges: Fees applied when you miss EMI payments.
    • Additional Costs: Legal, valuation, documentation, or insurance charges bundled into the loan.

    What Happens if You Default?

    If you default, the lender has legal remedies—but you also have rights:

    • SARFAESI Act: Banks can auction secured assets after proper notice.
    • Debt Recovery Tribunal (DRT): Handles large loan disputes where you can present your case.
    • Recovery Agent Rules: RBI prohibits harassment, abuse, or calls at odd hours.

    Can You Negotiate Loan Terms?

    Yes. A loan agreement is negotiable, especially if you have a strong credit profile.

    You may negotiate:

    • Lower interest margins
    • Processing fee waivers
    • Better prepayment terms

    Never hesitate to request changes before signing.


    How Does Lawizer Help You?

    Loan agreements are complex, and missing one clause can cost you significantly. Lawizer simplifies the process by providing expert legal assistance.

    Why Choose Lawizer?

    • Clause Analysis: Identifies hidden risks and unfair terms
    • Simple Explanation: Converts legal jargon into plain language
    • Negotiation Support: Helps you secure better terms
    • Legal Protection: Guidance against harassment or violations
    • Fully Online: Fast and affordable document review

    Protect your financial future before you sign.


    Frequently Asked Questions

    Can Lawizer help negotiate my loan agreement?

    A: Yes, Lawizer provides expert insights and actionable negotiation points.

    Is Lawizer a law firm?

    A: No, it is a legal-tech platform offering accessible legal solutions.

    What should I do if recovery agents harass me?

    A: File a complaint with the bank and escalate to RBI if needed.

    Can Lawizer help after signing the agreement?

    A: Yes, it can review active agreements and guide you on your rights.

  • How to Register a Copyright in India: Process, Cost, and What It Protects

    How to Register a Copyright in India: Process, Cost, and What It Protects

    Introduction

    Whether you are writing a novel, designing a logo, coding a new app, or producing music, your creative output is a valuable asset.

    In an age where digital theft and content scraping are rampant, protecting your intellectual property is no longer optional.

    Navigating intellectual property laws can feel intimidating, but understanding your rights is the first step to securing your work.

    Here is a complete guide on how to register a copyright in India, the costs involved, and the protections it guarantees and also how Lawizer can make the process easier.


    What is Copyright and What Types of Works are Automatically Protected?

    Copyright is a legal right granted to creators, giving them exclusive control over the use and distribution of their original work.

    Under the Indian Copyright Act, 1957, copyright is established automatically the moment an original work is created and fixed in a tangible medium.

    The law automatically protects:

    • Books, articles, and poems
    • Computer software and code
    • Paintings, photographs, and architectural designs
    • Musical compositions and song lyrics
    • Movies and audio recordings

    Why You Should Still Register Despite Automatic Protection

    If copyright is automatic, why go through the hassle of registering it? While you own the rights the moment you create the work, enforcing those rights without a certificate is difficult.

    Here is why registration is crucial:

    • Legal Evidence: A copyright certificate serves as prima facie evidence in court.
    • Statutory Damages: Easier to claim compensation in infringement cases.
    • Commercial Power: Required for licensing, selling, or transferring rights.

    Step-by-Step Copyright Registration Process

    Registering your work in India is done through the official government portal.

    1. Create an Account: Register on the portal.
    2. Fill Form XIV: Provide details of the work and author.
    3. Upload Work: Submit digital or physical copies.
    4. Pay Fees: Generate a diary number.
    5. Waiting Period: 30 days for objections.
    6. Examination: Review by authority.
    7. Registration: Certificate issued.

    Classes of Copyright Work

    Your work must fall under one of these categories:

    • Literary Works: Books, blogs, software.
    • Artistic Works: Logos, paintings, photographs.
    • Dramatic Works: Scripts and plays.
    • Musical Works: Compositions.
    • Sound Recordings: Audio tracks.
    • Cinematograph Films: Videos and films.

    Documents Required and Fees

    You will generally need:

    • Copies of the work
    • No Objection Certificate (if applicable)
    • Power of Attorney (if filed via agent)

    Government Fees

    • Literary/Artistic Works: ₹500
    • Logos (commercial use): ₹2,000
    • Films: ₹5,000
    • Sound Recordings: ₹2,000

    How Long Does Registration Take?

    The process typically takes 6 to 12 months due to the mandatory waiting period and examination process.


    Rights of a Copyright Owner

    As an owner, you get exclusive rights:

    • Reproduction: Make copies
    • Adaptation: Modify or translate
    • Communication: Share publicly
    • Moral Rights: Claim authorship and protect integrity

    How Lawizer Helps You

    The registration process can be complex. Lawizer simplifies it with expert assistance.

    Why Choose Lawizer?

    • End-to-End Filing
    • Document Preparation
    • Objection Handling
    • Status Tracking
    • Emergency Legal Support

    Protect your creative work with confidence.


    Conclusion

    Your creative work is valuable and deserves protection.

    While copyright exists automatically, registration strengthens your legal position and enables commercialization.

    With the right support, the process becomes simple and efficient.


    Frequently Asked Questions

    How long does copyright last in India?

    A: Lifetime of the author plus 60 years.

    Can I copyright an idea?

    A: No, only the expression of an idea is protected.

    What is Lawizer?

    A: Lawizer is a legal-tech platform simplifying legal services.

    Is Lawizer legitimate?

    A: Yes, it is a reliable platform.

    Is Lawizer a law firm?

    A: No, it is a legal-tech solution.

  • Non-disclosure agreement (NDA) India: When you need one and what to include

    Non-disclosure agreement (NDA) India: When you need one and what to include

    Introduction

    In today’s hyper-competitive business landscape, your ideas, data, and processes are your most valuable currency.

    Whether you are pitching a revolutionary app to an investor, hiring a new lead developer, or onboarding a manufacturing vendor, you have to share sensitive information to move forward.

    But how do you ensure the other party doesn’t steal your idea or leak your data to a competitor?

    This is where a Non-Disclosure Agreement (NDA) becomes your first line of defense.

    An NDA is a legally binding contract that establishes a confidential relationship between parties. It ensures that sensitive information shared for a specific purpose is not disclosed to unauthorized third parties.

    In this comprehensive guide, we will break down how NDAs work in India, when you need one, what clauses are non-negotiable, and how to enforce them if things go wrong. We will also see how Lawizer can help.


    What an NDA Protects and Its Legal Enforceability in India

    An NDA acts as a protective shield for anything that gives your business a competitive edge. This typically includes:

    • Trade Secrets: Algorithms, manufacturing processes, and formulas.
    • Business Information: Client lists, pricing strategies, financial records, and marketing plans.
    • Intellectual Property (IP): Unpublished patent applications, source code, and design prototypes.

    Is it legally enforceable in India? Yes. In India, NDAs are governed primarily by the Indian Contract Act, 1872.

    For an NDA to be valid, it must meet standard contract requirements: offer, acceptance, lawful object, consideration, and free consent.

    However, Section 27 restricts agreements that restrain trade or profession. Overly broad or unfair NDAs may be struck down.

    To be enforceable, confidentiality obligations must be reasonable in scope and duration.


    One-Way vs Mutual NDA

    1. One-Way (Unilateral) NDA

    Only one party shares confidential information.

    • Used for: Hiring employees, freelancers, consultants, or pitching ideas.

    2. Mutual (Bilateral) NDA

    Both parties share sensitive information.

    • Used for: Partnerships, joint ventures, mergers, and co-founder agreements.

    Key Clauses to Include in an NDA

    1. Definition of Confidential Information

    Clearly define what information is protected, such as source code, financial data, or client databases.

    2. Exclusions

    Specify what is not confidential:

    • Public domain information
    • Previously known information
    • Independently developed data
    • Legally required disclosures

    3. Duration

    Most NDAs last between 2 to 5 years. Perpetual clauses are usually not enforceable.

    4. Consequences of Breach

    Include rights to injunctions and monetary damages in case of violation.


    Common NDA Mistakes

    • Overly Broad Clauses: Makes agreement unenforceable.
    • No Stamp Duty: Must be executed on valid stamp paper.
    • Unclear Jurisdiction: Always define governing law and court location.

    Industries Where NDAs Are Essential

    • Tech & IT: Protect code and algorithms.
    • Healthcare: Secure patient and research data.
    • Manufacturing: Safeguard processes and designs.
    • Startups: Protect pitch decks and financial models.

    How to Enforce an NDA in India

    1. Gather Evidence: Document the breach.
    2. Send Legal Notice: Demand immediate action.
    3. Seek Injunction: Stop further disclosure.
    4. Claim Damages: Recover financial losses.

    Get a Custom NDA Drafted with Lawizer

    Using generic templates can expose your business to risks.

    Lawizer provides expert-drafted, customized NDAs tailored to Indian laws.

    Why Choose Lawizer?

    • India-Compliant Drafting
    • Customized Agreements
    • Strong Legal Protection
    • Fast Turnaround

    Protect your ideas before you share them.


    Conclusion

    An NDA is not just a formality—it is essential for protecting your business assets.

    Whether you are a startup or an established business, a well-drafted NDA ensures your confidential information remains secure.

    With proper legal support, you can collaborate and grow without fear.


    Frequently Asked Questions

    Is notarization mandatory for an NDA in India?

    A: No, but it must be executed on proper stamp paper.

    Can an NDA stop someone from joining a competitor?

    A: No, it only protects confidential information.

    Does an NDA cover verbal information?

    A: Yes, if documented later in writing.

    What is Lawizer?

    A: Lawizer is a legal-tech platform simplifying legal documentation.

    Is Lawizer legitimate?

    A: Yes, it is a trusted legal-tech solution.

    Is Lawizer a law firm?

    A: No, it is a legal-tech platform, not a law firm.

  • Employment Agreement in India: What Employers and Employees Must Know

    Employment Agreement in India: What Employers and Employees Must Know

    Introduction

    The foundation of any successful professional relationship is clarity. Whether you are a fast-growing startup bringing on your first hire or a seasoned professional evaluating a new job offer, the employment agreement is the most critical document you will handle.

    It dictates not just what you do and how much you get paid, but also your rights, obligations, and protections under Indian labour laws.

    A poorly drafted employment contract can lead to costly legal disputes, unprotected intellectual property, or unfair working conditions.

    In this comprehensive guide, we will break down everything both employers and employees need to know about employment agreements in India, including the legality of restrictive clauses, IP ownership, and how to ensure your contracts are airtight.

    We shall also discuss about Lawizer, a legal-tech platform that simplifies this process through expert legal support and technology-driven solutions.


    Is a Written Employment Agreement Legally Mandatory in India?

    Under the Indian Contract Act, 1872, a contract can technically be oral or written. However, in employment, an oral agreement is highly risky and practically unenforceable.

    Various state-specific Shops and Establishments Acts require employers to provide a formal appointment letter or written contract to employees.

    Therefore, despite central law allowing oral agreements, a written employment contract is essential for compliance, clarity, and legal protection.


    Essential Clauses Every Employment Agreement Needs

    A well-drafted employment agreement must clearly define all key terms to avoid disputes.

    • Designation and Scope of Work: Defines job role, reporting structure, and responsibilities.
    • Compensation and CTC Breakdown: Includes salary structure, allowances, deductions, and bonuses.
    • Probation Period: Typically 3–6 months with different notice terms.
    • Notice Period and Termination: Specifies exit terms and grounds for termination.
    • Leave Policy: Covers earned, sick, and casual leaves as per state laws.

    Restrictive Clauses: Non-Compete and Non-Solicitation

    Restrictive clauses protect business interests but must comply with Indian law.

    • Non-Compete Clauses: Post-employment non-competes are generally unenforceable under Section 27 of the Indian Contract Act. However, restrictions during employment are valid.
    • Non-Solicitation Clauses: Prevent employees from poaching clients or staff and are enforceable if reasonable.

    ESOP Provisions and Vesting Schedules

    Employee Stock Option Plans (ESOPs) are common in startups and must be clearly defined.

    • Grant: Number of options offered.
    • Vesting Schedule: Typically includes a 1-year cliff followed by phased vesting.
    • Exercise Price: Cost to convert options into shares.
    • Exit Conditions: Treatment of options on resignation or termination.

    IP Ownership and Moonlighting Rules

    Intellectual Property (IP)

    Employment contracts must include a Work for Hire and IP assignment clause to ensure all work created belongs to the employer.

    Moonlighting

    Dual employment is restricted under several Indian laws. Employers should include an Exclusivity Clause to prevent unauthorized secondary work.


    What Employees Must Check Before Signing

    1. Notice Period Symmetry: Ensure fairness for both parties.
    2. Hidden Salary Conditions: Verify bonus and performance-linked pay.
    3. Bond Clauses: Check for repayment obligations and ensure reasonableness.

    Draft Compliant Employment Agreements with Lawizer

    Using generic templates can lead to legal risks and unenforceable clauses.

    Lawizer helps businesses create legally compliant and customized employment agreements.

    Why Choose Lawizer?

    • State-Specific Compliance
    • Industry-Based Customization
    • Legally Enforceable Clauses
    • Fast Turnaround
    • Emergency Legal Support
    • Free Consultation
    • Transparent Pricing

    Secure your workforce with legally sound employment agreements today.


    Conclusion

    An employment agreement is the legal foundation of any professional relationship.

    For employers, it safeguards business interests and intellectual property. For employees, it ensures clarity, rights, and job security.

    With proper legal drafting and expert guidance, both parties can avoid disputes and build a transparent working relationship.


    Frequently Asked Questions

    Can an employer terminate an employee without notice?

    A: Yes, but only in cases of serious misconduct. Otherwise, notice or payment in lieu is required.

    Are employment bonds valid in India?

    A: They are enforceable only if reasonable and backed by actual training costs.

    What if I refuse to sign an employment agreement?

    A: Employers may withdraw the offer or initiate termination if terms are not accepted.

    Are digital signatures valid?

    A: Yes, under the Information Technology Act, 2000.

    Can employers change contract terms unilaterally?

    A: No, changes require mutual consent.

    What is Lawizer?

    A: Lawizer is a legal-tech platform that simplifies legal documentation and assistance.

    Is Lawizer legitimate?

    A: Yes, it is a reliable and technology-driven legal platform.

    Is Lawizer a law firm?

    A: No, it is a legal-tech platform, not a traditional law firm.

  • Gift Deed vs Will: Which is Better to Transfer Property to Family in India?

    Gift Deed vs Will: Which is Better to Transfer Property to Family in India?

    Introduction

    Deciding how to pass on your hard-earned property to your loved ones is a significant milestone. In India, property transfers within a family usually come down to two primary legal instruments: a Gift Deed or a Will.

    Both methods achieve the ultimate goal of transferring ownership, but they operate on entirely different timelines, carry distinct financial implications, and offer varying levels of protection against future family disputes.

    Choosing the wrong instrument can lead to unnecessary tax burdens, exorbitant stamp duties, or bitter legal battles for your heirs.

    In this comprehensive guide, we will break down the legal mechanics of Gift Deeds and Wills, compare their tax implications, and help you determine which option is the safest and most efficient for your specific situation.

    We shall also see how Lawizer, a legal-tech platform helps with the drafting of a gift deed or a will.


    What is a Gift Deed and How is it Executed?

    A Gift Deed is a legally binding document used to voluntarily transfer the ownership of a property from the owner (the donor) to another person (the done) without any financial exchange or consideration.

    Under the Transfer of Property Act, 1882, for a gift of immovable property to be legally valid, it must meet specific execution requirements:

    • Immediate Transfer: The transfer happens immediately during the lifetime of the donor.
    • Acceptance: The donee must accept the gift during the donor’s lifetime. If the done dies before accepting, the gift is void.
    • Registration is Mandatory: The gift deed must be signed, attested by two witnesses, and registered with the Sub-Registrar.
    • Irrevocability: Once registered and accepted, it is generally irrevocable.

    What is a Will and When Does it Come into Effect?

    A Will is a testamentary document that declares a person’s intention regarding the distribution of their assets after their death.

    Governed primarily by the Indian Succession Act, 1925, a Will differs significantly from a Gift Deed:

    • Takes Effect After Death: Beneficiaries receive rights only after the testator passes away.
    • Revocable: Can be modified or revoked anytime during lifetime.
    • Registration Optional: Not mandatory but recommended for authenticity.

    Key Differences: At a Glance

    Feature Gift Deed Will
    Time of Transfer Immediate After death
    Revocability Irrevocable Revocable anytime
    Registration Mandatory Optional
    Stamp Duty Applicable None
    Governing Law Transfer of Property Act Indian Succession Act

    Tax Implications of Each Method

    Income Tax and Capital Gains

    Under Section 56(2)(x) of the Income Tax Act, gifts received from specified relatives are exempt from tax.

    Gifts to non-relatives exceeding ₹50,000 are taxable.

    Inheritance through a Will is completely tax-free.

    Capital gains tax applies only when the recipient sells the property later.


    Stamp Duty

    Property transfer via a Will attracts zero stamp duty.

    A Gift Deed requires stamp duty (typically 2%–7%), depending on the state.


    Which is Safer from Legal Challenges?

    A Gift Deed is safer because it is executed and registered during the owner’s lifetime.

    A Will is more prone to disputes and can be challenged on grounds such as:

    • Unsound mind
    • Forgery
    • Coercion
    • Multiple Wills

    In cities like Mumbai, Kolkata, and Chennai, probate may also be required.


    When to Choose Gift Deed vs Will

    When a Gift Deed is Better:

    • Avoid disputes
    • Immediate transfer
    • No probate required
    • Financial security for family

    When a Will is Better:

    • Retain ownership during lifetime
    • Avoid stamp duty
    • Flexibility to change decisions
    • Distribute multiple assets

    Execute a Gift Deed or Draft a Will with Lawizer

    Property transfers require precise legal drafting.

    Lawizer ensures legally compliant, customized, and secure documentation.

    • Accurate Drafting
    • Personalized Advice
    • End-to-End Support
    • Legal Compliance
    • 24/7 Assistance

    Conclusion

    Both a Gift Deed and a Will are effective tools for property transfer.

    A Gift Deed ensures immediate, dispute-free transfer, while a Will offers flexibility and cost savings.

    Choosing the right option depends on your financial goals and family situation.


    Frequently Asked Questions

    Can a registered Gift Deed be cancelled?

    A: Generally no. It can only be cancelled in cases of fraud, coercion, or mutual agreement.

    Is it mandatory to register a Will in India?

    A: No, but registration is recommended for authenticity.

    Who pays stamp duty on a Gift Deed?

    A: Usually the recipient, unless agreed otherwise.

    Can I gift property to a non-relative?

    A: Yes, but it may attract tax.

    Do I need probate for a Will?

    A: Mandatory in Mumbai, Kolkata, Chennai; optional elsewhere.

    Is Lawizer a law firm?

    A: No, it is a legal-tech platform.

    Who is behind Lawizer?

    A: Lawizer is an initiative of Zeptus Pvt Ltd.

  • Angel Tax Exemptions under Section 80-IAC: A Founder’s Guide

    Angel Tax Exemptions under Section 80-IAC: A Founder’s Guide

    Introduction

    Starting a business in India is exciting, but founders often face complex tax rules while raising funds. One such issue that troubled startups for years was angel tax.

    To encourage innovation and investment, the government introduced several exemptions for eligible startups.

    One of the most important provisions founders should understand is Section 80-IAC of the Income Tax Act, 1961, which works alongside Startup India recognition and angel tax exemptions.

    In this guide, we explain what angel tax is, how Section 80-IAC benefits startups, eligibility requirements, and how founders can take advantage of these provisions.


    Understanding Angel Tax

    Angel tax refers to the tax imposed on startups when they raise funds at a valuation higher than the Fair Market Value (FMV) of their shares.

    This provision falls under Section 56(2)(viib) of the Income Tax Act.

    If a startup issues shares at a premium and the valuation is considered excessive, the excess amount is taxed as income from other sources.

    Example

    Suppose a startup issues shares with a face value of ₹10, but investors buy them at ₹100 per share.

    The difference of ₹90 per share may be taxed if the valuation cannot be justified.

    This created challenges because startups are valued based on future potential rather than current profits.


    Role of Section 80-IAC in Supporting Startups

    To promote entrepreneurship, the government introduced Section 80-IAC.

    This section provides a 100% tax deduction on profits for three consecutive years within the first ten years of incorporation.

    Although Section 80-IAC focuses on income tax benefits, startups eligible under this section and recognized under Startup India can also apply for angel tax exemption.

    It helps startups by:

    • Improving financial stability
    • Increasing investor confidence
    • Reducing tax burden in early stages

    Eligibility Criteria for Section 80-IAC

    To claim benefits, startups must meet the following conditions:

    1. DPIIT Recognition

    The startup must be recognized under the Startup India initiative.

    2. Incorporation Type

    The entity must be a Private Limited Company or LLP.

    3. Incorporation Period

    It must be incorporated between 1 April 2016 and 31 March 2025.

    4. Turnover Limit

    Annual turnover must not exceed ₹100 crore.

    5. Innovation Requirement

    The business should focus on innovation, improvement, or scalable models.

    6. IMB Certification

    Approval from the Inter-Ministerial Board (IMB) is required.


    Angel Tax Exemption for Startups

    Startups with DPIIT recognition can apply for angel tax exemption.

    If approved, they are not taxed under Section 56(2)(viib) for eligible investments.


    Conditions for Angel Tax Exemption

    1. Capital Limit

    Total paid-up capital and share premium must not exceed ₹25 crore.

    Certain investments are excluded, such as funds from:

    • Venture Capital Funds
    • Venture Capital Companies
    • Listed Companies
    • Specified investors

    2. Asset Restrictions

    For 7 years, startups cannot invest in non-business assets such as:

    • Non-business land
    • Residential property
    • Loans to other entities
    • Capital investments elsewhere

    This ensures funds are used for business growth.


    Benefits for Startup Founders

    Easier Fundraising

    Investors prefer startups with tax clarity.

    Tax Savings

    100% profit deduction for 3 years boosts reinvestment.

    Reduced Compliance Risk

    Minimizes scrutiny on valuation.

    Investor Confidence

    Encourages participation from angels and VCs.


    How to Apply for Angel Tax Exemption

    1. Incorporate as a Private Limited Company or LLP
    2. Apply for DPIIT recognition
    3. Submit required documents
    4. Apply for Section 80-IAC via IMB
    5. File declaration for exemption

    Once approved, startups can raise funds more efficiently.


    Common Mistakes Founders Should Avoid

    • Delaying DPIIT registration
    • Incorrect valuation reports
    • Exceeding ₹25 crore capital limit
    • Investing in restricted assets

    Proper planning ensures full compliance.


    Conclusion

    Angel tax was introduced to prevent misuse of share valuation but created challenges for genuine startups.

    With provisions like Section 80-IAC and Startup India recognition, the system now supports innovation while maintaining compliance.

    Understanding these benefits helps founders raise funds, reduce taxes, and scale efficiently.

    With the right legal guidance, startups can maximize benefits and avoid unnecessary tax burdens.


    Frequently Asked Questions

    What is angel tax?

    A: It is a tax on excess share premium above fair market value.

    Which section governs angel tax?

    A: Section 56(2)(viib) of the Income Tax Act.

    What does Section 80-IAC provide?

    A: 100% tax deduction on profits for 3 years.

    Who grants startup recognition?

    A: DPIIT under Startup India.

    What is the turnover limit?

    A: ₹100 crore annually.

    Is angel tax applicable to all investments?

    A: No, certain investors are exempt.

  • Your Tenant Won’t Leave. Now What? | Lawizer Blog

    Your Tenant Won’t Leave. Now What? | Lawizer Blog

    Free legal consultation for new clients  ·  Book yours at lawizer.com →Lawizer

    Free Consultation

    Property Law · India

    Your Tenant Won’t Leave.
    Now What?

    A no-jargon guide for Indian landlords dealing with non-paying or non-vacating tenants — and how to resolve it legally, quickly, and without a single court visit.

    By Lawizer Legal Team|8 min read|PropertyTenant Disputes

    “My tenant stopped paying rent and I didn’t know I had this much legal power. Lawizer sent the notice, and the tenant vacated within a week.”

    — Rajesh K., Noida — Lawizer Client

    7 days

    Average time to tenant response after a legal notice

    ₹0

    Cost of your first consultation with a Lawizer attorney

    100%

    Handled online — no court visits required at the notice stage

    The Situation No Landlord Expects:

    You trusted someone with your property. You signed a rent agreement. And now — they’ve stopped paying, stopped responding, or flatly refused to leave when the agreement expired. You’re owed money. Your property is stuck. And every time you think about going to court, you imagine years of hearings, lawyer fees, and exhausting paperwork.

    Here’s what most landlords in India don’t realize: you have far more power than you think, and most tenant disputes are resolved long before they reach a courtroom.

    This guide walks you through exactly what to do — step by step — from the moment you realize there’s a problem.

    “A well-drafted legal notice resolves more tenant disputes than all the court orders combined.”

    First, Know Where You Stand Legally:

    India doesn’t have a single national tenancy law. Depending on your state, your rights as a landlord are governed by one of these frameworks:

    Applicable Laws by State Type

    • States with Rent Control Acts (Delhi, Maharashtra, West Bengal, Tamil Nadu) — stronger tenant protections, specific eviction grounds required
    • States with new Model Tenancy Act alignment — more balanced landlord-tenant framework
    • Agreements registered under Transfer of Property Act, 1882 — contracts with teeth regardless of state-level rent control

    The most important document you have is your registered rent agreement. If it’s properly registered and clearly states the tenancy period, rent amount, and vacating clause — you’re in a strong position. If your agreement is unregistered or expired, don’t panic. You still have options, but timing matters.

    Your 5-Step Action Plan:

    01

    Document Everything Right Now

    Collect all rent receipts, bank transfer records, WhatsApp messages, and the signed agreement. Screenshot every message where you requested payment or vacation. This paper trail becomes your case.

    02

    Send a Formal Legal Notice

    This is the single most effective step. A legal notice sent by a lawyer via registered post carries serious weight. It signals you’re serious, creates a legal record, and gives the tenant a deadline to respond. Many disputes end here.

    03

    Negotiate a Settlement

    If the tenant responds, there’s often room to negotiate a departure timeline or partial payment. A structured exit — even if imperfect — is faster than litigation. Have a lawyer supervise any written agreement.

    04

    File an Eviction Case if Required

    Under the Transfer of Property Act Sec. 106 and your state’s Rent Control Act, you can file for eviction citing non-payment, misuse of property, or expiry of tenancy. Summary proceedings under CPC Order 37 allow faster recovery of dues.

    05

    Recover Unpaid Rent

    Rent recovery is a civil suit. Once you have a decree, the tenant’s movable assets or bank accounts can be attached. Combined with the eviction proceeding, most lawyers structure this as a single coordinated filing.

    Landlords underestimate the psychological and legal power of a formal notice. Here’s what it actually does:

    It creates a legal record. The moment your lawyer sends a registered notice, the clock starts. Any court proceeding later will note when you first formally demanded rent or vacation — this date matters for calculating dues and establishing bad faith on the tenant’s part.

    It triggers the response deadline. Under the Transfer of Property Act Sec. 106, tenants on a monthly lease must receive 15 days’ notice for termination. A formal notice starts this clock precisely.

    It moves the dispute out of the informal zone. Verbal requests, WhatsApp pleas, and in-person conversations carry no legal weight. A lawyer’s notice changes the entire dynamic — tenants who ignored you for months often respond within days.

    Lawizer Can Help

    Get a Legal Notice Drafted & Sent Today

    Our property lawyers review your agreement, draft a watertight notice, and send it via registered post — completely online. No office visit required. Consult a Property Lawyer Free →

    The 4 Mistakes Landlords Make (That Hurt Their Case)

    1. Cutting off electricity or water

    This feels satisfying. It is illegal. Courts treat it as coercion, and it can turn the landlord into the defendant. Do not do this under any circumstances.

    2. Accepting rent after the agreement expires

    If you accept even one month’s rent after the lease ends without a renewal, you may have legally created a periodic tenancy — and reset your eviction clock. Talk to a lawyer before accepting any post-agreement payments.

    3. Entering the property without notice

    Even as the owner, entering the tenant’s premises without advance notice (typically 24 hours) can constitute trespass. Document any entry attempts in writing.

    4. Waiting too long to act

    Every month of unpaid rent is a month of recoverable dues — but courts also look at whether you acted promptly. A six-month delay weakens your position. If the tenant hasn’t paid, issue a notice within 30 days of the first missed payment.

    Common Questions Landlords Ask Us:

    My rent agreement isn’t registered. Do I still have rights?

    Yes. An unregistered agreement is still evidence of the tenancy arrangement. However, it cannot be produced in court as primary evidence in the same way a registered document can. That said, bank records and messages corroborating rent payment can supplement the claim. Consult a lawyer to assess your specific situation.

    Can I ask the police to remove a tenant?

    In most cases, no. Tenancy disputes are civil matters. Police will not forcibly remove a tenant without a court order. However, if the tenant has physically threatened you or caused damage to property, an FIR and relevant IPC provisions may apply.

    How long does an eviction case actually take?

    It varies by state and court load. In Rent Control Tribunals (common in metro cities), cases can stretch from 6 months to several years. However, most disputes that begin with a proper legal notice are settled before a final order — which is exactly why that first step is so critical.

    What if the tenant just refuses to open the door?

    Once you have a court order for eviction, a court commissioner — accompanied by the local police — can enforce it. But you need the order first. The process is: notice → no compliance → court filing → order → enforcement.

    The landlord who documents everything and acts quickly wins. The one who waits six months hoping things resolve themselves — rarely does.

    The Bottom Line:

    A difficult tenant is stressful. But it’s a legal problem with a legal solution — and you don’t have to figure it out alone.

    Start with a free consultation. Have a lawyer look at your agreement and your situation. In most cases, a single strong legal notice is all it takes.

    Lawizer’s property lawyers have handled hundreds of landlord-tenant disputes across India — completely online, at transparent fees, with no surprise charges.

    If your tenant has stopped paying or won’t leave, the best time to act was last month. The second best time is today.

    In This Article

    1. 01 The situation no landlord expects
    2. 02 Know where you stand legally
    3. 03 Your 5-step action plan
    4. 04 The power of a legal notice
    5. 05 4 mistakes to avoid
    6. 06 Common questions answered
    7. 07 The bottom line

    Facing a tenant dispute right now?

    Talk to a Lawizer property lawyer free. We’ll tell you exactly where you stand in 30 minutes.Book Free Consultation

    Related Property Services

    More from the Lawizer Blog

    Startup Law Registering Your Company in India: The 7 Things No One Tells You Banking Cheque Bounce Under Section 138: Your Complete Legal Guide Tax ITR Filing Deadline 2025: Penalties, Extensions, and What to Do If You Missed It © 2026 Lawizer. All rights reserved.  ·  Privacy Policy  ·  Terms of Service  ·  +91 90628 15535

  • ESOP Management 101: How to Retain Top Talent for Your Startup

    ESOP Management 101: How to Retain Top Talent for Your Startup

    Introduction

    Building a startup is very challenging and Building a great team is even more challenging.

    In the early days, one might not have the money to offer high salaries like big companies. Yet, you still need smart, dedicated people who believe in your vision. This is where ESOPs come in.

    If you are a startup founder in India, understanding ESOP management is not optional anymore. It is one of the smartest ways to retain top talent and build long-term loyalty.


    What Is an ESOP?

    ESOP stands for Employee Stock Ownership Plan (or Employee Stock Option Plan).

    In simple words, an ESOP gives employees the right to buy shares of the company at a fixed price in the future. If the company grows and its valuation increases, those shares become valuable.

    Instead of only paying salary, you give employees a chance to become part-owners. It changes their mindset from: “I work here.” to “I am building this.”


    Why ESOP Management Matters for Startups?

    Startups are risky. Employees know that. When they join a startup, they are taking a leap of faith.

    Good ESOP management helps in:

    • Attracting strong talent
    • Retaining key employees
    • Aligning employee goals with company growth
    • Reducing attrition
    • Building a performance-driven culture

    Many startups registered under Startup India use ESOPs as a strategic tool to compete with larger corporations.

    In cities like Bengaluru, Mumbai, and Hyderabad, ESOPs have become almost standard practice in the startup ecosystem.


    How ESOPs Help Retain Top Talent?

    1. They Create Long-Term Commitment

    ESOPs usually come with a vesting schedule. This means employees earn their shares gradually over time. For example:

    • 4-year vesting period
    • 1-year cliff (no shares if they leave before 1 year)

    This structure encourages employees to stay longer. If they leave early, they lose unvested shares. This naturally improves retention.

    2. They Align Interests

    When employees own shares, they think differently. They care about:

    • Company valuation
    • Profitability
    • Customer satisfaction
    • Cost control

    Their success becomes directly linked to the company’s success. That alignment is powerful.

    3. They Build an Ownership Culture

    Top talent doesn’t just want a salary. They want impact. They want recognition. They want to feel important.

    ESOPs send a strong message: “You are not just an employee. You are a partner in growth.”

    That emotional connection builds loyalty.


    Common ESOP Mistakes Startups Make

    Even though ESOPs are powerful, poor ESOP management can create confusion and dissatisfaction. Here are common mistakes:

    1. No Clear Communication

    Many founders say, “You will get ESOPs,” but never explain:

    • How many shares?
    • What percentage?
    • What is the strike price?
    • When can they sell?

    Employees may not understand the real value. Transparency is key.

    2. Overpromising Valuation

    Telling employees, “These shares will be worth crores one day,” creates unrealistic expectations.

    Startup growth is uncertain. Be honest about risks.

    3. No Legal Structure

    In India, ESOPs must follow Companies Act guidelines if the company is a Private Limited Company.

    Proper board approval, shareholder approval, and documentation are required.

    Without proper structure, ESOPs can create legal complications later.

    4. Poor Exit Planning

    Employees often ask: “When can I sell my shares?”

    If there is no liquidity event (IPO or acquisition), shares may not convert into cash immediately. Clear policies around buybacks or exit events are important for good ESOP management.


    How to Design an Effective ESOP Plan?

    Now let’s talk practical steps.

    Step 1: Decide the ESOP Pool Size

    Most startups create an ESOP pool of 5%–15% of total equity.

    This pool is reserved specifically for employees.

    Step 2: Create a Vesting Schedule

    A standard vesting structure is:

    • 4 years total
    • 1-year cliff
    • Monthly or quarterly vesting after that. This ensures long-term commitment.

    Step 3: Define Eligibility Clearly

    Not every employee may get ESOPs. You can allocate ESOPs to:

    • Senior leadership
    • Key technical team members
    • High-performing employees, Be clear and consistent in allocation.

    Step 4: Communicate the Value Properly

    Do not just say “You have 1,000 options.”

    Explain:

    • Current company valuation
    • Strike price
    • Potential upside
    • Risks involved

    When employees understand the real picture, they trust the system more.

    Step 5: Keep Compliance in Check

    Follow proper legal procedures. Board approvals, documentation, grant letters, and maintaining an ESOP register are important. Clean documentation builds investor confidence during funding rounds.


    ESOPs and Startup Growth

    When managed properly, ESOPs can:

    • Reduce hiring costs
    • Improve retention
    • Increase productivity
    • Strengthen culture
    • Attract investors

    Investors also like companies where employees have skin in the game. It shows commitment and stability.

    In competitive startup ecosystems, ESOP management is no longer optional. It is strategic.


    Conclusion

    Retaining top talent is one of the biggest challenges for startups. You may not always compete on salary. But you can compete on ownership, vision, and long-term wealth creation.

    ESOP management is not just about giving shares. It is about building belief. When employees feel like co-creators instead of workers, they stay longer, work harder, and think bigger.

    And in the startup world, that mindset makes all the difference.


  • DPIIT Recognition: How Lawizer Helps Startups Unlock Government Benefits

    DPIIT Recognition: How Lawizer Helps Startups Unlock Government Benefits

    Introduction

    India has emerged as one of the fastest-growing startup ecosystems in the world. Thousands of entrepreneurs are building innovative businesses in sectors such as technology, healthcare, fintech, and education.

    To support these startups, the Government of India launched the Startup India initiative. Under this initiative, startups can obtain recognition from the Department for Promotion of Industry and Internal Trade (DPIIT).

    DPIIT recognition allows startups to access multiple government benefits including tax exemptions, funding opportunities, intellectual property support, and simplified compliance requirements.

    However, many founders struggle with the process and documentation involved. This is where platforms like Lawizer help startups unlock these benefits easily.


    What is DPIIT Recognition?

    DPIIT Recognition is an official certification granted to startup companies by the Department for Promotion of Industry and Internal Trade under the Startup India initiative.

    This recognition formally identifies a business as an eligible startup engaged in innovation or scalable business development.

    Once a startup receives DPIIT recognition, it becomes eligible for several government incentives and support schemes designed to help early-stage businesses grow.


    Eligibility Criteria for DPIIT Recognition

    To obtain DPIIT recognition, a startup must satisfy certain eligibility conditions.

    1. Type of Entity

    The business must be registered as one of the following:

    • Private Limited Company
    • Limited Liability Partnership (LLP)
    • Registered Partnership Firm

    2. Age of the Company

    The company should be less than 10 years old from the date of incorporation.

    3. Annual Turnover

    The startup’s annual turnover must not exceed ₹100 crore in any financial year since its incorporation.

    4. Innovation and Scalability

    The startup must focus on innovation or improvement in products or services. The business should aim to:

    • Develop new technology or processes
    • Improve existing products or services
    • Build a scalable business model
    • Generate employment or wealth creation

    Benefits of DPIIT Recognition for Startups

    1. Tax Holiday for Startups

    Early-stage startups often operate with limited financial resources. DPIIT-recognized startups can apply for a tax holiday under Section 80-IAC of the Income Tax Act.

    This provides 100% income tax exemption on profits for three consecutive years within the first ten years of incorporation.

    This benefit allows startups to reinvest their profits into:

    • Product development
    • Research and innovation
    • Business expansion

    2. Angel Tax Exemption

    Angel tax earlier created challenges for startups raising funds from investors.

    Angel tax applied when startups issued shares at a price higher than their fair market value. With DPIIT recognition, eligible startups can receive investments from angel investors without facing this tax burden.

    This makes fundraising easier and encourages more investors to support innovative startups.

    3. Access to Government Funding Schemes

    DPIIT recognition also provides startups with access to government funding programs such as:

    • Fund of Funds for Startups (FFS)
    • Startup India Seed Fund Scheme

    These schemes help startups receive financial assistance for:

    • Product development
    • Market entry
    • Scaling business operations

    Being DPIIT-recognized also increases a startup’s credibility among investors.

    4. Simplified Regulatory Compliance

    Startups often face complex regulatory requirements that consume time and resources.

    DPIIT-recognized startups are allowed to self-certify compliance with several labour and environmental laws.

    This reduces:

    • Frequent inspections
    • Regulatory paperwork
    • Administrative burden

    5. Intellectual Property (IP) Support

    Innovation is a key part of startup growth. DPIIT recognition provides strong support for intellectual property protection.

    Startups receive:

    • Fast-track patent examination
    • Up to 80% rebate on patent filing fees
    • Around 50% rebate on trademark registration fees

    How Does Lawizer Make the Process Seamless?

    Many startups are unaware of the documentation and procedures required for DPIIT recognition.

    Lawizer is a legal and business consulting platform that helps startups navigate regulatory compliance and government registrations smoothly.

    Lawizer assists startups in multiple areas including:

    • Company incorporation
    • Legal documentation
    • Intellectual property registration
    • DPIIT recognition
    • Compliance management

    Why Choose Lawizer?

    • Expert Guidance: Step-by-step assistance for accurate application filing.
    • Documentation Support: Reduces chances of rejection.
    • Faster Processing: Ensures smooth submission on Startup India portal.
    • End-to-End Support: Covers legal, compliance, and funding guidance.

    How Lawizer Simplifies the DPIIT Registration Process

    Step 1: Assistance with Documentation

    Lawizer helps founders prepare all the required documents needed for DPIIT recognition. This includes drafting a clear description of the startup’s innovative activities and business model.

    Step 2: Startup India Portal Registration

    The team assists startups in submitting their application through the Startup India portal. With expert guidance, the process becomes faster and smoother.

    Step 3: Guidance on Government Benefits

    Lawizer helps startups understand and apply for tax exemptions, government grants, intellectual property benefits, and funding schemes.

    Step 4: Ongoing Legal and Compliance Support

    Lawizer supports startups with shareholder agreements, legal documentation, regulatory compliance, and intellectual property protection.


    Conclusion

    DPIIT recognition plays a vital role in strengthening India’s startup ecosystem. It provides startups with tax incentives, funding opportunities, simplified compliance, and intellectual property support.

    However, navigating the recognition process and accessing these benefits can be challenging for new entrepreneurs.

    Companies like Lawizer simplify this journey by helping startups obtain DPIIT recognition and unlock the full range of government benefits available under the Startup India initiative.

    With the right guidance and government support, startups can innovate faster, scale their businesses, and contribute to India’s economic growth.


    Frequently Asked Questions

    What is DPIIT recognition?

    A: DPIIT recognition is a certification granted by the Department for Promotion of Industry and Internal Trade that officially identifies a business as an eligible startup under the Startup India initiative.

    Who can apply for DPIIT recognition?

    A: Private Limited Companies, LLPs, and Registered Partnership Firms that are less than 10 years old with turnover below ₹100 crore can apply.

    What are the benefits of DPIIT recognition?

    A: DPIIT-recognized startups receive tax exemptions, funding opportunities, compliance relaxations, and intellectual property benefits.

    Is DPIIT recognition mandatory for startups?

    A: No, DPIIT recognition is optional but highly beneficial for accessing government schemes and incentives.

    How long does it take to get DPIIT recognition?

    A: If all documents are correct, DPIIT recognition can usually be granted within a few days to a few weeks.

    Can DPIIT-recognized startups raise funds easily?

    A: Yes, DPIIT recognition provides exemption from angel tax, making it easier for startups to attract investors.

    Do DPIIT-recognized startups get tax benefits?

    A: Yes, eligible startups can claim a 3-year tax holiday under Section 80-IAC of the Income Tax Act.

    How does Lawizer help with DPIIT recognition?

    A: Lawizer helps startups with documentation, application filing, and guidance on accessing government benefits.


  • Common Mistakes to Avoid While Filing ITR for Salaried Employees in 2026

    Common Mistakes to Avoid While Filing ITR for Salaried Employees in 2026

    Introduction

    Filing an Income Tax Return (ITR) as a salaried employee often feels like navigating a bureaucratic maze. In 2026, the Income Tax Department has shifted toward advanced AI-driven data processing.

    This means even a minor clerical error can trigger an automatic tax notice.

    While technology has increased scrutiny, legal-tech platforms like Lawizer have made the process seamless. By connecting you with verified experts, Lawizer ensures your filing is stress-free and accurate.


    10 Common ITR Filing Mistakes You Must Avoid

    To ensure a smooth filing season, keep an eye out for these frequent pitfalls:

    1. Selecting the Wrong ITR Form

    Choosing the incorrect form results in a “Defective Return” notice.

    • ITR-1 (Sahaj): For individuals with income up to ₹50 lakhs and one house property.
    • ITR-2: For those with capital gains, multiple house properties, or income exceeding ₹50 lakhs.
    • ITR-3: For individuals with business or professional income.

    2. Quoting the Wrong Assessment Year (AY)

    For the current Financial Year (FY 2025-26), the corresponding Assessment Year is 2026-27. Confusing these dates can lead to double taxation or immediate rejection.

    3. Errors in Personal and Bank Information

    Your bank account must be pre-validated on the portal. Ensure your name and address match your PAN exactly. An incorrect IFSC code can stall your refund for months.

    4. Failure to Disclose “Hidden” Income Sources

    Don’t forget to report:

    • Savings Interest: Deductible up to ₹10,000 under Sec 80TTA.
    • Dividends: Often overlooked but taxable.
    • Minor’s Income: Deductible up to ₹1,250 per child (up to 2 children).

    5. Manual Entry and Formatting Errors

    Data must match your employer’s TDS filing perfectly. Inconsistent formatting often leads to automated system rejections.

    6. Ignoring AIS and TIS Reconciliations

    The Annual Information Statement (AIS) tracks stock trades, FD interest, and large credit card spends. If your ITR doesn’t match your Taxpayer Information Summary (TIS), an inquiry is almost certain.

    7. Mismatching TDS with Form 26AS

    Always verify that the tax deducted by your employer or bank is reflected in Form 26AS. If it isn’t, you won’t receive credit for that tax, resulting in a higher payout.

    8. Forgetting Section 80 Deductions

    Look beyond Section 80C. You can also claim:


  • Why Every Indian Startup Needs a Strong Founder’s Agreement

    Why Every Indian Startup Needs a Strong Founder’s Agreement

    Introduction

    Starting a business is exciting and thrilling. It often begins with a powerful idea, a late-night conversation, or a shared dream between friends.

    In the early days, everything feels possible. Everyone is motivated. Everyone trusts each other.

    But while passion and trust are important, they are not enough to build a successful company. This is exactly where a founder’s agreement for startups becomes essential.

    Many Indian startups fail not because the idea was weak or the founders were not hardworking. They fail because the founders were not aligned.

    Misunderstandings, money disputes, unclear responsibilities, or ego clashes slowly damage the business. A strong founder’s agreement for startups can prevent these problems before they even begin.


    What Is a Founder’s Agreement for Startups?

    A founder’s agreement for startups is a legal document signed by co-founders at the early stage of the company. It clearly defines the relationship between the founders and sets expectations from day one.

    It usually answers key questions like:

    1. Who owns how much of the company?
    2. What are each founder’s roles and responsibilities?
    3. How will important decisions be made?
    4. What happens if a founder leaves?
    5. How will disputes be resolved?

    In simple words, it protects both the business and the people involved.

    In India, startups are commonly registered as a Private Limited Company or a Limited Liability Partnership. No matter the structure, having a founder’s agreement for startups is equally important.


    Why Is a Founder’s Agreement for Startups So Important in India?

    India’s startup ecosystem is growing rapidly. Cities like Bengaluru, Mumbai, and Hyderabad are becoming major startup hubs.

    With growth comes competition, investor pressure, and legal complexities. Here’s why every Indian startup needs a strong founder’s agreement for startups:

    1. It Prevents Future Conflicts

    In the beginning, no one thinks about worst-case scenarios. Everyone assumes things will work out smoothly.

    But what if:

    • One founder contributes more time than the others?
    • One founder wants to sell their shares?
    • One founder resigns after six months?

    Without a written founder’s agreement for startups, these situations can turn ugly. Disagreements become personal. The company suffers.

    A clear agreement sets expectations from day one. It reduces confusion and protects relationships.


    2. It Protects Equity and Ownership

    Equity is emotional. It represents ownership, control, and future wealth. Many founders split shares equally without discussing long-term contributions.

    But is equal always fair?

    One founder may bring the idea. Another may bring capital. Another may manage daily operations. A strong founder’s agreement for startups clearly defines:

    • The equity split
    • The vesting schedule (earning shares over time)
    • What happens to shares if someone exits

    Vesting is extremely important. It ensures that no founder walks away with a large percentage of ownership without contributing long-term value.


    3. Investors Expect It

    If you plan to raise funding, investors will almost always ask, “Do you have a founder’s agreement?” Investors look for stability.

    Many startups registered under Startup India later realise that investors carefully examine founder agreements before investing. A well-drafted founder’s agreement for startups builds trust, credibility, and confidence.


    4. It Clearly Defines Roles and Responsibilities

    Unclear roles are one of the biggest reasons startups fail.

    For example:

    • Who handles finance?
    • Who manages marketing?
    • Who makes the final business decisions?

    If two founders both believe they are the “CEO,” conflict is inevitable.

    A founder’s agreement for startups clearly defines:

    • Titles
    • Duties
    • Authority levels
    • Time commitment

    This clarity avoids overlapping responsibilities and unnecessary power struggles.


    5. It Covers Exit and Separation

    Not all partnerships last forever. Life changes. Priorities shift.

    A founder may want to:

    • Move abroad
    • Study further
    • Start another venture
    • Take a break

    A strong founder’s agreement for startups answers critical questions like:

    • Can a founder sell shares to outsiders?
    • Do other founders get the first right to buy those shares?
    • What happens in case of death or incapacity?

    Planning for exit does not mean you expect failure. It simply means you are being practical and prepared.


    6. It Protects Intellectual Property (IP)

    In startups, ideas are everything. Your app code, brand name, logo, designs, and product formula are all valuable intellectual property.

    Without a founder’s agreement for startups, confusion may arise about who owns what.

    A proper agreement clearly states that all intellectual property belongs to the company, not to individual founders.


    7. It Helps During Legal Disputes

    If disagreements escalate, the founder’s agreement becomes your strongest protection.

    It usually includes:

    • Dispute resolution methods
    • Arbitration clauses
    • Governing law (Indian law)

    This makes resolving conflicts faster, smoother, and less expensive.


    Why Many Indian Founders Ignore It

    Despite its importance, many founders delay drafting a founder’s agreement for startups because:

    • “We are friends.”
    • “We trust each other.”
    • “We will figure it out later.”
    • “Legal documents are expensive.”

    Money, pressure, investor expectations, and market competition can change dynamics. A written agreement does not show distrust. It shows professionalism and maturity.


    What Should a Strong Founder’s Agreement Include?

    For full protection, a founder’s agreement for startups should cover:

    1. Founder details
    2. Equity split
    3. Vesting schedule
    4. Roles and responsibilities
    5. Decision-making process
    6. Salary and compensation
    7. Confidentiality clauses
    8. Non-compete clauses
    9. Exit terms
    10. Dispute resolution mechanism

    It should always be drafted carefully, ideally with professional legal guidance.


    Conclusion

    Starting a business is like starting a journey. And no journey is smooth without a clear map.

    A founder’s agreement for startups is not just another legal formality. It is a protection shield. It protects friendships, ownership, attracts investors, and secures the future of the company.


    Frequently Asked Questions

    What is a Founder’s Agreement?

    A Founder’s Agreement is a legal document that defines the roles, responsibilities, and equity ownership of startup founders.

    Why is a Founder’s Agreement important?

    It prevents disputes among founders by clearly outlining responsibilities, ownership, and decision-making authority.

    When should startups create a Founder’s Agreement?

    Startups should ideally create a Founder’s Agreement at the time of company incorporation.

    What clauses are included in a Founder’s Agreement?

    Common clauses include equity distribution, vesting schedules, intellectual property ownership, founder roles, and exit terms.

    Does a Founder’s Agreement help in raising investment?

    Yes, investors prefer startups that have clear legal agreements between founders.

    What is founder equity vesting?

    Founder vesting means founders earn their equity gradually over time rather than receiving it immediately.

    Who owns intellectual property in a startup?

    A Founder’s Agreement ensures that intellectual property created by founders belongs to the company.

    Can a Founder’s Agreement resolve founder disputes?

    Yes, it provides dispute resolution mechanisms such as mediation or arbitration.

  • Benefits of Registering as a Private Limited Company in India

    Introduction

    Choosing the right business structure is one of the most important decisions for any entrepreneur.

    In India, registering as a Private Limited Company under the Ministry of Corporate Affairs offers several legal, financial, and strategic advantages.

    Whether you are launching a startup or scaling an existing venture, understanding the benefits of registering as a private company can help you make a confident and informed decision.


    What is a Private Limited Company?

    A Private Limited Company is a legally recognized business entity with:

    • Limited liability for shareholders
    • Separate legal identity
    • Perpetual succession
    • Structured compliance requirements

    It is one of the most preferred business structures in India due to its credibility and growth potential.


    Key Benefits of Registering as a Private Limited Company

    1. Limited Liability Protection

    One of the biggest advantages of a private limited company is limited liability.

    This means:

    • Shareholders are only liable up to the amount they have invested.
    • Personal assets remain protected from business debts or legal claims.

    If the company faces financial losses or lawsuits, the personal property of owners is safeguarded. This reduces financial risk and encourages entrepreneurs to take calculated business decisions.


    2. Separate Legal Entity

    A Private Limited Company is legally distinct from its owners.

    This allows the company to:

    • Own property in its own name
    • Enter into contracts
    • Sue or be sued independently

    The company’s identity remains separate from its shareholders, ensuring operational stability.


    3. Perpetual Succession

    Unlike sole proprietorships or partnerships, a private limited company continues to exist even if:

    • A shareholder exits
    • A director resigns
    • Ownership changes

    This concept of perpetual succession ensures long-term business continuity and enhances investor confidence.


    4. Better Access to Funding

    Funding becomes significantly easier when you operate as a registered private limited company.

    You can:

    • Issue shares to raise capital
    • Attract venture capitalists and angel investors
    • Secure bank loans more easily

    Financial institutions prefer registered companies because of structured compliance and transparency.


    5. Enhanced Credibility and Brand Image

    Registration with the Ministry of Corporate Affairs increases business credibility.

    Clients, vendors, and partners often perceive private limited companies as:

    • More professional
    • More reliable
    • Better regulated

    This credibility can open doors to larger contracts and long-term partnerships.


    6. Easy Transfer of Ownership

    Ownership in a private limited company can be transferred through the transfer of shares.

    This makes it easier to:

    • Bring in new investors
    • Restructure ownership
    • Exit existing shareholders

    Business operations continue smoothly without disruption.


    7. Tax Benefits and Structured Compliance

    Private limited companies enjoy structured corporate tax rates and can claim deductions on legitimate business expenses.

    Additionally:

    • Proper financial reporting improves transparency
    • Statutory compliance builds investor trust
    • Organized records support long-term expansion

    8. Scalability and Growth Potential

    If your goal is business expansion, a private limited structure offers strong scalability.

    It allows you to:

    • Expand across regions
    • Attract institutional investment
    • Convert into a public company in the future

    This makes it ideal for startups planning long-term growth.


    9. Better Talent Acquisition

    Private limited companies can attract skilled professionals more easily.

    They can offer:

    • Job stability
    • Structured work roles
    • Employee Stock Option Plans (ESOPs)

    This helps in building a strong and motivated team.


    Conclusion

    Registering as a Private Limited Company in India provides legal protection, improved credibility, funding opportunities, and long-term growth advantages.

    Although compliance requirements and documentation are involved, the strategic benefits outweigh the initial effort. For entrepreneurs aiming to build a scalable and investor-friendly business, registering as a private company is often the smartest decision.


    Frequently Asked Questions

    What is a Private Limited Company?

    It is a legally registered business entity recognized by the Ministry of Corporate Affairs with limited liability and separate legal status.

    What is the main advantage of registering as a Private Limited Company?

    The primary advantage is limited liability, which protects shareholders’ personal assets.

    Can a Private Limited Company raise funds easily?

    Yes, it can raise capital by issuing shares and attracting investors more easily than unregistered businesses.

  • Legal Consultation Online: How Lawizer Connects You to Experts 24/7

    Introduction

    Online legal consultation has witnessed tremendous growth, especially in India, where digital adoption continues to rise rapidly.

    The legal industry has undergone a major transformation in recent years. What was once considered traditional and conservative has now evolved into a more accessible, approachable, and affordable model.

    Today, individuals and businesses prefer quick, remote, and secure legal advice over traditional in-office visits. This shift has reshaped how legal services are delivered.


    What is Online Legal Consultation?

    Online legal consultation refers to seeking legal advice, document review, or case strategy guidance through digital platforms.

    This may include:

    • Video consultations
    • Phone consultations
    • Chat-based legal advice
    • Email-based legal opinions
    • Digital document review

    Instead of physically visiting a lawyer’s office, clients can now access professional legal support remotely through legal-tech platforms and law firm websites.


    Why Online Legal Consultation Has Escalated Over Time

    1. Increased Legal Awareness

    More individuals are aware of their legal rights and prefer taking preliminary advice before escalating disputes. This proactive approach has increased demand for quick consultations.


    2. Startup & MSME Growth

    The rise of startups and MSMEs has significantly increased the need for affordable legal advice related to:

    • Contracts
    • Compliance
    • Business incorporation
    • Regulatory filings

    Entrepreneurs now seek faster legal clarity without long appointment delays.


    3. Digital Trust & Security

    Secure payment gateways, encrypted communication systems, and verified lawyer networks have strengthened public trust in online legal services.


    4. Government Digital Integration

    Digital filings under the Ministry of Corporate Affairs and the expansion of e-court initiatives have supported the growth of online legal consultation.

    Legal processes are becoming increasingly technology-driven, making remote consultation more practical than ever.


    The Future of Online Legal Consultation

    Online legal services are expected to integrate advanced technologies such as:

    • AI-powered legal assistance
    • Automated document drafting
    • Predictive case analysis
    • Blockchain-based documentation security

    The legal profession is steadily transitioning into a tech-enabled service ecosystem.


    How Lawizer Connects You to Legal Experts 24/7

    Legal issues don’t arise only during office hours. Whether it’s a compliance concern, police-related matter, contract dispute, or women’s safety issue, timely legal advice is critical.

    Lawizer bridges this gap by offering 24/7 digital connectivity to verified legal experts.

    Here’s how the system works:


    1. Instant Digital Access

    Lawizer allows users to raise legal queries anytime—day or night.

    Users can:

    • Submit their issue online
    • Select consultation type
    • Request immediate assistance

    This removes geographical and time barriers completely.


    2. Verified Expert Network

    Lawizer connects clients with verified and experienced lawyers across practice areas such as:

    • Criminal law
    • Family law
    • Corporate compliance
    • Property disputes
    • Women-centric legal matters

    Every expert is vetted before onboarding to ensure professional reliability.


    3. Smart Case Matching System

    Once a user submits a query, the platform categorizes it based on legal domain and urgency.

    The case is routed to the most suitable expert, ensuring:

    • Faster response time
    • Domain-specific advice
    • Accurate legal direction

    This eliminates random allocation and improves consultation efficiency.


    4. Multiple Consultation Modes

    To maintain 24/7 availability, Lawizer offers flexible communication options:

    • Call consultations
    • Video meetings
    • Chat-based advisory
    • Document review support

    Users can choose the format that suits their urgency and comfort.


    5. Immediate Response for Urgent Matters

    For emergencies such as police involvement, threats, or sensitive disputes, Lawizer prioritizes rapid lawyer connection.

    This ensures users receive immediate legal clarity when time is critical.


    6. Transparent and Structured Process

    From booking to payment and follow-ups, the system is fully digital and streamlined.

    This reduces delays and ensures smooth communication between clients and legal experts.


    7. Continuous Support Model

    Unlike traditional systems restricted to office hours, Lawizer’s digital-first structure ensures legal assistance remains accessible round the clock.


    Conclusion

    Online legal consultation has evolved from a convenience-based alternative into a mainstream legal service model.

    Lawizer connects users to legal experts 24/7 through digital accessibility, verified professionals, smart case allocation, and flexible consultation modes.

    By eliminating time and location barriers, it ensures that professional legal support is always within reach—whenever it is needed most.


    Frequently Asked Questions

    What is online legal consultation?

    Answer: It is the process of seeking legal advice digitally through calls, video meetings, chat, or document review.

    Is online legal consultation reliable?

    Answer: Yes, when conducted through verified platforms like Lawizer with vetted legal professionals.

    How quickly can I connect with a lawyer on Lawizer?

    Answer: Users can raise queries instantly and get connected based on urgency and case type.

    Is online legal advice confidential?

    Answer: Yes, consultations are conducted through secure and encrypted communication systems.

    Can businesses use Lawizer for compliance support?

    Answer: Yes, startups and MSMEs can seek assistance for contracts, incorporation, and regulatory compliance.


  • The Essential Checklist for Business Incorporation in India (2026)

    Introduction

    In 2026, forming a company in India has become significantly easier due to digital platforms and integrated regulatory systems.

    However, business incorporation still requires proper planning, documentation, and strict compliance with legal formalities.

    This essential checklist will help you with the entire process to ensure your company is incorporated smoothly, legally, and successfully.


    Why Proper Incorporation Planning Matters

    Choosing the right structure and completing regulatory steps correctly helps:

    • Protect personal liability
    • Ensure tax compliance
    • Build investor confidence
    • Avoid future legal disputes
    • Establish long-term operational stability

    Let’s break down the step-by-step incorporation process.


    1. Decide Your Business Structure

    Before starting the incorporation process, choose the most suitable legal structure based on your goals:

    • Private Limited Company – Ideal for startups seeking funding
    • One Person Company (OPC) – Suitable for solo entrepreneurs
    • Limited Liability Partnership (LLP) – Limited liability with simpler compliance
    • Partnership Firm – Suitable for small professional ventures
    • Sole Proprietorship – Simple structure but no limited liability

    Your decision impacts taxation, funding opportunities, compliance burden, and liability protection.


    2. Obtain Digital Signature Certificate (DSC)

    A Digital Signature Certificate (DSC) is mandatory for filing electronic documents.

    • Directors and authorized signatories must obtain DSC from licensed certifying agencies.
    • It serves as your official digital identity for government filings.

    3. Apply for Director Identification Number (DIN)

    Every proposed director must obtain a Director Identification Number (DIN) from the Ministry of Corporate Affairs.

    • DIN is a unique 8-digit identification number.
    • It is mandatory before submitting incorporation documents.

    4. Name Reservation (RUN / SPICe+)

    Choosing a compliant and unique business name is a crucial step.

    Ensure that:

    • The name is not identical to an existing company or trademark.
    • It complies with MCA naming guidelines.
    • It reflects your business activity and brand identity.

    You can reserve the name through:

    • RUN (Reserve Unique Name)
    • SPICe+ incorporation form

    5. Draft Key Company Documents

    You must prepare foundational legal documents:

    Memorandum of Association (MOA)

    Defines the company’s objectives and permitted activities.

    Articles of Association (AOA)

    Specifies internal governance rules and shareholder rights.

    These documents form the legal backbone of your company.


    6. Prepare Registered Office Proof

    Every company must have a registered office in India.

    Required documents include:

    • Utility bill (issued within last 2 months)
    • Rent agreement (if applicable)
    • No Objection Certificate (NOC) from property owner

    This address becomes the official communication point for government correspondence.


    7. File Incorporation Forms (SPICe+)

    The primary step is filing the SPICe+ (Simplified Proforma for Incorporating Company Electronically) form via the MCA portal.

    SPICe+ covers:

    • Company registration
    • PAN and TAN allotment
    • GST registration (if applicable)
    • EPFO/ESIC registration (if applicable)
    • Bank account integration

    This integrated filing system reduces duplication and speeds up approvals.


    8. PAN, TAN & Bank Account Setup

    After approval:

    • PAN (Permanent Account Number) is auto-generated
    • TAN (Tax Deduction Account Number) is issued
    • Open a current business bank account
    • Deposit initial share capital

    These steps activate your company financially.


    9. GST Registration (If Applicable)

    GST registration is mandatory if:

    • Your turnover exceeds prescribed thresholds
    • You engage in inter-state trade
    • Your business falls under notified categories

    Early GST registration ensures smooth compliance and invoicing.


    10. Post-Incorporation Compliance

    After incorporation, companies must:

    • Appoint a statutory auditor (within 30 days)
    • Conduct first board meeting (within 30 days)
    • Issue share certificates
    • File commencement of business declaration (if required)
    • Maintain statutory registers

    Annual compliance includes financial statements, annual returns, and tax filings.


    Document Checklist for Business Incorporation

    ✔ Director’s identity proof (PAN, Aadhaar, Passport)
    ✔ Director’s address proof
    ✔ Passport-sized photographs
    ✔ Registered office proof
    ✔ MOA & AOA drafts
    ✔ Consent to act as director
    ✔ Digital Signature Certificate details


    Key 2026 Considerations

    Business incorporation in 2026 involves:

    • Increased digital verification
    • Stronger KYC norms
    • Integrated MCA-GST-tax systems
    • Higher penalties for non-compliance

    Staying updated with regulatory changes is essential.


    Conclusion

    Incorporating a business in India in 2026 is faster and more streamlined than ever before. However, precision in documentation and compliance remains critical.

    By following this essential checklist, you ensure your business is legally structured, financially prepared, and ready for sustainable growth.

    Whether you are launching a startup or expanding operations, proper incorporation sets the foundation for long-term success.


    Frequently Asked Questions (FAQs)

    How long does business incorporation take in India?

    Answer: Typically, it takes 7–15 working days, depending on documentation and approvals.

    Is DIN mandatory for all directors?

    Answer: Yes, every proposed director must obtain a valid DIN.

    Is GST registration compulsory for every company?

    Answer: No, it depends on turnover thresholds and business nature.

    Can I incorporate a company completely online?

    Answer: Yes, the entire incorporation process is digital through the MCA portal.

    What is the most preferred business structure in India?

    Answer: Private Limited Company is commonly preferred for startups and growth-focused businesses.


  • The Role of Lawizer in Scaling Your Fintech Startup Compliantly in India

    The Role of Lawizer in Scaling Your Fintech Startup Compliantly in India

    Introduction

    In the rapidly evolving digital economy of India, fintech startups are no longer just “apps”—they are sophisticated financial institutions operating under the watchful eye of multiple regulators.

    As of 2026, the mantra for success has shifted from “growth at any cost” to “growth through compliance”.

    For a founder, navigating the labyrinth of Indian financial laws while trying to scale is a Herculean task. This is where Lawizer transforms from a service provider into a strategic partner.

    Lawizer is a high-velocity legal-tech platform designed to provide the infrastructure that fintechs need to remain compliant without sacrificing speed.


    The Regulatory Framework of Indian Fintech

    To scale a fintech startup in India, you must understand the three key regulatory pillars: RBI, SEBI, and the DPDP Act.

    RBI’s Digital Lending Framework

    The Reserve Bank of India (RBI) has introduced strict norms under its Digital Lending Directions. Startups acting as Lending Service Providers (LSPs) must ensure:

    • Fund Flow Transparency: Direct transfer from bank/NBFC to borrower; no pool accounts allowed.
    • Key Fact Statement (KFS): Clear disclosure of APR, total loan cost, and recovery terms.
    • Grievance Redressal: Appointment of a nodal officer for complaints.

    Payment Aggregator (PA) Guidelines

    Fintechs handling merchant payments must comply with RBI’s Payment Aggregator framework:

    • Net Worth Requirement: Must reach ₹25 Crore within the prescribed time.
    • Escrow Mechanism: Merchant funds must be routed through regulated escrow accounts.

    Digital Personal Data Protection (DPDP) Act

    Data protection is now a core legal requirement under the DPDP Act:

    • Consent Architecture: Users must be able to give, manage, and withdraw consent.
    • Data Minimization: Only necessary data can be collected.
    • Penalties: Non-compliance can lead to heavy financial penalties.

    How Lawizer Supports Fintech Startup Formation

    Forming a fintech startup requires a legally robust structure that supports funding and compliance. Lawizer simplifies this process:

    Choosing the Right Legal Structure

    • Private Limited Company: Ideal for startups seeking funding and credibility.
    • One Person Company (OPC): Suitable for solo founders.
    • Limited Liability Partnership (LLP): Offers flexibility for partner-led businesses.

    Tax and Business Registrations

    Intellectual Property Protection

    • Trademark Registration: Protects brand identity.
    • Copyright Registration: Secures software and digital assets.

    Scaling and Compliance Support

    As fintech startups grow, compliance becomes an ongoing requirement. Lawizer ensures continuous support:

    • Annual Compliance: Filing and regulatory requirements for companies and LLPs.
    • Corporate Governance: Managing directors, addresses, and legal changes.
    • SOS Feature: Immediate assistance for legal notices and urgent issues.
    • Consultation Support: Access to verified professionals for legal advice.

    Conclusion

    Scaling a fintech startup in India requires navigating complex and evolving regulations.

    From RBI compliance to data protection under the DPDP Act, every aspect of the business must align with legal requirements.

    Lawizer simplifies this journey by automating compliance, managing documentation, and connecting founders with legal experts.

    In a highly regulated environment, having a reliable legal-tech partner ensures sustainable growth and minimizes risk.


    Frequently Asked Questions

    Is Lawizer a law firm?

    Answer: No, Lawizer is a legal-tech platform that connects users with verified professionals and automates legal processes.

    Where is Lawizer based?

    Answer: Lawizer is based in West Bengal, India.

    Is Lawizer legitimate?

    Answer: Yes, Lawizer is an initiative of Zeptus Pvt Ltd and operates as a registered digital service provider.

    Do I need an NBFC license to start a lending app?

    Answer: Yes, if you lend your own funds. Otherwise, you can operate as an LSP under RBI guidelines.

    What is a Regulatory Sandbox?

    Answer: It is a framework by RBI and SEBI that allows fintech startups to test innovative products in a controlled environment.

  • Step-by-Step Guide to GST Registration for Small Shop Owners

    Step-by-Step Guide to GST Registration for Small Shop Owners

    Introduction

    GST registration is a transformative step for any sole proprietorship in India. It is the bridge that transitions a small local business into a legally recognized, tax-compliant entity.

    While the government has digitized the process through integrated portals, the journey often remains challenging due to rigorous documentation and legal verification requirements.

    The Goods and Services Tax (GST) law can be overwhelming for individual shop owners.

    However, utilizing Lawizer, a leading legal-tech solution, enables a stress-free registration process through direct consultations with verified legal experts.


    Understanding GST for Small Store Owners

    GST is a comprehensive, destination-based indirect tax that replaced the fragmented old system of VAT, Service Tax, and Excise Duty. For a small business owner, the business and the individual are legally inseparable.

    Consequently, your Permanent Account Number (PAN) acts as the primary identifier for your 15-digit GST Identification Number (GSTIN).

    Breaking Down the GSTIN

    • First 2 digits: State Code.
    • Next 10 digits: Proprietor’s PAN.
    • Last 3 digits: Entity number, default character, and checksum digit.

    Why Should You Register Today?

    Registering under GST is not just a legal requirement. It opens up growth opportunities for your business and builds long-term credibility.

    1. Legal Compliance: Every business exceeding the threshold limit must register to avoid heavy legal penalties.
    2. Input Tax Credit (ITC): You can claim back the GST paid on business purchases such as furniture, laptops, or shop rent.
    3. Market Expansion: Many large corporations and B2B clients only collaborate with GST-compliant vendors.
    4. E-Commerce Access: A GSTIN is mandatory to sell products on platforms like Amazon, Flipkart, or Myntra.

    2026 Thresholds: When is GST Registration Compulsory?

    As of 2026, the following turnover limits apply to sole proprietorships in India:

    Category Mandatory Threshold
    Service Providers Annual turnover exceeding ₹20 Lakhs
    Goods Suppliers Annual turnover exceeding ₹40 Lakhs
    Special Category States ₹10 Lakhs for services / ₹20 Lakhs for goods

    Zero-Threshold Cases (Mandatory Regardless of Turnover):

    You must register if you:

    • Engage in interstate sales.
    • Sell through e-commerce platforms.
    • Operate as a Casual Taxable Person.

    The 6-Step GST Registration Process

    Step 1: Initiation via Part A

    Visit the official GST portal. Provide PAN, mobile number, and email. After OTP verification, a Temporary Reference Number (TRN) is generated.

    Step 2: Business Details

    Log in using TRN and complete Part B by entering trade name, selecting proprietorship, and stating the reason for registration.

    Step 3: Document Uploads

    • Identity Proof: Aadhaar Card and PAN Card
    • Photograph: Proprietor’s image
    • Address Proof: Rent agreement, NOC, or utility bills
    • Bank Proof: Cancelled cheque or passbook copy

    Step 4: Aadhaar Authentication

    An Aadhaar-based e-KYC verification is required. Successful verification may eliminate physical inspection.

    Step 5: Officer Verification

    An officer reviews your application. If needed, a clarification notice (REG-03) is issued, which must be answered within 7 working days.

    Step 6: GSTIN Generation

    Upon approval, your GSTIN and Registration Certificate (Form REG-06) are issued. Download and display it at your place of business.


    How Does Lawizer Make the Process Seamless?

    GST registration can be complex, and errors often lead to delays. Lawizer connects business owners with professionals like Chartered Accountants and Company Secretaries to simplify the process.

    Why Choose Lawizer?

    • Expert Oversight: Ensures documentation meets government standards.
    • Fast Response: Provides quick consultations.
    • Virtual Office Solutions: Helps with business address documentation.
    • Query Handling: Experts manage government notices and responses.
    • Affordable: Free consultation with transparent pricing.

    Get GST Registered Without Hassle. Choose Lawizer Today!


    Frequently Asked Questions

    What is Central GST (CGST)?

    A: CGST is the tax levied by the Central Government on intra-state transactions.

    What is State GST (SGST)?

    A: SGST is the tax levied by the State Government on intra-state transactions.

    What is Integrated GST (IGST)?

    A: IGST applies to inter-state transactions and is collected by the Central Government.

    Are there fees for registration?

    A: While the government portal is free, Lawizer charges a service fee for handling documentation and filing.

    How long does the process take?

    A: Typically, GSTIN is issued within 3 to 10 working days after successful Aadhaar authentication.

    Is Lawizer a registered company?

    A: Yes. Lawizer is an initiative of Zeptus Private Limited, a registered entity in India.

  • Why Your Brand Needs Trademark Registration in India Today?

    In the hyper-competitive Indian market, your brand name isn’t just a label—it is a vital business asset.

    Many founders make the mistake of thinking a Domain Name or a Company Registration (RoC) gives them ownership of their brand.

    However, in the eyes of Indian law, a domain name is merely an address, and a RoC provides a legal identity but zero Intellectual Property (IP) protection.

    Without a registered trademark, you are building your business on a weak foundation. Lawizer, a leading legal-tech platform, offers the most efficient way to secure your brand.


    1. The Shield and Sword of Your Business:

    A trademark acts as both a defensive shield and an offensive sword under the Trade Marks Act, 1999. Registration grants you the exclusive right to use your brand name, logo, and tagline nationwide.

    • The Shield: It prevents others from feeding on your hard-earned reputation.
    • The Sword: It gives you the legal power to sue copycats who try to confuse your customers with similar-sounding names.

    2. The Power of the ® Symbol:

    The transition from a “TM” to an ® is more than just a character change; it’s a global signal of authenticity and trust.

    • Exclusive Rights: Grants sole legal authority to use your brand identity.
    • Statutory Weight: Provides the necessary legal standing to win infringement cases quickly.
    • Marketplace Entry: Most major e-commerce platforms and government tenders require a registered trademark for onboarding.

    3. Business Expansion and Franchising:

    If you plan to scale, franchise, or license your brand, trademark registration is mandatory.

    Investors and partners are more likely to fund brands with secured legal protection. A registered trademark allows you to enter “e-commerce” and international markets without the fear of brand theft.

    Costs and Duration to Register:

    • Affordability: Government charges are concessional for startups, individuals, and small enterprises.
    • Validity: Protection lasts for 10 years and is renewable indefinitely.
    • Timeline: The process typically takes 12 to 18 months.

    Key Industries Powered by Trademark Registration

    Trademarking is a strategic asset across these high-growth sectors:

    IndustryWhy It Matters
    Consumer GoodsPrevents “look-alike” products in crowded markets.
    Food & BeverageProtects unique packaging and brand names.
    HealthcareEnsures trust and stops dangerous counterfeit products.
    Tech & SoftwareSecures identity in fast-moving, innovative sectors.
    Luxury & FashionPreserves exclusivity by stopping counterfeiters.

    How Lawizer Simplifies the Process:

    Lawizer, an initiative of Zeptus Pvt Ltd, makes the journey from “TM” to “®” easy and stress-free.

    Lawizer Prerequisites:

    To get started, you will need the following documents:

    For Individuals / Startups / MSMEs:
    • Applicant’s PAN Card & Aadhaar
    • Address Proof
    • MSME/Udyam Certificate (for a 50% government fee concession)
    For Companies / LLPs / Partnerships:
    • Incorporation Certificate / Partnership Deed
    • PAN Card of the Entity
    • TM-48 Form (Authorizes our legal experts)

    What You Receive Through the Lawizer Portal:

    1. Instant TM Number: Use the “TM” symbol immediately after filing.
    2. Objection Management: Our experts handle “Examination Reports” to keep your application moving.
    3. Emergency SOS Button: Connect with an advocate within 2-3 minutes for urgent help.
    4. Free Consultation: Expert guidance for all first-time users.

    Conclusion: Legitimizing Your Innovation:

    In the “move fast and break things” culture of startups, don’t let your brand equity be the thing you break. Trademark registration is a business asset that increases your valuation during funding rounds.

    Secure Your Brand Today:

    Stop wondering if your brand is safe. Get expert guidance and end-to-end support with Lawizer. We’ll get back to you within 24 hours.

    Frequently Asked Questions (FAQs):

    Q1. Can I register a domain name as a trademark?

    A: Yes. If customers identify your service through your URL (e.g., Lawizer.com), the domain itself can be your trademark.

    Q2. What is the benefit of MSME/Udyam Registration?

    A: It is a massive cost-saver. Filing fees are ₹9,000 for companies but only ₹4,500 for MSMEs/Startups. Lawizer helps you leverage these concessions.

    Q3. How do I handle an “Objection”?

    A: Objections are common. Lawizer provides end-to-end support for these hearings, drafting the necessary legal counter-statements for you.

    Q4. Is Lawizer a registered company?

    A: Yes. Lawizer is an initiative of Zeptus Private Limited, a registered entity in West Bengal, India.

    Q5. Is Lawizer a law firm?

    A: No, Lawizer is a digital legal platform that connects you with qualified and verified lawyers. It does not provide legal advice directly.

  • How to Use Lawizer’s SOS Button for Legal Emergencies in India

    How to Use Lawizer’s SOS Button for Legal Emergencies in India

    In India, finding legal help can be a challenge, especially during a crisis.

    Whether you are dealing with a wrongfully issued traffic challan, a cybercrime situation, or a threat to women’s safety, immediate access to professional counsel is vital.

    Lawizer is designed to provide that instant support.

    By bridging the gap between technology and the legal profession, it offers a real-time solution for those who need an emergency legal aid application or immediate advocate support when every second counts.

    What is Lawizer?

    Lawizer is a next-generation digital legal platform that makes legal support fast, simple, and affordable for individuals and startups.

    It is important to note that Lawizer is not a law firm and does not provide legal advice directly.

    Instead, it functions as a secure bridge connecting users with verified advocates before minor problems escalate into major legal battles.

    Key Features:

    • 24/7 Legal SOS Button: For urgent, real-time action.
    • Transparent Pricing: Zero hidden fees and a free first consultation.
    • Verified Experts: Choose advocates based on experience, language, and credentials.

    Steps to Use Lawizer’s SOS Emergency Button:

    The SOS feature acts as a “panic button,” connecting you with a legal expert within minutes. Follow these steps to get help:

    Step 1: Visit the Website:

    Use your mobile browser to search for Lawizer and open the official website.

    Step 2: Click the SOS Button:

    On the homepage, locate and click the “Emergency SOS Button.”

    Step 3: Sign In or Register:

    You will be prompted to sign in. If you are a new user, enter your name, email, phone number, and a secure password.

    Step 4: Verify Your Email:

    Check your mailbox for a verification link to activate your account. This step is crucial for security.

    Step 5: Complete Your Profile:

    Log in and update your details, including your State and City. This helps the platform match you with a lawyer who understands your local jurisdiction.

    Step 6: Confirm the SOS Call:

    Click the Emergency SOS button once more to confirm. A phone number will appear on your dial pad. Call this number to be connected to an expert in 2–3 minutes.

    Tips for Efficient Communication During a Legal Crisis:

    When you are connected to a lawyer, providing structured information helps them protect you faster.

    1. Be Precise and Factual: Stick to the facts of the current situation.
    2. Share Evidence: Have your receipts, challans, or digital documents ready to share.
    3. Identify the Category: Specify if your issue is related to Criminal, Civil, Property, or Business law to bypass guesswork.
    4. Ask About Fees: While the first consultation is free, discuss future fee structures early to keep the process transparent.

    Conclusion:

    Lawizer’s 24/7 Legal SOS button empowers every Indian citizen to act with confidence during a crisis.

    By leveraging technology to provide real-time responses from verified experts, the platform ensures that help is always just a click away.

    Frequently Asked Questions (FAQs):

    Q1. Is Lawizer a legitimate company?

    A: Yes, Lawizer is an initiative of Zeptus Private Limited, registered in West Bengal, India.

    Q2. Is the first consultation really free?

    A: Yes. Lawizer offers the first consultation for free because they believe legal clarity should always come before cost.

    Q3. Can Lawizer help with cyber complaints or traffic police?

    A: Absolutely. The platform connects you with specialized lawyers for cybercrimes, traffic disputes, and general civil matters.

  • CORPORATE TAX FILING 101: A CHECKLIST FOR FILING ITR 6 FOR PRIVATE LIMITED COMPANIES

    CORPORATE TAX FILING 101: A CHECKLIST FOR FILING ITR 6 FOR PRIVATE LIMITED COMPANIES

    This blog will cover the basic requirements for filing ITR-6 , Importance of
    Corporate tax return India , ITR-6 Due date.

    ITR 6

    Introduction: Purpose Of Filing Under ITR-6:

    For filing under ITR-6 for the income tax return , it is especially done for
    companies which are incorporated under the Companies Act , 2013.

    This ensures not only reporting of income , deduction , taxes and transaction Filing an ITR-6 helps in maintaining the company whether is private or public, it keeps under a obligations effectively and systematically.

    Eligibility Criteria Of Filing ITR-6:

    The companies that are registered under the Companies Act 2013 should file
    ITR-6 . It includes Domestic Companies , Foreign Companies, Partnership Firms.

    Structure of the filing the ITR-6?

    • The Income Tax Department advices that are two parts and several
      schedules.
    • As a sequence wise they can file out a form by Part A , Schedules,
      Part B and Verification.

    How To File ITR-6 Form?

    This is generally done through compulsory electronically under digital signature to the income tax department.

    Filing Of ITR-6 Due Date:

    The due date for filing an income tax return is to be maintained by the is a assessee partner in a firm then the accounts is to be audited by 31st of October of the Assessment year.

    Benefits Of Filing In ITR-6?

    • It enhances and ensures transparency.
    • The collection of documents is required to be maintained for record
      purpose and tax audits statements.
    • It minimizes deduction and avoid penalties and interest charges.
    ITR 6

    Conclusion:

    The criteria and aspect of ITR-6 is detailed oriented and is only
    applicable to the companies.

    This helps companies in avoid penalties, interest and avoid tax compliance issue from tax authorities.

    Corporate Tax Doesn’t Have to Be Taxing. Private Limited Companies require precision—from balance sheets to audit reports.

    Don’t navigate the complex maze of corporate tax laws alone.

    Our team ensures your ITR-6 is filed with 100% accuracy and complete statutory compliance, letting you focus on growing your company.

    [Secure Your Corporate Tax Filing Services Now]

    Sources:

  • ITR-5 FILING GUIDE FOR PARTNERSHIP FIRMS AND LLPs: AVOID COMMON MISTAKES

    ITR-5 FILING GUIDE FOR PARTNERSHIP FIRMS AND LLPs: AVOID COMMON MISTAKES

    Introduction

    Many business entities such as partnership firms, Limited Liability Partnerships (LLPs), and associations are required to file their income tax returns every year. For these entities, the relevant tax return form is ITR-5.

    The procedure of filing ITR-5 is an important compliance requirement under the Income Tax Act. It helps businesses report their income, claim deductions, and ensure proper tax compliance with the Income Tax Department.

    Understanding the process of filing ITR-5, the due date, tax audit requirements, and applicable tax rates for partnership firms is essential for avoiding penalties and maintaining financial transparency.

    This guide explains the procedure of ITR-5 filing, LLP income tax returns, tax audit requirements, and the due date for filing ITR-5.


    What Is ITR-5?

    ITR-5 is the income tax return form used by certain business entities such as partnership firms, LLPs, and associations of persons.

    The form is designed to capture detailed financial information including business income, capital gains, deductions, and tax liabilities.

    ITR-5 is filed electronically through the Income Tax Department’s e-filing portal.


    Who Can File ITR-5?

    The following entities are eligible to file ITR-5:

    • Partnership Firms
    • Limited Liability Partnerships (LLPs)
    • Association of Persons (AOPs)
    • Body of Individuals (BOIs)
    • Co-operative Societies
    • Local Authorities

    However, individuals, Hindu Undivided Families (HUFs), and companies cannot use this form.


    Structure of the ITR-5 Form

    The ITR-5 form is comprehensive and contains several sections to report financial information accurately.

    The form is divided into two main parts:

    • Part A – General Information
    • Part B – Computation of Total Income and Tax Liability

    In addition, the form contains nearly 40 schedules used to report specific financial details such as capital gains, business income, deductions, and taxes paid.


    Procedure for Filing ITR-5

    The ITR-5 form must be filed electronically through the Income Tax Department’s e-filing portal.

    The return can be filed in the following ways:

    • Submitting the return electronically using a Digital Signature Certificate (DSC)
    • Uploading the return electronically and verifying it through e-verification methods

    After filing the return, the taxpayer must complete e-verification within 30 days of submission.


    Changes in ITR-5 Form (AY 2025-26)

    The Income Tax Department has introduced certain updates to the ITR-5 form for recent assessment years.

    • New reporting fields for high-value financial transactions exceeding ₹50 crore
    • Disclosure requirements for payments to Micro and Small Enterprises under Section 43B(h)
    • Additional reporting related to capital gains and specified securities

    These changes are intended to increase transparency and ensure proper reporting of financial transactions.


    Partnership Firm Tax Rate

    For the Assessment Year (AY) 2026-27, partnership firms including LLPs are taxed at a flat rate of 30% on their taxable income.

    In addition to this tax rate, surcharge and health & education cess may also apply depending on the income level.


    Tax Audit for Partnership Firms

    A tax audit is required to ensure that businesses maintain proper books of accounts and comply with the provisions of the Income Tax Act.

    Under Section 44AB, a tax audit becomes mandatory when the business turnover exceeds the prescribed limits.

    The audit helps verify:

    • Accuracy of financial statements
    • Proper maintenance of accounting records
    • Correct reporting of income and deductions
    • Compliance with tax regulations

    A tax audit also helps detect errors, irregularities, and potential financial discrepancies in the accounting records.


    Due Date for Filing ITR-5

    The due date for filing ITR-5 depends on whether the entity is subject to a tax audit.

    • 31 July – For entities not requiring a tax audit
    • 31 October – For entities requiring a tax audit

    Failing to file the return before the due date may lead to penalties and interest under the Income Tax Act.


    Conclusion

    Filing ITR-5 is a crucial compliance requirement for partnership firms, LLPs, and other eligible entities. It ensures that businesses properly report their income and comply with tax regulations.

    Timely filing of ITR-5, along with maintaining proper accounting records and completing tax audits when required, helps businesses avoid penalties and maintain financial transparency.

    Understanding the procedure of ITR-5 filing and staying updated with changes in tax laws allows firms to remain compliant and manage their finances effectively.


    Frequently Asked Questions

    Who cannot file ITR-5?

    Individuals, Hindu Undivided Families (HUFs), companies, and entities required to file ITR-7 cannot file ITR-5.

    Is tax audit applicable for ITR-5?

    Yes. A tax audit is required if the business turnover exceeds the limits specified under Section 44AB of the Income Tax Act.

    Is it mandatory for LLPs to file ITR-5?

    Yes. Limited Liability Partnerships (LLPs) are required to file their income tax return using the ITR-5 form.

    What is the time limit for e-verification of ITR-5?

    The return must be e-verified within 30 days of filing.


    Sources