Tag: lawizer

  • Founders Agreement Explained

    Founders Agreement Explained

    founders agreement explained: clauses & legal guide

    Starting a business with a co-founder often begins with trust, shared goals and an exciting idea. However, as the business grows, questions about ownership, salary, responsibilities and decision-making can become difficult. This is where founders agreement explained in practical terms becomes important for Indian entrepreneurs. A founders agreement records what the founders have agreed about the business before disagreements arise.

    For example, what happens if one founder stops working full-time? Who owns the intellectual property created before incorporation? Can a founder sell their shares to an outsider? What happens if two founders disagree about a major business decision?

    A properly drafted agreement can provide a framework for answering these questions. The Government of India’s Startup India guidance also recognises a co-founder agreement as a way to set out equity ownership, initial investment and founder responsibilities in writing.

    In this guide, we explain the purpose of a founders agreement, important clauses, founder salary and equity, CEO and founder authority, exit provisions and common questions Indian founders should understand.

    Founders agreement explained: what is a founders’ agreement?

    A founders’ agreement, also called a co-founders agreement, is a written contract between the people starting or jointly running a business. It records important arrangements between the founders, such as their responsibilities, ownership, contributions, decision-making rights and what happens if the relationship changes.

    The agreement is particularly useful when two or more people are building a business together. It converts important conversations into documented terms that the founders can refer to later.

    Depending on the business structure and circumstances, the agreement may work alongside documents such as the company’s Articles of Association, employment agreements, intellectual property assignments and a shareholders’ agreement.

    Lawizer provides business documentation and agreement drafting services, including a dedicated Co-Founder Agreement service for founders who want their arrangements documented clearly.

    What does a founders agreement cover?

    A founders agreement can cover many areas, including:

    • Founder names and business details
    • Equity ownership and capital contributions
    • Roles and responsibilities
    • Founder salary and expense reimbursement
    • Decision-making and voting
    • Founder vesting arrangements
    • Intellectual property ownership
    • Confidentiality
    • Share transfer restrictions
    • Founder exit and separation
    • Deadlock and dispute resolution

    The exact clauses should be tailored to the business rather than copied from a generic internet template.

    What is the purpose of a founders agreement?

    The main purpose is to reduce uncertainty between co-founders. Startup India describes a co-founder agreement as a way to formally record equity ownership, initial investments and responsibilities and reduce the possibility of serious surprises later.

    In practical terms, the agreement creates a written framework for situations that may be easy to ignore when the business is new.

    1. It defines founder roles and responsibilities

    Founders should decide who is responsible for areas such as technology, sales, finance, operations, marketing or product development.

    The agreement can also record whether each founder is expected to work full-time, how much time they are expected to contribute and which decisions fall within their authority.

    2. It records ownership and contributions

    Founders may contribute different amounts of money, intellectual property, experience, contacts or working time. The agreement can record the agreed ownership structure and the basis on which it was determined.

    There is no universal rule saying that two founders must split a company 50:50. The appropriate allocation depends on the circumstances and should be discussed carefully before it becomes a source of conflict.

    3. It establishes decision-making rules

    Not every business decision needs the same level of approval. Founders can establish which matters can be handled by an individual founder and which require approval from multiple founders, the board or shareholders.

    This can be especially important when founders have equal or similar ownership and a disagreement could otherwise create a deadlock.

    4. It prepares for a founder’s exit

    A founder may eventually resign, become unable to continue, move to another country, start another venture or simply decide that the business is no longer suitable for them.

    An agreement can establish what happens to their shares, confidential information, company property and responsibilities when they leave.

    5. It protects intellectual property

    For many startups, intellectual property is one of the most valuable assets. This can include software, source code, designs, branding, written content, inventions, databases and business processes.

    Founders should clearly address ownership and assignment of relevant intellectual property. Lawizer also provides an IP Assignment Agreement service for businesses that need separate documentation for intellectual property ownership.

    Key clauses in a founders agreement

    A strong agreement should deal with the issues that are most likely to create disagreement later. The following clauses are commonly considered when preparing founder documentation.

    Founder details and business information

    Start with the identity of each founder and the relevant business details. The document should clearly identify who is entering into the agreement and, where applicable, the company or proposed company connected with it.

    Equity ownership and capital contributions

    The agreement should state the agreed ownership structure and explain the founders’ initial contributions.

    Contributions may involve cash, assets, intellectual property, services or other agreed commitments. If additional funding may be required from founders, the agreement can also explain how those contributions will be handled.

    Founders should remember that an agreed percentage in a contract is not necessarily the same thing as the company’s legally issued and recorded shareholding. Corporate records, share issuances and applicable company documents must also be kept consistent.

    Roles, responsibilities and time commitment

    A founders agreement should explain who will perform which functions.

    • Who will lead operations?
    • Who will manage technology?
    • Who will handle sales and business development?
    • Who will manage finance?
    • Who will represent the company externally?

    Clear responsibilities reduce duplication and make accountability easier.

    Founder salary and expenses

    Founders should decide whether they will receive a salary, when salary will begin and how expenses will be reimbursed.

    Early-stage businesses may have limited cash. Therefore, founders may agree to take lower compensation initially and revisit it when revenue or funding reaches an agreed level.

    The important point is not choosing one universal salary. It is documenting the arrangement clearly enough that founders understand what they can expect.

    Founder vesting

    Vesting connects ownership to continued participation over an agreed period. It can help protect a company when a founder leaves soon after the business starts.

    A commonly discussed startup structure is four years with a one-year cliff. However, this is a market convention, not a mandatory statutory rule for every Indian startup. The actual arrangement should be drafted according to the company’s structure and legal requirements.

    Lawizer also explains founder vesting schedules in India in greater detail.

    Intellectual property and confidentiality

    The agreement should identify how intellectual property created for the business will be owned or assigned. It should also protect confidential business information.

    For example, the agreement may address source code, product designs, customer lists, pricing information, business plans and trade secrets.

    Founders can also consider a separate Non-Disclosure Agreement where appropriate.

    Decision-making and reserved matters

    Founders should identify important decisions that require additional approval. These may include issuing new shares, taking significant debt, selling substantial assets, changing the business model or entering major transactions.

    The exact approval thresholds should be tailored to the company’s ownership and governance structure.

    Founder exit and share transfers

    The agreement can establish procedures for voluntary resignation, termination where legally applicable, death, incapacity and other forms of departure.

    It can also address whether a departing founder can transfer shares to outsiders and whether existing shareholders receive a right to purchase those shares first.

    For a broader explanation of shareholder rights, see Lawizer’s guide to the key clauses in a shareholders’ agreement.

    Dispute resolution

    Disagreements are not always avoidable. A good agreement therefore establishes how disputes should be handled.

    Possible mechanisms include negotiation, mediation and arbitration, depending on the circumstances and drafting. The agreement should also address applicable law and jurisdiction where appropriate.

    Is a founders agreement legally binding?

    A founders agreement can be legally binding when it satisfies the requirements of a valid contract and its terms are enforceable under applicable law. The Indian Contract Act, 1872 contains the general framework for determining when agreements become contracts.

    Section 10 is important because it deals with agreements that qualify as contracts, subject to requirements including free consent, competent parties, lawful consideration and a lawful object, and subject to other provisions of law.

    However, simply signing a document does not make every clause automatically enforceable. Some provisions may be affected by statutory restrictions, company law, employment law, public policy or the particular facts of a dispute.

    For example, post-employment restrictions and non-compete provisions require particular care in India because Section 27 of the Indian Contract Act addresses agreements in restraint of trade.

    For authoritative reference, founders can review the Indian Contract Act, 1872 on India Code.

    If a company is already incorporated, the founders agreement should also be considered alongside its constitutional documents and other shareholder arrangements. Lawizer’s shareholders’ agreement guide explains why these documents should be coordinated.

    How much salary do founders take?

    There is no standard founder salary in India. Compensation varies according to the company’s stage, revenue, funding, founder responsibilities, industry and available cash.

    An early-stage founder may choose to take a modest salary to preserve cash for product development and hiring. A profitable business may support a higher salary.

    Founder salary should also be distinguished from founder equity. A person can have a large ownership stake but take a modest salary, particularly in the early stages.

    The agreement should make the compensation arrangement clear. If salary changes require founder, board or shareholder approval, that process should also be documented.

    How much of a company do founders usually own?

    There is no legally prescribed founder ownership percentage that applies to every startup.

    Founders may divide ownership based on their respective contributions, responsibilities, capital, intellectual property, time commitment and future role. They should also consider future investors, employees and other shareholders.

    Startup India’s guidance notes that deciding how to divide equity among co-founders and early contributors can be challenging and should be approached carefully rather than treated as an automatic equal split.

    If you are still deciding on your business structure, Lawizer’s guide comparing OPC, LLP and Private Limited Company can help explain the main structural differences.

    Who is more powerful: CEO or founder?

    The answer depends on the company’s ownership, board structure, constitutional documents and the person’s actual position in the organisation.

    A founder is someone who helped establish the business. A CEO is generally an executive responsible for managing the company’s operations within the authority given to them.

    One person can be both founder and CEO. Another founder can be a shareholder without being the CEO. Similarly, a professional CEO can be appointed even when the founders remain shareholders.

    Founder vs CEO: what is the difference?

    Founders may have ownership rights because they hold shares or other interests in the business. A CEO’s authority primarily comes from their appointment, employment terms, board authority and the company’s governance arrangements.

    Therefore, the title alone does not determine who has greater legal power.

    Can the chairman fire the CEO?

    Not automatically. Whether a chairman can remove a CEO depends on the company’s structure, the CEO’s legal position and the authority given by the company’s governing documents and applicable law.

    If the CEO is also a director, removal from the board is a separate corporate-law matter. Section 169 of the Companies Act, 2013 deals with removal of directors by the company, subject to the statutory procedure and exceptions.

    The Companies Act, 2013 on India Code contains the statutory framework governing directors and their removal.

    Who has higher power: CEO or chairman?

    The chairman and CEO normally have different roles. The board and its chair are associated with governance and oversight, while the CEO generally handles executive management.

    The exact division of authority depends on the company’s Articles of Association, board decisions, employment arrangements and applicable law.

    Who holds a CEO accountable?

    In a company structure, the board generally plays an important role in overseeing the CEO. Shareholders can also exercise rights provided by company law and the company’s governing documents.

    A founders agreement can help clarify how founders participate in major decisions, but it should not be drafted as though it overrides mandatory provisions of company law.

    Common problems a founders agreement can prevent

    Many founder disputes start with assumptions rather than deliberate wrongdoing. The founders simply remember their original conversation differently.

    A written agreement can reduce this uncertainty in several areas.

    • Unequal work: One founder may eventually contribute much more time than another.
    • Salary disputes: Founders may disagree about when compensation should increase.
    • Ownership disputes: A founder may believe that a different equity split was promised.
    • IP disputes: A departing founder may claim rights over work they created.
    • Decision deadlocks: Equal ownership can make major decisions difficult.
    • Founder exits: A departure can become disruptive if there are no agreed procedures.
    • Investor concerns: Unclear founder arrangements can create additional questions during due diligence.

    Lawizer’s guide on protecting Indian startups from co-founder disputes covers these risks in greater detail.

    How to create a founders agreement in India

    The process should begin with an honest discussion between all founders. The goal is not simply to sign a template. It is to make sure everyone understands the commercial arrangement.

    Step 1: Identify the founders and business

    Clearly identify every party and the business or proposed company to which the agreement relates.

    Step 2: Agree on ownership and contributions

    Record the agreed equity structure and initial contributions. If additional funding may be required, decide how future contributions will be handled.

    Step 3: Define roles and authority

    Set out each founder’s responsibilities, expected commitment and decision-making authority.

    Step 4: Decide compensation

    Document salary, reimbursements and the procedure for changing compensation.

    Step 5: Address vesting and exits

    Decide what happens if a founder leaves early, resigns, becomes unable to work or wants to transfer shares.

    Step 6: Protect intellectual property

    Make sure relevant business IP is appropriately assigned or licensed to the company. This is particularly important when founders create software, branding or other assets before incorporation.

    Step 7: Review and execute the agreement

    All founders should understand the final document before signing. The agreement should also be checked against the company’s Articles of Association, shareholder arrangements and other relevant contracts.

    If you are still setting up the business, Lawizer can assist with Private Limited Company registration, LLP registration and Startup India registration.

    What happens if there is no founders agreement?

    There is no single automatic outcome when founders have not signed a founders agreement. The parties may still have rights under applicable contracts, company law and other legal principles.

    The practical problem is uncertainty. Founders may disagree about what was promised and may have to rely on emails, messages, company records, share documents and other evidence.

    Disputes can become particularly difficult when they involve equity, intellectual property, founder responsibilities or an attempted exit.

    This is why documenting important arrangements early is usually easier than trying to reconstruct them after a disagreement.

    Frequently asked questions about founders agreements

    Is a founders agreement legally binding?

    It can be, provided the agreement satisfies the requirements of a valid contract and its individual provisions are legally enforceable. The Indian Contract Act, 1872 provides the general contractual framework, but specific clauses may be affected by other laws.

    How much salary do founders take?

    Founder salaries vary widely. Early-stage founders often balance personal compensation against the company’s cash requirements. Salary should be decided according to the business’s financial position and documented clearly.

    How much of a company do founders usually own?

    There is no standard percentage. Ownership depends on the founders’ contributions, responsibilities, funding and the company’s future financing plans.

    Is a low founder salary a red flag?

    Not necessarily. A low salary can be normal when a startup is conserving cash. It becomes important to understand the complete compensation arrangement, including equity, expenses and the expected timeline for reviewing salary.

    Who earns more, CEO or founder?

    It depends on the circumstances. A founder may receive substantial value through equity while taking a modest salary. A professional CEO may receive a higher cash compensation package. Salary and ownership should therefore be compared separately.

    What is a top 1% salary in India?

    The answer depends on the dataset and whether the measure refers to individual earnings, household income, salary or total income. A 2025 Institute for Competitiveness report based on PLFS data for 2023–24 stated that the top 1% income threshold was at least ₹75,000 per month. This should not be treated as a universal definition of a “top 1% salary” because income measures and datasets differ.

    What is Narendra Modi’s monthly salary?

    The Prime Minister’s remuneration is governed by the Salaries and Allowances of Ministers Act, 1952 and related rules. Official government information states that the Prime Minister’s pay and allowances are provided under that framework. Public figures commonly reported for the Prime Minister’s monthly remuneration can include salary and allowances, so figures should not be confused with basic salary alone.

    The official Salaries and Allowances of Ministers Act, 1952 is the appropriate legal reference.

    Who earns ₹48 crore per day?

    A widely circulated 2025 claim stated that Indian-origin technology executive Jagdeep Singh was earning an amount equivalent to about ₹48 crore per day. However, the figure was derived from a reported annual compensation figure and was widely described in media coverage as an exceptional stock-option and performance-linked package rather than an ordinary daily salary.

    Reports also noted that the compensation figure was not independently verified by all outlets. Therefore, it should not be presented as a normal CEO salary or as a guaranteed cash payment of ₹48 crore every day.

    Who is the richest CEO in India?

    There is no single reliable answer without defining what “richest” means. Net worth, founder ownership, salary and annual compensation are different measurements.

    A founder-CEO may have a large net worth because they own shares in a company. That does not mean they receive the same amount as salary.

    Which job pays ₹1 crore per month?

    ₹1 crore per month is an exceptionally high level of compensation. It is not a standard salary attached to one particular job. Such figures can arise in senior executive roles, investment management, entrepreneurship or performance-linked compensation, but they vary substantially.

    Who is the youngest CEO ever?

    Claims about the “youngest CEO” depend on the definition being used. Some lists include children who became CEOs of family businesses or small ventures, while others refer to CEOs of established companies. Therefore, age alone does not provide a meaningful comparison of executive responsibility.

    What should you do about a toxic CEO?

    The appropriate response depends on the company’s governance structure and the conduct involved. Founders or directors should document serious issues, review the company’s governing documents and use the appropriate internal escalation process.

    Where the issue involves potential misconduct, employment disputes, shareholder rights or corporate governance, professional legal advice may be appropriate.

    What are 10 signs of a toxic manager?

    Common warning signs may include:

    1. Micromanaging employees excessively
    2. Consistently shifting blame
    3. Ignoring reasonable feedback
    4. Favouritism or unfair treatment
    5. Publicly humiliating team members
    6. Creating unreasonable or constantly changing expectations
    7. Refusing to accept responsibility for mistakes
    8. Using intimidation instead of constructive management
    9. Withholding important information unnecessarily
    10. Creating a consistently unhealthy working environment

    Final takeaway: why founders should put agreements in writing

    A founders agreement is not about assuming that a business relationship will fail. It is about deciding important issues while the founders are still aligned.

    Ownership, responsibilities, salary, intellectual property, decision-making, vesting and founder exits are much easier to discuss before a disagreement occurs.

    For Indian startups, the agreement should also be coordinated with the company’s constitutional documents and other contracts. A carefully drafted document can provide clarity without trying to replace mandatory legal requirements.

    Founders should review the arrangement whenever there is a major change, such as a new investor, new co-founder, significant change in ownership or change in the business structure.

    Need help preparing your founders agreement?

    If you are starting a business with one or more co-founders, documenting your arrangement early can help reduce uncertainty later. Lawizer provides business agreement and legal documentation services, including Co-Founder Agreements, IP assignment and other startup documentation.

    If your business is still being established, you can also explore Private Limited Company registration, GST registration, trademark registration and annual compliance support.

    For founders who want to discuss their specific circumstances, consult Lawizer for professional legal documentation support before signing an agreement.

    Important: This article provides general legal information for Indian founders. It is not a substitute for legal advice on a specific agreement, company structure or dispute.
  • Shareholder Agreement Basics

    Shareholder Agreement Basics

    shareholder agreement basics: India Guide

    A clear understanding of shareholder agreement basics can help Indian founders avoid disputes over ownership, voting, management, share transfers and exits. A Shareholders’ Agreement (SHA) sets out agreed rights and obligations between shareholders and can provide a practical framework for running a company when more than one person owns it.

    For founders, the value of an SHA is often most obvious when circumstances change. A co-founder may want to leave, a new investor may join, shareholders may disagree about a major decision, or someone may want to sell their shares. A well-drafted agreement can make these situations easier to manage.

    This guide explains the key concepts in simple language, with a focus on Indian companies and small businesses.

    shareholder agreement basics for Indian startups and founders

    What Is a Shareholders’ Agreement?

    A Shareholders’ Agreement is a contract between some or all of the shareholders of a company. It records how the shareholders will exercise certain rights, make decisions and deal with events such as share transfers, founder exits and disputes.

    An SHA can be particularly useful for a private company where a small group of founders or investors needs clear rules for ownership and decision-making.

    It may cover matters such as:

    • Shareholding and ownership rights
    • Voting and decision-making
    • Appointment of directors
    • Reserved matters
    • Share transfer restrictions
    • Right of first refusal or similar transfer rights
    • Tag-along and drag-along rights
    • Founder vesting and exit arrangements
    • Confidentiality and intellectual property
    • Deadlock and dispute resolution

    An SHA should not be treated as a replacement for the Companies Act, 2013 or the company’s Articles of Association (AoA). It operates within the wider legal and constitutional framework of the company.

    Is a Shareholders’ Agreement Mandatory in India?

    There is no general rule under the Companies Act, 2013 requiring every Indian company to have a separate Shareholders’ Agreement. However, an SHA can be highly useful where there are multiple founders or investors.

    Without a written agreement, shareholders may have to rely on the company’s constitutional documents, applicable law and evidence of their other arrangements. That can leave important commercial questions unclear.

    Founders can also review Lawizer’s guide to important Shareholders’ Agreement clauses for a more detailed discussion of common SHA provisions.

    Shareholders’ Agreement vs Articles of Association

    The Articles of Association are the company’s internal rules and form part of its constitutional framework. A Shareholders’ Agreement is a private contract between the relevant parties.

    The distinction matters because an SHA should not contain provisions that conflict with mandatory company law or the company’s constitutional documents.

    The Supreme Court’s decision in V.B. Rangaraj v. V.B. Gopalakrishnan is an important authority on restrictions concerning share transfers and the Articles of Association. The practical lesson for founders is simple: important restrictions intended to operate at company level should be properly reflected in the company’s constitutional documents where required.

    shareholder agreement basics: What Should an SHA Include?

    The exact terms depend on the company, its shareholders and its funding arrangements. However, several areas commonly deserve careful attention.

    1. Shareholding and Ownership

    The agreement should clearly record the current ownership structure. This can include the number and class of shares held by each shareholder and, where relevant, the rights attached to those shares.

    It is also sensible to consider what happens if the company issues additional shares. A future funding round can change existing ownership percentages, so shareholders should understand how new capital may affect their interests.

    2. Voting Rights and Decision-Making

    An SHA can establish how shareholders will vote on important matters. It may also identify decisions that require a higher approval threshold than ordinary business decisions.

    For example, reserved matters may include:

    • Changing the Articles of Association
    • Issuing new shares
    • Taking on significant debt
    • Acquiring another business
    • Changing the company’s main business
    • Approving a major transaction
    • Winding up the company

    The exact list and approval threshold should be tailored to the company rather than copied from another business.

    3. Board and Management Rights

    Shareholders own shares, while directors generally manage the company through the Board subject to the Companies Act, the Articles and the company’s governance arrangements.

    An SHA may specify who can nominate directors, how board decisions are made and what happens if shareholders disagree with the Board.

    This distinction is especially important for founders. Owning a particular percentage of shares does not automatically mean that the shareholder personally manages every aspect of the company.

    4. Share Transfer Restrictions

    A shareholder may eventually want to sell or transfer shares. An SHA can establish procedures for such transfers.

    Common mechanisms include:

    • Right of First Refusal (ROFR)
    • Right of First Offer (ROFO)
    • Pre-emption rights
    • Restrictions on transfers to competitors
    • Consent requirements

    These provisions can help existing shareholders manage who may become a shareholder and protect the company from an unwanted transfer.

    5. Tag-Along and Drag-Along Rights

    Tag-along rights generally protect minority shareholders when a majority shareholder sells shares to a third party. Subject to the agreed terms, minority shareholders may have the right to participate in the sale on similar terms.

    Drag-along rights work differently. They can allow qualifying shareholders to require other shareholders to participate in a sale, subject to the agreement and applicable law.

    Both provisions should be drafted carefully because they can significantly affect a shareholder’s exit rights.

    6. Founder Vesting and Exit Provisions

    Founders may hold substantial equity from the beginning. A vesting arrangement can help address the risk of a founder leaving soon after incorporation while retaining a large stake.

    Founder arrangements may address:

    • Vesting periods
    • Cliff periods
    • Good leaver and bad leaver situations
    • Treatment of unvested shares
    • Buyback or transfer mechanisms where legally permissible

    These provisions should be structured carefully because Indian company law, contract law, securities rules and tax considerations can affect how an arrangement is implemented.

    Lawizer’s guide to founder vesting schedules in India explains why founders should address equity vesting before a dispute arises.

    7. Confidentiality and Intellectual Property

    An SHA can contain confidentiality obligations and provisions dealing with intellectual property. However, founders should not assume that a general SHA clause automatically handles every IP issue.

    For software, brands, designs, documents and other intellectual property, a separate assignment arrangement may also be appropriate.

    Businesses can also consider a separate intellectual property assignment agreement and NDA for protecting confidential information.

    8. Dispute Resolution

    Shareholder disputes can become expensive when there is no agreed process for resolving them. An SHA can establish a sequence such as negotiation, mediation and arbitration, depending on the parties’ requirements.

    The agreement should clearly identify the governing law and the dispute-resolution mechanism. Arbitration clauses should also be drafted consistently with the Arbitration and Conciliation Act, 1996.

    What Are the 7 Rules of a Contract?

    There is no single statutory list called the “seven rules of a contract” in Indian law. However, several core principles are useful when considering whether an SHA is legally sound.

    1. Offer and Acceptance

    The parties should reach an agreement through a valid offer and acceptance.

    2. Intention to Create Legal Relations

    The parties should intend their arrangement to have legal consequences.

    3. Lawful Consideration

    Where consideration is required, it must satisfy the requirements of Indian contract law.

    4. Capacity to Contract

    The parties must have legal capacity to enter into the agreement.

    5. Free Consent

    Consent should not be obtained through coercion, undue influence, fraud or misrepresentation.

    6. Lawful Object

    The purpose of the agreement must be lawful.

    7. Certainty and Enforceability

    The terms should be sufficiently clear and should not be contrary to applicable law.

    Section 10 of the Indian Contract Act, 1872 is particularly important because it identifies the requirements for agreements to qualify as contracts, including free consent, competent parties, lawful consideration and a lawful object.

    What Are the 5 Main Elements of a Contract?

    People often search for five main elements of a contract. In practical terms, an Indian business agreement should be examined for several connected requirements:

    • Agreement between the parties
    • Competency of the parties
    • Free consent
    • Lawful consideration and object
    • Terms that are not expressly void and can be legally enforced

    These requirements should be considered alongside the specific law applicable to the transaction.

    What Are the Five Principles of Contract Law?

    For a founder, the five principles can be simplified as consent, capacity, legality, consideration and enforceability.

    The Indian Contract Act, 1872 addresses these concepts through provisions dealing with contracts, competency, consent, lawful consideration and lawful objects.

    For business agreements, clarity is equally important. A clause that looks commercially attractive may still create problems if it is uncertain, unlawful or inconsistent with mandatory legislation.

    What Are the Three Stages of a Contract?

    1. Formation

    The parties negotiate and agree on the terms.

    2. Performance

    The parties perform the obligations they accepted under the contract.

    3. Discharge or Termination

    The contract eventually ends through performance, expiry, termination, agreement or another legally recognised mechanism.

    For an SHA, these stages may occur over several years because the agreement can continue while the shareholders remain invested in the company.

    Can a 50% Shareholder Remove a Director?

    Owning 50% of the shares does not automatically mean that a shareholder can personally remove a director whenever they choose.

    For companies governed by the Companies Act, 2013, director removal is subject to statutory procedure. Section 169 deals with removal of directors and generally provides for removal by ordinary resolution, subject to the section’s requirements and exceptions.

    A shareholder holding exactly 50% may also face a deadlock if another shareholder holds the other 50%. The outcome can depend on the company’s Articles, voting rights, board structure and any valid contractual arrangements.

    This is why a good SHA should address deadlocks before they happen.

    Who Is More Powerful: a Director or a Shareholder?

    There is no simple answer because directors and shareholders exercise different powers.

    What Shareholders Do

    • Hold ownership interests in the company
    • Exercise voting rights attached to their shares
    • Participate in shareholder resolutions
    • Exercise rights provided by company law and the Articles

    What Directors Do

    • Participate in Board decision-making
    • Oversee company management
    • Exercise powers assigned to the Board
    • Comply with statutory duties

    A shareholder can therefore have substantial ownership without directly running daily operations. Similarly, a director may have significant management authority without owning a controlling percentage of the company.

    Can a Company Director Just Quit and Walk Away?

    A director can resign, but resignation should be handled formally rather than by simply stopping work.

    Section 168 of the Companies Act, 2013 provides that a director may resign by giving written notice to the company. The section also sets out the effective date and continuing liability for offences committed during the director’s tenure.

    Resigning as a director is also different from selling shares. A person can cease to be a director while continuing to own shares in the company.

    Lawizer’s director resignation service can be useful when a company needs assistance with the formal process.

    What Should I Not Say When Resigning?

    A resignation letter should normally be factual, professional and clear.

    Avoid unnecessary accusations, threats or statements that could create unintended legal consequences. If there is a genuine dispute, it may be better to take legal advice before putting detailed allegations into a resignation letter.

    Also avoid suggesting that resignation automatically cancels your shareholding. Directorship and share ownership are separate matters.

    How Do I Resign in a Classy Way?

    A professional resignation usually contains:

    • A clear statement that you are resigning as a director
    • The intended effective date
    • A brief and professional explanation, if appropriate
    • A willingness to assist with a reasonable handover
    • A request for the company to complete the required records and filings

    Keeping the letter concise can help avoid unnecessary conflict.

    What Is Silent Quitting?

    “Silent quitting” is a workplace phrase describing a person doing only the work they are required to do rather than going beyond their formal responsibilities.

    It is not the same as legally resigning as a company director.

    A director who simply stops participating may still have statutory or contractual obligations. If the person intends to leave the Board, formal resignation should be considered instead.

    What Is the Format of a Shareholders’ Agreement?

    There is no single mandatory format for every SHA. A practical agreement may contain the following sections:

    1. Title and date
    2. Details of the parties
    3. Background and purpose
    4. Definitions
    5. Shareholding structure
    6. Shareholder rights and obligations
    7. Board and governance provisions
    8. Reserved matters
    9. Share transfer restrictions
    10. ROFR, ROFO or pre-emption provisions
    11. Tag-along and drag-along provisions
    12. Founder vesting and exit provisions
    13. Confidentiality and intellectual property
    14. Dispute resolution
    15. Amendment and termination
    16. Signatures and schedules

    The final document should be customised to the company’s actual ownership structure and commercial arrangements.

    What Are the Three Types of Shareholders?

    There is no universal statutory classification called the “three types of shareholders”. For practical business discussions, shareholders may be described as:

    Founders or Promoter Shareholders

    These are the people who establish or promote the business and commonly hold significant ownership.

    Investor Shareholders

    These shareholders invest capital and may receive negotiated voting, information, governance or exit rights.

    Minority Shareholders

    These shareholders hold a smaller percentage and may need specific protections, particularly regarding transfers, information and major transactions.

    The exact rights of any shareholder depend on the class of shares, the Articles, applicable law and valid agreements.

    What Is the “10 Shareholder Rule”?

    The phrase “10 shareholder rule” can be misleading because Indian company law does not have one universal rule stating that every company can have only ten shareholders.

    Depending on the context, people may actually be referring to a percentage-based voting or requisition requirement, a company’s membership rules or a rule from another jurisdiction.

    For example, the Companies Act contains provisions where specific percentages of members or voting rights matter. Therefore, founders should identify the exact provision before relying on a “10 shareholder rule”.

    The type of company also matters. A private company, public company and One Person Company do not have identical membership structures.

    What Are the Five Types of Shares?

    There is no universal statutory list of exactly five “types of shares” that applies in every Indian company context.

    For founders, the important distinction is often between equity shares and preference shares, along with the different rights or structures that may apply to securities issued by a company.

    Companies can also issue securities through mechanisms such as rights issues, bonus issues or employee stock option arrangements. These are not simply five different classes of shares.

    Before issuing or transferring shares, a company should review its Articles, capital structure and the applicable provisions of the Companies Act.

    What Are C Shares?

    “C shares” is not a universal standard category of shares under Indian company law. The term can have different meanings depending on the company, jurisdiction or transaction documents.

    If an SHA or investment document refers to “C shares”, the parties should read the definition and the rights attached to that particular class rather than assuming that every C share has the same legal characteristics.

    What Are the Top 10 Shares?

    “Top 10 shares” is generally an investment-market search query rather than a shareholder-agreement concept.

    The answer depends on factors such as the market, investment horizon, valuation, risk tolerance and financial performance. It should not be confused with ownership rights under an SHA.

    An Indian founder deciding how to structure a private company should focus on the company’s capital structure and shareholder rights rather than public-market stock rankings.

    Shareholder Agreement Basics: Common Mistakes to Avoid

    Even when founders have an SHA, the document may fail to protect them if important issues were overlooked.

    Using a Generic Template

    A template may provide a useful starting point, but every company has a different cap table, governance structure and commercial relationship.

    Ignoring the Articles of Association

    An SHA should be reviewed alongside the Articles. If the documents do not work together, enforcement problems can arise.

    Leaving Share Transfers Unclear

    Founders should understand what happens if someone wants to sell shares, transfer them to a family member or transfer them to an outside party.

    Ignoring Deadlock

    A 50–50 ownership structure can create a serious governance problem if both sides disagree. The SHA should establish a practical route for resolving a deadlock.

    Forgetting Future Funding

    New shares can dilute existing shareholders. The agreement should address how future fundraising and ownership changes will be handled.

    Not Planning for Founder Exit

    Founders should discuss what happens if someone resigns, becomes unable to continue, breaches the agreement or wants to sell their stake.

    Shareholders’ Agreement vs Founders’ Agreement

    A founders’ agreement generally focuses on the relationship between the founding team. It may address roles, equity, vesting, intellectual property, responsibilities and founder exits.

    A Shareholders’ Agreement generally governs the relationship between shareholders and can become particularly important when external investors join the company.

    The two documents should not contradict one another. Lawizer’s guide to founders’ agreements for Indian startups explains the issues founders should consider at an early stage.

    Founders preparing for incorporation can also explore Lawizer’s Private Limited Company registration guide.

    Frequently Asked Questions About Shareholder Agreement Basics

    What are the 5 main elements of a contract?

    The practical elements include agreement, competent parties, free consent, lawful consideration and lawful object, together with the requirement that the agreement is not expressly void and is legally enforceable.

    What are the five principles of contract law?

    For a simple explanation, focus on consent, capacity, legality, consideration and enforceability. The exact legal requirements depend on the applicable statute and facts.

    What are the 7 rules of a contract?

    There is no single statutory list of seven rules. The commonly discussed principles include offer and acceptance, intention, capacity, free consent, lawful consideration, lawful object and certainty.

    What are the three stages of a contract?

    The three broad stages are formation, performance and discharge or termination.

    Can a 50% shareholder remove a director?

    Not automatically. Director removal must follow the applicable statutory procedure, the company’s Articles and relevant voting requirements.

    Who has more control, a director or a shareholder?

    They exercise different powers. Shareholders exercise ownership and voting rights, while directors exercise Board and management powers subject to law and the company’s governance documents.

    Can a company director just quit and walk away?

    A director can resign by following the applicable legal procedure. However, resignation does not automatically dispose of any shares the person owns or remove other contractual obligations.

    What should I not say when resigning?

    Avoid unnecessary accusations, threats or admissions. Keep the resignation professional and seek legal advice before making detailed allegations if there is an ongoing dispute.
    How do I resign in a classy way?

    Give a clear written resignation, state the effective date, offer a reasonable handover and maintain a professional tone.

    What is silent quitting?

    Silent quitting is a workplace phrase. It is not a legal method of resigning as a company director.

    What is the format of a shareholders’ agreement?

    An SHA commonly contains parties, definitions, shareholding, governance, voting, reserved matters, transfers, exit provisions, confidentiality, IP, dispute resolution and termination provisions.

    What are the three types of shareholders?

    “Three types” is not a universal statutory classification. In business discussions, founders, investors and minority shareholders are commonly used descriptive categories.

    What is the 10 shareholder rule?

    There is no universal Indian rule limiting every company to ten shareholders. The correct answer depends on the provision and type of company being discussed.

    What are the five types of shares?

    Indian company law does not provide one universal list of exactly five share types. Equity and preference shares are important categories, while other terms may describe rights, classes or methods of issue.

    What are C shares?

    C shares do not have one universal meaning under Indian company law. Their rights depend on the company’s documents and the terms of the particular issue.

    What are the top 10 shares?

    This is generally a stock-market question rather than a shareholder-agreement question. The appropriate answer depends on the market, valuation, risk and investment objectives.

    Final Checklist for Indian Founders

    Before signing or updating an SHA, review the following:

    • Is the current shareholding accurately recorded?
    • Are voting rights clear?
    • Are reserved matters identified?
    • Are share-transfer restrictions clear?
    • Are ROFR or similar rights properly defined?
    • Are tag-along and drag-along provisions appropriate?
    • Are founder exit and vesting provisions clear?
    • Is intellectual property properly protected?
    • Are confidentiality obligations appropriate?
    • Is there a workable deadlock mechanism?
    • Does the SHA align with the Articles of Association?
    • Have all shareholders understood the document before signing?

    Companies should also keep their broader legal and compliance structure organised. Lawizer provides support for Private Limited Company registration, GST registration, trademark registration and annual compliance.

    Conclusion: Why a Good Shareholders’ Agreement Matters

    A Shareholders’ Agreement is not simply a document to sign when an investor asks for one. It can help founders establish clear expectations about ownership, voting, governance, transfers, exits and disputes.

    The most useful time to resolve shareholder questions is before a disagreement occurs. Once relationships have broken down, changing the agreed rules can become much harder.

    If your company is being incorporated, raising investment, changing its ownership structure or dealing with a founder exit, review the SHA alongside the Articles of Association and the Companies Act.

    Need help with your shareholder agreement? Lawizer can help founders and businesses prepare, review and organise important legal documents with professional support.

    Consult Lawizer for business legal documentation and get guidance suited to your company’s structure and requirements.

    Tags

    • shareholder agreement basics
    • shareholders agreement India
    • shareholders agreement for startups
    • shareholder rights India
    • founders agreement
    • company law India
    • Companies Act 2013
    • share transfer agreement
    • director rights India
    • startup legal documents
    • corporate governance India
    • startup compliance India
  • Business Licenses Every Startup Needs

    Business Licenses Every Startup Needs

    Business Licenses Every Startup Needs in India

    business licenses every startup needs in India checklist
    Business licence and compliance checklist for Indian startups.

    Starting a business in India involves more than registering a company and opening a bank account. The business licenses every startup needs depend on the business structure, industry, location, turnover, employees and activities of the startup. A food business, SaaS company, manufacturer and online retailer can have very different legal requirements.

    There is also an important distinction between a business registration, tax registration, licence and permit. Incorporating a Private Limited Company, for example, does not automatically give the company permission to carry out every regulated activity. Similarly, GST registration is a tax registration, while an FSSAI licence is relevant to food businesses.

    This guide explains the main registrations, licences and approvals Indian founders should evaluate before launching. It also covers industry-specific permissions, online businesses, MSME registration, Startup India, trademark protection and ongoing compliance.

    What Are the Business Licenses Every Startup Needs?

    There is no single licence package that applies to every Indian startup. The correct checklist depends on what the business does and where it operates.

    Most founders should review these categories:

    • Business or entity registration
    • PAN and TAN requirements
    • GST registration, where applicable
    • MSME Udyam registration
    • Shops and Establishments requirements
    • Local trade licences and municipal permissions
    • Industry-specific licences
    • Import and export registrations
    • Employment and labour registrations
    • Intellectual property protection

    Not every item on this list is mandatory for every startup. The goal is to identify which requirements apply to your specific business before you begin commercial operations.

    Business Registration Is the First Legal Step

    Before asking which licence you need, decide how the business will be structured. Common options include a sole proprietorship, partnership firm, LLP, One Person Company and Private Limited Company.

    Private Limited Company

    A Private Limited Company is commonly considered by startups planning to raise equity investment, issue shares or build a scalable corporate structure. It is a separate legal entity and offers limited liability, subject to applicable law.

    Founders can review Lawizer’s Private Limited Company registration service when evaluating this structure.

    Limited Liability Partnership

    An LLP combines partnership-style flexibility with limited liability protection. It can be suitable for professional firms, service businesses and founders who do not need the conventional share structure of a company.

    See Lawizer’s LLP registration service for more information.

    One Person Company

    An OPC can be considered by an eligible solo entrepreneur who wants a corporate structure with a single member. The suitability of an OPC depends on the founder’s plans, compliance requirements and future growth.

    Lawizer also provides One Person Company registration assistance.

    GST Registration: One of the Most Important Startup Tax Registrations

    GST is not a general business licence. It is a tax registration that becomes relevant when the business falls within the registration requirements under GST law.

    For many businesses, the commonly applicable threshold is based on aggregate turnover, with different thresholds and exceptions depending on the nature of supply, state and applicable notifications. Certain categories can also have registration obligations regardless of ordinary turnover thresholds.

    Therefore, founders should not assume that incorporation automatically means GST registration is mandatory. They should assess turnover, taxable supplies, location and the nature of their transactions.

    Lawizer’s GST registration service can help founders organise the registration process.

    For a deeper explanation, read GST Registration for Startups: Who Needs It and How to Apply.

    When Should a Startup Check GST Registration?

    • When turnover approaches the applicable registration threshold.
    • When the business makes transactions that trigger compulsory registration.
    • When the business model involves e-commerce or other specified categories.
    • When the startup begins making taxable supplies in circumstances where registration is required.
    • When the founder wants to evaluate voluntary registration for commercial reasons.

    GST rules can change through legislation, notifications and government decisions. Always check the current position before relying on a particular threshold.

    MSME Udyam Registration for Eligible Startups and Small Businesses

    Udyam registration is different from incorporation and GST registration. It is the government’s MSME registration mechanism for eligible enterprises.

    It is generally not a universal licence required before every startup can begin operations. However, eligible businesses may find Udyam registration useful for accessing schemes, credit-related benefits, government procurement opportunities and protections available under the MSME framework.

    The official Udyam portal states that registration is free and does not require renewal. The current MSME classification is based on investment and turnover criteria, so founders should check the latest government thresholds before applying.

    You can also review Lawizer’s MSME Udyam registration service.

    For more detail, read Udyam Registration: MSME Benefits, Eligibility & How to Apply Online.

    Shops and Establishments Registration

    State-specific Shops and Establishments laws can impose registration, working-condition and record-keeping requirements on certain commercial establishments. The exact rules differ from one state to another.

    A startup operating from a physical office, shop, commercial establishment or similar premises should therefore check the law applicable in its state.

    This is particularly important for founders who assume that company incorporation automatically covers local establishment requirements. It usually does not.

    Do Startups Need a Local Trade Licence?

    A local trade licence may be required by the relevant municipal or local authority depending on the business activity and premises. The requirement is therefore not identical across India.

    Restaurants, shops, workshops, manufacturing units and other establishments may face different local requirements. The location of the premises can also affect which authority is responsible.

    Before signing a long-term commercial lease, founders should check whether their intended business activity is permitted at the premises and whether additional local permissions are required.

    Industry-Specific Business Licences Every Startup Needs to Check

    The most important lesson for founders is that regulated industries can require additional licences beyond normal business registration and tax formalities.

    FSSAI Registration or Licence for Food Businesses

    Food businesses are regulated by the Food Safety and Standards Authority of India. Food Business Operators generally need the appropriate FSSAI registration or licence for their activity.

    This can affect restaurants, cloud kitchens, food manufacturers, processors, distributors, retailers and other food-related businesses.

    The exact category depends on factors such as the nature and scale of the food business. Founders should therefore check the applicable FSSAI category rather than choosing a licence solely based on the business name.

    Importer Exporter Code for Import and Export

    Businesses involved in import or export activities should assess whether they require an Importer Exporter Code, commonly called an IEC.

    DGFT rules generally require an IEC for undertaking import or export activities, subject to applicable exemptions. The IEC process is separate from ordinary company incorporation.

    This matters for manufacturers buying components from overseas, exporters selling Indian products abroad and businesses that regularly conduct cross-border trade.

    Environmental and Pollution-Control Approvals

    Manufacturing, processing, construction and other activities may require permissions from the relevant pollution-control or environmental authorities.

    The requirements can depend on the industry, location, scale and environmental impact. A startup should identify these requirements before establishing a factory or production facility.

    Fire Safety Approvals

    Certain commercial premises may require fire-safety approvals or a Fire NOC depending on local rules, building use, occupancy and other factors.

    Do not assume that the landlord’s existing approval automatically covers your particular business activity. Confirm the position with the relevant local authority.

    Legal Metrology Requirements

    Businesses selling packaged products may need to consider Legal Metrology requirements relating to declarations, quantities, weights, measures and packaged commodities.

    This can be particularly relevant to D2C brands, manufacturers, importers and e-commerce sellers.

    Sector-Specific Financial, Healthcare and Other Licences

    Some sectors have dedicated regulators and licensing frameworks. Financial services, healthcare, pharmaceuticals, education, insurance, telecom and other regulated industries can require approvals beyond the standard startup checklist.

    For such businesses, founders should conduct a sector-specific legal review before accepting customers or launching the regulated service.

    What Licences Does an Online Startup Need?

    An online business is not automatically exempt from regulatory requirements. The internet changes the delivery channel, but it does not necessarily remove the underlying legal obligations.

    For example, an online food business may still need FSSAI compliance. An e-commerce seller may need to assess GST, consumer protection and Legal Metrology requirements. An online business handling personal data should also review its privacy and data-protection obligations.

    Lawizer provides Privacy Policy and Terms of Use documentation for businesses that need appropriate website or application documents.

    Online startups should also consider trademark registration before investing heavily in a brand.

    Trademark Registration Is Not a Business Licence

    A trademark is not a licence to operate a business. Instead, trademark registration protects a brand identifier such as a name, logo or other distinctive mark, subject to the applicable legal requirements.

    Registering a trademark can help a startup protect the identity it is building. It can also become an important business asset when the company expands, raises investment or licenses its brand.

    Lawizer’s Trademark Registration service can assist founders with the filing process.

    You can also read Trademark Registration in India: A No-Jargon Guide for First-Time Founders.

    Startup India Registration: Is It Mandatory?

    DPIIT recognition under the Startup India initiative is not the same as incorporating a business. It is also not a universal licence that every startup must obtain before operating.

    Eligible startups can consider DPIIT recognition to access benefits available under the Startup India framework, subject to the relevant eligibility conditions and separate requirements for individual benefits.

    Founders interested in recognition can review Lawizer’s Startup India registration assistance.

    What Are the Business Licenses Every Startup Needs Before Launch?

    A practical pre-launch checklist can help founders avoid missing an important requirement.

    • Choose the appropriate business structure.
    • Complete company, LLP or other applicable registration.
    • Obtain or confirm PAN and TAN requirements.
    • Check GST applicability.
    • Evaluate Udyam registration if eligible.
    • Check Shops and Establishments requirements.
    • Check local trade licence requirements.
    • Identify industry-specific licences.
    • Check import/export requirements if relevant.
    • Review employee and labour-law registrations when hiring.
    • Protect the brand through trademark registration.
    • Prepare appropriate customer, vendor and founder contracts.
    • Set up a system for recurring tax and corporate compliance.

    Business Licences vs Registrations vs Permits

    These terms are often used interchangeably, but they can serve different purposes.

    Registration

    A registration records a business, taxpayer or enterprise with the relevant authority. Company incorporation and Udyam registration are examples of different types of registration.

    Licence

    A licence generally gives permission to conduct a regulated activity subject to specified conditions. Food businesses are a common example.

    Permit or NOC

    A permit or No Objection Certificate may relate to a particular activity, premises, safety requirement or local approval.

    This distinction matters because obtaining one registration does not automatically satisfy every other regulatory requirement.

    What Happens If a Startup Operates Without a Required Licence?

    The consequences depend on the specific law and the nature of the violation. Possible consequences can include notices, monetary penalties, suspension of operations, cancellation of a registration, difficulty continuing the regulated activity and, in serious cases, prosecution.

    There can also be commercial consequences. Investors may identify compliance gaps during due diligence. Customers may ask for regulatory certificates. Banks, marketplaces or enterprise clients may require evidence of registration before onboarding the business.

    That is why compliance should be treated as part of business planning rather than as paperwork to complete after launch.

    How to Identify the Right Licence Checklist for Your Startup

    Step 1: Identify the Business Activity

    Start with what you actually sell or provide. A software company, restaurant, manufacturer, consultant and pharmaceutical distributor should not use the same checklist.

    Step 2: Identify the Business Structure

    Determine whether you will operate as a proprietorship, partnership, LLP, OPC or company. The structure affects registration and continuing compliance.

    Step 3: Check Your State and Location

    Review state and municipal requirements for the location where the business operates. This is especially important for physical premises.

    Step 4: Check Tax Obligations

    Assess GST, TDS, income-tax and other applicable obligations. Tax registrations depend on the nature of the business and transactions.

    Step 5: Check Sector Regulations

    Ask whether your industry has a dedicated regulator. If yes, identify its registration, licence and reporting requirements before launch.

    Step 6: Review Ongoing Compliance

    Some registrations are only the beginning. Companies and LLPs have recurring filing obligations, while tax and sector-specific registrations can involve regular returns, renewals or updates.

    Lawizer’s annual compliance services can help businesses organise recurring corporate compliance.

    What Are the 7 Stages of a Startup?

    The commonly discussed seven stages are:

    1. Ideation
    2. Validation
    3. Business formation
    4. Launch
    5. Early growth
    6. Scaling
    7. Maturity, acquisition or exit

    Legal requirements can change as the startup moves through these stages. A founder may need only basic registrations initially but later require employment, intellectual-property, fundraising, data, sector or corporate compliance support.

    What Are the 7 Types of Business With Examples?

    There is no single statutory list of exactly seven business types. For practical purposes, businesses can be grouped into categories such as:

    • Retail: shops selling products directly to consumers.
    • Wholesale: businesses supplying products to other businesses.
    • Manufacturing: businesses producing physical goods.
    • Services: consultants, agencies and professional firms.
    • E-commerce: businesses selling through digital channels.
    • Technology/SaaS: software and technology platforms.
    • Import/export: businesses involved in international trade.

    The type of business often determines which regulatory requirements need to be investigated.

    What Are the 7 Main Points in a Business Plan?

    A practical business plan can include:

    1. Executive summary
    2. Business description
    3. Market analysis
    4. Products or services
    5. Marketing and sales strategy
    6. Operations and management plan
    7. Financial plan

    Founders should include legal and compliance costs in the operations and financial sections. This helps prevent unexpected expenses after launch.

    Frequently Asked Questions About Business Licences

    What are all the licences required to start a business in India?

    There is no universal list. Requirements depend on the business structure, state, location, turnover, employees and industry. Common areas include entity registration, GST where applicable, local registrations and industry-specific licences.

    What are the 10 types of business?

    There is no universal legal list of ten types. Common categories include retail, wholesale, manufacturing, services, e-commerce, technology, professional services, franchising, import/export and subscription businesses.

    What are the three types of licensing?

    There is no universal legal classification of exactly three types. In business discussions, licensing can refer to government or regulatory licences, intellectual-property licensing and commercial licensing arrangements.

    How many types of licences are there?

    There is no fixed number applicable to every Indian business. Licences can be created under central, state and local laws and can vary by industry and activity.

    What is the CC BY 4.0 licence?

    CC BY 4.0 is a Creative Commons licence that generally allows others to share and adapt licensed material, including for commercial purposes, provided they follow the licence conditions and give appropriate attribution.

    Is CC BY 4.0 free for commercial use?

    Generally, yes. CC BY 4.0 permits commercial use, subject to its attribution and other licence conditions. Always check that the material is actually offered under CC BY 4.0 and that third-party rights do not create additional restrictions.

    What are the six types of Creative Commons licences?

    The six main Creative Commons licences are CC BY, CC BY-SA, CC BY-ND, CC BY-NC, CC BY-NC-SA and CC BY-NC-ND. Their differences mainly concern attribution, commercial use and whether adaptations can be shared under the same or modified terms.

    What is the 80/20 rule for startups?

    The 80/20 rule, or Pareto principle, is a business-management concept rather than a startup law. It suggests that a relatively small number of inputs can produce a large share of results. Founders can use it to identify their most valuable customers, products and activities.

    Why do 90% of startups fail?

    The claim that 90% of startups fail should not be treated as a universal Indian statistic. Startup failure varies by industry, dataset and definition. Common risks include poor product-market fit, cash-flow problems, weak unit economics, founder disputes and regulatory failures.

    What business is easiest to start?

    Service businesses can often have lower initial capital requirements than manufacturing or inventory-heavy businesses. However, the easiest business depends on your skills, capital, customers, location and applicable regulations.

    What business has a 90% success rate?

    No general business category can reliably guarantee a 90% success rate. Business success depends on execution, demand, capital, competition, management and many other factors.

    What business will boom in 2026?

    Areas attracting attention include technology-enabled services, AI-related solutions, digital commerce, specialised professional services and businesses supporting India’s expanding digital economy. However, no sector is guaranteed to boom, so founders should validate actual customer demand.

    Who are Gen Z entrepreneurs?

    Gen Z entrepreneurs are founders from Generation Z who build businesses using approaches shaped by digital platforms, social media, online communities and technology. Their businesses can range from creator-led brands to software, e-commerce and professional services.

    How can I earn ₹2 lakh per month in business?

    Start by separating revenue from profit. To earn ₹2 lakh in monthly profit, calculate your expected gross margin, operating costs, customer acquisition costs and required sales volume. Then work backwards to determine how many customers or transactions you need.

    What are the 7 pillars of business?

    A useful seven-pillar framework is strategy, finance, operations, marketing, sales, people and legal/compliance. The exact framework varies, but these areas cover most of the core functions required to build a sustainable business.

    What are the 12 components of a business plan?

    A detailed business plan may include an executive summary, company description, problem and solution, market analysis, customer profile, competitive analysis, business model, marketing strategy, operations, management, financial projections and funding requirements.

    What are the 10 types of business plans?

    Common formats include startup plans, traditional plans, lean plans, strategic plans, operational plans, growth plans, expansion plans, feasibility plans, internal plans and contingency plans. The right format depends on the purpose of the document.

    What are the 7 key elements of a business plan?

    The seven key elements can be summarised as the executive summary, business description, market analysis, product or service strategy, marketing and sales plan, operations and management plan, and financial projections.

    Business Licences Every Startup Needs: Final Checklist

    Before launching, do not ask only whether your company is incorporated. Ask whether the business is legally ready to perform the specific activities it plans to undertake.

    • Choose the right business structure.
    • Complete the applicable business registration.
    • Confirm PAN and TAN requirements.
    • Check GST registration requirements.
    • Evaluate Udyam registration.
    • Check state Shops and Establishments requirements.
    • Check local trade licences.
    • Identify sector-specific licences.
    • Review FSSAI requirements if you operate a food business.
    • Check IEC requirements for import/export activities.
    • Review environmental, fire-safety and Legal Metrology requirements where relevant.
    • Protect your brand with trademark registration.
    • Prepare appropriate contracts and online business documents.
    • Set up a system for ongoing compliance and renewals.

    Get Help With Your Startup Compliance Checklist

    The right legal checklist depends on your business activity, structure, state, location and growth plans. A startup should therefore avoid copying another company’s licence list without checking whether the same rules actually apply.

    Lawizer helps Indian founders with company registration, LLP registration, GST registration, MSME Udyam registration, trademark registration, Startup India registration and ongoing annual compliance.

    If you are unsure which registrations, licences or permits apply to your startup, consult a qualified legal, tax or compliance professional before launching the regulated part of your business. Getting the checklist right early can help you avoid preventable penalties, delays and compliance gaps later.

    Ready to organise your startup’s legal setup? Explore Lawizer’s startup and business legal services and build a compliance checklist based on your actual business model.

  • How to sell trademark in India: A Legal Guide

    How to sell trademark in India: A Legal Guide

    How to sell trademark in India: A Legal Guide

    If you are wondering how to sell trademark rights in India, the process is generally possible through a legal assignment or transmission of the trademark. A trademark can be a valuable business asset, particularly when it has established goodwill, customer recognition and commercial value. However, selling a trademark is not simply a matter of agreeing on a price and handing over a brand name.

    The transaction should be properly documented, the ownership and status of the mark should be checked, and the transfer should be recorded with the Trade Marks Registry where required. The seller should also consider whether the transaction includes the goodwill associated with the business and whether any restrictions apply to the proposed assignment.

    This guide explains the process in practical terms for Indian founders and small-business owners, including trademark valuation, ownership transfer, assignment agreements, non-use risks and the difference between selling and licensing a trademark.

    If you are still building your brand, you can first explore trademark registration in India to understand how trademark ownership is established and protected.

    Can You Sell a Trademark in India?

    Yes. Under Indian trademark law, a registered trademark can generally be assigned or transmitted, subject to the provisions of the Trade Marks Act, 1999. The Act also recognises the assignment or transmission of unregistered trademarks, although the applicable legal requirements and practical considerations may differ.

    In simple terms, an assignment means transferring ownership of the trademark from one party to another. The person transferring the mark is commonly referred to as the assignor, while the person receiving it is the assignee.

    What Does Selling a Trademark Mean?

    When people talk about selling a trademark, they usually mean transferring the ownership rights in the mark for consideration. The transaction may relate to a brand name, logo, word mark or another protected trademark.

    This is different from merely allowing another business to use the mark. A licence generally gives someone permission to use intellectual property while ownership remains with the original owner. An assignment, by contrast, is intended to transfer ownership.

    Can I Sell My Registered Trademark?

    Yes. The registered proprietor has the statutory power to assign a trademark, subject to the applicable provisions of the Act. Section 38 also provides that registered trademarks are assignable and transmissible, subject to the restrictions contained in the relevant chapter of the Act.

    Before entering into a transaction, the seller should verify the registration details, proprietor information, goods or services covered and the current status of the trademark.

    It is also sensible to check whether the mark is involved in an opposition, rectification proceeding, infringement dispute or other legal issue.

    Can I Transfer Ownership of a Trademark?

    Yes. Trademark ownership may be transferred between individuals, companies or other eligible parties, depending on the circumstances of the transaction.

    For example, a founder may transfer a personally owned trademark to a company. A company may transfer a brand to another company as part of a restructuring or business sale. A trademark may also form part of a wider intellectual property transaction.

    The transfer should be supported by appropriate documentation and the change in title should be dealt with through the prescribed procedure.

    How to sell trademark: Step-by-Step Process

    There is no single “sell” button for a trademark. A proper transaction usually involves commercial negotiation, legal documentation and registration-related formalities.

    Step 1: Verify Trademark Ownership and Status

    Start by checking exactly what is being sold. The seller should verify the trademark application or registration number, proprietor details, classes and goods or services covered.

    Also check:

    • Whether the trademark is registered or still pending.
    • Whether the registration is currently in force.
    • Whether renewal requirements have been complied with.
    • Whether there are pending oppositions or rectification proceedings.
    • Whether the trademark is subject to any restrictions or limitations.
    • Whether third parties have any recorded rights or interests.

    If the trademark is approaching renewal, review the applicable requirements before completing the transaction. Lawizer provides a trademark renewal service for businesses that need assistance maintaining their registration.

    Step 2: Determine the Trademark’s Value

    A trademark does not have a fixed resale price simply because it is registered. Its commercial value depends on the strength and economic significance of the brand.

    Factors that may influence value include:

    • Brand recognition and reputation.
    • Revenue generated using the trademark.
    • Customer loyalty and goodwill.
    • Market share and geographic reach.
    • Distinctiveness of the mark.
    • Goods and services covered by the registration.
    • Online presence and domain-name value.
    • Existing licensing or distribution arrangements.
    • Potential for future expansion.
    • Existing disputes or enforcement history.

    Step 3: Negotiate the Assignment

    The parties should agree on the commercial terms before signing the final assignment document.

    Important points may include:

    • Purchase consideration.
    • Payment schedule.
    • Effective date of transfer.
    • Trademark numbers and classes covered.
    • Territory of the transfer.
    • Whether goodwill is included.
    • Existing licences or third-party arrangements.
    • Representations and warranties.
    • Indemnity and liability provisions.
    • Responsibility for government filings and transaction costs.

    The exact terms should reflect the nature of the transaction rather than relying on a generic template.

    Step 4: Execute a Trademark Assignment Agreement

    A written assignment document is central to the transaction. It records what is being transferred, from whom, to whom and on what terms.

    Depending on the transaction, the agreement may identify the trademark, registration number, classes, consideration, effective date, territory and whether the assignment is with or without goodwill.

    Where a more detailed intellectual property transfer document is required, Lawizer also provides IP Assignment Agreement drafting support.

    Step 5: Record the Transfer With the Trade Marks Registry

    Completing the private agreement is not the end of the process. Section 45 of the Trade Marks Act deals with registration of assignments and transmissions. A person who becomes entitled to a registered trademark by assignment or transmission is required to apply in the prescribed manner to have the title registered.

    The Registry process therefore matters because the official record should reflect the new proprietor. The parties should retain the executed assignment documentation and evidence of the filing.

    The exact procedural requirements and forms can depend on the circumstances of the transaction. For this reason, sellers should avoid assuming that every assignment follows exactly the same filing route.

    How to sell trademark at the Right Value

    One of the most difficult parts of a trademark transaction is deciding what the mark is actually worth. Registration alone does not automatically make a trademark commercially valuable.

    What Is a Trademark Worth?

    The value of a trademark depends largely on the economic benefit associated with the brand. A recognised mark with substantial customer goodwill can be worth considerably more than a newly registered mark that has never been commercially used.

    There is no universal government-set resale price for trademarks. The parties generally negotiate consideration based on the commercial value of the asset and the terms of the transaction.

    How Do You Calculate Trademark Value?

    Businesses may use different intellectual property valuation approaches depending on the circumstances.

    • Income approach: Estimates the economic benefit or future income attributable to the trademark.
    • Market approach: Considers comparable transactions, licensing arrangements or market evidence where reliable comparisons are available.
    • Cost approach: Considers the cost associated with developing or replacing the relevant brand asset, although this may not fully capture goodwill.

    For a significant transaction, valuation should be approached carefully and may require advice from appropriate legal, financial or valuation professionals.

    Trademark Value Checklist

    Before negotiating a price, consider:

    • How well known is the brand?
    • How much revenue is generated under the mark?
    • How loyal are its customers?
    • How distinctive is the mark?
    • How broad is its registration?
    • Are there existing licences?
    • Is the mark actively used?
    • Are there disputes involving the mark?
    • Does the brand have expansion potential?

    What Are the Different Types of Trademarks?

    Trademarks can take different forms. The relevant category depends on the nature of the mark and how it is used to distinguish goods or services.

    What Are the Four Types of Trademarks?

    Commonly discussed types include:

    • Word marks: Protection centred on words, names or combinations of letters and numbers.
    • Device or logo marks: Protection for a distinctive graphical representation.
    • Shape marks: Protection may apply to distinctive shapes associated with goods or packaging where legal requirements are satisfied.
    • Sound marks: Certain distinctive sounds may qualify for trademark protection where the statutory requirements are met.

    This is a simplified classification. Indian trademark law can cover a wider range of marks, and registrability depends on the facts.

    What Is the Strongest Type of Trademark?

    There is no single trademark category that is automatically the “strongest”. Legal strength often depends more on distinctiveness, scope of protection, actual use and the ability to enforce the rights than on whether the mark is a word, logo or sound mark.

    In general, distinctive marks are easier to protect than marks that are generic or purely descriptive of the goods or services.

    If you are deciding whether a brand should be protected before building significant goodwill, Lawizer’s trademark registration service can help with the registration process.

    Who Owns a Trademark?

    Trademark ownership should not be confused with who happens to use the brand in day-to-day business. For a registered mark, the register records the proprietor and the registered rights associated with the mark.

    Who Is the Owner of a Trademark?

    The person or entity recorded as the registered proprietor is central to determining registered ownership. The ownership structure may involve an individual, company or, depending on the circumstances, more than one proprietor.

    Before a sale, verify the official record and make sure the person signing the assignment has the necessary authority.

    Can a Trademark Be Sold by Someone Who Is Not the Registered Owner?

    A person should not assume that simply using a brand gives them authority to sell a registered trademark. The seller’s title and authority should be established before the transaction is completed.

    Where a company owns the trademark, the company should act through an appropriately authorised representative and maintain the necessary corporate records.

    What Happens If a Registered Trademark Is Not Used?

    Use of a trademark can become important when assessing its legal position and commercial value. A registration is not necessarily immune from challenge merely because it appears on the register.

    Do You Lose a Trademark If You Don’t Use It?

    Not automatically. However, Indian trademark law provides mechanisms for removal of a registered trademark on grounds of non-use in appropriate circumstances.

    Section 47 of the Trade Marks Act addresses removal from the register on the ground of non-use. Among other things, it deals with situations involving a continuous period of five years from the date the trademark was actually entered in the register, subject to the statutory requirements and exceptions.

    Therefore, “five years of non-use” should not be described as an automatic cancellation rule. A legal proceeding and the applicable statutory conditions matter.

    What Happens If a Registered Trademark Is Not Used for 5 Years?

    Where the statutory conditions are satisfied, an aggrieved person may seek removal of the trademark in relation to the relevant goods or services. Section 47 also recognises circumstances in which non-use may be excused, including certain special circumstances in the trade.

    This makes non-use an important due-diligence issue for a prospective purchaser. A buyer should investigate whether the trademark has actually been used and whether evidence of use and goodwill exists.

    Why Does Trademark Use Matter When Selling a Trademark?

    Actual use can affect both legal risk and commercial value. A buyer may want evidence showing that customers associate the mark with the business and that the brand has genuine commercial goodwill.

    Useful records may include:

    • Invoices and sales records.
    • Product packaging.
    • Advertising and marketing material.
    • Website and social-media records.
    • Distribution documents.
    • Licensing arrangements.
    • Other evidence of genuine commercial use.

    What Is Rule 47 in Trademark Law?

    Rule 47 of the Trade Marks Rules, 2017 should not be confused with Section 47 of the Trade Marks Act, 1999.

    What Is Rule 47 in Trademarks?

    Rule 47 deals with evidence in reply by an opponent in trademark opposition proceedings. It concerns the opportunity for the opponent to file evidence by affidavit in reply after receiving the applicant’s evidence.

    It is therefore not the provision that creates the general five-year non-use rule. The five-year non-use issue discussed above arises under Section 47 of the Trade Marks Act, 1999.

    This distinction is important because “Rule 47” and “Section 47” are sometimes incorrectly treated as referring to the same subject.

    What Are the Disadvantages of Selling a Trademark?

    Selling a trademark can provide an immediate financial return, but the decision can also have long-term consequences.

    Loss of Brand Control

    With a complete assignment, the seller gives up ownership of the transferred trademark. The new owner will generally control the future use of the mark within the scope of the transferred rights.

    Loss of Future Commercial Value

    If the brand has significant growth potential, selling it today may mean giving up future licensing, franchising or expansion opportunities.

    Contractual and Legal Risks

    A poorly drafted assignment can create disputes over consideration, territory, goodwill, existing licences or continuing obligations.

    Clear documentation is therefore important. Lawizer also provides IP assignment agreement drafting and licensing agreement drafting services for businesses dealing with intellectual property rights.

    Tax and Financial Considerations

    The tax treatment of a trademark transaction can depend on the nature of the asset, the seller, the transaction structure, the period of ownership and other facts. Do not assume that the sale price represents the seller’s final post-tax amount.

    For a material transaction, obtain appropriate tax advice before finalising the consideration and transaction structure.

    Selling vs Licensing a Trademark

    Not every founder who wants to monetise a trademark needs to sell it. Licensing can be an alternative when the owner wants another party to use the mark while retaining ownership.

    Factor Assignment Licensing
    Ownership Transfers to the assignee Remains with the owner
    Control Generally moves to the new owner Can be retained through contractual terms
    Payment May involve a one-time sale consideration May involve royalties or licence fees
    Long-term relationship Usually represents a permanent transfer Can be limited by duration and conditions

    If you want to retain ownership while allowing another party to use the intellectual property, a properly drafted licensing agreement may be more appropriate than an outright assignment.

    Documents Required to Sell or Transfer a Trademark

    The exact documentation depends on the transaction, but a seller should generally be prepared with the following:

    • Trademark application or registration details.
    • Details of the current proprietor.
    • Details of the proposed assignee.
    • Trademark assignment deed or agreement.
    • Consideration and payment details.
    • Authority documents where a company is involved.
    • Board resolution or other corporate authorisation, where applicable.
    • Documents required for the relevant Registry filing.
    • Evidence relating to goodwill or commercial use, where relevant.

    Lawizer’s Sell Your Trademark service specifically provides assignment deed support, Registry filing support and ownership-transfer assistance.

    Common Mistakes to Avoid When Selling a Trademark

    • Assuming registration automatically determines commercial value.
    • Failing to verify the registered proprietor.
    • Ignoring pending opposition or disputes.
    • Using an unclear or incomplete assignment agreement.
    • Failing to specify the trademarks and classes being transferred.
    • Ignoring whether goodwill is included.
    • Overlooking existing licences or contractual rights.
    • Failing to address the Registry filing.
    • Ignoring non-use risks.
    • Finalising the price without considering applicable tax and transaction costs.

    Frequently Asked Questions About Selling a Trademark

    Can I sell my registered trademark?

    Yes. A registered trademark can generally be assigned, subject to the Trade Marks Act and applicable restrictions. The transfer should be documented and the new proprietor’s title should be dealt with through the prescribed Registry procedure.

    Can you sell a trademark?

    Yes. Selling a trademark generally means transferring ownership of the trademark to another party in return for agreed consideration.

    Can I transfer ownership of a trademark?

    Yes. Ownership can generally be transferred by assignment or transmission, subject to applicable legal requirements.

    What is a trademark worth?

    There is no universal resale value. The value depends on factors such as goodwill, revenue, recognition, distinctiveness, market position, scope of protection and future commercial potential.

    How do I calculate the value of a trademark?

    Businesses may consider income, market and cost approaches, together with brand-specific factors such as customer recognition, revenue, goodwill and licensing potential.

    What are the disadvantages of selling a trademark?

    The seller loses ownership and future control over the transferred mark. The seller may also give up future licensing or expansion opportunities and must consider contractual, tax and transaction risks.

    Who is the owner of a trademark?

    For a registered trademark, the registered proprietor recorded on the register is central to determining ownership. Before an assignment, the parties should verify the registration record and the authority of the person signing the transaction.

    What happens if a registered trademark is not used for 5 years?

    Five years of continuous non-use can become relevant to a removal proceeding under Section 47 of the Trade Marks Act, subject to the statutory conditions and exceptions. It does not mean that a trademark is automatically cancelled the moment five years pass.

    Do you lose a trademark if you don’t use it?

    Not automatically. However, genuine use is important because Indian law provides grounds for seeking removal of a registered mark for non-use in appropriate circumstances.

    What is Rule 47 in trademarks?

    Rule 47 of the Trade Marks Rules, 2017 concerns evidence in reply by an opponent in opposition proceedings. It should not be confused with Section 47 of the Trade Marks Act, which deals with removal on grounds of non-use.

    What are the four types of trademarks?

    Commonly discussed categories include word marks, device or logo marks, shape marks and sound marks. Indian trademark law can recognise other forms of marks where the statutory requirements are satisfied.

    What is the strongest type of trademark?

    There is no universally strongest type. Distinctiveness, scope of protection, genuine use and enforceability are often more important than the category of the mark itself.

    Conclusion: Is Selling Your Trademark Right for You?

    A trademark can be an important business asset, and Indian law generally permits its assignment or transmission. But a successful transaction involves more than agreeing on a sale price.

    Before transferring the mark, verify ownership, assess its commercial value, review its use and legal status, document the transaction carefully and address the applicable Registry formalities.

    If your objective is to monetise the brand without permanently giving up ownership, licensing may also be worth considering.

    If you want professional assistance with the transaction, you can explore Lawizer’s Sell Your Trademark service for trademark assignment and ownership-transfer support. For businesses that need a customised document, Lawizer also offers IP Assignment Agreement drafting.

    For a significant transaction, particularly one involving substantial goodwill, multiple trademarks, existing licences or tax implications, consider obtaining appropriate legal and tax advice before signing the final agreement.

  • What Is Intellectual Property?

    What Is Intellectual Property?

    What Is Intellectual Property? India Guide

    If you are a founder, creator or small-business owner, you may be wondering what is intellectual property and why it matters to your business. Intellectual property, commonly called IP, refers broadly to creations of the mind and the legal rights that may protect qualifying creations, inventions, brands and creative works.

    Unlike physical property such as a building, vehicle or machine, intellectual property is intangible. However, it can have significant commercial value. A business name, logo, software code, product invention, original content or confidential business method can all represent valuable intellectual assets.

    Understanding intellectual property is therefore important before launching a brand, developing a product, hiring employees or sharing a new invention publicly. The right form of protection depends on the nature of the asset and the legal requirements that apply to it.

    In this guide, we explain the meaning of intellectual property, its major types, practical examples, ownership, protection in India and why IP matters to startups and small businesses.

    What Is Intellectual Property in Simple Terms?

    Intellectual property is a broad term for creations and commercially valuable intangible assets that may receive legal protection. The World Intellectual Property Organization describes IP as creations of the mind, including inventions, artistic works, computer programs, trademarks and other commercial signs.

    In simple terms, think of IP as something your business creates or develops that has value but cannot be physically held.

    For example, a startup might own:

    • A brand name that identifies its products.
    • A logo used on its website and packaging.
    • Original articles, photographs and videos.
    • Software and source code.
    • A qualifying technical invention.
    • A distinctive product design.
    • Confidential business information.

    These assets do not all receive the same type of legal protection. A brand name is generally considered for trademark protection, while original creative expression may receive copyright protection. A qualifying invention may be protected through a patent if it satisfies the applicable requirements.

    This distinction is important because registering one type of IP does not automatically protect every other asset belonging to the business.

    What Is the IP Meaning?

    IP stands for Intellectual Property. The term is used to describe a broad area of law covering different forms of intangible creations and commercial identifiers.

    Intellectual property rights can give their owners certain exclusive or enforceable rights, depending on the type of IP and the applicable law.

    What Is the Definition of Intellectual Property?

    There is no single Indian statute that provides one exhaustive definition covering every form of intellectual property. Instead, different forms of IP are governed by different laws.

    For example, trademarks are governed primarily by the Trade Marks Act, 1999, patents by the Patents Act, 1970, copyright by the Copyright Act, 1957, and industrial designs by the Designs Act, 2000.

    The official IP India website provides access to information on patents, designs, trademarks, geographical indications and copyright.

    What Is Intellectual Property in Business?

    For a business, IP can be an important intangible asset. A company’s intellectual property may help distinguish its products, protect its innovations, preserve its creative work and maintain its competitive advantage.

    For example, a technology startup could have a registered trademark for its brand, copyright in its software and website content, a patent application for a qualifying invention, and confidential information protected through contractual confidentiality obligations.

    This is why founders should identify their IP early rather than waiting until a dispute or funding round forces them to investigate ownership.

    What Are the 7 Types of Intellectual Property?

    There is no single universal list that every jurisdiction or organisation describes as exactly “seven types” of IP. Different classifications group intellectual property differently. For an Indian business, however, the following categories are useful to understand.

    1. Patents

    A patent protects a qualifying invention when the statutory requirements for patentability are satisfied.

    In India, patentability generally involves requirements such as novelty, inventive step and industrial applicability, along with the requirement that the subject matter is not excluded from patent protection.

    Examples may include a new technical product, a qualifying manufacturing process or a technical improvement that meets the requirements of patent law.

    Not every idea, discovery or business concept qualifies for a patent. A founder should assess patentability before publicly disclosing a potentially patentable invention.

    2. Trademarks

    A trademark helps distinguish the goods or services of one business from those of others. It can protect qualifying brand identifiers such as names, logos and certain other distinctive marks.

    For founders, trademark protection is particularly important because a brand can become one of the most recognisable and valuable assets of a business.

    If you are building a new brand, you can explore Lawizer’s Trademark Registration service.

    You can also read Lawizer’s practical guide on how to register a trademark in India.

    3. Copyright

    Copyright protects original expression in qualifying creative works. It can apply to literary, artistic, musical and dramatic works, cinematograph films, sound recordings and computer programmes, subject to the Copyright Act, 1957.

    For businesses, copyright can be relevant to:

    • Website content.
    • Software and source code.
    • Photographs.
    • Illustrations and artwork.
    • Videos.
    • Books and articles.
    • Advertising and creative material.

    Copyright generally arises automatically when an eligible original work is created. Registration is not a prerequisite for copyright to exist, although registration can provide an official record and useful evidence concerning the registered particulars.

    Lawizer also provides a Copyright Registration service for eligible creative works.

    4. Industrial Designs

    Design protection can apply to qualifying visual features of an article, including its shape, configuration, pattern or ornamentation, as recognised under the Designs Act, 2000.

    Design protection focuses on the visual appearance of an article rather than its underlying technical function.

    For example, a business developing a distinctive product shape or visual configuration may need to consider design protection separately from trademark or patent protection.

    5. Geographical Indications

    A geographical indication, or GI, identifies goods associated with a particular geographical territory where a specific quality, reputation or other characteristic is attributable to that origin.

    Indian examples include Darjeeling Tea, Basmati Rice, Kanchipuram silk saree and Kolhapuri chappal. The official IP India GI resources explain the connection between the product and its geographical origin.

    6. Trade Secrets and Confidential Information

    Trade secrets refer broadly to commercially valuable information that is kept confidential and provides an economic advantage.

    Examples can include:

    • Proprietary processes.
    • Manufacturing know-how.
    • Business strategies.
    • Confidential pricing information.
    • Customer or supplier information.
    • Internal technical information.

    Unlike a trademark or patent, a trade secret is generally protected through secrecy and appropriate contractual and organisational measures rather than simply obtaining a registration certificate.

    7. Plant Varieties and Specialised IP Rights

    India also has specialised legislation dealing with plant varieties and related rights. The Protection of Plant Varieties and Farmers’ Rights Act, 2001 provides a separate legal framework for eligible plant varieties and associated rights.

    This category is particularly relevant to agriculture, plant breeding and related industries rather than most ordinary service businesses.

    What Are the 4 Main Types of Intellectual Property?

    When people ask about the four main types of intellectual property, they commonly mean patents, trademarks, copyright and trade secrets. These four categories are especially useful for understanding the intellectual property needs of a typical business.

    IP Type What It Can Protect Example
    Patent Qualifying inventions New technical product
    Trademark Distinctive brand identifiers Brand name or logo
    Copyright Original creative expression Software, article or photograph
    Trade Secret Confidential commercial information Proprietary process

    These categories are not necessarily alternatives. A single business can own several types of intellectual property at the same time.

    Why Are These Four Important for Businesses?

    Imagine an Indian technology startup launching a new product. Different aspects of the same business may require different forms of IP protection.

    • Trademark: The startup’s brand name or logo may be protected as a trademark.
    • Copyright: Its original software, website content or marketing material may qualify for copyright protection.
    • Patent: A new technical invention may be considered for patent protection if it satisfies the applicable legal requirements.
    • Trade Secret: A confidential algorithm, formula or business process may be protected through appropriate confidentiality measures.

    Understanding these differences helps founders choose the appropriate form of protection instead of assuming that one registration protects every asset of the business.

    Protect Your Intellectual Property With Lawizer

    Protecting intellectual property is an important part of building and growing a business. Lawizer can help you with trademark registration, copyright registration, IP assignment, licensing and other legal documentation.

    Protect your intellectual property and strengthen your business with the right legal support.

  • How Startups Raise Funds in India

    How Startups Raise Funds in India

    How startups raise funds in India: A Guide

    Understanding how startups raise funds in India is important for founders who want to build, launch and scale a business without giving away more ownership than necessary. Startup funding can come from several sources, including personal savings, business revenue, friends and family, angel investors, venture capital firms, loans, incubators and government-backed schemes.

    There is no single funding route that works for every startup. A bootstrapped SaaS business may need very different funding from a deep-tech company developing a new product. Your stage, revenue, market opportunity, capital requirement and growth plans should determine the funding method you choose.

    This guide explains the main startup funding options in India, how the fundraising process works, government funding opportunities, founder equity and common reasons startups fail.

    How startups raise funds in India

    Indian startups generally use a combination of equity, debt and non-dilutive funding. The right option depends on how much money the business needs and what it can offer in return.

    1. Bootstrapping

    Bootstrapping means funding the business with the founders’ own savings or money generated by the business. It allows founders to retain greater control because there is no external investor taking equity.

    Bootstrapping can work well when the initial costs are manageable and the business can generate revenue quickly. It can also help founders prove demand before approaching investors.

    The limitation is that growth may be slower. Founders also carry more financial risk because they are using their own resources.

    2. Friends and family funding

    Some startups raise their first external capital from relatives, friends or personal networks. This can be useful at the idea or pre-seed stage when institutional investors may not yet be interested.

    However, informal funding should still be documented properly. The parties should clearly establish whether the money is a loan, equity investment or another arrangement.

    3. Angel investors

    Angel investors are individuals who invest their own money in early-stage businesses. In return, they may receive shares or another agreed investment instrument, depending on the structure of the transaction.

    Angels often evaluate the founding team, market opportunity, product, early traction and potential for growth. Some also provide introductions, mentoring and industry expertise.

    4. Venture capital

    Venture capital is generally aimed at startups that have the potential for substantial growth. VC investors typically invest in exchange for equity and expect the company to scale significantly over time.

    Funding rounds can occur at different stages, such as seed, Series A and later rounds. Each round can affect the founders’ ownership because new shares or other investment instruments may be issued.

    5. Startup and business loans

    Debt funding allows a business to raise money without immediately giving investors ownership of the company. However, loans create repayment obligations and may involve interest, security or other eligibility requirements.

    Debt can be appropriate for a business with predictable cash flow. It may be less suitable for an early-stage startup that has no revenue and cannot comfortably service repayments.

    6. Incubators and accelerators

    Incubators and accelerators can provide funding, mentorship, networking, workspace, technical support and access to investors. Some programmes take equity, while others provide grants or other forms of assistance.

    Founders should check the programme’s eligibility requirements, funding terms, equity conditions and obligations before joining.

    How to raise funds for a startup in India

    Fundraising is not simply about finding someone willing to invest. Investors usually want evidence that the business understands its market, has a credible team and can use capital efficiently.

    Step 1: Calculate how much funding you actually need

    Start by preparing a realistic financial plan. Estimate product development, salaries, technology, marketing, professional fees, office expenses and other operating costs.

    Then determine how much runway the proposed funding would provide. Avoid choosing a fundraising target simply because another startup raised a large amount.

    Step 2: Choose the right funding source

    Ask whether equity, debt, grants or bootstrapping is most appropriate for your stage.

    • Use bootstrapping when initial costs are manageable.
    • Consider angels when you need early-stage capital and strategic support.
    • Consider venture capital when the business has strong scalability potential.
    • Consider debt when cash flows can support repayment.
    • Explore government schemes when your startup meets their eligibility conditions.

    Step 3: Prepare your pitch deck

    A good pitch deck should explain the business clearly. It normally covers the problem, solution, market, business model, competition, traction, team, financial projections and funding requirement.

    Do not exaggerate revenue, market size or customer numbers. Investors conduct due diligence, and inconsistencies can damage trust.

    Step 4: Organise your legal documents

    Legal readiness can become particularly important during investor due diligence. Your company records, ownership information and contracts should match what you present to investors.

    For example, founders should review their startup legal documents and agreements, including founder arrangements, intellectual property assignments and investor documentation.

    If your business has multiple founders, a properly drafted Co-Founder Agreement can clarify roles, ownership, decision-making and exit arrangements.

    Step 5: Keep your cap table accurate

    A cap table records who owns what percentage of the company. It should account for founder shares, previous investments, employee equity arrangements and new securities issued during fundraising.

    A messy cap table can make due diligence harder. It can also create disagreements over valuation and dilution.

    Step 6: Complete due diligence and documentation

    Once an investor shows serious interest, the process may involve commercial, financial and legal due diligence. The parties may negotiate a term sheet before final investment documentation is signed.

    The exact documents depend on the transaction. They can include a share subscription agreement, shareholders’ agreement and corporate approvals.

    How startups raise funds in India through government schemes

    Government support can be useful for eligible startups, but founders should not assume that every government programme is a universal grant.

    One important example is the Startup India Seed Fund Scheme. The official scheme information states that eligible startups can receive up to ₹20 lakh as a grant for proof of concept, prototype development or product trials. It also provides for investment support of up to ₹50 lakh for market entry, commercialisation or scaling through specified instruments, subject to the scheme’s conditions.

    The scheme has specific eligibility requirements. For example, its published criteria include DPIIT recognition and incorporation within the specified period at the time of application. The official scheme page should always be checked for the current application status and applicable rules.

    For current information, founders should consult the official Startup India Seed Fund Scheme FAQ.

    What is a ₹20 lakh grant for startups?

    The ₹20 lakh figure generally refers to the grant component of the Startup India Seed Fund Scheme for eligible startups. It is not a universal ₹20 lakh payment available to every new business.

    The grant is intended for defined early-stage activities such as validation, proof of concept, prototype development and product trials. Eligibility and disbursement conditions apply.

    Therefore, founders should first determine whether their startup qualifies instead of treating the ₹20 lakh amount as guaranteed funding.

    How to get money from the government for a startup

    Government funding can take different forms. Depending on the programme, support may include grants, seed funding, credit support, subsidies or access to incubators.

    A practical process is:

    • Check whether your business meets the relevant definition and eligibility criteria.
    • Consider obtaining DPIIT recognition if your startup qualifies.
    • Identify central and state government programmes relevant to your sector.
    • Prepare your business plan, financial information and supporting documents.
    • Apply through the official portal or designated incubator.
    • Follow the programme’s reporting and utilisation requirements.

    Current DPIIT recognition rules should be checked before applying because eligibility criteria can change. The Startup India portal currently states that eligible recognised startups can include Private Limited Companies, LLPs, registered partnerships and cooperative societies, subject to the applicable conditions.

    Lawizer also provides assistance with Private Limited Company registration and Startup India registration for founders who need help getting their business structure and documentation ready.

    How much equity should founders give investors?

    Equity is one of the most important parts of startup fundraising. Giving away shares means giving investors a portion of future ownership and economic value.

    Is 1% equity in a startup good?

    There is no universal answer. One percent can be valuable in a highly successful company and nearly worthless in a company that never achieves significant value.

    The important question is what the 1% represents in relation to the company’s valuation and the investment being made.

    Founders should also consider future dilution. If the company issues additional shares in later funding rounds, an existing shareholder’s percentage may decrease.

    How much equity should a CEO get in a startup?

    If the CEO is also a founder, their ownership depends on the founders’ contributions, responsibilities, investment, intellectual property and agreed ownership structure.

    If the CEO is hired later, their compensation may instead combine salary, incentives and potentially equity or employee stock options, depending on the company’s structure and applicable rules.

    There is no legally prescribed percentage that every startup CEO must receive.

    Should co-founders be 50/50 or 51/49?

    Neither split is automatically correct. A 50/50 structure can reflect equal contribution, but it may create deadlock if the founders disagree on an important decision.

    A 51/49 structure gives one founder a numerical majority, but that does not automatically solve every governance issue.

    Founders should consider roles, capital contribution, expected workload, decision-making rights, vesting, founder exits and dispute resolution.

    A written Co-Founder Agreement can help document these arrangements before disagreements arise.

    Is having three co-founders too much?

    Three co-founders are not inherently too many. The real question is whether each founder contributes something important to the business.

    Three complementary founders may divide responsibilities effectively. However, three founders can also create disagreements over authority, equity and decision-making.

    The founders should establish clear responsibilities and governance arrangements from the beginning.

    What is the 80/20 rule for startups?

    The 80/20 rule, also called the Pareto principle, is the idea that a relatively small portion of inputs can sometimes produce a large portion of results.

    What does Pareto mean?

    The principle is associated with Italian economist Vilfredo Pareto. The concept became widely used in business to describe situations where results are unevenly distributed.

    The ratio does not have to be exactly 80/20. The important idea is to identify the activities or inputs producing the greatest impact.

    What is the 80/20 rule in business?

    A business might discover that a small group of customers generates a large share of revenue. Another business might find that a few products generate most sales.

    Similarly, a small number of marketing channels may produce most qualified leads.

    How does the 80/20 rule apply to startups?

    Founders can use the principle to identify high-impact activities.

    • Which customers generate the most revenue?
    • Which products have the strongest margins?
    • Which marketing channels produce the best leads?
    • Which tasks directly support growth?
    • Which expenses create little measurable value?

    The objective is not to force every business into an 80/20 ratio. Instead, founders can use their own data to decide where limited resources should go.

    Does the 80/20 rule really work?

    It can be a useful management principle, but it is not a guaranteed mathematical formula. Some businesses may have a very different distribution of results.

    Founders should therefore test the idea against actual customer, revenue and operational data.

    Why do startups fail in India?

    Startup failure is often discussed using simple statistics. However, the frequently repeated claim that 90% of startups fail should not be treated as a universal rule for every startup, sector or period.

    1) Is it true that 90% of startups fail?

    The “90% failure” statement is commonly repeated online, but the exact figure depends on how failure is defined and which companies are included in the dataset.

    A startup shutting down, being acquired, becoming inactive or failing to achieve its original growth target are not necessarily the same event.

    Founders should therefore focus on measurable risks instead of relying on a single failure percentage.

    2) Why do startups fail?

    Common reasons include:

    • Lack of product-market fit.
    • Insufficient customer demand.
    • Poor cash-flow management.
    • Running out of funding before reaching important milestones.
    • Weak pricing or unit economics.
    • Premature expansion.
    • Founder disagreements.
    • Strong competition.
    • Regulatory or compliance problems.
    • Failure to retain customers.

    Funding itself cannot fix a weak business model. A startup can raise substantial capital and still fail if it cannot create sustainable customer demand.

    3) Why do some startups fail after raising funding?

    External funding can increase the amount of money available, but it can also increase spending expectations.

    If a startup hires too quickly, spends heavily on marketing without proven economics or expands before establishing product-market fit, a large funding round can disappear faster than expected.

    Founders should treat every funding round as capital for achieving specific business milestones.

    Legal and compliance preparation before raising funds

    Investors usually want confidence that the company is legally organised and that its records accurately reflect the business.

    1) Choose an appropriate business structure

    Many startups that plan to raise equity investment choose a Private Limited Company because it provides a share-based corporate structure that is familiar to investors.

    However, the right structure depends on the business. Founders should compare the legal, tax and compliance implications before incorporation.

    Lawizer’s comparison of OPC, LLP and Private Limited Company can help founders understand the major differences.

    2) Protect the brand and intellectual property

    Your company name, logo, technology, content and other intellectual property can become valuable business assets.

    Consider protecting the brand through Trademark Registration where appropriate.

    Founders should also ensure that intellectual property created by founders, employees and contractors is properly assigned to the company where required.

    3) Keep tax and GST records organised

    Tax and GST compliance can become part of investor due diligence. Missing filings or inconsistent records may create unnecessary questions during a funding round.

    Where GST registration is applicable, Lawizer provides GST Registration and related compliance support.

    4) Maintain annual corporate compliance

    A company continues to have legal and reporting obligations after incorporation. Annual filings, financial statements, auditor-related requirements and other compliance obligations should be handled on time.

    Lawizer’s Annual Compliance service can help businesses manage recurring corporate compliance requirements.

    Common startup fundraising mistakes to avoid

    1) Raising money without a clear purpose

    Do not raise capital simply because funding is available. Define the milestones the money is expected to achieve.

    2) Giving away too much equity

    Consider valuation, dilution and future funding requirements before accepting an equity investment.

    3) Ignoring founder arrangements

    Verbal agreements between founders can become difficult to enforce or interpret later. Put important arrangements in writing.

    4) Having an inaccurate cap table

    Ownership records should be consistent across corporate records, investment documents and internal records.

    5) Ignoring compliance until the investor arrives

    Trying to repair years of missing filings immediately before a funding round can delay the transaction.

    Lawizer’s guide on why compliance gaps can affect startup funding rounds explains why legal readiness matters during due diligence.

    Frequently Asked Questions About How Startups Raise Funds in India

    1) How do most startups raise money?

    Startups commonly use bootstrapping, friends and family funding, angel investment, venture capital, loans, incubator support and government schemes. The most suitable option depends on the startup’s stage and financial needs.

    2) What is a ₹20 lakh grant for startups?

    The ₹20 lakh figure refers to the grant component available under the Startup India Seed Fund Scheme for eligible purposes such as proof of concept, prototype development and product trials. It is subject to eligibility and scheme conditions.

    3) What is a 20 lakh grant for startups?

    It is generally a reference to the Startup India Seed Fund Scheme’s provision for a grant of up to ₹20 lakh for specified early-stage activities. It should not be treated as an automatic grant for every startup.

    4) How to get money from government for startup?

    Identify a suitable central or state scheme, check eligibility, prepare the required documents and apply through the designated official channel or incubator. DPIIT recognition may be relevant for certain programmes.

    5) Is 1% equity in a start-up good?

    It depends on the company’s valuation, investment amount, growth prospects, investor rights and future dilution. The percentage alone does not determine whether an investment is good.

    6) How much equity should a CEO get in a startup?

    There is no standard percentage. Founder CEOs and professional CEOs may have very different compensation structures. Equity should reflect contribution, responsibilities, ownership arrangements and the company’s future funding plans.

    7) Should co-founders be 50/50 or 51/49?

    Both structures can work. Founders should consider contribution, responsibilities, decision-making, vesting and dispute resolution rather than choosing a percentage simply because it is common.

    8) Is 1% equity in a startup good?

    There is no universal answer. A 1% stake can be significant in a valuable company, but it can also become heavily diluted or have little value if the business does not succeed.

    9) Is 3 co-founders too much?

    No. Three founders can work well when their skills and responsibilities are complementary. The key is to document ownership, roles, authority and exit arrangements clearly.

    10) Is it true that 90% of startups fail?

    The 90% figure is a commonly repeated generalisation. The actual rate depends on the dataset, definition of failure, sector and period being studied.

    11) What is the Pareto rule?

    The Pareto principle suggests that a relatively small portion of inputs may produce a disproportionately large portion of results. It is often called the 80/20 rule.

    12) What is the 80-20 rule in business and how does it apply?

    Businesses can use it to identify customers, products, marketing channels or activities that generate a large share of their results. The exact ratio does not need to be 80/20.

    13) What does Pareto mean?

    Pareto refers to Vilfredo Pareto, whose observations about unequal distributions later became the basis of the Pareto principle used in business and management.

    14) What is the 80/20 rule in Pareto?

    It is the idea that approximately 80% of outcomes may sometimes come from approximately 20% of causes or inputs. It is a practical principle rather than a universal law.

    15) Does the 80/20 rule really work?

    It can help businesses focus on high-impact areas, but the exact distribution varies. Founders should use their own data rather than assuming that every business follows an 80/20 split.

    16) What is the 80/20 rule for startups?

    For startups, it can be used to identify the customers, products, channels and activities that contribute most to revenue or growth. This can help founders allocate limited resources more effectively.

    17) What are the top 10 failed startups in India?

    There is no universally accepted list of the top 10 failed startups. Different sources use different definitions of failure. It is more useful to study failed businesses by looking at factors such as product-market fit, cash flow, competition, execution and governance.

    18) Why do 90% of startups fail in India?

    There is no reliable universal rule that exactly 90% of Indian startups fail. Common causes of failure include weak market demand, poor financial management, excessive spending, founder disputes, competition and regulatory challenges.

    19) What are the richest startups in India?

    Startup wealth can be measured in different ways, including valuation, revenue and founder wealth. These measures are not interchangeable. A company’s valuation can also change significantly between funding rounds.

    Final takeaway: choose the funding that fits your startup

    Learning how startups raise funds in India is only the first step. The more important decision is choosing a funding method that fits your business model, growth stage and ability to manage financial and legal obligations.

    Before approaching investors, make sure your company structure, ownership records, founder agreements, intellectual property documents, tax records and statutory filings are organised.

    Funding should help your startup reach meaningful milestones. It should not become a goal by itself.

    Need help getting your startup funding-ready?

    If you are preparing for your first funding round, Lawizer can help you organise the legal and compliance foundation behind your business.

    Planning to raise funds? Get your legal structure, founder arrangements and compliance records in order before you approach investors. Consult Lawizer for practical startup legal and compliance support.

  • ESOP Guide for Startups: Equity Plans Explained

    ESOP Guide for Startups: Equity Plans Explained


    ESOP Guide for Startups: Equity Plans Explained

    An ESOP guide for startups is useful for founders who want to attract and retain talented employees without relying only on higher salaries. An Employee Stock Option Plan gives eligible employees the right to acquire shares in the company in the future, subject to the terms of the scheme.

    For an Indian startup, however, ESOPs are more than an employee benefit. They involve company law, shareholder dilution, vesting, exercise terms, tax implications and proper documentation. A well-designed plan can align employees with the long-term growth of the business. A poorly structured plan can create confusion about ownership, taxation and exit rights.

    This guide explains how startup ESOPs work, how equity is allocated, how vesting works, what employees should check and what founders should consider before implementing an ESOP scheme.

    ESOP guide for startups explaining employee equity, vesting and taxation in India
    Understanding employee stock options, vesting and equity can help Indian startups structure employee incentives more effectively.

    What Is an ESOP for a Startup?

    An Employee Stock Option Plan, commonly called an ESOP, is a plan under which eligible employees receive an option or right to acquire shares of the company at a future date at a predetermined price, subject to the applicable scheme and legal requirements.

    Under the Companies Act, 2013, an employee stock option is broadly defined as an option given to eligible directors, officers or employees that provides a benefit or right to purchase or subscribe for company shares at a future date at a predetermined price.

    The important point is that receiving an ESOP does not normally mean that an employee immediately owns the underlying shares. The employee first receives an option. That option may become exercisable after the relevant vesting conditions are satisfied.

    ESOP, shares and options: What is the difference?

    • Option: A contractual right to acquire shares in accordance with the ESOP terms.
    • Vesting: The process through which the employee earns the right to exercise vested options.
    • Exercise: The employee uses the vested option and pays the applicable exercise price, subject to the scheme.
    • Shares: After a valid exercise and allotment/transfer process, the employee becomes a shareholder to the extent provided by the applicable documents.

    Why Do Startups Offer Employee Stock Options?

    Startups often compete with established companies for employees. A young business may not have the cash resources to match every large company’s salary package. Equity-based incentives can provide another way to reward employees for contributing to long-term growth.

    Common reasons for creating an ESOP scheme include:

    • Attracting skilled employees.
    • Retaining key employees for longer periods.
    • Aligning employee incentives with company performance.
    • Creating a sense of long-term ownership.
    • Balancing cash compensation with potential future upside.

    Founders should still remember that an ESOP is not a guaranteed substitute for salary. The eventual value of startup equity depends on the company’s performance, valuation, dilution, liquidity and the terms attached to the options.

    How Does an ESOP Work in a Startup Company?

    The basic process can be understood through five stages: creating the pool, granting options, vesting, exercising and eventually holding or selling the shares where a lawful liquidity opportunity exists.

    1. Create the ESOP pool

    The company first determines how many shares may be reserved for employee options. The size should reflect expected hiring, employee seniority, future fundraising and the founders’ desired ownership structure.

    There is no universal ESOP percentage that is correct for every startup. A founder should model the proposed pool against the company’s current cap table and expected future funding rounds.

    2. Grant options to employees

    The company may grant a specified number of options to an eligible employee under the approved scheme. The grant documentation should clearly state relevant terms such as the number of options, exercise price, vesting conditions and applicable exercise period.

    3. Vesting

    Vesting determines when the employee earns the right to exercise the options. A scheme may use a cliff followed by monthly or quarterly vesting, depending on its terms.

    For example, a four-year vesting structure with a one-year cliff is common in startup practice. However, it should not be treated as a mandatory legal formula. The actual terms depend on the company’s ESOP scheme and grant documentation.

    4. Exercise

    Once options become vested and the employee meets the applicable conditions, the employee may exercise them by following the procedure in the ESOP scheme and paying the exercise price.

    The employee should understand the exercise price before accepting an ESOP grant. A large number of options does not automatically mean a valuable grant.

    5. Holding or selling the shares

    After exercise and the relevant corporate process, the employee may hold shares. Selling those shares depends on applicable law, the company’s constitutional documents, shareholder arrangements and whether a genuine liquidity opportunity exists.

    Private startup shares are generally not as liquid as listed shares. An employee should therefore avoid treating an ESOP grant as cash in hand.

    How Much Equity Should a Startup Give Employees?

    There is no single percentage that works for every startup. The right allocation depends on the company’s stage, valuation, existing shareholders, hiring plans, employee role and expected future dilution.

    Is 1% Equity in a Startup Good?

    One percent can be meaningful in one startup and relatively small in another. The percentage should always be examined alongside the company’s total share capital, valuation, ESOP pool and expected dilution.

    An employee evaluating a 1% grant should ask:

    • Is the 1% calculated on a fully diluted basis?
    • How many options does the percentage represent?
    • What is the exercise price?
    • What is the vesting schedule?
    • What happens if the employee leaves?
    • Are there restrictions on transferring the shares?
    • What future fundraising could dilute the holding?

    How Much Equity Should a CEO Get in a Startup?

    CEO equity is highly dependent on whether the CEO is also a founder. A founder-CEO may hold a substantial founding stake, while a professional CEO hired later may receive a smaller equity package combined with salary and other incentives.

    Instead of copying another startup’s percentage, founders should consider responsibility, joining stage, capital contributed, previous experience, expected contribution and future dilution.

    How Much Equity Do Startup Employees Get?

    Employee grants vary widely. Early senior employees may receive larger grants because they join when the company carries greater risk. Later employees may receive smaller grants because the company has progressed further and its valuation may be higher.

    Roles that are critical to the startup’s growth may also receive different grants from general positions. The most important point is to document the grant precisely rather than making informal promises such as “you will get 1% later.”

    ESOP Guide for Startups: Understanding Vesting

    Vesting is one of the most important concepts in an ESOP. It prevents an employee from receiving the full economic benefit of an option grant immediately when the company’s objective is to reward continued service.

    What is a cliff?

    A cliff is an initial period during which no options vest. Once the cliff is completed, a specified portion may vest at once, followed by periodic vesting under the scheme.

    For example, if a scheme uses a four-year vesting period with a one-year cliff, an employee may receive no vested options during the first year and then become entitled to the portion specified in the scheme at the one-year point. The remaining options may vest periodically afterward.

    The exact terms should always be checked in the approved ESOP scheme and individual grant letter.

    ESOP Taxation in India

    Tax is one of the most important parts of any startup equity plan. Employees should understand that ESOP taxation can involve different stages and that the tax treatment depends on the applicable law and circumstances.

    Is ESOP Taxable Under Salary?

    Generally, the taxable value of specified securities or sweat equity received under an ESOP arrangement can be treated as a perquisite under the income-tax rules at the relevant stage of exercise, subject to the applicable provisions.

    For eligible unlisted shares, fair market value may need to be determined using the prescribed valuation rules. Current income-tax rules provide specific mechanisms for determining fair market value, including valuation by a merchant banker in relevant cases.

    Because tax rules can change, employees should verify the calculation applicable for the relevant assessment year rather than relying on an old ESOP calculator or internet example.

    How to Calculate ESOP in Salary

    At a simplified level, the taxable perquisite is generally linked to the fair market value of the security on the relevant date less the amount actually paid by the employee, subject to the applicable provisions and valuation rules.

    For example, suppose an employee exercises options when the relevant fair market value is ₹100 per share and the exercise price is ₹40. The difference of ₹60 per share is the basic economic difference used in the perquisite calculation, subject to the tax rules applicable to that employee and transaction.

    This example is for understanding the concept only. The actual tax calculation can involve specific valuation rules, eligibility conditions and tax treatment.

    What Happens When ESOP Shares Are Sold?

    Taxation may also arise when the employee later sells the shares. At that stage, capital gains rules can become relevant. The applicable treatment depends on factors such as the type of shares, holding period, acquisition cost determined under tax law and the date of sale.

    Employees should therefore keep their grant letter, exercise records, valuation documents, tax statements and sale documentation.

    Do I Need to Declare ESOP in ITR?

    ESOP-related income and capital gains may need to be reported in the appropriate income-tax return, depending on what occurred during the financial year and the taxpayer’s circumstances.

    The Income Tax Department’s current guidance also identifies situations involving unlisted shares and deferred ESOP taxation that affect eligibility for simplified return forms. Therefore, employees should choose the correct ITR form rather than assuming that a salary-only return is always sufficient.

    If your ESOPs involve foreign shares or foreign assets, additional reporting requirements may apply. In such cases, professional tax advice is particularly important.

    Is ESOP Part of CTC?

    There is no universal rule that every ESOP must be treated as a fixed part of CTC in the same way as basic salary or other cash components. Employers may present equity separately or include it in an overall compensation discussion.

    Employees should read the offer letter and ESOP documents carefully. Look beyond the headline CTC and check the number of options, exercise price, vesting schedule and other conditions.

    What Are the Benefits of ESOPs for Startups?

    Attract and retain talent

    Equity can make an early-stage offer more attractive to employees who believe in the company’s long-term potential.

    Align employees with growth

    When employees have an economic interest in the company’s success, the incentive structure can encourage a longer-term perspective.

    Reduce pressure on cash compensation

    ESOPs can complement salary and benefits, particularly when a startup is managing limited cash resources.

    Build an ownership culture

    A properly explained option plan can help employees understand how their work connects with company value.

    What Are the Disadvantages of ESOPs?

    ESOPs are not risk-free. Founders and employees should understand the downside before signing the documents.

    • Dilution: New shares issued on exercise can reduce existing shareholders’ percentage ownership.
    • No guaranteed value: Startup equity may never become liquid or profitable.
    • Tax exposure: Tax can arise at the exercise stage in applicable circumstances, even when the employee has not sold the shares.
    • Administrative complexity: Companies need proper records, approvals and documentation.
    • Employee expectations: Confusion about valuation or future liquidity can create dissatisfaction.

    Is ESOP a Trap?

    An ESOP is not automatically a trap. It becomes risky when employees accept an equity grant without understanding what they are actually receiving.

    When can an ESOP become risky?

    • The exercise price is not properly understood.
    • The company has no realistic liquidity pathway.
    • The employee does not understand vesting or exit conditions.
    • The quoted percentage is not defined on a clear basis.
    • Future funding may cause significant dilution.
    • The tax implications have not been considered.

    How employees can evaluate an ESOP

    Before accepting a grant, ask the company for the relevant ESOP scheme and grant documentation. Review:

    • Number of options.
    • Exercise price.
    • Vesting schedule.
    • Cliff period, if any.
    • Exercise window.
    • What happens after resignation or termination.
    • Transfer restrictions.
    • Potential dilution.
    • Tax implications.

    The percentage alone is not enough to determine whether an ESOP is attractive.

    ESOP Guide for Startups: ESOP vs RSU

    ESOPs and Restricted Stock Units, or RSUs, are both equity-linked compensation tools, but they are not identical.

    Key differences between ESOPs and RSUs

    • ESOP: Generally gives an option or right to acquire shares subject to the plan.
    • RSU: Generally represents a promise to deliver shares or their value after specified vesting conditions are satisfied.
    • Exercise: Options typically involve an exercise process, while RSUs generally do not operate in the same way.
    • Tax: Tax treatment differs and must be assessed under the applicable provisions.

    There is no universal answer to whether ESOP or RSU is better. The appropriate structure depends on the company, employee, tax position, legal framework and liquidity expectations.

    Can a Company Buy Back ESOP Shares?

    A company may have ways to provide liquidity to shareholders, but a buyback is not simply an automatic right created by receiving an ESOP. Any company buyback must comply with the applicable legal requirements and corporate documents.

    Why might a startup provide an ESOP liquidity opportunity?

    • To provide employees with some liquidity.
    • To reward long-term contributors.
    • To support employee retention.
    • To facilitate a structured secondary transaction or exit.

    The exact mechanism can depend on the company’s structure, applicable law, shareholder arrangements and transaction terms. Employees should not assume that every startup will provide a buyback.

    How to Create an ESOP Plan for a Startup in India

    For an Indian company, an ESOP should be treated as a formal corporate and legal process rather than an informal promise to employees.

    Step 1: Decide the objective and pool

    Determine why the company wants an ESOP and how much equity it may need for current and future employees.

    Step 2: Review the company’s capital structure

    Prepare a clear cap table showing founders, investors, existing shareholders and the proposed option pool. Model potential dilution before finalising the pool.

    Founders should also consider related shareholder arrangements. Lawizer’s guide to shareholders’ agreements for startups explains why equity, transfer and governance provisions deserve careful drafting.

    Step 3: Draft the ESOP scheme

    The scheme should address matters such as eligibility, number of options, vesting, exercise price, exercise period, lapse conditions and treatment when an employee leaves.

    Step 4: Obtain the required approvals

    Section 62(1)(b) of the Companies Act, 2013 and the Companies (Share Capital and Debentures) Rules, 2014 contain the principal framework for employee stock options for companies to which those provisions apply. Required corporate approvals and disclosures should be completed according to the applicable rules and the company’s circumstances.

    The MCA framework also provides for maintaining a register of employee stock options. Proper records are therefore an important part of implementation.

    Step 5: Issue grants and maintain records

    Each employee should receive appropriate grant documentation. The company should maintain accurate records of grants, vesting, exercises, lapsed options and resulting shareholding.

    Step 6: Review the plan periodically

    Fundraising, acquisitions, changes in valuation and hiring plans can affect the usefulness of an ESOP pool. Review the plan when the company’s capital structure changes.

    If your business is still being incorporated, Lawizer provides Private Limited Company incorporation and startup legal services that can help founders establish the corporate structure needed for an equity-based growth plan.

    What Are the 7 Stages of a Startup?

    There is no single legally prescribed seven-stage startup lifecycle. However, founders commonly describe startup development through stages such as:

    1. Idea and problem validation.
    2. Product development.
    3. Pre-seed or seed funding.
    4. Early market traction.
    5. Growth and expansion.
    6. Scaling operations.
    7. Maturity, acquisition or another exit pathway.

    The ESOP strategy can change as the company moves through these stages. Early employees may receive larger grants because they take greater business risk. Later grants may be smaller as the company’s valuation and workforce increase.

    Common ESOP Mistakes Startups Should Avoid

    • Making informal equity promises.
    • Creating an option pool without modelling dilution.
    • Failing to explain the exercise price.
    • Ignoring vesting and exit provisions.
    • Not keeping the cap table updated.
    • Failing to maintain statutory and internal records.
    • Ignoring tax consequences for employees.
    • Using an outdated template without checking current law.
    • Promising employees a guaranteed future value.
    • Failing to review the scheme after funding or restructuring.

    Equity documentation should also be coordinated with other startup agreements. Lawizer’s founder’s agreement guide explains why roles, equity, vesting and exit arrangements should be addressed in writing.

    ESOP Guide for Startups: Frequently Asked Questions

    How does ESOP work in a startup company?

    An ESOP gives eligible employees options to acquire company shares subject to the scheme. Options generally vest according to specified conditions and may then be exercised at the applicable exercise price.

    Is ESOP taxable under salary?

    In applicable cases, the benefit arising when specified securities or sweat equity are allotted or transferred under an employee stock option arrangement can be taxed as a salary perquisite. The exact calculation depends on the applicable income-tax provisions and valuation rules.

    Do I lose my ESOP if I get fired?

    It depends on the ESOP scheme and the employee’s grant terms. Unvested options may lapse when employment ends, while vested options may remain exercisable for a specified period or may be subject to other conditions. Always check the termination provisions.

    Do I need to declare ESOP in ITR?

    ESOP-related taxable income, capital gains and applicable foreign-asset information may need to be reported in the appropriate income-tax return. The correct reporting depends on what happened during the financial year and the taxpayer’s circumstances.

    How to calculate ESOP in salary?

    For applicable ESOP taxation, the taxable perquisite generally involves the prescribed fair market value at the relevant exercise point minus the amount paid by the employee, subject to the applicable tax and valuation rules.

    Is ESOP part of CTC?

    It depends on how the employer structures and presents the compensation package. Employees should separately review the ESOP grant, number of options, exercise price and vesting terms instead of relying only on the total CTC figure.

    Is ESOP better than salary?

    Neither is automatically better. Salary provides predictable current income, while ESOPs may provide future upside but also carry risk and liquidity limitations. The right balance depends on the employee and the startup.

    Should cofounders be 50/50 or 51/49?

    There is no universally correct founder split. The allocation should reflect contribution, roles, responsibilities, investment, future commitment and decision-making arrangements. Founders should document the arrangement in a properly drafted agreement.

    Is it true that 90% of startups fail?

    There is no single reliable universal failure percentage that applies to every startup, country, industry and time period. Founders should avoid making equity decisions based on a simplified statistic and instead assess the actual risk of the business.

    Is 30% equity good?

    Thirty percent may be substantial, but the percentage alone does not determine value. The company’s valuation, share count, dilution, vesting, exercise price and exit prospects all matter.

    What is the 80/20 rule for startups?

    The 80/20 rule, or Pareto principle, is a general business idea suggesting that a relatively small number of inputs may produce a large proportion of results. It is not a statutory startup rule and should not be treated as a fixed formula for equity allocation.

    Why do startups fail?

    Startups can fail for many reasons, including weak product-market fit, insufficient capital, poor execution, regulatory issues, ineffective sales, competition and founder or team problems. There is no single cause that applies to every failed startup.

    At what stage do most startups fail?

    Failure can occur at different stages. Early-stage startups may struggle with product-market fit and funding, while later-stage businesses can face scaling, governance or cash-flow problems. Risk changes rather than disappearing as the company grows.

    What are the 10 steps in the startup process?

    A practical startup journey may include identifying a problem, validating the idea, choosing a business structure, incorporating, protecting intellectual property, building the product, finding customers, raising capital, hiring a team and scaling operations. The exact sequence varies by business.

    What are the 5 key elements of a startup?

    Five useful areas to evaluate are the problem, solution, market, team and financial model. Legal structure and compliance should support these areas from the beginning.

    What’s the next stage after startup?

    There is no universally defined stage after “startup.” A successful company may move into growth, scale-up, maturity, acquisition or public-market preparation depending on its business model.

    How many types of startups are there?

    There is no fixed legal classification that limits startups to a particular number of types. Startups may be described as technology, fintech, SaaS, D2C, social-impact, marketplace or other businesses based on their model and industry.

    What are the five pillars of a successful startup?

    A practical framework is a strong problem-solution fit, capable team, sustainable economics, effective execution and sound legal and financial governance. The exact framework can vary between businesses.

    What are the disadvantages of ESOPs?

    Potential disadvantages include dilution, uncertain value, tax exposure, administrative requirements and limited liquidity. Both founders and employees should understand these risks before implementing or accepting an ESOP.

    Which is better, ESOP or RSU?

    Neither is universally better. Options and RSUs have different legal, tax and economic characteristics. The appropriate structure depends on the company, employee, jurisdiction and applicable rules.

    How many ESOPs fail?

    There is no meaningful universal failure rate for ESOPs. An option grant may expire, lapse or become economically unattractive without representing a failure of the ESOP scheme itself.

    Can a company buy back ESOP?

    A company may provide liquidity through a legally compliant buyback or another permitted transaction, but employees should not assume that a buyback is guaranteed. The company’s documents and applicable law must be reviewed.

    Final Thoughts: Should Your Startup Create an ESOP?

    A well-structured ESOP can be a powerful tool for an Indian startup. It can help attract talent, encourage retention and connect employees with the company’s long-term success.

    However, equity should never be treated casually. Founders need to consider the ESOP pool, dilution, vesting, exercise terms, employee exits, taxation, corporate approvals and ongoing records.

    If your startup is planning to introduce employee equity, it is also worth reviewing its wider legal structure. Lawizer can help with startup incorporation and business legal requirements, while its guide to setting up ESOPs for startup employees provides additional context on scheme design, vesting and compliance.

    For founders who are still deciding their structure, Lawizer’s startup registration guide explains the incorporation process and related registrations. You can also explore shareholders’ agreement considerations when your equity structure involves multiple shareholders or investors.

    Need Help Structuring Your Startup’s Equity?

    ESOPs sit at the intersection of corporate law, employee compensation, taxation and shareholder rights. Before issuing options, founders should ensure that the scheme and supporting documents match the company’s structure and current legal requirements.

    Consult Lawizer for practical startup legal and compliance support. You can review the available startup and business legal services from Lawizer and discuss the requirements of your company before implementing an employee equity plan.

    Important: This article provides general educational information and is not a substitute for personalised legal, tax or financial advice. ESOP rules, tax provisions, valuation requirements and corporate compliance can change. Obtain professional advice for your specific transaction.

  • How to Open a Current Account for Business in India :

    How to Open a Current Account for Business in India :

    Featured image alt text: how to open a current account for business in India

    Starting a business involves more than choosing a name and finding customers. A separate bank account helps you manage business income, expenses, vendor payments and customer collections more efficiently. If you are wondering how to open a current account for business in India, the process generally involves choosing the right account, preparing KYC and business documents, completing the bank’s verification process and meeting any applicable account conditions.

    The exact requirements can vary depending on your business structure, the bank you choose and the nature of your transactions. A sole proprietor may have a different document requirement from a private limited company or an LLP. GST registration is also a separate legal requirement and is not automatically compulsory merely because you want to open a current account.

    This guide explains the process in simple terms, including eligibility, documents, GST, minimum balance, charges, large deposits and how to compare business banking options.

    What Is a Business Current Account?

    A current account is a bank account designed primarily for frequent transactions. Businesses commonly use current accounts to receive payments from customers, pay suppliers, manage operating expenses and handle regular business transactions.

    Unlike a typical savings account, a current account is generally designed around transaction convenience rather than earning interest on the account balance. The features, transaction limits and charges depend on the bank and the particular account product.

    Why Do Businesses Need a Current Account?

    A dedicated business account can make financial management much easier. It helps keep business transactions separate from personal spending and creates a clearer record for bookkeeping and tax purposes.

    • Receive payments from customers.
    • Pay suppliers, employees and service providers.
    • Track business income and expenses separately.
    • Manage regular bank transfers and collections.
    • Maintain cleaner financial records for accounting and tax purposes.
    • Access business-focused banking facilities offered by the bank.

    Separating business and personal transactions is particularly useful when the business begins handling a larger number of payments. It can also make it easier for your accountant or tax professional to reconcile business transactions.

    Current Account vs Savings Account

    A savings account is generally intended for personal savings and routine individual transactions. A current account is designed for businesses and other customers who need frequent commercial transactions.

    Before choosing an account, compare the transaction limits, cash-handling charges, minimum balance requirements, digital banking features and other conditions rather than choosing an account only because it has a low opening requirement.

    Who Can Open a Business Current Account?

    Banks may offer current accounts to several types of businesses. The documentation depends largely on the legal structure and the bank’s KYC requirements.

    • Sole proprietorships: The proprietor’s identity must be verified along with documents establishing the business or business activity.
    • Partnership firms: The bank may require the partnership deed, PAN and KYC documents of relevant partners or authorised persons.
    • LLPs: The LLP’s incorporation and constitutional documents, PAN and details of designated partners or authorised signatories may be required.
    • Private limited companies: The company generally provides incorporation and constitutional documents, PAN and authorisation for operating the account.
    • Other eligible organisations: Trusts, societies and other entities may have their own documentation and authorisation requirements.

    If you have not yet formalised your business, consider the structure before opening the account. Lawizer provides guidance on Private Limited Company registration, One Person Company registration and LLP registration.

    How to Open a Current Account for Business in India

    For most founders, the process can be broken into a few practical steps. The bank may request additional information depending on its internal policies and your business profile.

    Step 1: Choose the Right Business Bank Account

    Start by identifying how your business will use the account. A small consultancy with mostly digital payments may have different needs from a retailer that deposits cash regularly.

    Consider:

    • Expected monthly transaction volume.
    • Cash deposits and withdrawals.
    • Online payment requirements.
    • NEFT, RTGS and IMPS facilities.
    • Cheque and collection facilities.
    • Minimum balance requirements.
    • Cash deposit limits and charges.
    • Internet and mobile banking features.
    • Availability of branches or relationship managers.

    Do not select an account solely because the bank advertises it as “free”. Check the complete schedule of charges and account conditions.

    Step 2: Check the Eligibility and Documentation

    The bank will need to establish who owns or controls the business and who is authorised to operate the account. KYC requirements apply to account opening, and additional business information may be requested.

    For a company or LLP, make sure the entity’s legal name is consistent across the documents. For a proprietorship, keep documents showing the proprietor’s identity and the existence or activity of the business ready.

    Step 3: Prepare the Required Documents

    Prepare your PAN, identity and address documents and business registration or activity proofs before submitting the application. The exact list differs between banks and business structures.

    Step 4: Submit the Application

    Many banks allow applications to begin online, while some account types may require additional verification or a branch interaction. Complete the application with accurate information about the business, beneficial owners, authorised signatories and expected account activity.

    Step 5: Complete KYC and Business Verification

    The bank may verify the identity of the relevant individuals, the business address and the nature of the business. It may also ask questions about the expected transaction pattern or source of funds.

    RBI’s KYC framework requires regulated entities to conduct customer due diligence when establishing account relationships. For sole proprietary firms, additional business or activity documents may be required along with the proprietor’s KYC.

    Read the RBI KYC Directions and amendments for the regulatory framework applicable to customer due diligence.

    Step 6: Activate and Start Using the Account

    Once the bank completes its verification and opens the account, follow the bank’s instructions for activation. Set up internet banking, mobile banking, authorised users and transaction controls where applicable.

    Keep the account opening documents and statements safely. They can become important records for accounting, taxation, audits and business compliance.

    Documents Required to Open a Business Current Account

    There is no single document list that applies identically to every business. Banks can request documents according to their KYC policy and the nature of the entity.

    Common Documents

    • PAN of the business or relevant person, as applicable.
    • Identity and address proof of the proprietor, partners, directors or authorised signatories.
    • Business address proof.
    • Business registration or incorporation documents, where applicable.
    • GST registration certificate, where applicable.
    • Partnership deed or LLP agreement, where applicable.
    • Company constitutional documents and account-opening authorisation, where applicable.
    • Photographs or other KYC information requested by the bank.

    Documents for a Sole Proprietorship

    A proprietor normally needs to establish both the identity of the individual and the identity or business activity of the proprietary concern. RBI’s KYC directions specifically provide for customer due diligence of the proprietor and business or activity proof for a sole proprietary firm.

    The accepted documents can vary, so check the bank’s current list before applying. If you need to formalise a sole business, you can also explore Lawizer’s startup and business legal services.

    Documents for an LLP or Company

    An LLP or company generally has its own legal identity. The bank may therefore request incorporation documents, PAN, constitutional documents, registered office information and evidence showing who is authorised to operate the account.

    If you are still deciding between business structures, Lawizer’s guide on Private Limited vs LLP vs Sole Proprietorship can help you compare the main differences.

    For a more detailed document checklist, see Lawizer’s guide on documents required for company registration in India.

    Can I Open a Current Account Without GST?

    Yes, a business may be able to open a current account without GST registration if the business is not otherwise required to register under GST and the bank accepts the available business documents.

    It is important to separate two questions: whether a bank will open the account and whether the business is legally required to register under GST. A current account does not by itself create GST registration liability.

    When Is GST Registration Required?

    GST registration depends on factors such as aggregate turnover, the nature of supplies, the state or territory involved and specific compulsory-registration provisions. Thresholds and exceptions can differ depending on the circumstances.

    For this reason, do not assume that you need GST registration simply because a bank asks whether you have a GSTIN. Conversely, do not assume that GST is unnecessary just because your turnover is currently low.

    The official GST framework contains both threshold-based registration rules and specific cases where registration can become compulsory. You can check the CBIC GST FAQs and the GST registration rules for the applicable provisions.

    If you need help determining whether your business should register, Lawizer provides GST registration support.

    Can a Proprietorship Open a Current Account Without GST?

    A proprietorship does not automatically need GST registration simply to have a business bank account. However, the proprietor must satisfy the bank’s KYC and business-proof requirements.

    Depending on the bank, accepted business proof may include relevant registrations, licences or other documents that establish the name, address and activity of the concern.

    How Much Money Is Required to Open a Current Account?

    There is no single opening amount that applies to every current account in India. Banks offer different products with different opening requirements, minimum balance conditions and fee structures.

    Opening Deposit vs Minimum Balance

    These are two different concepts. An opening deposit is the amount the bank may require when the account is opened. A minimum or average balance condition determines whether you need to maintain a particular balance after opening the account.

    Always check the bank’s latest terms before opening an account. A product with a low opening deposit can still have higher maintenance or transaction charges.

    Are Zero-Balance Business Current Accounts Available?

    Some banks may offer products with low or zero balance requirements, but eligibility and conditions vary. “Zero balance” does not necessarily mean that every banking service is free.

    Check transaction limits, cash handling fees, payment charges and other service fees before deciding.

    Which Bank Is Good to Open a Current Account for Business?

    There is no single bank that is best for every business. The right choice depends on your transaction pattern and the services your business actually uses.

    What Should Small Business Owners Compare?

    • Monthly or quarterly balance requirements.
    • Cash deposit and withdrawal charges.
    • Digital banking facilities.
    • NEFT, RTGS and IMPS charges.
    • Cheque and collection services.
    • Transaction and withdrawal limits.
    • Payment collection and merchant services.
    • Branch and customer support availability.
    • Business loan or credit facilities, if required.

    Which Bank Is Best for Small Business Owners?

    A small business that receives most payments digitally may value strong online banking and payment integrations. A cash-heavy retailer may care more about cash deposit limits, branch access and cash-handling charges.

    Similarly, a growing company may prefer a bank with stronger business credit, collection and payment infrastructure. The best account is therefore the one that fits your actual operating pattern.

    Which Is the Cheapest Business Bank Account?

    The cheapest account is not always the one with the lowest advertised fee. Calculate the likely total cost based on how your business will use the account.

    For example, a business that makes frequent cash deposits should pay close attention to cash-handling charges. A digital-first company should compare online transaction and payment-related charges.

    Can I Deposit ₹50 Lakh in My Current Account?

    A balance of ₹50 lakh is not, by itself, a universal prohibition on holding money in a current account. However, large transactions can attract greater scrutiny, and businesses should be able to explain the source and purpose of funds with proper records.

    What Should You Keep in Mind With Large Deposits?

    • Maintain invoices and supporting business records.
    • Keep the source of funds properly documented.
    • Follow applicable tax and accounting requirements.
    • Be prepared to respond to legitimate bank KYC or transaction-monitoring queries.
    • Do not structure transactions merely to avoid reporting or compliance requirements.

    A bank account is not a substitute for proper accounting. If your business receives substantial amounts, reconcile the transactions with invoices, sales records and accounting entries.

    Is Money in a Current Account Taxable?

    The balance sitting in a bank account is not automatically a separate taxable item simply because it is in a current account. Tax consequences generally depend on the underlying income, transaction and applicable tax rules.

    For example, receiving business revenue into a current account does not mean the entire bank balance is automatically your taxable income. Business expenses, income recognition, applicable deductions and the nature of the transaction all matter.

    Advantages and Disadvantages of a Business Current Account

    Advantages

    • Designed for frequent business transactions.
    • Keeps business and personal finances separate.
    • Supports regular customer and vendor payments.
    • Can provide business-oriented banking services.
    • Makes transaction tracking and reconciliation easier.

    Disadvantages

    • Some accounts require a minimum or average balance.
    • Cash handling and other services may attract charges.
    • Transaction fees can become significant for high-volume businesses.
    • Current accounts are generally not designed primarily for earning interest.
    • Businesses may face additional KYC and verification requirements.

    Current Account or Savings Account: Which Is Better for Business?

    For a business with frequent commercial transactions, a current account is generally more suitable because it is designed around business banking needs.

    A savings account is primarily designed for personal savings and individual banking. Using a personal account for substantial business activity can also make bookkeeping and financial separation more difficult.

    The correct choice should therefore reflect the nature and scale of your transactions, not just the account’s opening balance.

    Current Account Charges You Should Check

    Before opening an account, review the bank’s latest schedule of charges. Fees can vary significantly between account products.

    • Minimum or average balance non-maintenance charges.
    • Cash deposit and withdrawal charges.
    • Cheque book or cheque-related charges.
    • Fund transfer charges, where applicable.
    • Debit card or business card charges.
    • Statement or notification charges.
    • Collection and payment-related charges.
    • Other account-specific service charges.

    Always rely on the bank’s current official tariff rather than an old comparison article because banking charges and account features can change.

    Frequently Asked Questions About Business Current Accounts

    Is GST compulsory for current accounts?

    No. GST registration is not automatically compulsory merely because you want to open a current account. GST liability depends on the applicable registration provisions and the facts of your business. The bank may, however, request a GST certificate if you are registered or if its account-opening requirements call for it.

    Which bank gives a free business account?

    Some banks may advertise accounts with zero or low fees under particular conditions. However, “free” does not necessarily mean every service is free. Compare the complete fee schedule, balance requirements, transaction limits and cash-handling charges.

    Which bank is best for small business owners?

    The best bank depends on the business. Compare the account’s balance requirements, transaction limits, cash deposit facilities, digital banking, payment collection options and customer support before choosing.

    What is the disadvantage of a current account?

    Potential disadvantages include minimum balance requirements, transaction charges, cash-handling fees and other service charges. Current accounts are generally focused on transaction convenience rather than interest on balances.

    Can I open a zero-balance current account for my proprietorship?

    Some banks offer products with low or zero balance requirements, but eligibility and conditions vary. A proprietor should compare the full terms rather than relying only on the zero-balance label.

    Which bank is best for a current account for proprietorship?

    Choose based on your transaction pattern. A cash-heavy proprietor may prioritise branch access and cash deposit facilities, while a digital business may prioritise online banking, payment collection and low digital transaction costs.

    Which current accounts are free?

    There is no universal category of completely free current accounts. Banks may waive certain charges subject to conditions. Review the latest account-specific schedule of charges before opening one.

    How much money do I need to open a current account?

    The required amount varies by bank and account product. Check both the initial funding requirement and the ongoing minimum or average balance condition.

    Which is the easiest current account to open?

    The easiest account is usually one for which your business structure and documentation match the bank’s requirements. Digital application options can make the process more convenient, but KYC and business verification still apply.

    Does a current account charge a monthly fee?

    It depends on the account. Some banks charge account maintenance or service fees, while others may waive particular charges if specified conditions are met. Check the latest tariff before applying.

    Which is better, current or cheque account?

    The term “cheque account” is not a universal Indian banking category equivalent to a current account. If you need frequent business transactions and cheque facilities, compare business current accounts and their specific cheque services.

    How much tax do I pay on ₹30 lakh?

    There is no single tax amount based only on a ₹30 lakh figure in a bank account. The answer depends on what the ₹30 lakh represents, such as business turnover, taxable profit, salary, capital receipt or another transaction.

    The applicable tax also depends on the taxpayer, business structure, deductions, applicable tax regime and the nature of the income. A bank balance should not be treated as the same thing as taxable income.

    For broader tax and return support, explore Lawizer’s ITR and tax services.

    Is money in a current account taxable?

    Keeping money in a current account does not, by itself, create a separate tax merely because the money is in the bank. The tax treatment depends on the underlying source and nature of the income or transaction.

    What are the four types of current accounts?

    There is no single universal four-type classification that applies to every bank in India. Banks may classify current accounts differently based on customer segment, transaction volume, balance requirements and features.

    How much amount can be kept in a current account?

    There is no simple universal balance figure that applies to every current account. The applicable account terms, banking controls and regulatory requirements should be considered. Large transactions should always be supported by proper business records.

    Which type of current account is best?

    The best account depends on your business needs. Compare transaction volume, cash deposits, digital payments, balance requirements, charges, branch access and other services before selecting an account.

    Key Takeaways Before Opening a Business Current Account

    Opening a business bank account is straightforward when your business documents and banking requirements are clear. Before applying, make sure you understand the following:

    • Choose an account based on your expected transaction pattern.
    • Check the bank’s current KYC and document requirements.
    • Do not assume GST registration is automatically required just to open an account.
    • Check minimum or average balance requirements.
    • Compare cash deposit and transaction charges.
    • Keep business and personal transactions separate.
    • Maintain proper invoices and accounting records for significant transactions.

    If you are still setting up the business itself, it may be useful to complete the relevant legal registrations before approaching a bank. Lawizer offers support across business registration and legal services, including incorporation, GST and MSME-related services.

    Need Help Setting Up Your Business?

    A current account is only one part of getting a business ready to operate. Depending on your business, you may also need entity registration, GST registration, MSME registration, tax filing or ongoing compliance support.

    Lawizer helps Indian founders and small-business owners handle these legal and compliance requirements online. You can explore Private Limited Company registration, OPC registration, LLP registration and GST registration based on your needs.

    If you are unsure which registrations or documents apply to your business, speak with a professional before submitting your bank application. Getting the underlying business structure and documentation right can make the banking process much smoother.

    Relevant Lawizer Resources

    Tags: Current Account, Business Current Account, Business Banking, Current Account for Business, GST Registration, Business Registration, Small Business India, Startup Compliance, KYC, Business Finance

  • NDA Explained For Businesses

    NDA Explained For Businesses


    NDA explained for businesses: Types, Red Flags & Risks

    NDA explained for businesses is a topic every founder should understand before sharing sensitive information with an employee, consultant, investor, vendor or business partner. A Non-Disclosure Agreement, commonly called an NDA, is a contract designed to protect confidential information from unauthorised disclosure or misuse.

    For an Indian business, confidential information can include customer lists, pricing models, source code, product plans, financial information, marketing strategies, supplier details and trade secrets. Sharing this information is often necessary to grow a business, but doing so without clear contractual protection can create avoidable risks.

    This guide explains what an NDA does, the main types of NDAs, how long they can last, common NDA red flags, potential risks of signing, and what founders should check before accepting one.


    NDA explained for businesses: What is an NDA?

    NDA stands for Non-Disclosure Agreement. It is a contract under which one or more parties agree to protect specified confidential information and use it only for an agreed purpose.

    For example, imagine that a startup wants to hire a software developer to work on an unreleased application. The developer may need access to source code, product specifications, customer information and business plans. An NDA can establish contractual obligations regarding how that information must be handled.

    Similarly, a founder negotiating with an investor or potential business partner may need to disclose financial projections, technology details or commercial plans. An NDA can define what information is confidential and what the recipient can and cannot do with it.

    Indian contract law provides the broader legal framework within which contractual obligations operate. The Indian Contract Act, 1872 contains provisions concerning valid contracts, lawful objects, restraint of trade and consequences of breach.

    What does an NDA protect?

    An NDA may protect different categories of information depending on how the agreement is drafted. Common examples include:

    • Business plans and growth strategies
    • Customer and supplier information
    • Pricing and commercial information
    • Financial records and projections
    • Source code and technical documentation
    • Product designs and prototypes
    • Marketing strategies
    • Manufacturing processes and know-how
    • Unreleased intellectual property
    • Trade secrets and other proprietary information

    The agreement should not simply say that “everything” is confidential without providing useful boundaries. A clear definition makes it easier for both parties to understand their obligations.

    When should a business use an NDA?

    An NDA can be useful whenever confidential information must be shared with someone outside the business or with people whose access needs contractual controls.

    • Before discussing a startup idea with a potential partner
    • When hiring employees or senior executives
    • When engaging consultants and freelancers
    • Before sharing information with manufacturers or vendors
    • During joint venture discussions
    • During investment or acquisition negotiations
    • When outsourcing software development
    • When sharing proprietary processes with another business

    Lawizer also provides a Non-Disclosure Agreement service along with other business documentation options for founders who need formal agreements.

    NDA explained for businesses: What are the three types?

    NDAs are commonly divided into unilateral, mutual or bilateral, and multilateral agreements. The correct structure depends on who will disclose confidential information.

    1. Unilateral or one-way NDA

    A unilateral NDA is used when primarily one party discloses confidential information and the other party receives it.

    For example, a startup may provide confidential information to a freelancer. The startup is the disclosing party, while the freelancer is the receiving party.

    Common situations include:

    • Employer and employee relationships
    • Startup and consultant relationships
    • Company and freelancer relationships
    • Business and vendor discussions
    • Founder and prospective investor discussions

    2. Mutual or bilateral NDA

    A mutual NDA applies when both parties expect to exchange confidential information.

    For example, two companies considering a strategic partnership may each need to disclose sensitive commercial information. A mutual NDA gives both parties confidentiality obligations.

    This structure is common in partnership negotiations, joint ventures, mergers, acquisitions and other commercial discussions.

    3. Multilateral NDA

    A multilateral NDA involves three or more parties. It can be useful when several businesses or individuals participate in the same confidential project.

    For example, a company, investor and external consultant may all exchange confidential information. Instead of relying on several separate agreements, the parties may use a multilateral NDA that clearly defines each party’s obligations.

    Are there two types or three types of NDAs?

    You may see sources describing only two main types: unilateral and mutual. Others add multilateral agreements as a third category.

    Both descriptions can be useful. The important point for a business owner is not the label but the actual obligations in the agreement. Always check who must keep information confidential, what information is covered and who can receive it.

    How long do NDAs usually last?

    There is no single universal NDA duration that applies to every business agreement. The period depends on the wording of the contract, the nature of the information and the commercial circumstances.

    Some NDAs contain a fixed confidentiality period. Others provide different treatment for different categories of information. For example, ordinary business information may be protected for a defined period, while information that remains a genuine trade secret may require continuing protection, subject to applicable law.

    What determines NDA duration?

    • The type of confidential information
    • How quickly the information becomes outdated
    • The purpose of the business relationship
    • The length of the project
    • Whether confidentiality obligations survive termination
    • The wording and enforceability of the agreement

    Founders should therefore avoid assuming that every NDA lasts for a particular number of years. Read the confidentiality period and any survival clause carefully.

    Can an NDA last indefinitely?

    An NDA can contain continuing confidentiality obligations, but an indefinite obligation should not automatically be treated as appropriate for every category of information.

    The more important question is whether the restriction is appropriately connected to the legitimate interest being protected. A clause covering genuine trade secrets may need different treatment from a clause covering information that becomes public or commercially irrelevant after a short period.

    If you are unsure whether the duration is appropriate, consider getting the agreement reviewed before signing it.

    What are the red flags in an NDA?

    One of the most important parts of NDA explained for businesses is learning how to recognise provisions that deserve closer review.

    1. An extremely broad definition of confidential information

    A definition that covers practically everything the recipient sees or hears may create uncertainty. The agreement should make it reasonably clear what information is protected.

    2. An unnecessarily long confidentiality period

    A long confidentiality period is not automatically invalid or unfair. However, founders should ask why such a period is necessary and whether it matches the information being protected.

    3. Excessive financial consequences

    Pay particular attention to clauses that specify large sums or penalties for breach. Under Section 74 of the Indian Contract Act, where a contract stipulates a sum or penalty for breach, the party complaining of the breach may be entitled to reasonable compensation subject to the statutory limits. The exact outcome depends on the agreement and circumstances.

    See the official text of Section 74 of the Indian Contract Act for the statutory provision.

    4. One-sided obligations

    If both parties exchange confidential information but only one party has meaningful protection, the agreement may deserve negotiation.

    5. Hidden restrictions on competition

    An NDA should protect confidential information. It should not automatically be treated as a general agreement preventing someone from carrying on a profession or business.

    Section 27 of the Indian Contract Act addresses agreements in restraint of trade. The official Indian Contract Act text should be consulted for the statutory wording and applicable exceptions.

    6. Unclear permitted use

    The recipient should understand why the information is being shared and what they are allowed to do with it. An NDA that prohibits practically every use may be difficult to comply with.

    7. Missing confidentiality exceptions

    Many well-drafted agreements address information that is already public, was already known to the recipient, is independently developed, or must be disclosed because of law or a legal requirement.

    8. Unclear return or destruction obligations

    Check what happens to documents, files, copies and other materials when the relationship ends. Digital information can make these clauses particularly important.

    9. Unfavourable dispute provisions

    Review the governing law, jurisdiction and dispute-resolution provisions. This becomes especially important when the parties operate in different states or countries.

    What are the main red flags in an NDA?

    For a quick review, founders can use the following NDA checklist:

    • Broad or vague confidentiality definitions
    • Unclear confidentiality duration
    • Disproportionate financial exposure
    • One-sided obligations
    • Restrictions that go beyond confidentiality
    • No clear exceptions
    • Unclear permitted use of information
    • Unreasonable return or destruction requirements
    • Unfavourable dispute-resolution terms
    • Clauses that are difficult to follow in day-to-day business operations

    A red flag does not necessarily mean that the entire NDA is invalid. It means that the clause deserves closer attention before you agree to it.

    Is signing an NDA risky?

    Signing an NDA is not inherently risky. A clear and proportionate NDA can actually reduce business risk by setting expectations before confidential information is exchanged.

    The risk arises when you agree to obligations that you do not fully understand or cannot realistically comply with.

    When is signing an NDA generally reasonable?

    • The confidential information is clearly identified.
    • The purpose of disclosure is clear.
    • The duration is understandable.
    • Standard exclusions are included.
    • The permitted recipients are clear.
    • The remedies are proportionate and legally appropriate.

    When should you be more cautious?

    Take additional care if the NDA contains unusually broad restrictions, substantial financial exposure, unclear obligations or provisions that appear to restrict your future work beyond protecting confidential information.

    Founders should also remember that an NDA is not a substitute for other intellectual-property protections. Depending on the asset, you may also need trademark protection, copyright protection, IP assignment clauses or other contractual safeguards.

    What voids an NDA?

    The question “what voids an NDA?” needs a careful answer. A problematic clause does not automatically mean that the entire agreement disappears.

    Contractual validity and enforceability depend on the facts, wording and applicable law. The Indian Contract Act contains provisions dealing with lawful objects, free consent, uncertainty and agreements that are void in specified circumstances.

    For example, Section 29 deals with agreements that are void for uncertainty, while Section 27 deals with restraint of trade. These provisions should not be used to assume that every imperfect NDA is automatically void.

    Can one problematic clause affect the whole NDA?

    Not necessarily. Some contracts contain severability provisions designed to separate an unenforceable provision from the remaining agreement. The effect depends on the wording and applicable law.

    For a specific agreement, professional legal review is preferable to relying on a general assumption about validity.

    Can you be sued for breaking an NDA?

    Yes, a party may face contractual proceedings after an alleged NDA breach. The precise remedy depends on the agreement, facts and applicable law.

    Section 73 of the Indian Contract Act provides for compensation for loss or damage caused by breach of contract, subject to the requirements stated in the provision.

    The official Section 73 text explains the statutory approach to compensation for contractual breach.

    What might happen after an alleged breach?

    • The parties may attempt to resolve the dispute commercially.
    • A legal notice may be issued.
    • The affected party may seek appropriate legal relief.
    • A claim for compensation may be made where legally available.
    • The dispute may proceed through the mechanism specified in the agreement.

    This is why businesses should maintain reasonable controls over confidential information and limit access to people who genuinely need it.

    What is a 3-way NDA called?

    A three-party NDA is commonly described as a multilateral NDA or three-party NDA.

    It is useful when three parties need to exchange confidential information for the same commercial purpose. The document should identify each party and explain how information shared by one party must be treated by the others.

    For example, a startup may work with an investor and an external technical consultant. A multilateral agreement can establish confidentiality obligations across the relationship.

    Can I tell my wife about an NDA?

    Being married to someone does not automatically mean that you are permitted to disclose confidential business information to that person.

    If the NDA limits disclosure to authorised representatives, employees, professional advisers or other specified recipients, a spouse may not fall within those categories.

    Before sharing confidential information with a family member, check the agreement’s permitted-disclosure provisions. If the agreement does not permit the disclosure, obtaining consent from the relevant party may be safer than assuming that personal relationships create an exception.

    What is a PIA vs NDA?

    PIA and NDA are not generally interchangeable terms.

    If PIA refers to a Privacy Impact Assessment, it is normally a process used to identify and assess privacy risks associated with handling personal information. An NDA, by contrast, is a contractual confidentiality mechanism.

    A business may need both depending on its activities. For example, a company processing personal information may assess privacy risks while also using contractual confidentiality provisions with employees or service providers.

    How to review an NDA before signing

    Before signing, founders should read the document systematically rather than focusing only on the confidentiality heading.

    Step 1: Check the parties

    Confirm that the legal names of the individuals or entities are correct. If a company is signing, ensure that the person signing has appropriate authority.

    Step 2: Identify confidential information

    Look for a clear definition. Ask whether it covers the information you actually expect to share.

    Step 3: Check the permitted purpose

    Make sure the recipient can use the information for the commercial purpose for which it was provided.

    Step 4: Check exclusions

    Look for provisions dealing with public information, previously known information, independently developed information and legally required disclosures.

    Step 5: Review the duration

    Check when confidentiality begins, how long it continues and whether obligations survive termination.

    Step 6: Review liability and remedies

    Look carefully at damages, indemnity provisions, injunction-related language and any specified amounts payable after breach.

    Step 7: Check return and destruction requirements

    Understand what must happen to documents and electronic information after the relationship ends.

    Step 8: Review dispute resolution

    Check the governing law, jurisdiction, arbitration provisions and other dispute mechanisms.

    If the document is complex, Lawizer’s business documentation services can be relevant when you need a professionally prepared agreement rather than relying blindly on a generic template.

    NDA best practices for Indian businesses

    A good confidentiality strategy involves more than signing an NDA. Businesses should also control how information is created, stored and shared.

    • Use written confidentiality terms before sharing sensitive information where appropriate.
    • Define confidential information clearly.
    • Share only the information necessary for the specific purpose.
    • Limit access to employees and contractors who need it.
    • Use appropriate access controls for digital information.
    • Keep records of important confidential disclosures.
    • Review employee and consultant agreements for confidentiality obligations.
    • Use separate IP agreements where ownership of work product needs to be addressed.
    • Review cross-border agreements carefully.
    • Seek legal advice for high-value transactions or unusually restrictive terms.

    For businesses that are still establishing their legal foundation, Lawizer also provides business registration support, Private Limited Company registration, Startup India registration, GST registration and MSME/Udyam registration.

    Once a company is operating, founders can also consider appropriate annual compliance support so that contractual protection is part of a broader compliance framework.

    NDA explained for businesses:

    Frequently Asked Questions:

    1) What are red flags in an NDA?

    Common red flags include vague confidentiality definitions, excessive duration, disproportionate liability, one-sided obligations, unclear permitted use, unusual restrictions and unfavourable dispute provisions. A red flag means the clause deserves review; it does not automatically mean the entire NDA is invalid.

    2) How long do NDAs usually last?

    There is no universal duration. The period depends on the agreement and the information being protected. Some agreements use a fixed period, while certain confidential information may require continuing protection. Always check the duration and survival provisions.

    3) What are the main red flags in an NDA?

    Look for broad definitions, excessive financial exposure, unclear obligations, restrictions beyond confidentiality, missing exceptions and difficult return or destruction requirements. Also check governing law and dispute-resolution clauses.

    4) What are the three types of NDA?

    The commonly discussed structures are unilateral, mutual or bilateral, and multilateral. A unilateral NDA primarily protects information disclosed by one party. A mutual NDA protects information exchanged by both parties. A multilateral NDA involves three or more parties.

    5) Can I tell my wife about an NDA?

    Not automatically. Whether you can disclose information to a spouse depends on the NDA’s permitted-disclosure provisions and the nature of the information. If a spouse is not an authorised recipient, sharing confidential information may create a contractual issue.

    6) What are the two types of NDAs?

    Many business resources describe the two principal NDA structures as unilateral and mutual. A multilateral NDA can be treated as a third structure when three or more parties participate in the confidential relationship.

    7) What are common NDA red flags?

    Common concerns include vague definitions, indefinite obligations without justification, excessive penalties, broad non-compete language, unclear exceptions and provisions that are difficult to follow in normal business operations.

    8) What is a 3-way NDA called?

    A three-party NDA is commonly called a multilateral NDA or three-party NDA. It establishes confidentiality obligations among three parties that need to exchange sensitive information for a shared purpose.

    9) What is a PIA vs NDA?

    A Privacy Impact Assessment is generally a risk-assessment process relating to privacy and personal information. An NDA is a contractual agreement concerning confidentiality. They address different purposes and may sometimes be used together.

    10) Is signing an NDA risky?

    Signing an NDA is not inherently risky. The risk depends on the terms. Pay particular attention to the definition of confidential information, duration, permitted use, liability, remedies and restrictions that may go beyond legitimate confidentiality protection.

    11) What voids an NDA?

    An NDA may be affected by issues such as unlawful terms, uncertainty, problems with consent or other defects recognised by applicable contract law. However, one problematic clause does not necessarily make the entire agreement void.

    12) Can I be sued for breaking an NDA?

    A breach can potentially lead to contractual proceedings and claims for legally available remedies. The consequences depend on the agreement, evidence, applicable law and circumstances. Section 73 of the Indian Contract Act addresses compensation for loss or damage caused by contractual breach.

    13) How long can an NDA last?

    The duration depends on the contract and the nature of the confidential information. Instead of relying on a standard number of years, review the actual confidentiality period and any provisions that continue after the business relationship ends.

    Conclusion: Protect confidential information carefully

    NDA explained for businesses is ultimately about understanding what you are agreeing to protect, how you can use confidential information and what happens if the agreement is breached.

    A well-drafted NDA can help founders share information more confidently with employees, consultants, investors, vendors and business partners. However, an NDA should be specific enough to be understood and proportionate to the legitimate business interest being protected.

    Before signing, check the definition of confidential information, permitted use, exclusions, duration, liability, remedies, return obligations and dispute-resolution terms.

    For startups and growing businesses, confidentiality should also work alongside appropriate intellectual-property protection, business contracts and ongoing compliance.

    Need help preparing or reviewing a business NDA? Lawizer provides legal documentation and business compliance support for Indian founders. You can explore the business documentation services or speak with the Lawizer team about your specific requirements.

    Important: This article provides general legal information for educational purposes. The enforceability of an NDA depends on its wording, the parties, the facts and applicable law. For a specific agreement or dispute, obtain professional legal advice before taking action.

  • Why Startups Should Trademark Early

    Why Startups Should Trademark Early

    Building a startup involves hundreds of decisions, from choosing a business structure to developing a product and finding customers. One decision that is often postponed is brand protection. Understanding why startups should trademark early matters because a brand name can become one of the most valuable assets a young business builds.

    A founder may spend months developing a name, designing a logo, buying a domain, creating social-media profiles and investing in advertising. But registering a company name or securing a domain does not automatically provide comprehensive trademark protection. If a similar mark already exists, or another party files a conflicting application, changing the brand later can become expensive and disruptive.

    This guide explains the practical reasons to consider trademark protection early, how trademark registration works in India, what it does and does not protect, and the common questions founders ask before filing.

    What Does a Trademark Protect for a Startup?

    A trademark is a sign capable of distinguishing the goods or services of one person from those of others. Depending on the circumstances, this can include a brand name, logo, slogan, letters, numbers, shapes and other distinctive elements.

    For a startup, the important point is that trademark protection is connected to the mark and the goods or services covered by the application or registration. Registration does not give a business ownership of an ordinary word in every possible context.

    For example, two businesses may potentially use similar words in unrelated fields where there is no relevant likelihood of confusion and no other legal bar. The analysis depends on the marks, goods or services and the surrounding facts.

    Founders can learn more about the process through Lawizer’s guide to registering a trademark in India.

    Why Startups Should Trademark Early: 7 Key Reasons

    1. Protect the Brand Before You Invest Heavily in It

    The earlier a startup begins thinking about trademark protection, the easier it is to identify a potential problem before large amounts of money are committed to the brand.

    Imagine launching a product after spending heavily on packaging, advertising and influencer campaigns, only to discover that another business has an earlier conflicting trademark. The business may then have to consider changing its name or defending a dispute.
    A trademark search before substantial investment gives founders an opportunity to assess whether the proposed name is commercially and legally sensible.

    2. Reduce the Risk of an Expensive Rebrand

    Rebranding is more than changing a logo on a website. An established startup may need to replace packaging, signage, advertisements, domain assets, sales material and social-media branding.

    There can also be an intangible cost. Customers may already associate the original name with the business. Changing that identity can create confusion and require additional marketing to rebuild recognition.

    Early clearance and filing do not guarantee that a mark will be registered, but they can help founders identify risks while changing course is still relatively manageable.

    3. Reduce the Risk of a Competing Trademark Application

    The filing date of a trademark application can be strategically important. However, founders should not reduce Indian trademark law to the simple statement that “whoever files first always wins.” Prior use and other provisions of the Trade Marks Act can affect the legal position.

    What early filing does provide is a formal application record and an important date in the trademark process. It can therefore be sensible to address brand protection once the founder has finalised a distinctive name and completed appropriate clearance.

    Section 11 of the Trade Marks Act, 1999 is particularly relevant where an applied-for mark conflicts with an earlier mark and there is a likelihood of confusion. This is one reason why searching before filing is so important.

    4. Turn the Brand Into a Recognisable Business Asset

    A successful brand can acquire goodwill and commercial value over time. A registered trademark can form part of the intellectual property portfolio of the business.

    Depending on the business model, trademarks can also become relevant to licensing, franchising, assignment and other commercial arrangements.

    For startups preparing for expansion, it is useful to think about intellectual property as part of the company’s overall asset base rather than as paperwork that only becomes relevant after the business becomes large.

    If multiple founders are involved, an IP Assignment Agreement can help clarify ownership of intellectual property created by founders, employees or contractors.

    5. Support Investor and Due-Diligence Readiness

    Investors, lenders, acquirers and strategic partners may conduct legal due diligence before entering a significant transaction. Intellectual-property ownership can be one part of that review.

    If a startup has a valuable brand but unclear ownership, unresolved conflicts or no organised record of its IP, those issues may need to be addressed during due diligence.

    Trademark registration is not a substitute for good corporate records, founder agreements or IP assignment documents. It is one component of a broader legal foundation.

    6. Strengthen Your Position Against Brand Misuse

    A registered trademark can provide important statutory rights against qualifying infringing uses. Section 29 of the Trade Marks Act deals with infringement of registered trademarks, subject to the conditions and exceptions provided by law.

    This does not mean registration automatically resolves every dispute. Trademark disputes can involve questions about similarity, goods or services, prior use, reputation, honest concurrent use and other facts.
    Still, registration can give a business a clearer legal position than relying entirely on unregistered rights and a passing-off action.

    7. Prepare for Expansion Into New Products and Markets

    Startups rarely remain exactly the same as they were on day one. A software company may add consulting services. A D2C brand may introduce new product categories. A local business may expand nationally or internationally.

    Trademark protection is tied to the goods and services covered. Founders should therefore think about the business’s realistic growth plans when deciding which classes and marks to consider.

    The goal is not to register every imaginable class. It is to build a sensible trademark strategy around the business you actually operate and the expansion you genuinely expect.

    When Should a Startup Trademark Its Brand?

    There is no universal date that applies to every startup. A practical point to consider trademark protection is when the founder has substantially finalised the brand and before significant expenditure has been made on building it.

    This may be before launch, particularly where the name is already finalised. A business can consider trademark registration separately from incorporation; Section 18 of the Trade Marks Act allows a person claiming to be the proprietor of a mark used or proposed to be used to apply for registration.

    That means a founder does not necessarily have to wait until a private limited company is incorporated before considering trademark protection.

    However, the applicant and eventual business structure should be planned carefully. If the brand will ultimately belong to a company, founders should consider ownership and IP assignment issues rather than casually filing everything in an individual’s name.

    Trademark Name, Logo or Both?

    A startup may have several brand elements worth protecting. The most important may be the word or name itself, while a logo may have separate commercial value.

    A word mark can be particularly important where the name is the core brand identity. A device or logo mark can protect the particular visual representation, subject to the scope of registration.

    Whether a startup should file one mark or multiple marks depends on its brand strategy, budget and the importance of each element. Founders should avoid assuming that one registration automatically gives comprehensive protection over every variation of a brand.

    Company Registration Is Not the Same as Trademark Registration

    One of the most common misconceptions among new founders is that registering a company name protects the brand.

    It does not. Company registration and trademark registration serve different purposes. A company name identifies the legal entity, while a trademark distinguishes goods or services in the marketplace.

    For example, a founder might incorporate a company under a particular name and separately operate a consumer-facing brand under another name. The company’s incorporation does not automatically create comprehensive trademark rights over that consumer brand.

    If you are still deciding on your business structure, Lawizer provides Private Limited Company registration and LLP registration services.

    What Happens If You Do Not Trademark Early?

    Not registering immediately does not mean that every legal right disappears. Indian law recognises certain rights arising from prior use, and an unregistered mark may in appropriate circumstances be protected through passing-off principles.

    But relying on unregistered rights can make a dispute more complicated because the business may need to establish facts such as goodwill, reputation, misrepresentation and damage.

    By contrast, a registered trademark can provide statutory rights against infringement, subject to the Act and the facts of the case.

    The biggest practical problem is often not the lawsuit itself. It is discovering the conflict after the startup has already invested heavily in the brand.

    How to Register a Trademark for a Startup in India

    Step 1: Choose a Distinctive Mark

    Start with the brand you actually want to build. A distinctive mark is generally easier to protect than a generic or purely descriptive expression.

    Before committing to a name, consider pronunciation, spelling, meaning, existing brands and the markets in which you expect to operate.
    Step 2: Conduct a Trademark Search

    Search the official trademark records before filing. Do not search only for an identical spelling.

    A sensible preliminary search should also consider:

    • Phonetically similar names.
    • Similar spellings.
    • Visually similar marks.
    • Existing applications as well as registrations.
    • Relevant and closely related goods or services.

    The official IP India trademark system provides government infrastructure for trademark applications and searches.

    Lawizer also explains this process in its article on how to protect your brand name in India.

    Step 3: Identify the Correct Trademark Class

    India uses the Nice Classification system for goods and services. There are 45 classes, with Classes 1–34 generally covering goods and Classes 35–45 covering services.

    The correct class depends on what your business actually offers. A software company and a clothing brand will generally have different classification considerations.

    Choosing classes simply because another business used them can be a mistake. The specification should reflect the applicant’s real goods or services and the intended scope of protection.
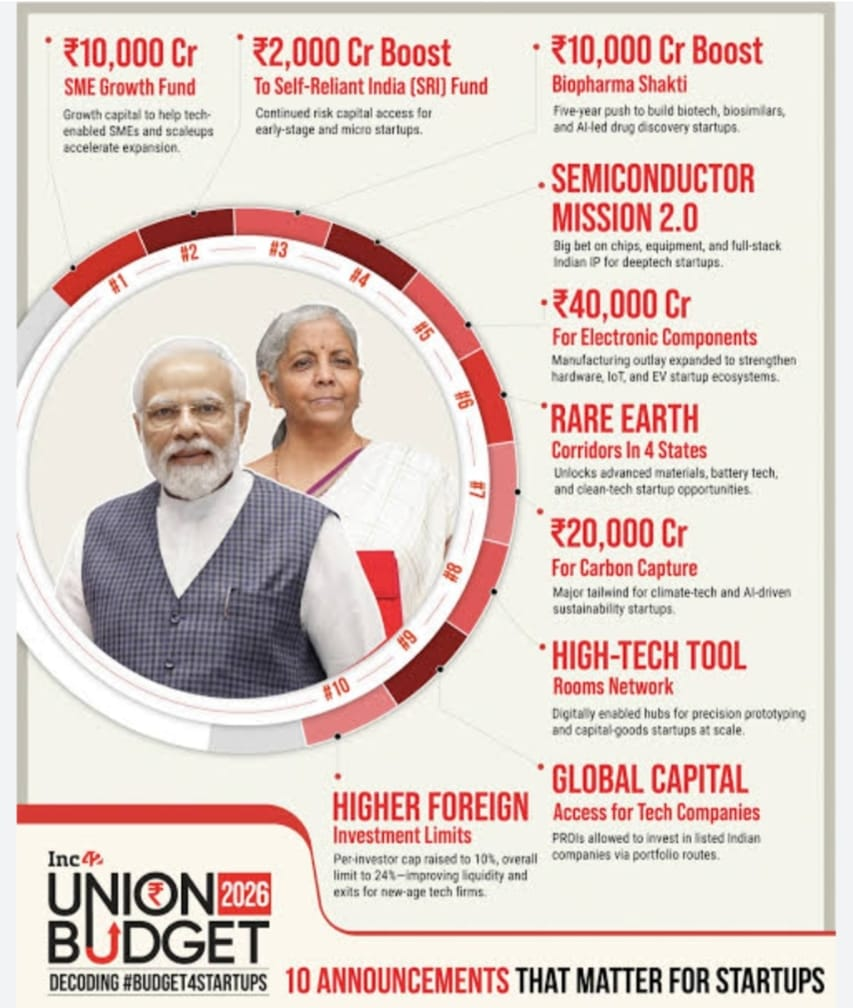
    Step 4: File Form TM-A

    The standard application for registration is filed using Form TM-A. The application identifies the applicant, the mark and the goods or services for which protection is sought.

    Government fees depend on the applicant category and filing method. For current fees, founders should verify the latest official IP India fee schedule before filing.

    Eligible startups may also have access to intellectual-property support and applicable fee concessions under government startup programmes, subject to the relevant eligibility requirements.

    Step 5: Monitor Examination and Respond to Objections

    Filing the application is not the end of the process. The Trade Marks Registry examines the application and may raise objections.

    An examination objection is not the same as a third-party opposition. An objection comes from the Registry during examination. An opposition is initiated by another party after the application reaches the relevant publication stage.

    If your application receives an objection, review the examination report carefully and respond within the applicable deadline. Lawizer provides a dedicated trademark objection reply service.

    Step 6: Publication and Opposition

    If an application progresses through examination, it may be advertised in the Trade Marks Journal. Third parties can oppose registration within the prescribed period.

    Under the Trade Marks Rules, 2017, the opposition procedure has specific timelines for notices, counter-statements and evidence. These procedural deadlines matter because missing them can affect the application or opposition.

    Step 7: Registration and Renewal

    If the application successfully completes the relevant stages, the mark can be entered on the Register and a registration certificate issued.

    Under the current framework, a registered trademark is valid for 10 years and can be renewed for successive 10-year periods. Government renewal fees depend on the applicable filing method and circumstances, so founders should verify the current fee schedule before renewal.

    Lawizer also provides trademark renewal assistance for businesses maintaining their registrations.

    How Much Does Startup Trademark Registration Cost?

    The government fee is only one part of the total cost. Your overall expenditure can depend on the applicant category, number of marks, number of classes and whether professional assistance is used.

    • Applicant category: Government fees vary depending on whether the applicant qualifies as an Individual, Startup, Small Enterprise or another category.
    • Number of classes: Government fees generally apply per mark and per class.
    • Filing method: Online and physical filing can have different government fees.
    • Professional assistance: Professional or facilitation charges are separate from government fees.

    Fees can change, so always check the latest official fee schedule before budgeting. For a broader explanation, see Lawizer’s guide to trademark registration cost, process and timeline in India.

    Common Startup Trademark Mistakes

    • Choosing a name before searching: A good-sounding name may already conflict with an earlier mark.
    • Searching only identical names: Similarity can arise from pronunciation, appearance or overall commercial impression.
    • Assuming company incorporation is enough: Entity registration and trademark registration are different.
    • Choosing the wrong class: Protection is linked to the goods and services covered.
    • Ignoring ownership: Founders should consider who should own the trademark and whether IP assignment documents are needed.
    • Forgetting renewal: A registered trademark requires timely renewal to maintain protection.
    • Using ® too early: The registered symbol should be used only after registration has actually been obtained.

    Lawizer’s legal checklist for new founders also covers wider legal groundwork that startups should consider alongside intellectual-property protection.

    Trademark FAQ for Indian Startup Founders

    Is It True That 90% of Startups Fail?

    No single 90% failure rate should be treated as a universal fact. Startup failure rates vary according to the definition of failure, industry, geography, time period and dataset. The more useful lesson for founders is to identify preventable risks and build a legal and financial foundation appropriate to the business.

    Is the 80/20 Rule Useful for Startups?

    The 80/20 rule, or Pareto principle, is a business heuristic suggesting that a relatively small number of inputs can account for a large proportion of results. Founders may use it to prioritise customers, products, channels or tasks. It is not a legal rule and does not replace proper compliance.

    What Is the 80/20 Rule for Startups?

    In startup planning, the 80/20 rule is commonly used to identify the activities or customers producing disproportionate results. For example, a small group of customers may generate a large share of revenue. The exact ratio does not have to be literally 80/20.

    Is 1% Equity in a Startup Good?

    There is no universal answer. The value of 1% depends on the company’s valuation, stage, dilution, vesting, the person’s role and the rights attached to the equity. A percentage should never be evaluated in isolation.

    Should Co-Founders Be 50/50 or 51/49?

    Neither split is automatically correct. Founders should consider contribution, responsibilities, decision-making, vesting, future fundraising and deadlock mechanisms. A well-drafted Co-Founder Agreement can help clarify these issues.

    Is Having Three Co-Founders Too Much?

    Not necessarily. Three founders can work well if responsibilities, ownership, decision-making and dispute-resolution mechanisms are clear. The number of founders matters less than whether the founding team has a workable governance structure.

    Is 1% Equity a Lot in a Startup?

    It depends on context. One percent of a very valuable company can be significant, while 1% of an early-stage company may carry substantial risk. Valuation, dilution, vesting and the person’s contribution all matter.

    What Are the Top 10 Failed Startups in India?

    There is no single authoritative list of the “top 10” failed Indian startups. Different publications use different definitions and datasets. Rather than relying on rankings, founders should examine the reasons behind individual failures, such as weak economics, poor governance, excessive spending or unresolved legal risks.

    Who Is Considered the “Bad Boy” of Indian Startups?

    “Bad boy” is an informal media or internet phrase, not a legal or official category. There is no authoritative Indian startup-law designation by that name. Any claim about a particular founder should be evaluated against reliable reporting and verified facts.

    Which Startup Is the Most Successful in India?

    There is no single objective answer. Success can mean valuation, revenue, profitability, market share, user growth, longevity or an eventual exit. A startup can rank highly on one measure and not another.

    Which Indian Startups Are in Loss?

    Startup financial performance changes over time. A company reporting a loss in one financial year is not necessarily failing. Revenue growth, operating margins, cash burn, funding position and the business model all need to be considered together.

    Who Are the Richest Startup Founders in India?

    Rankings of founder wealth are estimates and can change with private-company valuations, ownership percentages, secondary transactions and market movements. They should not be treated as precise unless supported by reliable financial information.

    What Are the Four Types of Trademarks?

    There is no complete statutory classification that limits Indian trademarks to exactly four types. Commonly discussed categories include word marks, device or logo marks, shape marks and sound marks. Other forms of marks can also be protected if they satisfy the legal requirements.

    What Happens If a Registered Trademark Is Not Used for 5 Years?

    Section 47 of the Trade Marks Act deals with removal of a registered trademark on grounds of non-use. In particular circumstances, a continuous period of five years and three months from the date on which the mark was actually entered in the Register can become relevant. The mark is not simply cancelled automatically after five years; a prescribed legal process and the facts of the case matter.

    What Is Rule 47 in Trademarks?

    Rule 47 of the Trade Marks Rules, 2017 concerns evidence in reply by the opponent in opposition proceedings. After receiving the applicant’s evidence, the opponent may file evidence by affidavit in reply within the period prescribed by the Rule. Rule 47 should not be confused with Section 47 of the Trade Marks Act, which concerns removal on grounds of non-use.

    How Do You Renew a Trademark After 10 Years?

    A registered trademark is generally valid for 10 years and may be renewed for further 10-year periods. Renewal is made using the prescribed process, including Form TM-R and the applicable fee. Founders should check the current official requirements and deadlines rather than relying on an old fee or timeline.

    How Much Does It Cost to Renew a Trademark in India?

    Renewal costs depend on the applicable government fee, filing method and whether additional charges apply because of delay or restoration. Government fees are separate from professional or facilitation charges. Check the current IP India fee schedule before renewal.

    What Is the Most Famous Trademark?

    “Most famous” is subjective. Brands such as Coca-Cola, Apple, Google and Nike are widely recognised examples, but fame does not have a single universal ranking. In legal terms, the more important question is whether a particular mark qualifies for protection and what rights it has in the relevant market.

    Is Sprite a Trademark?

    Yes. “Sprite” is used as a brand identifier and functions as a trademark for relevant goods. The important legal point is that trademark protection applies to the mark in connection with the relevant goods and services, rather than giving unrestricted ownership of the word in every context.

    Why Is Coca-Cola Not Patented?

    The Coca-Cola formula is widely discussed as a trade secret rather than a patent-protected formula. A patent generally requires disclosure of the invention and provides protection for a limited statutory period. A trade secret can potentially remain protected for as long as the information remains confidential and the legal requirements for trade-secret protection are met.

    Is “Coca-Cola” a Trademarked Name?

    Yes. Coca-Cola is a well-known brand and trademark. Its brand name and other identifying elements are distinct from the separate question of how the beverage formula is protected.

    Key Takeaway for Indian Startup Founders

    A startup’s brand may begin as just a name on a pitch deck. If the business succeeds, that same name can appear on products, websites, contracts, invoices, advertisements and customer reviews. At that point, changing it can become much harder.

    The practical approach is straightforward:

    • Choose a distinctive brand.
    • Search for conflicting marks before investing heavily.
    • Identify the correct goods and services classes.
    • Consider who should own the trademark.
    • File the application when commercially appropriate.
    • Monitor examination and opposition stages.
    • Maintain the registration and renew it on time.
    Trademark protection should therefore be considered alongside other early-stage legal requirements. Lawizer’s GST, MSME and trademark guide for founders explains how these different parts of the business-compliance picture can fit together.
    Protect Your Startup Brand Before It Becomes Expensive to Change

    If you have already finalised your startup’s brand name, the next sensible step is to check whether it is available and suitable for trademark protection.

    Lawizer can assist with trademark search, application filing and ongoing support through the trademark process. You can explore the Lawizer Trademark Registration service or review the trademark guide for first-time founders before deciding how to proceed.

    If your application later receives an objection, Lawizer also offers trademark objection reply assistance. For businesses with an existing registration, trademark renewal support can help with the next stage.

    f your startup has a brand worth building, make sure it is a brand worth protecting.

  • Website Terms And Conditions : India Business Guide

    Website Terms And Conditions : India Business Guide

    website terms and conditions are the rules that explain how people may use a business website and, where relevant, how online purchases, accounts, subscriptions, content and services are governed. For Indian founders, they are not merely a footer page. A well-drafted set of website terms can clarify responsibilities, reduce avoidable disputes and create a clearer legal framework for the website.

    Whether you operate an ecommerce store, SaaS platform, consulting website, marketplace, educational platform or service business, your website may involve customers, payments, personal data, intellectual property and third-party services. Clear terms help bring these activities under one consistent framework.

    However, there is no universal document that works for every website. The right terms depend on what your business sells, who uses the website, how users interact with it and which laws apply.

    What Are website terms and conditions?

    Website terms and conditions are contractual rules governing the relationship between a website operator and its users or customers. They can explain permitted website use, account responsibilities, payment terms, intellectual property rights, cancellations, refunds, disclaimers, liability and dispute resolution.

    The document may also be called Terms of Use, Terms of Service or simply Website Terms. The title matters less than the substance and the way the terms are presented and accepted.

    For example, a content website may mainly need rules covering intellectual property, acceptable use and disclaimers. An ecommerce website may need much more detail about orders, payment, delivery, cancellation, returns, refunds and consumer rights.

    Lawizer provides Privacy Policy and Terms of Use documentation for businesses that need a tailored online legal-document framework.

    Why Do Businesses Need website terms and conditions?

    A website can create legal and commercial relationships even when customers never sign a traditional paper contract. Users may create accounts, place orders, subscribe to services, download content or agree to recurring payments.

    Clear terms help establish what the business offers and what users are expected to do.

    • They define the scope of products or services.
    • They explain user responsibilities.
    • They set expectations about payments and cancellations.
    • They protect intellectual property.
    • They establish rules for accounts and website use.
    • They explain how disputes may be handled.
    • They can reduce uncertainty when a disagreement arises.

    Lawizer’s recent guidance for Indian founders also highlights customer terms, privacy documentation and other consumer-facing policies as part of the legal foundation for online businesses.

    Read Lawizer’s guide on legal mistakes startups make in India for a broader startup compliance checklist.

    What Should website terms and conditions Include?

    The contents should match the business model. A simple brochure website does not necessarily need the same clauses as a marketplace or subscription-based SaaS platform.

    1. Business and Website Information

    Start by identifying the business operating the website. Depending on the structure, this may include the legal name, business address, contact information and other appropriate details.

    The terms should make it reasonably clear who users are contracting with and how they can contact the business.

    2. User Eligibility and Account Rules

    If users create accounts, explain who can register and what information they must provide. State that users are responsible for keeping their credentials secure and for activities carried out through their account, subject to applicable law.

    You can also explain when an account may be suspended or terminated, such as for serious misuse, fraud or material breach of the terms.

    3. Acceptable Website Use

    Set out activities that users may not perform. These may include unauthorised access, interfering with website security, copying protected material without permission, distributing malicious code or using the website for unlawful purposes.

    Keep these restrictions relevant. Overly broad provisions can make terms harder to understand and may not provide the protection a business expects.

    4. Products, Services and Orders

    If the website sells goods or services, describe the basic commercial relationship. This can cover product descriptions, service scope, order acceptance, availability, pricing and circumstances in which an order may be cancelled.

    For an ecommerce business, the terms should work consistently with the website’s actual checkout process and consumer-facing policies.

    5. Payment, Cancellation and Refund Terms

    Payment provisions should explain when payment is due, accepted payment methods and what happens if a transaction fails.

    Cancellation and refund terms should be equally clear. Do not promise refunds in the terms if your actual business process does not provide them. Similarly, do not attempt to remove rights that applicable consumer law may provide.

    Businesses selling online should also review the Consumer Protection Act and related rules and the Consumer Protection (E-Commerce) Rules where applicable.

    6. Intellectual Property Rights

    Your website may contain logos, text, photographs, videos, software, designs, databases and other protected material. The terms can explain who owns those materials and what limited permission, if any, users receive to access them.

    For brand protection, founders can also explore Lawizer’s trademark registration service.

    7. User-Generated Content

    If customers can submit reviews, comments, photographs or other content, include rules for that material.

    The terms can address ownership, permissions granted to the business, prohibited content, moderation and removal. The wording should reflect the actual product and the type of content users can upload.

    8. Third-Party Links and Services

    Many websites use payment gateways, analytics tools, social-media plugins, maps, hosting providers and other third-party services.

    Your terms can explain that third-party services may be governed by their own terms. However, this clause should not be used to avoid responsibilities that legally remain with your business.

    9. Disclaimers and Limitation of Liability

    These clauses explain the circumstances in which the business limits responsibility for certain losses or website-related issues, subject to applicable law.

    They should be drafted carefully. A statement saying that the business has “no liability whatsoever” does not automatically make every possible claim disappear.

    10. Governing Law and Dispute Resolution

    The terms can identify the governing law and establish an appropriate mechanism for resolving disputes. Depending on the business, this may involve negotiation, mediation, arbitration or court proceedings.

    The clause should be consistent with applicable law and the actual business relationship.

    What Are the Five Essentials of website terms and conditions?

    There is no single statutory five-item checklist that applies to every website. However, founders can use five practical essentials when reviewing their terms:

    1. Clear identification: Users should understand who operates the website.
    2. Clear user obligations: The rules should explain what users may and may not do.
    3. Commercial terms: Products, services, payments, cancellations and refunds should be addressed where relevant.
    4. Legal protections: Intellectual property, liability, termination and dispute clauses should reflect the business.
    5. Effective acceptance: Users should have a clear opportunity to see and agree to the terms where contractual acceptance is intended.

    The exact requirements can vary with the transaction. Indian contract law generally focuses on matters such as competent parties, free consent, lawful consideration and lawful object, along with other applicable requirements.

    The Indian Contract Act, 1872 is the primary statute to review for general contract principles.

    What Are the 7 Requirements of a Valid Contract?

    Search results often describe a “seven requirements” list. However, there is no universal seven-point formula that should be treated as the complete legal test for every contract.

    A practical review may consider:

    • Offer or proposal.
    • Acceptance.
    • Consideration, where required.
    • Competency of the parties.
    • Free consent.
    • Lawful object and lawful consideration.
    • The agreement must not be one that the law treats as void or unenforceable.

    For a website, there is an additional practical issue: the business should consider how users are shown the terms and how acceptance is recorded.

    How Do You Make Simple website terms and conditions?

    You do not need to begin with a fifty-page legal document. Start by understanding the actual relationship between your business and its users.

    Step 1: Identify Your Business Model

    Ask what the website actually does. Is it an ecommerce store, SaaS product, marketplace, consulting business, content platform or lead-generation website?

    This decision affects the clauses you need.

    Step 2: Identify Your Users

    Determine whether you serve consumers, businesses, subscribers, vendors, freelancers, students or multiple groups.

    Different user groups can create different contractual and regulatory considerations.

    Step 3: Map the User Journey

    List every important interaction:

    • Landing on the website.
    • Creating an account.
    • Submitting information.
    • Purchasing a product.
    • Starting a subscription.
    • Downloading content.
    • Submitting reviews.
    • Contacting customer support.

    This helps you identify where legal terms need to apply.

    Step 4: Draft Relevant Clauses

    Build the document around the actual risks and transactions. Avoid filling it with clauses that have no connection to your business.

    If your business regularly signs contracts with freelancers, consultants or vendors, Lawizer also offers business documentation services.

    Step 5: Create a Clear Acceptance Process

    Where contractual acceptance is intended, consider using a clear mechanism such as an unchecked “I agree” checkbox linked to the terms before registration, checkout or another relevant action.

    Businesses should also retain appropriate records showing what terms applied and how acceptance occurred.

    Indian law recognises contracts formed through electronic means. Section 10A of the Information Technology Act, 2000 addresses the validity of contracts formed through electronic means.

    See the Information Technology Act, 2000 on India Code for the statutory text.

    Step 6: Keep the Terms Accessible

    Users should be able to find the terms easily. A footer link can improve accessibility, but businesses should consider whether users are given a meaningful opportunity to review the terms at the point where agreement is intended.

    Can I Legally Write My Own Website Terms?

    Yes. A business can draft its own terms. There is no general rule requiring every website to purchase a pre-written template from a lawyer.

    The bigger question is whether the document accurately reflects the business and applicable law.

    A generic template may contain irrelevant clauses, omit important provisions or describe a business process that you do not actually follow. That can create confusion when a dispute arises.

    Professional review becomes particularly useful for:

    • Marketplaces.
    • SaaS and subscription businesses.
    • Websites selling to consumers.
    • Businesses collecting substantial personal data.
    • Platforms with user-generated content.
    • Businesses using third-party sellers or service providers.
    • Regulated or industry-specific businesses.

    Lawizer’s Privacy Policy and Terms of Use service can be considered when a business wants its website documentation reviewed against its actual operations.

    Website Terms vs Privacy Policy vs Disclaimer

    Terms of Use

    Terms of Use establish the rules governing website access, services, accounts, transactions and other user relationships.

    Privacy Policy

    A Privacy Policy explains how the business handles personal data, including relevant information about collection, use, storage, sharing and user rights.

    These documents should not simply be merged without considering their different purposes.

    The Digital Personal Data Protection Act, 2023 should also be considered where its provisions apply. Businesses should verify current commencement notifications, rules and sector-specific requirements before relying on a compliance position.

    Disclaimer

    A disclaimer can explain limitations concerning information, professional advice, third-party material or particular risks. It is not a substitute for properly drafted website terms or privacy documentation.

    Important Legal Considerations for Indian Websites

    The legal framework depends heavily on the type of website and its activities. Founders should avoid assuming that one website policy automatically satisfies every legal requirement.

    Indian Contract Law

    The Indian Contract Act, 1872 provides the general contractual framework. Section 10 is particularly important when considering whether an agreement qualifies as a contract under the Act, subject to other applicable laws and provisions.

    Electronic Contracts

    Online agreements can be formed electronically. The Information Technology Act, 2000 specifically contains Section 10A on contracts formed through electronic means.

    Lawizer also explains electronic agreements in its guide to virtual contracts and legal validity in India.

    Consumer Protection

    If you sell goods or services to consumers online, consumer protection rules can become relevant. The Consumer Protection Act, 2019 and Consumer Protection (E-Commerce) Rules, 2020 should be reviewed where applicable.

    The Department of Consumer Affairs publishes the Consumer Protection Act and related rules, including the E-Commerce Rules.

    Data Protection

    If the website collects personal data, privacy documentation and data-handling practices should match what the business actually does.

    Do not copy a privacy policy that promises practices your business does not follow. Your website forms, analytics tools, payment systems, CRM and support systems should be considered when preparing the documentation.

    Common Mistakes in Website Terms and Conditions

    Copying Another Company’s Terms

    Another business may operate differently from yours. Its refund rules, customers, technology and legal risks may not apply to your business.

    Using a Generic Template Without Reviewing It

    Templates can provide a starting point. They should not replace a review of your actual website and business model.

    Making the Terms Impossible to Understand

    Legal protection does not require unnecessarily complicated language. Clear drafting makes obligations easier for users and business teams to follow.

    Hiding the Terms

    If users cannot easily locate the terms, the business may face questions about whether and how users were informed of them.

    Not Recording Acceptance

    For important online transactions, businesses should consider maintaining appropriate evidence of acceptance, including the version of the terms that applied at the relevant time.

    Ignoring Refund and Cancellation Rules

    Do not draft terms separately from the actual checkout process. The terms, refund policy and customer communications should tell the same story.

    Never Updating the Terms

    Your business can change quickly. New payment methods, subscriptions, products, markets and data practices can make old terms incomplete.

    Lawizer’s annual compliance services can also be useful as part of a broader process of keeping business documentation and recurring obligations organised.

    website terms and conditions Checklist for Indian Founders

    Before publishing or updating your website terms, use this checklist:

    • Identify the website operator clearly.
    • Describe the scope of the terms.
    • Define important users and accounts.
    • Set acceptable-use rules.
    • Explain products or services.
    • Set out payment conditions.
    • Address cancellation and refund rules.
    • Protect intellectual property.
    • Address user-generated content if applicable.
    • Explain third-party services where relevant.
    • Include appropriate disclaimers.
    • Include a suitable liability clause.
    • Address termination or suspension.
    • Specify governing law and dispute resolution where appropriate.
    • Provide contact or grievance information where required.
    • State an effective or last-updated date.
    • Provide a suitable acceptance mechanism.
    • Keep the document consistent with your Privacy Policy.

    Frequently Asked Questions About Website Terms

    What should a website terms and conditions document include?

    It should cover the rules relevant to the website and business. Common areas include user eligibility, account rules, acceptable use, products or services, payments, refunds, intellectual property, liability, termination and dispute resolution.

    Ecommerce and subscription businesses may need additional clauses because their customer relationships involve transactions, recurring services or consumer rights.

    What are the five essentials of a contract?

    There is no universal five-word formula. A common practical explanation covers offer, acceptance, consideration, competent parties and free consent, together with a lawful object and other applicable requirements.

    For a website, founders must also think about how users are presented with the terms and how acceptance is recorded.

    What are the 7 requirements of a valid contract?

    A commonly used seven-part summary includes offer, acceptance, consideration, competent parties, free consent, lawful object and an agreement that is not expressly void. The precise legal analysis depends on the transaction and applicable law.

    Can I legally write my own contract?

    Yes. A business can draft its own contract. However, the document should be reviewed against the actual transaction and applicable law. Complex websites can benefit from professional drafting or review.

    How do I make a simple legal contract?

    Identify the parties, define the purpose, describe the obligations of each side, establish payment or consideration where applicable, address important risks and provide an appropriate dispute mechanism. Make sure the parties receive and accept the terms properly.

    Can I create my own terms and conditions?

    Yes. You can create your own terms, but copying a template without customising it can leave important gaps. The document should accurately reflect your products, users, payment process and data practices.

    What are the 7 rules of a contract?

    There is no single universal list called the “seven rules of a contract”. Online searches often use this phrase to refer to different summaries of contract principles. It is better to assess the actual agreement against the applicable law.

    What are the 7 essential elements of a contract?

    Common explanations refer to offer, acceptance, consideration, intention or enforceability, competent parties, free consent and lawful purpose. However, the exact legal test should not be reduced to a universal seven-item checklist.

    What are the 10 essentials of a valid contract?

    Some educational resources use ten-item lists to explain contracts. These may break broad principles into smaller components. For a business website, the more useful approach is to identify the actual contractual requirements and website-specific risks.

    What are the 5 essential elements of a contract?

    A simplified explanation often includes offer, acceptance, consideration, intention to create legal obligations and competent parties. The Indian Contract Act and other applicable laws should be considered for the specific transaction.

    What things are required for freelancing and online business?

    Depending on the business, founders may need appropriate contracts, invoices, tax registrations, privacy documentation, website terms, intellectual property protection and other compliance measures.

    If your business works with freelancers, read Lawizer’s freelance contract guide for Indian founders.

    What is the difference between a freelancer and an independent contractor?

    The terms can overlap in ordinary business language. The legal classification depends on the actual relationship, contractual terms, control, work arrangement and applicable law. Businesses should avoid relying on labels alone.

    Final Takeaway: Keep Your Website Terms Clear and Current

    Good website terms are not about making a website look more “legal”. They are about making the business relationship clearer.

    The best document reflects what your business actually does. It explains the rules in language users can understand and supports the way your website collects information, takes orders, processes payments and provides services.

    Indian founders should also remember that website terms are only one part of a wider legal framework. Depending on the business, you may also need privacy documentation, commercial contracts, intellectual property protection, consumer-facing policies and ongoing compliance.

    Lawizer can help businesses review and organise these legal requirements. You can explore business documentation services, GST registration support, trademark registration and other startup and business legal services.

    Need help with your website’s legal documents? Consult Lawizer to understand which terms, privacy documents and business agreements are appropriate for your specific business model.

    Disclaimer: This article provides general educational information and is not a substitute for legal, tax or professional advice. Applicable requirements can vary based on the business structure, state, industry, customer base, transactions and changes in law. Businesses should obtain professional advice for their specific circumstances and verify current requirements with the relevant government authorities.

    Official Legal References

    Relevant Tags: Website Terms and Conditions, Terms of Use, Terms of Service, Indian Business Law, Startup Legal Compliance, Online Business Legal, Privacy Policy, Ecommerce Compliance, Business Contracts, Legal Documents for Startups, Indian Startups, Small Business Legal

  • Freelance Contract Essentials :

    Freelance Contract Essentials :

    freelance contract essentials for Indian businesses and freelancers

    Hiring a freelancer can help an Indian startup or small business move faster without adding a full-time employee. However, a simple WhatsApp conversation about the work, fee and deadline may not cover what happens when the project changes. freelance contract essentials give both sides a clear written framework for the work, payment, intellectual property, confidentiality and other important terms.

    A well-drafted agreement can reduce misunderstandings before they become disputes. It can also make it easier to establish what each party agreed to do, what the freelancer must deliver and when payment becomes due.

    This guide explains the key clauses every Indian business should consider when engaging a freelancer. It also covers contract validity, taxes, intellectual property, termination, dispute resolution and common mistakes.

    What Is a Freelance Contract?

    A freelance contract is a written agreement between a business or client and an independent professional. It sets out the services to be provided, deliverables, fees, timelines and responsibilities of both parties.

    For example, a startup may hire a designer to create a brand identity, a developer to build software, or a writer to produce website content. The contract should explain exactly what the freelancer is expected to provide and what the business must provide in return.

    The agreement can also deal with matters that are easy to overlook, such as ownership of source files, confidentiality, revision limits, termination and dispute resolution.

    Why a Written Freelance Agreement Matters

    A written agreement is useful because it creates a clear record of the commercial arrangement. It can reduce arguments about what was promised and provide a reference if a disagreement occurs.

    Indian contract law recognises agreements that satisfy the applicable requirements for a valid contract. Section 10 of the Indian Contract Act, 1872 refers to free consent, competent parties, lawful consideration and a lawful object, subject to other applicable legal requirements.

    Businesses can also use electronic methods to form contracts. Section 10A of the Information Technology Act, 2000 recognises that a contract is not unenforceable merely because electronic records or electronic communication were used in its formation.

    Read the Indian Contract Act, 1872 and the Information Technology Act, 2000 for the statutory framework.

    freelance contract essentials: What Should a Freelance Contract Include?

    The right agreement depends on the project, parties and risks involved. However, most businesses should consider the following core clauses.

    1. Details of the Client and Freelancer

    Start by identifying both parties correctly. For a business, use the legal name of the company or other contracting entity rather than only a brand name.

    • Full legal name of the client or business
    • Registered or correspondence address, where relevant
    • Freelancer’s full name or business name
    • Contact details
    • PAN and GST details where relevant
    • Name and authority of the person signing for a company

    Correct identification matters because the agreement should clearly establish who has the contractual rights and obligations.

    If your business is still being structured, you can also explore Private Limited Company Registration or LLP Registration through Lawizer.

    2. Scope of Work and Deliverables

    The scope of work is one of the most important freelance contract essentials. A vague description such as “build a website” or “manage social media” can create different expectations.

    Instead, describe the deliverables as specifically as possible.

    • What services will be provided?
    • What files, reports or outputs will be delivered?
    • How many pages, designs or posts are included?
    • What formats must be supplied?
    • What is excluded from the project?
    • How many revisions are included?
    • What milestones and deadlines apply?

    For example, a design agreement could specify five website screens, desktop and mobile versions, two revision rounds and delivery of specified source and export files.

    3. Change Requests and Scope Creep

    Projects often change after work begins. Your contract should explain what happens when the client requests additional work.

    A useful clause can require written approval and a separate fee or revised timeline for work outside the original scope. This protects both parties from an assumption that every new request is included in the original price.

    Lawizer’s Service Agreement and Term Sheet drafting service focuses on defining scope, fees, deliverables, milestones and timelines.

    4. Payment Terms and Invoicing

    A contract should state how much the freelancer will be paid and when payment becomes due. Do not leave payment terms to an informal conversation.

    • Total professional fee
    • Fixed, hourly or milestone-based pricing
    • Advance payment, if applicable
    • Milestone payment dates
    • Invoice requirements
    • Payment method
    • Applicable taxes
    • Consequences of delayed payment

    If payment is milestone-based, identify each milestone clearly. This can prevent disagreements about whether the freelancer has completed enough work to raise the next invoice.

    Any late-payment interest should be drafted carefully and should comply with applicable law and the agreed commercial terms. Avoid inserting an arbitrary penalty simply because it appears in an online template.

    5. Intellectual Property Ownership

    Intellectual property is particularly important when a freelancer creates software, designs, photographs, videos, written content, branding or other creative work.

    Do not assume that paying an invoice automatically answers every question about ownership. The agreement should expressly address the intended ownership and rights in the work product.

    The IP clause can specify:

    • Which deliverables are covered
    • Whether rights are assigned or licensed
    • When the transfer or licence becomes effective
    • Whether source and working files are included
    • How pre-existing materials are treated
    • Whether the freelancer may display the work in a portfolio
    • How third-party materials and licences are handled

    For projects where a separate transfer document is appropriate, Lawizer offers an IP Assignment Agreement service.

    Businesses that create original software, written material, artwork or other copyrightable works can also consider Copyright Registration where appropriate.

    6. Confidentiality and NDA Protection

    Freelancers may receive access to confidential business information while working on a project. This may include customer information, pricing, source code, business plans, product roadmaps or internal documents.

    A freelance agreement can contain confidentiality obligations. For sensitive engagements, a separate Non-Disclosure Agreement (NDA) may provide a more detailed framework.

    A confidentiality clause should explain:

    • What information is confidential
    • How the information may be used
    • Who may receive it
    • What information is excluded
    • How long confidentiality obligations continue
    • What happens when the engagement ends

    Confidentiality should not be drafted so broadly that it creates unreasonable restrictions. The agreement should reflect the legitimate information the business actually needs to protect.

    7. Tax, TDS and GST Terms

    Tax treatment should be considered when drafting the payment clause. A business should not simply copy an old freelance contract that refers to outdated tax provisions.

    For payments or credits from 1 April 2026, TDS provisions are governed by the Income-tax Act, 2025. The Income Tax Department states that Section 393 contains the relevant TDS framework for payments other than salaries, with tables specifying the applicable payment categories, thresholds and rates.

    Therefore, instead of inserting an old section number or fixed rate without checking the transaction, the agreement can state that applicable TDS will be deducted in accordance with the law in force at the relevant time.

    You can verify current tax requirements through the Income Tax Department. Businesses can also explore Lawizer’s ITR filing services for applicable business and professional tax-return needs.

    GST should also be considered. Whether a freelancer must register, charge GST or comply with other GST requirements depends on the nature of the supply, turnover and applicable rules. The agreement should clarify whether quoted fees are inclusive or exclusive of applicable GST.

    For current registration rules, refer to the CBIC GST FAQs and consider GST Registration assistance where appropriate.

    8. Deadlines, Milestones and Acceptance

    A good freelance contract should make the delivery process easy to understand. State the project start date, milestones and expected completion dates.

    Also consider how the client will review the work. For example, the contract can establish a reasonable review period and explain how feedback should be provided.

    Where a delay is caused by the client’s failure to provide required information, approvals or materials, the agreement can explain how the deadline will be adjusted.

    9. Termination and Exit Terms

    Every project should have an exit mechanism. Termination provisions explain when either party can end the relationship and what happens afterwards.

    Consider including:

    • Termination for convenience, if appropriate
    • Termination for material breach
    • Notice requirements
    • Payment for completed work
    • Treatment of partially completed work
    • Return or deletion of confidential information
    • Delivery of completed files
    • Survival of confidentiality and other relevant clauses

    There is no universal notice period that applies to every freelance engagement. The appropriate period depends on the project, contract structure and commercial relationship.

    10. Dispute Resolution and Governing Law

    A dispute clause can explain what happens if the client and freelancer cannot resolve a disagreement.

    Depending on the arrangement, the contract may provide for negotiation, mediation or arbitration before court proceedings. It should also identify the governing law and, where appropriate, the jurisdiction or seat of arbitration.

    Do not choose a dispute mechanism simply because it appears in another agreement. Consider the value of the contract, location of the parties and practical cost of enforcement.

    freelance contract essentials: What Makes a Contract Valid?

    Searches about freelance agreements often lead to questions about the “five essentials” or “seven requirements” of a valid contract. These lists can vary because different sources group the legal principles differently.

    Under Section 10 of the Indian Contract Act, 1872, agreements are contracts when they are made with free consent by parties competent to contract, for lawful consideration and a lawful object, and are not expressly declared void.

    In practical terms, a freelance arrangement should therefore have clear agreement between the parties and lawful terms. The parties should also have the legal capacity to enter into the agreement.

    What Are the Five Essentials of a Contract?

    A simple way to understand the basic principles is to look at:

    1. Offer: One party proposes the arrangement.
    2. Acceptance: The other party accepts the relevant terms.
    3. Consideration: There is a lawful exchange of value, such as payment for services.
    4. Competent parties: The parties must be legally capable of contracting.
    5. Lawful object: The purpose of the agreement must be lawful.

    Free consent and other statutory requirements also matter. A practical freelance contract should therefore do more than merely mention the fee and service. It should record the commercial terms clearly.

    What Are the 7 Requirements of a Valid Contract?

    Different legal resources may present the list differently, but a practical checklist can include:

    • Offer and acceptance
    • Competent parties
    • Free consent
    • Lawful consideration
    • Lawful object
    • Certainty of important terms
    • Terms that are not expressly void or otherwise unenforceable

    The exact legal position can depend on the facts and the type of transaction. For an important or high-value agreement, professional legal review is preferable to relying on a generic checklist.

    Can I Legally Write My Own Freelance Contract?

    Generally, parties can prepare their own contracts. There is no universal rule requiring every freelance agreement to be drafted by a lawyer.

    However, preparing a document and preparing a suitable legal agreement are two different things. A generic template may leave out important commercial terms or contain provisions that do not fit the actual transaction.

    Professional review becomes more valuable when the engagement involves significant intellectual property, sensitive customer information, international payments, high-value work, complex milestones or substantial business risk.

    How to Make a Simple Legal Freelance Contract

    1. Identify the parties. Use the correct legal names.
    2. Describe the services. List specific deliverables.
    3. Set the price. State the fee and payment schedule.
    4. Set deadlines. Add milestones and acceptance requirements.
    5. Protect IP and confidential information. Explain ownership and permitted use.
    6. Add termination terms. Explain how the relationship can end.
    7. Set dispute terms. State the governing law and dispute mechanism.
    8. Sign the agreement. Keep the final signed version and relevant records.

    For a business service arrangement, Lawizer’s Service Agreement drafting service can be relevant when the engagement needs clearly defined scope, fees and timelines.

    Freelance Contract Essentials: Freelancer vs Independent Contractor

    The terms “freelancer” and “independent contractor” are often used interchangeably in everyday business discussions, but they can describe slightly different concepts.

    A freelancer commonly provides project-based or independent services to clients. An independent contractor is a broader description of someone engaged under a contract to provide services independently rather than as an employee.

    The actual legal relationship depends on the facts, the agreement and applicable law. Simply calling someone an “independent contractor” does not automatically determine their legal status.

    If a person is actually being engaged as an employee, an employment arrangement may be more appropriate. Lawizer also provides Employment Agreement drafting for employer-employee relationships.

    What Things Are Required for Freelancing?

    Freelancing requires more than a professional skill. A reliable business process helps the freelancer and client work together smoothly.

    • A marketable professional skill
    • A portfolio or evidence of previous work
    • Clear pricing and payment terms
    • A defined client onboarding process
    • A written service or freelance agreement
    • A reliable invoicing and record-keeping system
    • Appropriate tax and GST compliance where applicable
    • Secure handling of client information

    Freelancers earning professional income should also understand their income-tax filing obligations. Lawizer’s guide to ITR-3 for freelancers and business owners explains the return and expense considerations for applicable taxpayers.

    What Are 7 High-Paying Freelance Skills?

    Rates vary significantly by experience, industry, location and client. However, skills that can command strong professional fees may include:

    • Software development
    • AI and automation
    • Cybersecurity
    • UI/UX design
    • Digital marketing
    • Copywriting and content strategy
    • Business or financial consulting

    Whatever the skill, a written agreement helps define exactly what the client is paying for.

    Common Freelance Contract Mistakes to Avoid

    Even when a business uses a contract, certain drafting mistakes can reduce its practical value.

    1. Using a Vague Scope

    “Complete the project” is rarely enough. List the actual outputs, specifications, deadlines and exclusions.

    2. Leaving Payment Terms Unclear

    State the fee, payment milestones, invoice process and applicable tax treatment.

    3. Assuming Payment Automatically Settles IP Ownership

    Address IP rights expressly. Identify what is being transferred or licensed and when the relevant rights take effect.

    4. Ignoring Tax Requirements

    Tax provisions change. Do not copy an old contract containing outdated TDS references or thresholds. Check the law applicable when the payment or credit occurs.

    5. Allowing Unlimited Revisions

    Unlimited revisions can create uncertainty for both sides. Set a reasonable revision process and explain how additional requests will be handled.

    6. Forgetting Confidentiality

    If the freelancer can access sensitive information, include suitable confidentiality obligations or use a separate NDA.

    7. Having No Termination Clause

    Projects can change. A clear exit mechanism is better than trying to negotiate termination after a dispute begins.

    8. Starting Work Before Signing

    Ideally, finalise the commercial terms before substantial work begins or an advance is paid. This reduces uncertainty about what the parties actually agreed.

    Frequently Asked Questions About Freelance Contract Essentials

    What should a freelance contract include?

    A freelance contract should generally cover the parties, scope of work, deliverables, fees, payment schedule, deadlines, intellectual property, confidentiality, taxes where relevant, termination and dispute resolution. The exact clauses should reflect the project.

    What are the five essentials of a contract?

    A common simplified explanation includes offer, acceptance, consideration, competent parties and lawful object. Free consent and other legal requirements also matter under Indian contract law.

    What are the 7 requirements for a valid contract?

    A practical checklist includes offer and acceptance, competent parties, free consent, lawful consideration, lawful object, certainty of important terms and the absence of terms that are expressly void or otherwise unenforceable.

    How do I make a simple legal contract?

    Identify the parties, describe the services, agree on payment, set deadlines, address IP and confidentiality, add termination and dispute clauses, and sign the final document. Complex arrangements should be reviewed professionally.

    Can I legally write my own contract?

    Yes, parties can generally prepare their own agreements. However, a self-drafted contract may not address risks specific to the project. Professional review can be useful for high-value, complex or IP-heavy engagements.

    Can I create my own contract?

    Yes. You can create a contract yourself, provided the agreement complies with applicable law and accurately records the parties’ agreement. A generic template should be customised rather than copied without review.

    What are the 7 rules of a contract?

    There is no single universally accepted seven-rule list. Practical rules include clear agreement, lawful terms, competent parties, free consent, definite obligations, appropriate consideration and provisions that are not void or otherwise unenforceable.

    What things are required for freelancing?

    A freelancer generally needs a marketable skill, portfolio, clients, pricing and invoicing processes, suitable contracts, record keeping and compliance with applicable tax or GST requirements.

    Do I pay tax if I freelance?

    Freelance income can be taxable. The amount and method of taxation depend on the taxpayer’s income, nature of professional activity, applicable deductions, tax regime and other facts. Freelancers should assess their individual tax position rather than rely on a general rate.

    How much tax will I pay as a freelancer?

    There is no single freelancer tax rate. Tax liability depends on the applicable income-tax rules, total taxable income, deductions, regime and the nature of the income. Current rules should be checked for the relevant tax year.

    What’s the difference between a freelance and an independent contractor?

    A freelancer usually refers to an independent professional providing services, often on a project basis. Independent contractor is a broader contractual description. The legal relationship depends on the actual arrangement rather than the label alone.

    What are 7 high-paying freelance skills?

    Software development, AI and automation, cybersecurity, UI/UX design, digital marketing, copywriting and consulting can all be commercially valuable freelance skills. Actual earnings vary by expertise, demand and client.

    Freelance Agreement Checklist for Indian Businesses

    Before signing a freelance agreement, use this quick checklist:

    • Correct legal names of both parties
    • Clear scope of work
    • Specific deliverables
    • Revision limits
    • Milestones and deadlines
    • Fee and payment schedule
    • Applicable TDS and GST treatment
    • IP ownership or licensing terms
    • Confidentiality obligations
    • Termination procedure
    • Dispute resolution mechanism
    • Governing law and jurisdiction, where appropriate
    • Signatures and final copies

    Conclusion: Put the Agreement in Place Before Work Starts

    A freelance relationship works best when both parties understand their responsibilities from the beginning. The strongest freelance contract essentials are not complicated: define the work, agree on payment, protect intellectual property and confidential information, address taxes, and establish what happens if the project changes or ends early.

    Do not treat the agreement as paperwork to complete after a dispute appears. Put the important terms in writing before substantial work begins.

    If you are hiring a freelancer for software development, design, marketing, consulting, content or another professional service, Lawizer can help you choose and prepare the appropriate business documentation.

    Explore Lawizer’s Consultancy Agreement drafting, Service Agreement drafting, NDA drafting and IP Assignment Agreement drafting services for different business requirements.

    Need help with your agreement? Consult Lawizer for assistance with business contracts and legal documentation tailored to your situation.

    Disclaimer: This article is for general informational purposes and does not constitute legal, tax or professional advice. Contract, tax, GST, stamping, registration and enforcement requirements can depend on the facts, parties, state and applicable law. Obtain professional advice for a specific transaction.

  • How to register a trademark in India

    How to register a trademark in India

    Your brand name, logo or tagline can become one of your business’s most valuable assets. But using a brand in the market does not automatically give you the strongest statutory protection available under Indian trademark law. If you are a founder or small-business owner wondering how to register a trademark in India, the process involves more than simply filling out an online form.

    You need to select a distinctive mark, search existing trademarks, identify the correct class of goods or services, prepare the application, respond to any examination objections and monitor the application until registration. This guide explains each stage in clear language, along with the documents, government fees, timelines and common mistakes you should know about.

    The process is governed principally by the Trade Marks Act, 1999 and the Trade Marks Rules, 2017.

    What Is a Trademark in India?

    A trademark is a mark capable of distinguishing the goods or services of one person from those of others. Depending on the circumstances, it can include words, names, logos, symbols, slogans, shapes, colours and other distinctive elements.

    For a business, the important point is that trademark protection is linked to the mark and the goods or services for which it is registered. Registration does not give you ownership over an ordinary word in every possible context.

    For example, the same or similar word may potentially be used by different businesses operating in unrelated fields, depending on the facts and the applicable trademark classes.

    What Can Be Registered as a Trademark?

    • Brand or business names
    • Logos and device marks
    • Taglines and slogans
    • Letters and numbers
    • Distinctive combinations of words, designs or other elements
    • Other marks that satisfy the legal requirements for registration

    What Cannot Be Registered as a Trademark?

    Not every proposed brand is registrable. The Trade Marks Act contains absolute and relative grounds that can prevent registration.

    Problems may arise where a mark is non-distinctive, descriptive in a manner covered by the statutory restrictions, deceptive or likely to cause confusion, prohibited by law, or conflicting with an earlier trademark or other protected right. Sections 9 and 11 of the Act are particularly important when assessing registrability.

    This is why a trademark search should ideally happen before you spend heavily on packaging, advertising, websites or other brand assets.

    Who Can Register a Trademark in India?

    You do not need to incorporate a private limited company before applying for a trademark. Under Section 18 of the Trade Marks Act, a person claiming to be the proprietor of a trademark can apply for registration.

    Depending on the circumstances, applicants can include:

    • Individuals and freelancers
    • Sole proprietors
    • Startups
    • Small enterprises
    • Partnership firms
    • LLPs
    • Private or public companies
    • Other eligible applicants

    If your business is still being set up, it is therefore possible to consider trademark protection separately from your choice of business structure. If you are deciding whether you need a company, LLP or another structure, you can also explore Lawizer’s startup and business legal services.

    How to Register a Trademark in India: Step-by-Step Process

    The registration journey can be understood as a series of stages. The exact experience varies depending on the mark, class, examination objections and whether a third party opposes the application.

    Step 1: Choose a Distinctive Trademark

    Start by deciding exactly what you want to protect. This could be your brand name, logo, tagline or another distinctive element.

    A strong trademark is generally one that can distinguish your goods or services from those of competitors. Avoid choosing a mark solely because it describes what you sell. The more distinctive the mark, the stronger the starting point for registration.

    Also decide whether you need protection for a word mark, a logo or both. A business may ultimately want separate protection for different brand elements.

    Step 2: Conduct a Trademark Search

    Before filing, search the official trademark records to identify identical or deceptively similar marks. The IP India online trademark system provides the relevant government infrastructure for trademark applications and searches.

    Do not limit your search to an exact spelling. Consider:

    • Similar spellings
    • Phonetic similarities
    • Similar-looking marks
    • Existing applications as well as registrations
    • Marks in relevant and potentially related classes

    A search cannot guarantee registration, but it can reveal obvious conflicts before you spend more money building the brand.

    Step 3: Identify the Correct Trademark Class

    India uses the Nice Classification system for goods and services. The classification has 45 classes, with Classes 1–34 covering goods and Classes 35–45 covering services.

    Your application should identify the goods or services for which the mark is being used or proposed to be used. Choosing the wrong class can leave an important part of your business inadequately protected.

    For instance, a software business and a clothing business have very different commercial activities and may require different classes. A business operating across multiple product or service categories may need protection in more than one class.

    Do not select classes simply because another company used them. The correct classification depends on what your business actually offers.

    Step 4: Prepare the Trademark Application Documents

    The documents and information required will depend on the applicant and the nature of the application. Common requirements include:

    • Applicant’s name and address
    • Details identifying the applicant’s legal status
    • A clear representation of the trademark
    • Description of the relevant goods or services
    • Details of the class or classes
    • Information regarding use or proposed use of the mark
    • Supporting documents where a particular claim or applicant category requires them
    • Authorisation documents where an agent or attorney files on behalf of the applicant

    If prior use of the mark is claimed, the Trade Marks Rules require a statement regarding use and an affidavit with supporting documents in the circumstances prescribed by the Rules.

    Step 5: File Form TM-A

    The standard application for registration of a trademark is filed using Form TM-A. The application identifies the applicant, the mark, the relevant goods or services and the applicable class or classes.

    The application can be filed electronically through the IP India system. After filing, the application receives an application number that can be used to monitor its progress.

    For the current official fee schedule, see the IP India Forms and Official Fees page.

    Step 6: Monitor the Application Status

    Filing the application is not the final step. The applicant should monitor the status and communications issued by the Trade Marks Registry.

    The application may move through examination and other procedural stages before it reaches registration. If the Registry raises an objection or requires a response, failing to act within the applicable deadline can seriously affect the application.

    Step 7: Respond to a Trademark Examination Objection

    An examination report may raise objections concerning the registrability of the mark. Common issues include lack of distinctiveness, descriptiveness or similarity with an earlier mark.

    An objection is not the same thing as a final refusal. The applicant can respond with appropriate legal and factual submissions and supporting material. Depending on the case, a hearing may also be required.

    For businesses that receive an examination objection, Lawizer also provides a dedicated trademark registration and objection-support service.

    Step 8: Publication in the Trade Marks Journal

    Once the application reaches the relevant stage of acceptance, it may be advertised in the Trade Marks Journal. Publication provides an opportunity for third parties to oppose registration.

    Under Rule 42 of the Trade Marks Rules, a notice of opposition is generally filed within four months from the date of publication or re-publication of the application in the Trade Marks Journal.

    This is an important distinction: an examination objection comes from the Registry, while an opposition is brought by a third party.

    Step 9: Registration and Trademark Certificate

    If the application completes the relevant stages without a successful opposition preventing registration, the Registrar can enter the mark on the Register and issue the registration certificate in accordance with the Act and Rules.

    Once registered, the proprietor can use the ® symbol in connection with the registered mark. The symbol should not be used as though the mark were registered when it has not actually been registered.

    What Documents Are Required for Trademark Registration?

    There is no single document checklist that applies identically to every applicant. However, a typical application may involve:

    • Applicant identity and contact details
    • Address details
    • Trademark representation, particularly where a logo or device mark is involved
    • Goods or services specification
    • Details of proposed use or prior use
    • Affidavit and supporting evidence where prior use is claimed
    • Startup or small-enterprise documentation where the applicant is claiming the applicable fee category
    • Authorisation documents where filing is through an agent

    Applicants should provide accurate information because inconsistencies between the application and supporting material can create avoidable complications.

    How Much Does Trademark Registration Cost in India?

    The government filing fee depends on the applicant category, filing mode, number of classes and number of marks.

    As reflected in the current official IP India fee schedule, the online filing fee for a standard trademark application is:

    • ₹4,500 per class per mark for an Individual, Startup or Small Enterprise.
    • ₹9,000 per class per mark for other applicants.

    The corresponding physical filing fees are higher: ₹5,000 for an Individual/Startup/Small Enterprise and ₹10,000 for other applicants. These are government fees and are separate from professional or facilitation charges.

    If you file in multiple classes, the government fee applies according to the applicable fee structure for each class and mark. The total cost can therefore vary considerably between businesses.

    For context, Lawizer’s current trademark registration service lists its facilitation fee separately from government charges.

    How Long Does Trademark Registration Take in India?

    There is no single guaranteed timeline for every trademark application. A straightforward application may progress through the Registry without major disputes, while an application facing objections or opposition can take substantially longer.

    The timeline can be affected by:

    • Examination of the application
    • Objections and responses
    • Hearings, where applicable
    • Publication in the Trade Marks Journal
    • Third-party opposition
    • Procedural delays or additional requirements

    Lawizer currently describes the process as involving several stages and notes that an uncontested application can take approximately 6–12 months, while its broader educational material also cautions that contested matters can take longer. Treat any stated timeline as an estimate rather than a guarantee.

    Can You Use the ™ and ® Symbols?

    What Does ™ Mean?

    The ™ symbol is commonly used to indicate that a business is claiming a mark as its trademark. Registration is not required simply to use the symbol.

    When Can You Use ®?

    The ® symbol is associated with a registered trademark. A business should not represent an unregistered mark as registered.

    In practical terms, use ™ while your brand is being claimed as a trademark, and use ® after the relevant mark has actually been registered.

    What Happens If Your Trademark Is Objected To or Opposed?

    Trademark Objection vs Trademark Opposition

    These two terms are often confused.

    • Examination objection: raised by the Trade Marks Registry during examination of the application.
    • Opposition: initiated by a third party after the application is advertised in the Trade Marks Journal.

    An examination objection generally requires a written response addressing the grounds raised by the Examiner. Depending on the matter, the applicant may later be called for a hearing.

    An opposition is a separate proceeding. The applicant may need to file a counterstatement and participate in the subsequent evidentiary and hearing stages. The Rules prescribe specific forms and deadlines for these proceedings.

    If you receive an examination objection, you can review Lawizer’s startup and business legal services or its trademark-related support options before deciding how to proceed.

    Common Trademark Registration Mistakes to Avoid

    Small mistakes at the beginning can create significant problems later. Founders should watch out for these common issues:

    • Skipping the trademark search: A brand may look unique but still conflict with an earlier mark.
    • Choosing a weak mark: Highly descriptive or non-distinctive marks can face registration difficulties.
    • Choosing the wrong class: Registration only protects the mark in relation to the goods or services covered by the registration.
    • Claiming prior use without evidence: A prior-use claim should be supported in accordance with the Rules.
    • Ignoring application status: Important Registry communications can have deadlines.
    • Missing opposition or response deadlines: Trademark proceedings are deadline-driven.
    • Using ® too early: Do not present an unregistered mark as registered.
    • Assuming company registration equals trademark registration: A company name and a trademark are different forms of legal protection.

    Trademark Registration vs Company Registration: What Is the Difference?

    Company registration and trademark registration protect different things.

    • Company registration creates or registers a legal business entity under the applicable corporate framework.
    • Trademark registration protects a distinctive mark used to identify particular goods or services.

    Registering a company does not automatically mean that the company’s brand name is protected as a trademark. Likewise, a trademark can sometimes be owned by an individual or other eligible proprietor without first incorporating a private limited company.

    If you are still deciding on your business structure, Lawizer’s Private Limited Company registration service may be useful alongside its trademark services.

    Why Should Founders Register a Trademark Early?

    A brand often becomes more valuable as a business grows. Marketing, customer recognition, packaging, social media presence and goodwill can all become connected with the same name or logo.

    Filing early can therefore be strategically useful once you have settled on a brand. It can help establish an earlier filing position and reduce the risk of discovering a serious conflict after significant investment in branding.

    However, early filing does not eliminate every possible issue. Prior-user rights and other statutory considerations can remain relevant, so founders should not treat filing as a substitute for a proper clearance search.

    For a broader discussion of brand protection, see Lawizer’s guide on why your brand needs trademark registration in India.

    How to Register a Trademark in India: FAQ

    Can I register a trademark myself in India?

    Yes. An eligible applicant can file a trademark application without necessarily hiring a professional. However, professional assistance can be useful when the search is complex, multiple classes are involved, prior use is claimed, or an objection or opposition arises.

    Can an individual register a trademark in India?

    Yes. Section 18 permits a person claiming to be the proprietor of a trademark to apply for registration. The applicant does not have to be a private limited company.

    Is a trademark search compulsory before filing?

    A preliminary search is an important risk-reduction step, although it should not be confused with a separate mandatory filing document. Searching helps identify earlier marks that may create problems under the Act.

    How many trademark classes do I need?

    That depends on the goods and services your business actually provides or intends to provide. If your business operates across substantially different categories, more than one class may be appropriate.

    Can I register both my brand name and logo?

    Yes, but the protection sought should be planned carefully. A word mark and a logo/device mark are different representations of your brand and may require separate applications depending on what you want protected.

    How long is a registered trademark valid in India?

    A registered trademark is valid for 10 years and can be renewed for successive 10-year periods. Section 25 provides the statutory framework for renewal and restoration.

    Lawizer also provides a trademark renewal service for businesses approaching renewal.

    What happens after I file a trademark application?

    The application is examined by the Trade Marks Registry. Depending on the outcome, it may proceed toward acceptance and Journal publication, or the applicant may need to respond to an objection. After publication, third parties have the prescribed period to oppose the application. If the registration requirements are ultimately satisfied, the mark is entered on the Register.

    What if someone already has a similar trademark?

    Do not assume that changing one letter will solve the problem. Similarity can be assessed by appearance, sound, meaning and the commercial relationship between the relevant goods or services. An earlier mark may therefore affect your application even where the names are not identical.

    What if my trademark application is refused?

    The appropriate response depends on the reason for refusal and the procedural stage. Depending on the circumstances, an applicant may have opportunities to respond, attend a hearing or pursue an available legal remedy. A refusal should therefore be assessed on its specific grounds rather than treated as an automatic end to the matter.

    Final Checklist Before Filing Your Trademark

    • Choose a distinctive brand name or mark.
    • Search existing and pending marks.
    • Identify every relevant goods/services class.
    • Decide whether you need a word mark, logo mark or both.
    • Prepare accurate applicant information.
    • Collect prior-use evidence if claiming prior use.
    • Check whether you qualify for the applicable government fee category.
    • File the correct application and pay the applicable government fee.
    • Track the application after filing.
    • Respond to Registry communications within the applicable deadlines.

    Protect Your Brand With Lawizer

    A trademark can become a long-term business asset, so the filing decision deserves more care than simply choosing a name and submitting a form. A proper search, correct classification and accurate application can reduce avoidable complications later.

    If you want professional assistance with the process, you can explore Lawizer’s trademark registration service. Lawizer also provides support for related startup legal requirements, including company, GST, MSME and other business legal services.

    You can also explore Lawizer’s legal guides and business law blog for practical information on incorporation, compliance, intellectual property and other issues faced by Indian businesses.

    Important: This article is for general information and does not constitute legal advice. Trademark registrability, fees, procedural requirements and outcomes depend on the facts of each application. Always verify the applicable requirements with the Trade Marks Registry or a qualified professional before filing.

  • Trademark Renewal Process in India

    Trademark Renewal Process in India

    Building a strong brand takes time, money and consistent effort. Once your trademark is registered, keeping that protection active is equally important. The trademark renewal process allows a registered trademark to continue beyond its initial 10-year registration period.

    In India, a registered trademark is generally valid for 10 years and can be renewed for further 10-year periods. Businesses should therefore keep track of their trademark expiry dates and complete renewal within the prescribed period.

    Missing the deadline does not always mean that the trademark is permanently lost. However, renewal after expiry can involve an additional surcharge, while a trademark already removed from the Register may require restoration and renewal.

    This guide explains the trademark renewal process in India, including the renewal timeline, Form TM-R, government fees, renewal after expiry, restoration, self-filing and common mistakes that businesses should avoid.

    What Is Trademark Renewal?

    Trademark renewal is the process of extending an existing trademark registration for another period. Section 25 of the Trade Marks Act, 1999 provides for a 10-year registration period and allows the registration to be renewed from time to time.

    Renewal is different from applying for a trademark for the first time. During registration, the applicant seeks protection for a mark that has not yet been registered. During renewal, the proprietor maintains an existing registered trademark.

    This distinction is important for businesses because a registered brand can become a valuable intellectual property asset. The proprietor should therefore keep track of the registration’s expiry date instead of assuming that protection continues automatically.

    A registered trademark can generally be renewed repeatedly for further 10-year periods, subject to the applicable legal requirements and prescribed fees.

    If you have not registered your brand yet, you can first understand how trademark registration works in India before considering renewal.

    How Long Is a Trademark Valid in India?

    A registered trademark in India is generally valid for 10 years. Section 25 of the Trade Marks Act, 1999 provides for renewal for another 10 years from the expiry of the original registration or the last renewal.

    There is no fixed maximum number of renewals. A trademark can therefore continue to be renewed repeatedly as long as the proprietor complies with the applicable requirements.

    For example, once the initial 10-year registration period approaches its expiry, the proprietor can apply for renewal and extend the registration for another 10-year period.

    The same process can be repeated in subsequent 10-year periods.

    This is particularly important for established businesses. A brand name may become one of a company’s most valuable intangible assets over time. Allowing its registration to lapse unnecessarily can create avoidable legal and commercial risks.

    Do You Need to Renew Your Trademark Every Year?

    No. Trademark registration does not have to be renewed every year.

    A registered trademark is generally valid for 10 years. Renewal is required when that registration period approaches its expiry and the proprietor wants to continue the registration.

    However, businesses should review their trademark portfolio regularly. Checking expiry dates as part of an annual compliance review can help prevent a missed renewal deadline.

    For a company with several brands, it is useful to maintain a simple intellectual property register containing each trademark’s registration number, class, proprietor and renewal date.

    When Should You Start the Trademark Renewal Process?

    Under Rule 57 of the Trade Marks Rules, 2017, an application for renewal can be made in Form TM-R at any time not more than one year before the expiration of the last registration.

    This means that businesses do not have to wait until the final weeks before expiry. Starting early gives the proprietor time to check the registration details and complete the filing correctly.

    The safest approach is to identify the renewal date well in advance and begin preparing during the permitted renewal window.

    What Happens If You Miss the Trademark Renewal Date?

    Missing the expiry date does not necessarily mean that the trademark can never be renewed.

    Section 25 of the Trade Marks Act and the applicable Rules provide mechanisms for renewal after expiry and restoration in specified circumstances.

    Where the required application and surcharge are filed within six months from expiry, the law provides a route for renewal with the applicable surcharge.

    If the mark has already been removed from the Register, restoration and renewal may be available within one year from the expiration of the last registration, subject to the statutory requirements and the Registrar’s consideration.

    Because the procedure becomes more complicated after expiry, completing the renewal before the registration expires is generally preferable.

    Trademark Renewal Process in India: Step-by-Step

    The trademark renewal process is easier to manage when the registration details are accurate and the application is filed within the permitted period.

    Step 1: Check Your Trademark Registration Details

    Start by identifying the trademark registration that needs renewal.

    Check the following details:

    • Trademark registration number
    • Proprietor’s name
    • Registered class or classes
    • Date of registration
    • Expiry date
    • Current trademark status

    If your business owns several trademarks, check each registration separately. Different registrations may have different expiry dates and classes.

    You can use the official IP India trademark search and status system to review relevant trademark information.

    Step 2: Verify the Proprietor Details

    Before filing the renewal application, check whether the proprietor’s name and other registration details are accurate.

    If the business has undergone an assignment, transfer, merger, name change or another relevant change, do not assume that renewal itself will automatically update the trademark record.

    Depending on the circumstances, a separate filing may be necessary. Reviewing the record before renewal can therefore help identify issues before the application is filed.

    Step 3: Check the Registered Class or Classes

    Trademark rights are connected with the goods or services covered by the registration. Therefore, check the class or classes in which your trademark is registered.

    If the same brand is registered in several classes, renewal fees generally apply for each class.

    Businesses should also distinguish renewal from expansion into a new class. If you have started offering a completely different category of goods or services, simply renewing the existing registration may not provide protection for that new category.

    If you are considering protecting a new brand or expanding your trademark portfolio, explore Lawizer’s trademark registration service.

    Step 4: Prepare Form TM-R

    The prescribed form for trademark renewal is Form TM-R.

    Form TM-R covers applications relating to renewal and restoration of trademark registration, including payment of the applicable surcharge where relevant.

    The proprietor or authorised person should provide the required information accurately and select the appropriate filing category.

    You can review the official Form TM-R issued by IP India before filing.

    Step 5: Pay the Applicable Government Fee

    The applicable government fee depends on the type of renewal and filing method.

    For ordinary renewal under Section 25, the current official fee is:

    • ₹9,000 per class for e-filing.
    • ₹10,000 per class for physical filing.

    If the application is being made after expiry, the prescribed surcharge is additional to the renewal fee. Restoration and renewal also involve an additional prescribed fee.

    Always check the current IP India trademark fee schedule before making payment because official fees and procedures can be updated.

    Step 6: Submit the Renewal Application

    After checking the details and paying the applicable fee, submit Form TM-R through the prescribed filing system.

    Keep the filing acknowledgement and payment details safely. These records can help demonstrate when the renewal application was filed and can make future compliance easier.

    Step 7: Track the Trademark Status

    Filing the application is not the same as completing the entire process.

    Keep track of the trademark record and any communication from the Trade Marks Registry. If the Registry raises an issue or requires further action, responding appropriately can help prevent unnecessary complications.

    The official IP India trademark status system can be used to monitor relevant information.

    Once the renewal is processed, maintain the updated records with the company’s intellectual property documents.

    Can I Renew My Trademark Myself?

    Yes. A trademark proprietor can generally undertake the renewal filing themselves.

    For a straightforward renewal where the trademark is active, the proprietor’s details are correct and the application is being filed within the permitted period, self-filing may be practical.

    However, professional assistance can be useful where the trademark has expired, has been removed from the Register or involves ownership and record-related complications.

    When Should You Consider Professional Assistance?

    Professional assistance may be particularly useful when:

    • The trademark registration has already expired.
    • The trademark has been removed from the Register.
    • The matter requires restoration and renewal.
    • There has been an assignment or ownership change.
    • The proprietor’s details need to be changed or corrected.
    • The business owns multiple registrations or classes.
    • You are unsure which renewal option applies.
    • There is correspondence or an issue pending before the Trade Marks Registry.

    How Much Does It Cost to Renew a Trademark?

    Trademark renewal fees are prescribed by the Trade Marks Rules and the applicable official fee schedule.

    For a standard renewal under Section 25, the current official fee is:

    • ₹9,000 per class for e-filing
    • ₹10,000 per class for physical filing

    These are government fees. If you use a professional service, the service provider may charge a separate professional or facilitation fee.

    What If You Renew Your Trademark After Expiry?

    If the renewal is filed within six months after expiry, the applicable renewal fee is accompanied by the prescribed surcharge.

    The current official fee schedule provides a surcharge of:

    • ₹4,500 per class for e-filing
    • ₹5,000 per class for physical filing

    This is in addition to the applicable renewal fee.

    Therefore, delaying renewal can increase the overall cost.

    What If the Trademark Has Been Removed?

    Where restoration and renewal are sought after removal, an additional restoration-related fee applies.

    The current fee schedule provides a restoration and renewal fee of ₹9,000 for e-filing or ₹10,000 for physical filing per class, in addition to the applicable renewal fee.

    Because fees and filing requirements can change, always verify the amount on the current IP India official fees page before making payment.

    How Long Does the Trademark Renewal Process Take?

    There is no single guaranteed processing time that applies to every trademark renewal.

    The time involved can depend on:

    • Completeness of the application
    • Accuracy of the information provided
    • Payment of the correct fee
    • Registry processing
    • Any discrepancy in the records
    • Whether additional action is required

    A straightforward renewal filed within the permitted period is generally less complicated than a matter involving expiry, restoration, ownership changes or other issues.

    For this reason, businesses should avoid planning their compliance around a last-minute filing.

    The important deadline is the statutory expiry date, not an estimated processing date.

    What Happens If You Do Not Renew Your Trademark?

    If the prescribed renewal requirements are not completed, the Registrar may remove the trademark from the Register in accordance with Section 25.

    The Trade Marks Rules also provide procedures relating to removal and publication of the fact of removal, subject to the applicable statutory provisions.

    This is why allowing a registration to lapse can create unnecessary legal and administrative complications.

    A business may also have to consider additional fees and restoration procedures if it does not act within the relevant post-expiry period.

    Can You Restore an Expired Trademark?

    There are different situations to distinguish.

    First, a proprietor may seek renewal after expiry within the applicable six-month period by paying the renewal fee and prescribed surcharge.

    Second, where the trademark has been removed from the Register for non-payment, Section 25(4) provides for restoration and renewal after six months and within one year from the expiration of the last registration, subject to the statutory conditions.

    Rule 60 further provides for an application for restoration and renewal in Form TM-R within one year from the expiration of the registration, along with the prescribed fee.

    The Registrar must also consider the interests of other affected persons.

    Because restoration involves additional statutory requirements, businesses should not treat it as an equivalent substitute for timely renewal.

    Trademark Renewal vs Trademark Registration

    Renewal and registration are related but different legal processes.

    • Trademark registration: The initial process of seeking registration of a brand name, logo, symbol or another eligible mark.
    • Trademark renewal: The process of extending an existing registered trademark for another 10-year period.
    • Trademark restoration: A mechanism that may apply when a trademark has been removed from the Register for failure to renew within the applicable period.

    If you are researching the initial registration stage, Lawizer’s trademark registration guide for founders explains the broader registration journey.

    Common Mistakes to Avoid During Trademark Renewal

    1. Assuming Renewal Is Annual

    A registered trademark generally has a 10-year term.

    However, businesses should still review their trademark portfolio regularly so that expiry dates are not forgotten.

    2. Waiting Until After Expiry

    Post-expiry renewal can involve an additional surcharge.

    Waiting longer can also create restoration issues. Early action is therefore preferable.

    3. Checking Only the Brand Name

    Do not rely only on the spelling of the brand.

    Check the registration number, proprietor, class and other relevant particulars before filing.

    4. Ignoring Multiple Classes

    If your brand is registered in multiple classes, make sure the renewal covers the registrations that actually require renewal.

    Fees may apply separately to each class.

    5. Assuming Renewal Updates Ownership

    Renewal does not automatically resolve every ownership or record-related issue.

    If there has been an assignment or another change, the appropriate separate procedure may need to be followed.

    6. Forgetting to Maintain Records

    Keep the filing acknowledgement, payment details and updated trademark records together.

    This makes future renewals easier to manage.

    Trademark Renewal Checklist for Indian Businesses

    Before starting the renewal, check the following:

    • Trademark registration number
    • Expiry date
    • Proprietor’s name and details
    • Registered class or classes
    • Current trademark status
    • Any pending ownership or record changes
    • Whether the renewal is being filed before or after expiry
    • Correct Form TM-R
    • Current government fee
    • Filing acknowledgement
    • Payment receipt
    • Application status

    Once the renewal is completed, record the next renewal date in your business compliance calendar.

    Why Timely Trademark Renewal Matters for Founders

    A trademark is more than a registration number.

    For many businesses, it represents the name customers recognise, the reputation the company has built and the goodwill associated with its products or services.

    Keeping the registration active helps preserve the statutory rights associated with the registered mark.

    Section 28 of the Trade Marks Act provides, subject to the Act and applicable conditions, that registration gives the registered proprietor exclusive rights to use the trademark in relation to the registered goods or services and to seek relief for infringement.

    That makes trademark renewal an important part of long-term brand management.

    Founders should therefore treat trademark expiry dates as part of their intellectual property compliance calendar rather than as a task to remember only once every decade.

    Frequently Asked Questions About Trademark Renewal

    Can I renew my trademark myself?

    Yes. A proprietor can file the renewal application themselves.

    The process generally involves checking the registration, completing Form TM-R and paying the applicable government fee.

    Professional assistance may be useful for expired registrations, restoration or complicated record issues.

    How much does it cost to renew a trademark?

    The current official fee for ordinary renewal is ₹9,000 per class for e-filing and ₹10,000 per class for physical filing.

    Additional surcharge or restoration fees may apply where renewal is delayed or restoration is required.

    How long does it take to renew a trademark?

    There is no single guaranteed processing period for every case.

    A straightforward application may be simpler to process than a matter involving expiry, restoration, ownership changes or other issues.

    Businesses should therefore file well before the deadline.

    Do I need to renew my trademark every year?

    No.

    A registered trademark is generally valid for 10 years and can be renewed for further 10-year periods.

    Businesses should nevertheless monitor their portfolio regularly so that the renewal date is not missed.

    What happens if I miss my trademark renewal date?

    If the renewal deadline is missed, the law provides a limited post-expiry route involving the renewal fee and prescribed surcharge.

    If the mark has been removed from the Register, restoration and renewal may be available within the statutory period, subject to the applicable requirements.

    Can I renew my trademark after it expires?

    Yes, in specified circumstances.

    Section 25 and Rule 59 provide a route for renewal with surcharge where the required application is made within six months from expiry.

    If the mark has been removed, restoration and renewal may be sought within one year from expiry under the applicable provisions.

    How early can I renew my trademark?

    Under Rule 57 of the Trade Marks Rules, 2017, an application for renewal may be made at any time not more than one year before the expiration of the last registration.

    Which form is used for trademark renewal?

    Trademark renewal is filed using Form TM-R.

    The form also covers renewal after expiry and restoration and renewal, depending on the circumstances.

    Related Lawizer Resources

    If you are managing your brand’s wider legal protection, these Lawizer resources may also help:

    Keep Your Brand Protection Active

    The trademark renewal process is a recurring legal requirement that should not be overlooked simply because the renewal date may be many years apart.

    For most businesses, the safest approach is simple: know your expiry date, verify your registration details, file the appropriate Form TM-R, pay the correct fee and keep the renewal records safely.

    If your trademark has already expired, has been removed from the Register or has complicated ownership or record issues, the appropriate procedure may be different.

    In such cases, getting professional guidance can help you understand the available options.

    Need help with your trademark renewal? Lawizer can assist businesses with trademark-related legal processes and help you understand the appropriate next step for maintaining your brand protection.

    Explore Lawizer’s trademark services or visit Lawizer to explore legal services for startups and growing businesses.

    Disclaimer: This article is for general informational purposes and does not constitute legal advice. Trademark fees, forms, procedures and Registry requirements may change. Always verify the latest requirements and fees on the official IP India website before filing.

  • How to Protect Your Brand Name in India

    How to Protect Your Brand Name in India

    How to protect your brand name is an important question for every founder, business owner and creator building a long-term business in India. Your brand name may become one of your most valuable business assets. It helps customers identify your products or services and distinguishes your business from competitors.

    However, simply choosing a name, registering a domain or incorporating a company does not automatically give you comprehensive trademark protection. If another business adopts a similar name, you may face customer confusion, marketplace disputes or costly legal proceedings.

    The most practical way to protect a distinctive brand name in India is to consider trademark protection early. A proper search, correctly chosen trademark class, timely filing and continued monitoring can significantly reduce the risk of disputes.

    Why Should You Protect Your Brand Name?

    A brand name is more than a marketing asset. Over time, customers may associate the name with the quality, reputation and goodwill of your business. If another business uses a confusingly similar name, your customers may mistake one business for the other.

    Trademark law provides a framework for protecting distinctive marks used in connection with goods and services. The main legislation is the Trade Marks Act, 1999.

    Registering a trademark can provide important legal advantages, including stronger rights against infringement and clearer evidence of ownership.

    Before investing heavily in packaging, advertising, social media campaigns or a website, it is therefore sensible to determine whether the proposed brand name is available for protection.

    How to Protect Your Brand Name Before Launching

    Brand protection should ideally begin before you spend significant money building the brand. A basic pre-launch process can help you identify potential problems early.

    1. Choose a Distinctive Brand Name

    A strong brand name should be capable of distinguishing your goods or services from those of other businesses. Highly descriptive or generic terms can be difficult to protect as trademarks.

    For example, a highly distinctive coined word may generally have stronger trademark potential than a name that merely describes the product or service.

    When developing a name, consider:

    • Whether the name is distinctive.
    • Whether it is easy to remember and pronounce.
    • Whether similar names already exist in your industry.
    • Whether the name has unwanted meanings in important markets.
    • Whether the corresponding domain and social media handles are reasonably available.
    • Whether you intend to expand into additional products or services.

    Choosing a distinctive name at the beginning is usually easier than changing your brand after customers have already become familiar with it.

    2. Search Existing Trademarks

    One of the most important steps in protecting a new brand is conducting a trademark search before filing an application.

    The official IP India website provides a trademark search facility through which applicants can investigate existing marks.

    Do not search only for an exact spelling. A proper preliminary review should also consider marks that may be visually, phonetically or conceptually similar, particularly when they cover related goods or services.

    This is important because a brand name can face problems even when it is not identical to an existing trademark.

    Does Registering a Company Name Protect Your Brand?

    No. Company registration and trademark registration are separate forms of legal protection.

    For example, registering a company with a particular name through the Ministry of Corporate Affairs does not automatically give you exclusive trademark rights over the brand name for your products or services.

    This distinction is often misunderstood by new entrepreneurs.

    A company name primarily identifies the legal entity. A trademark identifies the source of particular goods or services and protects the brand used in commerce.

    Lawizer also explains this distinction in its guide on Private Limited Company Registration in India.

    If you are incorporating a business and have already selected your brand, consider checking trademark availability as part of the same early-stage legal process.

    How to Protect Your Brand Name Through Trademark Registration

    Trademark registration is one of the most important legal steps for businesses that want to establish stronger protection for their brand identity.

    The Trade Marks Registry administers trademark registration under the Trade Marks Act, 1999 and the Trade Marks Rules, 2017. The Registry maintains the Register of Trade Marks and examines applications that meet the legal requirements.

    You can review the official Trade Marks Act and related resources on the IP India website.

    Step 1: Conduct a Trademark Search

    Start by searching the proposed brand name and relevant similar marks.

    The search should be considered alongside the goods or services for which you intend to use the name. Trademark protection is connected to the goods or services covered by the registration.

    A name that appears available in one area may create problems in another if a similar mark already exists for related goods or services.

    Step 2: Identify the Correct Trademark Class

    Trademark applications are filed in relation to specific goods or services. India follows the international classification system for goods and services.

    Choosing the correct class is therefore an important part of the application.

    For example, a business selling clothing and a business providing software services may require protection in different classes. A business operating across multiple categories may need to consider more than one class.

    Do not select a class solely because another business has used it. The correct classification depends on the actual goods or services connected with your brand.

    Step 3: File the Trademark Application

    Once the name and applicable class or classes have been considered, a trademark application can be filed with the Trade Marks Registry.

    Trademark applications are generally filed using Form TM-A. The application contains information such as the applicant’s details, the mark and the goods or services covered by the application.

    The official IP India fee schedule currently lists different government filing fees depending on the applicant category. For e-filing, the listed fee is ₹4,500 per mark per class for individuals, startups and small enterprises, and ₹9,000 per mark per class for other applicants. Fees can change, so applicants should verify the current official trademark fees before filing.

    Lawizer’s Trademark Registration service separately lists its facilitation charges, with government charges additional.

    Step 4: Respond to Examination

    After filing, the application is examined by the Trade Marks Registry.

    An examiner may raise objections if the mark does not satisfy the legal requirements or if there are concerns relating to existing marks. Common issues may involve distinctiveness or similarity with an earlier mark.

    An objection does not necessarily mean that your trademark application has failed. The applicant may have an opportunity to respond to the examination report within the prescribed period and may also be required to attend a hearing.

    If your application receives an objection, Lawizer provides a dedicated Trademark Objection Reply service.

    You can also read Lawizer’s detailed guide on how to file a trademark objection reply in India.

    Step 5: Publication and Opposition

    If the application progresses beyond examination, it may be published in the Trade Marks Journal.

    Publication gives third parties an opportunity to oppose the registration within the period prescribed under the applicable law and rules.

    If no opposition is filed within the prescribed period, the application may proceed towards registration, subject to the applicable requirements.

    If an opposition is filed, the matter can involve pleadings, evidence and hearings. The timeline can therefore become considerably longer.

    Step 6: Registration and Renewal

    Once the application successfully completes the registration process, the Registrar issues the registration certificate.

    A registered trademark is generally valid for 10 years and can be renewed for further periods in accordance with the law.

    Businesses should therefore maintain a record of renewal deadlines and monitor the continued use of their trademark.

    Lawizer also provides a Trademark Renewal service for businesses that need assistance with maintaining their registration.

    How to Protect Your Brand Name Without Trademark Registration

    Trademark registration is usually the strongest practical route for protecting a brand name, but businesses should also take other preventive measures.

    These steps do not replace trademark registration, but they can strengthen your overall brand-protection strategy.

    • Use the brand consistently across your products and business communications.
    • Maintain dated records showing when you began using the brand.
    • Keep invoices, packaging, advertisements and promotional materials showing genuine commercial use.
    • Secure relevant domain names where commercially appropriate.
    • Reserve important social media handles where available.
    • Use written agreements with agencies, designers and freelancers dealing with your brand assets.
    • Monitor marketplaces and online platforms for potentially infringing uses.
    • Consider trademark registration before substantial investment in the brand.

    Evidence of use can become relevant in certain trademark disputes, particularly where questions of prior use or goodwill arise. However, relying solely on unregistered rights can be more complicated than having a registered trademark.

    Can Copyright Protect Your Brand Name?

    Copyright and trademark protection serve different purposes.

    A brand name itself is generally approached through trademark law rather than copyright law. However, the creative elements associated with a brand may raise separate copyright considerations.

    For example, original artwork, illustrations, photographs, written content or certain creative logo elements may qualify for copyright protection depending on the circumstances.

    Lawizer provides a separate Copyright Registration service for protecting eligible creative works.

    Businesses should therefore consider whether they need one form of intellectual property protection or a combination of protections.

    How to Protect Your Brand Name From Infringement

    Registration is only one part of brand protection. Once your trademark application or registration exists, you should continue watching for potentially confusing uses.

    Regular monitoring can help you identify:

    • New businesses using a similar name.
    • Similar trademark applications.
    • Counterfeit products.
    • Unauthorised use of your logo or brand identity.
    • Confusingly similar social media accounts.
    • Marketplace listings that appear to imitate your brand.

    Early action can be important. Depending on the facts, possible responses may include sending a legal notice, requesting removal from an online platform, opposing a conflicting trademark application or pursuing appropriate legal proceedings.

    The correct response depends on the nature of the infringement, the status of your trademark and the evidence available.

    What Happens If Someone Uses Your Brand Name?

    If another business starts using your brand name or a confusingly similar mark, do not immediately assume that registration guarantees an automatic result.

    The legal position depends on factors such as the marks involved, the goods or services, the nature of the use, the relevant dates, the strength of the mark and the evidence of confusion or goodwill.

    A registered proprietor may have remedies for trademark infringement under the applicable provisions of the Trade Marks Act, while unregistered marks may in appropriate circumstances be protected through the common-law action of passing off.

    Because trademark disputes can become fact-specific, businesses should obtain legal advice before sending threats or commencing proceedings.

    How Much Does It Cost to Protect a Brand Name?

    The total cost depends on the type of protection, applicant category, number of classes, professional or facilitation charges and whether the application faces objections or opposition.

    Government trademark fees are generally calculated per mark and per class. Additional professional costs may apply when a business uses legal or trademark filing assistance.

    For this reason, there is no single universal price for protecting every brand.

    Before filing, check the current official fee schedule and obtain a clear breakdown of government fees and professional or facilitation charges.

    How Long Does Brand Name Protection Take?

    Trademark registration is not an instant process. It involves filing, examination and, where applicable, publication and opposition proceedings before registration.

    An uncontested application may progress within several months, but actual timelines vary depending on examination, objections, hearings, opposition and the workload of the Registry.

    Applications facing objections or opposition can take substantially longer.

    Therefore, businesses should not make major commercial decisions based on an assumed fixed registration date.

    Common Mistakes When Protecting a Brand Name

    Using the Name Before Checking Availability

    Launching a brand without conducting a trademark search can lead to expensive rebranding if an earlier conflicting mark is discovered later.

    Assuming Company Registration Is Enough

    Registering a company or LLP name does not replace trademark registration. These are different legal processes with different purposes.

    Choosing the Wrong Trademark Class

    A trademark application must accurately identify the goods or services for which protection is sought. Incorrect classification can limit the practical value of the registration.

    Ignoring Similar Marks

    Searching only for identical names is not enough. Similarity can arise from spelling, pronunciation, appearance or the overall commercial impression.

    Forgetting to Monitor the Trademark

    Obtaining registration does not mean you should stop watching the market. Businesses should monitor potential conflicts and respond appropriately when necessary.

    Using the ® Symbol Too Early

    The ® symbol should not be used as though a mark is registered before registration has actually been obtained. Businesses using an unregistered mark commonly use the ™ symbol instead.

    Brand Protection Checklist for Indian Businesses

    • Choose a distinctive brand name.
    • Search existing trademarks.
    • Review similar marks, not only identical marks.
    • Identify the correct goods and services classes.
    • Consider whether the brand should be protected in more than one class.
    • Consider registering the word mark and relevant logo separately where appropriate.
    • File the trademark application as early as commercially sensible.
    • Keep evidence of genuine brand use.
    • Monitor applications and marketplace activity.
    • Respond promptly to objections or legal notices.
    • Track the trademark renewal date.

    Frequently Asked Questions About Protecting a Brand Name

    How do I legally protect my brand name in India?

    The main route is to seek trademark registration for the brand name in the relevant goods or services classes. Before filing, conduct a proper search and assess whether the mark is distinctive and conflicts with earlier marks.

    Can I trademark my business or brand name?

    Yes, a name may be eligible for trademark protection if it satisfies the legal requirements. The proposed mark must be considered in relation to the goods or services for which protection is sought.

    Is trademark registration mandatory to use a brand name?

    No. A business may use an unregistered mark, and certain rights may arise from use. However, registration can provide stronger and clearer statutory protection and is generally advisable for a brand that is intended to grow.

    Does registering a company name protect the brand?

    No. Company or LLP name registration and trademark registration are separate. Registering an entity name does not automatically provide comprehensive trademark rights over the brand.

    How can I check whether a brand name is already registered?

    You can use the official IP India trademark search facility to search existing marks. A professional search should also consider potentially similar marks and the relevant goods or services.

    How much does trademark registration cost in India?

    The government fee depends on the applicant category and the number of marks and classes involved. Professional or facilitation charges are separate. Always verify the current government fee schedule before filing.

    How long does trademark registration take?

    There is no guaranteed fixed timeline. The process may take several months and can take longer if an objection, hearing or opposition arises.

    What if my trademark application is objected to?

    A trademark objection is not necessarily a final rejection. The applicant can respond to the examination report within the prescribed period and may need to attend a hearing depending on the case.

    Can copyright protect my brand logo?

    Copyright and trademark law protect different interests. Original artistic or creative elements may qualify for copyright protection, while trademark registration is generally the principal form of protection for a brand identifier used to distinguish goods or services.

    Can I protect my brand name without registering a trademark?

    You can take practical measures such as maintaining evidence of use, securing domains and monitoring the market. In appropriate cases, unregistered marks may also receive protection through passing-off principles. However, these rights can be more difficult to establish and enforce than registered trademark rights.

    Protect Your Brand Before It Becomes a Problem

    Your brand may take years to build, but a trademark conflict can disrupt it much faster. The safest approach is to consider intellectual property protection before investing heavily in marketing, packaging and customer acquisition.

    Start with a trademark search, identify the right classes and assess whether registration is appropriate for your business. Once filed, keep track of the application and respond promptly to any objection or opposition.

    If you need help with the process, Lawizer can assist with trademark registration and brand protection, including filing and application support.

    Want to protect your brand name? Consult Lawizer to understand the appropriate trademark strategy for your business before you invest further in building the brand.

    Explore Lawizer’s legal services for businesses or get professional assistance with your trademark application.

    Useful Resources

  • Private Limited Registration in India: Complete Guide, Process, Documents & FAQs

    Private Limited Registration in India: Complete Guide, Process, Documents & FAQs

    Starting a business is exciting, but choosing the right legal structure is one of the first important decisions an entrepreneur has to make.

    For startups, growing businesses and founders who may want to raise investment in the future, private limited registration is one of the most popular business registration options in India.

    A Private Limited Company is a separate legal entity from its shareholders. It can own property, enter into contracts, open bank accounts, raise capital and conduct business in its own name. The Companies Act, 2013 permits two or more persons to form a private company by subscribing to its memorandum and complying with the applicable incorporation requirements.

    But how exactly does private limited registration work?

    What documents are required? How many directors and shareholders are needed? Is GST mandatory? Can you register the company yourself? And is a Private Limited Company better than an LLP or OPC?

    This guide explains the private limited registration process in India, the documents required, basic eligibility, costs, post-incorporation requirements and the most common questions founders ask before registering their company.

    What is a Private Limited Company?

    A Private Limited Company is a company incorporated under the Companies Act, 2013 and is treated as a separate legal entity from its members.

    The word “Private” means that the company’s shares are subject to restrictions prescribed by law and its Articles of Association, and the company does not invite the public to subscribe to its securities in the same manner as a public company.

    For entrepreneurs, one of the biggest advantages is limited liability. Generally, the liability of shareholders is limited to the amount unpaid on the shares held by them.

    A Private Limited Company can also provide a more structured ownership framework for businesses that intend to bring in co-founders, investors or employees through equity-based arrangements.

    Who Can Register a Private Limited Company?

    Generally, a Private Limited Company requires at least:

    • 2 shareholders
    • 2 directors
    • 1 resident director meeting the applicable residency requirement
    • A registered office address in India
    • A proposed company name
    • A lawful business object

    The shareholders and directors can be the same individuals.

    For example, two founders can incorporate a company where both founders are shareholders and both are appointed as directors.

    A person who wants to operate completely alone may instead consider an One Person Company (OPC), subject to the applicable eligibility requirements.

    Why Choose a Private Limited Company?

    Private limited registration is particularly popular among startups and businesses that expect to grow.

    1. Limited liability

    One of the primary advantages is limited liability protection for shareholders, subject to the applicable provisions of law.

    This creates a separation between the company’s liabilities and the personal assets of its shareholders in ordinary circumstances.

    2. Separate legal identity

    The company has its own legal identity.

    It can enter into agreements, own assets, borrow money and conduct business independently from its individual shareholders.

    3. Better structure for fundraising

    If your business plans to raise angel investment, venture capital or other equity funding, a Private Limited Company is often a suitable structure because ownership can be represented through shares.

    Investors can acquire shares in the company without the business necessarily having to change its fundamental legal structure.

    4. Easier ownership structuring

    A Private Limited Company allows founders to clearly document their ownership through shareholding.

    This can be particularly useful when there are multiple founders or when investors may join later.

    5. Professional credibility

    Registration as a company can provide a formal corporate structure when dealing with customers, vendors, banks, investors and other stakeholders.

    However, registration alone does not guarantee credibility. Proper accounting, taxation and annual compliance remain essential.

    6. Continuity

    A company has a legal existence independent of changes in its individual shareholders or directors, subject to applicable law.

    This makes the structure more suitable for businesses intended to continue beyond the involvement of one particular founder.

    Private Limited Registration: Basic Eligibility and Requirements

    Before starting the incorporation process, founders should check a few basic requirements.

    Minimum shareholders

    A Private Limited Company generally requires at least two members.

    There is no requirement that every shareholder must also be a director.

    Minimum directors

    A Private Limited Company generally requires at least two directors.

    The directors must satisfy the requirements under the Companies Act, 2013 and related rules.

    Resident director

    The company must have at least one director who satisfies the applicable requirement of staying in India for the prescribed period.

    Founders should check the residency requirement applicable to their incorporation circumstances rather than assuming that any director automatically qualifies.

    Registered office

    The company must have a registered office capable of receiving official communications.

    A residential property can potentially be used as the registered office if the relevant address and supporting documents satisfy the applicable requirements.

    Proposed name

    The company needs a name that complies with the naming requirements under the Companies Act and related rules.

    A proposed name may be rejected if it is too similar to an existing company or LLP, conflicts with a registered trademark or otherwise violates the applicable naming requirements.

    Documents Required for Private Limited Registration

    The exact documents can vary depending on the promoters, registered office and circumstances of incorporation.

    For Indian individual promoters, the commonly required documents include:

    For directors and shareholders

    • PAN card
    • Identity proof
    • Address proof
    • Recent photograph
    • Mobile number
    • Email address
    • Residential address details
    • Digital Signature Certificate where required

    Acceptable identity and address documents should be checked against the current MCA requirements before filing.

    For the registered office

    Commonly required documents may include:

    • Proof of ownership or authorised occupancy
    • Recent utility bill or other prescribed address proof
    • Rent or lease agreement, where applicable
    • No-objection certificate from the owner, where applicable

    The registered office documentation should match the address provided in the incorporation application.

    Step-by-Step Private Limited Registration Process

    The incorporation process is primarily completed through the MCA’s online incorporation framework.

    Step 1: Decide the business structure

    Before filing anything, decide whether a Private Limited Company is actually suitable for your business.

    Consider:

    • Number of founders
    • Planned investment
    • Ownership structure
    • Compliance requirements
    • Expected turnover
    • Future fundraising
    • Employee stock options
    • Whether outside investors may join

    A Private Limited Company is not automatically the best structure for every business.

    Step 2: Finalise the proposed company name

    Choose a suitable company name and check whether it is likely to be available.

    The name should comply with the applicable MCA naming rules and should also be checked from a trademark perspective.

    A company name being available on the MCA portal does not necessarily mean that the corresponding trademark is available.

    Step 3: Obtain Digital Signature Certificates

    Digital signatures are used for electronically signing incorporation documents and related filings.

    The applicable subscribers and directors may need valid DSCs depending on the filing structure.

    Step 4: File SPICe+ Part A

    SPICe+ is the MCA’s electronic incorporation framework.

    Part A is used for name reservation.

    The applicant provides details such as the proposed company name and business activity/NIC classification.

    Where applicable, supporting documents may also need to be submitted.

    Step 5: Complete SPICe+ Part B

    Once the incorporation application proceeds to Part B, detailed information regarding the proposed company is submitted.

    This can include:

    • Company structure
    • Registered office
    • Subscribers
    • Directors
    • Share capital
    • PAN and TAN information
    • Other incorporation details
    • Required declarations and attachments

    The MCA’s SPICe+ documentation divides Part B into multiple sections covering company structure, address, subscribers/directors, stamp duty, PAN/TAN, attachments and declarations.

    Step 6: File linked forms

    Depending on the company and its circumstances, linked forms can include:

    • e-MOA
    • e-AOA
    • AGILE-PRO-S
    • INC-9, where applicable

    The MCA’s current SPICe+ FAQs specify the sequence for uploading the relevant linked forms.

    Step 7: Pay government fees and stamp duty

    The applicable government fees and stamp duty depend on factors such as the company’s authorised capital and the state in which the registered office is situated.

    Therefore, there is no single government fee applicable to every Private Limited Company.

    Step 8: MCA examination and approval

    After submission, the Registrar of Companies examines the incorporation application.

    If the application satisfies the applicable requirements, the company is incorporated.

    If there are deficiencies, the application may require correction or resubmission.

    Step 9: Receive the Certificate of Incorporation

    Once approved, the company receives its Certificate of Incorporation (COI).

    The company is then legally incorporated and receives its Corporate Identity Number (CIN).

    PAN and TAN are also integrated into the incorporation process where applicable.

    How Much Does Private Limited Registration Cost?

    The cost of private limited registration generally consists of several components rather than one universal amount.

    These can include:

    • Government filing fees
    • State stamp duty
    • Digital Signature Certificate charges
    • Professional or facilitation fees
    • Any additional services requested by the founders

    The government component can vary depending on factors such as authorised capital and the state of incorporation.

    Therefore, founders should compare the total cost, not just an advertised professional fee.

    It is also important to check whether government charges, DSC charges and additional services are included in a quoted package.

    Is GST Mandatory for a Private Limited Company?

    No. GST registration is not automatically mandatory simply because a business is incorporated as a Private Limited Company.

    GST applicability depends on the nature of the business, turnover, supplies, state and other conditions prescribed under GST law.

    For example, a newly incorporated company may exist without immediately becoming liable for GST registration if the applicable conditions for mandatory registration are not triggered.

    However, certain businesses may require GST registration even in circumstances where the general turnover threshold would otherwise be relevant.

    Therefore, GST should be evaluated separately after incorporation rather than treating it as an automatic consequence of company registration.

    Can I Register a Private Limited Company Myself?

    Yes, it is possible to initiate and complete incorporation through the MCA’s online system if you understand the applicable requirements and can correctly prepare the forms and supporting documents.

    However, incorporation involves more than simply filling out an online form.

    You need to correctly handle:

    • Name selection
    • Business activity classification
    • Share capital
    • Director details
    • Registered office documentation
    • MOA and AOA
    • Digital signatures
    • Linked forms
    • Declarations
    • Government fees
    • Resubmission, if required

    A mistake in the incorporation application can result in rejection, resubmission or unnecessary delays.

    For founders unfamiliar with MCA filings, professional assistance can simplify the process and reduce documentation errors.

    Private Limited Company vs LLP: Which is Better?

    There is no universally better structure. The right choice depends on your business model.

    Private Limited Company

    Generally more suitable when you:

    • Want to raise equity investment
    • Expect multiple investors
    • Want a share-based ownership structure
    • Plan to build a scalable startup
    • May consider ESOPs
    • Want a conventional corporate structure

    LLP

    An LLP can be attractive where:

    • Partners want operational flexibility
    • The business is professional or partnership-oriented
    • Equity investment is not the immediate objective
    • The founders prefer an LLP structure

    If your long-term plan includes venture capital or significant equity fundraising, a Private Limited Company is often the more practical structure to evaluate.

    Private Limited Company vs OPC

    An OPC is designed for a single-member structure, while a Private Limited Company generally requires at least two members.

    An OPC can be useful for a solo entrepreneur who wants a corporate form without immediately bringing in another shareholder.

    A Private Limited Company may be more suitable where:

    • There are two or more founders
    • You expect investors
    • You want multiple shareholders
    • You may issue or transfer shares
    • You expect the business to scale significantly

    The decision should be based on the founder’s current structure as well as future plans.

    Private Limited Company vs Limited Company

    A “Limited Company” can refer broadly to a company with limited liability, but in common Indian business usage, entrepreneurs often use “Private Limited Company” to distinguish it from a public limited company.

    A Private Limited Company generally has restrictions on the transfer of shares and does not invite the public to subscribe to its securities.

    A public company has a different legal and regulatory framework and may be more appropriate for businesses that require access to public capital markets, subject to the applicable requirements.

    For most early-stage startups and privately held businesses, Private Limited registration is generally the more relevant structure to consider.

    What Happens After Private Limited Registration?

    Getting the Certificate of Incorporation is not the end of the compliance process.

    It is the beginning.

    After incorporation, founders should consider:

    1. Open the company’s bank account

    The company should operate through its own bank account rather than mixing company transactions with personal accounts.

    2. Bring in subscribed capital

    The subscribers should contribute the capital they have agreed to contribute to the company.

    3. Check commencement requirements

    Companies having share capital are required to comply with the applicable declaration regarding commencement of business and exercising borrowing powers under Section 10A and the prescribed form.

    The MCA’s INC-20A framework provides for the commencement declaration and specifies the applicable filing timeline.

    4. Appoint the first auditor

    The company must comply with the applicable requirements relating to appointment of its auditor.

    5. Maintain statutory records

    Companies need to maintain appropriate registers, books and corporate records.

    6. Complete annual ROC compliance

    Private Limited Companies have continuing annual compliance obligations.

    Depending on the company and its circumstances, these can include financial statement filing, annual return filing, income-tax compliance, auditor-related compliance and other applicable filings.

    Incorporation is therefore not a one-time compliance event.

    Common Mistakes to Avoid During Private Limited Registration

    Choosing a name without checking trademarks

    MCA name approval and trademark protection are separate issues.

    Before finalising your company name, conduct an appropriate trademark search.

    Using incorrect registered office documents

    An incorrect address, outdated proof or missing consent documentation can create problems during incorporation.

    Selecting the wrong business activity

    The company’s business activity and NIC classification should accurately reflect its proposed operations.

    Ignoring post-incorporation compliance

    Some founders believe that receiving the Certificate of Incorporation means all legal work is finished.

    It does not.

    A company must continue complying with applicable corporate, tax and regulatory requirements.

    Looking only at the cheapest registration package

    The lowest advertised incorporation fee may not represent the lowest total cost.

    Always check what is included and whether government charges, DSCs and post-incorporation assistance are covered.

    Frequently Asked Questions

    Who is the owner of a Private Limited Company?

    A Private Limited Company is owned by its shareholders.

    The shareholders own shares in the company, while directors are responsible for managing the company’s affairs in accordance with the Companies Act, the Articles of Association and applicable decisions of the company.

    The person running the company is therefore not necessarily its “owner”.

    For example, a founder may be both a shareholder and director, but the legal ownership of the company is represented through shareholding.

    Can one person start a Private Limited Company?

    A conventional Private Limited Company generally requires at least two members.

    If an individual wants to establish a company alone, an OPC may be an alternative subject to applicable eligibility requirements.

    Is GST mandatory for a Private Limited Company?

    No.

    Private limited registration by itself does not automatically make GST registration mandatory.

    GST registration depends on the applicable GST provisions, including turnover, nature of supply and other prescribed conditions.

    Can I register a Private Limited Company myself?

    Yes.

    The MCA provides an online incorporation mechanism through SPICe+.

    However, the process requires careful preparation of company details, documents, declarations and linked forms.

    Professional assistance can be useful if you are unfamiliar with MCA incorporation procedures.

    Who is eligible to register a Private Limited Company?

    Generally, two or more persons can form a Private Limited Company subject to the requirements of the Companies Act, 2013 and applicable rules.

    The proposed directors and shareholders must satisfy the relevant legal and documentation requirements.

    Which is better: LLP or Private Limited Company?

    It depends on the business.

    An LLP may be suitable for businesses seeking partnership-style flexibility, while a Private Limited Company is often preferred by startups expecting equity investment, multiple shareholders or significant scaling.

    Which company is better: Limited or Private Limited?

    The answer depends on your objectives.

    A Private Limited Company is generally suitable for privately held startups and growing businesses, whereas a public company follows a different regulatory framework and may be appropriate for businesses seeking public investment, subject to eligibility.

    How many members are there in a Private Limited Company?

    A Private Limited Company generally requires at least two members.

    The maximum number of members is generally 200, subject to the applicable provisions of the Companies Act, 2013.

    Is a Private Limited Company better than an OPC?

    Not necessarily.

    An OPC can be appropriate for a single founder, while a Private Limited Company can be more suitable when there are multiple founders or when the business expects to bring in investors and shareholders.

    Can a Private Limited Company become an OPC?

    A company cannot simply be treated as an OPC whenever it wants.

    The applicable conversion and eligibility provisions must be examined based on the company’s circumstances and the Companies Act and rules in force at that time.

    What is the difference between an LLC and a Private Limited Company?

    LLC generally refers to a Limited Liability Company, a business structure commonly associated with jurisdictions such as the United States.

    India has its own corporate structures, including Private Limited Companies and LLPs.

    Therefore, an entrepreneur in India should generally compare a Private Limited Company with an LLP or other Indian business structures rather than treating an American LLC and an Indian Private Limited Company as identical entities.

    What are the disadvantages of a Private Limited Company?

    Some common disadvantages include:

    • More compliance than an informal business structure
    • Annual ROC filings
    • Maintenance of corporate records
    • Accounting and audit-related obligations
    • Restrictions and procedures around share transfers
    • Additional professional and compliance costs

    For a business intending to scale, however, these obligations may be justified by the benefits of the corporate structure.

    Final Thoughts

    Private limited registration can provide a strong legal foundation for entrepreneurs who want to build a scalable and professionally structured business.

    It offers limited liability, separate legal identity and a share-based ownership structure that can be useful for bringing in co-founders and investors.

    But incorporation should not be treated as merely obtaining a Certificate of Incorporation.

    The right company name, correct documentation, appropriate business structure, accurate incorporation forms and post-incorporation compliance all matter.

    If you are unsure whether a Private Limited Company, LLP or OPC is right for your business, it is better to evaluate your business model and future plans before filing.

    Start Your Business With Lawizer

    From choosing the right business structure to incorporation and ongoing compliance, Lawizer helps entrepreneurs navigate the legal side of starting and growing a business.

    Need help with Private Limited Company registration?

    Get professional assistance with the incorporation process and start your business on a stronger legal foundation.

    Get Started with Private Limited Company Registration →

    Disclaimer: This article is intended for general informational purposes and does not constitute legal, tax or professional advice. Company incorporation requirements, fees, forms and regulatory requirements may change. Always verify the current requirements applicable to your company before filing.

  • Cryptocurrency and Tax in India: The Definitive 2026 Guide

    Cryptocurrency and Tax in India: The Definitive 2026 Guide

    Introduction

    The Indian crypto landscape has traveled a long road from the uncertainty of 2018 to the structured—yet stringent—regulatory framework of 2026.

    As Virtual Digital Assets (VDAs) become a mainstay in the portfolios of Indian retail investors and institutional players alike, staying compliant is no longer just about avoiding penalties; it is about protecting your digital wealth.

    With the Union Budget 2026 introducing refined definitions for Decentralized Finance (DeFi) and cross-border transactions, the tax authorities are watching more closely than ever.

    This guide breaks down everything you need to know about navigating crypto taxes in India this year.


    The Core Tax Architecture: The 30% Rule

    Since the introduction of Section 115BBH in the Income Tax Act, the fundamental rule for crypto taxation in India has remained consistent.

    The Flat Tax Rate

    Income from the transfer of any Virtual Digital Asset is taxed at a flat rate of 30%, regardless of your income tax slab.

    • No Deductions: Only the cost of acquisition is allowed. Expenses like electricity or platform fees cannot be claimed.
    • No Loss Set-off: Losses from one crypto asset cannot be adjusted against gains from another.

    The 1% TDS Mandate

    A 1% Tax Deducted at Source (TDS) under Section 194S is applicable on transactions exceeding ₹50,000 annually for specified persons.


    New for 2026: The Global Reporting Standard

    India has integrated with the Crypto-Asset Reporting Framework (CARF).

    The Income Tax Department now receives transaction data from international exchanges.

    This means offshore holdings are no longer invisible to regulators, and global compliance is now mandatory.


    Classifying Different Crypto Activities

    Taxation varies depending on how you engage with crypto assets:

    • Staking & Yield Farming: Taxed as “Income from Other Sources” at the time of receipt.
    • Airdrops & Gifts: Taxable if value exceeds ₹50,000.
    • Mining: Cost of acquisition is considered zero, making full sale value taxable.

    Why Compliance is Getting Complex: The PMLA Factor

    Crypto transactions now fall under the Prevention of Money Laundering Act (PMLA).

    Investors must maintain detailed records, including wallet addresses and transaction logs, for at least six years.


    How Lawizer Simplifies Crypto Compliance

    Tracking crypto transactions across exchanges and DeFi platforms can be overwhelming.

    Lawizer provides a streamlined solution for managing crypto tax compliance and audit readiness.

    Why Choose Lawizer?

    1. Automated Audit Trails: Generates tax-ready reports based on latest compliance rules.
    2. PMLA Compliance Support: Ensures AML and KYC adherence.
    3. Legal Review: Helps ensure tokens and smart contracts align with regulatory guidelines.

    Filing Your Returns: ITR-2 and ITR-3

    When filing your Income Tax Returns (AY 2026–27), ensure accurate reporting:

    • Schedule VDA: Report acquisition and transfer details.
    • Schedule FA: Mandatory for foreign-held crypto assets.

    Failure to disclose foreign assets may attract penalties up to ₹10 lakh under applicable laws.


    The Road Ahead: Regulation vs Innovation

    India is moving toward a “Regulate to Protect” approach under global frameworks like the G20 coordination model.

    The Reserve Bank of India (RBI) is also advancing its Digital Rupee initiative, which will further define the future of digital assets.


    Conclusion: Don’t Trade in the Dark

    In 2026, transparency is essential for crypto investors. Compliance is no longer optional—it is critical for protecting your assets.

    Using platforms like Lawizer ensures that your crypto investments remain legally secure and audit-ready.


    Frequently Asked Questions

    Is the 30% tax on crypto profits still mandatory in 2026?

    A: Yes. Under Section 115BBH, crypto income is taxed at 30% plus surcharge and cess.

    Can I offset losses between different cryptocurrencies?

    A: No. Losses cannot be set off against gains from other VDAs.

    What is the purpose of 1% TDS?

    A: It helps the government track transactions and can be claimed as tax credit.

    Do I need to report crypto held on foreign exchanges?

    A: Yes. It must be disclosed in Schedule FA to avoid heavy penalties.

    How is staking income taxed?

    A: It is taxed at receipt as income and again at sale under capital gains rules.

    Are crypto-to-crypto swaps taxable?

    A: Yes. They are treated as transfers and taxed accordingly.

  • The Rise of Green Credits: New Tax Incentives for India’s Eco-Startups in 2026

    The Rise of Green Credits: New Tax Incentives for India’s Eco-Startups in 2026

    Introduction

    The global shift toward sustainability is no longer a corporate social responsibility (CSR) footnote—it is a core economic driver. In India, the year 2026 marks a defining moment for the Green Economy.

    With the operationalization of the Green Credit Program (GCP) and new tax incentives introduced in the Union Budget, eco-startups are moving to the center of institutional investment.


    Defining the Green Credit Program (GCP)

    Unlike traditional carbon credit systems that focus only on emissions reduction, the Green Credit Rules, 2023 take a broader approach to environmental impact.

    Green Credits are awarded for the following activities:

    • Tree Plantation: Increasing green cover through afforestation.
    • Water Management: Conservation and wastewater treatment.
    • Sustainable Agriculture: Promoting organic farming and land restoration.
    • Waste Management: Recycling initiatives and circular economy models.

    How the Ecosystem Functions

    The system is administered by the Indian Council of Forestry Research and Education (ICFRE).

    Startups must register projects on the Green Credit Portal and undergo verification before credits are issued.


    Tax Incentives: The 2026 Fiscal Push

    The Union Budget 2026 introduces strong financial incentives to support green businesses.

    Section 80-IBA Extension for Green Housing

    Startups working on green buildings certified by the Bureau of Energy Efficiency (BEE) can claim extended tax benefits.

    This includes eligibility for 100% profit deductions for sustainable infrastructure projects.

    Accelerated Depreciation on Green Technology

    Under the Income Tax Act, eco-startups can claim up to 40% accelerated depreciation on green equipment.

    Angel Tax Exemptions

    Investments in DPIIT-recognized startups focused on climate solutions are exempt from Angel Tax if used for green capital expenditure.


    The Tradability of Impact: ESG and Green Credits

    Demand for Green Credits is driven by large listed companies in India.

    Under the SEBI BRSR framework, companies must disclose environmental performance.

    • Marketplace: Startups can sell Green Credits to corporations.
    • Revenue Stream: Provides additional and stable income.
    • Compliance Tracking: Monitor disclosures via the Ministry of Corporate Affairs.

    Navigating the Regulatory Framework

    To qualify for Green Credits and incentives, startups must comply with strict regulations.

    1. Verification: Conducted by the Central Pollution Control Board (CPCB) and auditors.
    2. Digital Tracking: Credits are digitally recorded to prevent misuse.
    3. FEMA Compliance: Required for foreign funding under RBI guidelines.

    Challenges in the Green Credit Market

    Despite growth, eco-startups face key challenges:

    • Price Volatility: Credit values fluctuate based on demand.
    • Verification Delays: Credit issuance may take 6–12 months.

    The Future of Green Credits

    The government is working on integrating Green Credits with global carbon markets.

    Under Article 6 of the Paris Agreement, startups may soon convert Green Credits into Carbon Credits for international trade.


    Strategic Checklist for Eco-Founders

    • DPIIT Recognition: Register on Startup India.
    • BEE Certification: Obtain energy efficiency certifications.
    • Audit Trail: Maintain digital environmental records.

    How Lawizer Powers Your Green Startup

    Managing environmental compliance and tax regulations can be complex. Lawizer simplifies this process through advanced legal-tech solutions.

    It helps automate registration, manage documentation, and track compliance requirements across multiple government frameworks.

    Why Choose Lawizer?

    • Automated Compliance: Reduces manual effort.
    • Regulatory Tracking: Stay updated with policy changes.
    • Documentation Support: Ensure accuracy and compliance.
    • Centralized Dashboard: Manage everything in one place.

    Build a sustainable business with confidence using Lawizer.


    Conclusion: Scalability Through Sustainability

    Green Credits are emerging as a key asset in India’s startup ecosystem.

    The future belongs to businesses that not only generate profits but also contribute to environmental restoration.


    Frequently Asked Questions

    What is the difference between Carbon Credits and Green Credits?

    A: Carbon Credits focus on emission reduction, while Green Credits reward broader environmental actions like water conservation and waste management.

    Can startups claim both tax benefits and Green Credits?

    A: Yes. Startups can earn Green Credits while also claiming tax incentives under relevant provisions.

    How can Green Credits be monetized?

    A: Verified credits can be sold to corporations that need them for ESG compliance.

    Are eco-startups exempt from Angel Tax?

    A: Yes, DPIIT-recognized startups working on green initiatives are generally exempt.

    What are FEMA requirements for green funding?

    A: Foreign investments must comply with RBI guidelines, including rules for external borrowings.

    Who verifies environmental impact?

    A: Agencies like CPCB and authorized auditors verify environmental claims.

  • Self-Certification for Labor Laws: How to Simplify Your Compliance in 2026

    Self-Certification for Labor Laws: How to Simplify Your Compliance in 2026

    Introduction

    For the modern Indian entrepreneur, “Labor Law Compliance” often evokes images of dusty registers, surprise inspections, and mountain-high paperwork.

    However, as India moves toward a more digitized and pro-business regulatory environment, the Self-Certification Scheme has emerged as a game-changer.

    In 2026, self-certification is no longer just an alternative; it is the gold standard for startups and MSMEs looking to scale without the friction of traditional inspections.

    This guide explains how you can leverage self-certification to simplify your compliance roadmap.


    What is the Self-Certification Scheme?

    Self-certification is a simplified compliance mechanism that allows employers to certify their own adherence to various labor laws through an online portal.

    Instead of routine physical inspections by labor officers, businesses provide a legal undertaking confirming that they comply with statutory requirements.

    The Startup India Advantage

    Under the Startup India Action Plan, recognized startups can self-certify compliance for 9 labor laws and 3 environmental laws.

    For the first 3 to 5 years, startups are exempt from inspections unless a credible written complaint is filed.


    Key Labor Laws Covered Under Self-Certification

    The central framework generally covers the following major labor laws:

    • The Building and Other Construction Workers Act, 1996: Regulates safety and welfare of construction workers.
    • The Inter-State Migrant Workmen Act, 1979: Protects rights of workers employed across states.
    • The Payment of Gratuity Act, 1972: Governs employee retirement benefits.
    • The Employees’ Provident Funds Act, 1952: Managed by the EPFO.

    The Shift to the Shram Suvidha Portal

    The Shram Suvidha Portal, launched by the Ministry of Labour & Employment, acts as a unified compliance platform.

    It provides a single window for multiple labor law requirements.

    1. LIN Generation: Every business gets a unique Labour Identification Number.
    2. Online Returns: File a unified annual return covering multiple laws.
    3. Transparent Inspections: Inspections are randomized through a system-based algorithm.

    How to Apply for Self-Certification

    Step 1: DPIIT Recognition

    Startups must obtain DPIIT recognition to access self-certification benefits and inspection exemptions.

    Step 2: Register on Shram Suvidha Portal

    Register using your PAN and business details on the Shram Suvidha Portal and activate your LIN.

    Step 3: File Unified Annual Return

    Submit the Unified Annual Return (UAR) instead of filing multiple returns for EPF, ESI, and other laws.


    Why Self-Certification is the Best Strategy in 2026

    The shift from “Inspector Raj” to “Self-Regulation” offers significant advantages:

    • Cost Efficiency: Reduces reliance on manual compliance consultants.
    • Risk Control: Encourages internal audits and reduces violations.
    • Investor Confidence: Clean compliance history improves due diligence outcomes.

    How Lawizer Simplifies the Process

    Managing multiple compliance portals can be complex. Lawizer simplifies this through an automated legal-tech platform.

    It integrates with government systems to track deadlines, auto-fill returns, and maintain audit-ready records.

    Why Choose Lawizer?

    • Automated Compliance: Reduces manual effort.
    • Deadline Tracking: Never miss filings.
    • Audit-Ready Records: Maintain digital registers.
    • Centralized Dashboard: Manage all compliance in one place.

    Simplify compliance and scale your business with Lawizer.


    Conclusion: The Era of Informed Compliance

    Self-certification represents a shift toward trust-based governance and digital compliance.

    By adopting modern tools and government platforms, businesses can focus on growth rather than administrative burden.


    Frequently Asked Questions

    Does self-certification eliminate inspections?

    A: No. Routine inspections are removed, but complaint-based inspections can still occur.

    Is self-certification available for all industries?

    A: Most service-based and non-hazardous businesses qualify. Hazardous industries may still require inspections.

    Can EPF and ESI be self-certified?

    A: Yes. Compliance can be managed through the unified portal, though contributions must be paid regularly.

  • Navigating the New GST E-Invoicing Limits for 2026: A Roadmap for Compliance

    Navigating the New GST E-Invoicing Limits for 2026: A Roadmap for Compliance

    Introduction

    In the world of Indian indirect taxation, the “Paperless Revolution” has reached its final frontier.

    As of 2026, the Goods and Services Tax (GST) framework has shifted from an optional digital convenience to a mandatory real-time reporting requirement for almost the entire organized sector.

    The latest lowering of e-invoicing turnover thresholds has brought lakhs of small and medium enterprises (SMEs) into the digital net.

    In 2026, compliance is no longer a monthly filing task—it is a live, transaction-by-transaction responsibility.


    What are the New E-Invoicing Limits for 2026?

    The phased implementation of e-invoicing started in 2020 for large corporations. Since then, the GST Council has systematically lowered this threshold to digitize the supply chain and curb tax evasion.

    The 2026 Threshold Shift

    Starting in the 2026 fiscal year, any business with an aggregate turnover exceeding ₹2 Crores in any preceding financial year (from 2017-18 onwards) is now mandated to generate e-invoices for all B2B transactions and exports.

    Why This Matters for Your Business

    • Universal Digitization: This pulls in almost every stable SME and high-growth startup in India.
    • Input Tax Credit (ITC): Customers cannot claim ITC unless you provide a valid e-invoice with a unique Invoice Reference Number (IRN).

    Understanding the E-Invoicing Workflow

    E-invoicing does not mean generating an invoice directly on the GST portal. Instead, invoices are created in your accounting system and reported to the Invoice Registration Portal (IRP).

    The Step-by-Step Process

    1. Generation: Create the invoice in your ERP or accounting software.
    2. Reporting: Upload the invoice JSON file to the IRP.
    3. Validation: The IRP validates and generates a unique 64-character IRN and QR Code.
    4. Auto-Population: Data is pushed to GSTR-1 and the buyer’s GSTR-2B.

    The Risks of Non-Compliance

    In 2026, the Central Board of Indirect Taxes and Customs (CBIC) has tightened oversight on GST compliance.

    • Invalid Invoices: Without an IRN, invoices are not legally valid.
    • Heavy Penalties: 100% of tax due or ₹10,000 per invoice (whichever is higher).
    • Blocked Logistics: Without e-invoicing, generating an E-Way Bill becomes difficult.
    • Loss of Business: Buyers prefer compliant vendors to secure ITC benefits.

    How Lawizer Simplifies E-Invoicing

    For businesses crossing the ₹2 Crore threshold, technical integration can be complex. Lawizer provides a seamless solution to simplify compliance.

    Why Choose Lawizer?

    • One-Click IRN Generation: Direct invoice generation from your dashboard.
    • Error Validation: AI-based checks prevent GSTIN and HSN errors.
    • ITC Reconciliation: Auto-match vendor invoices with purchase records.
    • GSTN Integration: Smooth connectivity with the GST network.

    Stay compliant and scale your business effortlessly with Lawizer.


    Conclusion: Compliance as a Competitive Edge

    The 2026 e-invoicing mandate signals a shift toward real-time tax transparency in India.

    While initial adaptation may seem complex, benefits like faster ITC claims and reduced audits make it worthwhile.

    With expert support from Lawizer, businesses can remain compliant, efficient, and growth-focused.


    Frequently Asked Questions

    Does the ₹2 Crore limit apply to current turnover?

    A: No. It applies if turnover exceeded ₹2 Crores in any previous financial year since 2017-18.

    Is e-invoicing required for B2C transactions?

    A: No. It is currently mandatory only for B2B, B2G, and export transactions.

    Can an e-invoice be canceled?

    A: Yes, but only within 24 hours on the IRP. After that, a credit note must be issued.

  • Union Budget 2026: The Strategic “Operating System” for Indian Tech Startups

    Union Budget 2026: The Strategic “Operating System” for Indian Tech Startups

    Introduction

    The Union Budget 2026-27 has officially signaled the end of the “quick-fix” subsidy era.

    Finance Minister Nirmala Sitharaman has instead unveiled a structural “Operating System” for the Indian tech ecosystem—focusing on long-term infrastructure, tax predictability, and a massive bet on the Orange Economy.

    For the Indian tech ecosystem, this isn’t just another fiscal plan; it’s a strategic blueprint for the next decade of innovation.

    As India marches toward Viksit Bharat 2047, the 2026 budget provides the “predictable rails” necessary for startups to transition from disruptors to national infrastructure.

    In this guide, we break down the key takeaways every founder, investor, and tech professional must understand.


    Startup India Fund of Funds (FFS) 2.0 Boost

    The government has approved Startup India Fund of Funds 2.0 with a fresh corpus of ₹10,000 crore.

    This version prioritizes DeepTech, AI, and SpaceTech, aiming to reduce risks for investors in high-gestation sectors.

    • Impact: Increased domestic venture capital with government acting as an anchor investor.
    • Next Step: Founders should align their pitch decks with national priority sectors via Startup India.

    Tax Reforms and Startup Benefits

    The budget brings major clarity and incentives for startups under tax laws.

    Extension of Section 80-IAC Tax Holiday

    Startups incorporated until March 31, 2030 can claim 100% tax deduction for three consecutive years.

    The turnover eligibility limit has increased to ₹150 crore, allowing scaling startups to benefit longer.

    Check eligibility through Lawizer.

    New Income Tax Act (Effective April 1, 2026)

    • Share Buybacks: Now taxed as capital gains, improving employee and investor returns.
    • MAT Reduction: Lowered to 14%, allowing better reinvestment capacity.

    Safe Harbour for SaaS and ITeS

    A new Global SaaS Safe Harbour reduces transfer pricing disputes.

    • Threshold: Increased to ₹2,000 crore.
    • Benefit: Fixed 15.5% margin reduces litigation and encourages reverse flipping.

    This reform addresses long-standing concerns with the Income Tax Department.


    Growth of the Orange Economy (AVGC)

    The government has recognized the AVGC sector (Animation, VFX, Gaming, Comics) as a major growth engine.

    Plans include setting up creator labs in 15,000 schools to build a future-ready workforce.

    This creates opportunities for startups in EdTech, MediaTech, and Gaming via institutions like Indian Institute of Creative Technologies.


    DeepTech and Semiconductor Push

    The India Semiconductor Mission (ISM) 2.0 has been allocated ₹40,000 crore.

    • Data Centers: Tax holiday until 2047 for global cloud providers.
    • R&D Incentives: Reduced tax friction for research-driven startups.

    E-commerce Export Boost (D2C)

    The removal of the ₹10 lakh export cap simplifies global shipping for startups.

    D2C brands can now scale exports seamlessly via logistics partners.

    The ONDC network will enable global storefront access for Indian businesses.


    Simplified Export Returns and Compliance

    The government introduced a Digital Export Feedback Loop through the DGFT portal.

    This allows duty-free re-import of returned goods, protecting margins for exporters.


    Focus on AI Skills and Employability

    The budget shifts focus from job creation to skill development.

    A new committee aims to bridge gaps between education and employment in AI-driven industries.

    Support is enhanced through the Anusandhan National Research Foundation (ANRF).


    Ease of Doing Business Improvements

    The government has decriminalized minor compliance defaults to promote a trust-based system.

    • Tax Disputes: Pre-deposit reduced from 20% to 10%.
    • TReDS Mandate: Faster payments for startups via receivable discounting systems.

    Conclusion: Building for 2047

    The Union Budget 2026 integrates startups into India’s long-term economic infrastructure.

    Build for the world, solve for India, and growth will follow.

    By aligning with Viksit Bharat 2047, founders can unlock significant opportunities.


    Frequently Asked Questions

    What is the new Safe Harbour threshold for SaaS startups?

    A: The threshold has been increased to ₹2,000 crore, allowing companies to opt for a fixed 15.5% margin and avoid transfer pricing disputes.

    How does the cloud tax holiday work?

    A: Foreign cloud providers using Indian data centers get a tax holiday until 2047, with domestic compliance requirements.

    What are the benefits for D2C startups?

    A: Removal of export caps and simplified logistics enable easier global expansion via DGFT.

    What is the Orange Economy?

    A: It refers to AVGC sectors like animation, gaming, and media, now supported by government initiatives.

    How is the AI talent gap addressed?

    A: Through education reforms and a dedicated committee aligning curriculum with AI and deep-tech needs.

    Is there support for startup liquidity?

    A: Yes, TReDS ensures faster payments to startups, improving cash flow cycles.

  • Drafting Virtual Contracts: Legal Validity in the Indian Market (2026)

    Drafting Virtual Contracts: Legal Validity in the Indian Market (2026)

    Introduction

    In the rapid-fire world of the Indian startup ecosystem, the traditional “wet ink” signature is fast becoming a relic of the past. From SaaS subscriptions to high-stake founder agreements, the Virtual Contract is now the primary vehicle for commerce.

    However, as we move through 2026, a critical question remains: Is a digital agreement truly as enforceable as a paper one in an Indian court?

    The answer is a resounding yes, provided you navigate the specific intersection of the IT Act and the Indian Evidence Act correctly.


    The Legal Pillars: IT Act, 2000 and Beyond

    The bedrock of virtual contracting in India is the Information Technology Act, 2000. Section 10A of the Act specifically grants legal recognition to contracts formed through electronic means.

    What Constitutes a Valid Virtual Contract?

    Under Indian law, a contract is formed when an offer is made and accepted with lawful consideration. In the digital realm, this typically happens through:

    • Click-wrap Agreements: The ubiquitous “I Agree” checkboxes.
    • Browse-wrap Agreements: Terms linked at the footer of a website.
    • E-Signatures: Documents signed via Aadhaar-based eSign or digital signature certificates (DSC).

    The Admissibility of Electronic Records

    In 2026, judicial scrutiny of digital evidence is highly sophisticated. For a virtual contract to hold up during litigation, it must comply with Section 65B of the Indian Evidence Act, 1872 (now integrated into the Bharatiya Sakshya Adhiniyam).

    The Certificate Requirement

    To present a virtual contract as evidence, a business must produce a Section 65B Certificate. This document certifies the authenticity of the computer output and ensures the electronic record has not been tampered with.

    Pro Tip: Courts now demand “Audit Trails”—digital logs showing the exact timestamp, IP address, and device ID of the signer.


    The “Stamping” Hurdle: Can Digital Be Stamped?

    A common pitfall in drafting virtual contracts is the payment of Stamp Duty. Under the Indian Stamp Act, 1899, an unstamped contract is generally inadmissible in court.

    E-Stamping in 2026

    Most Indian states have now integrated e-Stamping services. For a virtual contract to be “bulletproof,” the digital document should be associated with an e-Stamp certificate. Failing to do this can lead to penalties—often up to 10 times the original stamp duty amount.


    Specific Exclusions: When Digital is Not Enough

    Despite the digital push, certain documents cannot be executed virtually in India:

    1. Negotiable Instruments: Such as Promissory Notes (excluding cheques).
    2. Power of Attorney: Generally requires physical execution.
    3. Trust Deeds and Wills: These necessitate physical “wet” signatures.
    4. Real Estate Transfers: Sale deeds still require physical registration at the Sub-Registrar’s Office.

    How Lawizer Secures Your Virtual Agreements

    Drafting a contract is only half the battle; ensuring its “evidentiary weight” is the other half. Lawizer, a premier legal-tech firm, transforms your digital workflow into a secure legal asset.

    Lawizer’s “Smart-Contract” Suite Offers

    • Automated Audit Trails: Captures comprehensive metadata for every signature, auto-generating required legal certificates.
    • Integrated E-Stamping: Seamlessly procure and attach e-Stamps within the platform.
    • Aadhaar e-Sign Integration: Uses the UIDAI framework for secure authentication.

    Make your digital agreements legally strong and court-ready with Lawizer.


    Conclusion: Designing for Defensibility

    In 2026, the validity of a virtual contract depends on the infrastructure behind it.

    By combining sound legal drafting with robust technical verification, businesses can significantly reduce litigation risk.

    Partnering with tech-legal platforms like Lawizer ensures your digital agreements are as enforceable as traditional contracts.


    Frequently Asked Questions

    Is an email exchange a valid contract in India?

    A: Yes, provided essential contract elements exist. However, proving identity is harder without formal e-signature tools.

    Are “I Agree” checkboxes legally binding?

    A: Yes, click-wrap agreements are valid if terms are clearly communicated.

    What is the difference between an E-signature and a Digital Signature?

    A: An E-signature is a broad category (like Aadhaar eSign), while a Digital Signature (DSC) is a secure, certificate-based signature issued by a Certifying Authority (CA).

  • What to Do If Your Cheque Bounces: Legal Steps Under Section 138 NI Act

    What to Do If Your Cheque Bounces: Legal Steps Under Section 138 NI Act

    Introduction

    Dealing with a bounced cheque can be a highly frustrating experience. Whether you are a business owner waiting on a critical client payment, a landlord collecting rent, or an individual expecting the repayment of a friendly loan, an unpaid cheque disrupts your cash flow and breaches your trust.

    However, Indian law provides a robust mechanism to protect payees and penalize defaulters.

    If you are wondering exactly what to do if your cheque bounces, the Negotiable Instruments (NI) Act, 1881, specifically Section 138, is your primary legal weapon.

    Navigating this process requires strict adherence to timelines and procedures.

    In this article, we will discuss everything related to cheque bounce cases and how Lawizer helps simplify this process, making it easier for you to draft your legal notice and take swift action.


    What is Cheque Dishonour and Why is it a Criminal Offence in India?

    A cheque is said to be “dishonoured” or “bounced” when a bank refuses to pay the amount mentioned on the cheque to the payee.

    The bank returns the cheque along with a “Cheque Return Memo” stating the specific reason for the bounce. Common reasons include:

    • Insufficient funds
    • Signature mismatch
    • Account closed
    • Payment stopped by the drawer

    Historically, cheque bounce cases were treated as civil disputes, leading to long delays in recovery.

    To address this, Section 138 of the Negotiable Instruments Act was introduced, making cheque dishonour a criminal offence under specific conditions.


    Why is Cheque Bounce a Criminal Offence?

    The objective behind criminalizing cheque bounce is to maintain trust in financial transactions and ensure smooth business operations.

    The law imposes strict liability, meaning the burden of proof lies on the drawer if the cheque bounces due to insufficient funds.

    This discourages misuse of cheques and ensures accountability in financial dealings.


    The 30-15-30 Rule You Must Follow

    Time is critical in cheque bounce cases. Missing deadlines can weaken your case significantly.

    1. 30-Day Notice Period

    You must send a legal notice within 30 days from receiving the cheque return memo.

    2. 15-Day Payment Window

    The drawer gets 15 days to make payment after receiving the notice.

    3. 30-Day Court Filing Window

    If payment is not made, you must file a case within 30 days after the 15-day period expires.


    Example Timeline

    • March 1: Return memo received
    • March 20: Legal notice sent
    • March 25: Notice received
    • April 9: Payment deadline ends
    • May 9: Last date to file case

    How to Draft a Legal Notice for Cheque Bounce

    A legal notice is the foundation of your case. Any error can weaken your claim.

    Key Elements to Include

    • Transaction details
    • Cheque details
    • Reason for dishonour
    • Demand for payment
    • Legal warning

    How to Send the Notice

    Always send the notice via Registered Post or Speed Post to ensure proof of delivery.


    Filing a Case Under Section 138

    If payment is not made, you can file a criminal complaint before the Magistrate.

    Jurisdiction

    The case must be filed where your bank branch is located.

    Required Documents

    • Original cheque
    • Cheque return memo
    • Legal notice copy
    • Proof of delivery
    • Supporting documents

    What Relief Can You Get?

    • Imprisonment: Up to 2 years
    • Fine: Up to twice the cheque amount
    • Interim Compensation: Up to 20% during trial

    Out-of-Court Settlement Options

    Cheque bounce cases can be settled outside court as they are compoundable offences.

    • Mediation and Lok Adalat settlements
    • Mutual agreement between parties
    • Payment with interest or legal costs

    How Lawizer Helps You

    Lawizer simplifies cheque bounce cases by connecting you with verified legal professionals.

    Why Choose Lawizer?

    • Expert legal notice drafting
    • Verified lawyers
    • End-to-end case support
    • Affordable pricing
    • Quick turnaround

    Take action today and recover your money faster.


    Conclusion

    A bounced cheque is not just an inconvenience—it is a serious financial issue.

    By following the legal process and acting within deadlines, you can effectively recover your money.

    Taking timely legal action ensures accountability and protects your financial interests.

    Take control of the situation and act swiftly with Lawizer.


    Frequently Asked Questions

    Is Lawizer a legit company?

    A: Yes, Lawizer is a legitimate legal-tech platform in India.

    Is Lawizer a law firm?

    A: No, it is a legal-tech platform connecting users with lawyers.

    Can I file a case if I miss the 30-day notice deadline?

    A: No, but you can still pursue a civil case for recovery.

    What if partial payment is made?

    A: You can proceed legally for the remaining amount.

    Will the bank take legal action for me?

    A: No, you must initiate legal proceedings yourself.

    Will the defaulter go to jail immediately?

    A: No, imprisonment happens only after trial and conviction.

  • How to Recover Money from a UPI Scam in India: A Step-by-Step Guide

    How to Recover Money from a UPI Scam in India: A Step-by-Step Guide

    Introduction

    India’s rapid adoption of digital payments has made transferring money as easy as sending a text. Unfortunately, scammers have also levelled up their game.

    If you have just realized that you are the victim of a UPI fraud, take a deep breath. Panic is a natural reaction, but acting swiftly and methodically is your best weapon.

    Time is the most critical factor in recovering stolen funds. Here is a complete guide on what to do, your rights under the law, and how to navigate the recovery process with the help of Lawizer.


    How Common UPI Scams Work

    Scammers constantly invent new ways to trick victims, but most UPI frauds fall into common patterns:

    • Fake QR Codes: Fraudsters send QR codes claiming money will be credited. In reality, scanning it initiates a payment.
    • Rule of Thumb: You never need to scan a QR code or enter your UPI PIN to receive money.
    • Screen Sharing Apps: Scammers posing as customer support ask you to install apps like AnyDesk or TeamViewer, gaining access to OTPs and sensitive data.
    • Vishing (Voice Phishing): Fraudsters impersonate bank officials or authorities to trick you into revealing your UPI PIN or OTP.

    Immediate Steps to Take Within the First Hour

    The first 60 minutes after a scam are often referred to as the “Golden Hour.” Acting quickly significantly improves your chances of recovery.

    1. Block Your Account: Contact your bank immediately to freeze your account and disable your UPI ID.
    2. Call the Helpline (1930): Report the fraud to the national cybercrime helpline. Authorities may freeze the scammer’s account if the funds are still in transit.
    3. Seek Immediate Guidance: Use the Lawizer SOS button for instant legal and financial assistance.


    How to File a Complaint on the Cybercrime Portal

    Once your accounts are secure, filing an official complaint is essential.

    1. Visit the official portal: cybercrime.gov.in.
    2. Create an account using your mobile number.
    3. Provide detailed information including transaction ID (UTR), date, time, and supporting evidence.
    4. Submit the complaint and save the acknowledgment number.

    RBI Guidelines on Fraud Liability

    The Reserve Bank of India (RBI) provides protection for victims of unauthorized electronic transactions.

    If you report fraud within 3 working days, your liability is zero, and the bank must compensate the loss.

    If reported within 4 to 7 working days, liability is limited (typically ₹10,000–₹25,000 depending on account type).


    Filing an FIR: What to Include and Why it Matters

    In addition to the cybercrime portal, filing an FIR at your local police station or cyber cell strengthens your case.

    Include the following details:

    • Timeline of events
    • Transaction IDs and bank details
    • Scammer’s phone number or UPI ID
    • Screenshots and supporting evidence

    A well-drafted FIR ensures your complaint is taken seriously and avoids delays.


    How to Escalate if the Bank Doesn’t Cooperate

    If your bank fails to resolve the issue within 30 days or rejects your complaint unfairly, you can escalate the matter.

    File a complaint with the RBI Banking Ombudsman through the CMS portal.


    How Lawizer Helps with Cybercrime Complaints

    Navigating police procedures and bank systems can be overwhelming. Lawizer simplifies the process by providing expert legal assistance.

    Why Choose Lawizer?

    • 24/7 SOS Emergency Support
    • Free Initial Legal Consultation
    • Expert FIR & Complaint Drafting
    • Digital Case Tracking Dashboard
    • Verified Legal Experts
    • Transparent Pricing

    Get expert help and improve your chances of recovering lost funds.


    Conclusion

    Losing money to a UPI scam is stressful, but quick action can significantly improve recovery chances.

    By securing your accounts, reporting immediately, leveraging RBI protections, and seeking professional support, you can take control of the situation.

    With the right steps and tools, fighting back against fraud is possible.


    Frequently Asked Questions

    What exactly is Lawizer?

    A: Lawizer is a legal-tech platform that helps individuals handle legal issues like cyber fraud with expert support.

    Is Lawizer a legitimate platform?

    A: Yes, it is a reliable and transparent legal-tech solution.

    Is Lawizer a law firm?

    A: No, it is a technology platform that simplifies legal processes.

    How do I reset a forgotten UPI PIN?

    A: Use your UPI app to reset your PIN via debit card or Aadhaar authentication with OTP verification.

  • Loan Agreement in India: Key Clauses Every Borrower Must Read Before Signing

    Loan Agreement in India: Key Clauses Every Borrower Must Read Before Signing

    Introduction

    Getting approved for a loan—whether it is for a new home, a car, or scaling your business—is an exciting milestone. However, the excitement often overshadows the most critical step of the process: reading the fine print.

    Borrowers in India frequently sign lengthy legal documents without reviewing them carefully, assuming they are standard non-negotiable templates. This can lead to serious financial and legal consequences later.

    Here is a comprehensive guide to understanding your loan agreement and the key clauses you must review before signing.


    Why a Loan Agreement is Legally Binding

    A loan agreement is not just a document issued by a bank—it is a legally binding contract governed by the Indian Contract Act, 1872.

    Once signed, it binds both the borrower and the lender. While you are obligated to repay the loan, the bank must also follow the agreed terms.

    This means lenders cannot arbitrarily change core conditions without adhering to the contract, giving you legal grounds to hold them accountable.


    Key Clauses You Must Always Read

    Do not let legal jargon overwhelm you. Focus on these critical clauses:

    • Interest Rate (Fixed vs Floating): Check whether your rate is fixed or fluctuates with market conditions and how often it resets.
    • Prepayment & Foreclosure Charges: Some banks charge penalties for early repayment, although RBI restricts this for certain loans.
    • Default Clause: Understand what qualifies as a default, including cross-default triggers linked to other loans.

    What is the MITC Document?

    The RBI requires lenders to provide a Most Important Terms and Conditions (MITC) document.

    This is a simplified summary of your loan’s key aspects such as interest rates, penalties, and charges.

    Always review the MITC carefully—it is designed for transparency and quick understanding.


    Hidden Charges You Must Watch Out For

    The advertised interest rate is not the only cost. Pay attention to:

    • Processing Fees: One-time non-refundable charges.
    • Penal Charges: Fees applied when you miss EMI payments.
    • Additional Costs: Legal, valuation, documentation, or insurance charges bundled into the loan.

    What Happens if You Default?

    If you default, the lender has legal remedies—but you also have rights:

    • SARFAESI Act: Banks can auction secured assets after proper notice.
    • Debt Recovery Tribunal (DRT): Handles large loan disputes where you can present your case.
    • Recovery Agent Rules: RBI prohibits harassment, abuse, or calls at odd hours.

    Can You Negotiate Loan Terms?

    Yes. A loan agreement is negotiable, especially if you have a strong credit profile.

    You may negotiate:

    • Lower interest margins
    • Processing fee waivers
    • Better prepayment terms

    Never hesitate to request changes before signing.


    How Does Lawizer Help You?

    Loan agreements are complex, and missing one clause can cost you significantly. Lawizer simplifies the process by providing expert legal assistance.

    Why Choose Lawizer?

    • Clause Analysis: Identifies hidden risks and unfair terms
    • Simple Explanation: Converts legal jargon into plain language
    • Negotiation Support: Helps you secure better terms
    • Legal Protection: Guidance against harassment or violations
    • Fully Online: Fast and affordable document review

    Protect your financial future before you sign.


    Frequently Asked Questions

    Can Lawizer help negotiate my loan agreement?

    A: Yes, Lawizer provides expert insights and actionable negotiation points.

    Is Lawizer a law firm?

    A: No, it is a legal-tech platform offering accessible legal solutions.

    What should I do if recovery agents harass me?

    A: File a complaint with the bank and escalate to RBI if needed.

    Can Lawizer help after signing the agreement?

    A: Yes, it can review active agreements and guide you on your rights.

  • How to Register a Copyright in India: Process, Cost, and What It Protects

    How to Register a Copyright in India: Process, Cost, and What It Protects

    Introduction

    Whether you are writing a novel, designing a logo, coding a new app, or producing music, your creative output is a valuable asset.

    In an age where digital theft and content scraping are rampant, protecting your intellectual property is no longer optional.

    Navigating intellectual property laws can feel intimidating, but understanding your rights is the first step to securing your work.

    Here is a complete guide on how to register a copyright in India, the costs involved, and the protections it guarantees and also how Lawizer can make the process easier.


    What is Copyright and What Types of Works are Automatically Protected?

    Copyright is a legal right granted to creators, giving them exclusive control over the use and distribution of their original work.

    Under the Indian Copyright Act, 1957, copyright is established automatically the moment an original work is created and fixed in a tangible medium.

    The law automatically protects:

    • Books, articles, and poems
    • Computer software and code
    • Paintings, photographs, and architectural designs
    • Musical compositions and song lyrics
    • Movies and audio recordings

    Why You Should Still Register Despite Automatic Protection

    If copyright is automatic, why go through the hassle of registering it? While you own the rights the moment you create the work, enforcing those rights without a certificate is difficult.

    Here is why registration is crucial:

    • Legal Evidence: A copyright certificate serves as prima facie evidence in court.
    • Statutory Damages: Easier to claim compensation in infringement cases.
    • Commercial Power: Required for licensing, selling, or transferring rights.

    Step-by-Step Copyright Registration Process

    Registering your work in India is done through the official government portal.

    1. Create an Account: Register on the portal.
    2. Fill Form XIV: Provide details of the work and author.
    3. Upload Work: Submit digital or physical copies.
    4. Pay Fees: Generate a diary number.
    5. Waiting Period: 30 days for objections.
    6. Examination: Review by authority.
    7. Registration: Certificate issued.

    Classes of Copyright Work

    Your work must fall under one of these categories:

    • Literary Works: Books, blogs, software.
    • Artistic Works: Logos, paintings, photographs.
    • Dramatic Works: Scripts and plays.
    • Musical Works: Compositions.
    • Sound Recordings: Audio tracks.
    • Cinematograph Films: Videos and films.

    Documents Required and Fees

    You will generally need:

    • Copies of the work
    • No Objection Certificate (if applicable)
    • Power of Attorney (if filed via agent)

    Government Fees

    • Literary/Artistic Works: ₹500
    • Logos (commercial use): ₹2,000
    • Films: ₹5,000
    • Sound Recordings: ₹2,000

    How Long Does Registration Take?

    The process typically takes 6 to 12 months due to the mandatory waiting period and examination process.


    Rights of a Copyright Owner

    As an owner, you get exclusive rights:

    • Reproduction: Make copies
    • Adaptation: Modify or translate
    • Communication: Share publicly
    • Moral Rights: Claim authorship and protect integrity

    How Lawizer Helps You

    The registration process can be complex. Lawizer simplifies it with expert assistance.

    Why Choose Lawizer?

    • End-to-End Filing
    • Document Preparation
    • Objection Handling
    • Status Tracking
    • Emergency Legal Support

    Protect your creative work with confidence.


    Conclusion

    Your creative work is valuable and deserves protection.

    While copyright exists automatically, registration strengthens your legal position and enables commercialization.

    With the right support, the process becomes simple and efficient.


    Frequently Asked Questions

    How long does copyright last in India?

    A: Lifetime of the author plus 60 years.

    Can I copyright an idea?

    A: No, only the expression of an idea is protected.

    What is Lawizer?

    A: Lawizer is a legal-tech platform simplifying legal services.

    Is Lawizer legitimate?

    A: Yes, it is a reliable platform.

    Is Lawizer a law firm?

    A: No, it is a legal-tech solution.

  • Non-disclosure agreement (NDA) India: When you need one and what to include

    Non-disclosure agreement (NDA) India: When you need one and what to include

    Introduction

    In today’s hyper-competitive business landscape, your ideas, data, and processes are your most valuable currency.

    Whether you are pitching a revolutionary app to an investor, hiring a new lead developer, or onboarding a manufacturing vendor, you have to share sensitive information to move forward.

    But how do you ensure the other party doesn’t steal your idea or leak your data to a competitor?

    This is where a Non-Disclosure Agreement (NDA) becomes your first line of defense.

    An NDA is a legally binding contract that establishes a confidential relationship between parties. It ensures that sensitive information shared for a specific purpose is not disclosed to unauthorized third parties.

    In this comprehensive guide, we will break down how NDAs work in India, when you need one, what clauses are non-negotiable, and how to enforce them if things go wrong. We will also see how Lawizer can help.


    What an NDA Protects and Its Legal Enforceability in India

    An NDA acts as a protective shield for anything that gives your business a competitive edge. This typically includes:

    • Trade Secrets: Algorithms, manufacturing processes, and formulas.
    • Business Information: Client lists, pricing strategies, financial records, and marketing plans.
    • Intellectual Property (IP): Unpublished patent applications, source code, and design prototypes.

    Is it legally enforceable in India? Yes. In India, NDAs are governed primarily by the Indian Contract Act, 1872.

    For an NDA to be valid, it must meet standard contract requirements: offer, acceptance, lawful object, consideration, and free consent.

    However, Section 27 restricts agreements that restrain trade or profession. Overly broad or unfair NDAs may be struck down.

    To be enforceable, confidentiality obligations must be reasonable in scope and duration.


    One-Way vs Mutual NDA

    1. One-Way (Unilateral) NDA

    Only one party shares confidential information.

    • Used for: Hiring employees, freelancers, consultants, or pitching ideas.

    2. Mutual (Bilateral) NDA

    Both parties share sensitive information.

    • Used for: Partnerships, joint ventures, mergers, and co-founder agreements.

    Key Clauses to Include in an NDA

    1. Definition of Confidential Information

    Clearly define what information is protected, such as source code, financial data, or client databases.

    2. Exclusions

    Specify what is not confidential:

    • Public domain information
    • Previously known information
    • Independently developed data
    • Legally required disclosures

    3. Duration

    Most NDAs last between 2 to 5 years. Perpetual clauses are usually not enforceable.

    4. Consequences of Breach

    Include rights to injunctions and monetary damages in case of violation.


    Common NDA Mistakes

    • Overly Broad Clauses: Makes agreement unenforceable.
    • No Stamp Duty: Must be executed on valid stamp paper.
    • Unclear Jurisdiction: Always define governing law and court location.

    Industries Where NDAs Are Essential

    • Tech & IT: Protect code and algorithms.
    • Healthcare: Secure patient and research data.
    • Manufacturing: Safeguard processes and designs.
    • Startups: Protect pitch decks and financial models.

    How to Enforce an NDA in India

    1. Gather Evidence: Document the breach.
    2. Send Legal Notice: Demand immediate action.
    3. Seek Injunction: Stop further disclosure.
    4. Claim Damages: Recover financial losses.

    Get a Custom NDA Drafted with Lawizer

    Using generic templates can expose your business to risks.

    Lawizer provides expert-drafted, customized NDAs tailored to Indian laws.

    Why Choose Lawizer?

    • India-Compliant Drafting
    • Customized Agreements
    • Strong Legal Protection
    • Fast Turnaround

    Protect your ideas before you share them.


    Conclusion

    An NDA is not just a formality—it is essential for protecting your business assets.

    Whether you are a startup or an established business, a well-drafted NDA ensures your confidential information remains secure.

    With proper legal support, you can collaborate and grow without fear.


    Frequently Asked Questions

    Is notarization mandatory for an NDA in India?

    A: No, but it must be executed on proper stamp paper.

    Can an NDA stop someone from joining a competitor?

    A: No, it only protects confidential information.

    Does an NDA cover verbal information?

    A: Yes, if documented later in writing.

    What is Lawizer?

    A: Lawizer is a legal-tech platform simplifying legal documentation.

    Is Lawizer legitimate?

    A: Yes, it is a trusted legal-tech solution.

    Is Lawizer a law firm?

    A: No, it is a legal-tech platform, not a law firm.

  • Employment Agreement in India: What Employers and Employees Must Know

    Employment Agreement in India: What Employers and Employees Must Know

    Introduction

    The foundation of any successful professional relationship is clarity. Whether you are a fast-growing startup bringing on your first hire or a seasoned professional evaluating a new job offer, the employment agreement is the most critical document you will handle.

    It dictates not just what you do and how much you get paid, but also your rights, obligations, and protections under Indian labour laws.

    A poorly drafted employment contract can lead to costly legal disputes, unprotected intellectual property, or unfair working conditions.

    In this comprehensive guide, we will break down everything both employers and employees need to know about employment agreements in India, including the legality of restrictive clauses, IP ownership, and how to ensure your contracts are airtight.

    We shall also discuss about Lawizer, a legal-tech platform that simplifies this process through expert legal support and technology-driven solutions.


    Is a Written Employment Agreement Legally Mandatory in India?

    Under the Indian Contract Act, 1872, a contract can technically be oral or written. However, in employment, an oral agreement is highly risky and practically unenforceable.

    Various state-specific Shops and Establishments Acts require employers to provide a formal appointment letter or written contract to employees.

    Therefore, despite central law allowing oral agreements, a written employment contract is essential for compliance, clarity, and legal protection.


    Essential Clauses Every Employment Agreement Needs

    A well-drafted employment agreement must clearly define all key terms to avoid disputes.

    • Designation and Scope of Work: Defines job role, reporting structure, and responsibilities.
    • Compensation and CTC Breakdown: Includes salary structure, allowances, deductions, and bonuses.
    • Probation Period: Typically 3–6 months with different notice terms.
    • Notice Period and Termination: Specifies exit terms and grounds for termination.
    • Leave Policy: Covers earned, sick, and casual leaves as per state laws.

    Restrictive Clauses: Non-Compete and Non-Solicitation

    Restrictive clauses protect business interests but must comply with Indian law.

    • Non-Compete Clauses: Post-employment non-competes are generally unenforceable under Section 27 of the Indian Contract Act. However, restrictions during employment are valid.
    • Non-Solicitation Clauses: Prevent employees from poaching clients or staff and are enforceable if reasonable.

    ESOP Provisions and Vesting Schedules

    Employee Stock Option Plans (ESOPs) are common in startups and must be clearly defined.

    • Grant: Number of options offered.
    • Vesting Schedule: Typically includes a 1-year cliff followed by phased vesting.
    • Exercise Price: Cost to convert options into shares.
    • Exit Conditions: Treatment of options on resignation or termination.

    IP Ownership and Moonlighting Rules

    Intellectual Property (IP)

    Employment contracts must include a Work for Hire and IP assignment clause to ensure all work created belongs to the employer.

    Moonlighting

    Dual employment is restricted under several Indian laws. Employers should include an Exclusivity Clause to prevent unauthorized secondary work.


    What Employees Must Check Before Signing

    1. Notice Period Symmetry: Ensure fairness for both parties.
    2. Hidden Salary Conditions: Verify bonus and performance-linked pay.
    3. Bond Clauses: Check for repayment obligations and ensure reasonableness.

    Draft Compliant Employment Agreements with Lawizer

    Using generic templates can lead to legal risks and unenforceable clauses.

    Lawizer helps businesses create legally compliant and customized employment agreements.

    Why Choose Lawizer?

    • State-Specific Compliance
    • Industry-Based Customization
    • Legally Enforceable Clauses
    • Fast Turnaround
    • Emergency Legal Support
    • Free Consultation
    • Transparent Pricing

    Secure your workforce with legally sound employment agreements today.


    Conclusion

    An employment agreement is the legal foundation of any professional relationship.

    For employers, it safeguards business interests and intellectual property. For employees, it ensures clarity, rights, and job security.

    With proper legal drafting and expert guidance, both parties can avoid disputes and build a transparent working relationship.


    Frequently Asked Questions

    Can an employer terminate an employee without notice?

    A: Yes, but only in cases of serious misconduct. Otherwise, notice or payment in lieu is required.

    Are employment bonds valid in India?

    A: They are enforceable only if reasonable and backed by actual training costs.

    What if I refuse to sign an employment agreement?

    A: Employers may withdraw the offer or initiate termination if terms are not accepted.

    Are digital signatures valid?

    A: Yes, under the Information Technology Act, 2000.

    Can employers change contract terms unilaterally?

    A: No, changes require mutual consent.

    What is Lawizer?

    A: Lawizer is a legal-tech platform that simplifies legal documentation and assistance.

    Is Lawizer legitimate?

    A: Yes, it is a reliable and technology-driven legal platform.

    Is Lawizer a law firm?

    A: No, it is a legal-tech platform, not a traditional law firm.

  • Gift Deed vs Will: Which is Better to Transfer Property to Family in India?

    Gift Deed vs Will: Which is Better to Transfer Property to Family in India?

    Introduction

    Deciding how to pass on your hard-earned property to your loved ones is a significant milestone. In India, property transfers within a family usually come down to two primary legal instruments: a Gift Deed or a Will.

    Both methods achieve the ultimate goal of transferring ownership, but they operate on entirely different timelines, carry distinct financial implications, and offer varying levels of protection against future family disputes.

    Choosing the wrong instrument can lead to unnecessary tax burdens, exorbitant stamp duties, or bitter legal battles for your heirs.

    In this comprehensive guide, we will break down the legal mechanics of Gift Deeds and Wills, compare their tax implications, and help you determine which option is the safest and most efficient for your specific situation.

    We shall also see how Lawizer, a legal-tech platform helps with the drafting of a gift deed or a will.


    What is a Gift Deed and How is it Executed?

    A Gift Deed is a legally binding document used to voluntarily transfer the ownership of a property from the owner (the donor) to another person (the done) without any financial exchange or consideration.

    Under the Transfer of Property Act, 1882, for a gift of immovable property to be legally valid, it must meet specific execution requirements:

    • Immediate Transfer: The transfer happens immediately during the lifetime of the donor.
    • Acceptance: The donee must accept the gift during the donor’s lifetime. If the done dies before accepting, the gift is void.
    • Registration is Mandatory: The gift deed must be signed, attested by two witnesses, and registered with the Sub-Registrar.
    • Irrevocability: Once registered and accepted, it is generally irrevocable.

    What is a Will and When Does it Come into Effect?

    A Will is a testamentary document that declares a person’s intention regarding the distribution of their assets after their death.

    Governed primarily by the Indian Succession Act, 1925, a Will differs significantly from a Gift Deed:

    • Takes Effect After Death: Beneficiaries receive rights only after the testator passes away.
    • Revocable: Can be modified or revoked anytime during lifetime.
    • Registration Optional: Not mandatory but recommended for authenticity.

    Key Differences: At a Glance

    Feature Gift Deed Will
    Time of Transfer Immediate After death
    Revocability Irrevocable Revocable anytime
    Registration Mandatory Optional
    Stamp Duty Applicable None
    Governing Law Transfer of Property Act Indian Succession Act

    Tax Implications of Each Method

    Income Tax and Capital Gains

    Under Section 56(2)(x) of the Income Tax Act, gifts received from specified relatives are exempt from tax.

    Gifts to non-relatives exceeding ₹50,000 are taxable.

    Inheritance through a Will is completely tax-free.

    Capital gains tax applies only when the recipient sells the property later.


    Stamp Duty

    Property transfer via a Will attracts zero stamp duty.

    A Gift Deed requires stamp duty (typically 2%–7%), depending on the state.


    Which is Safer from Legal Challenges?

    A Gift Deed is safer because it is executed and registered during the owner’s lifetime.

    A Will is more prone to disputes and can be challenged on grounds such as:

    • Unsound mind
    • Forgery
    • Coercion
    • Multiple Wills

    In cities like Mumbai, Kolkata, and Chennai, probate may also be required.


    When to Choose Gift Deed vs Will

    When a Gift Deed is Better:

    • Avoid disputes
    • Immediate transfer
    • No probate required
    • Financial security for family

    When a Will is Better:

    • Retain ownership during lifetime
    • Avoid stamp duty
    • Flexibility to change decisions
    • Distribute multiple assets

    Execute a Gift Deed or Draft a Will with Lawizer

    Property transfers require precise legal drafting.

    Lawizer ensures legally compliant, customized, and secure documentation.

    • Accurate Drafting
    • Personalized Advice
    • End-to-End Support
    • Legal Compliance
    • 24/7 Assistance

    Conclusion

    Both a Gift Deed and a Will are effective tools for property transfer.

    A Gift Deed ensures immediate, dispute-free transfer, while a Will offers flexibility and cost savings.

    Choosing the right option depends on your financial goals and family situation.


    Frequently Asked Questions

    Can a registered Gift Deed be cancelled?

    A: Generally no. It can only be cancelled in cases of fraud, coercion, or mutual agreement.

    Is it mandatory to register a Will in India?

    A: No, but registration is recommended for authenticity.

    Who pays stamp duty on a Gift Deed?

    A: Usually the recipient, unless agreed otherwise.

    Can I gift property to a non-relative?

    A: Yes, but it may attract tax.

    Do I need probate for a Will?

    A: Mandatory in Mumbai, Kolkata, Chennai; optional elsewhere.

    Is Lawizer a law firm?

    A: No, it is a legal-tech platform.

    Who is behind Lawizer?

    A: Lawizer is an initiative of Zeptus Pvt Ltd.

  • Angel Tax Exemptions under Section 80-IAC: A Founder’s Guide

    Angel Tax Exemptions under Section 80-IAC: A Founder’s Guide

    Introduction

    Starting a business in India is exciting, but founders often face complex tax rules while raising funds. One such issue that troubled startups for years was angel tax.

    To encourage innovation and investment, the government introduced several exemptions for eligible startups.

    One of the most important provisions founders should understand is Section 80-IAC of the Income Tax Act, 1961, which works alongside Startup India recognition and angel tax exemptions.

    In this guide, we explain what angel tax is, how Section 80-IAC benefits startups, eligibility requirements, and how founders can take advantage of these provisions.


    Understanding Angel Tax

    Angel tax refers to the tax imposed on startups when they raise funds at a valuation higher than the Fair Market Value (FMV) of their shares.

    This provision falls under Section 56(2)(viib) of the Income Tax Act.

    If a startup issues shares at a premium and the valuation is considered excessive, the excess amount is taxed as income from other sources.

    Example

    Suppose a startup issues shares with a face value of ₹10, but investors buy them at ₹100 per share.

    The difference of ₹90 per share may be taxed if the valuation cannot be justified.

    This created challenges because startups are valued based on future potential rather than current profits.


    Role of Section 80-IAC in Supporting Startups

    To promote entrepreneurship, the government introduced Section 80-IAC.

    This section provides a 100% tax deduction on profits for three consecutive years within the first ten years of incorporation.

    Although Section 80-IAC focuses on income tax benefits, startups eligible under this section and recognized under Startup India can also apply for angel tax exemption.

    It helps startups by:

    • Improving financial stability
    • Increasing investor confidence
    • Reducing tax burden in early stages

    Eligibility Criteria for Section 80-IAC

    To claim benefits, startups must meet the following conditions:

    1. DPIIT Recognition

    The startup must be recognized under the Startup India initiative.

    2. Incorporation Type

    The entity must be a Private Limited Company or LLP.

    3. Incorporation Period

    It must be incorporated between 1 April 2016 and 31 March 2025.

    4. Turnover Limit

    Annual turnover must not exceed ₹100 crore.

    5. Innovation Requirement

    The business should focus on innovation, improvement, or scalable models.

    6. IMB Certification

    Approval from the Inter-Ministerial Board (IMB) is required.


    Angel Tax Exemption for Startups

    Startups with DPIIT recognition can apply for angel tax exemption.

    If approved, they are not taxed under Section 56(2)(viib) for eligible investments.


    Conditions for Angel Tax Exemption

    1. Capital Limit

    Total paid-up capital and share premium must not exceed ₹25 crore.

    Certain investments are excluded, such as funds from:

    • Venture Capital Funds
    • Venture Capital Companies
    • Listed Companies
    • Specified investors

    2. Asset Restrictions

    For 7 years, startups cannot invest in non-business assets such as:

    • Non-business land
    • Residential property
    • Loans to other entities
    • Capital investments elsewhere

    This ensures funds are used for business growth.


    Benefits for Startup Founders

    Easier Fundraising

    Investors prefer startups with tax clarity.

    Tax Savings

    100% profit deduction for 3 years boosts reinvestment.

    Reduced Compliance Risk

    Minimizes scrutiny on valuation.

    Investor Confidence

    Encourages participation from angels and VCs.


    How to Apply for Angel Tax Exemption

    1. Incorporate as a Private Limited Company or LLP
    2. Apply for DPIIT recognition
    3. Submit required documents
    4. Apply for Section 80-IAC via IMB
    5. File declaration for exemption

    Once approved, startups can raise funds more efficiently.


    Common Mistakes Founders Should Avoid

    • Delaying DPIIT registration
    • Incorrect valuation reports
    • Exceeding ₹25 crore capital limit
    • Investing in restricted assets

    Proper planning ensures full compliance.


    Conclusion

    Angel tax was introduced to prevent misuse of share valuation but created challenges for genuine startups.

    With provisions like Section 80-IAC and Startup India recognition, the system now supports innovation while maintaining compliance.

    Understanding these benefits helps founders raise funds, reduce taxes, and scale efficiently.

    With the right legal guidance, startups can maximize benefits and avoid unnecessary tax burdens.


    Frequently Asked Questions

    What is angel tax?

    A: It is a tax on excess share premium above fair market value.

    Which section governs angel tax?

    A: Section 56(2)(viib) of the Income Tax Act.

    What does Section 80-IAC provide?

    A: 100% tax deduction on profits for 3 years.

    Who grants startup recognition?

    A: DPIIT under Startup India.

    What is the turnover limit?

    A: ₹100 crore annually.

    Is angel tax applicable to all investments?

    A: No, certain investors are exempt.

  • Your Tenant Won’t Leave. Now What? | Lawizer Blog

    Your Tenant Won’t Leave. Now What? | Lawizer Blog

    Free legal consultation for new clients  ·  Book yours at lawizer.com →Lawizer

    Free Consultation

    Property Law · India

    Your Tenant Won’t Leave.
    Now What?

    A no-jargon guide for Indian landlords dealing with non-paying or non-vacating tenants — and how to resolve it legally, quickly, and without a single court visit.

    By Lawizer Legal Team|8 min read|PropertyTenant Disputes

    “My tenant stopped paying rent and I didn’t know I had this much legal power. Lawizer sent the notice, and the tenant vacated within a week.”

    — Rajesh K., Noida — Lawizer Client

    7 days

    Average time to tenant response after a legal notice

    ₹0

    Cost of your first consultation with a Lawizer attorney

    100%

    Handled online — no court visits required at the notice stage

    The Situation No Landlord Expects:

    You trusted someone with your property. You signed a rent agreement. And now — they’ve stopped paying, stopped responding, or flatly refused to leave when the agreement expired. You’re owed money. Your property is stuck. And every time you think about going to court, you imagine years of hearings, lawyer fees, and exhausting paperwork.

    Here’s what most landlords in India don’t realize: you have far more power than you think, and most tenant disputes are resolved long before they reach a courtroom.

    This guide walks you through exactly what to do — step by step — from the moment you realize there’s a problem.

    “A well-drafted legal notice resolves more tenant disputes than all the court orders combined.”

    First, Know Where You Stand Legally:

    India doesn’t have a single national tenancy law. Depending on your state, your rights as a landlord are governed by one of these frameworks:

    Applicable Laws by State Type

    • States with Rent Control Acts (Delhi, Maharashtra, West Bengal, Tamil Nadu) — stronger tenant protections, specific eviction grounds required
    • States with new Model Tenancy Act alignment — more balanced landlord-tenant framework
    • Agreements registered under Transfer of Property Act, 1882 — contracts with teeth regardless of state-level rent control

    The most important document you have is your registered rent agreement. If it’s properly registered and clearly states the tenancy period, rent amount, and vacating clause — you’re in a strong position. If your agreement is unregistered or expired, don’t panic. You still have options, but timing matters.

    Your 5-Step Action Plan:

    01

    Document Everything Right Now

    Collect all rent receipts, bank transfer records, WhatsApp messages, and the signed agreement. Screenshot every message where you requested payment or vacation. This paper trail becomes your case.

    02

    Send a Formal Legal Notice

    This is the single most effective step. A legal notice sent by a lawyer via registered post carries serious weight. It signals you’re serious, creates a legal record, and gives the tenant a deadline to respond. Many disputes end here.

    03

    Negotiate a Settlement

    If the tenant responds, there’s often room to negotiate a departure timeline or partial payment. A structured exit — even if imperfect — is faster than litigation. Have a lawyer supervise any written agreement.

    04

    File an Eviction Case if Required

    Under the Transfer of Property Act Sec. 106 and your state’s Rent Control Act, you can file for eviction citing non-payment, misuse of property, or expiry of tenancy. Summary proceedings under CPC Order 37 allow faster recovery of dues.

    05

    Recover Unpaid Rent

    Rent recovery is a civil suit. Once you have a decree, the tenant’s movable assets or bank accounts can be attached. Combined with the eviction proceeding, most lawyers structure this as a single coordinated filing.

    Landlords underestimate the psychological and legal power of a formal notice. Here’s what it actually does:

    It creates a legal record. The moment your lawyer sends a registered notice, the clock starts. Any court proceeding later will note when you first formally demanded rent or vacation — this date matters for calculating dues and establishing bad faith on the tenant’s part.

    It triggers the response deadline. Under the Transfer of Property Act Sec. 106, tenants on a monthly lease must receive 15 days’ notice for termination. A formal notice starts this clock precisely.

    It moves the dispute out of the informal zone. Verbal requests, WhatsApp pleas, and in-person conversations carry no legal weight. A lawyer’s notice changes the entire dynamic — tenants who ignored you for months often respond within days.

    Lawizer Can Help

    Get a Legal Notice Drafted & Sent Today

    Our property lawyers review your agreement, draft a watertight notice, and send it via registered post — completely online. No office visit required. Consult a Property Lawyer Free →

    The 4 Mistakes Landlords Make (That Hurt Their Case)

    1. Cutting off electricity or water

    This feels satisfying. It is illegal. Courts treat it as coercion, and it can turn the landlord into the defendant. Do not do this under any circumstances.

    2. Accepting rent after the agreement expires

    If you accept even one month’s rent after the lease ends without a renewal, you may have legally created a periodic tenancy — and reset your eviction clock. Talk to a lawyer before accepting any post-agreement payments.

    3. Entering the property without notice

    Even as the owner, entering the tenant’s premises without advance notice (typically 24 hours) can constitute trespass. Document any entry attempts in writing.

    4. Waiting too long to act

    Every month of unpaid rent is a month of recoverable dues — but courts also look at whether you acted promptly. A six-month delay weakens your position. If the tenant hasn’t paid, issue a notice within 30 days of the first missed payment.

    Common Questions Landlords Ask Us:

    My rent agreement isn’t registered. Do I still have rights?

    Yes. An unregistered agreement is still evidence of the tenancy arrangement. However, it cannot be produced in court as primary evidence in the same way a registered document can. That said, bank records and messages corroborating rent payment can supplement the claim. Consult a lawyer to assess your specific situation.

    Can I ask the police to remove a tenant?

    In most cases, no. Tenancy disputes are civil matters. Police will not forcibly remove a tenant without a court order. However, if the tenant has physically threatened you or caused damage to property, an FIR and relevant IPC provisions may apply.

    How long does an eviction case actually take?

    It varies by state and court load. In Rent Control Tribunals (common in metro cities), cases can stretch from 6 months to several years. However, most disputes that begin with a proper legal notice are settled before a final order — which is exactly why that first step is so critical.

    What if the tenant just refuses to open the door?

    Once you have a court order for eviction, a court commissioner — accompanied by the local police — can enforce it. But you need the order first. The process is: notice → no compliance → court filing → order → enforcement.

    The landlord who documents everything and acts quickly wins. The one who waits six months hoping things resolve themselves — rarely does.

    The Bottom Line:

    A difficult tenant is stressful. But it’s a legal problem with a legal solution — and you don’t have to figure it out alone.

    Start with a free consultation. Have a lawyer look at your agreement and your situation. In most cases, a single strong legal notice is all it takes.

    Lawizer’s property lawyers have handled hundreds of landlord-tenant disputes across India — completely online, at transparent fees, with no surprise charges.

    If your tenant has stopped paying or won’t leave, the best time to act was last month. The second best time is today.

    In This Article

    1. 01 The situation no landlord expects
    2. 02 Know where you stand legally
    3. 03 Your 5-step action plan
    4. 04 The power of a legal notice
    5. 05 4 mistakes to avoid
    6. 06 Common questions answered
    7. 07 The bottom line

    Facing a tenant dispute right now?

    Talk to a Lawizer property lawyer free. We’ll tell you exactly where you stand in 30 minutes.Book Free Consultation

    Related Property Services

    More from the Lawizer Blog

    Startup Law Registering Your Company in India: The 7 Things No One Tells You Banking Cheque Bounce Under Section 138: Your Complete Legal Guide Tax ITR Filing Deadline 2025: Penalties, Extensions, and What to Do If You Missed It © 2026 Lawizer. All rights reserved.  ·  Privacy Policy  ·  Terms of Service  ·  +91 90628 15535

  • ESOP Management 101: How to Retain Top Talent for Your Startup

    ESOP Management 101: How to Retain Top Talent for Your Startup

    Introduction

    Building a startup is very challenging and Building a great team is even more challenging.

    In the early days, one might not have the money to offer high salaries like big companies. Yet, you still need smart, dedicated people who believe in your vision. This is where ESOPs come in.

    If you are a startup founder in India, understanding ESOP management is not optional anymore. It is one of the smartest ways to retain top talent and build long-term loyalty.


    What Is an ESOP?

    ESOP stands for Employee Stock Ownership Plan (or Employee Stock Option Plan).

    In simple words, an ESOP gives employees the right to buy shares of the company at a fixed price in the future. If the company grows and its valuation increases, those shares become valuable.

    Instead of only paying salary, you give employees a chance to become part-owners. It changes their mindset from: “I work here.” to “I am building this.”


    Why ESOP Management Matters for Startups?

    Startups are risky. Employees know that. When they join a startup, they are taking a leap of faith.

    Good ESOP management helps in:

    • Attracting strong talent
    • Retaining key employees
    • Aligning employee goals with company growth
    • Reducing attrition
    • Building a performance-driven culture

    Many startups registered under Startup India use ESOPs as a strategic tool to compete with larger corporations.

    In cities like Bengaluru, Mumbai, and Hyderabad, ESOPs have become almost standard practice in the startup ecosystem.


    How ESOPs Help Retain Top Talent?

    1. They Create Long-Term Commitment

    ESOPs usually come with a vesting schedule. This means employees earn their shares gradually over time. For example:

    • 4-year vesting period
    • 1-year cliff (no shares if they leave before 1 year)

    This structure encourages employees to stay longer. If they leave early, they lose unvested shares. This naturally improves retention.

    2. They Align Interests

    When employees own shares, they think differently. They care about:

    • Company valuation
    • Profitability
    • Customer satisfaction
    • Cost control

    Their success becomes directly linked to the company’s success. That alignment is powerful.

    3. They Build an Ownership Culture

    Top talent doesn’t just want a salary. They want impact. They want recognition. They want to feel important.

    ESOPs send a strong message: “You are not just an employee. You are a partner in growth.”

    That emotional connection builds loyalty.


    Common ESOP Mistakes Startups Make

    Even though ESOPs are powerful, poor ESOP management can create confusion and dissatisfaction. Here are common mistakes:

    1. No Clear Communication

    Many founders say, “You will get ESOPs,” but never explain:

    • How many shares?
    • What percentage?
    • What is the strike price?
    • When can they sell?

    Employees may not understand the real value. Transparency is key.

    2. Overpromising Valuation

    Telling employees, “These shares will be worth crores one day,” creates unrealistic expectations.

    Startup growth is uncertain. Be honest about risks.

    3. No Legal Structure

    In India, ESOPs must follow Companies Act guidelines if the company is a Private Limited Company.

    Proper board approval, shareholder approval, and documentation are required.

    Without proper structure, ESOPs can create legal complications later.

    4. Poor Exit Planning

    Employees often ask: “When can I sell my shares?”

    If there is no liquidity event (IPO or acquisition), shares may not convert into cash immediately. Clear policies around buybacks or exit events are important for good ESOP management.


    How to Design an Effective ESOP Plan?

    Now let’s talk practical steps.

    Step 1: Decide the ESOP Pool Size

    Most startups create an ESOP pool of 5%–15% of total equity.

    This pool is reserved specifically for employees.

    Step 2: Create a Vesting Schedule

    A standard vesting structure is:

    • 4 years total
    • 1-year cliff
    • Monthly or quarterly vesting after that. This ensures long-term commitment.

    Step 3: Define Eligibility Clearly

    Not every employee may get ESOPs. You can allocate ESOPs to:

    • Senior leadership
    • Key technical team members
    • High-performing employees, Be clear and consistent in allocation.

    Step 4: Communicate the Value Properly

    Do not just say “You have 1,000 options.”

    Explain:

    • Current company valuation
    • Strike price
    • Potential upside
    • Risks involved

    When employees understand the real picture, they trust the system more.

    Step 5: Keep Compliance in Check

    Follow proper legal procedures. Board approvals, documentation, grant letters, and maintaining an ESOP register are important. Clean documentation builds investor confidence during funding rounds.


    ESOPs and Startup Growth

    When managed properly, ESOPs can:

    • Reduce hiring costs
    • Improve retention
    • Increase productivity
    • Strengthen culture
    • Attract investors

    Investors also like companies where employees have skin in the game. It shows commitment and stability.

    In competitive startup ecosystems, ESOP management is no longer optional. It is strategic.


    Conclusion

    Retaining top talent is one of the biggest challenges for startups. You may not always compete on salary. But you can compete on ownership, vision, and long-term wealth creation.

    ESOP management is not just about giving shares. It is about building belief. When employees feel like co-creators instead of workers, they stay longer, work harder, and think bigger.

    And in the startup world, that mindset makes all the difference.


  • DPIIT Recognition: How Lawizer Helps Startups Unlock Government Benefits

    DPIIT Recognition: How Lawizer Helps Startups Unlock Government Benefits

    Introduction

    India has emerged as one of the fastest-growing startup ecosystems in the world. Thousands of entrepreneurs are building innovative businesses in sectors such as technology, healthcare, fintech, and education.

    To support these startups, the Government of India launched the Startup India initiative. Under this initiative, startups can obtain recognition from the Department for Promotion of Industry and Internal Trade (DPIIT).

    DPIIT recognition allows startups to access multiple government benefits including tax exemptions, funding opportunities, intellectual property support, and simplified compliance requirements.

    However, many founders struggle with the process and documentation involved. This is where platforms like Lawizer help startups unlock these benefits easily.


    What is DPIIT Recognition?

    DPIIT Recognition is an official certification granted to startup companies by the Department for Promotion of Industry and Internal Trade under the Startup India initiative.

    This recognition formally identifies a business as an eligible startup engaged in innovation or scalable business development.

    Once a startup receives DPIIT recognition, it becomes eligible for several government incentives and support schemes designed to help early-stage businesses grow.


    Eligibility Criteria for DPIIT Recognition

    To obtain DPIIT recognition, a startup must satisfy certain eligibility conditions.

    1. Type of Entity

    The business must be registered as one of the following:

    • Private Limited Company
    • Limited Liability Partnership (LLP)
    • Registered Partnership Firm

    2. Age of the Company

    The company should be less than 10 years old from the date of incorporation.

    3. Annual Turnover

    The startup’s annual turnover must not exceed ₹100 crore in any financial year since its incorporation.

    4. Innovation and Scalability

    The startup must focus on innovation or improvement in products or services. The business should aim to:

    • Develop new technology or processes
    • Improve existing products or services
    • Build a scalable business model
    • Generate employment or wealth creation

    Benefits of DPIIT Recognition for Startups

    1. Tax Holiday for Startups

    Early-stage startups often operate with limited financial resources. DPIIT-recognized startups can apply for a tax holiday under Section 80-IAC of the Income Tax Act.

    This provides 100% income tax exemption on profits for three consecutive years within the first ten years of incorporation.

    This benefit allows startups to reinvest their profits into:

    • Product development
    • Research and innovation
    • Business expansion

    2. Angel Tax Exemption

    Angel tax earlier created challenges for startups raising funds from investors.

    Angel tax applied when startups issued shares at a price higher than their fair market value. With DPIIT recognition, eligible startups can receive investments from angel investors without facing this tax burden.

    This makes fundraising easier and encourages more investors to support innovative startups.

    3. Access to Government Funding Schemes

    DPIIT recognition also provides startups with access to government funding programs such as:

    • Fund of Funds for Startups (FFS)
    • Startup India Seed Fund Scheme

    These schemes help startups receive financial assistance for:

    • Product development
    • Market entry
    • Scaling business operations

    Being DPIIT-recognized also increases a startup’s credibility among investors.

    4. Simplified Regulatory Compliance

    Startups often face complex regulatory requirements that consume time and resources.

    DPIIT-recognized startups are allowed to self-certify compliance with several labour and environmental laws.

    This reduces:

    • Frequent inspections
    • Regulatory paperwork
    • Administrative burden

    5. Intellectual Property (IP) Support

    Innovation is a key part of startup growth. DPIIT recognition provides strong support for intellectual property protection.

    Startups receive:

    • Fast-track patent examination
    • Up to 80% rebate on patent filing fees
    • Around 50% rebate on trademark registration fees

    How Does Lawizer Make the Process Seamless?

    Many startups are unaware of the documentation and procedures required for DPIIT recognition.

    Lawizer is a legal and business consulting platform that helps startups navigate regulatory compliance and government registrations smoothly.

    Lawizer assists startups in multiple areas including:

    • Company incorporation
    • Legal documentation
    • Intellectual property registration
    • DPIIT recognition
    • Compliance management

    Why Choose Lawizer?

    • Expert Guidance: Step-by-step assistance for accurate application filing.
    • Documentation Support: Reduces chances of rejection.
    • Faster Processing: Ensures smooth submission on Startup India portal.
    • End-to-End Support: Covers legal, compliance, and funding guidance.

    How Lawizer Simplifies the DPIIT Registration Process

    Step 1: Assistance with Documentation

    Lawizer helps founders prepare all the required documents needed for DPIIT recognition. This includes drafting a clear description of the startup’s innovative activities and business model.

    Step 2: Startup India Portal Registration

    The team assists startups in submitting their application through the Startup India portal. With expert guidance, the process becomes faster and smoother.

    Step 3: Guidance on Government Benefits

    Lawizer helps startups understand and apply for tax exemptions, government grants, intellectual property benefits, and funding schemes.

    Step 4: Ongoing Legal and Compliance Support

    Lawizer supports startups with shareholder agreements, legal documentation, regulatory compliance, and intellectual property protection.


    Conclusion

    DPIIT recognition plays a vital role in strengthening India’s startup ecosystem. It provides startups with tax incentives, funding opportunities, simplified compliance, and intellectual property support.

    However, navigating the recognition process and accessing these benefits can be challenging for new entrepreneurs.

    Companies like Lawizer simplify this journey by helping startups obtain DPIIT recognition and unlock the full range of government benefits available under the Startup India initiative.

    With the right guidance and government support, startups can innovate faster, scale their businesses, and contribute to India’s economic growth.


    Frequently Asked Questions

    What is DPIIT recognition?

    A: DPIIT recognition is a certification granted by the Department for Promotion of Industry and Internal Trade that officially identifies a business as an eligible startup under the Startup India initiative.

    Who can apply for DPIIT recognition?

    A: Private Limited Companies, LLPs, and Registered Partnership Firms that are less than 10 years old with turnover below ₹100 crore can apply.

    What are the benefits of DPIIT recognition?

    A: DPIIT-recognized startups receive tax exemptions, funding opportunities, compliance relaxations, and intellectual property benefits.

    Is DPIIT recognition mandatory for startups?

    A: No, DPIIT recognition is optional but highly beneficial for accessing government schemes and incentives.

    How long does it take to get DPIIT recognition?

    A: If all documents are correct, DPIIT recognition can usually be granted within a few days to a few weeks.

    Can DPIIT-recognized startups raise funds easily?

    A: Yes, DPIIT recognition provides exemption from angel tax, making it easier for startups to attract investors.

    Do DPIIT-recognized startups get tax benefits?

    A: Yes, eligible startups can claim a 3-year tax holiday under Section 80-IAC of the Income Tax Act.

    How does Lawizer help with DPIIT recognition?

    A: Lawizer helps startups with documentation, application filing, and guidance on accessing government benefits.


  • Common Mistakes to Avoid While Filing ITR for Salaried Employees in 2026

    Common Mistakes to Avoid While Filing ITR for Salaried Employees in 2026

    Introduction

    Filing an Income Tax Return (ITR) as a salaried employee often feels like navigating a bureaucratic maze. In 2026, the Income Tax Department has shifted toward advanced AI-driven data processing.

    This means even a minor clerical error can trigger an automatic tax notice.

    While technology has increased scrutiny, legal-tech platforms like Lawizer have made the process seamless. By connecting you with verified experts, Lawizer ensures your filing is stress-free and accurate.


    10 Common ITR Filing Mistakes You Must Avoid

    To ensure a smooth filing season, keep an eye out for these frequent pitfalls:

    1. Selecting the Wrong ITR Form

    Choosing the incorrect form results in a “Defective Return” notice.

    • ITR-1 (Sahaj): For individuals with income up to ₹50 lakhs and one house property.
    • ITR-2: For those with capital gains, multiple house properties, or income exceeding ₹50 lakhs.
    • ITR-3: For individuals with business or professional income.

    2. Quoting the Wrong Assessment Year (AY)

    For the current Financial Year (FY 2025-26), the corresponding Assessment Year is 2026-27. Confusing these dates can lead to double taxation or immediate rejection.

    3. Errors in Personal and Bank Information

    Your bank account must be pre-validated on the portal. Ensure your name and address match your PAN exactly. An incorrect IFSC code can stall your refund for months.

    4. Failure to Disclose “Hidden” Income Sources

    Don’t forget to report:

    • Savings Interest: Deductible up to ₹10,000 under Sec 80TTA.
    • Dividends: Often overlooked but taxable.
    • Minor’s Income: Deductible up to ₹1,250 per child (up to 2 children).

    5. Manual Entry and Formatting Errors

    Data must match your employer’s TDS filing perfectly. Inconsistent formatting often leads to automated system rejections.

    6. Ignoring AIS and TIS Reconciliations

    The Annual Information Statement (AIS) tracks stock trades, FD interest, and large credit card spends. If your ITR doesn’t match your Taxpayer Information Summary (TIS), an inquiry is almost certain.

    7. Mismatching TDS with Form 26AS

    Always verify that the tax deducted by your employer or bank is reflected in Form 26AS. If it isn’t, you won’t receive credit for that tax, resulting in a higher payout.

    8. Forgetting Section 80 Deductions

    Look beyond Section 80C. You can also claim:


  • Why Every Indian Startup Needs a Strong Founder’s Agreement

    Why Every Indian Startup Needs a Strong Founder’s Agreement

    Introduction

    Starting a business is exciting and thrilling. It often begins with a powerful idea, a late-night conversation, or a shared dream between friends.

    In the early days, everything feels possible. Everyone is motivated. Everyone trusts each other.

    But while passion and trust are important, they are not enough to build a successful company. This is exactly where a founder’s agreement for startups becomes essential.

    Many Indian startups fail not because the idea was weak or the founders were not hardworking. They fail because the founders were not aligned.

    Misunderstandings, money disputes, unclear responsibilities, or ego clashes slowly damage the business. A strong founder’s agreement for startups can prevent these problems before they even begin.


    What Is a Founder’s Agreement for Startups?

    A founder’s agreement for startups is a legal document signed by co-founders at the early stage of the company. It clearly defines the relationship between the founders and sets expectations from day one.

    It usually answers key questions like:

    1. Who owns how much of the company?
    2. What are each founder’s roles and responsibilities?
    3. How will important decisions be made?
    4. What happens if a founder leaves?
    5. How will disputes be resolved?

    In simple words, it protects both the business and the people involved.

    In India, startups are commonly registered as a Private Limited Company or a Limited Liability Partnership. No matter the structure, having a founder’s agreement for startups is equally important.


    Why Is a Founder’s Agreement for Startups So Important in India?

    India’s startup ecosystem is growing rapidly. Cities like Bengaluru, Mumbai, and Hyderabad are becoming major startup hubs.

    With growth comes competition, investor pressure, and legal complexities. Here’s why every Indian startup needs a strong founder’s agreement for startups:

    1. It Prevents Future Conflicts

    In the beginning, no one thinks about worst-case scenarios. Everyone assumes things will work out smoothly.

    But what if:

    • One founder contributes more time than the others?
    • One founder wants to sell their shares?
    • One founder resigns after six months?

    Without a written founder’s agreement for startups, these situations can turn ugly. Disagreements become personal. The company suffers.

    A clear agreement sets expectations from day one. It reduces confusion and protects relationships.


    2. It Protects Equity and Ownership

    Equity is emotional. It represents ownership, control, and future wealth. Many founders split shares equally without discussing long-term contributions.

    But is equal always fair?

    One founder may bring the idea. Another may bring capital. Another may manage daily operations. A strong founder’s agreement for startups clearly defines:

    • The equity split
    • The vesting schedule (earning shares over time)
    • What happens to shares if someone exits

    Vesting is extremely important. It ensures that no founder walks away with a large percentage of ownership without contributing long-term value.


    3. Investors Expect It

    If you plan to raise funding, investors will almost always ask, “Do you have a founder’s agreement?” Investors look for stability.

    Many startups registered under Startup India later realise that investors carefully examine founder agreements before investing. A well-drafted founder’s agreement for startups builds trust, credibility, and confidence.


    4. It Clearly Defines Roles and Responsibilities

    Unclear roles are one of the biggest reasons startups fail.

    For example:

    • Who handles finance?
    • Who manages marketing?
    • Who makes the final business decisions?

    If two founders both believe they are the “CEO,” conflict is inevitable.

    A founder’s agreement for startups clearly defines:

    • Titles
    • Duties
    • Authority levels
    • Time commitment

    This clarity avoids overlapping responsibilities and unnecessary power struggles.


    5. It Covers Exit and Separation

    Not all partnerships last forever. Life changes. Priorities shift.

    A founder may want to:

    • Move abroad
    • Study further
    • Start another venture
    • Take a break

    A strong founder’s agreement for startups answers critical questions like:

    • Can a founder sell shares to outsiders?
    • Do other founders get the first right to buy those shares?
    • What happens in case of death or incapacity?

    Planning for exit does not mean you expect failure. It simply means you are being practical and prepared.


    6. It Protects Intellectual Property (IP)

    In startups, ideas are everything. Your app code, brand name, logo, designs, and product formula are all valuable intellectual property.

    Without a founder’s agreement for startups, confusion may arise about who owns what.

    A proper agreement clearly states that all intellectual property belongs to the company, not to individual founders.


    7. It Helps During Legal Disputes

    If disagreements escalate, the founder’s agreement becomes your strongest protection.

    It usually includes:

    • Dispute resolution methods
    • Arbitration clauses
    • Governing law (Indian law)

    This makes resolving conflicts faster, smoother, and less expensive.


    Why Many Indian Founders Ignore It

    Despite its importance, many founders delay drafting a founder’s agreement for startups because:

    • “We are friends.”
    • “We trust each other.”
    • “We will figure it out later.”
    • “Legal documents are expensive.”

    Money, pressure, investor expectations, and market competition can change dynamics. A written agreement does not show distrust. It shows professionalism and maturity.


    What Should a Strong Founder’s Agreement Include?

    For full protection, a founder’s agreement for startups should cover:

    1. Founder details
    2. Equity split
    3. Vesting schedule
    4. Roles and responsibilities
    5. Decision-making process
    6. Salary and compensation
    7. Confidentiality clauses
    8. Non-compete clauses
    9. Exit terms
    10. Dispute resolution mechanism

    It should always be drafted carefully, ideally with professional legal guidance.


    Conclusion

    Starting a business is like starting a journey. And no journey is smooth without a clear map.

    A founder’s agreement for startups is not just another legal formality. It is a protection shield. It protects friendships, ownership, attracts investors, and secures the future of the company.


    Frequently Asked Questions

    What is a Founder’s Agreement?

    A Founder’s Agreement is a legal document that defines the roles, responsibilities, and equity ownership of startup founders.

    Why is a Founder’s Agreement important?

    It prevents disputes among founders by clearly outlining responsibilities, ownership, and decision-making authority.

    When should startups create a Founder’s Agreement?

    Startups should ideally create a Founder’s Agreement at the time of company incorporation.

    What clauses are included in a Founder’s Agreement?

    Common clauses include equity distribution, vesting schedules, intellectual property ownership, founder roles, and exit terms.

    Does a Founder’s Agreement help in raising investment?

    Yes, investors prefer startups that have clear legal agreements between founders.

    What is founder equity vesting?

    Founder vesting means founders earn their equity gradually over time rather than receiving it immediately.

    Who owns intellectual property in a startup?

    A Founder’s Agreement ensures that intellectual property created by founders belongs to the company.

    Can a Founder’s Agreement resolve founder disputes?

    Yes, it provides dispute resolution mechanisms such as mediation or arbitration.

  • Benefits of Registering as a Private Limited Company in India

    Introduction

    Choosing the right business structure is one of the most important decisions for any entrepreneur.

    In India, registering as a Private Limited Company under the Ministry of Corporate Affairs offers several legal, financial, and strategic advantages.

    Whether you are launching a startup or scaling an existing venture, understanding the benefits of registering as a private company can help you make a confident and informed decision.


    What is a Private Limited Company?

    A Private Limited Company is a legally recognized business entity with:

    • Limited liability for shareholders
    • Separate legal identity
    • Perpetual succession
    • Structured compliance requirements

    It is one of the most preferred business structures in India due to its credibility and growth potential.


    Key Benefits of Registering as a Private Limited Company

    1. Limited Liability Protection

    One of the biggest advantages of a private limited company is limited liability.

    This means:

    • Shareholders are only liable up to the amount they have invested.
    • Personal assets remain protected from business debts or legal claims.

    If the company faces financial losses or lawsuits, the personal property of owners is safeguarded. This reduces financial risk and encourages entrepreneurs to take calculated business decisions.


    2. Separate Legal Entity

    A Private Limited Company is legally distinct from its owners.

    This allows the company to:

    • Own property in its own name
    • Enter into contracts
    • Sue or be sued independently

    The company’s identity remains separate from its shareholders, ensuring operational stability.


    3. Perpetual Succession

    Unlike sole proprietorships or partnerships, a private limited company continues to exist even if:

    • A shareholder exits
    • A director resigns
    • Ownership changes

    This concept of perpetual succession ensures long-term business continuity and enhances investor confidence.


    4. Better Access to Funding

    Funding becomes significantly easier when you operate as a registered private limited company.

    You can:

    • Issue shares to raise capital
    • Attract venture capitalists and angel investors
    • Secure bank loans more easily

    Financial institutions prefer registered companies because of structured compliance and transparency.


    5. Enhanced Credibility and Brand Image

    Registration with the Ministry of Corporate Affairs increases business credibility.

    Clients, vendors, and partners often perceive private limited companies as:

    • More professional
    • More reliable
    • Better regulated

    This credibility can open doors to larger contracts and long-term partnerships.


    6. Easy Transfer of Ownership

    Ownership in a private limited company can be transferred through the transfer of shares.

    This makes it easier to:

    • Bring in new investors
    • Restructure ownership
    • Exit existing shareholders

    Business operations continue smoothly without disruption.


    7. Tax Benefits and Structured Compliance

    Private limited companies enjoy structured corporate tax rates and can claim deductions on legitimate business expenses.

    Additionally:

    • Proper financial reporting improves transparency
    • Statutory compliance builds investor trust
    • Organized records support long-term expansion

    8. Scalability and Growth Potential

    If your goal is business expansion, a private limited structure offers strong scalability.

    It allows you to:

    • Expand across regions
    • Attract institutional investment
    • Convert into a public company in the future

    This makes it ideal for startups planning long-term growth.


    9. Better Talent Acquisition

    Private limited companies can attract skilled professionals more easily.

    They can offer:

    • Job stability
    • Structured work roles
    • Employee Stock Option Plans (ESOPs)

    This helps in building a strong and motivated team.


    Conclusion

    Registering as a Private Limited Company in India provides legal protection, improved credibility, funding opportunities, and long-term growth advantages.

    Although compliance requirements and documentation are involved, the strategic benefits outweigh the initial effort. For entrepreneurs aiming to build a scalable and investor-friendly business, registering as a private company is often the smartest decision.


    Frequently Asked Questions

    What is a Private Limited Company?

    It is a legally registered business entity recognized by the Ministry of Corporate Affairs with limited liability and separate legal status.

    What is the main advantage of registering as a Private Limited Company?

    The primary advantage is limited liability, which protects shareholders’ personal assets.

    Can a Private Limited Company raise funds easily?

    Yes, it can raise capital by issuing shares and attracting investors more easily than unregistered businesses.

  • Legal Consultation Online: How Lawizer Connects You to Experts 24/7

    Introduction

    Online legal consultation has witnessed tremendous growth, especially in India, where digital adoption continues to rise rapidly.

    The legal industry has undergone a major transformation in recent years. What was once considered traditional and conservative has now evolved into a more accessible, approachable, and affordable model.

    Today, individuals and businesses prefer quick, remote, and secure legal advice over traditional in-office visits. This shift has reshaped how legal services are delivered.


    What is Online Legal Consultation?

    Online legal consultation refers to seeking legal advice, document review, or case strategy guidance through digital platforms.

    This may include:

    • Video consultations
    • Phone consultations
    • Chat-based legal advice
    • Email-based legal opinions
    • Digital document review

    Instead of physically visiting a lawyer’s office, clients can now access professional legal support remotely through legal-tech platforms and law firm websites.


    Why Online Legal Consultation Has Escalated Over Time

    1. Increased Legal Awareness

    More individuals are aware of their legal rights and prefer taking preliminary advice before escalating disputes. This proactive approach has increased demand for quick consultations.


    2. Startup & MSME Growth

    The rise of startups and MSMEs has significantly increased the need for affordable legal advice related to:

    • Contracts
    • Compliance
    • Business incorporation
    • Regulatory filings

    Entrepreneurs now seek faster legal clarity without long appointment delays.


    3. Digital Trust & Security

    Secure payment gateways, encrypted communication systems, and verified lawyer networks have strengthened public trust in online legal services.


    4. Government Digital Integration

    Digital filings under the Ministry of Corporate Affairs and the expansion of e-court initiatives have supported the growth of online legal consultation.

    Legal processes are becoming increasingly technology-driven, making remote consultation more practical than ever.


    The Future of Online Legal Consultation

    Online legal services are expected to integrate advanced technologies such as:

    • AI-powered legal assistance
    • Automated document drafting
    • Predictive case analysis
    • Blockchain-based documentation security

    The legal profession is steadily transitioning into a tech-enabled service ecosystem.


    How Lawizer Connects You to Legal Experts 24/7

    Legal issues don’t arise only during office hours. Whether it’s a compliance concern, police-related matter, contract dispute, or women’s safety issue, timely legal advice is critical.

    Lawizer bridges this gap by offering 24/7 digital connectivity to verified legal experts.

    Here’s how the system works:


    1. Instant Digital Access

    Lawizer allows users to raise legal queries anytime—day or night.

    Users can:

    • Submit their issue online
    • Select consultation type
    • Request immediate assistance

    This removes geographical and time barriers completely.


    2. Verified Expert Network

    Lawizer connects clients with verified and experienced lawyers across practice areas such as:

    • Criminal law
    • Family law
    • Corporate compliance
    • Property disputes
    • Women-centric legal matters

    Every expert is vetted before onboarding to ensure professional reliability.


    3. Smart Case Matching System

    Once a user submits a query, the platform categorizes it based on legal domain and urgency.

    The case is routed to the most suitable expert, ensuring:

    • Faster response time
    • Domain-specific advice
    • Accurate legal direction

    This eliminates random allocation and improves consultation efficiency.


    4. Multiple Consultation Modes

    To maintain 24/7 availability, Lawizer offers flexible communication options:

    • Call consultations
    • Video meetings
    • Chat-based advisory
    • Document review support

    Users can choose the format that suits their urgency and comfort.


    5. Immediate Response for Urgent Matters

    For emergencies such as police involvement, threats, or sensitive disputes, Lawizer prioritizes rapid lawyer connection.

    This ensures users receive immediate legal clarity when time is critical.


    6. Transparent and Structured Process

    From booking to payment and follow-ups, the system is fully digital and streamlined.

    This reduces delays and ensures smooth communication between clients and legal experts.


    7. Continuous Support Model

    Unlike traditional systems restricted to office hours, Lawizer’s digital-first structure ensures legal assistance remains accessible round the clock.


    Conclusion

    Online legal consultation has evolved from a convenience-based alternative into a mainstream legal service model.

    Lawizer connects users to legal experts 24/7 through digital accessibility, verified professionals, smart case allocation, and flexible consultation modes.

    By eliminating time and location barriers, it ensures that professional legal support is always within reach—whenever it is needed most.


    Frequently Asked Questions

    What is online legal consultation?

    Answer: It is the process of seeking legal advice digitally through calls, video meetings, chat, or document review.

    Is online legal consultation reliable?

    Answer: Yes, when conducted through verified platforms like Lawizer with vetted legal professionals.

    How quickly can I connect with a lawyer on Lawizer?

    Answer: Users can raise queries instantly and get connected based on urgency and case type.

    Is online legal advice confidential?

    Answer: Yes, consultations are conducted through secure and encrypted communication systems.

    Can businesses use Lawizer for compliance support?

    Answer: Yes, startups and MSMEs can seek assistance for contracts, incorporation, and regulatory compliance.


  • The Essential Checklist for Business Incorporation in India (2026)

    Introduction

    In 2026, forming a company in India has become significantly easier due to digital platforms and integrated regulatory systems.

    However, business incorporation still requires proper planning, documentation, and strict compliance with legal formalities.

    This essential checklist will help you with the entire process to ensure your company is incorporated smoothly, legally, and successfully.


    Why Proper Incorporation Planning Matters

    Choosing the right structure and completing regulatory steps correctly helps:

    • Protect personal liability
    • Ensure tax compliance
    • Build investor confidence
    • Avoid future legal disputes
    • Establish long-term operational stability

    Let’s break down the step-by-step incorporation process.


    1. Decide Your Business Structure

    Before starting the incorporation process, choose the most suitable legal structure based on your goals:

    • Private Limited Company – Ideal for startups seeking funding
    • One Person Company (OPC) – Suitable for solo entrepreneurs
    • Limited Liability Partnership (LLP) – Limited liability with simpler compliance
    • Partnership Firm – Suitable for small professional ventures
    • Sole Proprietorship – Simple structure but no limited liability

    Your decision impacts taxation, funding opportunities, compliance burden, and liability protection.


    2. Obtain Digital Signature Certificate (DSC)

    A Digital Signature Certificate (DSC) is mandatory for filing electronic documents.

    • Directors and authorized signatories must obtain DSC from licensed certifying agencies.
    • It serves as your official digital identity for government filings.

    3. Apply for Director Identification Number (DIN)

    Every proposed director must obtain a Director Identification Number (DIN) from the Ministry of Corporate Affairs.

    • DIN is a unique 8-digit identification number.
    • It is mandatory before submitting incorporation documents.

    4. Name Reservation (RUN / SPICe+)

    Choosing a compliant and unique business name is a crucial step.

    Ensure that:

    • The name is not identical to an existing company or trademark.
    • It complies with MCA naming guidelines.
    • It reflects your business activity and brand identity.

    You can reserve the name through:

    • RUN (Reserve Unique Name)
    • SPICe+ incorporation form

    5. Draft Key Company Documents

    You must prepare foundational legal documents:

    Memorandum of Association (MOA)

    Defines the company’s objectives and permitted activities.

    Articles of Association (AOA)

    Specifies internal governance rules and shareholder rights.

    These documents form the legal backbone of your company.


    6. Prepare Registered Office Proof

    Every company must have a registered office in India.

    Required documents include:

    • Utility bill (issued within last 2 months)
    • Rent agreement (if applicable)
    • No Objection Certificate (NOC) from property owner

    This address becomes the official communication point for government correspondence.


    7. File Incorporation Forms (SPICe+)

    The primary step is filing the SPICe+ (Simplified Proforma for Incorporating Company Electronically) form via the MCA portal.

    SPICe+ covers:

    • Company registration
    • PAN and TAN allotment
    • GST registration (if applicable)
    • EPFO/ESIC registration (if applicable)
    • Bank account integration

    This integrated filing system reduces duplication and speeds up approvals.


    8. PAN, TAN & Bank Account Setup

    After approval:

    • PAN (Permanent Account Number) is auto-generated
    • TAN (Tax Deduction Account Number) is issued
    • Open a current business bank account
    • Deposit initial share capital

    These steps activate your company financially.


    9. GST Registration (If Applicable)

    GST registration is mandatory if:

    • Your turnover exceeds prescribed thresholds
    • You engage in inter-state trade
    • Your business falls under notified categories

    Early GST registration ensures smooth compliance and invoicing.


    10. Post-Incorporation Compliance

    After incorporation, companies must:

    • Appoint a statutory auditor (within 30 days)
    • Conduct first board meeting (within 30 days)
    • Issue share certificates
    • File commencement of business declaration (if required)
    • Maintain statutory registers

    Annual compliance includes financial statements, annual returns, and tax filings.


    Document Checklist for Business Incorporation

    ✔ Director’s identity proof (PAN, Aadhaar, Passport)
    ✔ Director’s address proof
    ✔ Passport-sized photographs
    ✔ Registered office proof
    ✔ MOA & AOA drafts
    ✔ Consent to act as director
    ✔ Digital Signature Certificate details


    Key 2026 Considerations

    Business incorporation in 2026 involves:

    • Increased digital verification
    • Stronger KYC norms
    • Integrated MCA-GST-tax systems
    • Higher penalties for non-compliance

    Staying updated with regulatory changes is essential.


    Conclusion

    Incorporating a business in India in 2026 is faster and more streamlined than ever before. However, precision in documentation and compliance remains critical.

    By following this essential checklist, you ensure your business is legally structured, financially prepared, and ready for sustainable growth.

    Whether you are launching a startup or expanding operations, proper incorporation sets the foundation for long-term success.


    Frequently Asked Questions (FAQs)

    How long does business incorporation take in India?

    Answer: Typically, it takes 7–15 working days, depending on documentation and approvals.

    Is DIN mandatory for all directors?

    Answer: Yes, every proposed director must obtain a valid DIN.

    Is GST registration compulsory for every company?

    Answer: No, it depends on turnover thresholds and business nature.

    Can I incorporate a company completely online?

    Answer: Yes, the entire incorporation process is digital through the MCA portal.

    What is the most preferred business structure in India?

    Answer: Private Limited Company is commonly preferred for startups and growth-focused businesses.


  • The Role of Lawizer in Scaling Your Fintech Startup Compliantly in India

    The Role of Lawizer in Scaling Your Fintech Startup Compliantly in India

    Introduction

    In the rapidly evolving digital economy of India, fintech startups are no longer just “apps”—they are sophisticated financial institutions operating under the watchful eye of multiple regulators.

    As of 2026, the mantra for success has shifted from “growth at any cost” to “growth through compliance”.

    For a founder, navigating the labyrinth of Indian financial laws while trying to scale is a Herculean task. This is where Lawizer transforms from a service provider into a strategic partner.

    Lawizer is a high-velocity legal-tech platform designed to provide the infrastructure that fintechs need to remain compliant without sacrificing speed.


    The Regulatory Framework of Indian Fintech

    To scale a fintech startup in India, you must understand the three key regulatory pillars: RBI, SEBI, and the DPDP Act.

    RBI’s Digital Lending Framework

    The Reserve Bank of India (RBI) has introduced strict norms under its Digital Lending Directions. Startups acting as Lending Service Providers (LSPs) must ensure:

    • Fund Flow Transparency: Direct transfer from bank/NBFC to borrower; no pool accounts allowed.
    • Key Fact Statement (KFS): Clear disclosure of APR, total loan cost, and recovery terms.
    • Grievance Redressal: Appointment of a nodal officer for complaints.

    Payment Aggregator (PA) Guidelines

    Fintechs handling merchant payments must comply with RBI’s Payment Aggregator framework:

    • Net Worth Requirement: Must reach ₹25 Crore within the prescribed time.
    • Escrow Mechanism: Merchant funds must be routed through regulated escrow accounts.

    Digital Personal Data Protection (DPDP) Act

    Data protection is now a core legal requirement under the DPDP Act:

    • Consent Architecture: Users must be able to give, manage, and withdraw consent.
    • Data Minimization: Only necessary data can be collected.
    • Penalties: Non-compliance can lead to heavy financial penalties.

    How Lawizer Supports Fintech Startup Formation

    Forming a fintech startup requires a legally robust structure that supports funding and compliance. Lawizer simplifies this process:

    Choosing the Right Legal Structure

    • Private Limited Company: Ideal for startups seeking funding and credibility.
    • One Person Company (OPC): Suitable for solo founders.
    • Limited Liability Partnership (LLP): Offers flexibility for partner-led businesses.

    Tax and Business Registrations

    Intellectual Property Protection

    • Trademark Registration: Protects brand identity.
    • Copyright Registration: Secures software and digital assets.

    Scaling and Compliance Support

    As fintech startups grow, compliance becomes an ongoing requirement. Lawizer ensures continuous support:

    • Annual Compliance: Filing and regulatory requirements for companies and LLPs.
    • Corporate Governance: Managing directors, addresses, and legal changes.
    • SOS Feature: Immediate assistance for legal notices and urgent issues.
    • Consultation Support: Access to verified professionals for legal advice.

    Conclusion

    Scaling a fintech startup in India requires navigating complex and evolving regulations.

    From RBI compliance to data protection under the DPDP Act, every aspect of the business must align with legal requirements.

    Lawizer simplifies this journey by automating compliance, managing documentation, and connecting founders with legal experts.

    In a highly regulated environment, having a reliable legal-tech partner ensures sustainable growth and minimizes risk.


    Frequently Asked Questions

    Is Lawizer a law firm?

    Answer: No, Lawizer is a legal-tech platform that connects users with verified professionals and automates legal processes.

    Where is Lawizer based?

    Answer: Lawizer is based in West Bengal, India.

    Is Lawizer legitimate?

    Answer: Yes, Lawizer is an initiative of Zeptus Pvt Ltd and operates as a registered digital service provider.

    Do I need an NBFC license to start a lending app?

    Answer: Yes, if you lend your own funds. Otherwise, you can operate as an LSP under RBI guidelines.

    What is a Regulatory Sandbox?

    Answer: It is a framework by RBI and SEBI that allows fintech startups to test innovative products in a controlled environment.

  • Step-by-Step Guide to GST Registration for Small Shop Owners

    Step-by-Step Guide to GST Registration for Small Shop Owners

    Introduction

    GST registration is a transformative step for any sole proprietorship in India. It is the bridge that transitions a small local business into a legally recognized, tax-compliant entity.

    While the government has digitized the process through integrated portals, the journey often remains challenging due to rigorous documentation and legal verification requirements.

    The Goods and Services Tax (GST) law can be overwhelming for individual shop owners.

    However, utilizing Lawizer, a leading legal-tech solution, enables a stress-free registration process through direct consultations with verified legal experts.


    Understanding GST for Small Store Owners

    GST is a comprehensive, destination-based indirect tax that replaced the fragmented old system of VAT, Service Tax, and Excise Duty. For a small business owner, the business and the individual are legally inseparable.

    Consequently, your Permanent Account Number (PAN) acts as the primary identifier for your 15-digit GST Identification Number (GSTIN).

    Breaking Down the GSTIN

    • First 2 digits: State Code.
    • Next 10 digits: Proprietor’s PAN.
    • Last 3 digits: Entity number, default character, and checksum digit.

    Why Should You Register Today?

    Registering under GST is not just a legal requirement. It opens up growth opportunities for your business and builds long-term credibility.

    1. Legal Compliance: Every business exceeding the threshold limit must register to avoid heavy legal penalties.
    2. Input Tax Credit (ITC): You can claim back the GST paid on business purchases such as furniture, laptops, or shop rent.
    3. Market Expansion: Many large corporations and B2B clients only collaborate with GST-compliant vendors.
    4. E-Commerce Access: A GSTIN is mandatory to sell products on platforms like Amazon, Flipkart, or Myntra.

    2026 Thresholds: When is GST Registration Compulsory?

    As of 2026, the following turnover limits apply to sole proprietorships in India:

    Category Mandatory Threshold
    Service Providers Annual turnover exceeding ₹20 Lakhs
    Goods Suppliers Annual turnover exceeding ₹40 Lakhs
    Special Category States ₹10 Lakhs for services / ₹20 Lakhs for goods

    Zero-Threshold Cases (Mandatory Regardless of Turnover):

    You must register if you:

    • Engage in interstate sales.
    • Sell through e-commerce platforms.
    • Operate as a Casual Taxable Person.

    The 6-Step GST Registration Process

    Step 1: Initiation via Part A

    Visit the official GST portal. Provide PAN, mobile number, and email. After OTP verification, a Temporary Reference Number (TRN) is generated.

    Step 2: Business Details

    Log in using TRN and complete Part B by entering trade name, selecting proprietorship, and stating the reason for registration.

    Step 3: Document Uploads

    • Identity Proof: Aadhaar Card and PAN Card
    • Photograph: Proprietor’s image
    • Address Proof: Rent agreement, NOC, or utility bills
    • Bank Proof: Cancelled cheque or passbook copy

    Step 4: Aadhaar Authentication

    An Aadhaar-based e-KYC verification is required. Successful verification may eliminate physical inspection.

    Step 5: Officer Verification

    An officer reviews your application. If needed, a clarification notice (REG-03) is issued, which must be answered within 7 working days.

    Step 6: GSTIN Generation

    Upon approval, your GSTIN and Registration Certificate (Form REG-06) are issued. Download and display it at your place of business.


    How Does Lawizer Make the Process Seamless?

    GST registration can be complex, and errors often lead to delays. Lawizer connects business owners with professionals like Chartered Accountants and Company Secretaries to simplify the process.

    Why Choose Lawizer?

    • Expert Oversight: Ensures documentation meets government standards.
    • Fast Response: Provides quick consultations.
    • Virtual Office Solutions: Helps with business address documentation.
    • Query Handling: Experts manage government notices and responses.
    • Affordable: Free consultation with transparent pricing.

    Get GST Registered Without Hassle. Choose Lawizer Today!


    Frequently Asked Questions

    What is Central GST (CGST)?

    A: CGST is the tax levied by the Central Government on intra-state transactions.

    What is State GST (SGST)?

    A: SGST is the tax levied by the State Government on intra-state transactions.

    What is Integrated GST (IGST)?

    A: IGST applies to inter-state transactions and is collected by the Central Government.

    Are there fees for registration?

    A: While the government portal is free, Lawizer charges a service fee for handling documentation and filing.

    How long does the process take?

    A: Typically, GSTIN is issued within 3 to 10 working days after successful Aadhaar authentication.

    Is Lawizer a registered company?

    A: Yes. Lawizer is an initiative of Zeptus Private Limited, a registered entity in India.

  • Why Your Brand Needs Trademark Registration in India Today?

    In the hyper-competitive Indian market, your brand name isn’t just a label—it is a vital business asset.

    Many founders make the mistake of thinking a Domain Name or a Company Registration (RoC) gives them ownership of their brand.

    However, in the eyes of Indian law, a domain name is merely an address, and a RoC provides a legal identity but zero Intellectual Property (IP) protection.

    Without a registered trademark, you are building your business on a weak foundation. Lawizer, a leading legal-tech platform, offers the most efficient way to secure your brand.


    1. The Shield and Sword of Your Business:

    A trademark acts as both a defensive shield and an offensive sword under the Trade Marks Act, 1999. Registration grants you the exclusive right to use your brand name, logo, and tagline nationwide.

    • The Shield: It prevents others from feeding on your hard-earned reputation.
    • The Sword: It gives you the legal power to sue copycats who try to confuse your customers with similar-sounding names.

    2. The Power of the ® Symbol:

    The transition from a “TM” to an ® is more than just a character change; it’s a global signal of authenticity and trust.

    • Exclusive Rights: Grants sole legal authority to use your brand identity.
    • Statutory Weight: Provides the necessary legal standing to win infringement cases quickly.
    • Marketplace Entry: Most major e-commerce platforms and government tenders require a registered trademark for onboarding.

    3. Business Expansion and Franchising:

    If you plan to scale, franchise, or license your brand, trademark registration is mandatory.

    Investors and partners are more likely to fund brands with secured legal protection. A registered trademark allows you to enter “e-commerce” and international markets without the fear of brand theft.

    Costs and Duration to Register:

    • Affordability: Government charges are concessional for startups, individuals, and small enterprises.
    • Validity: Protection lasts for 10 years and is renewable indefinitely.
    • Timeline: The process typically takes 12 to 18 months.

    Key Industries Powered by Trademark Registration

    Trademarking is a strategic asset across these high-growth sectors:

    IndustryWhy It Matters
    Consumer GoodsPrevents “look-alike” products in crowded markets.
    Food & BeverageProtects unique packaging and brand names.
    HealthcareEnsures trust and stops dangerous counterfeit products.
    Tech & SoftwareSecures identity in fast-moving, innovative sectors.
    Luxury & FashionPreserves exclusivity by stopping counterfeiters.

    How Lawizer Simplifies the Process:

    Lawizer, an initiative of Zeptus Pvt Ltd, makes the journey from “TM” to “®” easy and stress-free.

    Lawizer Prerequisites:

    To get started, you will need the following documents:

    For Individuals / Startups / MSMEs:
    • Applicant’s PAN Card & Aadhaar
    • Address Proof
    • MSME/Udyam Certificate (for a 50% government fee concession)
    For Companies / LLPs / Partnerships:
    • Incorporation Certificate / Partnership Deed
    • PAN Card of the Entity
    • TM-48 Form (Authorizes our legal experts)

    What You Receive Through the Lawizer Portal:

    1. Instant TM Number: Use the “TM” symbol immediately after filing.
    2. Objection Management: Our experts handle “Examination Reports” to keep your application moving.
    3. Emergency SOS Button: Connect with an advocate within 2-3 minutes for urgent help.
    4. Free Consultation: Expert guidance for all first-time users.

    Conclusion: Legitimizing Your Innovation:

    In the “move fast and break things” culture of startups, don’t let your brand equity be the thing you break. Trademark registration is a business asset that increases your valuation during funding rounds.

    Secure Your Brand Today:

    Stop wondering if your brand is safe. Get expert guidance and end-to-end support with Lawizer. We’ll get back to you within 24 hours.

    Frequently Asked Questions (FAQs):

    Q1. Can I register a domain name as a trademark?

    A: Yes. If customers identify your service through your URL (e.g., Lawizer.com), the domain itself can be your trademark.

    Q2. What is the benefit of MSME/Udyam Registration?

    A: It is a massive cost-saver. Filing fees are ₹9,000 for companies but only ₹4,500 for MSMEs/Startups. Lawizer helps you leverage these concessions.

    Q3. How do I handle an “Objection”?

    A: Objections are common. Lawizer provides end-to-end support for these hearings, drafting the necessary legal counter-statements for you.

    Q4. Is Lawizer a registered company?

    A: Yes. Lawizer is an initiative of Zeptus Private Limited, a registered entity in West Bengal, India.

    Q5. Is Lawizer a law firm?

    A: No, Lawizer is a digital legal platform that connects you with qualified and verified lawyers. It does not provide legal advice directly.

  • How to Use Lawizer’s SOS Button for Legal Emergencies in India

    How to Use Lawizer’s SOS Button for Legal Emergencies in India

    In India, finding legal help can be a challenge, especially during a crisis.

    Whether you are dealing with a wrongfully issued traffic challan, a cybercrime situation, or a threat to women’s safety, immediate access to professional counsel is vital.

    Lawizer is designed to provide that instant support.

    By bridging the gap between technology and the legal profession, it offers a real-time solution for those who need an emergency legal aid application or immediate advocate support when every second counts.

    What is Lawizer?

    Lawizer is a next-generation digital legal platform that makes legal support fast, simple, and affordable for individuals and startups.

    It is important to note that Lawizer is not a law firm and does not provide legal advice directly.

    Instead, it functions as a secure bridge connecting users with verified advocates before minor problems escalate into major legal battles.

    Key Features:

    • 24/7 Legal SOS Button: For urgent, real-time action.
    • Transparent Pricing: Zero hidden fees and a free first consultation.
    • Verified Experts: Choose advocates based on experience, language, and credentials.

    Steps to Use Lawizer’s SOS Emergency Button:

    The SOS feature acts as a “panic button,” connecting you with a legal expert within minutes. Follow these steps to get help:

    Step 1: Visit the Website:

    Use your mobile browser to search for Lawizer and open the official website.

    Step 2: Click the SOS Button:

    On the homepage, locate and click the “Emergency SOS Button.”

    Step 3: Sign In or Register:

    You will be prompted to sign in. If you are a new user, enter your name, email, phone number, and a secure password.

    Step 4: Verify Your Email:

    Check your mailbox for a verification link to activate your account. This step is crucial for security.

    Step 5: Complete Your Profile:

    Log in and update your details, including your State and City. This helps the platform match you with a lawyer who understands your local jurisdiction.

    Step 6: Confirm the SOS Call:

    Click the Emergency SOS button once more to confirm. A phone number will appear on your dial pad. Call this number to be connected to an expert in 2–3 minutes.

    Tips for Efficient Communication During a Legal Crisis:

    When you are connected to a lawyer, providing structured information helps them protect you faster.

    1. Be Precise and Factual: Stick to the facts of the current situation.
    2. Share Evidence: Have your receipts, challans, or digital documents ready to share.
    3. Identify the Category: Specify if your issue is related to Criminal, Civil, Property, or Business law to bypass guesswork.
    4. Ask About Fees: While the first consultation is free, discuss future fee structures early to keep the process transparent.

    Conclusion:

    Lawizer’s 24/7 Legal SOS button empowers every Indian citizen to act with confidence during a crisis.

    By leveraging technology to provide real-time responses from verified experts, the platform ensures that help is always just a click away.

    Frequently Asked Questions (FAQs):

    Q1. Is Lawizer a legitimate company?

    A: Yes, Lawizer is an initiative of Zeptus Private Limited, registered in West Bengal, India.

    Q2. Is the first consultation really free?

    A: Yes. Lawizer offers the first consultation for free because they believe legal clarity should always come before cost.

    Q3. Can Lawizer help with cyber complaints or traffic police?

    A: Absolutely. The platform connects you with specialized lawyers for cybercrimes, traffic disputes, and general civil matters.

  • CORPORATE TAX FILING 101: A CHECKLIST FOR FILING ITR 6 FOR PRIVATE LIMITED COMPANIES

    CORPORATE TAX FILING 101: A CHECKLIST FOR FILING ITR 6 FOR PRIVATE LIMITED COMPANIES

    This blog will cover the basic requirements for filing ITR-6 , Importance of
    Corporate tax return India , ITR-6 Due date.

    ITR 6

    Introduction: Purpose Of Filing Under ITR-6:

    For filing under ITR-6 for the income tax return , it is especially done for
    companies which are incorporated under the Companies Act , 2013.

    This ensures not only reporting of income , deduction , taxes and transaction Filing an ITR-6 helps in maintaining the company whether is private or public, it keeps under a obligations effectively and systematically.

    Eligibility Criteria Of Filing ITR-6:

    The companies that are registered under the Companies Act 2013 should file
    ITR-6 . It includes Domestic Companies , Foreign Companies, Partnership Firms.

    Structure of the filing the ITR-6?

    • The Income Tax Department advices that are two parts and several
      schedules.
    • As a sequence wise they can file out a form by Part A , Schedules,
      Part B and Verification.

    How To File ITR-6 Form?

    This is generally done through compulsory electronically under digital signature to the income tax department.

    Filing Of ITR-6 Due Date:

    The due date for filing an income tax return is to be maintained by the is a assessee partner in a firm then the accounts is to be audited by 31st of October of the Assessment year.

    Benefits Of Filing In ITR-6?

    • It enhances and ensures transparency.
    • The collection of documents is required to be maintained for record
      purpose and tax audits statements.
    • It minimizes deduction and avoid penalties and interest charges.
    ITR 6

    Conclusion:

    The criteria and aspect of ITR-6 is detailed oriented and is only
    applicable to the companies.

    This helps companies in avoid penalties, interest and avoid tax compliance issue from tax authorities.

    Corporate Tax Doesn’t Have to Be Taxing. Private Limited Companies require precision—from balance sheets to audit reports.

    Don’t navigate the complex maze of corporate tax laws alone.

    Our team ensures your ITR-6 is filed with 100% accuracy and complete statutory compliance, letting you focus on growing your company.

    [Secure Your Corporate Tax Filing Services Now]

    Sources:

  • ITR-5 FILING GUIDE FOR PARTNERSHIP FIRMS AND LLPs: AVOID COMMON MISTAKES

    ITR-5 FILING GUIDE FOR PARTNERSHIP FIRMS AND LLPs: AVOID COMMON MISTAKES

    Introduction

    Many business entities such as partnership firms, Limited Liability Partnerships (LLPs), and associations are required to file their income tax returns every year. For these entities, the relevant tax return form is ITR-5.

    The procedure of filing ITR-5 is an important compliance requirement under the Income Tax Act. It helps businesses report their income, claim deductions, and ensure proper tax compliance with the Income Tax Department.

    Understanding the process of filing ITR-5, the due date, tax audit requirements, and applicable tax rates for partnership firms is essential for avoiding penalties and maintaining financial transparency.

    This guide explains the procedure of ITR-5 filing, LLP income tax returns, tax audit requirements, and the due date for filing ITR-5.


    What Is ITR-5?

    ITR-5 is the income tax return form used by certain business entities such as partnership firms, LLPs, and associations of persons.

    The form is designed to capture detailed financial information including business income, capital gains, deductions, and tax liabilities.

    ITR-5 is filed electronically through the Income Tax Department’s e-filing portal.


    Who Can File ITR-5?

    The following entities are eligible to file ITR-5:

    • Partnership Firms
    • Limited Liability Partnerships (LLPs)
    • Association of Persons (AOPs)
    • Body of Individuals (BOIs)
    • Co-operative Societies
    • Local Authorities

    However, individuals, Hindu Undivided Families (HUFs), and companies cannot use this form.


    Structure of the ITR-5 Form

    The ITR-5 form is comprehensive and contains several sections to report financial information accurately.

    The form is divided into two main parts:

    • Part A – General Information
    • Part B – Computation of Total Income and Tax Liability

    In addition, the form contains nearly 40 schedules used to report specific financial details such as capital gains, business income, deductions, and taxes paid.


    Procedure for Filing ITR-5

    The ITR-5 form must be filed electronically through the Income Tax Department’s e-filing portal.

    The return can be filed in the following ways:

    • Submitting the return electronically using a Digital Signature Certificate (DSC)
    • Uploading the return electronically and verifying it through e-verification methods

    After filing the return, the taxpayer must complete e-verification within 30 days of submission.


    Changes in ITR-5 Form (AY 2025-26)

    The Income Tax Department has introduced certain updates to the ITR-5 form for recent assessment years.

    • New reporting fields for high-value financial transactions exceeding ₹50 crore
    • Disclosure requirements for payments to Micro and Small Enterprises under Section 43B(h)
    • Additional reporting related to capital gains and specified securities

    These changes are intended to increase transparency and ensure proper reporting of financial transactions.


    Partnership Firm Tax Rate

    For the Assessment Year (AY) 2026-27, partnership firms including LLPs are taxed at a flat rate of 30% on their taxable income.

    In addition to this tax rate, surcharge and health & education cess may also apply depending on the income level.


    Tax Audit for Partnership Firms

    A tax audit is required to ensure that businesses maintain proper books of accounts and comply with the provisions of the Income Tax Act.

    Under Section 44AB, a tax audit becomes mandatory when the business turnover exceeds the prescribed limits.

    The audit helps verify:

    • Accuracy of financial statements
    • Proper maintenance of accounting records
    • Correct reporting of income and deductions
    • Compliance with tax regulations

    A tax audit also helps detect errors, irregularities, and potential financial discrepancies in the accounting records.


    Due Date for Filing ITR-5

    The due date for filing ITR-5 depends on whether the entity is subject to a tax audit.

    • 31 July – For entities not requiring a tax audit
    • 31 October – For entities requiring a tax audit

    Failing to file the return before the due date may lead to penalties and interest under the Income Tax Act.


    Conclusion

    Filing ITR-5 is a crucial compliance requirement for partnership firms, LLPs, and other eligible entities. It ensures that businesses properly report their income and comply with tax regulations.

    Timely filing of ITR-5, along with maintaining proper accounting records and completing tax audits when required, helps businesses avoid penalties and maintain financial transparency.

    Understanding the procedure of ITR-5 filing and staying updated with changes in tax laws allows firms to remain compliant and manage their finances effectively.


    Frequently Asked Questions

    Who cannot file ITR-5?

    Individuals, Hindu Undivided Families (HUFs), companies, and entities required to file ITR-7 cannot file ITR-5.

    Is tax audit applicable for ITR-5?

    Yes. A tax audit is required if the business turnover exceeds the limits specified under Section 44AB of the Income Tax Act.

    Is it mandatory for LLPs to file ITR-5?

    Yes. Limited Liability Partnerships (LLPs) are required to file their income tax return using the ITR-5 form.

    What is the time limit for e-verification of ITR-5?

    The return must be e-verified within 30 days of filing.


    Sources

  • HOW TO SAVE TAXES FOR THE SMALL BUSINESSES? (SECTION 44AD)

    HOW TO SAVE TAXES FOR THE SMALL BUSINESSES? (SECTION 44AD)

    This blog consists of Benefits of Section 44AD, Eligibility Criteria of ITR-4, Presumptive Taxation scheme and Tax saving for small business.


    ITR4


    Introduction: Purpose Of Section 44AD (Presumptive Taxtation)

    Section 44AD is designed to provide an easier way to solve compliance issue that sometimes arises in the business taxpayers by allowing income declaration to fixed percentages.

    This is applicable to any business except to any agency business or brokerage business.

    This section entails about maintaining detailed books of account that provides presumptive taxation scheme for small taxpayers.

    The Tax is payable in one installment by 15th march.


    Key Benefits

    • The tax issues gets simplified.
    • There is no such requirement for tax audit under section 44AB.

    Eligibility Criteria Of ITR-4

    A Resident individual, HUFs can file ITR-4 if the following conditions are fulfilled:

    • The income must not exceed Rs50 lakh during the financial year.
    • The income is applied on the basis of the presumptive basis under SECTION 44AD.
    • In case of long term capital gains the amount must not exceed beyond Rs 1.25 lakh.
    • Income from salary or pension or own house property is allowed about Rs 5000.

    Presumptive Taxation Scheme

    It is given as a relief to small taxpayers from the tedious job of maintenance of book of account.

    It is framed under the Presumptive Taxation Scheme under Section 44ADA and 44AE of the Income Tax Act, 1961.

    Eligibility Criteria For Presumptive Taxation In India

    • Legal
    • Medical
    • Engineering
    • Technical Consultancy
    • Architecture
    • Other Professions By CBDT

    Sec 44AD For Professional

    This is applicable to 8% of the turnover or gross receipt of the eligible business during the financial year which is amount to the total taxable income.

    In order to promote digital transaction and encourage small business to accept digital payments, income shall unorganized business to accept digital payments.

    Therefore the income will be compute to the 6% interest and 8% turnover.


    Tax Saving For Small Business

    Income Tax can be saving in small business if it is well planned practically.

    • By leveraging the business into deduction to reduce tax income.
    • By depreciating the cost of assets.
    • By strategically managing the travel expenses and other travel expenses.
    • By investing in medical insurance this reduces the tax deduction.
    • By advertisement like through Digital Marketing , it plays an effective role in tax – deductible.
    • By donating funds in charitable organization.

    Conclusion

    This concludes that ITR-4 promotes in ease for filing, time efficiency and simplified tax compliance for small business and hereby if an individual opts for the presumptive taxation scheme under Section 44AD this becomes easier and promotes less compliance issue.

    Simplify Your Taxes, Amplify Your Savings. Why drown in bookkeeping when you can use Presumptive Taxation?

    If you are a small business owner, Section 44AD is your golden ticket to easier compliance and lower tax burdens.

    We specialize in helping small businesses file ITR-4 (Sugam) correctly to ensure you never pay a penny more than needed.

    Start Your ITR-4 Filing & Save on Taxes Today


    Frequently Asked Questions

    What is the maximum income limit to file ITR-4?

    A: The maximum amount should not exceed to Rs50 lakh in the financial year.

    Is salary income allowed in ITR 4?

    A: Yes, they are allowed from salary/pension.

    Is agricultural income allowed in ITR-4?

    A: Yes, agriculture income is up to Rs 5000 can be allotted.

    Are professionals like doctors or lawyers file ITR-4?

    A: YES, only if they opt that under section 44ADA.

  • FREELANCER OR BUSINESS OWNER? COMPLETE GUIDE TO FILING ITR-3 AND CLAIMING EXPENSES

    FREELANCER OR BUSINESS OWNER? COMPLETE GUIDE TO FILING ITR-3 AND CLAIMING EXPENSES

    Introduction

    Many professionals, freelancers, and business owners in India are required to file their income tax returns every year. For individuals and Hindu Undivided Families (HUFs) who earn income from business or profession, the applicable tax return form is ITR-3.

    Understanding the procedure for filing ITR-3, the due date, audit limits, and allowable business expense deductions is important for maintaining tax compliance.

    This guide explains the process of filing ITR-3, audit requirements for businesses, due dates, and common business expense deductions for freelancers and professionals in India.


    What Is ITR-3?

    ITR-3 is the income tax return form used by individuals and Hindu Undivided Families (HUFs) who earn income from a business or profession and are required to maintain books of accounts.

    The form allows taxpayers to report income from multiple sources including:

    • Business or professional income
    • Salary or pension
    • Income from house property
    • Capital gains
    • Income from other sources

    ITR-3 is filed electronically through the Income Tax Department’s e-filing portal.


    Who Should File ITR-3?

    The following taxpayers are required to file ITR-3:

    • Individuals running a business
    • Freelancers and self-employed professionals
    • Hindu Undivided Families (HUFs) earning business income
    • Professionals such as consultants, doctors, lawyers, and architects

    However, individuals earning income only from salary, pension, or interest cannot use this form.


    Documents Required for Filing ITR-3

    To file the ITR-3 return accurately, taxpayers should keep the following documents ready:

    • Basic details such as PAN, Aadhaar, name, and address
    • Details of income from business or profession
    • Income details from salary, house property, or other sources
    • Bank account details for all accounts held during the financial year
    • Investment proofs for deductions under Section 80C, 80D, and other sections
    • Books of accounts and financial statements for the business

    Maintaining proper documentation helps ensure accurate reporting of income and deductions.


    Due Date for Filing ITR-3

    The due date for filing ITR-3 depends on whether the taxpayer is required to undergo a tax audit.

    • 31 July – For individuals or HUFs not requiring a tax audit
    • 31 October – For taxpayers whose accounts require a tax audit

    For example, for the Financial Year 2025-26 (Assessment Year 2026-27), the due date without audit is 31 July 2026.

    Filing the return after the due date may result in penalties and interest.


    Audit Limit for Business and Professionals

    A tax audit under Section 44AB of the Income Tax Act becomes mandatory when business or professional income exceeds certain limits.

    • Business: Audit required if turnover exceeds ₹1 crore (or higher limits depending on digital transactions).
    • Profession: Audit required if gross receipts exceed ₹50 lakh in a financial year.

    The purpose of a tax audit is to verify financial records, ensure correct reporting of income, and maintain compliance with tax laws.


    Understanding Business Expense Deductions

    Business expenses refer to costs incurred in the ordinary course of running a business or profession.

    These expenses are allowed as deductions while calculating taxable income.

    Keeping proper records of business expenses throughout the year helps reduce tax liability legally.

    Business expenses are generally categorized into two types:

    • Capital Expenditure – Expenses related to long-term assets such as machinery or equipment.
    • Operational Expenditure – Day-to-day expenses required for running the business.

    Common Deductible Business Expenses

    Some common expenses that freelancers and business owners can claim as deductions include:

    • Interest paid on business loans
    • Utility expenses such as electricity, internet, and phone bills
    • Advertising and marketing expenses
    • Office rent and maintenance costs
    • Employee salaries and wages
    • Professional service fees
    • Travel and transportation expenses for business purposes

    Proper documentation of these expenses helps reduce taxable income and ensures compliance during tax assessments.


    Conclusion

    Filing ITR-3 is essential for freelancers, professionals, and business owners who earn income from business activities.

    Understanding the filing procedure, audit limits, and available deductions helps taxpayers comply with the Income Tax Act and reduce their tax liability legally.

    Maintaining proper financial records and filing the return before the due date ensures smooth tax compliance and avoids penalties.


    Frequently Asked Questions

    Is ITR-3 applicable for freelancers?

    Yes. Freelancers and self-employed professionals who earn income from business or professional services must file their returns using the ITR-3 form.

    Is a tax audit compulsory for ITR-3?

    A tax audit is required only if business turnover or professional receipts exceed the limits specified under Section 44AB of the Income Tax Act.

    Who can file ITR-3?

    Individuals and Hindu Undivided Families (HUFs) who earn income from business or profession are required to file ITR-3.

    What is the deduction limit under Section 80C?

    Taxpayers can claim deductions up to ₹1.5 lakh per financial year under Section 80C for eligible investments such as PPF, ELSS, life insurance premiums, and others.


    Sources

  • “SOLD STOCKS OR CRYPTO? WHY YOU MUST FILE ITR-2 INSTEAD OF ITR-1”

    “SOLD STOCKS OR CRYPTO? WHY YOU MUST FILE ITR-2 INSTEAD OF ITR-1”

    This blog will focus upon the Capital Gains Tax of India, Purpose of Crypto tax filing in India, ITR for mutual funds.


    ITR2


    Introduction: Purpose Of Investing In Stocks

    This is the most vital aspect for an individual in order to achieve in long term financial goals. Investing in stocks gives benefits to grow over time and gives presence of multiple buyers and sellers in the markets.

    The investor gets a lot of diverse aspect across all the sectors which help them in benefiting in higher liquidity, returns and plan them in reaching their investment goals.


    Why Capital Gains In India Are Important?

    Capital Gains

    • Long term capital gains are important in order to generate revenue for funds. Government gains assets sales through the share of the wealth created through investment.
    • Capital gains are necessary in order to get profit from increase in asset value to pay the fair share for wages and salary earners.
    • The long term capital gains ensures in encouragement in fairness towards the institution that provide productive gains from businesses, housing and infrastructure.
    • The long term capital gains helps in promoting productive reinvestment towards the growth sectors.

    Purpose of Crypto Tax Filing in India

    The crypto tax filing helps in regulating the legal framework and misuse of crypto transaction with the help of Virtual Digital Assets under the Income Tax Act.

    Filing crypto ensures that profits that are being generated from rapid digital assets markets contribute fairly to the national exchequer.

    It helps in checking TDS tracking; schedule VDA, proper flow of tax data sharing without in sort of laundering unaccounted.

    The government maintains a strict policy regarding the obligations to protect policy and helps in balancing innovation with oversight. This also empowers in preparing India for cross – border crypto regulations.


    Importance Of ITR For Mutual Funds

    1. Filing of Income Tax Return for Mutual is essential in order to support for effective financial planning for investors.
    2. Proper disclosure and transaction data helps in minimizing capital loss and thereby helps in reporting income accurately.
    3. Filing an ITR allows in supporting and gaining long term financial gains avoids any tax compliance issue.
    4. This helps in maintaining proper tracking investment performance and notices every income tax invoices without any penalties.

    Conclusion

    Crypto Tax filing is designed in such a way that it helps to minimize the compliance issue and prevent financial misuse and provides a robust legal framework in governing the standard regulations in order to gain profitability and generate revenue.

    Don’t Let Capital Gains Complicate Your Life. Calculating profit and loss on stocks or crypto can be a nightmare, and choosing the wrong form invites notice from the IT department.

    Skip the spreadsheets and confusion. Let our tax experts handle your Capital Gains calculations and file your ITR-2 accurately today.

    Click Here to File Your Capital Gains Tax Effortlessly


    Frequently Asked Questions

    Is it necessary to file an ITR if a person starts investing in mutual funds?

    A: Yes, when the capital gain which exceeds the total income exceeds the exemption limits, it is mandatory.

    Which form of ITR is basically useful for mutual fund income?

    A: ITR-2 is more preferable in order to have capital gains from mutual funds.

    State the list of documents that are required for filing the ITR for mutual funds?

    A:
    Pan card
    Aadhar card
    Bank details
    Capital Gain Statements

    Does the income tax record every financial statement and why so?

    A: Yes, the department records every detail in order to avoid mismatch errors that can arise from any income tax scrutiny.


    Sources

  • HOW TO FILE ITR-1 SAHAJ ONLINE (AY 2026 – 27) : A STEP -BY – STEP GUIDE FOR SALARIED EMPLOYEE

    HOW TO FILE ITR-1 SAHAJ ONLINE (AY 2026 – 27) : A STEP -BY – STEP GUIDE FOR SALARIED EMPLOYEE

    This blog will focus upon how to File ITR-1 online, What are the ITR-1 Sahaj step by step, Income Tax Return for the Salaried, ITR-1 eligibility, Old vs New Tax Regime of 2026.


    Introduction

    An ITR stands for Income Tax Return which is a form that a person or individual submits to the Income Tax Department of India to file the necessary financial documents needed for the income and tax payable during the respective year.

    The time required to file an ITR should be applicable between 1st April to 31st March of the next year.

    The source of income could be from profit of a business, dividends or capital gains. It carries out the forward loss and ask for the return from the income tax department.


    How To File ITR-1 Online?

    • STEP 1: The filing of ITR-1 form is done through the e-Filing Portal or by through the accessibility of html utility.
    • STEP 2: The registered user on the e-Filing Portal must login with the help of their valid user ID and password, their PAN card must be active.
    • STEP 3: The PAN and ADHAAR CARD must be linked.
    • STEP 4: Only the residential can file the ITR-1 whose income does not exceed Rs 50 lakh during the financial year.
    • STEP 5: Atleast one bank account must be pre-validated for receiving refunds.
    • STEP 6: The form includes 5 main pre-filled sections and the taxpayers must verify each steps before submissions. The steps includes personal informational, tax paid, total deductions, total tax liability.

    Eligibility Criteria Of ITR-1

    • Resident individual who have income from salary.
    • This includes one house property, interest or dividends, from agriculture income.
    • Income from other sources (excluding winnings, lottery and income from race horses from lottery taxable under sec 115BBDA).
    • Long term capital gains under section 112A up to Rs 1.25.

    Old vs New Tax Regimes 2026

    There have been numerous deductions and exemption been allotted in these regimes as given below:

    Old Tax Regimes

    1. It is been allotted to the House Rent allowances for the exemption available only on rent paid.
    2. Deduction on Rs 2 lakh on the loan interest on self – occupied property.
    3. Deduction on Rs 1.5 for investment under section 80C.
    4. Deductions for health insurance premium that are under section 80D.
    5. Deduction is allotted on education loans.

    New Tax Regimes

    1. The slab rates have been lowered.
    2. Rs 75000 have been the standard deduction amount for the salaried persons.
    3. It does not allow popular deduction under Section 80C.
    4. Tax free income up to Rs 12 lakh.

    Conclusion

    The main aspect of both the tax regime is totally dependent upon the individual person income structure. The income tax department had made both regime so that it can be helpful towards to the younger, professional and elderly people too.

    Filing your taxes as a salaried employee should be straightforward, but missing deductions can cost you money. Lawizer ensures your ITR-1 is filed accurately, claiming every benefit you are entitled to while keeping you fully compliant with the latest tax rules.


    File ITR-1 Now with Lawizer.


    Frequently Asked Questions

    How to choose which tax regimes for filing?

    For 2025-26 one can choose the old tax regime for filing an ITR whereas for new tax regime one has to file a form 10IEA within the due date for filing an ITR.

    Is the standard deduction allowed in the new tax regime?

    Yes, as per the new tax regime the standard deduction is Rs 75000.


    Sources

  • “SOLE VS SHARED CUSTODY: WHAT IS BEST FOR YOUR CHILD?”

    “SOLE VS SHARED CUSTODY: WHAT IS BEST FOR YOUR CHILD?”

    This Blog ensure about the Concept “Shared Parenting” which ensures the betterment of the child’s welfare of the Indian Courts. A Parent often does not know the difference between the Judicial Custody and Parental Custody.


    Types Of Custody In India

    • Physical Custody: This is the most common type of custody where the child lives with one parent and the other parent gets visitation rights. The custodial parent meets the child’s daily needs.
    • Joint Custody: The Joint Custody is not yet very common in India, but it is steadily gaining recognition. A Joint Custody explains how both parents share the custody of the child. This ensures the child’s upbringing and welfare while creating strong emotional bonds with both parents.
    • Legal Custody: This type of custody ensures the responsibility of the child’s long-term welfare. Even when a parent does not have physical custody, their role continues. They remain an important part of the child’s life including decisions about education, healthcare and other important matters.
    • Sole Custody: In situations where one parent is deemed unfit or in abusive circumstances, the court may grant sole custody to the other parent. The court carefully considers the child’s wellbeing before making such a decision.
    • Third Party Custody: This type of custody happens rarely where the court grants custody to a third person (non-biological guardian). The court may take this step only if the parents are unfit or incapable of taking care of the child.

    How To File An Application For Interim Custody Of A Child

    To file an application for child custody, a petition must be filed under Section 25 of the Guardians and Wards Act, 1890. This provision allows the court to grant custody of a minor child through a formal legal petition.

    Interim Custody refers to temporary custody of the child for a limited period of time. The application for interim custody of a minor child is generally filed under Section 12 read with Section 25 of the Guardians and Wards Act, 1890.

    Sole Custody and Shared Custody


    How Visitation Rights Can Preserve The Rights Of Parents

    Visitation rights are granted by the court based on mutual agreement between the parents. The aim is to ensure that the child continues to maintain a healthy relationship with both parents even after separation or divorce.

    Types Of Visitation

    Fixed Visitation: This includes predetermined days such as weekends or holidays when the parent can meet the child.

    Reasonable Visitation: This allows flexible time where parents decide mutually when the child can meet the non-custodial parent.

    Visitation rights support the emotional wellbeing of the child by helping them remain connected with both parents.


    Case Law: Yashita Sahu vs State of Rajasthan

    This case was decided by the Supreme Court of India and highlighted the importance of joint custody. The court emphasized that both parents should actively participate in the child’s upbringing and welfare.


    Conclusion

    Courts grant equal importance to the rights of both parents while prioritizing the welfare of the child. This approach ensures the child’s wellbeing both in the present and in the future.

    To resolve such sensitive disputes, courts also encourage counseling sessions and support mechanisms for both parents and children.

    Determining whether sole or shared custody is better depends entirely on the child’s welfare. Consulting child custody experts can help parents understand which arrangement best suits their family’s circumstances.

    Discuss Your Custody Case with the top lawyers of the country.


    Frequently Asked Questions

    How can you claim child custody under Hindu law?

    A: A custody claim can be filed under the Guardians and Wards Act along with provisions of the Hindu Minority and Guardianship Act.

    How much time does a child custody case take?

    A: A custody case may take around 2–3 years depending on the circumstances. However, parents can file an application for interim custody during the proceedings.

    Are visitation rights applicable to the father?

    A: Yes. Courts often grant visitation rights to fathers so that they can remain involved in the child’s life and contribute to the child’s welfare.

    Who gets custody of a minor child after divorce?

    A: Both parents have equal rights over the child. The court ultimately decides custody based on the best interests and welfare of the child.

  • HOW TO FILE A DOMESTIC VIOLENCE COMPLAINT : A
SURVIVOR’S LEGAL GUIDE:

    HOW TO FILE A DOMESTIC VIOLENCE COMPLAINT : A SURVIVOR’S LEGAL GUIDE:

    Introduction

    Domestic Violence is a form of violence that any person faces as a form abusive ness from their partner. It includes both Physical and mental abuse. This causes a trauma to the person and a serious threat to the society.

    In order to govern upon such matter it is very important to understand the rights , effectiveness , impact and legal framework in order to protect themselves from such situation.


    Legal Framework On Domestic Violence: What Are The Remedies Available For The Victims?

    Authoritative rights and protection is an eminent factor towards the people who are stuck in an abusive relationship, faces hurdles every day.

    There are many people who do not report for such offences due to social stigma which leads to rise of violence and gives power to such people who commits such act.

    Legal Reforms available to deal with such acts are:

    • One should file against such act under section 498A of the Indian Penal Code (IPC)
    • Should file a complaint under any specialized officer/NGOs.
    • Complaint or case can should be filed under The Domestic Violence Act for Women act 2005, which was governed and came into force in 2006.
    • Must seek assistance from the Police and file a report
    • Must seek assistance for counseling sessions
    • Must hire or seek approval an advocate and take proper assistance for it.

    How To File A Case Or Lawsuit Against Domestic Violence In India?

    Laws have becoming progressive and changing its pattern for new implementation and awareness.

    In such framework the victim should be completely make themselves ready to fight for their Justice.

    The court reforms are there to help for the victims to fight their dignity, considerations and legal aids.

    In order to fight such cases it is an utmost important aspect that the victim must hire a good lawyer to seek assistance and guidance.

    • First and fore most, The Government Of India has a Portal of National Commission for women available 24*7 for the women to register for sort of violence if they are being affected. Website link – https://www.digitalindia.gov.in and Helpline number – 14490.

    How Effective Is The Protection Of Women From Domestic Violation Act, 2005?

    • The Protection of Women from Domestic Violence Act, 2005 which came into force on 2005 aims to provide protection for women who get harassed by their partners, relatives etc. This act is made with a aim to help and provide protection to all the mothers, sisters and minor girl child and also covers issues of dowry or harassment cases.
    • Many NGOS, Portals, website are their available 24*7 for any assistance.
    • They can obtain for shelter, protection for themselves and their children.
    • Various legal aids are also available for help and monitoring such cases.
    • The affected party must lodge a complain to nearby Police Station, appoint a lawyer and make a lawsuit for the matter in the District Court.
    • A chief protection officer must also be appointed for looking into such matters cause this type of cases are sensitive and there are a lot of chance of cyber attacks or threats also takes place.
    • A women victim has the provision of getting an immediate civil remedies within 60 days.

    Recent Supreme Court Judgement

    Case Laws: We The Women Of India VS Union Of India

    On 20th May 2025, The SC made a detailed effective implementation towards THE PROTECTION OF WOMEN FROM DOMESTIC VIOLENCE ACT, 2005.

    They ensured about the importance of regular reporting, shelter homes, conduct awareness programs.

    This act is a civil law therefore monetary assistance, relief, custody is crucial.

    Last but not least they also mentioned about how the process are getting inconsistence and should be given utmost priority.


    Conclusion

    It is very important to take effective steps in order to attain protection, custody and interim relief in order to deal such matter.

    The law supports such safety and concern and well being towards the women.

    You do not have to suffer in silence. Lawizer provides a safe space and immediate legal avenues to file a complaint and seek protection orders. Your safety is our priority.


    Get Urgent Legal Protection, talk to our expert lawyers now.


    Frequently Asked Questions

    Are legal remedies available for this act?

    Absolutely available, a women can seek protection order or assistance from the portal given above.

    Can a wife complain against her husband?

    Yes, she can.

    Can a partner who is in a live-in relationship file for such offence?

    Yes, they can file a complain if any abusive or violence takes place.

    Who can guide to file the case?

    NGOs, Welfare Protection officer.

  • THE ADOPTION PROCESS: A STEP-BY-STEP LEGAL GUIDE FOR FAMILIES

    THE ADOPTION PROCESS: A STEP-BY-STEP LEGAL GUIDE FOR FAMILIES

    Introduction

    An adoption process is legal framework of adopting a child lawfully with all verification of the authorities through courts order.

    An adoption is seen as a change in both for the Child who has gone through a loss of being accepted, taken care of by their family or has never got a privilege to experience family bond.

    An adoption establishes a true sense of parenthood which they grant to the child and accept them with all heart. It creates a sense of belonging ness and creates a better life for the child.


    Legal Framework And Guidelines Governing Adoption

    In order to adopt a child legally and lawfully it is very necessary to have a comprehensive idea about the laws and procedure that will provide a basic idea about this.

    The eligibility criteria of adoption process in India are done with the help of Juvenile Justice (Care and Protection of Children) Act 2015, which involves registering with the CARA Portal (Central Adoption Resource Authority) with the help of an expert who can guide for Specialized Adoption Agency (SAA).

    This involves a step by step process in order to enter such framework.

    The process involves by filling a petition for a court order and matching the criteria that the parents needed in order to receive the child lawfully without any hindrance.


    Guidelines For CARA (Central Adoption Resource Authority)

    1. The Central Adoption Resource Authority functions under the Ministry of Women and Child Development and it involves all the effective adoption schemes that are needed for the betterment of the child.
    2. Every adoption process comes with effective criteria that will meet the standards of the child as well as the parents which includes healthcare, welfare, fostering of the child and overall upbringing.
    3. In order to have standardized and lawful procedure to adopt a child then they have to file a petition and registration process is necessary through CARA Portal under the authorization of the Juvenile Justice Act.
    4. A specialized counselor is mandatory to be appointed for both the Child and the Parent who have approach for the process. A counseling session is done and questioning to the non- biological parents is needed in order to have a basic consideration for the adoption of the child.
    5. The adoptive parents have to go through some regulatory assessment which will firmly believe that are ready to adopt the child.
    6. The role of Specialized Adoption Agencies (SAA) and Home study report is beneficiary in order to ensure the process is smooth and protected without any illegal practices.
    7. Court order is also necessary for the meeting all the above needs and gives the parental custody officially to the adoptive parents so that the child can lawfully attains all the rights.

    Conclusion

    The overall laws and guidelines are meant extending the best interest for the Child and foremost the emotional security that is been bonded to the adoptive parents.

    Upbringing a Child by emphasizing their care and moral support is all what a Child truly needs.

    There are many Children who are their struggling with identity crises, lost in their own thoughts at such a tender age, at that point all what matters is they need care and affection which a parent can give, who are willing to take up all the responsibility willfully.

    Hence this will benefit a large to the overall society.

    Adoption is a journey of love, but the CARA guidelines and court processes are strict legal steps. Our family lawyers guide prospective parents through the documentation to ensure your adoption is legally secure.


    Connect with Adoption Experts


    Frequently Asked Questions

    What are the Challenges those most adoptive centers?

    A lot of time it has happened that the child faces with their identity issue and lack of self believe if they can adjust in the new place.

    Can a person adopt a 6 Month old baby India?

    Yes absolutely, A person can adopt a Child from 6 months to 16 years of age.

    Is Registration Process mandatory for Adopting a Child?

    Yes, It is necessary for adopting a child. The procedure is done through CARA Portal governed by The Juvenile Justice Act, 2015.

    How much time does it take to go through this process?

    The time frame depends upon the regulatory framework, preferences that the child meets and needs and attaining every availability of the court without any due process.

    What are the rights that a child gets from the adoptive parents?

    After all the regulatory framework is done the Child gets the overall authority and lawful rights from their adoptive parents which is same as a biological parent gives to their child.

    Is the adoption process Reversible?

    No, once the process is done and gets a final order from court then it becomes irreversible.

  • “CHILD CUSTODY LAWS IN INDIA: HOW TO WIN CUSTODY AS A FATHER”

    “CHILD CUSTODY LAWS IN INDIA: HOW TO WIN CUSTODY AS A FATHER”

    Introduction

    Child custody is one of the most sensitive and important aspects of family law. It determines the future, wellbeing, and upbringing of a child when parents separate or divorce.

    During emotional custody disputes, the most crucial question the court considers is: what is in the best interest of the child?

    This guide explains the legal, emotional, and psychological aspects of child custody in India, along with the legal provisions that protect the rights of both parents and ensure the welfare of the child.


    What Is Child Custody and Why Is It Important?

    Child custody refers to the legal rights and responsibilities given to a parent or guardian to care for and make decisions about a child’s upbringing.

    Custody is not only a legal matter but also involves the emotional and psychological wellbeing of the child. Courts aim to ensure that the child receives proper care, stability, and support for their development.

    Parental separation can significantly affect a child’s emotional and mental health. Therefore, courts carefully evaluate all circumstances before making custody decisions.

    The Indian judicial system always follows one primary principle in such cases:

    The welfare of the child is the paramount consideration.


    Legal Provisions for Child Custody in India

    In India, child custody laws aim to ensure the child receives proper emotional, financial, and educational support.

    In cases involving older children (usually around 12 years or above), the court may consider the child’s opinion while deciding custody matters, as the child may have a basic understanding of their own welfare.

    The main laws governing child custody in India include:

    • The Guardians and Wards Act, 1890
    • The Special Marriage Act, 1954

    Under Section 7 of the Guardians and Wards Act, 1890, courts have the authority to appoint a guardian for a minor if it is necessary for the welfare of the child.

    This law applies to individuals of all religions.

    Additionally, Section 38 of the Special Marriage Act, 1954 empowers district courts to pass interim orders regarding the custody, maintenance, and education of minor children during matrimonial proceedings.

    The common objective of these provisions is to ensure the best possible upbringing and welfare of the child.


    Father’s Rights in Child Custody

    In custody disputes, the law recognizes that fathers also play an important role in the upbringing and development of a child.

    Some of the fundamental responsibilities and rights of a father include:

    1. Providing emotional and financial support to the child.
    2. Participating in important decisions regarding healthcare and education.
    3. Ensuring proper care, nurturing, and maintenance of the child.

    According to Section 17 of the Guardians and Wards Act, 1890, the court considers several factors while appointing a guardian, including the welfare and best interests of the child.

    Although younger children are often placed in the custody of the mother, modern courts increasingly recognize that fathers can also provide a stable and supportive environment for the child.


    Rights of a Custodial Father

    In certain situations, courts may grant custody of a child to the father. These circumstances may include:

    • If the mother is abusive or engages in violence against the child.
    • If the mother suffers from serious health issues that prevent proper care.
    • If the mother voluntarily transfers custody to the father.
    • If the father is capable of providing financial stability and proper upbringing when the mother is unable to do so.

    Courts evaluate each case carefully and make decisions based on what will provide the most stable and supportive environment for the child.


    Important Case Laws on Child Custody

    Vivek Singh vs. Romani Singh

    This case highlighted the significance of a father’s role in a child’s life and emphasized the importance of the child’s welfare.

    The court considered two major aspects:

    • The child expressed a desire to stay with the father.
    • The welfare and best interests of the child were the highest priority.


    Read more about this case

    Gaurav Nagpal vs. Sumedha Nagpal (2009)

    In this case, the court emphasized that the welfare of the child must always be the most important consideration in custody disputes.

    The decision recognized the importance of the father’s role while also ensuring visitation rights for the mother.

    The judgment demonstrated that courts are increasingly open to granting custody to fathers when they can provide a stable and supportive environment for the child.


    Read more about this case


    Conclusion

    Child custody disputes are highly sensitive matters that directly affect a child’s future. Courts must approach such cases with care, ensuring that the emotional wellbeing and development of the child remain the top priority.

    In many situations, counseling for both parents and the child can help reduce conflict and prevent parental alienation.

    Ultimately, providing a stable, supportive, and nurturing environment is essential for raising a healthy and confident individual.

    Fathers play a crucial role in a child’s life, and modern Indian courts increasingly recognize this. If you are facing a custody dispute, it is important to build a strong legal strategy that demonstrates your ability to provide a secure and supportive environment for your child.

    Secure Your Parental Rights by talking to the best custody lawyers in the country.


    Frequently Asked Questions

    Where should a child custody petition be filed?

    Child custody petitions are generally filed in the Family Court or the District Court that has jurisdiction over the matter.

    At what stage can child custody be requested?

    A parent can request custody of a child at any stage during divorce proceedings or marital disputes.

    Does the child’s opinion matter in custody cases?

    Yes. Courts may consider the child’s preference, particularly if the child is mature enough to understand the situation. The court evaluates the emotional bond between the child and each parent before making a decision.

    Are visitation rights granted to fathers?

    Yes. Even if custody is granted to the mother, fathers are often given visitation rights to maintain a healthy relationship with the child.


    Sources

  • HINDU MARRIAGE ACT REGISTRATION: A STEP-BY-STEP GUIDE (2025)

    HINDU MARRIAGE ACT REGISTRATION: A STEP-BY-STEP GUIDE (2025)

    Introduction

    The Hindu Marriage Act, 1955 applies to the whole of India (originally excluding Jammu & Kashmir) and governs marriages among Hindus. The Act came into force on 18th May 1955.

    This Act applies to any person who is a Hindu by religion, including Buddhists, Jains, and Sikhs. It does not apply to Muslims, Christians, Parsis, or Jews unless specifically provided under law.


    Why Is Registration of Marriage Important?

    A Marriage Certificate is crucial to establish a lawful and legally recognized marriage. Marriage registration serves as official legal proof and protects the rights of both spouses.

    Registration acts as substantial evidence of marriage and safeguards individuals—especially women—from issues such as fraud, bigamy, and denial of marital rights.

    It also helps couples avoid legal complications related to property rights, visas, bank accounts, insurance, inheritance, and other official matters.


    Conditions for a Valid Hindu Marriage

    A marriage between two Hindus can be legally solemnized if the following conditions are fulfilled:

    • Neither party has a living spouse at the time of marriage.
    • Both parties give lawful and free consent.
    • The groom must be at least 21 years old and the bride must be at least 18 years old.
    • The parties must not fall within the degrees of prohibited relationship unless permitted by custom or usage.

    Legal Provisions for Registration (Section 8)

    • Registration of Hindu marriages is governed under Section 8 of the Hindu Marriage Act, 1955.
    • The State Government appoints a Marriage Registrar for this purpose.
    • Rules framed under this section must be laid before the State Legislature.
    • Failure to comply with prescribed rules may attract a nominal fine depending on state rules.
    • Although non-registration does not invalidate the marriage, registration provides strong legal evidence.

    Offline Procedure for Hindu Marriage Registration

    1. Visit the office of the Marriage Registrar.
    2. Submit the prescribed application form, usually available through the Sub-Divisional Magistrate office.
    3. Provide the required documents along with identity and address proof.
    4. Witnesses (generally three, depending on applicable law) must be present.
    5. The marriage certificate is usually issued within 15–30 days depending on state procedures.

    Online Procedure for Hindu Marriage Registration

    Many states now provide online registration facilities through official government portals. The general process includes the following steps:

    1. Visit the official State e-District or Marriage Registration portal.
    2. Book an appointment with the Marriage Registrar.
    3. Fill out the online application form.
    4. Upload the required documents.
    5. Appear before the Sub-Divisional Magistrate for verification if required.
    6. Receive the digitally issued Marriage Certificate.

    Landmark Case Law: Smt. Seema v. Ashwani Kumar (AIR 2006 SC 1158)

    In this landmark judgment, the Hon’ble Supreme Court held that marriages in India should be compulsorily registered irrespective of religion. The ruling aimed to prevent child marriages, bigamy, and fraudulent practices while protecting the rights of women.


    Conclusion

    Although registration is not mandatory for the validity of a Hindu marriage, it is strongly recommended for legal security and documentation.

    The Hindu Marriage Act, 1955 plays an important role in authenticating marriages. Ceremonies such as Saptapadi (mentioned under Section 7) complete the solemnization of marriage, while registration provides official documentary proof.

    Marriage registration strengthens legal protection, promotes women’s welfare, and helps prevent fraudulent practices such as bigamy and child marriage.

    While traditional ceremonies remain culturally significant, obtaining a marriage certificate is essential for matters such as visas, loans, joint property ownership, insurance claims, and inheritance.

    Need assistance with marriage registration?
    Get Professional Registration Support


    Frequently Asked Questions

    Is it necessary to register a marriage under the Hindu Marriage Act?

    Answer: Registration is not mandatory for the validity of the marriage, but obtaining a marriage certificate is highly important as legal proof.

    What is the minimum age for marriage under the Hindu Marriage Act?

    Answer: The minimum age is 21 years for the groom and 18 years for the bride.

    Is a legal advisor required for Hindu Marriage registration?

    Answer: No, a legal advisor is not mandatory. However, professional guidance can help ensure a smoother and error-free registration process.

  • CHEQUE BOUNCE CASE (SECTION 138): LEGAL NOTICE, RULES & PUNISHMENT

    CHEQUE BOUNCE CASE (SECTION 138): LEGAL NOTICE, RULES & PUNISHMENT

    Introduction:

    Cheque Bounce (or dishonor of cheque) comes under section 138 of the Negotiable Instrument Act, 1881.

    This occurs when a cheque may bounce if it is being expired or there has been serious issue with the date. It usually happens when a bank refuses to pay a cheque usually due to insufficient funds.

    Section 138 Of Negotiable Instrument Act:

    It is essentially makes it an offense to issue a cheque that bounces, providing a legal recourse for the payee or holder in due course. There are three key aspects to it:

    • Dishonor Of Cheque This states when a cheque is drawn on an account which is maintained by the drawer for payment of a debt or liability is returned unpaid by the bank.
    • Cause Of Dishonor : The cheque can be returned unpaid due to insufficient funds in the account or because signature mismatch or it could be the amount exceeds the arrangement made with the bank.
    • Punishment: If the above following conditions are met, then the drawer of the cheques can be punished with the imprisonment which can extend upto 2 years or a fine which can lead to twice the amount of the cheque or both.
    Notice for cheque bounce
    Notice for cheque bounce

    What Is A Cheque?

    It is defined under Section 6 of the NI Act stating that a cheque as a Bill of exchange drawn on a specified banker and not expressed to be payable otherwise then on demand and it includes the electronic image and in an electronic form.

    A Cheque in the electronic form means a cheque drawn in the electronic form by using any computer resources and signed in a secure system with digital signature (with or without biometric signatures) and Asymmetric Crypto System or with electronic signatures.

    What Is The Due Date For Clearance?

    Key Essential Features Under Section 138 NI Act:

    NI Act penalizes the dishonor of a cheque, however dishonor of a cheque is by itself if the following ingredients have to be fulfilled.

    • Drawing of the cheque.
    • Presentation of the cheque of the Bank.
    • Return of the cheque unpaid by the drawee bank.
    • Issuance of the notice in the writing to the drawer of the cheque demanding payment of the cheque amount.
    • Failure of the drawer to make the payment within 15 days of receipt of the notice.

    Legal Process For The Dishonor Of Cheque Or Cheque Bounce:

    1) Drawing of the Cheque : The Cheque is created by the drawer.

    2) Presentation to the Bank: The Cheque is to submitted to the bank for
    payment.

    3) Issuance of Notice: The holder in due course must send a written legal
    demand notice to the drawer within 30days.

    4) Return unpaid: A notice period of 15 days is given to the drawer to make the payment , if not given then the action arises.

    5) Filling of complaint: If the drawer fails to pay within 15 days , then as it is a criminal act intent , so a criminal complaint will be lodged against the drawer within the 30 days before the Judicial Magistrate of First class.

    A Limitation For Filing A Complaint In Respect Of The
    Offence Under Section 138 NI Act:

    Section 142 NI Act prescribed an outer limit of one month for filing of a complaint from the data of the cause of action arises.

    Recent Guidelines By Supreme Court Of India On Cheque Bounce:

    • The Supreme Court of India has issued a fresh guidelines to ensure a speedy procedure regarding the cheque bounces cases which has created a lot of backlogs.
    • Dishonor of cheque under Section 138 of Negotiable Instruments Act which accounts for upto 50% of pending cases
    • As per the new directions that has been issued by the Supreme Court the cheque bounces cases are now to be served only in person by through digital medium that is via Email and Whatsapp.
    • Complainants are there to provide there necessary details for quick response.
    • These creates and facilitates to provide early dispute towards such issues.

    Conclusion:

    Thus we conclude, the statutory framework relating to cheque dishonor ensures financial discipline towards by providing an effective legal remedy against the defaulters which creates a strong financial instruments by strong legal framework.

    In essence with that it creates striking balance in reinforcement and safeguards regarding the dishonor of payment.

    If a cheque issued to you has dishonoured, time is of the essence. You must send a statutory legal notice within the stipulated timeline to recover your dues or initiate criminal proceedings against the defaulter.

    Send a Legal Notice Today:

    Frequently Asked Questions:

    Q1. What are the documents needed for cheque bounce case?

    Ans: To file a case under Section 138, you must submit the original dishonored cheque and the bank’s return memo stating the reason for rejection. You also need a copy of the legal notice sent to the defaulter within 30 days, the postal proof of service or delivery report, and the formal complaint petition supported by a sworn affidavit. Invoices or agreements proving the debt are also recommended.

    Q2. Can a company be held liable for cheque bounce?

    Ans: Yes, under Section 141 of the NI Act, a company is a legal entity and can be prosecuted. Along with the company, every person (like a Director or Manager) who was “in charge of and responsible for” the business at the time of the offense is vicariously liable.
    However, you must arraign the company itself as an accused; suing only the directors is not legally maintainable.

    Q3. Can multiple cheque bounce may lead to multiple case?

    Ans: Yes, but the law allows grouping them. Under Section 219 of the CrPC, up to three offenses of the same kind committed by the same person within 12 months can be tried together in a single trial.
    A single legal notice can also cover multiple dishonored cheques if they relate to the same transaction. Courts are now encouraged to hold joint trials to expedite these cases.

    Q4. What is the due date for clearance?

    Ans: Legally, a cheque is valid for presentation and clearance for 3 months from the date issued.
    Regarding bank processing speed, current RBI guidelines under the Cheque Truncation System (CTS) ensure that cheques deposited by 4:00 PM are cleared and settled by the same day or the next working day.
    New “Continuous Clearing” measures are further reducing this time to just a few hours.

  • SECOND MARRIAGE REGISTRATION IN INDIA: PROCEUDURE & DOCUMENTS (2025)

    SECOND MARRIAGE REGISTRATION IN INDIA: PROCEUDURE & DOCUMENTS (2025)

    Introduction:

    A Second Marriage in India refers to the marriage which is being contracted by a person which has been lawfully dissolved or either the husband or wife has died.

    Otherwise the second marriage would be held void or it may condemn a criminal liability. This provision comes under the Hindu Marriage Act, 1955.

    Registration Procedure For Second Marriage:

    • The First marriage has to be lawfully ended which is mandatory eligibility criteria for this procedure.
    • The intended party must submit an affidavit which clarifies that the previous marriage has been dissolved.
    • An application is mandatory to be filed with the Marriage Registrar or local Sub-Registrar Office
    • Verification is required by the registrar who will act as a conclusive proof towards the marriage.
    • For the verification purpose some necessary documents are required such as identity proof, proof of the previous marriage to be dissolved (certificate),passport size photo

    Applicability Of Second Marriage Under Special Marriage Act, 1954:

    Penalties of Remarriage & its legalities
    Penalties of Remarriage & its legalities
    • Both the parties have free will to marry under this act only if the previous marriage has been dissolved or lawfully ended.
    • A 30 Day notice period is required as per the act for registration purpose.

    Common Legal Issues:

    1) If the First marriage is in subsistence then the second marriage would be
    condemned to void under the Hindu Marriage Act, 1954.
    2) If the intended party fails to provide previous marriage valid divorce
    certificate or death certificate that it can lead to major issues towards legal
    disputes.
    3) The parties should have proper consent towards each other mutual decision otherwise it creates procedural irregularities.
    4) In aspect of the child inheritance there have been major issues from the
    second marriage.
    5) While registration procedure there have been many a times legal Compliance issue or delays in documentation process.

    Recent Judgement Passed On Kerala High Court:

    A Muslim man had fallen in love with other women while being in
    existence of his first marriage. He claimed for a plea stating that he married
    for the second time only with the consent of his first wife.

    The court said that the marriage registration officer can hear and will let the Muslim women give an opportunity of hearing when the husband re marry.

    Later on the plea was dismissed.
    This clarifies that the second marriage is not invalid only if the legal
    requirement of the first marriage is being dissolved.

    Documentation Required For Second Marriage Registration:

    • ID/Adhere proofs.
    • Previous Divorce Decree/Death Certificate.
    • Address proof.
    • An Affidavit which states about the previous marriage decree or dissolution of marriage.
    • Three Witnesses (If the marriage is being solemnized Under Special Marriage Act,1954)

    Conclusion:

    Thus we conclude that the procedure for registration for Second Marriage Act which comes under the Hindu Marriage Act strictly restrict if first marriage is in existence, it will claim to be void and a criminal act.

    The law is abide by it rule and it does not overpower it though its strict legislative procedure it protects and creates liability towards the society so that there must be no issues of child inheritance or bigamy.

    This act is abiding by to protect its dignity to the overall aspect of marriage and makes a clear understanding that are sought for clarity.

    Remarriage comes with specific legal prerequisites regarding divorce decrees or death certificates of previous spouses. Ensure your new union is legally valid and fully compliant with Indian laws by consulting our specialists. Consult on Remarriage Laws with India’s top lawyers.

    Frequently Asked Questions:

    Q1. Does the registrar verify or check the documents?

    Yes, rigorous verification is mandatory. For a second marriage, the verification process is stricter than for a first marriage. The Marriage Officer (or Sub-Registrar) is legally obligated to verify the eligibility of both parties to ensure no fraud or bigamy is being committed. They specifically check:
    The Death Certificate of the previous spouse (if widowed).
    The Decree of Divorce (if divorced) to ensure the appeal period has passed.
    Age and identity proofs.

    Q2. To whom are the affidavits needed to be submitted?

    The affidavits must be submitted to the Marriage Registrar or the Sub-Divisional Magistrate (SDM) of the district where you are applying. Both parties must file separate affidavits stating:
    Current Marital Status (e.g., “Divorcee” or “Widower”).
    Date of the previous marriage’s dissolution (Death or Divorce).
    A declaration that they are not related to each other within the “prohibited degree of relationship.”

    Q3. Is it obligatory to end the first marriage in order to for
    first marriage?

    Absolutely Yes. Under Indian laws (Section 5(i) of the Hindu Marriage Act and Section 4(a) of the Special Marriage Act), a second marriage is legal only if the first marriage is dissolved.
    If you marry without a legal divorce or death certificate, the second marriage is Void (invalid) ab initio.
    You can also be prosecuted for Bigamy (Section 494 IPC), which carries a prison sentence of up to 7 years. Mere separation is not enough; a court decree is mandatory.

  • SPECIAL MARRIAGE ACT 1954: A STEP-BY-STEP REGISTRATION GUIDE FOR COUPLES

    SPECIAL MARRIAGE ACT 1954: A STEP-BY-STEP REGISTRATION GUIDE FOR COUPLES

    Introduction:

    In Indian Society, Marriage holds a sacred place and the Special Marriage Act promotes a framework how individual can marry through a civil procedure which is irrespective of religion, caste or creed.

    The Act permits individuals to marry outside their faith by laying down conditions relating to age, eligibility, soundness of mind and safeguarding towards the individual rights.

    Moreover, the Act creates certain complexities; it actively drives progressive social change by encouraging inter-caste and inter-faith marriages.

    Evolution and legislative Framework:

    The Legislature enacted this provision in newly independent India to establish an effective legislative framework.

    The Special Marriage act, 1954 was intended to regulate a special type of marriage by though a compulsory registration and certification which is an essential aspect in order to legalize the aspect of marriage.

    This act is applicable to all the Indian whether they live in India or outside.


    Basic Requirements For Registration:

    1) Both the parties must be Indian Citizen
    2) The parties must be in full consent of the marriage
    3) If any of the parties had an n earlier marriage then it has to been legally dissolved.
    4) The age limit of the male should be 21years and female should be at least eighteen years.

    5) The marriage is too solemnized in front of the marriage officer and three witnesses.
    6) Should have a copy for marriage notice book.

    Special Marriage Act
    Special Marriage Act

    Special Marriage Act Procedure:

    Why Does Registration Of Marriage Matter So Much Under The Special Marriage Act?

    This is an eminent step towards entering in to recognition of registration of the marriage which also symbolizes as secure and protection towards the couple.

    An application will be duly mandatory for both the parties in order to refrain from any objections of marriage.

    A marriage officer will be appointed and will give a notice period of 30 days as a mandatory enquiry.

    Now, within this period if any issue arises from any of the parties , then the marriage cannot be solemnized and therefore it might led to for an enquiry which will be conducted by the marriage officer.


    Legal Problems That Are Being Faced Under This Provision:

    1) This act compels both the parties to wait for the Mandatory one month notice period for any objection as per mentioned in section 5 of the act.

    The problem that arises is that the law provides an intimation of the parties which sometimes led to violation of privacy as the notice will be displayed publicly outside the Marriage Officers.

    Under such circumstances, this can lead to the individual’s life jeopardized and harm personal liberty.

    2) Another important issue that arises as per section 7 that any person may object before the expiration of thirty days’ notice period.

    This sometimes led to confusions, societal pressure which might cause insufficient and weak towards the existing protection. This creates a negative aspect to the socio culture belief leading to emotional coercion.

    3) Special Marriage acts aims to provide with a vision of secular marriage so that through this act so it does not create tension between the individual.

    However, a substantial segment of the population is unaware of the measures which lead to socio cultural oppression.

    4) Procedural regulation is often delayed which causes objections, regulations, lack of uniformity, harassment to both the intended parties.

    5) Last but not the least due to issuance of the notice of 30 days period publicly creates an objection towards infringement of Right to Privacy under article 21 of Constitution , were the disclosure of personal information such data of the individuals breaks the limits provided in section 5 and 7.


    Recent Legal Issues:


    FORGERY OF THE CERTIFICATE: Recently, in Allahabad High Court passed an
    order stating that a marriage which is being held under this act is only valid if there is no unlawful conversion of certificate.

    If one of the intended parties illegally found in conversion of certificate then the marriage will not be held valid.

    PIL FILLED AGAINST 30 DAYS NOTICE PERIOD: A Public Interest litigation
    was filled under Special Marriage Act, 1954 stating that the parties who intended to marry must obey the one month notice before solemnizing the marriage.

    This PIL was filled in Supreme Court, 2020. Later on the Petition was heard and dismissed as they found no such reason to be discussed upon.

    However, in April 2023 D Y CHANDRACHUD confronted and stated about the Provision to be “Patriarchal”.

    The major concern about this notice is that it raises a regime to privacy infringement and safety concern of the couple which are being exposed to public officially during the 30 days period.


    Conclusion:


    As we reach the end, we can conclude that The Special Marriage Act provides an exhaustive details relating the institution of marriage, promotes secular and empowers the people to believe in inter- caste and inter – faith marriages but also lacks in procedural segments that undermines privacy, safety and personal wellbeing to the individual parties.

    Planning an inter-faith or civil marriage? Don’t let bureaucratic hurdles delay your special day. We assist couples with document verification and the 30-day notice period to ensure a hassle-free registry marriage.

    Simplify Your Marriage Registration:

    Frequently Asked Questions:


    Q`1. Why does 30 days notice period is considered so essential and does it affect to an individual privacy?

    When the Special Marriage Act was enacted in 1954, the lawmakers intended to create a secular law for inter-faith or inter-caste couples. The 30-day notice (under Section 5 and 6) was designed as a public fraud-check mechanism.
    Public Scrutiny: The law requires the Marriage Officer to display a notice containing the couple’s names, addresses, photos, and occupation on a public board for 30 days.
    Inviting Objections: The purpose is to allow anyone to object if the marriage violates the law. The specific grounds for objection are:
    Bigamy: If one party is already married.
    Prohibited Relationship: If the parties are related by blood (incest).
    Age: If the groom is under 21 or the bride is under 18.
    Unsound Mind: If one party is mentally unfit to consent.

    Q2. How does this act provides protection and privacy to the couples?

    The Special Marriage Act (SMA) primarily protects couples by allowing them to marry without religious conversion, preserving their individual identities.
    It serves as a secular legal shield that overrides family objections and validates inter-faith unions.
    Regarding privacy, while the original law required a 30-day public notice, recent
    High Court rulings (like Safiya Sultana) have held that couples can opt out of this display to prevent harassment.
    Additionally, an SMA application acts as legal proof to secure immediate police protection and access to safe houses if the couple faces threats of violence.

    Q3. How procedural lapses causes unnecessary delays in this
    provision?

    Procedural lapses primarily stem from bureaucratic overreach. Marriage Officers sometimes demand documents not required by law (like parental no-objection certificates) or delay the process to investigate frivolous objections raised by the public under Section 8.
    Since the Act mandates an inquiry for every objection, a simple administrative lapse or a false claim can pause the marriage for an additional 30 days.
    Furthermore, minor clerical errors in the Notice of Intended Marriage often force couples to restart the entire notice period.

  • INDIAN CRIMINAL JURISPUDENCE

    INDIAN CRIMINAL JURISPUDENCE

    What is the criminal Law in India?

    From the antiquity the Indian society has always been governed by specific set of law like the i.e. Harappan Civilization but it differs in terms of its regulations from time to time

    Ancient:

    In the ancient times laws were often linked with divine origin for their validation it was often unjust and biased but people did not have enough exposure to rectify the problems.

    There was altogether no uniform system and religious text use to guide the citizens. Dharma which prescribed the moral and legal duty. Manusmriti, Arthashastra.

    Crime was seen as adharma. And the criminal procedures were often conducted in royal courts and by royal officers.

    Medieval:

    Things started to become complex with the advent of monarchial rule being established because this time the last verdict was not rational but the decision of the king.

    More often the monarch tried to provide their subject justice but not always it was carried out. The punishments were also arbitrary and with no mercy considered.

    Pre Independence Era:

    With the inception of the British colony in India and overthrow existing norms they tried to impose their form of law on our society as there was not uniform law whatsoever with the regional difference taken in account.

    Under the law commission of British India headed by lord Thomas Babington Macaulay the first uniform legal codes were enacted through governor general Lord canning in 1860 the Indian Penal Code, Criminal Procedure code and the Indian Evidence act.

    As been mentioned previously law in India was followed in accordance with the divinity, to make things more systematic the British enforced these laws.

    Post Independence:

    Even after independence the government of the countries restructured the pre-established law according to our country and enforced it only.

    Contemporary Situations:

    The situations change altogether, as to remove all the leftovers of the British government the old criminal laws were replaced with the new ones in 2023. IPC was changed into Bharatiya Nyaya Sanhita

    CrPC was replaced with Bharatiya Nagarik Suraksha Sanhita, further the Indian evidence act was replaced with Bhartiya sakshya adhiniyam to deal with the changing and diverse society of ours.

    IPC:

    IPC refers to as Indian Penal Code. That came in effect in 1860 under the British raj the main purpose of introduction of this particular law was to prevail a unifying criminal justice system.

    IPC is enacted when the crime is already committed and the offender is already been convicted in the judicial process.

    It was drafted by the first Law commission of India (1834) which was headed and chaired by lord Thomas Babington Macaulay, and it was enforced by governor general lord canning.

    Even after partition both of the country’s government took its form of IPC, restructured and modified according to their country. After serving the country till 2023 with 511 section and 23 chapter it was finally replaced with BNS.

    CrPC:

    The Code of Criminal Procedure, commonly called Criminal Procedure Code (CrPC), was the main legislation on procedure for administration of substantive criminal law in India.

    It was enacted in 1973 and came into force on 1 April 1974.

    It provides the machinery for the investigation of crime, apprehension of suspected criminals, collection of evidence, determination of guilt or innocence of the accused person and the determination of punishment of the guilty.

    It also deals with public nuisance, prevention of offences and maintenance of wife, child and parents.

    On 11 August 2023, a Bill to replace the CrPC with the Bharatiya Nagarik Suraksha Sanhita (BNSS) was introduced in the Lok Sabha. On 26 December 2023, it was replaced with Bharatiya Nagarik Suraksha Sanhita (BNSS).

    IEA:

    The Indian Evidence Act, originally passed in India by the Imperial Legislative Council in 1872 during the British Raj, contains a set of rules and related provisions governing the admissibility of evidence in Indian courts of law.

    The India Evidence Act was replaced by the Bharatiya Sakshya Adhiniyam on 1 July 2024.

    The enactment and adoption of the Indian Evidence Act was a significant development in India, transforming the system of rules regarding the admissibility of evidence in Indian courts of law.

    Until then, the rules of evidence were based on the traditional legal systems of different social groups and communities of India and were different for different people depending on caste, community, faith and social position.

    The Indian Evidence Act introduced a standard set of law applicable to all Indians.

    The law is mainly based upon the firm work by Sir James Fitzjames Stephen, who could be called the founding father of this comprehensive piece of legislation.

    In some Islamic-majority legal systems, such as Palestinian law and Iranian law, commercial law still well into the 21st century, relies heavily on testimonial evidence or customary law, rather than documentary evidence.

    The New Criminal Law:

    BNS:

    The Bharatiya Nyaya Sanhita (BNS), 2023 (Bhartiya Nyaya Sanhita Indian Justice Code (IJC), 2023) is the new criminal code of India. It came into effect on 01 July 2024, after being passed by the Parliament in December 2023, replacing the colonial-era Indian Penal Code of 1860 (IPC).

    In the BNS, 20 new offences have been added to and 19 provisions in the repealed IPC have been dropped.

    The punishment of imprisonment has been increased for 33 offences, and fines have been increased for 83 offences.

    A mandatory minimum punishment has been introduced for 23 offences. A sentence of community service has been introduced for six offences.

    • Offences against the body: The BNS retains the provisions of the IPC on murder, abetment of suicide, assault and causing grievous hurt. It adds new offences such as organized crime, terrorism, and murder or grievous hurt by a group on certain grounds.
    • Sexual offences against women: The BNS retains the provisions of the IPC on rape, voyeurism, stalking and insulting the modesty of a woman. It increases the threshold for the victim to be classified as an adult, in the case of gang rape, from 16 to 18 years of age.
    • Offences against property: The BNS retains the provisions of the IPC on theft, robbery, burglary and cheating. It adds new offences such as cybercrime and financial fraud.
    • Offences against the state: The BNS removes sedition as an offence. Instead, there is a new offence for acts endangering India’s sovereignty, unity and integrity.
    • Offences against the public: The BNS adds new offences such as environmental pollution and human trafficking.

    BNSS:

    The Bharatiya Nagarik Suraksha Sanhita (BNSS), 2023 (Bhartiya Nagarik Suraksha Sanhita Indian Citizen Safety Code (ICSC), 2023), is the main legislation on procedure for administration of substantive criminal law in India

    Consolidating and simplifying the law: The BNSS consolidates and simplifies the law by repealing and amending a number of provisions of the CrPC.

    Strengthening the rights of the accused: The BNSS strengthens the rights of the accused by providing for safeguards, such as the right to a lawyer of choice during interrogation, though not throughout the interrogation, and the right to a fair trial.

    Every police officer or other person arresting any person without warrant shall forthwith communicate to him full particulars of the offence for which he is arrested or other grounds for such arrest.

    When any person is arrested, he shall be examined by a medical officer in the service of the Central Government or a State Government, and in case the medical officer is not available, by a registered medical practitioner soon after the arrest is made.

    Improving the efficiency of the criminal justice system: The BNSS seeks to improve the efficiency of the criminal justice system by streamlining procedures and reducing delays.

    The following are some of the key changes made in the BNSS:

    Arrest: The BNSS expands the grounds for arrest and allows for arrest without a warrant in a wider range of cases.

    Investigation: The BNSS gives the police more powers to investigate crimes and requires them to complete investigations within a specified time period.

    Trial: The BNSS streamlines the trial process and requires courts to dispose of cases within a specified time period.

    BSA:

    The Bharatiya Sakshya Adhiniyam (BSA), 2023 Bhartiya Saskya Adhiniyam Indian Evidence Act (IEA), 2023) is an Act of the Parliament of India.

  • CRIME AND CRIMINAL: PUNISHMENTS & ITS TYPES

    CRIME AND CRIMINAL: PUNISHMENTS & ITS TYPES

    What kind of activities shall be classified under the term “Crime” or be called “Criminal”?

    Any act or omission of offences which may be or ought to be committed against a person or a society and is punishable by law can be called a crime and the person or group of people committing it may be called criminals.

    The law to regulate such activities can be named as criminal Law.

    Criminal Law varies according to jurisdiction as due to the dynamism and diverseness of the society and also differs from civil law where emphasis is more on compensation rather than punishment.

    Separate procedures are carried out in the eye of rule of law to settle the dispute conducted.

    Elements of a crime:

    Any activity weighing with the burden of the harsh and rigorous punishment requires preparation and various elements for its enactment

    1. Human Being: Any actions or omission that is classified under crime or guilty in the eye of the law shall or has to be committed against a human and should cost him safety or life hazard.
    2. Actus Rea: A Latin term used for defining Guilty Act. It is said that anybody shall not be held on the basis of their preparation or intention of committing a crime there has to be an act that is found guilty.
    3. Mens Rea: A Latin term literally meaning Guilty mind referring if a crime is committed it has to have a person with the intent to actually commit that instance. That’s why an unsound mind is often not guilty in the eye of law. “Actus non facit Reum nisi mens sit rea” literally meaning an act does not make a person guilty unless the mind is also guilty
    4. Injury: With the commitment of a crime an injury or harm is must as it is said but numerous times on the basis of apprehension people are accused.

    Punishment:

    Unlike any other forms of law, the criminal law specifically emphasizes on punishment. It is a legal repercussion after the conviction imposed by the state. There are various theory advocating for the rationality of punishment.

    For instance, the deterrent theory aims to create fear in society, the retributive theory is a form revenge by the state, where as the reformative gives a chance the offender by rehabilitating.

    Punishment is of various types:

    1. Death Penalty: An offence that caused the death of the victim and has utmost serious importance of the state requires the offender to pay by their life. More often this form of punishment has highly criticized as no one has the right to take someone’s life not even the state.
    2. Imprisonment: After commitment of the crime when the punishment is served in detention or in the judicial custody that kind of punishment is known as imprisonment. Imprisonment is of 3 types: Simple: It is the most basic imprisonment where offender has to live in detention for a tenure prescribed by the court. Rigorous: This type also has tenure but varies in terms of livelihood as it is much harsher. The offender has to serve the society by doing some work. Life: With the gravity of crime increasing the offender has to spend the rest of his life behind the bars.

        3. Seizure of property: Sometimes in accordance with the intensity of offence often property of the offender is seized.

    Stages of crime:

    1. Intention. It is the mental stage where a person decides to commit a crime. In criminal law prevailing this stage is not punishable unless your thoughts were expressed through conduct.

    2. Preparation. The arrangement of means by the offender is considered under preparation, this is not punishable except for some crucial scenario. Preparation with explosive substance, preparation to commute dacoity and robbery.

    3. Attempt. The direct movement toward the commission of the offence and it is punishable even if the crime fails. But as mentioned earlier the offender has to be fit to sound mind.

    4. Commission. With the completion and execution of crime the commission and crimes end.

    Conclusion:-

    Facing criminal charges can be daunting, but understanding potential punishments is the first step toward building a defense, connect with experienced criminal lawyers who can evaluate your case and fight for the best outcome.

    Find an Expert Defense Lawyer

  • WHAT IS CRIMINAL LAW? A COMPLETE GUIDE

    WHAT IS CRIMINAL LAW? A COMPLETE GUIDE

    Introduction

    Criminal law is a branch of law that deals with crimes, punishment, and the legal procedures used to prosecute individuals accused of committing offences. It is designed to protect society by defining actions that are considered harmful or dangerous and prescribing penalties for those who violate these rules.

    Criminal law helps maintain public order, safety, and justice by ensuring that individuals who commit offences face legal consequences through established judicial processes.


    What Is Criminal Law?

    Criminal law refers to a body of rules and regulations that define criminal offences and prescribe punishments for those who commit them.

    Activities that harm individuals, threaten public safety, or endanger society are classified as crimes. When such laws are violated, the offender may face penalties such as fines, imprisonment, or in extreme cases, the death penalty.

    In most democratic countries, including India, criminal laws are created and enforced through a structured system involving different branches of government.

    • Legislature: Enacts laws by passing legislation.
    • Executive: Enforces the laws through police and administrative authorities.
    • Judiciary: Interprets the law and delivers justice when violations occur.

    Theories of Punishment in Criminal Law

    Various theories explain the purpose and justification of punishment within criminal law. Some of the major theories include:

    Retributive Theory of Justice

    The retributive theory is based on the concept of “an eye for an eye.” In ancient societies, the punishment given to an offender often mirrored the harm caused by the crime. Although historically common, this approach is considered harsh and less acceptable in modern legal systems.

    Preventive Theory of Justice

    The preventive theory focuses on preventing future crimes by restricting or incapacitating the offender. In earlier societies, offenders were often isolated or removed from the community to protect the rest of the population.

    Deterrent Theory of Justice

    The deterrent theory aims to discourage crime by imposing strict and severe punishments. The idea is that harsh consequences will discourage both the offender and others from committing similar crimes in the future.

    Reformative Theory of Justice

    The reformative theory emphasizes rehabilitation rather than punishment. It seeks to reform offenders by providing opportunities for education, counseling, and social reintegration. This theory is widely accepted in modern criminal justice systems.


    History of Criminal Law

    The criminal law system we see today developed gradually over centuries and was not present in early human societies.

    In primitive civilizations, there was little distinction between civil and criminal matters. Societies were largely nomadic and lacked structured governance. Disputes and crimes were often resolved through direct retaliation.

    The first known codified legal systems appeared in ancient Mesopotamian civilizations. Although these laws were strict and sometimes unequal due to class distinctions, they represented an early attempt to regulate social conduct.

    In the Indian subcontinent, early legal frameworks can be traced back to around 200 BCE through texts such as Manusmriti and Kautilya’s Arthashastra during the Mauryan Empire.

    Later, Greek and Roman civilizations made significant contributions to legal development. They introduced formal judicial procedures, state-administered justice, and important legal concepts such as mens rea (the intention behind committing a crime).

    Roman law greatly influenced modern legal systems by clearly distinguishing between criminal offences and civil wrongs while promoting principles like the presumption of innocence and fair trials.

    During the medieval period, legal systems in many regions became harsh and arbitrary under monarchic rule, often involving severe punishments and torture.

    With the emergence of the modern era, legal systems began to focus more on rational governance, human behavior, and the rule of law. Arbitrary state power was gradually restricted, and structured legal institutions were established.

    During colonial periods, many colonial powers imposed their own legal codes in occupied territories. After gaining independence, many nations reformed or restructured these laws to better suit their social, cultural, and constitutional frameworks.

    Today, criminal law continues to evolve as societies change, with increasing emphasis on fairness, human rights, and rehabilitation.


    Conclusion

    Understanding criminal law is essential for recognizing how societies maintain order and justice. The evolution of criminal law reflects humanity’s effort to balance punishment, deterrence, and rehabilitation.

    If you are facing legal uncertainties or require clarification regarding criminal charges or procedures, seeking professional legal advice can help you better understand your rights and available legal remedies.

    Get a Free Legal Consultation


    Frequently Asked Questions

    How are criminal law cases handled by Lawizer?

    Lawizer connects individuals with experienced criminal law advocates who specialize in handling criminal cases and providing legal guidance.

    What is the difference between a cognizable offence and a non-cognizable offence?

    A cognizable offence (such as murder, rape, or dowry death) allows the police to arrest an accused person without a warrant and begin an investigation without prior court approval.

    A non-cognizable offence (such as minor assault or certain forgery cases) requires a warrant for arrest and court permission before an investigation can begin.

    Can I get bail before arrest?

    Yes, a person who fears arrest may apply for anticipatory bail. This is a legal provision where the court directs that the individual be released on bail in the event of an arrest.

    Anticipatory bail is often used when a person believes they may be falsely implicated in a criminal case.

  • HOW TO INCORPORATE A PRIVATE LIMITED COMPANY IN INDIA: A COMPLETE STEP-BY-STEP GUIDE

    HOW TO INCORPORATE A PRIVATE LIMITED COMPANY IN INDIA: A COMPLETE STEP-BY-STEP GUIDE

    Starting a business in India begins with choosing the right legal structure. Among all business entities, a Private Limited Company is the most preferred choice for startups, entrepreneurs, and growing businesses due to its credibility, limited liability, and scalability. In this blog, we explain what a private limited company is, eligibility criteria, step-by-step incorporation process, and how Lawizer simplifies company registration for you.

    What Is a Private Limited Company?

    A Private Limited Company (Pvt Ltd) is a business entity registered under the Companies Act, 2013, where the liability of shareholders is limited to their shareholding. It is a separate legal entity, meaning the company has its own legal identity distinct from its owners.

    Key Features:

    • Separate legal entity
    • Limited liability protection
    • Perpetual succession
    • Easy transferability of shares (restricted)
    • Higher trust among investors and customers

    Eligibility Criteria to Incorporate a Private Limited Company:

    To register a private limited company in India, the following eligibility requirements must be met:

    1. Minimum 2 Directors (maximum 15)
    2. Minimum 2 Shareholders (directors can be shareholders)
    3. At least one director must be an Indian resident
    4. Unique company name
    5. Registered office address in India
    6. Directors must have DIN (Director Identification Number) and DSC (Digital Signature Certificate)

    Step-by-Step Process to Incorporate a Private Limited Company:

    Documents Required for Private Limited Company Registration

    • PAN and Aadhaar of directors
    • Passport (for foreign nationals, if any)
    • Address proof (bank statement / utility bill)
    • Registered office proof (rent agreement / ownership document)
    • Passport-size photographs

    Step 1: Obtain Digital Signature Certificate (DSC)

    DSC is mandatory for filing online incorporation documents with the Ministry of Corporate Affairs (MCA).

    Step 2: Apply for Director Identification Number (DIN)

    DIN is required for all proposed directors of the company.

    Step 3: Name Approval (SPICe+ Part A)

    Choose a unique company name and apply for approval through the MCA portal.

    Step 4: Draft MOA & AOA

    • MOA (Memorandum of Association) defines the company’s objectives.
    • AOA (Articles of Association) defines internal rules and management.

    Step 5: File SPICe+ Form (Part B)

    Submit incorporation documents, registered office details, PAN, TAN, and GST (optional) in a single form.

    Step 6: Certificate of Incorporation

    Once approved, the Registrar of Companies (ROC) issues the Certificate of Incorporation, officially registering your private limited company.


    How Lawizer Helps You Incorporate a Private Limited Company

    Lawizer is a trusted legaltech platform that simplifies the entire company incorporation process through expert-driven, tech-enabled solutions.

    Why Choose Lawizer?

    • ✅ End-to-end company registration support
    • ✅ Verified corporate lawyers & CS professionals
    • ✅ Fast, affordable, and transparent pricing
    • ✅ Expert drafting of MOA & AOA
    • ✅ Real-time updates and dedicated support
    • ✅ Secure document handling

    With Lawizer, you don’t need to worry about complex legal procedures, compliance errors, or delays. Our experts handle everything—from name approval to final incorporation—so you can focus on growing your business.

    Conclusion

    Incorporating a private limited company is a smart step toward building a credible and scalable business. While the legal process may seem complex, the right legaltech partner can make it effortless. Lawizer ensures a smooth, compliant, and hassle-free incorporation experience—trusted by entrepreneurs, startups, and businesses across India.

    👉 Get your Private Limited Company registered today with Lawizer.